
 Stainless Steel Plumbing Pipes Market | 2026-2036
Stainless Steel Plumbing Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Plumbing Pipes Market Analysis
EPA lead-and-copper rule revisions is pivoting municipal procurement toward certified stainless steel alternatives. Mueller Industries leverages captive brass-to-stainless conversion capacity to anchor North American specification channels. Jindal Stainless Limited sustains cost-competitive hot-rolled coil supply through integrated melt-to-pipe operations in India. Geberit AG differentiates via press-fit system integration that locks contractors into proprietary tooling ecosystems.
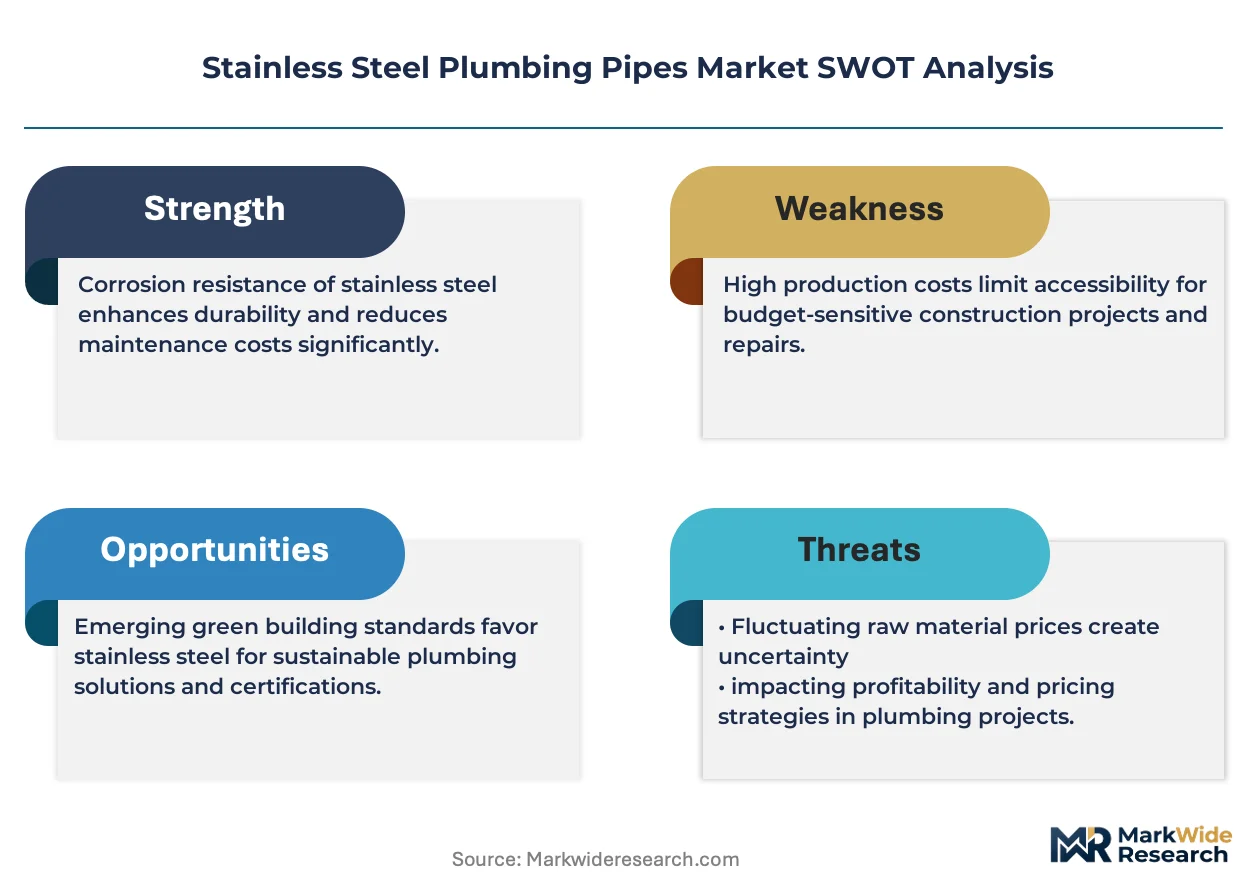
Stainless steel plumbing pipes are hollow cylindrical sections fabricated from austenitic or ferritic alloys, typically containing 10.5% minimum chromium by mass, manufactured through extrusion, welding, or seamless piercing processes to convey pressurized fluids and gases in building services. Welded pipes dominate volume production due to lower unit economics in residential water supply, while seamless configurations command premium positioning in high-pressure industrial process lines. Grade 316 specifications with molybdenum enhancement capture expanding share in coastal HVAC and marine-adjacent drainage systems where chloride exposure accelerates pitting corrosion in standard 304 alloys.
NSF/ANSI 61 certification governs potable water contact safety in the United States, while EU Drinking Water Directive revisions tighten nickel leaching thresholds that favor low-carbon 316L variants across European specification markets. China's GB/T 19228 series mandates dimensional interoperability for press-fit connections that Viega and NIBCO must satisfy for project eligibility. Stakeholders should monitor alloy surcharge volatility and evolving lead-content thresholds as dual levers that will determine which fabrication technologies and geographic supply bases capture disproportionate margin pools.
Market Dynamics
The EPA's lead-and-copper rule revisions are forcing municipal water infrastructure upgrades across the United States, pivoting procurement toward certified stainless steel alternatives and compressing specification cycles for corrosion-resistant piping systems.
Growth Catalysts
- EPA Lead-and-Copper Rule Revisions:Municipal water utilities in the United States face mandated infrastructure replacement timelines, accelerating specification shifts toward NSF/ANSI 61-certified stainless steel alternatives that eliminate lead leaching risks.
- Commercial Building Retrofit Cycles:Aging HVAC and plumbing infrastructure in Class A office towers across Germany's industrial corridor drives demand for Grade 316 press-fit systems with enhanced chloride corrosion resistance.
- Press-Fit Connection Technology:Mechanical joining systems eliminate open-flame installation requirements, reducing labor certification barriers and accelerating adoption in fire-sensitive healthcare and hospitality environments.
Market Restraints
- Alloy Surcharge Volatility:Nickel and molybdenum price swings in commodity markets create unpredictable input cost structures that compress fabrication margins and destabilize project bidding.
- Seamless Pipe Supply Concentration:Limited global capacity for large-diameter seamless piercing operations concentrates high-pressure industrial supply among specialized mills in Germany and Japan.
- Copper Piping Substitution:Established contractor familiarity with soft copper tube and flare fitting techniques sustains incumbent specification patterns in residential water supply segments.
Strategic Opportunities
- EU Drinking Water Directive Nickel Thresholds:Tightened leaching standards favor low-carbon 316L variants, creating specification upgrade revenue for mills with vacuum oxygen decarburization capability.
- Coastal HVAC Expansion:Marine-adjacent installations in Florida and California expose standard 304 alloys to accelerated pitting, opening premium positioning for molybdenum-enhanced alternatives.
- Digital Specification Platforms:Building information modeling integration allows manufacturers to embed proprietary press-fit geometries directly into architectural workflows, locking contractor tool ecosystems.
Industry Challenges
- Certification Timeline Compression:NSF/ANSI 61 testing protocols require extended lead times for new alloy formulations, delaying product launches and constraining responsiveness to specification shifts.
- Skilled Press-Fit Technician Scarcity:Proprietary tooling ecosystems from Viega and Geberit demand certified installer networks that lag behind product availability in emerging specification markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Plumbing Pipes Market |
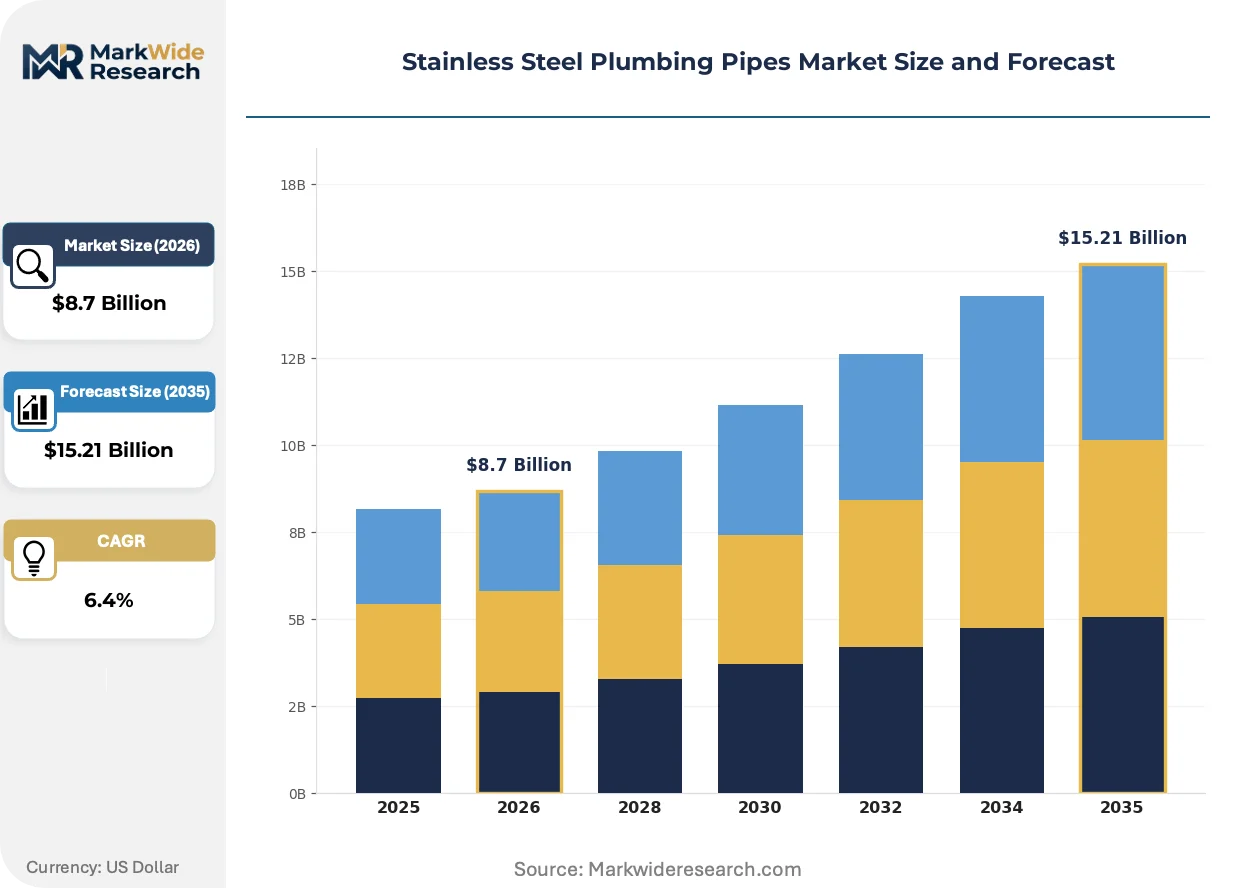
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless Pipes, Welded Pipes, Cold Drawn Pipes, Hot Finished Pipes Application: Water Supply, Drainage Systems, Gas Supply, HVAC Systems End User: Residential, Commercial, Industrial, Construction Grade: Grade 304, Grade 316, Grade 321, Grade 430 |
| Companies Covered | Mueller Industries, Geberit AG, Jindal Stainless Limited, Central States Industrial, Steelmor Industries, Uponor Corporation, Reliance Worldwide Corporation, NIBCO Inc., Viega LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Plumbing Pipes Market Emerging Trajectories
Mechanical joining technologies and alloy specification standards are converging to reshape procurement patterns across commercial construction and municipal infrastructure sectors.
Press-fit connection systems are unifying piping installation workflows by eliminating brazing and welding requirements. Mechanical contractors in healthcare and hospitality verticals are adopting these systems at accelerating rates. This unification is compressing project timelines and reducing skilled trade dependencies that previously constrained stainless steel specification.
REACH nickel leaching restrictions in Europe are tightening material composition thresholds for potable water contact. Fabricators must now certify low-carbon 316L variants through extended migration testing protocols. German specification markets are responding fastest, with Viega and Geberit anchoring compliant distribution networks.
Building information modeling is embedding material specifications earlier in project development cycles. Architects in California and Florida are specifying chloride-resistant alloys during schematic design phases, displacing value-engineering substitutions that previously occurred during construction documentation. This front-loading is most visible in coastal commercial towers where marine exposure accelerates corrosion failure risks.
Stainless Steel Plumbing Pipes Market Segmentation
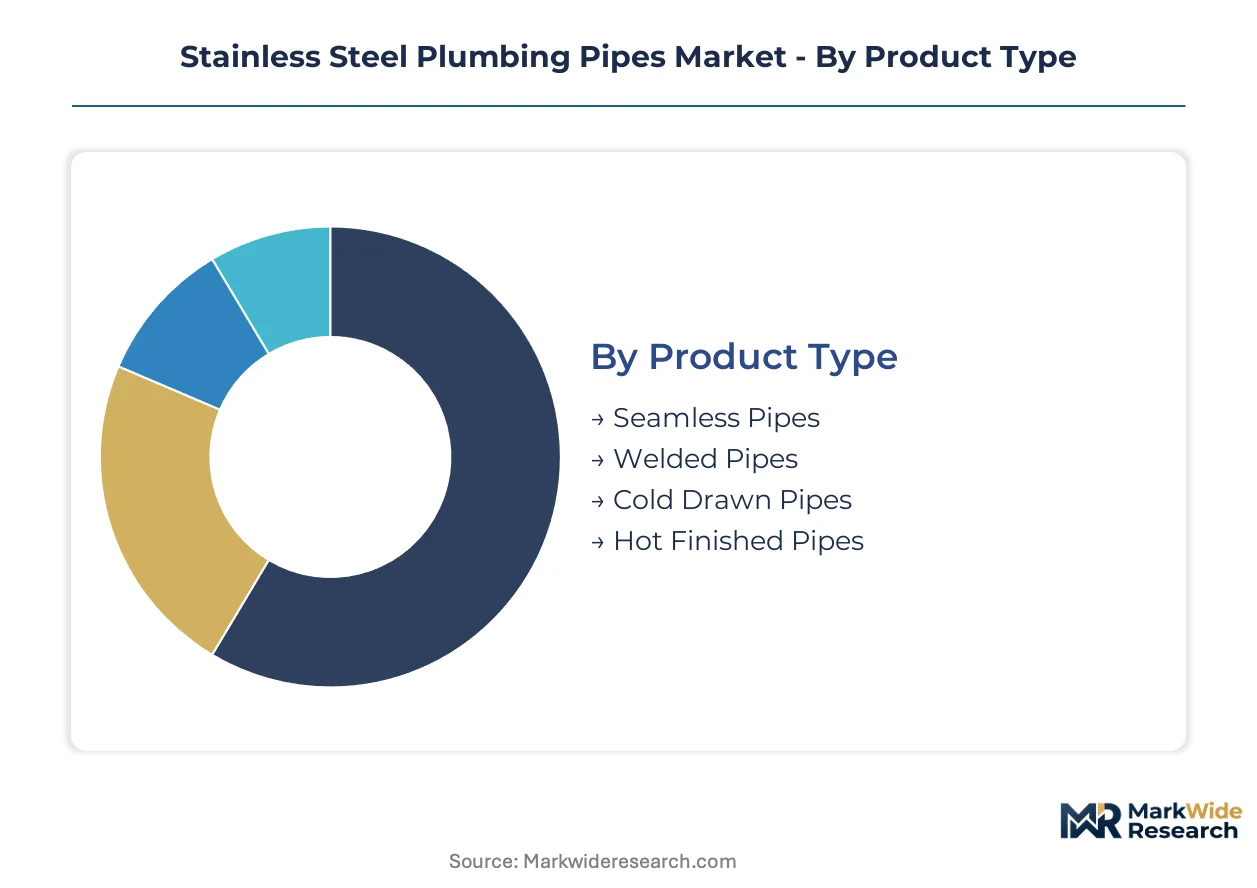
Stainless steel plumbing pipes fragment across four critical dimensions that determine specification pathways, certification requirements, and margin structures. Product type and grade specifications govern corrosion resistance and pressure ratings, while application context and end-user category dictate procurement volume and contract terms. Understanding these intersections allows suppliers to align fabrication capacity with the highest-value specification channels.
Product Type:
Customization intensity spans from commodity welded configurations to precision seamless piercing, with cost tier and performance tier diverging sharply across the spectrum.
- Seamless Pipes:Formed through rotary piercing and extrusion without longitudinal welds, delivering uniform circumferential strength for high-pressure process lines. Demand concentrates in German industrial corridors and Japanese chemical facilities where burst-pressure specifications exceed 10,000 psi; alloy surcharge volatility compresses margins for non-integrated mills lacking captive melt shops.
- Welded Pipes:Produced via electric resistance welding or TIG fusion of coiled strip, dominating residential water supply volumes through lower unit economics. Municipal procurement in EPA-mandated replacement zones across the United States anchors specification-grade volume for NSF/ANSI 61-certified welded product.
- Cold Drawn Pipes:Post-weld or post-extrusion dimensional refinement for tight-tolerance instrumentation lines.
- Hot Finished Pipes:Mill-direct sizing for structural and general plumbing applications with relaxed dimensional tolerances.
Most installed capacity flows through welded pipe mills serving municipal and residential channels. Expansion is steepest in seamless configurations for industrial process applications.
Application:
Corrosion exposure severity and pressure cycling frequency stratify demand across building service categories, with coastal and healthcare environments commanding premium alloy specifications.
- Water Supply:Pressurized potable distribution networks requiring NSF/ANSI 61 or equivalent drinking water contact certification. EPA lead-and-copper rule revisions across the United States are accelerating specification shifts toward certified stainless alternatives in municipal retrofit programs.
- HVAC Systems:Chilled water, steam, and refrigerant conveyance with chloride exposure risks in coastal installations. Florida and California commercial towers specify Grade 316 with molybdenum enhancement to resist pitting from marine atmospheric corrosion.
- Drainage Systems:Gravity-flow sanitary and stormwater discharge with lower pressure requirements but chemical exposure considerations.
- Gas Supply:Natural gas and medical gas distribution with leak-tight jointing mandates and fire safety protocols.
Water supply applications absorb the largest share of welded pipe volume. HVAC systems are gaining share fastest as coastal construction intensifies and press-fit adoption accelerates.
End User:
Procurement sophistication and specification authority vary dramatically, with industrial buyers leveraging metallurgical expertise and residential channels deferring to contractor preferences.
- Commercial:Class A office towers, healthcare facilities, and hospitality properties with extended design lifecycles and fire-sensitivity constraints. Germany's industrial corridor anchors specification-grade demand for press-fit systems with integrated tooling ecosystems.
- Industrial:Chemical processing, food and beverage, and pharmaceutical manufacturing with process-critical hygiene and pressure requirements. Japanese and German chemical clusters specify seamless Grade 316L for high-purity steam and solvent lines.
- Residential:Single-family and multi-family housing with cost-driven substitution between copper, PEX, and stainless alternatives.
- Construction:Mixed-use developments and infrastructure projects with phased specification authority across design and build contractors.
Commercial end users command the highest premium per linear foot through specification-grade system integration. Industrial procurement is climbing the fastest as process hygiene standards tighten globally.
Grade:
Alloy composition determines corrosion resistance hierarchy, with chromium-nickel-molybdenum ratios stratifying price points and geographic specification patterns.
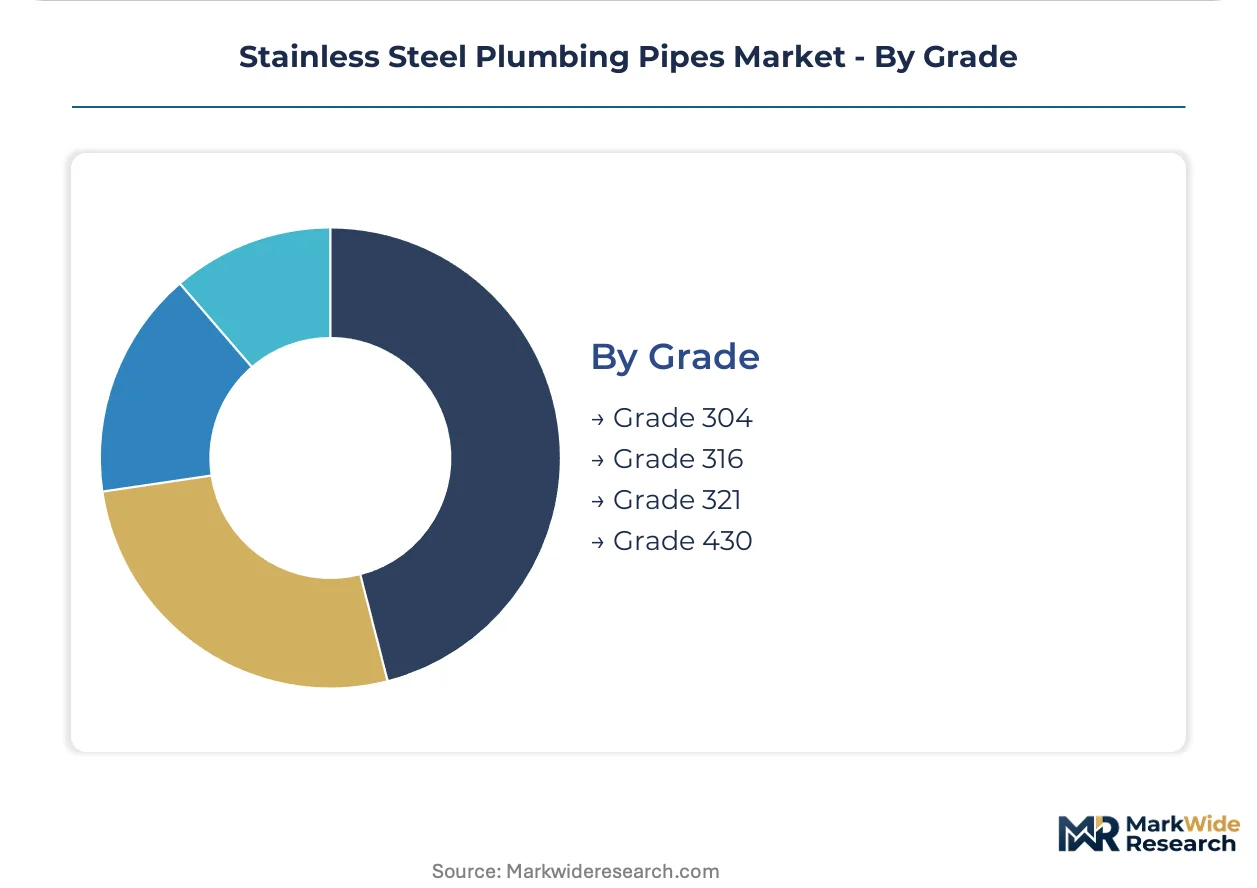
- Grade 316:Austenitic alloy with 2-3% molybdenum addition for chloride pitting resistance, commanding premium positioning in marine-adjacent HVAC and coastal drainage. EU Drinking Water Directive nickel leaching thresholds favor low-carbon 316L variants with vacuum oxygen decarburization certification.
- Grade 304:Standard 18/8 austenitic composition dominating volume production for interior water supply and non-corrosive environments. Indian integrated mills sustain cost-competitive supply through captive melt-to-pipe operations serving domestic infrastructure programs.
- Grade 321:Titanium-stabilized variant for high-temperature service and weld decay resistance in exhaust and process heat applications.
- Grade 430:Ferritic alloy with lower nickel content for cost-sensitive decorative and non-pressurized drainage applications.
Grade 304 retains the dominant share of tonnage shipped. Grade 316 is expanding most quickly as coastal construction codes harden and REACH nickel restrictions tighten European specification thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled press-fit technician networks concentrate most densely in Germany's industrial corridor, where Viega and Geberit anchor specification-grade distribution ecosystems that lock contractors into proprietary tooling requirements.
United States
EPA lead-and-copper rule revisions are forcing municipal water infrastructure upgrades across California, Texas, and the Great Lakes states. NSF/ANSI 61 certification governs potable water contact safety, compressing specification cycles for corrosion-resistant piping systems. Mueller Industries leverages captive brass-to-stainless conversion capacity to anchor North American specification channels.
Germany
REACH nickel leaching restrictions tighten material composition thresholds for potable water contact across Bavaria and North Rhine-Westphalia. The EU Drinking Water Directive favors low-carbon 316L variants with vacuum oxygen decarburization certification. Viega and Geberit anchor compliant distribution networks in the country's industrial corridor.
India
Jindal Stainless Limited sustains cost-competitive hot-rolled coil supply through integrated melt-to-pipe operations serving domestic infrastructure programs. BIS standards mandate dimensional interoperability for press-fit connections. Maharashtra and Gujarat industrial clusters absorb the largest share of Grade 304 tonnage shipped for non-corrosive interior water supply applications.
Japan
Japanese chemical facilities in the Chubu and Kansai regions specify seamless Grade 316L for high-purity steam and solvent lines requiring burst-pressure specifications exceeding 10,000 psi. METI industrial standards govern process-critical hygiene requirements. Limited global capacity for large-diameter seamless piercing operations concentrates high-pressure industrial supply among specialized domestic mills.
China
GB/T 19228 series mandates dimensional interoperability for press-fit connections that foreign manufacturers must satisfy for project eligibility in coastal provinces. The Yangtze River Delta and Pearl River Delta construction markets specify chloride-resistant alloys during schematic design phases. Marine-adjacent installations expose standard 304 alloys to accelerated pitting, opening premium positioning for molybdenum-enhanced alternatives.
Stainless Steel Plumbing Pipes Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered vendor base that fragments by fabrication technology and geographic supply base. Consolidation pressure concentrates among seamless pipe producers lacking captive melt shops, while welded pipe capacity expands more broadly. Three archetypes dominate: integrated mills controlling upstream coil supply, specification-grade system integrators with proprietary press-fit ecosystems, and regional fabricators serving cost-sensitive municipal procurement. Capacity expansion and strategic partnerships represent the dominant competitive moves as alloy surcharge volatility compresses margins.
Among North American fabricators, Mueller Industries exemplifies the integrated mill archetype with captive brass-to-stainless conversion capabilities. Geberit AG and Viega LLC occupy positions within the specification-grade system integrator tier, anchoring proprietary press-fit tooling ecosystems that lock contractors into compliant installation networks. Jindal Stainless Limited represents the scale-driven integrated producer model through melt-to-pipe operations in India.
| Leading Market Players |
|---|
| Mueller Industries |
| Geberit AG |
| Jindal Stainless Limited |
| Central States Industrial |
| Steelmor Industries |
| Uponor Corporation |
| Reliance Worldwide Corporation |
| NIBCO Inc. |
| Viega LLC |
| Others |
Supply Flow & Price Mechanics
Skilled press-fit technician networks in Germany's industrial corridor widen pricing-tier spreads between specification-grade system bundles and commodity welded pipe transactions. Labor-cost differentials between certified installer markets and general plumbing contractor regions compress margins on unbundled product sales while amplifying premium capture for integrated tooling ecosystems.
Pricing Analysis
Bundled press-fit system packages versus unbundled pipe-only sales define the pricing architecture. Three-tier pricing structure across premium specification-grade, standard certified-welded, and economy non-certified levels separates NSF/ANSI 61-certified product from commodity alternatives. Price differentiation hinges on certification tier and after-sales service depth. Cost compression in economy welded segments is intensifying because Indian integrated mills flood residential channels with captive melt-shop output. Municipal procurement teams exhibit highest price sensitivity; German commercial specifiers show lowest.
Supply Chain Analysis
Domestic-content mandates in India's infrastructure programs and China's GB/T 19228 series are reshaping sourcing patterns for foreign manufacturers seeking project eligibility. Geographic supply concentrates in India, China, and Germany. Raw material flows draw from nickel ore processing in Indonesia, ferrochrome smelting in South Africa, and scrap stainless recovery in European mills. Single-source vulnerability in large-diameter seamless piercing capacity threatens industrial project timelines. Distribution runs through specification-grade distributors in developed markets and direct mill relationships in cost-sensitive regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA lead-and-copper rule revisions force municipal infrastructure replacement cycles that sustain demand visibility regardless of construction cyclicality.
For Market Incumbents: Hedge alloy surcharge exposure through captive melt-shop ownership or long-term nickel offtake agreements. Lock contractor ecosystems via proprietary press-fit tooling certification programs that raise switching costs. Copper piping substitution in residential segments and seamless pipe supply concentration in Germany and Japan threaten margin stability; vertical integration into hot-rolled coil supply anchors cost competitiveness. For New Entrants and Emerging Players: Launch via digital specification platforms that embed product geometries into building information modeling workflows before schematic design phases. Target coastal HVAC retrofit channels in Florida and California where chloride corrosion accelerates Grade 316 specification upgrades ahead of incumbent sales coverage. White-space exists in certified press-fit technician training networks across Texas and the Great Lakes states. For Investors and Strategic Acquirers: Building products conglomerates with plumbing fixture portfolios are the most active acquirer in this space, seeking specification-grade pipe assets that complete system offerings. Long-term viability rests on regulatory tailwinds from drinking water safety mandates that outlast construction cyclicality. Acquire seamless pipe mills with vacuum oxygen decarburization capability for 316L certification. Monitor nickel price volatility indices as inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hot-Rolled Coil Supply | Captive melt-shop ownership insulates margins from LME nickel volatility that destabilizes project bidding. |
| Press-Fit Technician Certification Network Expansion | Proprietary installer ecosystems lock contractors into Geberit and Viega tooling specifications across German commercial markets. |
| NSF/ANSI 61 Certification Investment | Potable water contact safety approval unlocks EPA-mandated municipal replacement procurement in California and Texas. |
| Digital Specification Platform Development | BIM-embedded product geometries displace value-engineering substitutions during California coastal tower schematic phases. |
| Long-Term Nickel Offtake Agreement | Fixed-price raw material supply stabilizes input cost structures for seamless pipe producers serving Japanese chemical facilities. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from municipal procurement officers, mechanical contracting executives, specification-grade distributor principals, and metallurgical engineers at integrated mills. Secondary validation drew from EPA enforcement action databases, NSF/ANSI certification registries, customs trade flow records, and SEC filings of publicly traded pipe manufacturers. Bottom-up volume modeling and top-down macroeconomic anchoring triangulated demand estimates.
Segment-weighting approaches distributed value across product type, grade specification, application context, and end-user category. The analytical framework projected volume and value across the analysis window by modeling welded versus seamless pipe splits, Grade 304 versus 316 alloy shares, and commercial versus industrial versus residential procurement patterns. CAGRs derived from historical trajectory analysis and regulatory mandate timing. Forecast inputs incorporated EPA lead-and-copper rule implementation schedules and REACH nickel leaching threshold revisions.
Several conditions sit outside the modeled scope, including extreme nickel price volatility scenarios beyond historical bands, trade policy disruptions affecting coil supply flows, and breakthrough substitution technologies in potable water conveyance. Forecasts reflect documented assumptions about regulatory enforcement continuity and certification timeline norms. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Saudi Arabia PVC Pipes Market
Pipes and Tubes
Compressed Air Pipe Market
Pipes and Tubes
Polyethylene Pipes Market
Pipes and Tubes
Gathering Pipeline Market
Pipes and Tubes
United States Copper Pipes and Tubes Market
Pipes and Tubes
GRP Pipe Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
Aluminum Pipe Market
Pipes and Tubes
Copper Tube Market
Pipes and Tubes
Cryogenic Pipes Market
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market
Pipes and Tubes
Plastic Pipe Jointing and Welding Market
Pipes and Tubes
Metal Pipe Market
Pipes and Tubes
Coiled Tubing Manufacturing Market
Pipes and Tubes
Galvanized Steel Tubes Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market