
 United Kingdom Digital Health Market | 2026-2036
United Kingdom Digital Health Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Digital Health Market Analytics
The UK Medical Devices Regulations 2002 (as amended) is broadening compliance obligations for AI-enabled diagnostic platforms entering the National Health Service supply chain. EMIS Health leverages its installed base across NHS primary care networks to sustain long-term contracts. TPP anchors its position through deep integration with the NHS Spine infrastructure. Oracle Health competes by extending enterprise-grade cloud architecture into acute trust environments.
Digital health encompasses software-driven systems, connected hardware, and data analytics platforms engineered to deliver, manage, or augment medical care and wellness services. These technologies incorporate interoperability standards such as HL7 FHIR, process real-time biometric streams, and serve to reduce clinical workload while improving patient outcomes. Telemedicine and remote patient monitoring command the largest revenue pools as NHS backlog reduction drives video consultation and home-based vital sign tracking. Artificial Intelligence within the technology dimension attracts concentrated R&D investment as trusts pilot diagnostic imaging algorithms and clinical decision support tools.
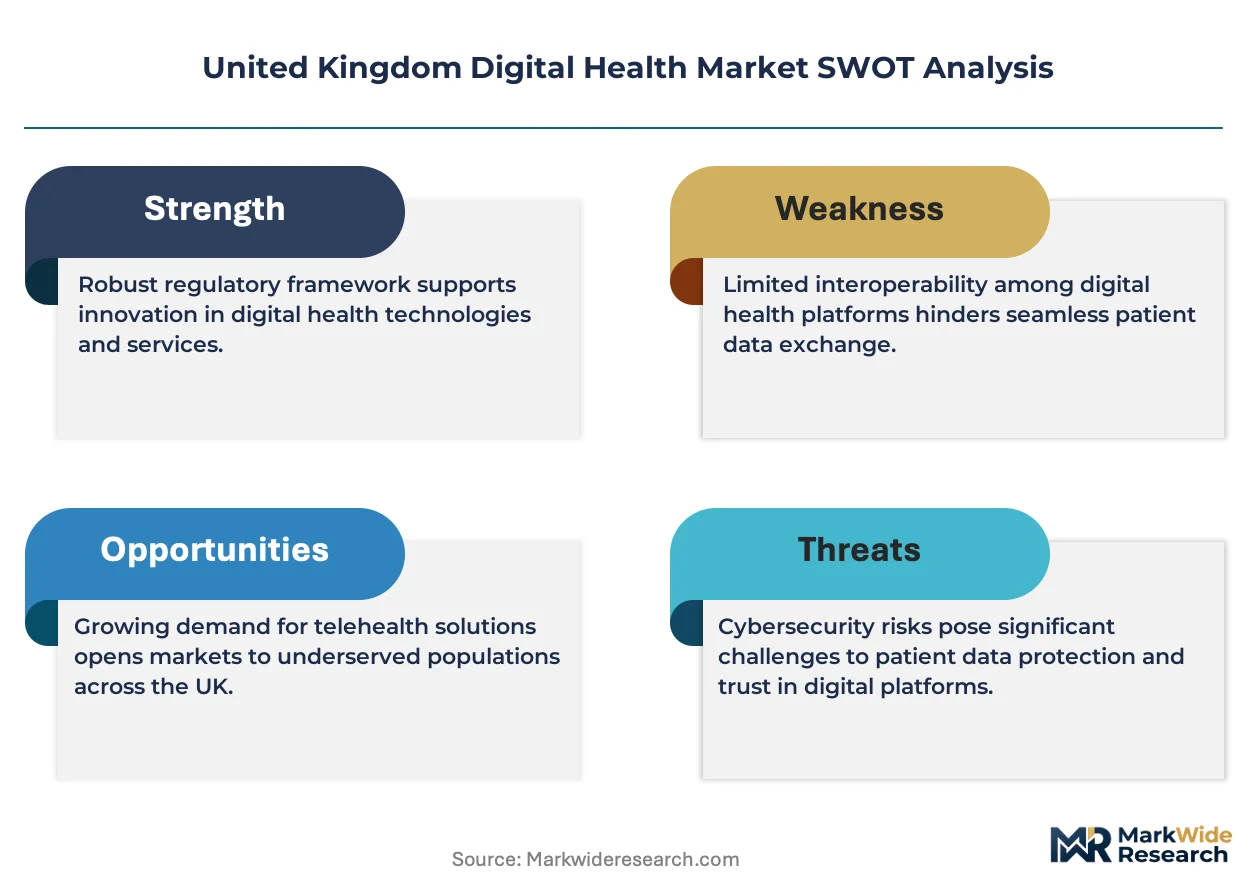
The Medicines and Healthcare products Regulatory Agency governs software-as-medical-device classifications, while NHS Digital sets interoperability and data security mandates that determine market access for platform vendors. The Care Quality Commission inspects digital service providers against safety standards, creating a layered approval environment that filters entrants by compliance maturity. Stakeholders must weigh regulatory trajectory against deployment speed when calibrating product roadmaps for the NHS procurement cycle.
Market Dynamics
NHS backlog reduction mandates are compressing procurement cycles for remote patient monitoring platforms, forcing vendors to accelerate MHRA software-as-medical-device certifications while maintaining interoperability with legacy EMIS and TPP installations.
Growth Catalysts
- NHS Long Term Workforce Plan:The 2023 framework mandates technology adoption to offset clinical staffing shortfalls, directly funding telemedicine infrastructure across integrated care systems.
- MHRA Software Guidance Updates:Streamlined classification pathways for AI diagnostic tools reduce time-to-market for algorithm developers targeting NHS supply chains.
- Greater Manchester Health Innovation Cluster:Concentrated R&D tax incentives and test-bed facilities attract digital health startups piloting biometric monitoring wearables.
Market Restraints
- Interoperability Fragmentation:Proprietary data formats between EMIS, TPP, and Oracle Health platforms force costly integration middleware development.
- Cybersecurity Compliance Burden:NHS Digital Data Security and Protection Toolkit requirements consume 18-24 month implementation timelines for new entrants.
- Clinical Validation Costs:Health Technology Assessment pathways through NICE demand extensive real-world evidence generation before reimbursement approval.
Strategic Opportunities
- Integrated Care System Consolidation:42 ICS structures create procurement scale for population health analytics platforms spanning multiple trusts.
- Social Care Technology Fund:Department of Health and Social Care allocations for domiciliary care monitoring expand addressable market beyond acute settings.
- FHIR R4 Mandate:NHS England interoperability standards create replacement demand for legacy HL7 v2 systems in community pharmacy networks.
Industry Challenges
- Clinical Informatics Talent Scarcity:NHS digital academies cannot produce sufficient data scientists fluent in both healthcare workflows and FHIR implementation.
- Legacy Spine Integration:New platforms must maintain bidirectional synchronization with NHS Spine demographics and prescribing data, extending development sprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Digital Health Market |
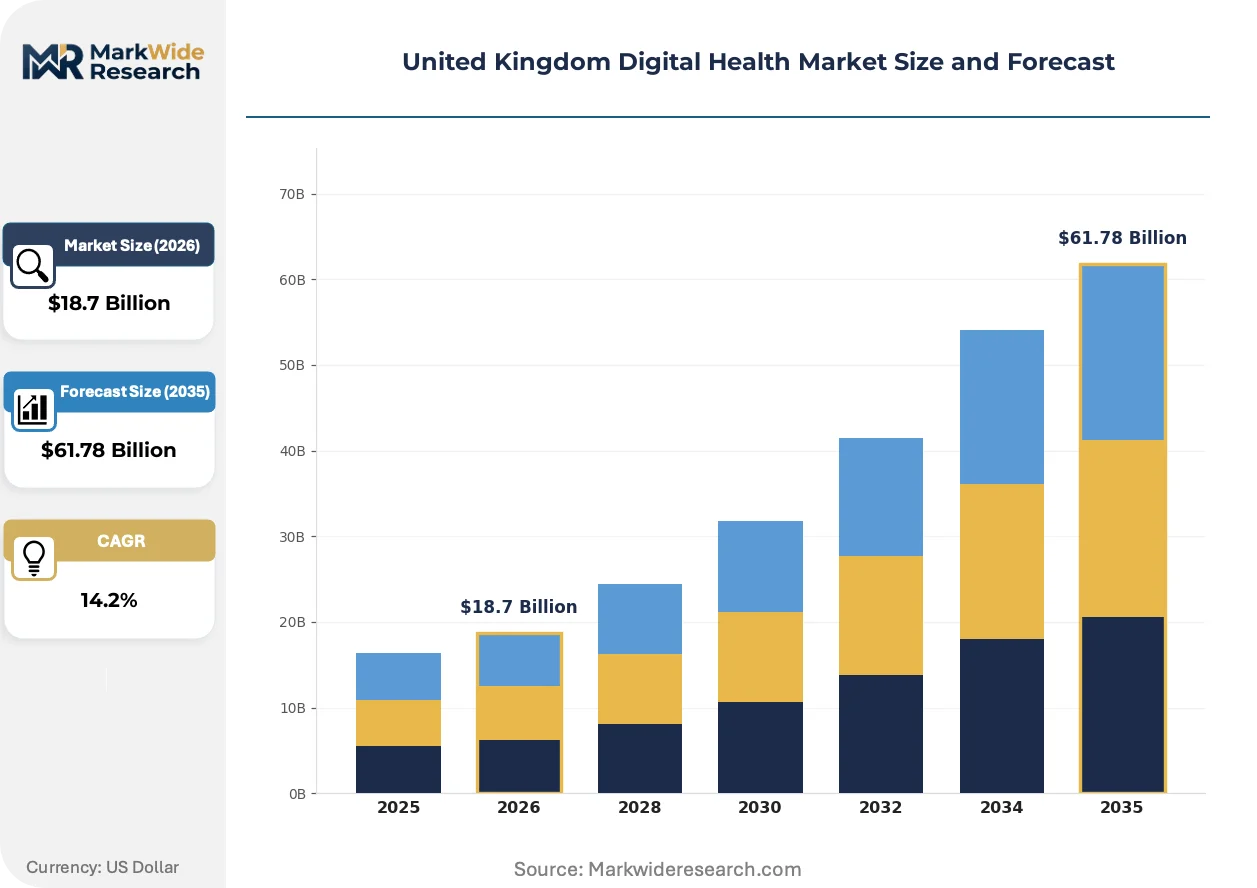
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telemedicine, Mobile Health Apps, Wearable Devices, Remote Patient Monitoring Technology: Artificial Intelligence, Cloud Computing, Blockchain, Internet of Things End User: Hospitals, Clinics, Insurance Providers, Patients Application: Chronic Disease Management, Mental Health Support, Wellness Monitoring, Rehabilitation |
| Companies Covered | EMIS Health, TPP, Oracle Health, Epic Systems, Alcidion, Babylon Health, Livi, Doccla, Graphnet Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Digital Health Market Evolving Landscape
Artificial intelligence diagnostic tools are absorbing regulatory scrutiny and clinical validation resources, reshaping how vendors sequence product roadmaps for NHS entry. Three developments are compressing competitive timelines.
Machine learning algorithms for radiology and pathology are absorbing the majority of MHRA pre-market consultation hours. Acute trusts in London and Manchester are piloting chest X-ray and dermatology classifiers under clinical safety oversight. This concentration is absorbing venture funding that previously flowed into administrative automation, narrowing the field of well-capitalized diagnostic developers.
The Medicines and Healthcare products Regulatory Agency's 2024 software-as-medical-device guidance introduces predicate device requirements for AI updates. Developers must now submit change control protocols for model retraining cycles. Imaging algorithm vendors are responding by freezing model versions for 12-month intervals, trading performance drift for regulatory predictability.
Trust procurement teams are consolidating vendor relationships around integrated platform suites rather than point solutions. Category managers at NHS Supply Chain are bundling telemedicine, remote monitoring, and analytics under single-framework agreements. This preference concentration is most visible in the South East and Midlands ICS regions, where Oracle Health and EMIS are capturing multi-year enterprise contracts.
United Kingdom Digital Health Market Segmentation
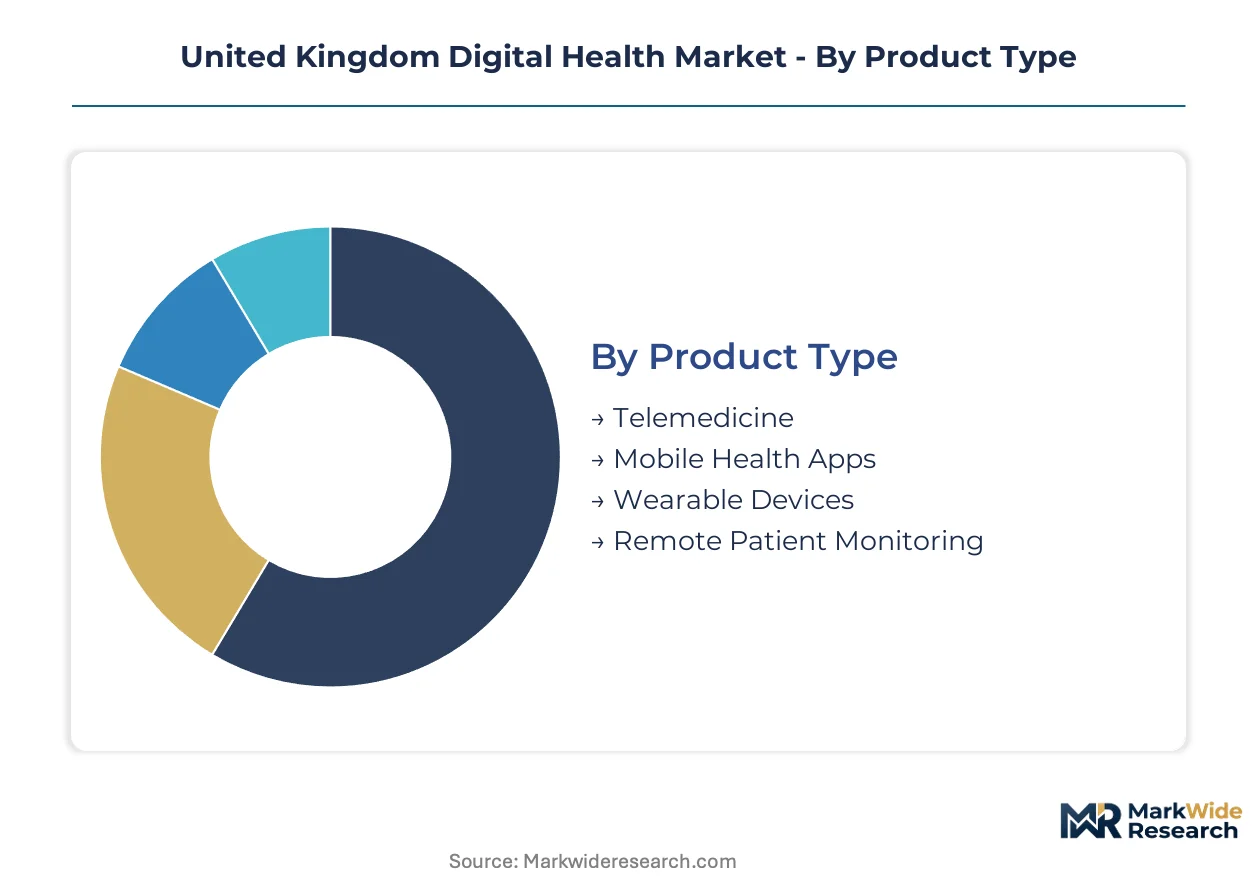
NHS procurement frameworks segment digital health offerings by integration depth, with standalone solutions commanding different pricing and compliance pathways than embedded systems. Understanding these divisions clarifies where vendors must build interoperability layers versus where point solutions retain viability.
Product Type:
Standalone platforms operate at the EMR periphery, while embedded modules require deep Spine integration and longer sales cycles.
- Telemedicine:Video consultation infrastructure processes encrypted patient-provider sessions through NHS-approved hosting environments. Demand concentrates in London ICS trusts seeking backlog reduction; MHRA software-as-medical-device classification timelines constrain vendor onboarding speed.
- Remote Patient Monitoring:Biometric sensor networks stream vital signs to clinical dashboards for triage and intervention. Greater Manchester health innovation clusters pilot hypertension and COPD monitoring at scale; NICE health technology assessment pathways determine reimbursement eligibility.
- Mobile Health Apps:Patient-facing applications deliver medication adherence prompts and symptom tracking through iOS and Android distribution.
- Wearable Devices:Consumer-grade and medical-grade sensors capture continuous physiological data for clinical review.
Volume placements concentrate in Remote Patient Monitoring; the faster expansion belongs to Telemedicine.
Technology:
Cost tiers separate enterprise-grade infrastructure from emerging protocols still seeking clinical validation and trust procurement approval.
- Artificial Intelligence:Machine learning models classify diagnostic images and predict patient deterioration risk from electronic health record signals. Acute trusts in London deploy chest X-ray and dermatology algorithms under clinical safety oversight; MHRA predicate device requirements for model updates freeze development cycles at 12-month intervals.
- Cloud Computing:Scalable hosting architectures process patient data across distributed NHS Digital-approved data centers. Oracle Health and EMIS compete for enterprise contracts in South East and Midlands ICS regions; NHS Digital Data Security and Protection Toolkit compliance consumes 18-24 month implementation timelines.
- Internet of Things:Connected sensor networks enable real-time biometric streaming from home and community settings.
- Blockchain:Distributed ledger technologies pilot patient consent management and pharmaceutical supply chain traceability.
Enterprise contract value clusters in Cloud Computing; the steepest expansion trajectory sits with Artificial Intelligence.
End User:
Customer type determines procurement pathway complexity, with NHS entities requiring framework compliance and private channels permitting faster deployment.
- Hospitals:Acute trusts purchase enterprise platforms for diagnostic imaging, clinical decision support, and patient flow optimization. TPP and Oracle Health capture multi-year contracts through deep EMR integration; legacy Spine synchronization requirements extend vendor development sprints.
- Clinics:Primary care networks procure telemedicine and remote monitoring for chronic disease cohort management. EMIS Health leverages installed base across NHS primary care networks; the 2023 NHS Long Term Workforce Plan mandates technology adoption to offset clinical staffing shortfalls.
- Patients:Direct-to-consumer channels bypass NHS procurement for wellness and mental health applications.
- Insurance Providers:Private payers fund preventive monitoring and rehabilitation programs for policyholder risk reduction.
Procurement volume favors Hospitals; the fastest share gain is occurring in Clinics.
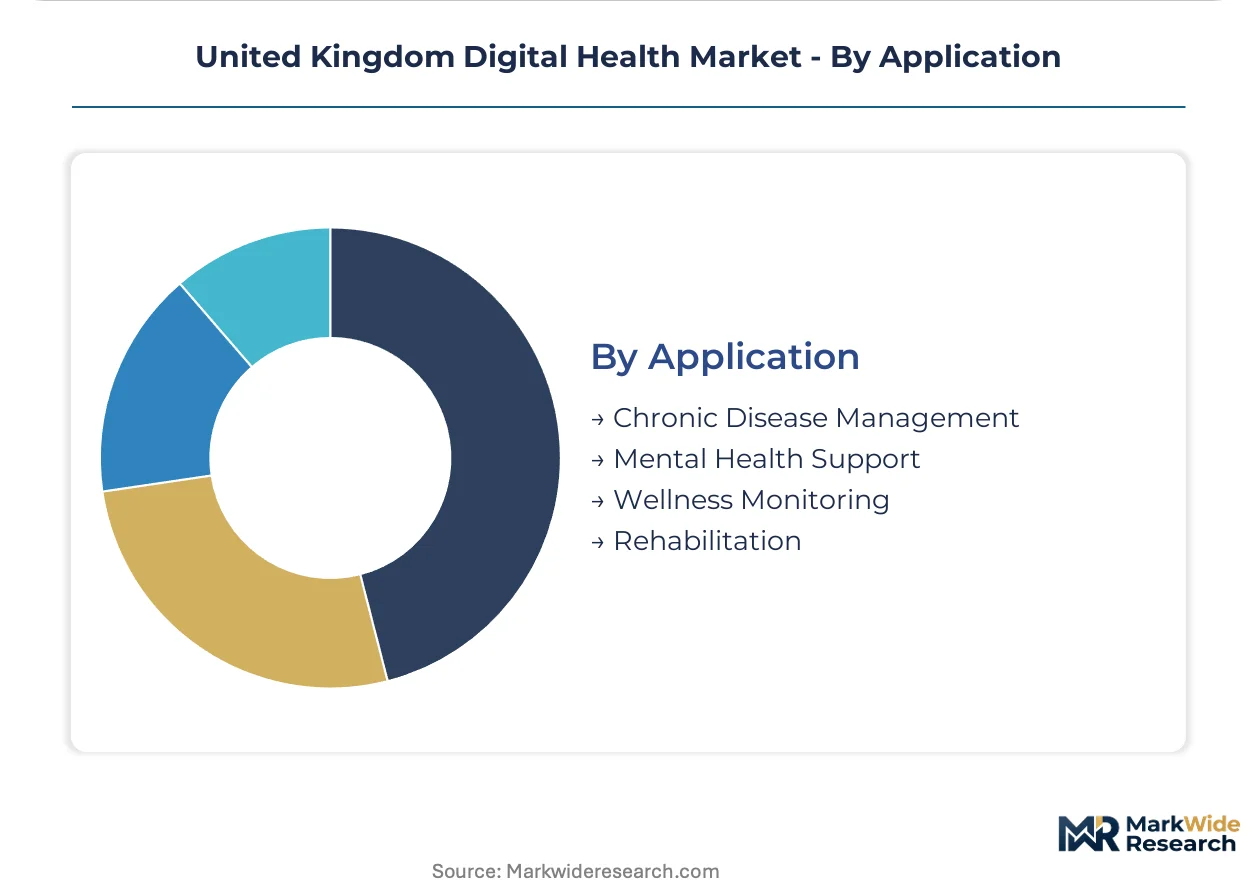
Application:
Maturity levels separate established reimbursement pathways from emerging categories still building clinical evidence bases.
- Chronic Disease Management:Integrated platforms coordinate diabetes, cardiovascular, and respiratory care across primary and secondary settings. NHS England interoperability standards create replacement demand for legacy HL7 v2 systems; FHIR R4 mandates drive community pharmacy network upgrades.
- Mental Health Support:Digital therapeutics and crisis intervention tools address workforce shortages in psychological services. Social Care Technology Fund allocations expand addressable market beyond acute settings into domiciliary care monitoring.
- Wellness Monitoring:Preventive health tracking targets lifestyle modification and early risk detection.
- Rehabilitation:Remote physiotherapy and post-surgical recovery tools support patient discharge and home-based recovery.
Reimbursement stability anchors Chronic Disease Management; the quickest climb belongs to Mental Health Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Manchester Health Innovation Zone tax incentives concentrate digital health R&D investment, drawing biometric monitoring startups and clinical trial networks into purpose-built test-bed facilities.
London and the Southeast
Acute trusts in London deploy AI diagnostic imaging algorithms for chest X-ray and dermatology classification under MHRA clinical safety oversight. NHS England Long Term Plan funding streams prioritize video consultation infrastructure for backlog reduction across integrated care systems. The Golden Triangle research corridor spanning London, Oxford and Cambridge anchors health-tech venture capital flows and university spinout formation.
Midlands
Integrated care system consolidation across 42 structures creates procurement scale for population health analytics platforms spanning multiple trusts. Oracle Health and EMIS compete for multi-year enterprise contracts through deep EMR integration and cloud architecture deployment. Birmingham health innovation partnerships pilot remote patient monitoring for chronic disease cohorts with NICE health technology assessment pathway alignment.
North England
Greater Manchester Health Innovation Zone R&D tax incentives attract digital health startups piloting hypertension and COPD biometric monitoring at scale. The Department of Health and Social Care Social Care Technology Fund expands addressable market into domiciliary care monitoring beyond acute settings. Leeds and Sheffield anchor northern health-tech clusters with NHS Digital-approved data center proximity.
Scotland
NHS Scotland digital strategy mandates accelerate telemedicine adoption for rural and island community access. The Scottish Government health innovation funding supports remote patient monitoring pilots for cardiovascular and respiratory conditions. Edinburgh and Glasgow university hospitals anchor AI diagnostic tool validation partnerships with MHRA regulatory pathway alignment.
Wales
Welsh Government digital health investment prioritizes community pharmacy network FHIR R4 interoperability upgrades from legacy HL7 v2 systems. NHS Wales informatics infrastructure supports remote consultation platforms for geographically dispersed populations. Cardiff and Swansea health board procurement concentrates on integrated care system analytics for population health management.
United Kingdom Digital Health Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across NHS procurement frameworks, creating a tiered vendor structure segmented by integration depth and compliance maturity. EMR-embedded platforms command longer sales cycles but sustain multi-year contracts through Spine infrastructure synchronization. Three archetypes dominate: legacy EMR vendors with installed base leverage, cloud-native challengers with interoperability-first architectures, and point-solution specialists targeting clinical workflow gaps. Competitive moves center on framework consolidation bidding and MHRA software-as-medical-device certification acceleration.
Within the legacy-installed-base tier, EMIS Health and TPP occupy positions sustained through deep NHS primary care network penetration and Spine infrastructure integration. Oracle Health exemplifies the cloud-native challenger archetype extending enterprise-grade architecture into acute trust environments. Babylon Health represents the point-solution specialist model targeting direct-to-consumer and NHS-contracted telemedicine channels.
| Leading Market Players |
|---|
| EMIS Health |
| TPP |
| Oracle Health |
| Epic Systems |
| Alcidion |
| Babylon Health |
| Livi |
| Doccla |
| Graphnet Health |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialists consolidating NHS digital health procurement are compressing vendor margins while extending payment terms to platform developers, embedding supply chain leverage directly into contract pricing structures. This ownership pattern concentrates purchasing power across integrated care systems, forcing software vendors to absorb integration costs upfront in exchange for multi-year framework access.
Pricing Analysis
Short lead-time deployments command premium pricing as NHS trusts accelerate backlog reduction procurement under MHRA software-as-medical-device deadlines. SaaS-tiered subscription models dominate, with pricing stratifying across enterprise-grade EMR integration, mid-tier interoperability modules, and economy standalone telemedicine licenses. Cost compression in the economy tier intensifies because new entrants flood point-solution telemedicine; primary care networks remain most price-sensitive while acute trusts prioritize integration depth over unit cost.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data centers in Ireland, Germany, and the UK meeting NHS Digital Data Security and Protection Toolkit requirements. Biometric sensor hardware draws from Taiwanese OEMs, Chinese component assemblers, and Nordic semiconductor designers. Single-source vulnerability concentrates in Spine integration middleware where EMIS and TPP proprietary protocols lock switching costs. Distribution runs through NHS Supply Chain framework agreements and direct trust procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with pre-certified MHRA software-as-medical-device portfolios, forcing undercapitalized point-solution developers toward distressed exits or acquisition.
For Market Incumbents: Acquire clinical informatics talent pools to offset NHS digital academy output shortfalls. Deepen Spine infrastructure synchronization capabilities to extend switching-cost moats against Oracle Health cloud-native challenges. Prioritize FHIR R4 certification investment ahead of NHS England interoperability mandates to capture community pharmacy network replacement demand.
For New Entrants and Emerging Players: Direct-to-clinic digital channels bypass NHS Supply Chain procurement complexity for faster revenue traction. Target Greater Manchester Health Innovation Zone pilot programs as the most penetrable entry point, leveraging R&D tax incentives and test-bed facilities. Position around AI diagnostic imaging niches with frozen 12-month model versions to satisfy MHRA predicate device requirements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor MHRA pre-certified software-as-medical-device developers in Greater Manchester and London clusters with proven trust pilot contracts. Long-term viability over a five-to-ten year window hinges on embedded EMR integration depth rather than standalone feature velocity. Watch NICE health technology assessment reimbursement approvals as the primary inflection signal for platform scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| MHRA Software-as-Medical-Device Certification | Unlocks NHS procurement framework eligibility and accelerates trust sales cycles. |
| Spine Infrastructure Integration | Creates bidirectional data synchronization with NHS demographics and prescribing systems. |
| FHIR R4 Interoperability Development | Positions vendors for NHS England-mandated legacy HL7 v2 replacement contracts. |
| Integrated Care System Partnership | Captures multi-trust procurement scale across 42 ICS population health analytics tenders. |
| AI Diagnostic Imaging Validation | Secures clinical safety oversight for radiology and pathology algorithm deployment. |
Research Methodology
Independent corroboration across NHS Digital procurement databases, MHRA software-as-medical-device registration filings, and integrated care system tender records underwrites the qualitative findings. Primary interviews with NHS trust chief information officers, MHRA regulatory affairs specialists, and digital health platform product directors combined with secondary validation from hospital procurement databases, GPO contracts, and Care Quality Commission inspection reports. Bottom-up vendor revenue estimates triangulated against top-down NHS England technology spending allocations.
Comparable-period anchoring tied projection windows to historical NHS Long Term Plan funding disbursement patterns and workforce mandate implementation phases. Segmentation modeling spanned product type, technology layer, end-user archetype, and application maturity across the projection horizon. CAGRs derived from spline-interpolated adoption curves weighted by MHRA certification timeline acceleration and ICS consolidation procurement velocity. Forecast inputs incorporated NICE health technology assessment pathway throughput and Social Care Technology Fund allocation trajectories.
The model holds under sustained NHS backlog reduction funding and stable MHRA regulatory pathway timelines; deviation in integrated care system merger activity or AI diagnostic safety incidents would shift vendor share trajectories. A small set of triggers—NICE reimbursement rulings, FHIR R4 mandate enforcement dates, and cybersecurity incident disclosures—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
VR in Healthcare Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Vaccine Management Software Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
Care Coordination Software Market
Digital Health Solutions
US Real World Evidence Solutions Market
Digital Health Solutions
Digiceuticals Market
Digital Health Solutions
Long Term Post-Acute Care Software Market
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Patient Case Management Software Market
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Global Physical Therapy Software Market