
 Europe Digital Therapeutic (Dtx) Market | 2026-2036
Europe Digital Therapeutic (Dtx) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Therapeutic (Dtx) Market Foresight
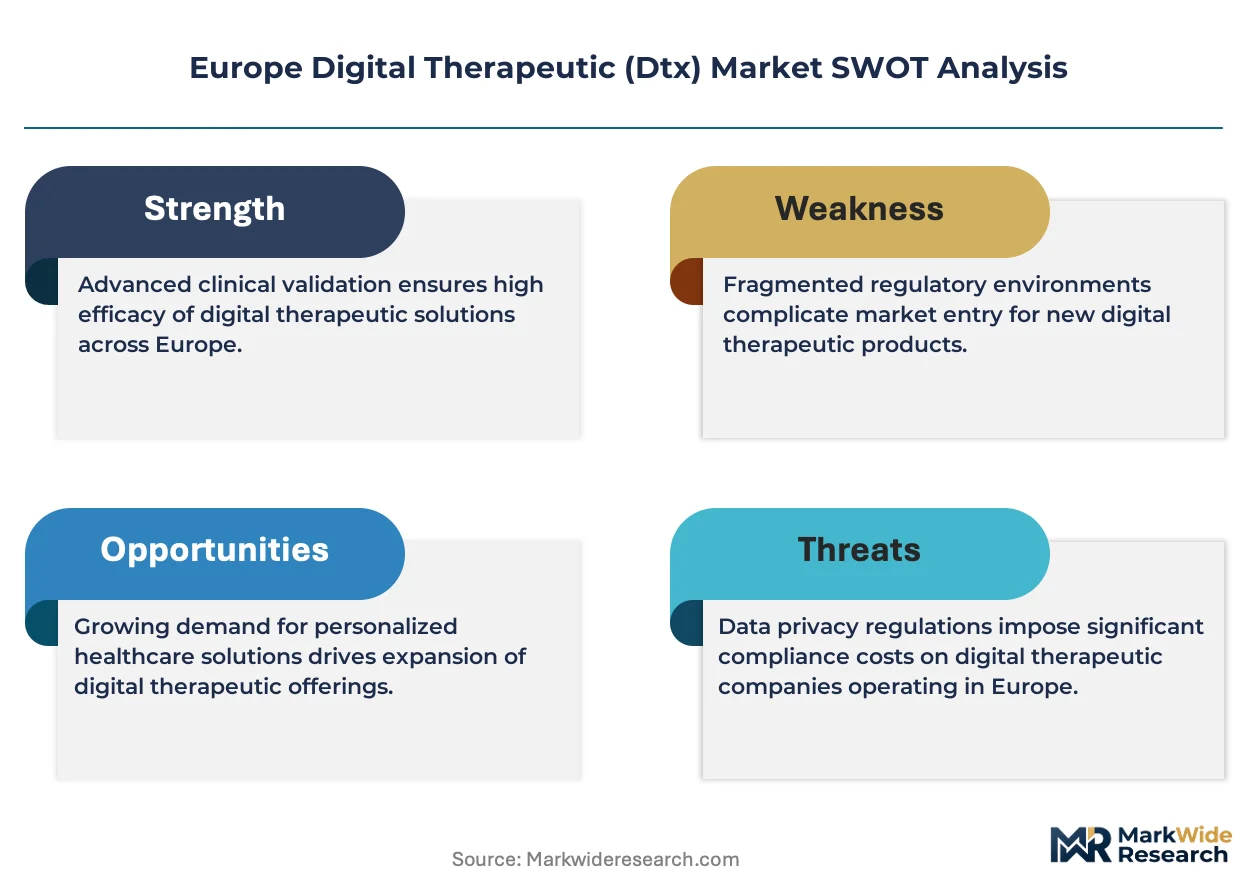
Reimbursement-based financing is rewriting competitive access across Europe's digital therapeutic landscape. Kaia Health Software GmbH leverages its musculoskeletal specialization to anchor partnerships with statutory health insurers in Germany. Voluntis sustains its oncology and diabetes focus through regulated prescription digital therapeutics that comply with France's national reimbursement schemes. Ada Health GmbH competes by extending its symptom-assessment engine into differential diagnosis support for clinical workflows.
Digital therapeutics comprise evidence-based software interventions designed to prevent, manage, or treat medical conditions through behavioral and physiological mechanisms, typically delivered via mobile applications or connected platforms with clinical validation protocols comparable to pharmaceutical trials. The primary commercial purpose centers on reducing disease burden through scalable, personalized interventions that complement or substitute conventional pharmacotherapy. Mobile apps and software solutions dominate technology deployment, while prescription-based product types capture concentrated margin pools due to regulatory barriers that filter out unvalidated competitors. Mental health and chronic disease therapy areas absorb the bulk of reimbursement attention, though pain management applications show accelerating clinical trial activity.
EMA guidance on software medical devices, the EU Medical Device Regulation, and Germany's BfArM fast-track approval for digital health applications collectively determine market access timelines and reimbursement eligibility across the continent. France's national health technology assessment body adds a secondary gate for pricing and coverage decisions that shapes commercial viability. Stakeholders must monitor evolving interoperability mandates and cross-border data portability rules that will determine which platforms achieve scalable deployment.
Market Dynamics
Reimbursement pathway fragmentation between Germany's DiGA fast-track and France's national health technology assessment is forcing platform developers to maintain parallel regulatory workstreams. This structural pressure favors larger players with dedicated regulatory affairs functions while squeezing mid-stage ventures.
Growth Catalysts
- DiGA Fast-Track Framework:Germany's BfArM approval pathway for digital health applications creates predictable reimbursement timelines. Statutory health insurers must reimburse approved products within 90 days.
- Chronic Disease Burden:Diabetes and cardiovascular patient populations across France, Italy, and Spain generate sustained demand for remote monitoring interventions that reduce hospitalization frequency.
- Interoperability Mandates:EU-wide electronic health record standards enable seamless data exchange between digital therapeutics and hospital information systems.
Market Restraints
- MDR Certification Complexity:EU Medical Device Regulation reclassification of software-as-medical-device products extends approval timelines and elevates clinical evidence requirements.
- Reimbursement Geography:Patchy coverage across Italy, Spain, and Eastern Europe limits addressable market size outside Germany and France.
- Clinical Validation Costs:Randomized controlled trial requirements comparable to pharmaceutical standards impose capital barriers on early-stage developers.
Strategic Opportunities
- Pain Management White Space:Musculoskeletal and chronic pain applications show accelerating trial activity with limited approved competitors in the reimbursement channel.
- Behavioral Health Integration:Convergence of cognitive behavioral therapy protocols with biometric monitoring enables hybrid interventions for depression and anxiety disorders.
- Poland and Romania:Underpenetrated Central European markets with nascent digital health infrastructure offer first-mover positioning before reimbursement frameworks mature.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Shortage of professionals experienced in both software development lifecycle management and medical device quality systems.
- Legacy EMR Integration:Hospital information systems across Southern Europe lack standardized APIs, forcing costly custom interoperability builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Therapeutic (Dtx) Market |
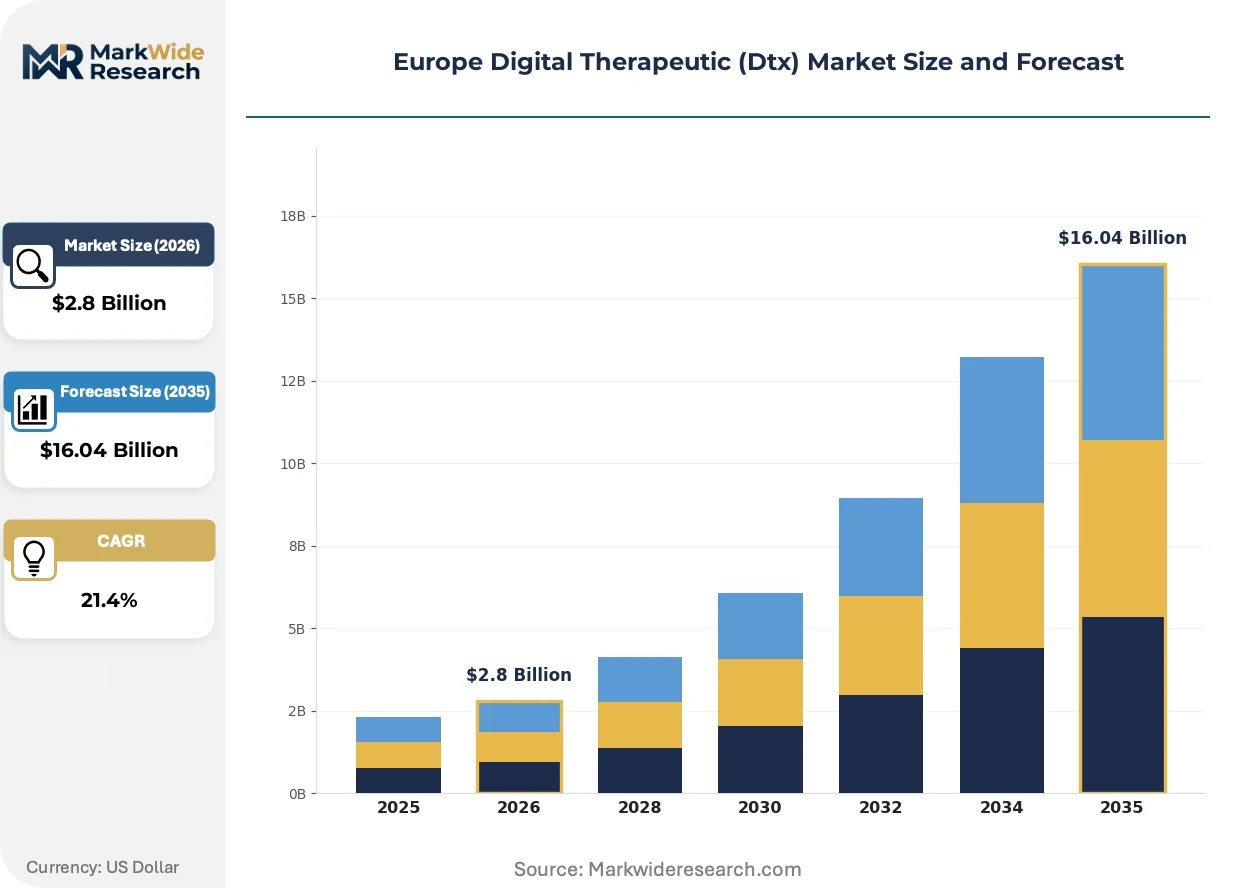
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $16.04 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mobile Apps, Wearable Devices, Telehealth Platforms, Software Solutions Therapy Area: Mental Health, Chronic Diseases, Pain Management, Diabetes End User: Hospitals, Clinics, Patients, Research Institutions Product Type: Prescription-Based, Over-the-Counter, Digital Counseling, Remote Monitoring |
| Companies Covered | Mindable Health GmbH, Cara Care, Kaia Health Software GmbH, HealthHero, GAIA AG, ResMed Germany Inc., Ada Health GmbH, Sidekick Health Germany GmbH, Voluntis, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Therapeutic (Dtx) Market Shifts & Advancements
Evidence generation models are pivoting from traditional pharmaceutical-style trials toward real-world evidence frameworks that capture outcomes in clinical practice settings. This shift reshapes how developers allocate capital across product lifecycles.
Prescription digital therapeutics are migrating from standalone mobile applications toward embedded modules within electronic health record workflows. Hospital systems in Germany and the Netherlands are piloting integrated deployment models that surface therapeutic content within clinician decision-support interfaces. This migration from consumer-direct to provider-embedded distribution compresses patient acquisition costs while elevating platform technical requirements.
France's national health technology assessment body has tightened evidentiary standards for digital therapeutic reimbursement, requiring demonstrated cost-effectiveness against standard of care. This policy shift elevates the importance of health economics modeling in product development. Oncology and diabetes management platforms face the most acute pressure to generate comparative effectiveness data.
Hospital procurement committees are consolidating vendor relationships around platforms that demonstrate interoperability with existing infrastructure. German hospital networks favor suppliers offering modular deployment across multiple therapeutic areas. This concentration of purchasing authority within integrated delivery networks is displacing fragmented departmental buying patterns that previously characterized the market.
Europe Digital Therapeutic (Dtx) Market Segmentation
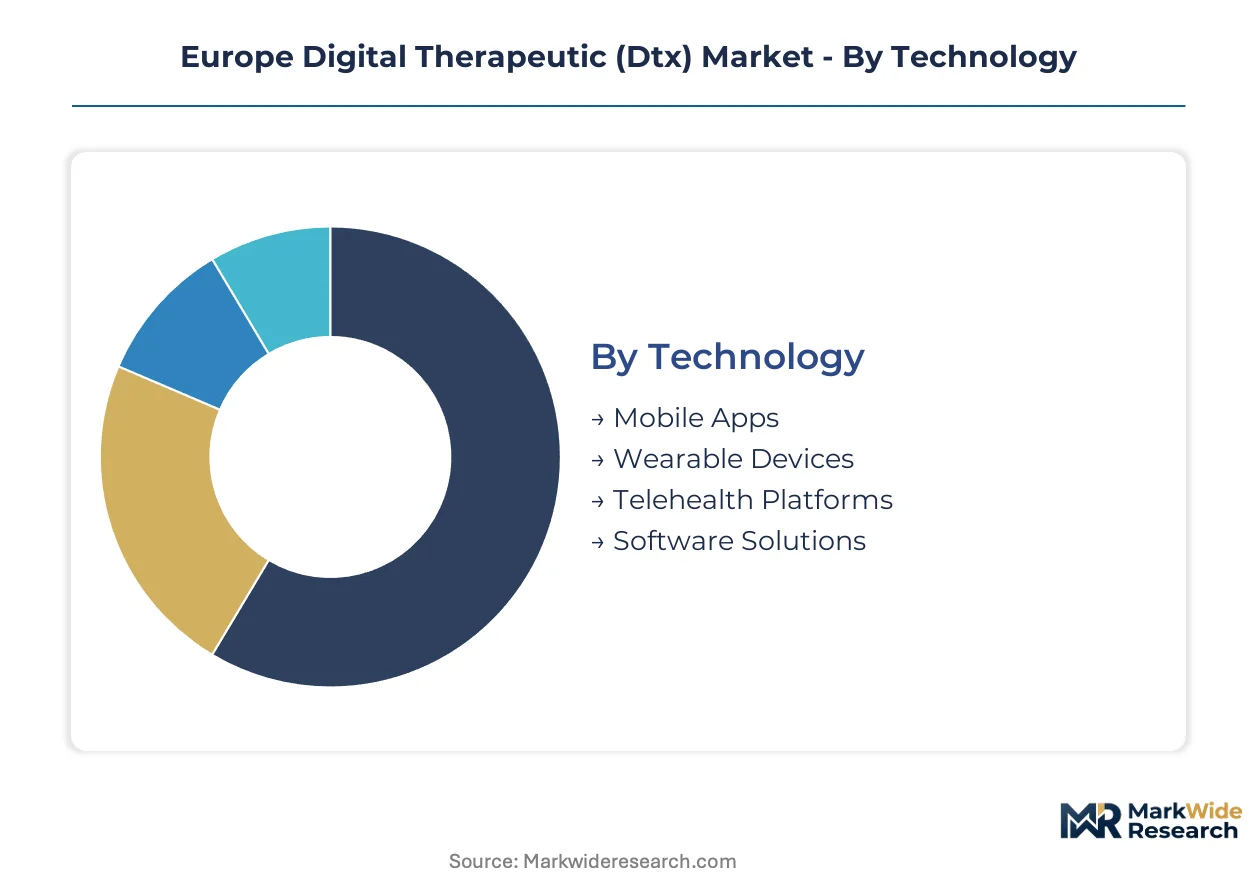
Segmentation in Europe's digital therapeutic market reveals how reimbursement pathways and clinical validation requirements concentrate value across distinct technology and delivery models. Understanding these divisions exposes where regulatory barriers filter competition and which product architectures achieve scalable deployment.
Technology:
Cycle times vary dramatically across technology segments, with software-only solutions iterating quarterly while hardware-integrated platforms face 18-24 month recertification timelines under MDR.
- Mobile Apps:Smartphone-delivered interventions dominate prescription volume in Germany's DiGA channel. Hospital systems in the Netherlands embed these within clinician workflows to compress patient acquisition costs and reduce deployment friction.
- Wearable Devices:Biometric sensors integrated with therapeutic protocols enable real-time physiological feedback for cardiovascular and diabetes management. French reimbursement schemes now demand demonstrated cost-effectiveness against standard monitoring, elevating health economics requirements for device developers.
- Telehealth Platforms:Video-based delivery infrastructure supports synchronous therapeutic sessions across Spain and Italy where specialist access remains uneven.
- Software Solutions:Cloud-hosted platforms without patient-facing hardware achieve fastest regulatory iteration but face interoperability mandates from EU electronic health record standards.
Mobile Apps dominate installed base. Software Solutions are where expansion concentrates.
Therapy Area:
Cost tiers separate segments, with oncology and diabetes platforms commanding premium reimbursement rates while mental health applications compete on volume.
- Mental Health:Cognitive behavioral therapy protocols delivered via mobile platforms absorb the bulk of patient registrations in Germany. Statutory health insurers prioritize these for depression and anxiety given demonstrated hospitalization reduction.
- Chronic Diseases:Cardiovascular and respiratory management platforms integrate with remote monitoring infrastructure across French hospital networks. EMA guidance on software medical devices shapes clinical evidence requirements for these interventions.
- Pain Management:Musculoskeletal applications show accelerating trial activity with limited approved competitors in reimbursement channels.
- Diabetes:Glucose monitoring integration with insulin dosing algorithms faces the most acute pressure to generate comparative effectiveness data under France's tightened HTA standards.
Chronic Diseases capture premium reimbursement. Mental Health is climbing the fastest.
End User:
Customer type determines procurement authority concentration, with integrated hospital networks displacing fragmented departmental buying.
- Hospitals:German hospital procurement committees consolidate vendor relationships around platforms demonstrating interoperability with existing infrastructure. These integrated delivery networks now control therapeutic platform selection previously managed by individual departments.
- Clinics:Outpatient settings in France leverage national reimbursement schemes for prescription digital therapeutics, with Voluntis sustaining oncology focus through this channel.
- Patients:Direct-to-consumer models persist in markets lacking reimbursement frameworks, particularly Italy and Spain where patchy coverage limits addressable market size.
- Research Institutions:Academic medical centers in the Netherlands pilot real-world evidence frameworks that reshape how developers allocate capital across product lifecycles.
Hospitals control procurement volume. Clinics are gaining share fastest.
Product Type:
Margin structures stratify sharply, with prescription-based products capturing concentrated value pools due to regulatory barriers that filter unvalidated competitors.
- Prescription-Based:Regulated digital therapeutics requiring clinician authorization command reimbursement premiums in Germany and France. BfArM's 90-day mandatory reimbursement timeline for approved DiGA products creates predictable revenue visibility.
- Over-the-Counter:Consumer-direct wellness applications without clinical validation face commoditization pressure as hospital systems migrate toward embedded EHR modules.
- Digital Counseling:Asynchronous therapeutic messaging platforms occupy a regulatory gray zone between medical device and general wellness classification.
- Remote Monitoring:Continuous data transmission infrastructure supports chronic disease management but requires costly custom interoperability builds where Southern European hospital information systems lack standardized APIs.
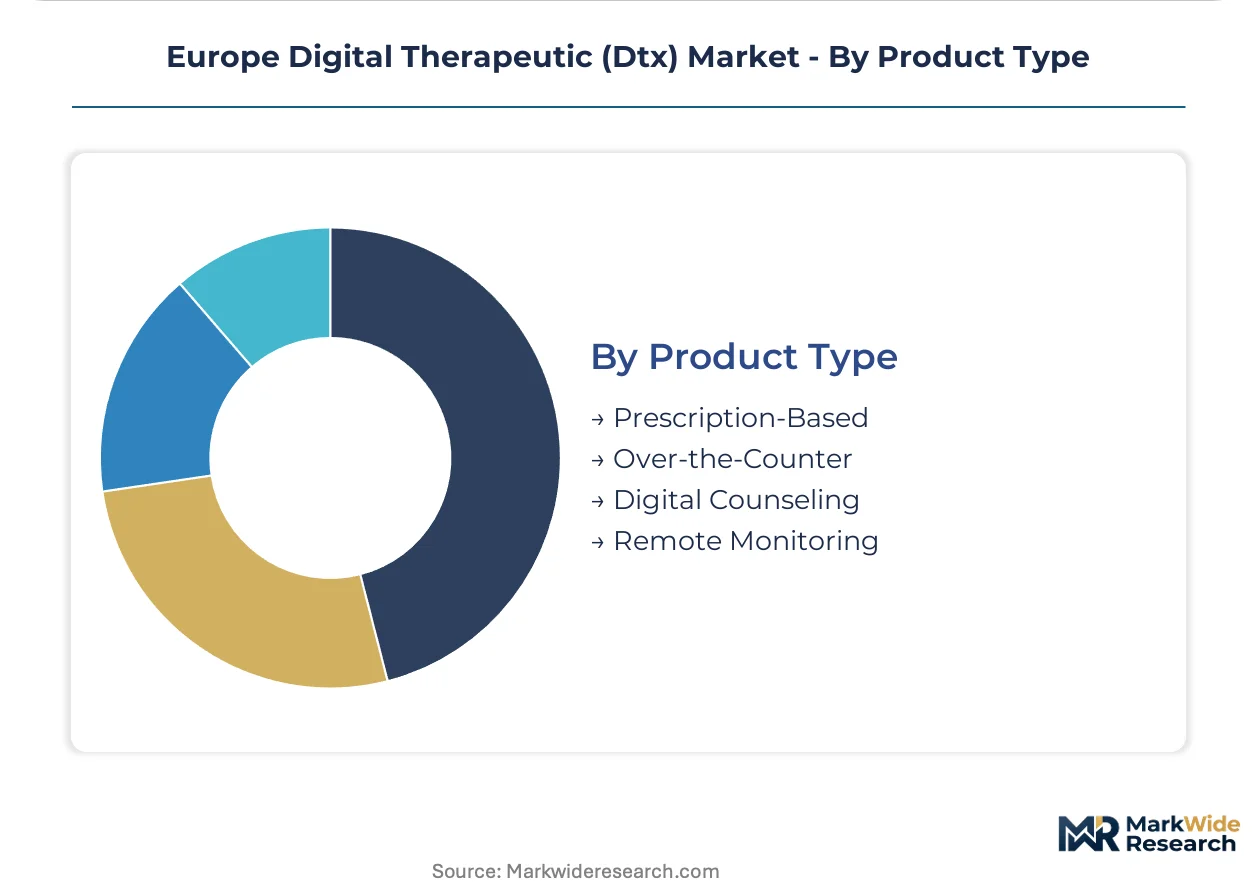
Prescription-Based products dominate revenue concentration. Remote Monitoring shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany and France concentrate purchasing authority, while fragmented reimbursement across Southern Europe limits addressable market expansion. Integrated delivery networks now control therapeutic platform selection previously managed by individual departments.
Germany
Statutory health insurers drive demand for prescription-based digital therapeutics through mandatory reimbursement obligations. BfArM's DiGA fast-track approval creates predictable 90-day coverage timelines for approved products. Berlin and Munich host dense clusters of digital health developers scaling musculoskeletal and mental health applications.
France
HAS and ANSM gate reimbursement through tightened health technology assessment standards requiring cost-effectiveness demonstration. National coverage schemes for oncology and diabetes management sustain platform demand. Paris-based hospital networks pilot embedded EHR deployment models that surface therapeutic content within clinician workflows.
United Kingdom
NICE evaluation frameworks shape adoption decisions across NHS integrated care systems seeking hospitalization reduction. MHRA software medical device guidance determines regulatory access timelines for prescription digital therapeutics. London and Cambridge clusters concentrate developers building real-world evidence frameworks for clinical validation.
Netherlands
Hospital information system interoperability mandates accelerate procurement of platforms demonstrating seamless data exchange. Dutch academic medical centers pilot integrated deployment models compressing patient acquisition costs. Amsterdam and Utrecht health networks favor modular suppliers spanning multiple therapeutic areas.
Spain
Uneven regional reimbursement coverage limits prescription digital therapeutic penetration outside Catalonia and Madrid. Patchy statutory insurance integration forces reliance on direct-to-consumer models in Andalusia and Valencia. Barcelona hospital systems advance pilot programs for chronic disease remote monitoring awaiting national coverage harmonization.
Europe Digital Therapeutic (Dtx) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented reimbursement geographies. German statutory insurer partnerships and French national health technology assessment approvals create dual gatekeeping structures that favor dedicated regulatory affairs capabilities. Three archetypes dominate: musculoskeletal specialists leveraging DiGA fast-track advantages, oncology-diabetes platforms sustaining reimbursement through HAS compliance, and symptom-assessment engines extending into clinical workflow integration. Competitive moves concentrate on EHR interoperability certification and parallel regulatory workstream maintenance across BfArM and ANSM pathways.
Among Germany-based developers, Kaia Health Software GmbH, Mindable Health GmbH, and Sidekick Health Germany GmbH occupy positions within the prescription-based reimbursement channel. Kaia Health Software GmbH anchors musculoskeletal specialization. Voluntis represents French regulatory compliance archetypes in oncology and diabetes. Ada Health GmbH exemplifies symptom-assessment engine extension into differential diagnosis support.
| Leading Market Players |
|---|
| Mindable Health GmbH |
| Cara Care |
| Kaia Health Software GmbH |
| HealthHero |
| GAIA AG |
| ResMed Germany Inc. |
| Ada Health GmbH |
| Sidekick Health Germany GmbH |
| Voluntis |
| Others |
Supply & Pricing Matrix
Undercapacity in clinical validation infrastructure across Southern Europe tightens pricing discipline for developers seeking MDR certification. German and French reimbursement concentration grants DiGA and HAS-approved platforms premium positioning, while patchy coverage elsewhere forces volume-based discounting to sustain trial enrollment.
Pricing Analysis
Cost-plus contracts with statutory health insurers index pricing to demonstrated hospitalization reduction metrics. Three-tier pricing structure across DiGA-premium, national HTA-standard, and direct-to-consumer economy levels separates regulated prescription products from wellness applications. Price differentiation hinges on BfArM approval status and interoperability certification with hospital EMR systems. Pricing pressure stems from France's tightened cost-effectiveness requirements under HAS evaluation frameworks. Direct-to-consumer segments in Italy and Spain exhibit acute price sensitivity, while German hospital procurement committees prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Export-control regimes restricting AI-enabled diagnostic algorithms limit technology flows into European clinical trial sites. Cloud infrastructure concentration rests on Ireland, Netherlands, and Germany for data residency compliance under GDPR. Raw material dependencies include biometric sensor components from Taiwan, encryption modules from Switzerland, and clinical evidence generation services from UK academic medical centers. Single-source vulnerability concentrates in MDR-notified body capacity for software-as-medical-device certification. Distribution runs through hospital procurement committees and statutory health insurer formularies rather than traditional pharmaceutical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through German hospital network consolidation and French national formulary centralization, displacing fragmented departmental purchasing that previously enabled vendor fragmentation.
For Market Incumbents: Pre-empt regulatory arbitrage by maintaining parallel BfArM and ANSM workstreams before mid-stage competitors achieve dual certification. Anchor partnerships with statutory health insurers through demonstrated interoperability with hospital information systems. Vertical integration into real-world evidence generation capabilities counters France's tightened HTA evidentiary demands. For New Entrants and Emerging Players: Build out pain management specialization where reimbursement channel competition remains sparse and trial activity accelerates. Poland and Romania offer penetrable geographies before national reimbursement frameworks mature. Target hospital system pilot programs in Netherlands and Spain seeking chronic disease remote monitoring solutions prior to coverage harmonization. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across clinical validation infrastructure as MDR recertification timelines extend. Platforms with existing DiGA approval and modular multi-therapeutic deployment architecture represent viable acquisition targets. Monitor BfArM approval velocity as an inflection indicator for revenue visibility compression.| Strategic Initiative | Industry Significance |
|---|---|
| DiGA Fast-Track Certification | BfArM approval unlocks mandatory 90-day statutory insurer reimbursement in Germany. |
| EMR Interoperability Certification | Hospital procurement committees in Netherlands prioritize seamless data exchange capabilities. |
| Real-World Evidence Framework | HAS cost-effectiveness requirements elevate health economics modeling in product development. |
| Pain Management Pipeline | Musculoskeletal applications face limited approved competitors in reimbursement channels. |
| Central European Geographic Expansion | Poland and Romania digital health infrastructure offers first-mover positioning advantages. |
Research Methodology
A spread of perspectives from regulatory affairs directors at DiGA-approved developers, statutory health insurer formulary managers, hospital procurement committee chairs, and MDR-notified body auditors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through BfArM approval databases, HAS reimbursement decisions, EMA software medical device guidance documents, and hospital procurement records. Bottom-up enrollment projections and top-down reimbursement expenditure estimates were triangulated against statutory health insurance spending data.
Demand-supply balance modeling anchored forecasts across the analysis window, with segmentation dimensions spanning technology deployment mode, therapy area reimbursement tier, end-user procurement authority, and product type regulatory classification. CAGRs were derived from fitted growth curves calibrated to historical DiGA approval velocity and statutory insurance coverage expansion patterns. Key inputs included BfArM approval pipeline data, France HAS evaluation timelines, and hospital EMR interoperability mandate implementation schedules.
Sensitivities concentrate around MDR certification timeline extensions, HAS cost-effectiveness threshold adjustments, and statutory health insurance budget allocation shifts. Forecasts reflect assumptions on reimbursement geography expansion and clinical validation cost trajectories. Material shifts in EU Medical Device Regulation guidance or national health technology assessment methodologies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Behavioral Mental Health Care Software Market
Digital Health Solutions
Care Coordination Software Market
Digital Health Solutions
Prescribed Health Apps Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Mhealth Apps Market
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Middle East and Africa Virtual Reality (VR) Health Market
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Telepsychiatry Software Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Digital Health Market