
 Healthcare Navigation Platform Market | 2026-2036
Healthcare Navigation Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Navigation Platform Market Analytics
Artificial intelligence is expanding as the core computational material replacing rules-based clinical decision trees in platform architectures. Accolade leverages machine learning models to personalize care routing for employer populations. Quantum Health anchors its competitive position through high-touch advocacy services layered on predictive analytics. Castlight Health specializes in price transparency tools that differentiate its offering within crowded benefits marketplaces.
A healthcare navigation platform constitutes a digital care coordination system that integrates patient data aggregation, clinical risk stratification algorithms, and real-time provider directory management to direct individuals toward appropriate, cost-effective medical services. Cloud-based delivery modes dominate deployment architectures, while SaaS subscription structures capture recurring revenue streams with superior margin profiles compared to on-premise installations. API integrations represent the fastest-expanding product type as health systems demand embedded connectivity with existing electronic health record ecosystems rather than standalone portal experiences.
The FDA oversees software-as-medical-device determinations for diagnostic recommendation engines, while HIPAA mandates encryption and access controls for protected health information flowing through these platforms. The ONC Cures Act Final Rule imposes information blocking prohibitions that accelerate demand for interoperable navigation tools capable of querying disparate clinical data repositories. Stakeholders must monitor evolving state-level surprise billing regulations and their implications for out-of-network steerage functionality embedded in platform logic.
Market Dynamics
Self-funded employers are consolidating procurement power around integrated navigation platforms that absorb fragmented point solutions into unified care coordination stacks, compressing vendor count while raising performance guarantees.
Growth Catalysts
- Interoperability mandates:The ONC Cures Act Final Rule imposes information blocking prohibitions that compel health systems to adopt API-first navigation tools capable of querying disparate clinical repositories.
- Cloud migration:Health systems are abandoning on-premise installations for SaaS delivery modes that reduce IT overhead and accelerate deployment cycles across multi-site networks.
- Employer cost pressure:Large self-funded plans in the United States are demanding navigation platforms that demonstrate measurable reductions in medical spend and administrative burden.
Market Restraints
- Data integration complexity:Legacy electronic health record systems require costly middleware development to achieve real-time connectivity with modern navigation architectures.
- Regulatory fragmentation:State-level surprise billing regulations create conflicting steerage logic requirements that complicate platform deployment across multi-state employer populations.
- Specialist talent scarcity:Shortages of clinical informaticists and health data engineers constrain implementation velocity for advanced risk stratification modules.
Strategic Opportunities
- Medicare Advantage expansion:Navigation platforms can capture growing senior populations as Medicare Advantage plans seek care coordination tools for complex chronic disease management.
- Behavioral health integration:Converging mental health routing algorithms with physical care pathways addresses unmet demand for whole-person navigation.
- Value-based contract enablement:Platforms that embed quality measurement and episode tracking capabilities align with CMS alternative payment model incentives.
Industry Challenges
- HIPAA compliance engineering:Encryption and access control implementations for protected health information flows require continuous security architecture investment.
- FDA software-as-medical-device determinations:Diagnostic recommendation engines face evolving regulatory classification that extends commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Navigation Platform Market |
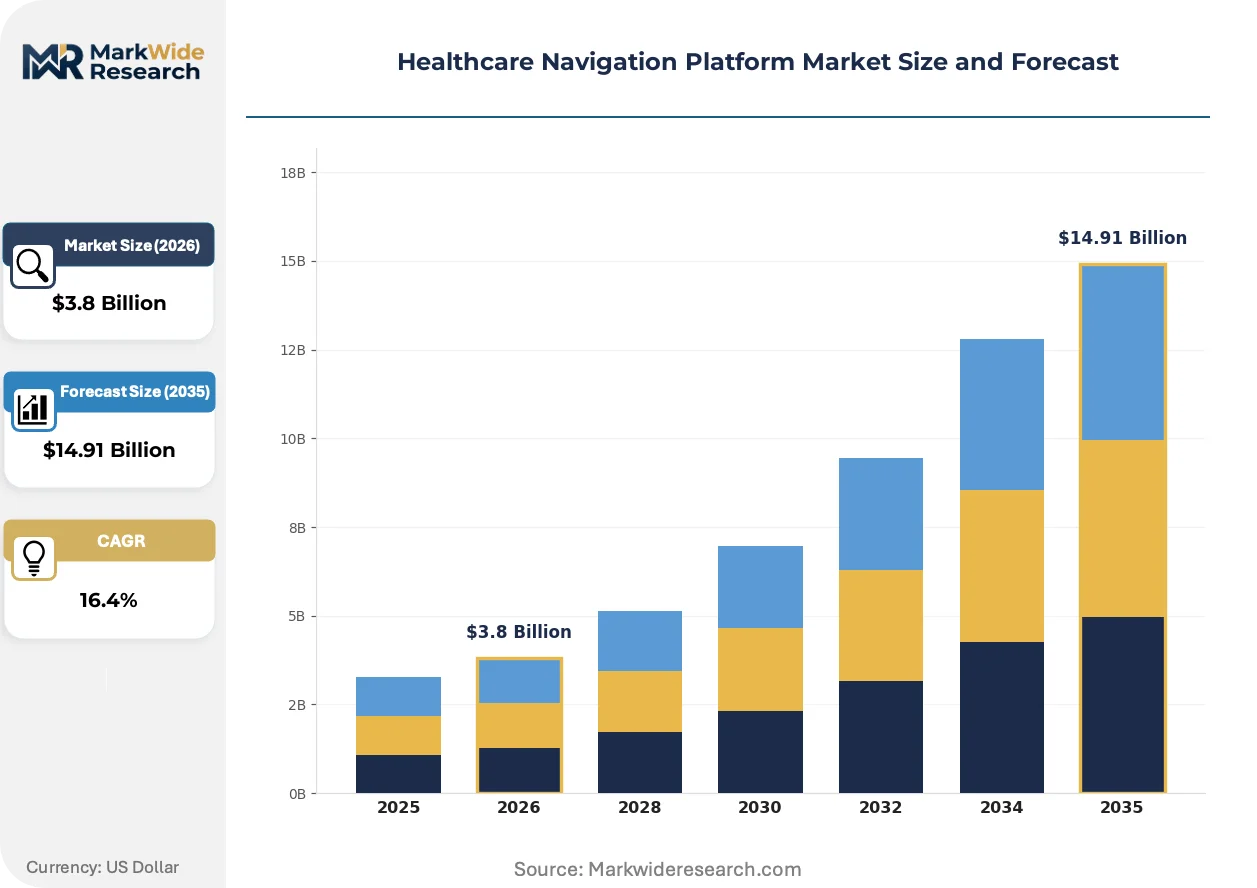
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Web Platforms, Onboarding Solutions, API Integrations Delivery Mode: Cloud-based, On-premise, Hybrid, SaaS End User: Patients, Providers, Payers, Healthcare Institutions Application: Patient Engagement, Care Coordination, Appointment Scheduling, Resource Management |
| Companies Covered | Sharecare, Apree Health, Accolade, Buoy Health, Health Advocate, Quantum Health, Castlight Health, Brightside Health, Included Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Navigation Platform Market Evolving Landscape
Machine learning architectures are replacing deterministic clinical decision trees across platform stacks, enabling dynamic personalization that static rule engines cannot match.
Natural language processing for patient intake and symptom assessment is overtaking structured questionnaire workflows in employer-sponsored navigation deployments. Large self-funded plans are adopting conversational interfaces that reduce friction in initial care routing. This compression of intake latency is enabling same-day specialist matching that traditional triage protocols required 48-72 hours to execute.
The FDA is intensifying scrutiny of algorithmic diagnostic outputs through expanded software-as-medical-device guidance. Platform developers must now submit clinical validation evidence for predictive risk scores that drive care recommendations. Vendors with employer-focused offerings are responding by segregating diagnostic support features from administrative navigation modules to contain regulatory exposure.
Self-insured employers are consolidating vendor relationships around single-platform solutions that absorb price transparency, advocacy, and care routing functions previously purchased separately. Benefits consultants are steering procurement toward integrated suites that reduce contract management overhead. This bundling pressure is most visible in the United States, where large employer-sponsored insurance pools possess concentrated negotiating leverage.
Healthcare Navigation Platform Market Segmentation
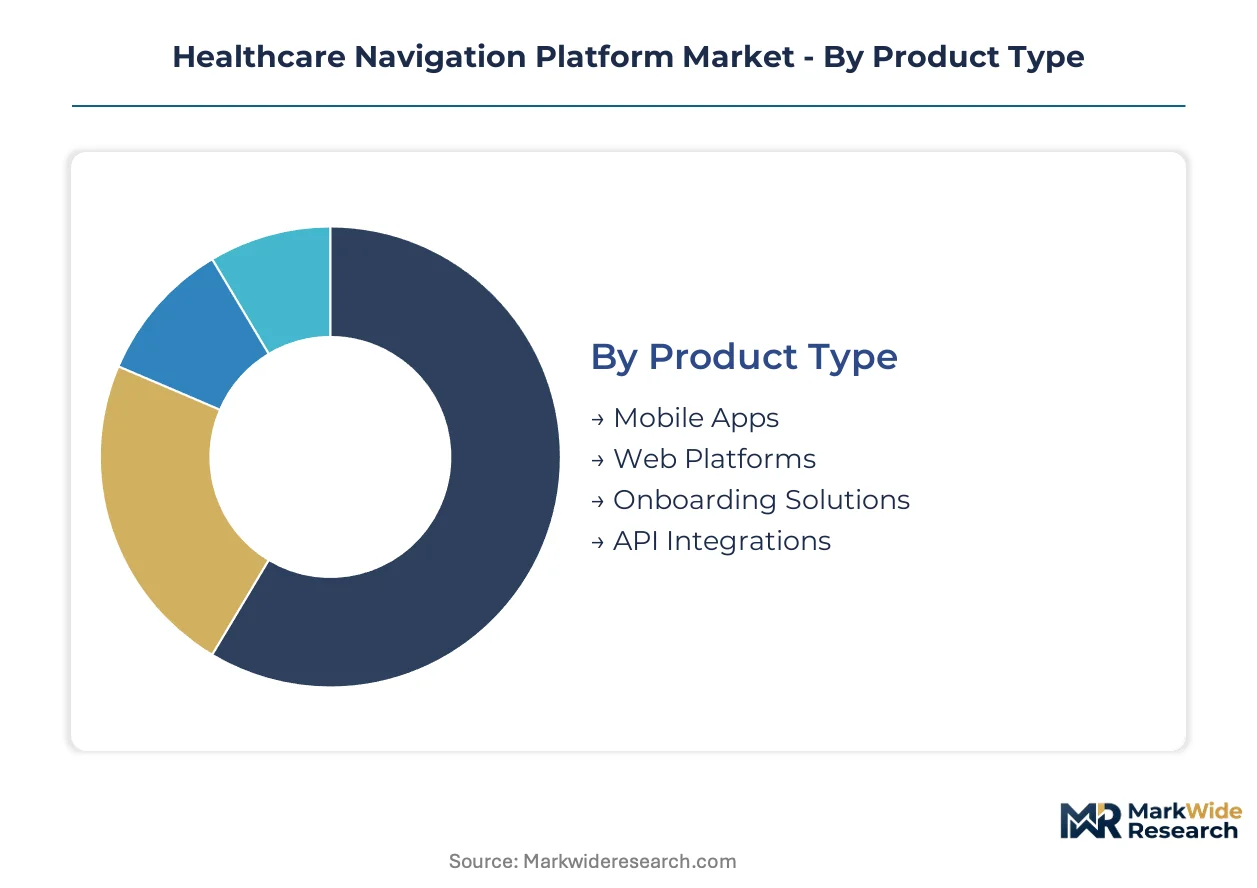
Healthcare navigation platforms segment across product architecture, deployment infrastructure, user constituency, and functional application. These dimensions determine integration complexity, recurring revenue potential, and regulatory exposure for vendors competing in employer-sponsored and health system markets.
Product Type:
Standalone mobile applications operate at the consumer-facing edge of navigation ecosystems, while embedded API layers penetrate deepest into clinical workflow infrastructure.
- Mobile Apps:Native iOS and Android applications deliver push-notification care reminders and real-time provider search to smartphone-dependent populations. Large self-funded employers in the United States deploy these as frontline member engagement tools, though retention challenges persist beyond initial onboarding periods.
- Web Platforms:Browser-accessible dashboards aggregate price transparency, benefit verification, and care routing through responsive interfaces. Health systems favor these for lower development overhead compared to multi-OS mobile deployment.
- Onboarding Solutions:Specialized intake modules streamline benefits enrollment and initial care team assignment.
- API Integrations:Embedded connectivity layers query electronic health record systems directly, eliminating portal friction. Health systems demand these for ONC Cures Act compliance, accelerating procurement fastest among all product types.
Web Platforms lead volumes today; API Integrations are gaining share fastest.
Delivery Mode:
Cost tier stratification separates capital-intensive on-premise installations from operational-expense SaaS models preferred by mid-market health systems.
- Cloud-based:Multi-tenant architectures hosted on AWS, Azure, or Google Cloud reduce IT staffing requirements and accelerate deployment across distributed hospital networks. HIPAA Business Associate Agreements with hyperscale providers address compliance automation.
- On-premise:Dedicated server installations within health system data centers satisfy stringent data residency requirements. Academic medical centers and Department of Veterans Affairs facilities maintain these despite higher total cost of ownership.
- Hybrid:Split architectures process PHI-sensitive operations on-premise while offloading analytics workloads to cloud infrastructure.
- SaaS:Subscription licensing with per-member-per-month pricing dominates employer-sponsored procurement, capturing recurring revenue streams with superior margin profiles.
SaaS leads volumes today; Cloud-based deployments are expanding most quickly.
End User:
Application maturity varies sharply across user types, with payer-focused platforms demonstrating the most advanced risk stratification capabilities.
- Patients:Consumer-facing interfaces emphasize price transparency and appointment accessibility. Medicare Advantage populations drive demand growth as seniors require navigation support for complex chronic conditions.
- Providers:Clinical workflow integration targets physician time savings through automated prior authorization and referral management. Epic and Cerner compatibility determines vendor selection.
- Payers:Insurance carriers deploy navigation to steer members toward narrow networks and value-based providers.
- Healthcare Institutions:Integrated delivery networks consolidate navigation across employed physicians, affiliated hospitals, and owned health plans.
Payers lead volumes today; Patient-facing solutions are climbing the fastest.
Application:
Functional specialization fragments the vendor landscape, with care coordination modules commanding premium pricing due to clinical outcome accountability.
- Patient Engagement:Gamified health challenges, medication adherence tracking, and personalized content delivery reduce gaps in care. Employers measure success through biometric screening participation rates.
- Care Coordination:Risk-stratified outreach to high-acuity members prevents emergency department utilization and inpatient admissions. CMS alternative payment models incentivize these investments.
- Appointment Scheduling:Real-time calendar integration across provider networks reduces scheduling latency.
- Resource Management:Bed availability, equipment utilization, and staffing optimization modules target health system operational efficiency.
Patient Engagement leads volumes today; Care Coordination shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's healthcare technology corridor anchors platform development, with Massachusetts General Brigham and Harvard-affiliated startups driving clinical AI integration. Employer procurement concentrates in metropolitan areas with dense self-insured corporate headquarters.
United States
Large self-funded employers in Minnesota, Illinois, and California drive procurement volume for integrated navigation suites. HIPAA mandates encryption standards for protected health information flows, while the ONC Cures Act Final Rule accelerates API adoption. The Minneapolis-St. Paul corridor hosts concentration of benefits administration technology vendors serving Fortune 500 health plans.
Germany
Statutory health insurance funds explore navigation tools for chronic disease management in aging populations. The EU AI Act imposes risk classification requirements for diagnostic recommendation algorithms. Berlin's digital health startup ecosystem attracts venture investment for care coordination platforms targeting integrated care contracts.
United Kingdom
NHS Integrated Care Systems pilot navigation platforms to reduce emergency department utilization and elective surgery backlogs. NHS England's digital transformation mandates prioritize interoperability with existing electronic health record infrastructure. London's health tech cluster concentrates vendor development for patient-facing appointment and referral management tools.
Japan
Super-aging demographics drive demand for senior-focused navigation supporting dementia care and polypharmacy management. METI's Society 5.0 initiative funds AI-enabled health platforms for regional medical coordination. Tokyo and Osaka metropolitan areas concentrate deployment of cloud-based care coordination for hospital network consolidation.
Australia
Medicare Advantage-like private health insurance expansion creates navigation procurement opportunities for chronic condition management. The Australian Digital Health Agency's interoperability framework mandates FHIR-compliant data exchange. Sydney and Melbourne health technology clusters develop platforms integrating with My Health Record national infrastructure.
Healthcare Navigation Platform Market Competitive Landscape
Global majors compete with regional champions across employer-sponsored and health system market segments, creating a tiered structure with distinct capability specializations. The vendor base separates into integrated platform operators, point-solution specialists, and health plan captive services. Strategic archetypes include AI-native care routers, high-touch advocacy services, and price transparency tool vendors. M&A consolidation absorbs point solutions into unified stacks, while API-first partnerships embed navigation into existing electronic health record workflows.
Within the integrated platform tier, Accolade and Quantum Health exemplify divergent approaches to employer population management, with the former emphasizing machine learning personalization and the latter anchoring on predictive analytics layered with human advocacy. Castlight Health occupies a position representing price transparency specialization within crowded benefits marketplaces. These three entities demonstrate how vendor strategy fragments across automation depth versus high-touch service intensity versus functional narrowness.
| Leading Market Players |
|---|
| Sharecare |
| Apree Health |
| Accolade |
| Buoy Health |
| Health Advocate |
| Quantum Health |
| Castlight Health |
| Brightside Health |
| Included Health |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure pricing indices from AWS, Azure, and Google Cloud cascade through SaaS delivery models into three-tier subscription structures across employer-sponsored navigation platforms, compressing margins for vendors lacking scale economies while enabling premium pricing for API-integrated offerings with embedded EHR connectivity.
Pricing Analysis
Input-cost pass-through from hyperscale cloud providers drives SaaS subscription pricing tiers across per-member-per-month models. Price differentiation rests on integration depth with Epic and Cerner systems versus standalone portal deployments. Pricing pressure stems from employer consolidation around unified platforms that absorb fragmented point solutions. Mid-market health systems exhibit highest price sensitivity; large self-funded employers with concentrated procurement power command volume discounts.
Supply Chain Analysis
Reverse-logistics flows for decommissioned on-premise servers and legacy middleware components create secondary refurbishment markets as health systems migrate to cloud architectures. Supply concentration centers on the United States for platform development, India for health data engineering talent, and Ireland for European data residency compliance. Raw material dependencies include GPU clusters for machine learning inference, encrypted storage arrays for PHI compliance, and API gateway infrastructure for interoperability. Single-source vulnerability in NVIDIA AI chip supply chains threatens deployment velocity. Distribution runs through direct enterprise sales teams and benefits consultant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in healthcare navigation platforms derives from cloud infrastructure cost curves flattening and employers upgrading from basic engagement tools to premium care coordination modules with outcome guarantees.
For Market Incumbents: Anchor defensive positioning through API-first architecture investments that deepen Epic and Cerner integration moats. Acquire behavioral health routing specialists to preempt point-solution competitors from occupying whole-person navigation white space. Consolidate vendor relationships with large employers before benefits consultants steer procurement toward integrated suites.
For New Entrants and Emerging Players: Enter via Medicare Advantage navigation gaps where incumbent platforms lack senior-specific dementia care and polypharmacy management workflows. Target Japanese and Australian markets where super-aging demographics and national health record infrastructure create procurement windows. Pursue hospital system partnerships as primary go-to-market channel rather than direct employer sales.
For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native care routing platforms possessing FDA software-as-medical-device clearance pathways and proven clinical validation datasets. Long-term viability favors vendors with demonstrated medical spend reduction metrics across multi-year employer contracts. Monitor ONC Cures Act enforcement intensity as signal for interoperability-mandated procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Development | Embedded EHR connectivity satisfies ONC Cures Act mandates and accelerates health system procurement cycles. |
| Behavioral Health Module Integration | Mental health routing algorithms address unmet whole-person navigation demand from self-funded employers. |
| Medicare Advantage Partnership | Senior-focused platforms capture growing chronic disease management spend from CMS alternative payment models. |
| Clinical AI Validation Investment | FDA software-as-medical-device submissions extend regulatory moats against undifferentiated administrative tools. |
| Cloud Infrastructure Migration | Multi-tenant SaaS delivery reduces IT overhead and enables rapid deployment across distributed hospital networks. |
Research Methodology
Multiple input streams — executive interviews with navigation platform CTOs, procurement discussions with benefits consultants at large self-funded employers, and regulatory filings with ONC and FDA — were reconciled against secondary validation from hospital procurement databases, GPO contracts, and CMS Medicare Advantage enrollment data. Primary fieldwork engaged clinical informaticists, health data engineers, and payer strategy officers across the United States, Germany, and Japan. Bottom-up sizing of vendor-reported member counts and top-down triangulation against employer-sponsored insurance market penetration produced convergent estimates.
Data-stream reconciliation across product type, delivery mode, end user, and application dimensions anchored the analytical framework over the projection horizon. Modeled segmentation captured cloud versus on-premise deployment, SaaS versus perpetual licensing, patient versus provider versus payer orientation, and care coordination versus engagement versus scheduling functionality. CAGRs were derived from trend extrapolation of employer procurement consolidation and API adoption curves. Forecast inputs included HIPAA compliance cost trajectories and FDA software-as-medical-device clearance timelines.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in real-time EHR interoperability implementation rates introduce uncertainty bands around API integration adoption forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
AI-Powered Clinical Decision Support Market
Digital Health Solutions
Medical Virtual Reality Operating Systems Market
Digital Health Solutions
Global Urgent Care Apps Market
Digital Health Solutions
Global Metaverse in Healthcare Market
Digital Health Solutions
Prescribed Health Apps Market
Digital Health Solutions
Connected Health and Wellness Solutions Market
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
North America Digital Health Market
Digital Health Solutions
Women Digital Health Solutions Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Digiceuticals Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Pregnancy Tracking and Postpartum Care Apps Market
Digital Health Solutions
Digital Health Tracking Apps Market