
 Middle East and Africa Heart Failure Software Market | 2026-2036
Middle East and Africa Heart Failure Software Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Heart Failure Software Market Foresight
CE marking under the EU Medical Device Regulation is restructuring market access requirements for software vendors exporting into North African markets aligned with European trade frameworks. Medtronic plc leverages its established cardiac device ecosystem to anchor remote monitoring deployments across Gulf hospital systems. Philips N.V. competes through integrated informatics platforms that unify imaging and patient data workflows. Siemens Healthcare Private specializes in on-premise infrastructure tailored to data sovereignty concerns prevalent in Saudi and Emirati facilities.
Heart failure software encompasses clinical applications designed to capture, analyze, and transmit patient physiological data for the management of chronic cardiac dysfunction, typically integrating with implantable devices or wearable sensors to track hemodynamic parameters, arrhythmia patterns, and fluid status indicators. These systems serve cardiologists and care teams by enabling proactive intervention before acute decompensation events require hospitalization. Cloud-based solutions dominate current procurement as Gulf health systems prioritize scalable infrastructure over capital-intensive server deployments. Hospitals represent the most entrenched end-user segment, though telehealth providers are expanding fastest where specialist cardiologist shortages in secondary cities drive remote consultation models.
South Africa's Health Products Regulatory Authority and Saudi Arabia's Food and Drug Authority impose divergent software lifecycle documentation requirements, compelling vendors to maintain parallel quality management systems or risk exclusion from either market. The UAE's Ministry of Health and Prevention has introduced accelerated pathways for AI-enabled diagnostic tools, reshaping how machine learning modules receive clinical validation. Stakeholders must monitor evolving data localization mandates across Gulf states, as requirements for domestic hosting of patient records threaten to fragment cloud architectures currently designed for regional scale.
Market Dynamics
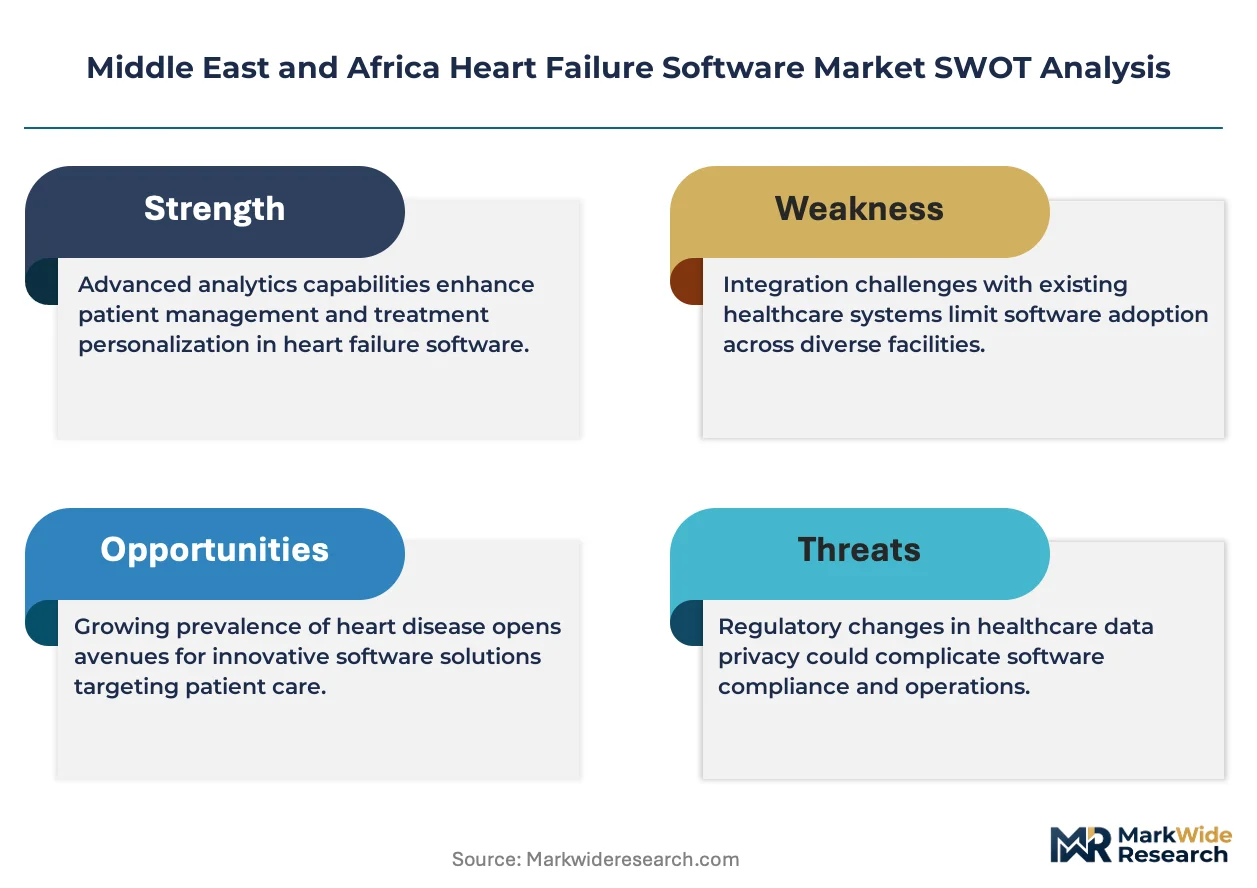
Hospital procurement officers across Gulf Cooperation Council states are consolidating vendor relationships around integrated cardiac informatics platforms, compressing the addressable supplier base while elevating data sovereignty and interoperability specifications as primary selection criteria.
Growth Catalysts
- Saudi Arabia's Ministry of Health digitization mandates:National cardiovascular care pathway modernization is creating structured demand for remote patient monitoring infrastructure in tertiary hospital networks.
- CE marking alignment in North African trade frameworks:Egyptian and Moroccan import regulations now recognize EU Medical Device Regulation conformity, reducing market entry friction for validated software vendors.
- Implantable hemodynamic sensor maturation:Next-generation pulmonary artery pressure monitors are enabling automated decompensation alerts that reduce emergency readmissions.
Market Restraints
- Data localization mandates:Saudi and Emirati requirements for domestic patient record hosting fragment cloud architectures designed for regional scale.
- Specialist cardiologist scarcity:Secondary cities across Nigeria and Kenya lack sufficient clinical workforce to interpret remote monitoring data streams.
- Validation timeline divergence:South Africa's Health Products Regulatory Authority and Saudi Arabia's Food and Drug Authority impose non-harmonized software lifecycle documentation requirements.
Strategic Opportunities
- UAE's AI-enabled diagnostic accelerated pathways:Machine learning modules for arrhythmia detection now qualify for expedited clinical validation under Ministry of Health and Prevention frameworks.
- Telehealth provider expansion:Remote consultation platforms in secondary Egyptian and Jordanian cities are creating demand for asynchronous cardiac data review workflows.
- Wearable sensor convergence with mobile networks:5G infrastructure rollout in Gulf states enables real-time transmission of high-fidelity electrocardiogram streams from patient homes.
Industry Challenges
- Interoperability with legacy hospital information systems:Many Saudi and South African facilities operate on-premise electronic health record architectures that resist cloud-native cardiac platform integration.
- Biomedical informatics talent scarcity:Shortage of professionals capable of configuring HL7 FHIR interfaces between implantable devices and hospital data repositories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Heart Failure Software Market |
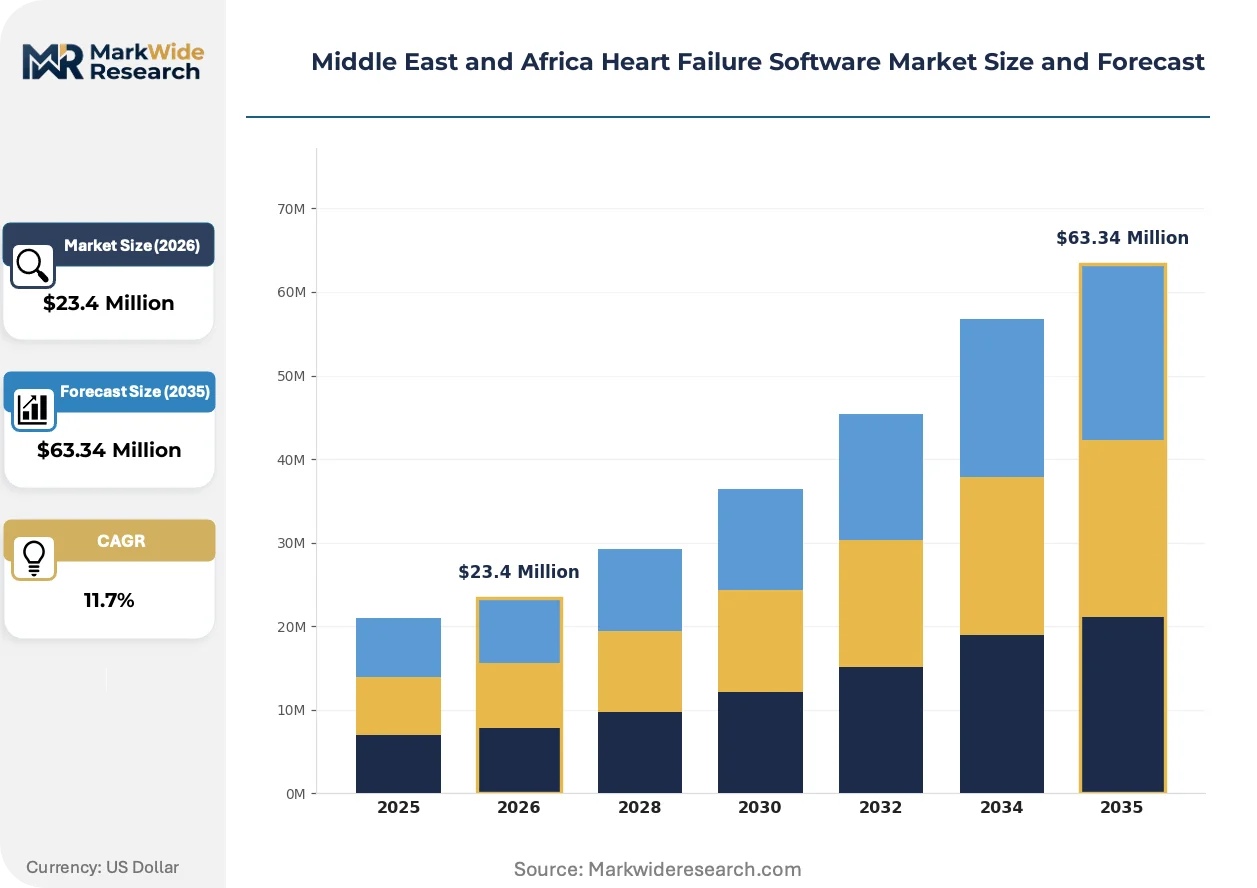
| Market Size in 2026 | $23.4 Million |
| Market Size in 2035 | $63.34 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, Mobile Applications, Remote Monitoring Tools, Data Analytics Platforms End User: Clinics, Hospitals, Telehealth Providers, Home Healthcare Services Deployment: On-Premise, Cloud, Hybrid, Software as a Service Technology: Artificial Intelligence, Machine Learning, Big Data Analytics, Internet of Medical Things |
| Companies Covered | Cerner Corporation, Koninklijke Philips N.V., Siemens Healthcare Private, Medtronic plc, Abbott Laboratories, GE Healthcare, 4S Information Systems Ltd., Axis Clinical Software Inc., CitiusTech Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Heart Failure Software Market Shifts & Advancements
Cardiac care delivery models across the Middle East and Africa are restructuring around predictive analytics capabilities that anticipate decompensation events before acute hospitalization becomes necessary.
Cloud-native remote monitoring architectures are overtaking on-premise server deployments as Gulf health systems prioritize scalable operational expenditure models over capital-intensive infrastructure commitments. Saudi Arabia's Ministry of Health and UAE hospital networks are consolidating procurement around software-as-a-service cardiac platforms. This shift is compressing deployment timelines from months to weeks while elevating vendor responsibility for cybersecurity maintenance.
South Africa's Health Products Regulatory Authority is tightening software validation requirements for connected medical devices, extending documentation obligations to machine learning components that adapt algorithmic thresholds based on patient-specific data patterns. Medical device manufacturers must now submit updated clinical evidence when algorithm modifications exceed predefined performance boundaries. Cardiac monitoring vendors are responding by partitioning static and adaptive software elements to isolate regulatory exposure.
Hospital procurement committees are unbundling after-sales clinical support from software licensing agreements, creating separate contracting vehicles for cardiologist training and 24-hour monitoring center operations. This fragmentation is most visible in Saudi Arabia where Ministry of Health tenders now distinguish platform subscription fees from implementation services. Specialist shortages in secondary cities are driving demand for vendor-managed clinical interpretation services that supplement local workforce gaps.
Middle East and Africa Heart Failure Software Market Segmentation
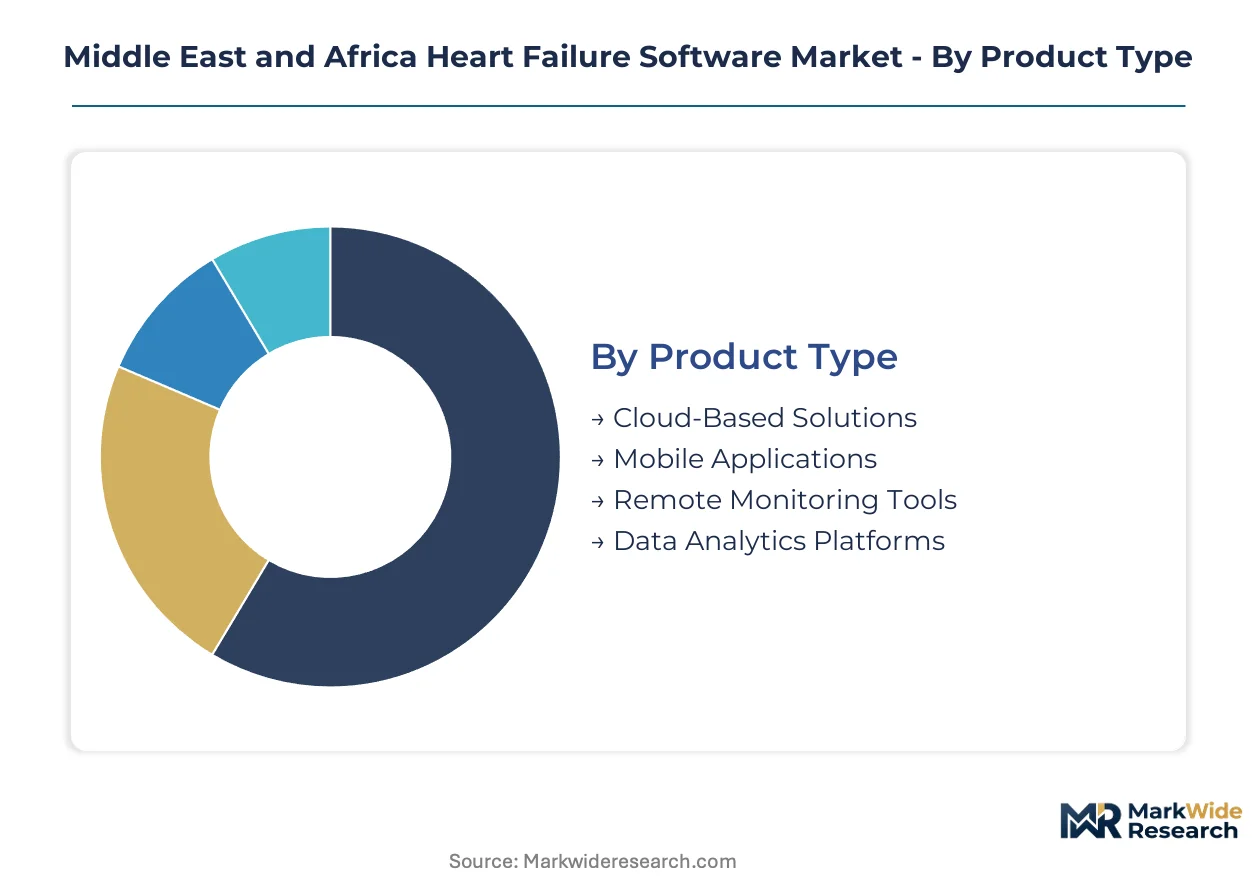
Procurement officers across Gulf hospital systems weight scalability against data sovereignty when selecting cardiac software architectures. Segmentation reveals how deployment preferences diverge between tertiary medical centers and emerging telehealth networks. Understanding these divides enables vendors to align product roadmaps with buyer decision hierarchies.
Product Type:
Hospital procurement committees prioritize total cost of ownership and integration complexity when evaluating software categories.
- Cloud-Based Solutions:These platforms host patient data on distributed server infrastructure managed by third-party providers. Saudi Arabia's Ministry of Health digitization mandates are concentrating demand here as tertiary hospital networks seek scalable operational expenditure models without capital-intensive server deployments. Cybersecurity maintenance responsibilities shift to vendors under this arrangement.
- Remote Monitoring Tools:Systems designed to capture and transmit physiological data from implantable devices or wearable sensors to clinical teams. Demand concentrates in UAE hospital networks where specialist cardiologist shortages in secondary cities drive remote consultation models requiring real-time hemodynamic surveillance.
- Mobile Applications:Patient-facing interfaces enabling symptom logging and medication adherence tracking.
- Data Analytics Platforms:Backend systems processing aggregated cardiac datasets for population health insights.
Cloud-Based Solutions lead on scale; Remote Monitoring Tools lead on momentum.
End User:
Clinical workforce availability and infrastructure maturity determine which customer segments dominate procurement volumes.
- Hospitals:Tertiary medical centers with established cardiology departments and on-premise electronic health record systems. Saudi and Emirati facilities represent the core revenue base, though legacy HL7 FHIR integration challenges complicate cloud-native platform adoption. Procurement committees now unbundle after-sales clinical support from software licensing agreements.
- Telehealth Providers:Remote consultation platforms serving secondary cities with specialist shortages. Egyptian and Jordanian operators are expanding fastest where asynchronous cardiac data review workflows address workforce gaps. These providers prioritize vendor-managed clinical interpretation services.
- Clinics:Smaller outpatient facilities with limited cardiology specialization.
- Home Healthcare Services:Post-acute care providers managing discharged heart failure patients.
Hospitals anchor current revenue; Telehealth Providers are climbing the fastest.
Deployment:
Data localization mandates and regulatory validation timelines shape architectural preferences across jurisdictions.
- Software as a Service:Subscription-based delivery where vendors maintain infrastructure and security patches. Gulf health systems favor this model for compressed deployment timelines and reduced IT staffing requirements. Saudi Arabia's Food and Drug Authority and South Africa's Health Products Regulatory Authority impose divergent documentation requirements that complicate vendor compliance.
- On-Premise:Server infrastructure installed within facility premises to satisfy data sovereignty concerns. Emirati and Saudi requirements for domestic patient record hosting sustain demand despite higher capital expenditure. Siemens Healthcare Private specializes in these configurations.
- Cloud:Third-party hosted solutions without full SaaS managed services.
- Hybrid:Architectures combining on-premise data storage with cloud-based analytics processing.
Software as a Service dominates new procurement; On-Premise retains defensive positions in regulated markets.
Technology:
Regulatory pathways for algorithmic medical devices determine which technology investments yield fastest market access.
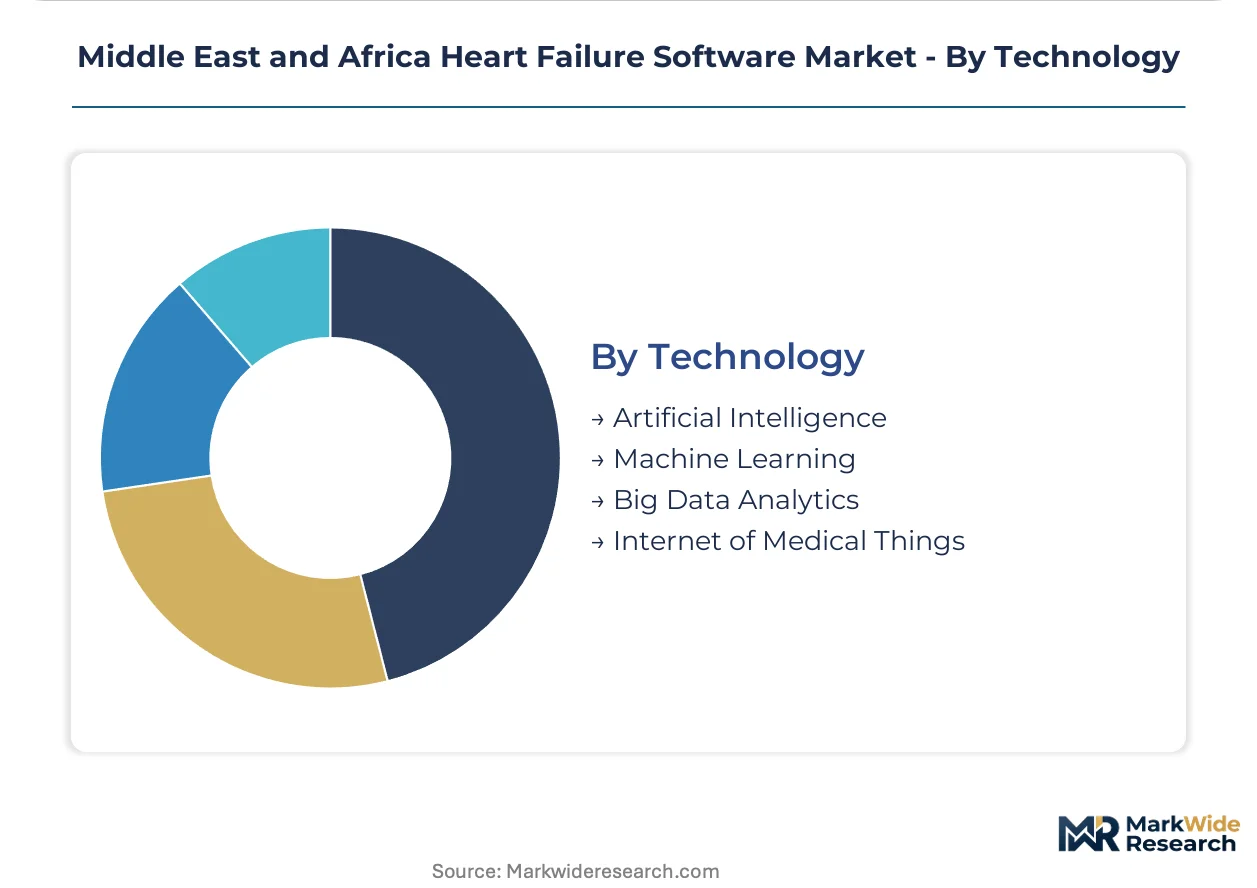
- Artificial Intelligence:Algorithmic systems enabling predictive decompensation alerts and automated arrhythmia classification. The UAE's Ministry of Health and Prevention accelerated pathways for AI-enabled diagnostic tools are reshaping clinical validation requirements. Vendors must submit updated evidence when algorithm modifications exceed predefined performance boundaries.
- Machine Learning:Adaptive algorithms that adjust thresholds based on patient-specific data patterns. South Africa's Health Products Regulatory Authority extends documentation obligations to these components, compelling manufacturers to partition static and adaptive software elements.
- Big Data Analytics:Population-level processing of aggregated cardiac datasets.
- Internet of Medical Things:Networked sensor ecosystems connecting implantable devices to clinical platforms.
Artificial Intelligence captures premium pricing; Machine Learning faces steepest regulatory compliance burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist cardiologist shortages across secondary cities concentrate procurement activity in tertiary hospital networks and telehealth platforms. Gulf Cooperation Council states anchor regional demand through Ministry of Health digitization mandates. South Africa's regulatory infrastructure shapes vendor compliance strategies for sub-Saharan expansion.
Saudi Arabia
Ministry of Health cardiovascular care pathway modernization drives structured procurement of remote patient monitoring infrastructure. Saudi Food and Drug Authority software lifecycle documentation requirements compel vendors to maintain localized quality management systems. Riyadh and Jeddah tertiary hospital networks are consolidating vendor relationships around integrated cardiac informatics platforms.
United Arab Emirates
Specialist cardiologist shortages in secondary cities accelerate telehealth provider adoption of real-time hemodynamic surveillance systems. Ministry of Health and Prevention accelerated pathways for AI-enabled diagnostic tools reshape machine learning module validation timelines. Dubai and Abu Dhabi hospital networks prioritize vendor-managed clinical interpretation services to address workforce gaps.
South Africa
Health Products Regulatory Authority tightening of software validation requirements for connected medical devices extends documentation to adaptive algorithmic components. Non-harmonized requirements with Gulf regulators force parallel quality system maintenance. Johannesburg and Cape Town tertiary facilities operate on-premise electronic health record architectures that resist cloud-native platform integration.
Egypt
CE marking alignment under EU Medical Device Regulation conformity reduces market entry friction for validated software vendors. Asynchronous cardiac data review workflows address specialist shortages in secondary cities. Cairo and Alexandria telehealth operators are expanding fastest where remote consultation platforms create demand for vendor-managed interpretation services.
Nigeria
Secondary city infrastructure gaps limit deployment of real-time monitoring systems requiring continuous connectivity. National regulatory frameworks for software-as-a-service medical devices remain under development. Lagos and Abuja hospital procurement committees prioritize total cost of ownership and integration complexity when evaluating cardiac platform architectures.
Middle East and Africa Heart Failure Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels in Gulf hospital systems. The vendor base organizes into three strategic tiers: diversified medical technology conglomerates with established cardiac device ecosystems, healthcare informatics specialists with integrated imaging and data workflow platforms, and regional infrastructure providers addressing data sovereignty requirements. Dominant competitive moves include unbundling after-sales clinical support from software licensing agreements and partitioning static and adaptive software elements to isolate regulatory exposure.
Within the diversified conglomerate tier, Medtronic plc and Koninklijke Philips N.V. exemplify positioning anchored in cardiac device ecosystems and integrated informatics platforms respectively. Siemens Healthcare Private occupies a position addressing on-premise infrastructure demand from Saudi and Emirati facilities with data sovereignty concerns. These three entities represent how vendor specialization around deployment architecture and regulatory compliance is reshaping competitive positioning across Ministry of Health procurement channels.
| Leading Market Players |
|---|
| Cerner Corporation |
| Koninklijke Philips N.V. |
| Siemens Healthcare Private |
| Medtronic plc |
| Abbott Laboratories |
| GE Healthcare |
| 4S Information Systems Ltd. |
| Axis Clinical Software Inc. |
| CitiusTech Inc. |
| Others |
Supply & Pricing Matrix
Cloud infrastructure subscription indices cascade through cardiac software supply chains, compressing vendor margins on SaaS tiers while elevating premium pricing for on-premise deployments that satisfy Saudi and Emirati data localization mandates. Gulf hospital procurement committees translate these input cost structures into unbundled contracting vehicles that separate platform fees from implementation services.
Pricing Analysis
The bundled-vs-unbundled service split now dominates cardiac software contracting across Middle East and Africa markets. Saudi Ministry of Health tenders distinguish platform subscription fees from cardiologist training and 24-hour monitoring center operations, creating three-tier pricing stratification across premium integrated suites, standard modular platforms, and economy remote monitoring tools. Price differentiation hinges on HL7 FHIR interoperability certification and domestic data hosting compliance. Cost compression in cloud-native tiers is intensifying because Gulf health systems prioritize scalable operational expenditure models. Telehealth providers in secondary Egyptian and Jordanian cities exhibit highest price sensitivity, while tertiary Saudi hospital networks prioritize total cost of ownership over upfront licensing.
Supply Chain Analysis
Logistics and freight cost volatility from Asia-Pacific server component suppliers feeds into extended deployment timelines for on-premise cardiac infrastructure across Gulf Cooperation Council states. Software supply chains draw from Ireland and Netherlands for CE-marked validation documentation, India for HL7 FHIR interface engineering talent, and Singapore for cloud hosting infrastructure serving Middle East latency requirements. Single-source vulnerability concentrates in biomedical informatics professionals capable of configuring device-to-hospital data pipelines. Distribution runs through hospital procurement committees and group purchasing organizations in Riyadh, Dubai, and Johannesburg, with telehealth platforms in Cairo and Lagos emerging as direct contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where vendors exploit regulatory timeline gaps between South Africa's Health Products Regulatory Authority validation requirements and UAE Ministry of Health and Prevention accelerated AI pathways to compress market entry costs.
For Market Incumbents: Lock in Gulf hospital network relationships through multi-year SaaS contracts that embed cybersecurity maintenance obligations, insulating against emerging pure-play remote monitoring specialists. Deepen backward integration into HL7 FHIR interface development capabilities to reduce dependency on scarce biomedical informatics talent. Prioritize certification investment for Saudi Food and Drug Authority software lifecycle documentation to preempt regulatory exclusion.
For New Entrants and Emerging Players: Enter via asynchronous cardiac data review workflows serving Egyptian and Jordanian telehealth providers where specialist cardiologist shortages create immediate demand for vendor-managed interpretation services. Target secondary city hospital procurement in Nigeria and Kenya where real-time monitoring infrastructure gaps limit incumbent platform deployment. Pursue strategic partnerships with 5G infrastructure providers to enable high-fidelity electrocardiogram transmission from patient homes.
For Investors and Strategic Acquirers: Consolidation pressure builds where parallel quality management system maintenance for South African and Saudi regulators fragments vendor operating economics. Long-term viability favors platforms with partitioned static and adaptive software architectures that isolate machine learning regulatory exposure. Acquisition target archetype: regional infrastructure providers with established on-premise deployments in data-sovereignty-sensitive facilities. Signal to monitor: harmonization initiatives between Health Products Regulatory Authority and Gulf regulators that would collapse compliance cost advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR alignment unlocks Egyptian and Moroccan procurement channels for validated software vendors. |
| Hospital System Partnership | Gulf Cooperation Council tertiary network consolidation elevates integrated cardiac informatics platform demand. |
| Software Companion Development | Patient-facing mobile interfaces for medication adherence tracking address post-acute care workflow gaps. |
| Reimbursement Strategy | Structured remote patient monitoring codes under Saudi Ministry of Health digitization mandates enable sustainable revenue. |
| Platform Integration | HL7 FHIR connectivity with legacy electronic health record systems resolves Saudi and South African adoption barriers. |
Research Methodology
Coverage spans Middle East and Africa, with primary inputs from each regional cluster combining structured interviews with hospital procurement officers, biomedical informatics directors, cardiac care unit clinicians, and telehealth platform operators. Secondary validation draws from Saudi Food and Drug Authority software registration databases, South Africa Health Products Regulatory Authority device filings, UAE Ministry of Health and Prevention AI pathway documentation, and hospital procurement tender records. Bottom-up deployment volume estimates triangulate against top-down healthcare IT expenditure projections across the analysis window.
Granularity-level modeling captures cloud versus on-premise deployment splits, AI-enabled versus conventional algorithmic architectures, and tertiary hospital versus telehealth provider end-user segments throughout the projection horizon. CAGRs derive from fitted growth curves applied to validated baseline estimates, with cross-segment consistency checks against cardiovascular disease prevalence trajectories and specialist workforce availability by geography. Industry-specific inputs include implantable hemodynamic sensor adoption curves and 5G infrastructure rollout timelines across Gulf states.
Inputs from regulatory filing databases and hospital procurement platforms were available through the study window; gaps in real-time telehealth provider financial disclosures introduce uncertainty bands around segment growth trajectories. Forecasts reflect assumptions regarding Ministry of Health digitization mandate continuity and CE marking alignment persistence in North African trade frameworks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Patient Portal Market
Digital Health Solutions
Global Patient Engagement Solution Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Women Digital Health Solutions Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
AI Health and Fitness Products Market
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
North America Virtual Reality (VR) Health Market
Digital Health Solutions
Virtual Reality (VR) in Healthcare Market
Digital Health Solutions
US Real World Evidence Solutions Market
Digital Health Solutions
Econsent in Healthcare Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
Mhealth Market