
 L-Cysteine Market | 2026-2036
L-Cysteine Market Size, Share, and Industry Trends Forecast 2026-2036
L-Cysteine Market Analysis
Fermentation engineering talent scarcity is bifurcating the L-Cysteine competitive landscape into biotech-capable producers and legacy chemical manufacturers. Evonik Industries AG leverages its decades of amino acid fermentation expertise to sustain premium positioning in pharmaceutical-grade supply. Ajinomoto Co. Inc. anchors Asian production networks with integrated fermentation complexes. Merck KGaA competes through stringent quality protocols that dominate life science customer specifications.
L-Cysteine is a sulfur-containing proteinogenic amino acid with the molecular formula C₃H₇NO₂S, typically manufactured through microbial fermentation of glucose using genetically optimized bacterial strains or via acid hydrolysis of keratin-rich materials. Its thiol functional group enables disulfide bond formation, making it indispensable for protein stabilization in pharmaceutical formulations, dough conditioning in baked goods, and antioxidant preservation in cosmetics. The pharmaceutical formulations segment leads value capture due to injectable and oral drug stability requirements, while nutritional supplements represent the fastest-growing application as sports nutrition brands expand branched-chain and sulfur-amino acid portfolios. Food additives remain a mature, volume-driven category where L-Cysteine Hydrochloride dominates commodity pricing.
EU REACH substance restrictions and EFSA food additive evaluations shape product formulation standards across European markets, while China's NMPA and SAMR enforce pharmaceutical-grade purity benchmarks that govern export eligibility. The US FDA maintains cGMP oversight of L-Cysteine used in prescription drug manufacturing through active pharmaceutical ingredient documentation requirements. Stakeholders must monitor regulatory divergence between fermentation-derived and chemically synthesized origin classifications, as labeling and import tariff implications are intensifying procurement complexity without harmonized international standards.
Market Dynamics
Fermentation-based L-Cysteine production is consolidating competitive advantage as EU REACH substance restrictions eliminate keratin-extraction methods, concentrating supply capability among biotech-enabled manufacturers with validated bacterial strain libraries and glucose-to-thiol conversion efficiency above 85%.
Growth Catalysts
- Biologics peptide synthesis expansion:Pharmaceutical manufacturers are scaling recombinant protein and antibody-drug conjugate pipelines that require pharmaceutical-grade L-Cysteine for disulfide bond formation in therapeutic molecules.
- EU REACH substance restrictions:The regulatory framework's tightening controls on human hair and duck feather sourcing are accelerating fermentation capacity investments by eliminating lower-cost extraction alternatives.
- Sports nutrition sulfur-amino acid portfolios:Functional food brands are expanding branched-chain amino acid product lines to include L-Cysteine for antioxidant and recovery positioning in premium supplement formulations.
Market Restraints
- Glucose feedstock cost volatility:Corn and wheat-derived glucose prices fluctuate with agricultural commodity cycles, compressing fermentation margins during harvest shortfalls in major grain-producing regions.
- Chinese supply concentration:Over 60% of global fermentation capacity sits within Zhejiang and Shandong provinces, creating geographic risk exposure to regional energy rationing and environmental enforcement actions.
- Keratin hydrolysate substitution:Acid-hydrolyzed poultry feather meal retains cost advantages in animal feed applications, limiting L-Cysteine penetration in non-pharmaceutical nutritional markets.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's accelerated API approval pathways and PLI scheme incentives for fermentation-based manufacturing create first-mover advantages for capacity investments serving domestic and export markets.
- Cosmetic antioxidant positioning:Clean beauty formulations are incorporating L-Cysteine as a glutathione precursor for skin brightening claims, opening premium personal care channels with 3-5x pharmaceutical pricing multiples.
- Continuous fermentation technology:Chemostat and perfusion bioreactor convergence with real-time metabolite sensing enables 40% productivity gains over batch processes, rewarding capital deployment in next-generation facilities.
Industry Challenges
- Fermentation engineering talent scarcity:Industrial microbiology and bioprocess optimization expertise concentrates at established amino acid producers, constraining new entrant scale-up timelines.
- cGMP certification complexity:FDA active pharmaceutical ingredient documentation and EU GMP facility inspections require 18-24 month qualification periods that delay revenue recognition from pharmaceutical customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | L-Cysteine Market |
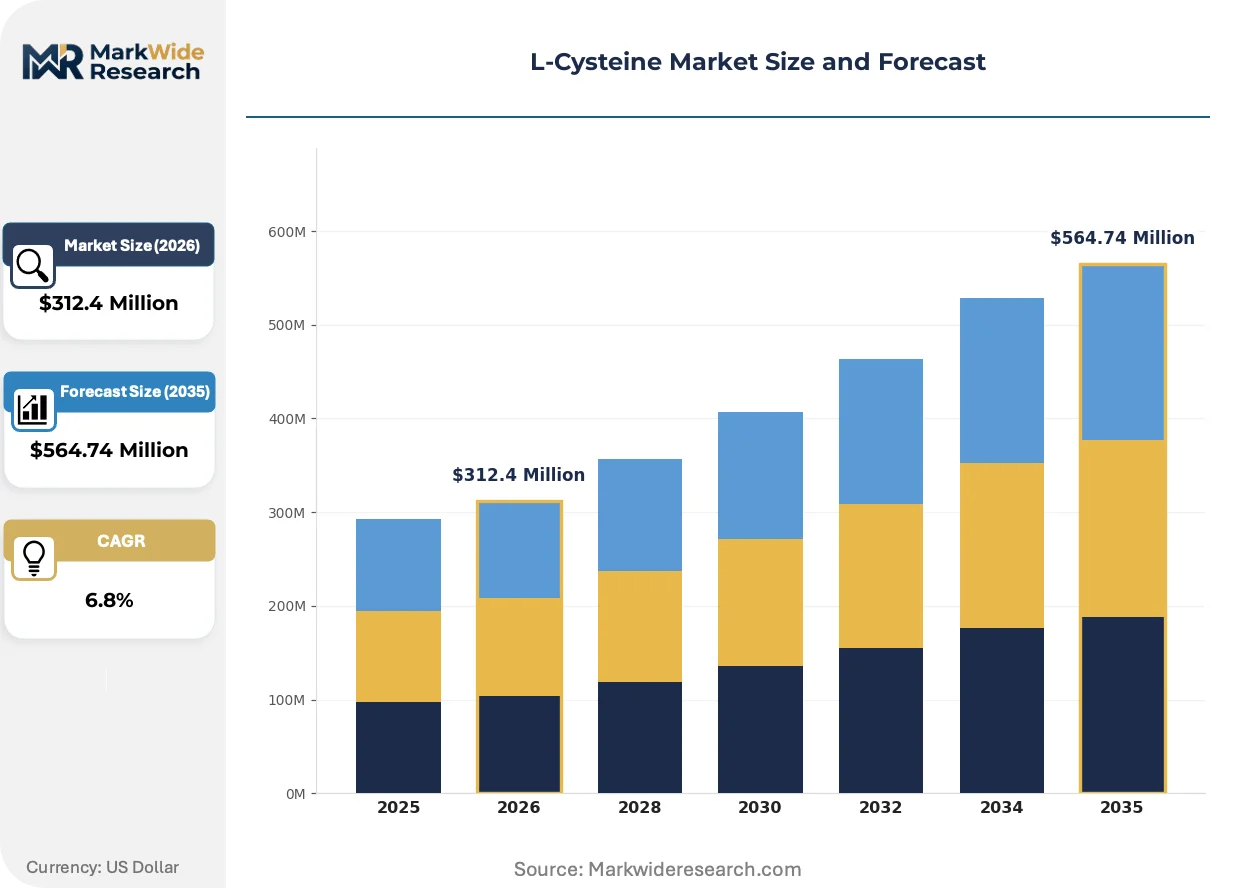
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Cysteine Hydrochloride, L-Cysteine Free Base, L-Cysteine Acetate, L-Cysteine Sodium Application: Food Additives, Pharmaceutical Formulations, Cosmetic Products, Nutritional Supplements End User: Food Industry, Healthcare Sector, Cosmetic Manufacturers, Dietary Supplement Providers Distribution Channel: Online Sales, Direct Sales, Grocery Stores, Specialty Retailers |
| Companies Covered | Merck KGaA, CJ CHEILJEDANG CORP., Wacker Chemie AG, NIPPON RIKA CO., LTD, Shine Star (Hubei) Biological Engineering Co., Ltd., Evonik Industries AG, Zhejiang NHU Co., Ltd., Fengchen Group Co., Ltd., Ajinomoto Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
L-Cysteine Market Emerging Trajectories
Microbial strain engineering and regulatory origin-tracking are restructuring how L-Cysteine is manufactured, certified, and procured across pharmaceutical, food, and cosmetic value chains. Three developments are compressing legacy competitive positions.
CRISPR-optimized Corynebacterium glutamicum strains with enhanced serine O-acetyltransferase expression are supplanting first-generation fermentation hosts. Biologics contract manufacturers are qualifying these engineered lines for pharmaceutical-grade supply within 12-month validation cycles. The technology is compressing yield gaps between established producers and new entrants with access to synthetic biology toolkits.
EFSA's 2023 food additive re-evaluation and EU REACH substance restrictions are bifurcating origin certification requirements. Fermentation-derived L-Cysteine now commands documentation premiums for kosher, halal, and vegan label claims that keratin-sourced material cannot satisfy. European bakery and nutraceutical formulators are restructuring supplier qualification protocols to exclude non-fermentation origins entirely.
Direct contracting between pharmaceutical API buyers and fermentation facilities is disintermediating traditional amino acid distributors. Large molecule CDMOs in Germany, Switzerland, and the United States are establishing multi-year offtake agreements with named-origin fermentation plants. The pattern is most visible in parenteral drug applications where batch traceability requirements exceed distributor documentation capabilities.
L-Cysteine Market Segmentation
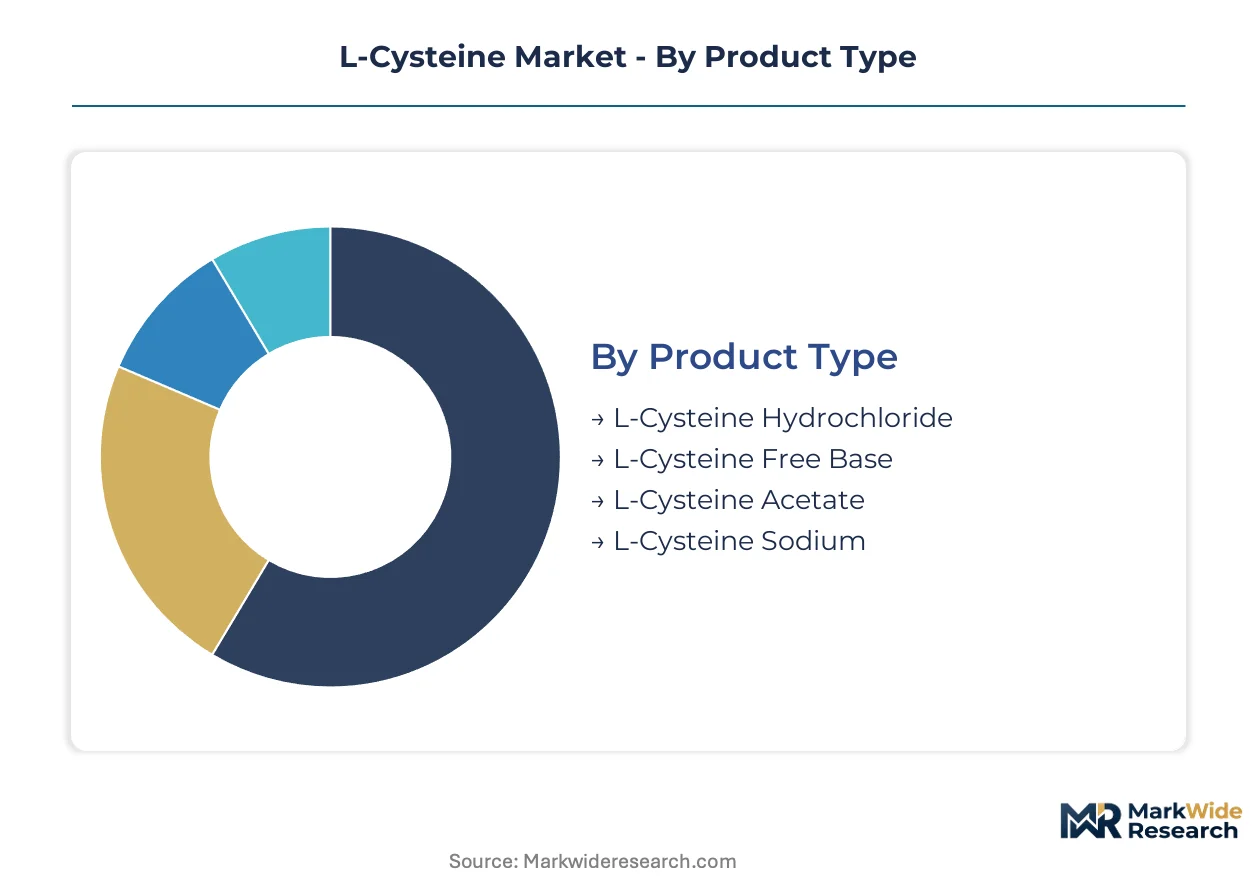
Segmentation in the L-Cysteine market reveals how regulatory origin requirements and application-grade specifications create distinct pricing tiers. Pharmaceutical-grade fermentation-derived material commands substantial premiums over food-grade alternatives, while distribution channels fragment based on documentation complexity.
Product Type:
L-Cysteine Hydrochloride faces the most intense substitution pressure from keratin hydrolysates in animal feed, while fermentation-derived free base and specialty salts defend margin through pharmaceutical and cosmetic certification barriers.
- L-Cysteine Hydrochloride:The monohydrate salt form dominates food additive applications with standardized purity specifications for dough conditioning and flavor enhancement. Bakery manufacturers in Germany and France source this grade under EFSA additive codes, though pricing compresses against acid-hydrolyzed feather meal in non-EU markets.
- L-Cysteine Free Base:The unneutralized amino acid serves parenteral drug formulations requiring precise pH control in biologic stabilization. Injectable antibody manufacturers in Switzerland and Massachusetts specify this grade for disulfide bond engineering in therapeutic proteins.
- L-Cysteine Acetate:The acetate salt variant offers enhanced solubility profiles for liquid nutritional formulations.
- L-Cysteine Sodium:The sodium salt provides alkaline pH compatibility for specific cosmetic buffer systems.
L-Cysteine Hydrochloride anchors the volume base while L-Cysteine Free Base gains share at the steepest rate.
Application:
Application segments diverge sharply by margin structure, with pharmaceutical and cosmetic channels capturing value through certification complexity while food additives compete on commodity efficiency.
- Pharmaceutical Formulations:Peptide synthesis and biologic stabilization require US FDA cGMP-documented, fermentation-origin material with batch-level traceability. Contract development and manufacturing organizations in Germany and Switzerland now mandate direct supplier relationships bypassing traditional distributors to satisfy audit requirements.
- Cosmetic Products:Clean beauty formulations position L-Cysteine as a glutathione precursor for antioxidant and skin-brightening claims. Premium personal care brands in South Korea and France specify fermentation-origin certificates to support vegan and halal labeling.
- Food Additives:Volume-driven bakery and processed meat applications face margin pressure from alternative reducing agents.
- Nutritional Supplements:Sports nutrition brands expand sulfur-amino acid portfolios for recovery positioning.
Food Additives generates the highest shipment volumes while Cosmetic Products expands most quickly through premium positioning.
End User:
End user concentration reflects how quality protocols and procurement scale separate pharmaceutical buyers from commodity food processors.
- Healthcare Sector:Hospital systems, compounding pharmacies, and biologics manufacturers enforce the most stringent supplier qualification protocols. Multi-year offtake agreements with named fermentation facilities are becoming standard for parenteral drug applications in the United States and Germany.
- Food Industry:Industrial bakeries and meat processors represent high-volume, price-sensitive procurement with limited origin documentation requirements.
- Cosmetic Manufacturers:Formulation houses blend L-Cysteine into premium skincare with 3-5x pharmaceutical pricing multiples.
- Dietary Supplement Providers:Contract manufacturers serve sports nutrition brands with capsule and powder formulations.
The Food Industry commands aggregate volume while the Healthcare Sector drives margin expansion through specification tightening.
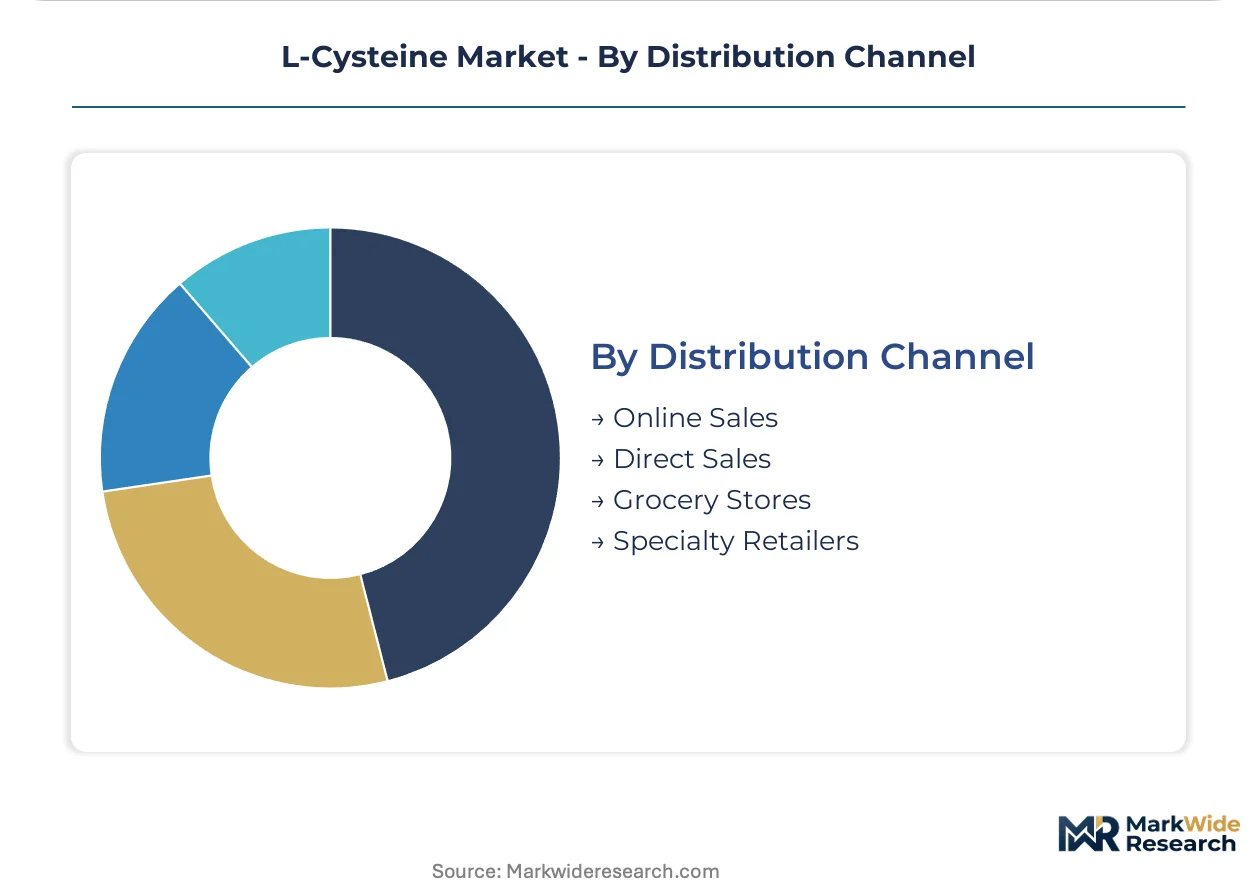
Distribution Channel:
Channel structure fragments based on documentation depth, with pharmaceutical-grade material bypassing traditional intermediaries while commodity grades flow through conventional trade.
- Direct Sales:Pharmaceutical API buyers establish multi-year contracts with named-origin fermentation plants for batch traceability exceeding distributor capabilities. Large molecule CDMOs in Germany, Switzerland, and the United States lead this disintermediation pattern.
- Online Sales:E-commerce platforms serve small-scale cosmetic formulators and specialty food producers with lower minimum order quantities.
- Specialty Retailers:Nutritional supplement channels stock finished formulations rather than raw material.
- Grocery Stores:Consumer-facing retail carries negligible L-Cysteine as standalone product.
Direct Sales captures the value-intensive pharmaceutical segment while Online Sales climbs fastest serving fragmented cosmetic and specialty food demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA and SAMR pharmaceutical-grade purity benchmarks govern export eligibility from Chinese fermentation facilities. EU REACH substance restrictions eliminate keratin-extraction alternatives, concentrating supply capability among biotech-enabled manufacturers. FDA cGMP oversight shapes procurement protocols for injectable drug applications across North American markets.
China
Biologics manufacturers in Zhejiang and Shandong provinces expand peptide synthesis capacity requiring pharmaceutical-grade material. NMPA enforces batch-level traceability documentation for active pharmaceutical ingredient exports. Hangzhou and Weifang anchor regional supply chains where Zhejiang NHU Co., Ltd. and Fengchen Group Co., Ltd. maintain integrated fermentation complexes serving domestic consumption and international markets.
Germany
Large molecule CDMOs in Bavaria and Baden-Württemberg mandate direct supplier relationships for parenteral drug applications. EMA and EFSA coordinate on fermentation-origin certification requirements that exclude keratin-sourced material. Ludwigshafen and Darmstadt host bioprocess engineering clusters where Evonik Industries AG leverages decades of amino acid fermentation expertise for premium pharmaceutical-grade supply.
United States
Antibody-drug conjugate pipelines in Massachusetts and California require disulfide bond engineering capabilities. FDA maintains active pharmaceutical ingredient documentation requirements through cGMP oversight of prescription drug manufacturing. Greater Boston and San Francisco Bay Area biotech corridors drive multi-year offtake agreements with named-origin fermentation plants for batch traceability exceeding distributor capabilities.
India
CDMOs in Maharashtra and Telangana accelerate API approval pathways for fermentation-based manufacturing investments. PLI scheme incentives reward domestic production capacity serving export markets. Hyderabad and Mumbai pharmaceutical clusters attract first-mover advantages as contract manufacturers expand recombinant protein pipelines requiring pharmaceutical-grade L-Cysteine.
Japan
Sports nutrition brands in Kanto and Kansai regions expand sulfur-amino acid portfolios for recovery positioning. PMDA and METI coordinate on quality protocols that separate pharmaceutical-grade from commodity material. Osaka and Tokyo formulation houses source fermentation-derived material for clean beauty applications positioning L-Cysteine as a glutathione precursor.
L-Cysteine Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the L-Cysteine competitive structure. Fermentation engineering talent scarcity bifurcates the landscape into biotech-capable producers with validated bacterial strain libraries and legacy chemical manufacturers without glucose-to-thiol conversion capabilities. Strategic archetypes include integrated fermentation specialists, pharmaceutical-grade purity defenders, and regional volume suppliers. Dominant competitive moves encompass backward integration into glucose feedstock sourcing and cGMP certification investments for API documentation.
Within the integrated fermentation tier, Evonik Industries AG and Ajinomoto Co. Inc. exemplify bioprocess optimization capabilities that sustain premium positioning. Zhejiang NHU Co., Ltd. anchors Chinese supply concentration with domestic and export market reach. Among pharmaceutical-grade purity defenders, Merck KGaA occupies a position defined by stringent quality protocols that dominate life science customer specifications.
| Leading Market Players |
|---|
| Merck KGaA |
| CJ CHEILJEDANG CORP. |
| Wacker Chemie AG |
| NIPPON RIKA CO., LTD |
| Shine Star (Hubei) Biological Engineering Co., Ltd. |
| Evonik Industries AG |
| Zhejiang NHU Co., Ltd. |
| Fengchen Group Co., Ltd. |
| Ajinomoto Co. Inc. |
| Others |
Supply Flow & Price Mechanics
Eighteen-month cGMP qualification timelines for pharmaceutical-grade material concentrate pricing power with established fermentation facilities possessing validated bacterial strain libraries and documented batch traceability. This lead-time barrier bifurcates procurement into long-term offtake contracts for parenteral drug applications and spot-market transactions for food-grade alternatives, with EU REACH substance restrictions eliminating lower-cost keratin-extraction competition entirely.
Pricing Analysis
Chinese export pricing for fermentation-derived L-Cysteine Hydrochloride runs 15-25% below European pharmaceutical-grade quotations, though the spread compresses once cGMP certification and origin documentation requirements are applied. Contract-based long-term offtake agreements dominate pharmaceutical procurement, with price differentiation anchored in certification grade and batch traceability depth rather than volume scale alone. Cost compression in food-grade material intensifies as acid-hydrolyzed poultry feather meal retains cost advantages in animal feed applications. Industrial bakeries and meat processors exhibit highest price sensitivity, while injectable drug manufacturers accept substantial premiums for documented fermentation-origin supply.
Supply Chain Analysis
Sixty-day inventory cycles at Zhejiang and Shandong fermentation complexes reflect glucose feedstock dependency and seasonal agricultural commodity fluctuations. Production concentrates in China, Germany, and Japan, with Chinese facilities drawing from corn and wheat-derived glucose while European plants source beet sugar feedstocks. Supply chain risk centers on single-source vulnerability from geographic concentration in eastern Chinese provinces exposed to regional energy rationing. Distribution runs through direct sales channels for pharmaceutical API buyers and amino acid distributors for commodity food-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial microbiology expertise scarcity constrains new entrant scale-up timelines, creating defensive moats for established producers with validated Corynebacterium glutamicum strain libraries and integrated glucose sourcing.
For Market Incumbents: Fortify cGMP certification portfolios against emerging biotech-enabled competitors by accelerating continuous fermentation technology deployment in next-generation facilities. Backward integration into glucose feedstock sourcing mitigates margin compression from agricultural commodity volatility. Secure multi-year offtake agreements with large molecule CDMOs in Germany and Switzerland before synthetic biology toolkits democratize strain engineering capabilities. For New Entrants and Emerging Players: Cosmetic formulation services for clean beauty brands represent an under-served channel where fermentation-origin certificates command 3-5x pharmaceutical pricing multiples. Indian pharmaceutical manufacturing clusters offer penetrable white-space as CDSCO accelerated API approval pathways and PLI scheme incentives attract first-mover capacity investments. Pursue direct contracting relationships with South Korean and French personal care formulators seeking glutathione precursor positioning. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-origins play because EU REACH substance restrictions and EFSA re-evaluations permanently eliminate keratin-extraction alternatives, entrenching fermentation-capable asset values. Target acquisition candidates with validated bacterial strain libraries and existing cGMP documentation rather than greenfield fermentation engineering projects. Monitor CRISPR-optimized strain validation cycles as the inflection signal for competitive yield convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Technology Deployment | Chemostat and perfusion bioreactor convergence with real-time metabolite sensing enables productivity gains over batch processes. |
| Backward Integration into Glucose Feedstock | Captive corn and wheat sourcing mitigates margin compression from agricultural commodity price volatility in major grain-producing regions. |
| cGMP Certification Investment | FDA active pharmaceutical ingredient documentation and EU GMP facility inspections secure 18-24 month qualification barriers against new entrants. |
| Direct Sales Channel Establishment | Multi-year offtake agreements with named-origin fermentation plants satisfy batch traceability requirements exceeding distributor capabilities. |
| Cosmetic Application Expansion | Clean beauty formulations positioning L-Cysteine as glutathione precursor open premium personal care channels with superior pricing multiples. |
Methodological Framework
A spread of perspectives from fermentation engineering directors, pharmaceutical procurement managers at biologics CDMOs, regulatory affairs leads at amino acid manufacturers, and cosmetic formulators converged on the working assumptions. Primary interviews combined with secondary validation from NMPA export documentation, EFSA food additive evaluations, FDA cGMP inspection records, and customs trade data. Bottom-up capacity assessments at Zhejiang and Shandong fermentation facilities triangulated against top-down demand modeling from peptide synthesis and biologic stabilization applications.
Segmentation dimensions modeled include product type, application grade, end-user industry, and distribution channel across the analysis window. CAGRs derived from production capacity expansion timelines, regulatory transition curves from keratin-extraction to fermentation-origin material, and end-use demand elasticity in pharmaceutical versus food additive segments. Forecast inputs incorporated glucose feedstock price scenarios and cGMP qualification pipeline visibility from named fermentation facilities.
Underlying assumptions cover sustained EU REACH substance restriction enforcement and Chinese environmental compliance continuity, with deviation risk concentrated in agricultural commodity harvest variability and synthetic biology strain engineering acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Global Sodium Lignosulfonate Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Amino Acids Market
Functional Chemicals
Soy-Based Chemical Market
Functional Chemicals
Serine Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
2-Propylheptanol Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Sodium Lauroyl Glutamate Market
Functional Chemicals
Jellyfish-Derived Peptide Ingredient Concepts Market
Functional Chemicals
Thiamine Market