
 Industrial Grade Urea Market | 2026-2036
Industrial Grade Urea Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Grade Urea Market Foresight
Aftermarket service revenue from technical advisory and soil-testing programs is tilting toward integrated suppliers with captive agronomy teams. Yara International ASA leverages its digital farming platform to lock in recurring service contracts alongside bulk urea shipments. CF Industries Holdings, Inc. sustains margin capture through backward integration into natural gas feedstock and ammonia production. Nutrien Ltd. anchors North American distribution through its owned retail network of farm-service centers.
Industrial grade urea refers to synthetic carbamide containing minimum 46% nitrogen by weight, produced via the Bosch-Haber process combining ammonia and carbon dioxide under high pressure, primarily serving as a nitrogen source for crop nutrition and industrial chemical synthesis. Prilled urea dominates high-volume export corridors due to lower production energy intensity and superior flowability in bulk handling systems. Granular urea commands premium positioning in mechanical spreading applications where particle uniformity reduces application drift. Coated urea variants are gaining traction in specialty agriculture segments where controlled-release nitrogen aligns with nutrient management regulations and precision farming protocols.
The EPA oversees air emissions from urea manufacturing under Clean Air Act provisions, while REACH governs chemical registration and safe handling protocols across European supply chains, and India's Fertilizer Control Order mandates quality specifications and pricing controls for domestic distribution. These regulatory frameworks shape product formulation requirements, manufacturing site permitting, and cross-border trade compliance costs. Stakeholders must monitor evolving carbon accounting rules and border tax mechanisms that will restructure competitive positioning between gas-advantaged producers and import-dependent markets.
Market Dynamics
Natural gas feedstock concentration in the Middle East and Russia is restructuring competitive economics for ammonia-integrated urea producers, forcing import-dependent buyers to absorb carbon border adjustment costs while subsidized domestic manufacturing in India captures volume share.
Growth Catalysts
- India's Fertilizer Control Order:Government-mandated quality specifications and subsidized distribution networks accelerate offtake from domestic manufacturing clusters serving soil health programs.
- Precision agriculture adoption:Specialty coated urea variants align with nutrient management regulations in developed agricultural economies, expanding premium product penetration.
- Carbon capture integration:Bosch-Haber process modifications utilizing captured CO2 streams reduce compliance exposure under emerging carbon accounting frameworks.
Market Restraints
- Feedstock volatility:Natural gas price swings in European supply contracts compress margins for non-integrated nitrogen fertilizer producers.
- Geographic supply concentration:Ammonia production clustering in gas-advantaged regions exposes import-dependent buyers to shipping cost spikes and currency fluctuation.
- Substitution pressure:Ammonium nitrate and calcium ammonium nitrate alternatives displace urea in explosive and select industrial chemical applications.
Strategic Opportunities
- Controlled-release technology convergence:Polymer coating innovations combined with digital soil-monitoring platforms open premium positioning in specialty agriculture segments.
- EU F-Gas Regulation tailwinds:Refrigeration-grade urea demand for transport and stationary cooling systems expands as fluorinated gas phase-outs accelerate.
- Direct-to-farm channel innovation:Bypassing traditional wholesale distributors through owned agronomy service centers captures margin and locks in recurring technical advisory revenue.
Industry Challenges
- Process engineering talent scarcity:Specialized expertise in high-pressure ammonia synthesis and carbon capture retrofitting commands premium compensation, constraining capacity expansion timelines.
- Permitting complexity:EPA Clean Air Act pre-construction reviews and state-level environmental impact assessments extend greenfield urea plant commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Grade Urea Market |
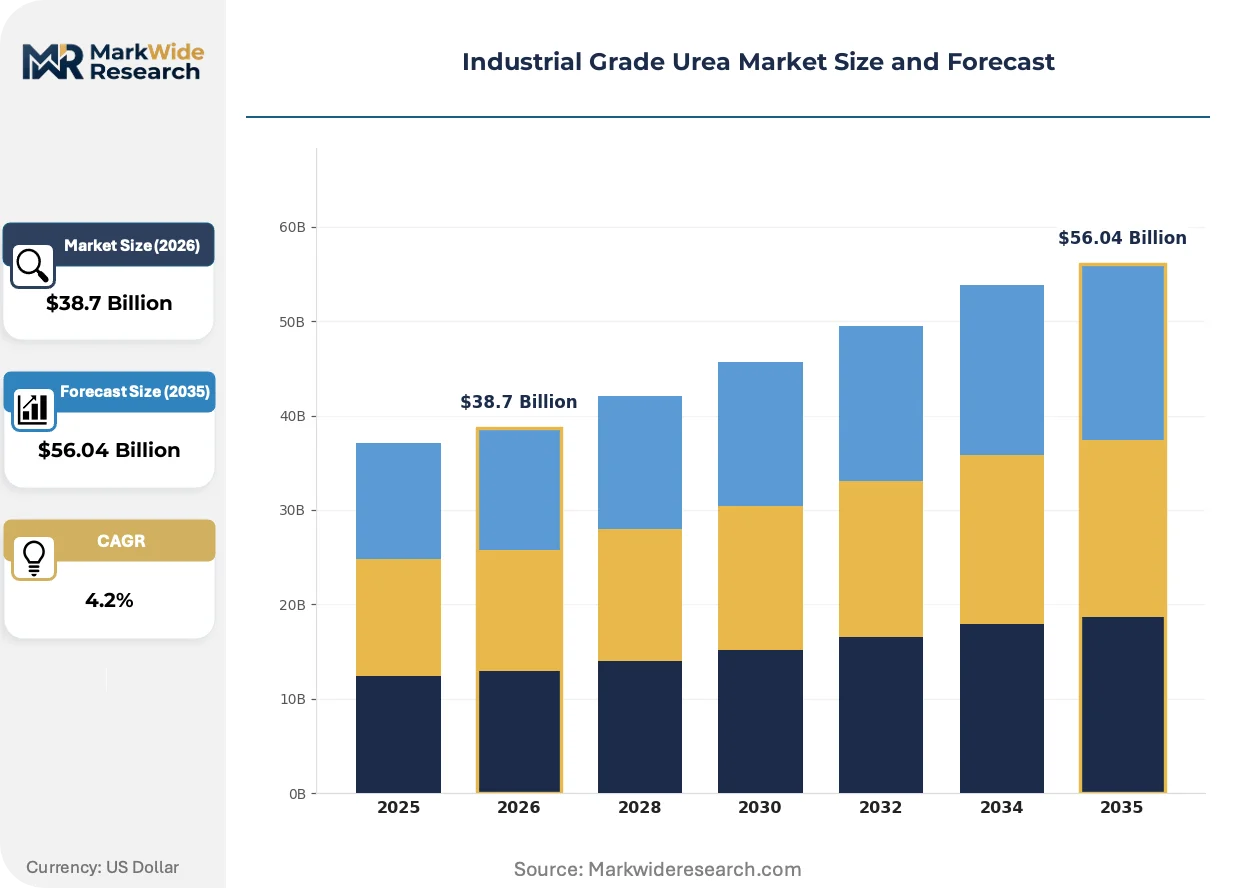
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Urea, Prilled Urea, Liquid Urea, Coated Urea Application: Agriculture, Chemical Manufacturing, Fertilizer Production, Animal Feed End User: Farms, Manufacturing Plants, Animal Farms, Research Institutions Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Agrochemical Dealers |
| Companies Covered | Yara International ASA, CF Industries Holdings, Inc., Nutrien Ltd., OCI Global N.V., EuroChem Group AG, SABIC Agri-Nutrients Company, Qatar Fertiliser Company (QAFCO), Acron Group, Koch Fertilizer, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Grade Urea Market Shifts & Advancements
Digital farming platforms and controlled-release formulations are compressing traditional commodity pricing power while regulatory carbon accounting forces process technology reinvestment across nitrogen fertilizer manufacturing.
Stabilized urea incorporating nitrification and urease inhibitors is collapsing the volume premium previously commanded by slow-release alternatives. Large-scale grain operations in the US Corn Belt and Brazilian Cerrado are adopting inhibitor-treated products at accelerating rates. The technology is collapsing differentiation between standard and coated urea in bulk procurement tenders, forcing coating specialists to emphasize micronutrient integration rather than nitrogen release control.
REACH chemical registration requirements and the EU's Carbon Border Adjustment Mechanism are reshaping import compliance costs for nitrogen-based inputs. Manufacturers must document embedded emissions across ammonia feedstock supply chains to maintain market access. Granular urea shipments into Rotterdam and Antwerp terminals face heightened scrutiny, prompting Middle Eastern exporters to invest in certified low-carbon ammonia production.
Integrated suppliers are unbundling technical advisory services from bulk product sales, converting one-time transactions into recurring revenue streams. Farm-service centers owned by major distributors now lead soil-testing programs and variable-rate application recommendations. This shift is most visible in North American row-crop agriculture, where cooperative purchasing groups negotiate multi-year agronomy contracts alongside volume urea commitments.
Industrial Grade Urea Market Segmentation
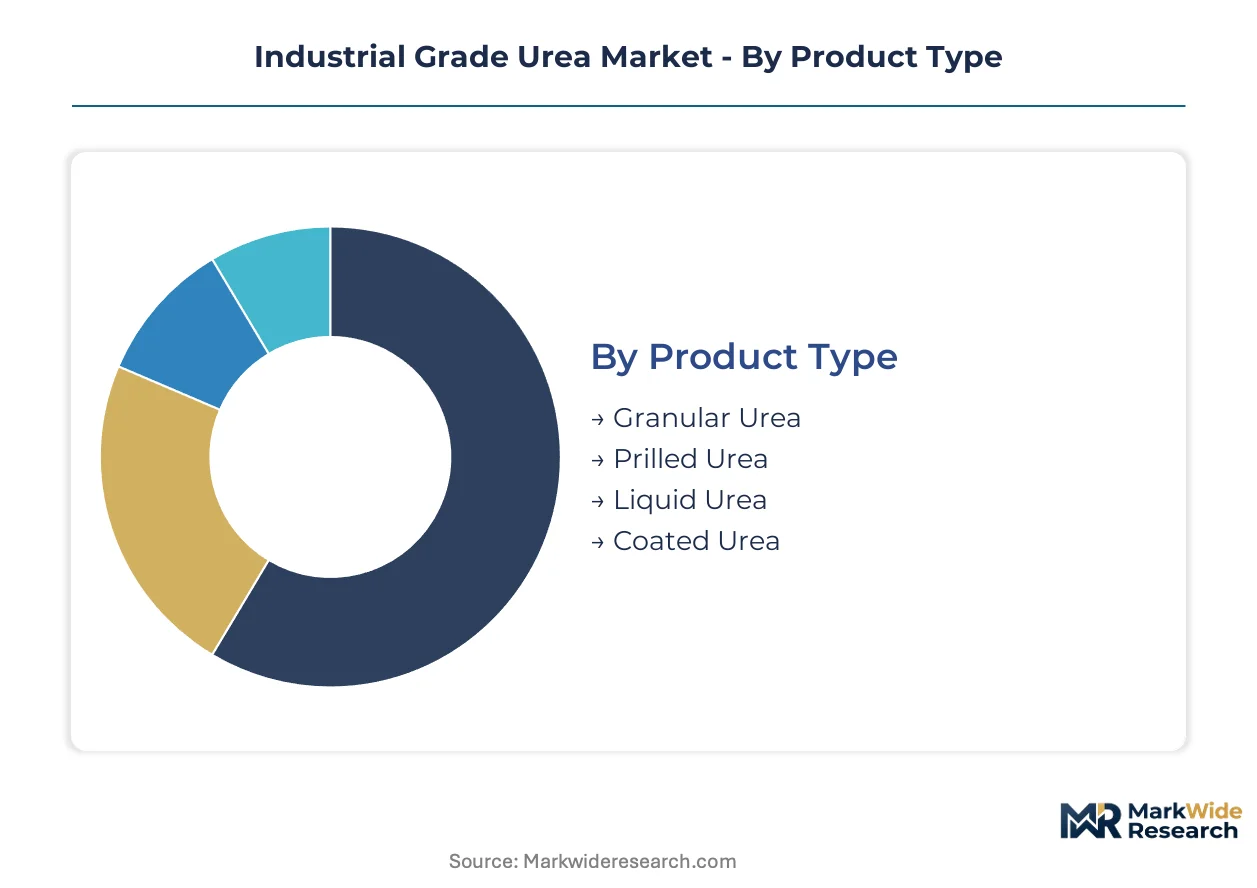
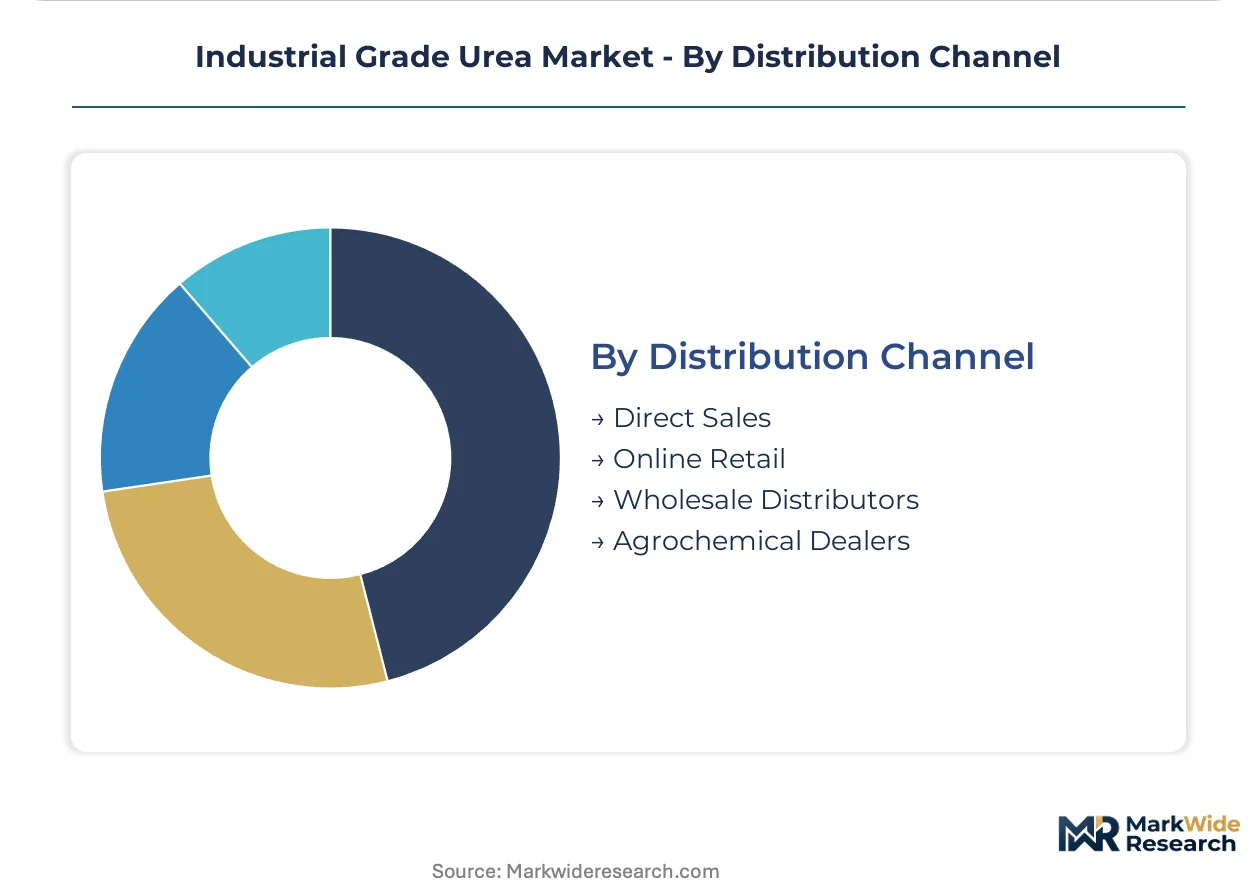
Industrial grade urea segments by physical form, downstream use, customer type, and channel structure. Each dimension captures distinct margin profiles and regulatory exposure.
Product Type:
Use-case spectrum spans bulk commodity handling to precision application systems.
- Granular Urea:Hard, spherical particles sized 2-4mm with superior crush strength and flowability. Mechanical spreading operations in the US Corn Belt and Brazilian Cerrado drive procurement, where particle uniformity reduces application drift and improves nitrogen placement accuracy.
- Prilled Urea:Smaller, softer spheres produced via spray-drying with lower energy intensity per ton. High-volume export corridors from Middle Eastern production clusters favor this form for bulk vessel loading and long-haul ocean freight economics.
- Liquid Urea:Aqueous solutions containing 32% nitrogen by weight, typically UAN (urea-ammonium nitrate) formulations. Fertigation systems and center-pivot irrigation in water-scarce agricultural regions absorb this form for direct soil injection.
- Coated Urea:Polymer or sulfur-encapsulated variants enabling controlled nitrogen release. Specialty agriculture segments in the European Union and Japan adopt these for compliance with nutrient management regulations and reduced leaching mandates.
The dominant share belongs to prilled urea, while coated urea is closing the gap fastest.
Application:
Cost tier differentiation separates commodity nitrogen sales from value-added chemical synthesis.
- Agriculture:Direct soil application as straight fertilizer or in NPK blends. India's subsidized distribution network under the Fertilizer Control Order channels volume through domestic manufacturing clusters serving soil health programs.
- Chemical Manufacturing:Feedstock for melamine, urea-formaldehyde resins, and diesel exhaust fluid production. REACH registration requirements and EU Carbon Border Adjustment Mechanism documentation reshape import compliance costs for European chemical processors.
- Fertilizer Production:Intermediate input for compound and specialty fertilizer blending. Integrated producers with captive ammonia supply capture margin through backward integration into natural gas feedstock.
- Animal Feed:Ruminant feed additive providing non-protein nitrogen for microbial protein synthesis. Quality specifications under FDA and equivalent national regulators govern inclusion rates and purity thresholds.
Agriculture commands volume leadership, though chemical manufacturing delivers the steepest expansion trajectory.
End User:
Customer type determines service bundling requirements and procurement contract structures.
- Farms:Row-crop operations, specialty crop producers, and cooperative purchasing groups. North American farm-service centers now bundle soil-testing programs with multi-year urea supply agreements.
- Manufacturing Plants:Chemical processors, resin producers, and emissions control fluid blenders. These buyers prioritize certified low-carbon ammonia documentation for EU market access.
- Animal Farms:Cattle feedlots and dairy operations incorporating urea into total mixed rations. Regulatory compliance with national feed safety authorities constrains supplier qualification.
- Research Institutions:Agricultural universities and soil science laboratories conducting controlled-release trials and nitrification inhibitor studies.
Farms absorb the dominant procurement volume, while manufacturing plants are gaining share fastest.
Distribution Channel:
Supply concentration in gas-advantaged regions dictates channel economics and margin capture.
- Direct Sales:Producer-to-end-user contracts for large-volume agricultural and industrial buyers. Major suppliers deploy captive agronomy teams to convert transactions into recurring technical advisory revenue.
- Online Retail:Digital platforms serving smallholder farmers and specialty crop producers with packaged urea products. Logistics complexity limits penetration for bulk commodity grades.
- Wholesale Distributors:Regional aggregators managing inventory and credit risk for import-dependent markets. Currency fluctuation and shipping cost spikes compress their margin stability.
- Agrochemical Dealers:Local retail networks providing application equipment and agronomic guidance. These intermediaries face displacement pressure from direct-to-farm channel innovation.
Direct sales holds the dominant position, while agrochemical dealers are losing ground fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes industrial grade urea predominantly through subsidized agricultural channels, while European buyers prioritize certified low-carbon grades for chemical manufacturing under border adjustment rules. This consumption-mix differential fragments procurement priorities across major demand centers.
India
Soil health programs and subsidized fertilizer distribution drive volume through domestic manufacturing clusters. The Fertilizer Control Order mandates quality specifications and pricing controls that channel offtake toward government-authorized suppliers. Gujarat and Maharashtra host concentrated production corridors serving northern grain belts.
United States
Mechanical spreading operations in the Corn Belt absorb granular urea for precision nitrogen placement. EPA Clean Air Act provisions govern manufacturing emissions, extending permitting timelines for capacity additions. Louisiana and Iowa anchor the supply-demand interface through ammonia-integrated plants and farm-service center networks.
Germany
Chemical processors procure industrial grade urea for melamine and resin synthesis under REACH registration requirements. The EU Carbon Border Adjustment Mechanism reshapes import compliance costs, favoring suppliers with documented low-carbon ammonia certification. The Rhine-Ruhr industrial corridor concentrates demand from downstream chemical manufacturers.
China
Domestic fertilizer blending and diesel exhaust fluid production absorb substantial urea volumes. GB standards and dual carbon goals under MEE oversight pressure producers toward carbon capture retrofits. Shandong Province and the Yangtze River Delta host manufacturing clusters supplying both agricultural and industrial chemical channels.
Brazil
The Cerrado agricultural frontier drives granular urea demand for soybean and corn production systems. ANVISA and national agricultural regulators govern import quality standards for fertilizer products. Mato Grosso and Rio Grande do Sul concentrate procurement through port terminals receiving Middle Eastern shipments.
Industrial Grade Urea Market Competitive Landscape
Capability concentration sits with integrated producers possessing captive ammonia supply; scale advantage sits with gas-advantaged exporters in the Middle East and Russia. The market structures around three tiers: backward-integrated nitrogen majors, state-linked gas-feedstock exporters, and regional distributors with agronomy service bundling. Dominant competitive moves include direct-to-farm channel expansion and carbon capture technology licensing for compliance positioning.
Within the integrated nitrogen major tier, Yara International ASA, CF Industries Holdings, Inc., and Nutrien Ltd. exemplify divergent geographic and strategic positioning. Yara anchors European and Brazilian market presence through digital farming platform integration. CF Industries occupies a position defined by North American natural gas feedstock access and ammonia production scale. Nutrien represents the retail-network model, capturing margin through owned farm-service centers rather than wholesale distribution.
| Leading Market Players |
|---|
| Yara International ASA |
| CF Industries Holdings, Inc. |
| Nutrien Ltd. |
| OCI Global N.V. |
| EuroChem Group AG |
| SABIC Agri-Nutrients Company |
| Qatar Fertiliser Company (QAFCO) |
| Acron Group |
| Koch Fertilizer, LLC |
| Others |
Supply & Pricing Matrix
Overcapacity in Middle Eastern ammonia-integrated plants compresses spot premiums while tightening European contract negotiations, forcing buyers to absorb carbon border adjustment costs and suppliers to prioritize long-term offtake security over volume maximization.
Pricing Analysis
Long-term offtake contracts dominate procurement for import-dependent buyers seeking feedstock security, while spot markets absorb residual volume from gas-advantaged exporters. Price differentiation hinges on carbon intensity certification and volume scale, with Rotterdam-quoted granular urea commanding premiums over prilled alternatives. Pricing pressure intensifies as stabilized urea with nitrification inhibitors collapses the premium previously captured by polymer-coated variants. Large cooperative purchasing groups in North America exhibit lowest price sensitivity due to bundled agronomy service contracts, while smallholder distributors in fragmented Asian markets face acute margin compression.
Supply Chain Analysis
Ammonia production concentrates in Qatar, Saudi Arabia, and Russia, where integrated petrochemical complexes feed urea granulation trains. Natural gas feedstock, carbon dioxide capture streams, and high-pressure synthesis catalysts constitute critical input dependencies. Single-source vulnerability from Strait of Hormuz transit routes exposes Asian buyers to shipping cost spikes and currency fluctuation. Distribution runs through port-terminal aggregators managing bulk vessel logistics, with inland movement relying on rail and barge networks serving farm-service centers and chemical manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial grade urea market functions as a defensive-moat industry where regulatory entrenchment through carbon accounting documentation and captive ammonia supply creates durable competitive positioning for integrated incumbents.
For Market Incumbents: Build switching-cost moats through multi-year agronomy service contracts that embed soil-testing programs and variable-rate application recommendations alongside bulk urea shipments. Deepen backward integration into certified low-carbon ammonia production to preempt EU Carbon Border Adjustment Mechanism compliance exposure. Defend against stabilized urea substitution by accelerating micronutrient integration in coating formulations rather than competing on nitrogen release control alone. For New Entrants and Emerging Players: Mid-tier chemical processors in Southeast Asia seeking certified low-carbon feedstock represent the most penetrable entry point for specialty urea variants with documented emissions profiles. Direct-to-farm channel innovation in Brazilian Cerrado cooperatives bypasses entrenched wholesale distributors through owned agronomy service centers. Partner with digital farming platforms to capture recurring technical advisory revenue rather than competing solely on commodity volume. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated suppliers with captive retail networks bundling soil-testing programs with multi-year supply agreements. Long-term viability favors acquisition targets possessing ammonia-integrated production and established farm-service center footprints over pure-play distributors exposed to margin compression. Monitor carbon capture retrofit deployment rates as inflection indicator for compliance positioning under emerging border adjustment mechanisms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Gas Feedstock | CF Industries anchors margin capture through Louisiana ammonia production and pipeline access. |
| Carbon Capture Technology Licensing | Qatari exporters secure EU market access via certified low-carbon ammonia documentation. |
| Direct-to-Farm Channel Expansion | Nutrien converts transactions into recurring agronomy contracts through owned retail networks. |
| Controlled-Release Coating Innovation | Specialty agriculture segments in Japan adopt polymer-encapsulated variants for nutrient management compliance. |
| Long-term Supply Agreement Structuring | Indian domestic manufacturers lock in volume through Fertilizer Control Order authorized distribution. |
Research Methodology
A spread of perspectives from plant operations managers, procurement leads at downstream chemical processors, distribution channel partners, and technical R&D directors converged on the working assumptions underlying demand modeling. Primary fieldwork combined structured interviews with secondary validation against customs and trade data, ACC and Cefic industry reports, and SEC 10-K disclosures from nitrogen fertilizer majors. Bottom-up segment sizing triangulated against top-down macroeconomic indicators to ensure internal consistency across the analysis window.
Demand-supply balance dynamics anchored the forecast framework, with granular urea, prilled urea, liquid UAN, and coated variants modeled separately alongside agriculture, chemical manufacturing, and animal feed end-use segments. CAGRs derived from trend extrapolation adjusted for regulatory inflection points and feedstock cost trajectories. Carbon border adjustment implementation timelines and natural gas contract structures in European supply agreements served as critical forecast inputs.
Practitioners should monitor carbon capture retrofit deployment rates, EU Carbon Border Adjustment Mechanism enforcement thresholds, and stabilized urea adoption curves in the US Corn Belt for early signals of competitive repositioning. Forecasts reflect assumptions regarding regulatory continuity and feedstock cost trajectories that could revise materially under policy discontinuity or supply disruption scenarios. Quarterly review of ammonia plant utilization rates, shipping cost indices, and agronomy service contract renewal rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Backing Material Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Europe Molecular Sieve Market
Industrial Chemicals
Alkyl Acrylate Market
Industrial Chemicals
North America Biocides Market
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
Organophosphate Insecticides Market
Industrial Chemicals
Industrial Phosphate Market
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Explosion Venting Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Asia-Pacific Activated Carbon Market