
 Para-Aminophenol Market | 2026-2036
Para-Aminophenol Market Size, Share, and Industry Trends Forecast 2026-2036
Para-Aminophenol Market Insights
ISO 9001 certification is unwinding competitive access across the Para-Aminophenol supply base, filtering out smaller traders who cannot sustain documented quality systems. Valiant Organics leverages backward integration into nitrobenzene feedstock to control input costs across its Indian manufacturing footprint. SEQENS anchors European supply through its multi-site pharmaceutical chemical network, while Taixing Yangzi Pharm Chemical dominates volume output from the Yangtze River Delta cluster.
Para-aminophenol is an aromatic amine with molecular formula C6H7NO, synthesized primarily through catalytic hydrogenation of nitrobenzene or iron-acid reduction routes, serving as the principal precursor for paracetamol production and a coupling component in azo dye chemistry. Pharmaceutical grade material commands the deepest margin pool due to USP and EP compliance burdens, while hair dye application represents the most price-sensitive volume segment where industrial grade specifications prevail. Analytical grade volumes remain thin but carry premium pricing for research laboratory end users who require certified reference material traceability.
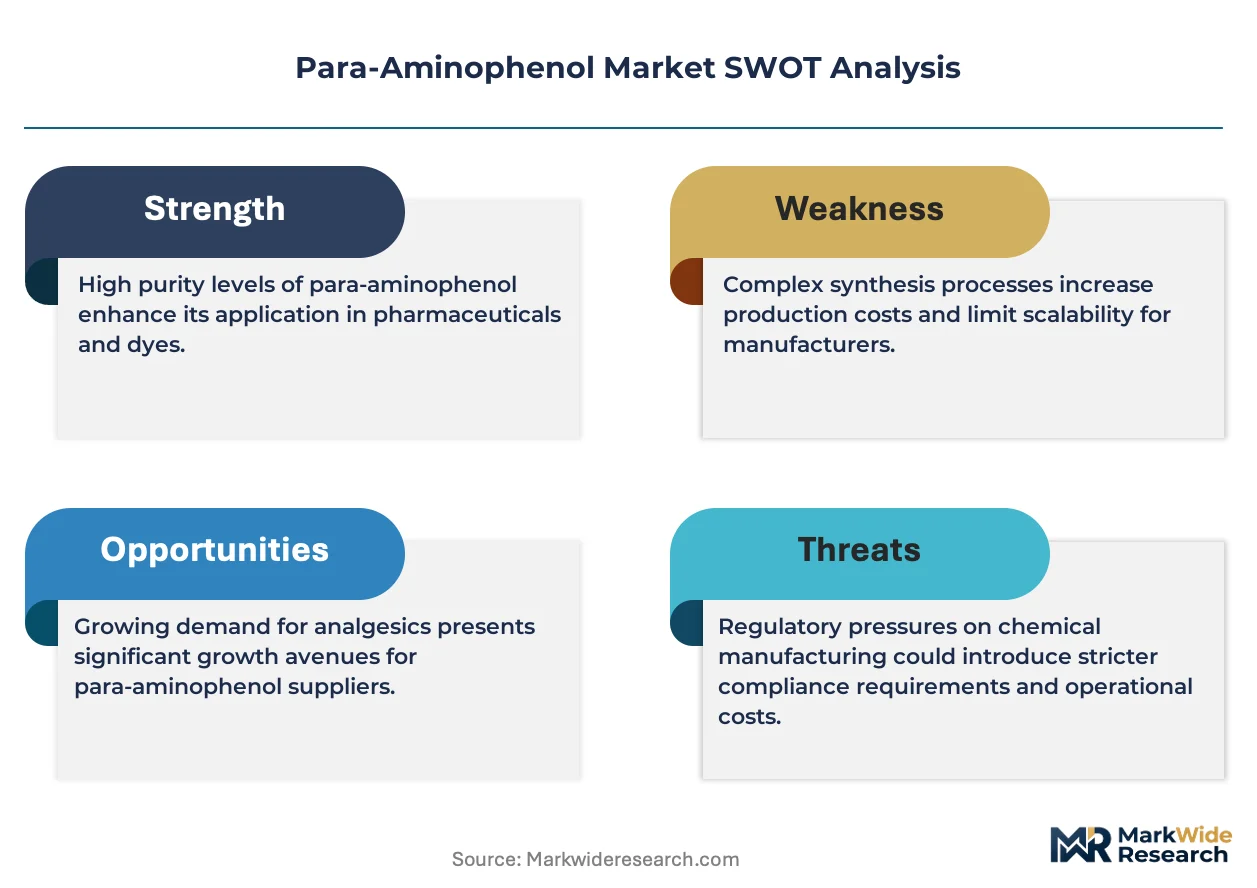
EPA regulations in the United States and REACH registration requirements in Europe impose divergent toxicity testing and documentation burdens on exporters, effectively segmenting market access by regulatory preparedness rather than manufacturing cost alone. India's CDSCO aligns with ICH Q3C guidelines for residual solvent limits, creating a harmonization pathway for API-grade producers serving multiple jurisdictions. Stakeholders must monitor regulatory divergence between pharmaceutical and industrial grade standards, as tightening purity thresholds in one segment rarely propagate evenly across all application categories.
Market Dynamics
Pharmaceutical grade certification requirements are compressing supplier margins while concentrating procurement among vertically integrated API manufacturers who can absorb compliance costs across paracetamol production.
Growth Catalysts
- India's PLI scheme for bulk drugs:Production-linked incentives draw capacity investments into pharmaceutical-grade para-aminophenol manufacturing, reducing import dependency for domestic API synthesis.
- REACH registration tiering:European chemical regulation creates differentiated market access, rewarding producers who complete full substance dossiers with preferential supply relationships to EU formulators.
- Catalytic hydrogenation advances:Continuous-flow reactor designs lower nitrobenzene conversion costs, improving yield efficiency for producers operating at pharmaceutical purity thresholds.
Market Restraints
- Nitrobenzene price volatility:Feedstock cost swings transmit directly to para-aminophenol production economics, compressing margins for non-integrated manufacturers lacking captive aniline supply.
- Yangtze River Delta concentration:Volume output clusters in China's Jiangsu province, exposing global buyers to single-region weather, environmental enforcement, and logistics disruption risks.
- Iron-acid reduction phase-out:Legacy batch processes face tightening wastewater discharge limits, forcing capital-intensive upgrades or shutdowns among smaller Indian and Chinese producers.
Strategic Opportunities
- CDSCO-ICH harmonization:India's alignment with international residual solvent guidelines streamlines multi-jurisdiction certification for API-grade producers, opening simultaneous EU and US market access.
- Azo dye coupling agent specialization:Industrial grade specifications for hair colorant applications reward producers who optimize batch consistency for cosmetic formulators seeking reliable coupling performance.
- Direct-to-laboratory distribution:Analytical grade reference material bypasses traditional chemical distributors, enabling premium pricing through certified traceability documentation for research institutions.
Industry Challenges
- USP and EP compliance timelines:Pharmaceutical grade certification requires extended stability testing and documentation preparation, delaying revenue recognition for new production lines by multiple quarters.
- Multi-site audit coordination:Global pharmaceutical buyers demand synchronized quality system verification across manufacturing locations, straining quality assurance staffing at mid-scale suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Para-Aminophenol Market |
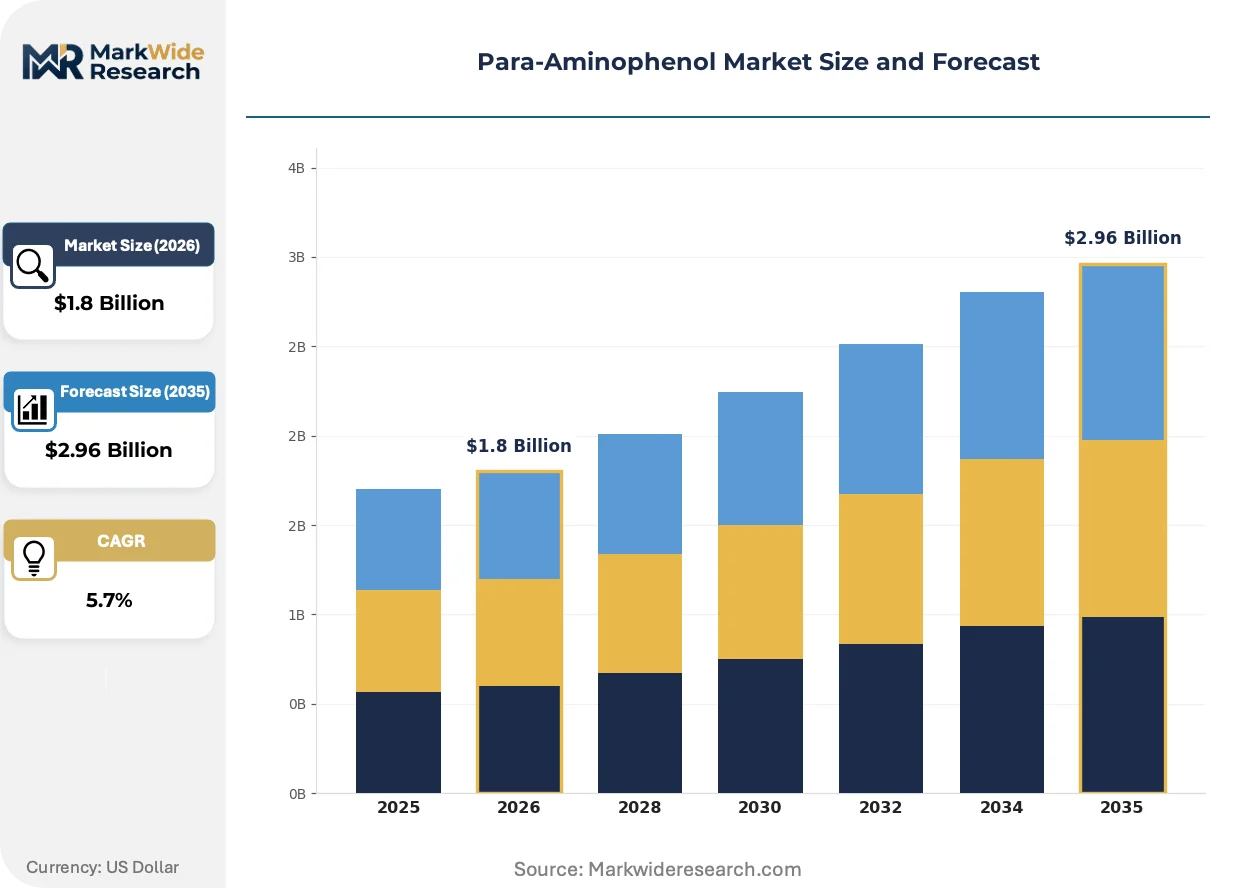
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Industrial Grade, Analytical Grade, Technical Grade Application: Hair Dye, Antipyretics, Dye Intermediates, Rubber Processing Chemicals End User: Pharmaceutical Manufacturers, Cosmetic Producers, Chemical Suppliers, Research Laboratories Packaging Type: Drums, Bags, Bulk Containers, Bottles |
| Companies Covered | Glentham Life Sciences, Wego Chemical Group, Central Drug House, Taixing Yangzi Pharm Chemical, Haihang Industry, Hefei TNJ Chemical Industry, Valiant Organics, SEQENS, Sadhana Nitro Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Para-Aminophenol Market Trends and Innovations
Continuous processing technology is displacing batch manufacturing economics, while regulatory divergence between pharmaceutical and industrial grade standards forces dual-track quality system investments.
Membrane separation technology for final purification is fragmenting the competitive landscape between established crystallization specialists and new entrants. Pharmaceutical formulators in Germany and Switzerland are piloting membrane-polished material for high-purity paracetamol synthesis. This diffusion is fragmenting traditional supply relationships as buyers qualify alternative purification routes.
EPA toxic substance reporting under TSCA Section 8 is tightening documentation burdens for US-imported para-aminophenol. The regulation forces foreign manufacturers to disclose supply chain chemical safety data previously treated as proprietary. API-grade exporters to the United States are responding by segregating US-bound production lines with dedicated compliance documentation systems.
Long-term offtake contracting is displacing spot market purchases among European pharmaceutical manufacturers. Large API producers in Italy and Spain now secure eighteen to twenty-four month supply agreements with fixed volume tiers, replacing quarterly competitive bidding. This shift is most visible in the paracetamol precursor segment, where formulators prioritize supply security over price optimization amid recent raw material volatility.
Para-Aminophenol Market Segmentation
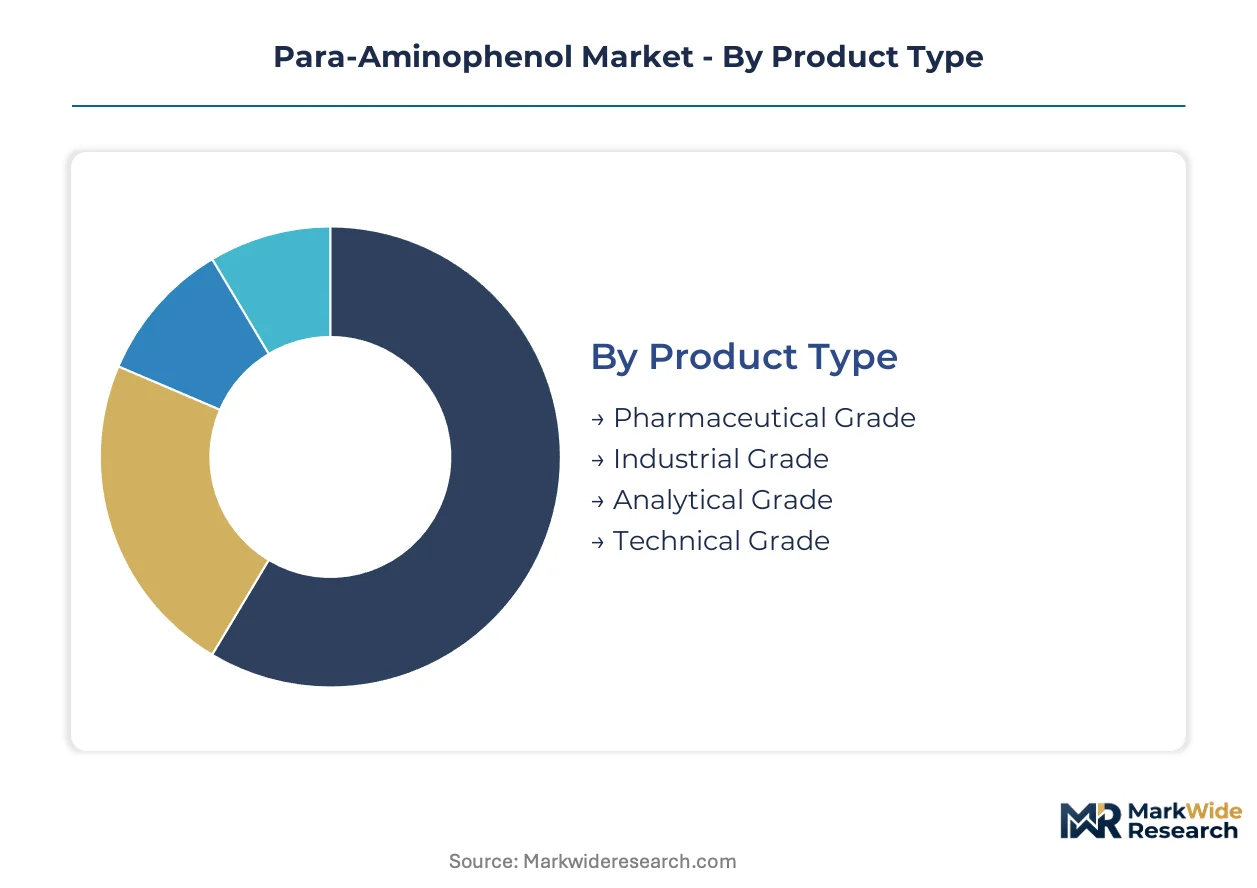
Segmentation in para-aminophenol markets tracks how purity specifications fragment procurement behavior across pharmaceutical, industrial, and research channels. Each tier operates under distinct regulatory burdens and substitution economics that reshape supplier positioning.
Product Type:
Pharmaceutical grade faces acute substitution pressure from membrane-polished alternatives, while technical grade confronts displacement by iron-acid reduction phase-outs.
- Pharmaceutical Grade:USP and EP compliant material with residual solvent limits aligned to ICH Q3C guidelines. CDSCO-registered Indian API manufacturers concentrate procurement here to serve paracetamol export markets under REACH dossier requirements.
- Industrial Grade:Specifications prioritize coupling performance for azo dye chemistry over trace impurity control. Hair colorant formulators in Europe drive volume through cosmetic safety assessments rather than pharmaceutical certification burdens.
- Analytical Grade:Certified reference material with documented traceability for research institutions.
- Technical Grade:Lowest purity tier serving rubber processing and legacy dye applications.
Industrial grade retains volume leadership; pharmaceutical grade holds the steepest expansion curve.
Application:
Cost tier stratification separates margin-rich pharmaceutical synthesis from price-commoditized industrial uses.
- Hair Dye:Azo dye coupling demands batch consistency for cosmetic formulators. European REACH registration creates compliance moats against unregistered Asian suppliers.
- Antipyretics:Paracetamol precursor applications command premium pricing through USP stability testing and extended documentation timelines. Italian and Spanish API producers now contract eighteen to twenty-four month supply agreements to secure input.
- Dye Intermediates:Traditional textile chemistry applications facing environmental enforcement pressure.
- Rubber Processing Chemicals:Industrial antioxidant and accelerator feedstock with thin specification requirements.
Hair dye applications dominate volume throughput; antipyretic synthesis captures the widest margin spreads.
End User:
Customer type determines whether procurement emphasizes certified quality systems or spot-price flexibility.
- Pharmaceutical Manufacturers:Vertically integrated API producers absorb compliance costs across paracetamol production. Multi-site audit demands strain quality assurance staffing at mid-scale suppliers serving this segment.
- Cosmetic Producers:Hair colorant formulators prioritize coupling reliability over pharmaceutical-grade purity. SEQENS and Taixing Yangzi Pharm Chemical anchor supply relationships through dedicated cosmetic chemical networks.
- Chemical Suppliers:Distributors bridging industrial grade specifications to fragmented downstream users.
- Research Laboratories:Direct-to-laboratory channels bypass traditional distribution for analytical grade reference materials.
Pharmaceutical manufacturers anchor value capture; research laboratories expand most quickly through certified traceability premiums.
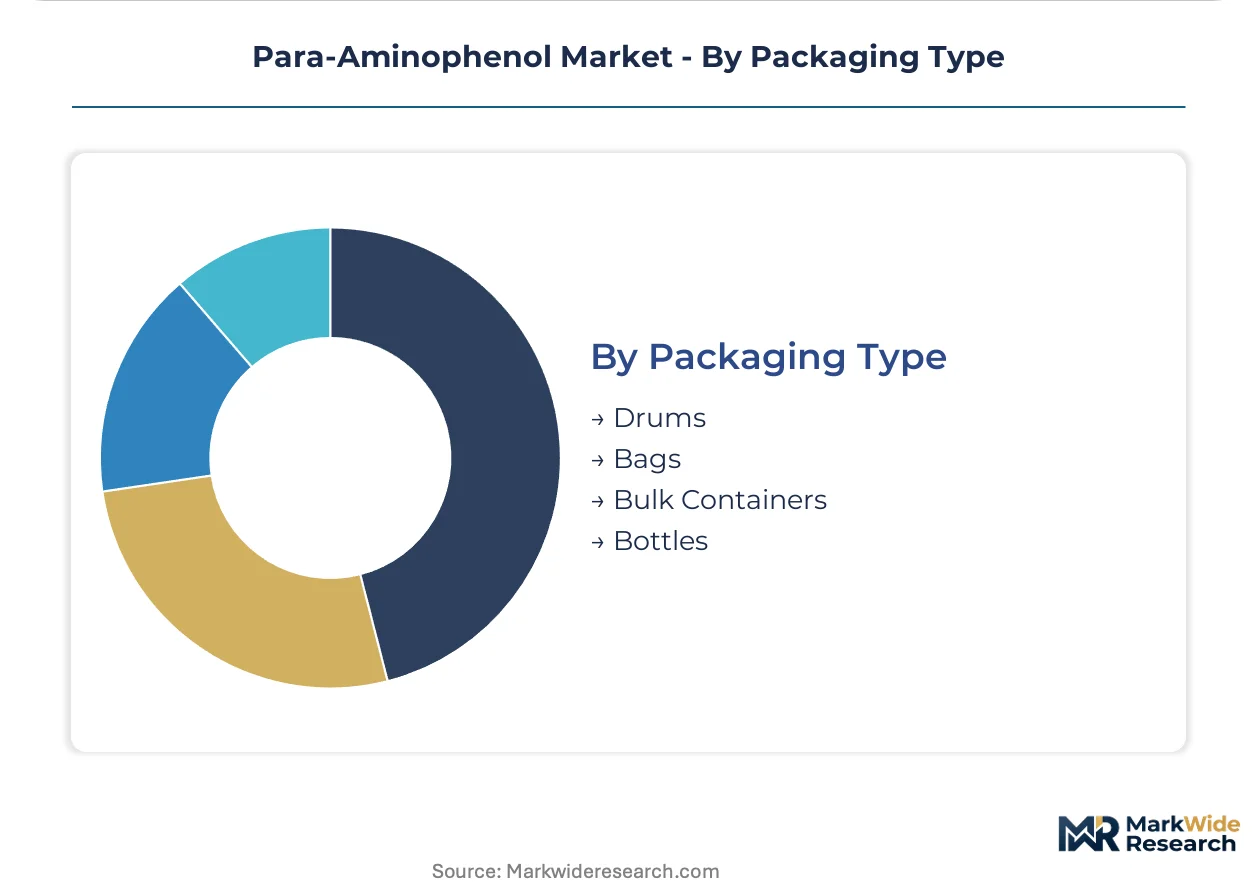
Packaging Type:
Volume scale and handling requirements fragment logistics configurations across container formats.
- Drums:Standard pharmaceutical-grade containment for API manufacturing with UN certification for hazardous material transport. European formulators specify drum formats for ISO 9001-documented supply chains.
- Bulk Containers:Industrial grade shipments to hair dye and rubber chemical producers minimize per-unit handling costs. Yangtze River Delta cluster exports favor bulk formats for ocean freight efficiency.
- Bags:Powder handling for dye intermediate processors.
- Bottles:Laboratory-scale analytical grade distribution.
Bulk containers retain volume leadership; bottles gain share fastest through direct-to-laboratory channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in Italy and Spain anchor European procurement through long-term offtake agreements, while Indian API producers concentrate demand under CDSCO-ICH harmonization. Chinese volume output clusters in the Yangtze River Delta, exposing buyers to single-region environmental enforcement risks.
China
Taixing Yangzi Pharm Chemical drives volume throughput from the Jiangsu province cluster, serving hair dye formulators and pharmaceutical intermediates buyers. MEE wastewater discharge limits are forcing iron-acid reduction phase-outs among smaller producers. The Yangtze River Delta concentration creates weather and logistics vulnerability for global supply chains dependent on bulk container exports.
India
CDSCO-registered API manufacturers concentrate procurement of pharmaceutical-grade material for paracetamol export markets. The PLI scheme for bulk drugs draws capacity investments from specialty chemical suppliers into pharmaceutical-grade manufacturing. Maharashtra and Gujarat host expanding production footprints as domestic formulators reduce import dependency.
Germany
SEQENS anchors European pharmaceutical chemical supply through its multi-site network serving REACH-registered customers. ECHA dossier requirements create compliance moats that filter out unregistered Asian suppliers. The country's formulators pilot membrane-polished material for high-purity paracetamol synthesis, fragmenting traditional crystallization supply relationships.
United States
EPA toxic substance reporting under TSCA Section 8 tightens documentation burdens on imported para-aminophenol. API-grade exporters respond by segregating US-bound production lines with dedicated compliance documentation systems. Wego Chemical Group and domestic distributors bridge pharmaceutical and industrial grade specifications to fragmented downstream users.
Italy
Antipyretic API producers in Lombardy and Emilia-Romagna now secure eighteen to twenty-four month supply agreements with fixed volume tiers. EMA-aligned pharmaceutical manufacturers prioritize supply security over quarterly price optimization amid raw material volatility. Italian formulators represent the vanguard of long-term contracting displacement of spot market purchases.
Para-Aminophenol Market Competitive Landscape
Player mix skews toward specialty chemical suppliers with pharmaceutical certification capabilities and regional distributors serving industrial grade segments. The competitive terrain splits between vertically integrated API precursors and merchant market suppliers dependent on spot price exposure. Three archetypes dominate: backward-integrated Indian manufacturers, European pharmaceutical chemical networks, and Chinese volume exporters. Capacity expansion and regulatory compliance investments constitute the dominant competitive moves as iron-acid reduction phase-outs force capital-intensive upgrades.
Within the Indian specialty chemical tier, Valiant Organics and Sadhana Nitro Chem exemplify producers leveraging domestic API demand expansion under PLI incentives. Taixing Yangzi Pharm Chemical anchors Chinese volume positioning from the Yangtze River Delta cluster. SEQENS occupies the European pharmaceutical chemical network archetype, serving REACH-registered customers through multi-site quality systems. Glentham Life Sciences and Central Drug House represent laboratory and distribution-focused models bridging analytical grade requirements to research institutions.
| Leading Market Players |
|---|
| Glentham Life Sciences |
| Wego Chemical Group |
| Central Drug House |
| Taixing Yangzi Pharm Chemical |
| Haihang Industry |
| Hefei TNJ Chemical Industry |
| Valiant Organics |
| SEQENS |
| Sadhana Nitro Chem |
| Others |
Pricing and Supply Chain Analysis
Membrane-polished pharmaceutical grade material is displacing traditional crystallization routes, simultaneously shifting production gravity toward German and Swiss formulators while compressing margin premiums for established Indian and Chinese suppliers dependent on legacy purification economics.
Pricing Analysis
Long-term offtake contracts with nitrobenzene indexation anchor pricing for European pharmaceutical buyers, replacing quarterly spot bidding. Three-tier pricing structure across pharmaceutical, industrial, and technical grade levels separates USP-certified material from hair dye coupling specifications. Cost compression in industrial grade is intensifying because iron-acid reduction phase-outs force capital upgrades among smaller Chinese and Indian producers. Hair dye formulators exhibit highest price sensitivity, while paracetamol API manufacturers absorb premium pricing for supply security.
Supply Chain Analysis
Strategic stockpiling dominates European pharmaceutical procurement, contrasting with just-in-time bulk container flows from the Yangtze River Delta. Supply concentrates in China, India, and Germany, with nitrobenzene, catalytic hydrogenation equipment, and membrane separation systems as critical inputs. Single-region environmental enforcement in Jiangsu province poses structural vulnerability for global buyers. Distribution runs through vertically integrated API manufacturers for pharmaceutical grade and chemical distributors for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous-flow catalytic hydrogenation is disrupting batch manufacturing economics, with CDSCO-ICH harmonization creating regulatory acceleration for multi-jurisdiction API suppliers.
For Market Incumbents: Shield market position by deepening backward integration into nitrobenzene feedstock and accelerating REACH dossier completion ahead of ECHA deadline clustering. Membrane-polished alternatives threaten crystallization-dependent producers. Certification investment in dual USP-EP systems anchors pricing power against unregistered Asian competition. For New Entrants and Emerging Players: Analytical grade reference material distribution represents an under-served service layer where incumbents rely on traditional chemical distributors. Target research laboratories in Germany and Switzerland with certified traceability documentation. Direct-to-laboratory channels bypass established distribution markups and command premium positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian specialty chemical platforms holding PLI scheme allocations but lacking REACH registration capabilities. Five-to-ten year viability hinges on regulatory harmonization execution. Watch for CDSCO-EU mutual recognition agreement progress as inflection signal for portfolio rebalancing toward dossier-complete producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrobenzene | Valiant Organics controls input costs across Maharashtra and Gujarat manufacturing sites. |
| REACH Dossier Completion | SEQENS secures preferential supply relationships to EMA-aligned Italian formulators. |
| Membrane Separation Technology Adoption | German pilot programs fragment traditional crystallization supply relationships. |
| Long-term Supply Agreement Structuring | Italian API producers secure eighteen-to-twenty-four month fixed volume tiers. |
| CDSCO-ICH Harmonization Investment | Indian manufacturers streamline simultaneous EU and US market access pathways. |
Research Methodology
Cross-validation between primary interviews with plant managers at catalytic hydrogenation facilities and secondary analysis of CDSCO registration databases anchors the qualitative findings. Procurement leads at downstream paracetamol API manufacturers, distribution channel partners serving hair dye formulators, and technical R&D directors at membrane separation equipment suppliers contributed field perspectives. Trade data from Indian DGFT export filings, ECHA registration dossiers, SEC 10-K disclosures from listed chemical producers, and customs records from Yangtze River Delta port authorities provided secondary validation. Bottom-up capacity assessments and top-down demand modeling from pharmaceutical formulation forecasts were reconciled.
Sensitivity analysis around nitrobenzene price volatility and REACH registration timeline slippage informs the projection framework. Segmentation dimensions span pharmaceutical-industrial-analytical grade tiers, paracetamol precursor versus azo dye coupling end-uses, drum versus bulk container packaging formats, and regional production hub concentration. CAGRs derive from installed capacity expansion schedules cross-referenced against formulation demand trajectories. Catalytic hydrogenation yield improvements and iron-acid reduction phase-out enforcement intensity serve as key forecast inputs.
Underlying assumptions cover sustained PLI scheme disbursement continuity and ECHA dossier acceptance rates, with deviation risk concentrated in Yangtze River Delta environmental enforcement intensity and nitrobenzene feedstock price spikes. Revision becomes warranted when membrane-polished material qualification timelines at EMA-aligned formulators accelerate beyond baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Potassium Methylate Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Phthalimide Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Paraben Market
Functional Chemicals
Glutaraldehyde Market
Functional Chemicals
Global Potassium Citrate Market
Functional Chemicals
Fumaric Acid Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Adipamide Market
Functional Chemicals
Jellyfish-Derived Peptide Ingredient Concepts Market
Functional Chemicals
Europe Formic Acid Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
Sodium Malate Market