
 Serine Market | 2026-2036
Serine Market Size, Share, and Industry Trends Forecast 2026-2036
Serine Market Analytics
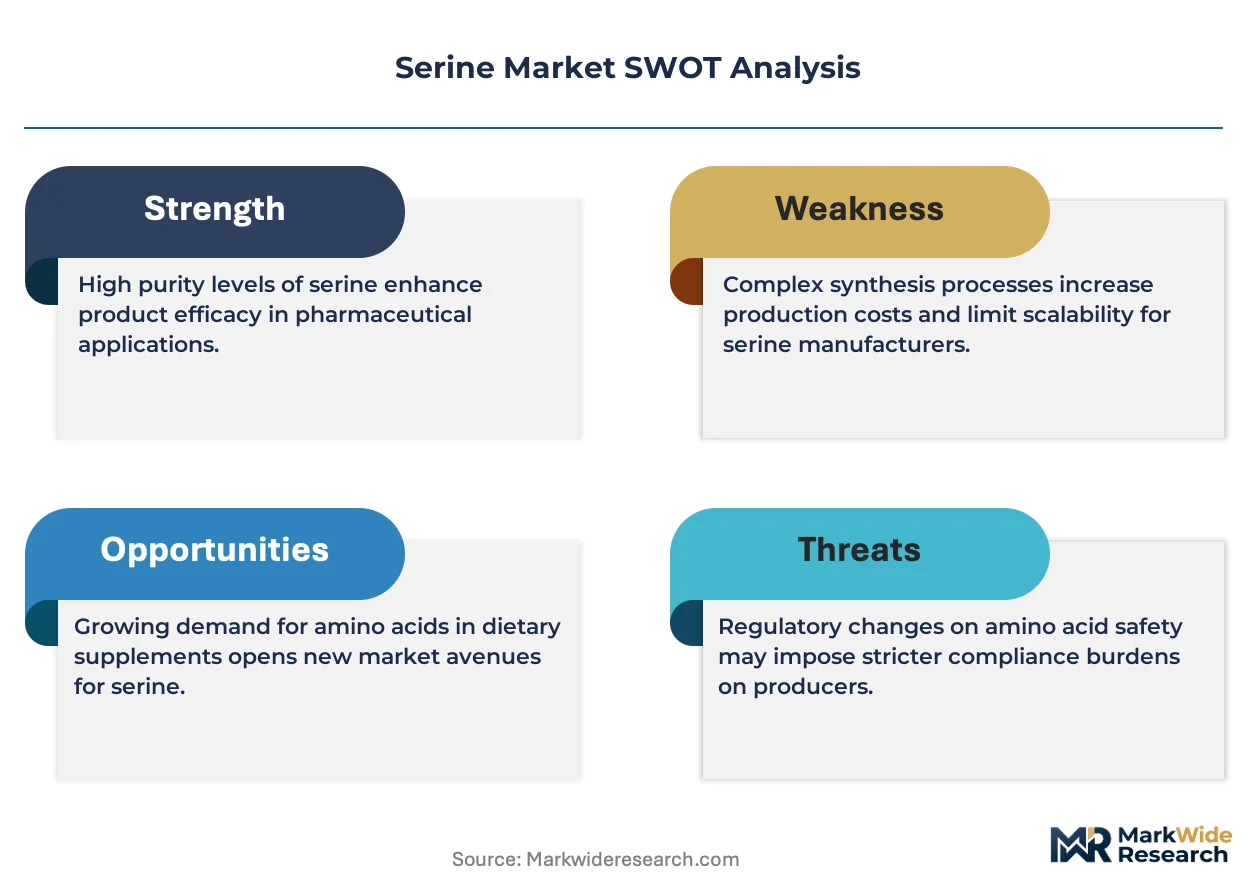
The serine market is rebalancing as pharmaceutical-grade specifications diverge sharply from commodity feed-grade pricing and purity benchmarks. Ajinomoto leverages its fermentation expertise to dominate high-purity L-serine for cell culture media. Evonik anchors European supply through specialty amino acid derivatives for injectable formulations. Mitsui Chemicals competes on synthetic process efficiency, serving industrial and cosmetic applications with cost-optimized output.
Serine, a non-essential proteinogenic amino acid with the molecular formula C3H7NO3, functions as a precursor for phospholipids, glycine, and tryptophan synthesis across metabolic pathways. Industrial production employs either microbial fermentation or chemical synthesis from glycine formaldehyde, with fermentation yielding chirally pure L-serine essential for pharmaceutical applications. The L-Serine product category captures the dominant revenue share due to its indispensability in biopharmaceutical cell culture systems and parenteral nutrition solutions. Pharmaceuticals application demand outpaces other segments, driven by monoclonal antibody production expansion and personalized medicine growth, while Cosmetics represents an emerging margin pool as peptide-based skincare formulations proliferate.
Regulatory frameworks including FDA Current Good Manufacturing Practice, EMA guidelines on amino acid excipients, and China's NMPA drug master file requirements collectively elevate barrier thresholds for new serine suppliers entering pharmaceutical channels. REACH registration in Europe and evolving EPA environmental assessments for fermentation effluents further constrain capacity expansion timelines. Stakeholders must monitor fermentation yield improvements and glycine feedstock price volatility as determinants of competitive positioning in contract manufacturing negotiations.
Market Dynamics
Fermentation yield improvements and glycine feedstock volatility are compressing margins for chemical synthesis routes while elevating biopharmaceutical-grade specifications as the decisive competitive filter.
Growth Catalysts
- Biologics manufacturing expansion:Monoclonal antibody production facilities in China and India are scaling L-serine procurement for cell culture media formulations.
- REACH registration requirements:ECHA mandates for amino acid derivatives are consolidating European supply toward cGMP-certified producers capable of pharmaceutical-grade documentation.
- Peptide-based skincare proliferation:Cosmetic formulators in South Korea and Japan are incorporating serine-derived phospholipids into barrier-repair formulations.
Market Restraints
- Glycine formaldehyde feedstock volatility:Petrochemical-derived glycine prices fluctuate with methanol and ammonia input costs, squeezing synthetic route economics.
- Fermentation capacity concentration:High-purity L-serine production clusters among established amino acid specialists with decades of strain optimization IP.
- Substitution by synthetic alternatives:Certain industrial applications are migrating toward cheaper non-chiral serine analogs where enantiomeric purity is non-critical.
Strategic Opportunities
- Indian pharmaceutical excipient market:CDSCO's tightening import substitution policies create openings for domestic fermentation-based L-serine producers.
- Continuous processing technology:Integration of perfusion bioreactors with in-line purification is expanding into contract manufacturing negotiations for parenteral-grade material.
- Japan's regenerative medicine push:METI funding for cell therapy manufacturing infrastructure is generating demand for serum-free media components including pharmaceutical-grade serine.
Industry Challenges
- Strain engineering talent scarcity:Microbial metabolic pathway optimization requires rare combinations of synthetic biology and industrial fermentation expertise.
- cGMP certification timelines:FDA and EMA facility inspections for amino acid excipient production extend qualification periods by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serine Market |
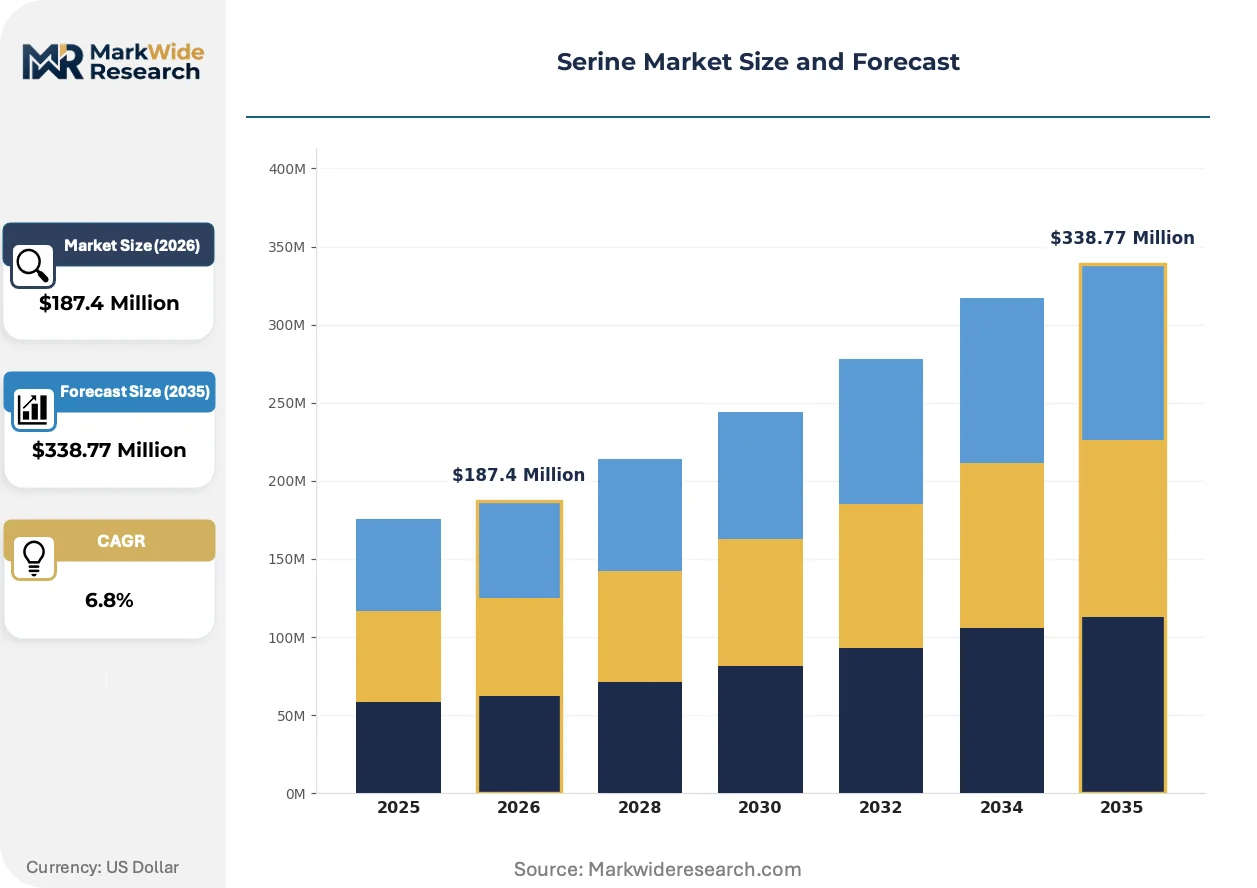
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Serine, D-Serine, Glycine, Others Application: Pharmaceuticals, Food & Beverages, Nutraceuticals, Cosmetics End User: Healthcare Providers, Food Manufacturers, Cosmetic Companies, Research Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Mitsui Chemicals, Apeloa, Ajinomoto, Jiahe Biotech, Bafeng Pharmaceutical, Evonik, Wuxi Jinghai Amino Acid, Merck KGaA, KYOWA HAKKO BIO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serine Market Evolving Landscape
Process intensification and regulatory digitization are compressing development cycles while fragmenting buyer procurement patterns across spot and contract mechanisms.
Continuous fermentation with cell retention technology is expanding into pharmaceutical-grade L-serine manufacturing. Biologics contract manufacturers in Germany and Switzerland are adopting perfusion systems to reduce batch-to-batch variability. This technology is expanding into long-term supply agreements where real-time release testing replaces end-point QC.
EMA's revised guidelines on elemental impurities in amino acid excipients are forcing upstream purification investments. Manufacturers must now document ICP-MS testing for catalyst residues across all production batches. European parenteral nutrition suppliers are responding by dual-sourcing from REACH-registered producers with validated impurity profiles.
Direct procurement from fermentation specialists is displacing traditional distributor channels for large-volume buyers. Biopharmaceutical CDMOs in Massachusetts and North Carolina are negotiating multi-year offtake agreements bypassing regional chemical distributors. This pattern concentrates most visibly among monoclonal antibody producers with captive media formulation capabilities.
Serine Market Segmentation
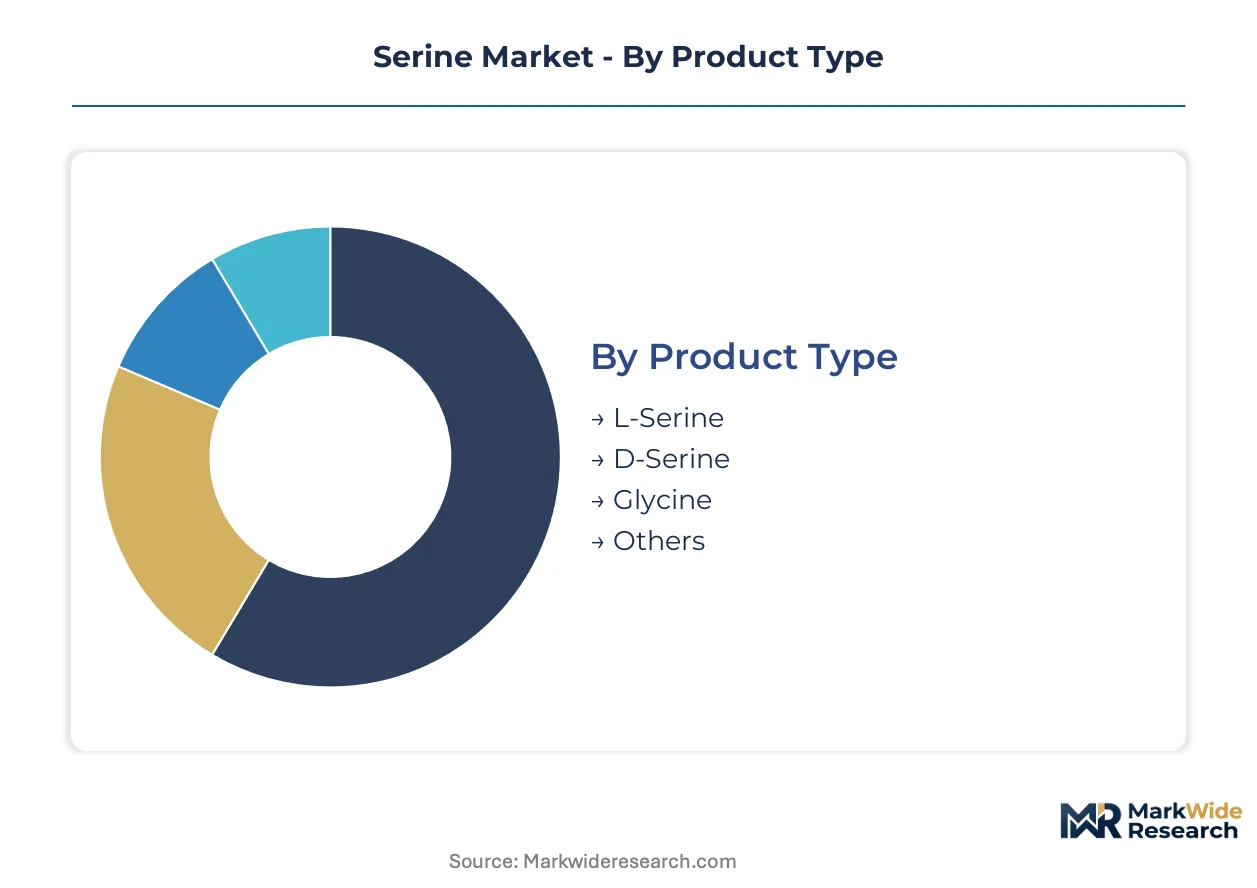
Serine market segmentation reveals how purity specifications and regulatory pathways fragment procurement strategies. Pharmaceutical-grade L-serine commands fundamentally different supply chains than commodity grades, creating distinct competitive arenas across each dimension.
Product Type:
Capital intensity escalates sharply with enantiomeric purity requirements, separating fermentation-based L-serine from synthetic alternatives.
- L-Serine:Chirally pure L-enantiomer produced through microbial fermentation with Corynebacterium glutamicum strains. Monoclonal antibody manufacturers in Massachusetts and North Carolina concentrate procurement for serum-free cell culture media, with FDA cGMP documentation mandatory for excipient qualification.
- D-Serine:Mirror-image enantiomer synthesized through chemical resolution or stereoselective catalysis. NMDA receptor research at German and Swiss neuropharmacology institutes drives modest demand, constrained by limited therapeutic approval pathways.
- Glycine:Simplest proteinogenic amino acid serving as serine precursor and independent commodity. Industrial applications in China and India absorb volume for metal chelation and buffering formulations.
- Others:DL-racemic mixtures and specialty derivatives including phosphatidylserine and acetylserine. Cosmetic peptide suppliers in South Korea utilize these for barrier-function skincare actives.
Most installed capacity flows through L-Serine. Expansion is steepest in pharmaceutical-grade fermentation systems.
Application:
Margin structure diverges across applications, with parenteral nutrition and biologics sustaining premium pricing against commoditized food-grade volumes.
- Pharmaceuticals:Cell culture media, parenteral nutrition solutions, and active pharmaceutical ingredient synthesis. EMA's revised elemental impurity guidelines and FDA drug master file requirements enforce multi-tier documentation burdens.
- Food & Beverages:Flavor enhancement and nutritional fortification in sports drinks and infant formula. FSSAI and China's SAMR maintain divergent purity specifications, fragmenting supplier qualification.
- Nutraceuticals:Cognitive health supplements leveraging phosphatidylserine complexes. Japanese and South Korean regulatory frameworks for functional foods create distinct go-to-market pathways.
- Cosmetics:Peptide-based skincare and barrier-repair formulations. METI-funded regenerative medicine initiatives in Japan are spilling over into cosmetic peptide demand.
Pharmaceuticals commands the highest purity premiums. Cosmetics is climbing the fastest as peptide formulation science advances.
End User:
Procurement sophistication varies dramatically, from institutional tender processes to spot-market commodity purchasing.
- Healthcare Providers:Hospital systems and specialty clinics sourcing parenteral nutrition compounds. US 503B compounding pharmacies and European hospital pharmacies enforce distinct vendor qualification.
- Food Manufacturers:Industrial-scale amino acid buyers optimizing for cost-per-kilogram. China's amino acid production clusters serve both domestic processors and export markets.
- Cosmetic Companies:Formulation houses in Seoul and Tokyo seeking peptide-grade serine derivatives. Clean beauty certification requirements are adding documentation layers.
- Research Institutions:Academic and contract research organizations with fragmented, small-volume purchasing. Direct procurement from fermentation specialists is displacing traditional distributor relationships.
Healthcare Providers anchor volume through long-term supply agreements. Research Institutions are gaining share fastest as cell therapy manufacturing scales.
Distribution Channel:
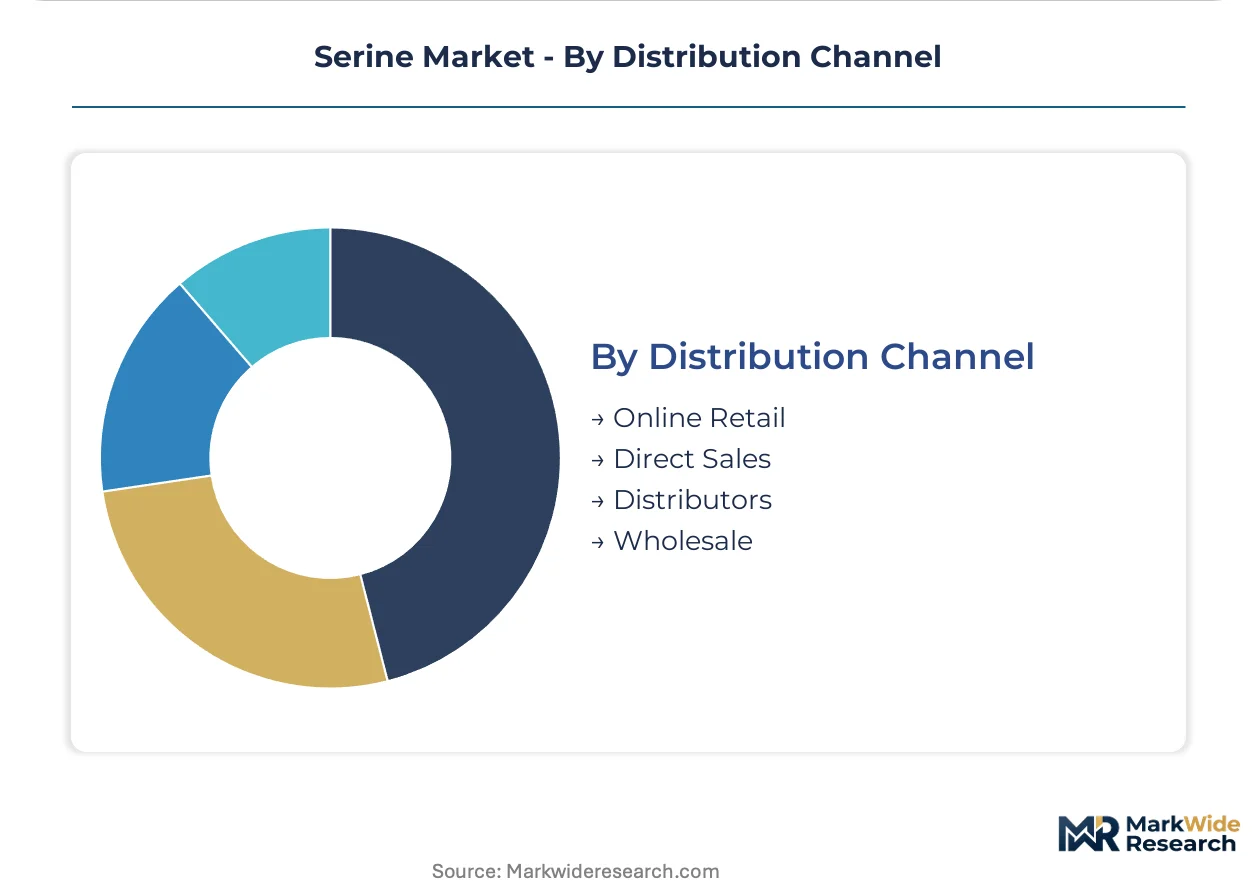
Channel economics reflect lot-size thresholds and documentation requirements, with direct sales capturing pharmaceutical-grade flows.
- Online Retail:E-commerce platforms serving nutraceutical and cosmetic ingredient buyers. Alibaba and specialty chemical marketplaces aggregate fragmented small-lot demand.
- Direct Sales:Manufacturer-to-end-user contracts for pharmaceutical and large-volume food accounts. CDMOs in Germany and Switzerland negotiate multi-year offtake agreements with bypassed intermediaries.
- Distributors:Regional chemical distributors holding inventory for qualified pharmaceutical and food-grade material. REACH registration and FDA establishment identification requirements consolidate viable supplier bases.
- Wholesale:Commodity-grade glycine and racemic serine through bulk chemical traders. Price volatility in methanol and ammonia feedstocks compresses margins.
Direct Sales commands the most pharmaceutical-grade volume. Online Retail is expanding most quickly for nutraceutical and cosmetic ingredients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands fermentation capacity for pharmaceutical-grade serine, while India scales import-substitution fermentation infrastructure. Germany anchors European regulatory compliance and specialty derivatives production.
China
Monoclonal antibody manufacturing expansion in Suzhou and Shanghai drives L-serine procurement for serum-free cell culture media. NMPA drug master file requirements enforce documentation standards that filter supplier qualification. Zhejiang and Jiangsu provinces concentrate amino acid fermentation clusters where producers scale capacity for export markets.
India
CDSCO tightening of import substitution policies creates openings for domestic pharmaceutical-grade serine fermentation. Parenteral nutrition compounders in Hyderabad and Ahmedabad enforce vendor qualification distinct from US 503B compounding pharmacy standards. Maharashtra and Gujarat host emerging fermentation infrastructure targeting biopharmaceutical excipient supply.
Germany
EMA revised guidelines on elemental impurities in amino acid excipients force upstream purification investments by parenteral nutrition suppliers. REACH registration mandates consolidate viable supplier bases toward cGMP-certified producers. Bavaria and North Rhine-Westphalia anchor biologics contract manufacturing where perfusion bioreactor adoption reduces batch-to-batch variability.
United States
FDA Current Good Manufacturing Practice enforcement extends qualification periods for amino acid excipient production facilities. Biopharmaceutical CDMOs in Massachusetts and North Carolina negotiate multi-year offtake agreements bypassing regional chemical distributors. Greater Boston and Research Triangle Park concentrate monoclonal antibody producers with captive media formulation capabilities.
Japan
METI funding for cell therapy manufacturing infrastructure generates demand for serum-free media components including pharmaceutical-grade serine. PMDA guidelines on regenerative medicine materials enforce documentation burdens distinct from pharmaceutical excipient pathways. Kansai region peptide formulators incorporate serine-derived phospholipids into barrier-repair cosmetic actives.
Serine Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade fermentation, while commodity chemical synthesis competes on cost-optimized output. Ajinomoto leverages decades of strain optimization intellectual property in high-purity L-serine. Evonik anchors European supply through specialty amino acid derivatives. Mitsui Chemicals competes on synthetic process efficiency. Dominant competitive moves include capacity expansion in India and China and strategic partnerships for continuous processing technology licensing.
Within the fermentation-specialist tier, Ajinomoto, Evonik, and KYOWA HAKKO BIO represent archetypes of strain-engineering capability concentration. Ajinomoto exemplifies integrated amino acid fermentation expertise extending into pharmaceutical-grade documentation. Evonik occupies a position bridging European regulatory compliance and specialty derivatives production. KYOWA HAKKO BIO anchors Japanese biotechnology fermentation heritage. Mitsui Chemicals and Merck KGaA sit within chemical synthesis and life science materials archetypes respectively, while Apeloa, Jiahe Biotech, Bafeng Pharmaceutical, and Wuxi Jinghai Amino Acid represent Chinese fermentation capacity scaling.
| Leading Market Players |
|---|
| Mitsui Chemicals |
| Apeloa |
| Ajinomoto |
| Jiahe Biotech |
| Bafeng Pharmaceutical |
| Evonik |
| Wuxi Jinghai Amino Acid |
| Merck KGaA |
| KYOWA HAKKO BIO |
| Others |
Value Network & Pricing Analysis
Biopharmaceutical CDMO procurement consolidation toward direct manufacturer contracts is forcing fermentation specialists to absorb documentation costs while defending margin structures across pharmaceutical-grade tiers.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for commodity-grade serine while pharmaceutical-grade premiums widen. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates FDA-cGMP documented material from REACH-registered and uncertified tiers. Cost compression in synthetic routes is intensifying because glycine formaldehyde feedstock volatility squeezes chemical synthesis economics. Food manufacturers show highest price sensitivity, while monoclonal antibody producers prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for pharmaceutical-grade material. Manufacturing concentrates in China, India, and Germany, with Zhejiang fermentation clusters and Bavarian contract manufacturing sites serving distinct documentation requirements. Supply draws from glycine formaldehyde, Corynebacterium glutamicum strain banks, and purification resin inputs. Single-source vulnerability concentrates in high-purity L-serine where decades of strain optimization IP create replacement barriers. Distribution runs through direct sales for pharmaceutical accounts and Alibaba aggregators for cosmetic ingredient buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The serine market functions as a stable compounder anchored by biologics manufacturing expansion and irreplaceable cell culture media demand.
For Market Incumbents: Lock in long-term offtake agreements with Massachusetts and North Carolina monoclonal antibody producers before CDSCO import substitution policies mature Indian domestic supply. Deepen backward integration into glycine feedstock through captive production or strategic partnerships to neutralize petrochemical price volatility. Prioritize continuous fermentation technology licensing to capture perfusion bioreactor adoption among German and Swiss contract manufacturers. For New Entrants and Emerging Players: E-commerce platforms serving South Korean cosmetic peptide formulators offer the most penetrable entry vector with lower certification barriers than pharmaceutical channels. Target India's parenteral nutrition compounders in Hyderabad and Ahmedabad with CDSCO-compliant documentation as domestic substitution policies tighten. Pursue white-label manufacturing arrangements with established amino acid distributors to bypass strain engineering talent scarcity. For Investors and Strategic Acquirers: Asymmetric upside sits with Indian fermentation specialists building cGMP capacity ahead of CDSCO enforcement timelines. The five-to-ten year viability window favors producers with validated drug master files and REACH registrations already in place. Watch for METI funding disbursement velocity in Japan's cell therapy infrastructure as an inflection signal for serum-free media component demand.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Technology Licensing | Perfusion bioreactor adoption by German CDMOs reduces batch-to-batch variability for parenteral-grade supply. |
| Backward Integration into Glycine Feedstock | Captive glycine production insulates synthetic route economics from methanol and ammonia price volatility. |
| CDSCO cGMP Certification Investment | Domestic Indian qualification captures import substitution demand from Hyderabad parenteral nutrition compounders. |
| Direct Sales Channel Expansion | Manufacturer-to-CDMO contracts in Massachusetts bypass distributor markups and strengthen volume commitments. |
| Strain Engineering Talent Acquisition | Synthetic biology expertise concentration addresses the bottleneck in Corynebacterium glutamicum pathway optimization. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement spanned fermentation plant managers, biopharmaceutical procurement leads at CDMOs, amino acid distribution channel partners, and regulatory affairs directors navigating FDA and EMA excipient pathways. Secondary validation drew from NMPA drug master file databases, ECHA REACH registration records, CDSCO import policy circulars, and SEC filings of publicly traded amino acid producers. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Historical reference periods established baseline fermentation yield trends and glycine feedstock price corridors that informed projection parameters across the analysis window. Segmentation modeling captured grade tier, end-use application, regional production hub, and distribution channel dimensions. CAGRs emerged from curve-fitting across documented capacity expansions and biologics manufacturing buildouts. Strain engineering productivity gains and regulatory approval timelines for new fermentation facilities served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for continuous fermentation with cell retention would alter the outlook if perfusion bioreactor adoption accelerates beyond contract manufacturing negotiations. Forecasts reflect assumptions around CDSCO enforcement timing, METI funding disbursement, and EMA elemental impurity guideline implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Global Potassium Citrate Market
Functional Chemicals
Threonine Acids Market
Functional Chemicals
Para-Aminophenol Market
Functional Chemicals
Phthalimide Market
Functional Chemicals
Thiamine Market
Functional Chemicals
Sodium Methylate Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Global Sodium Lignosulfonate Market
Functional Chemicals
Lauric Acid Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Furan Dicarboxylic Methyl Ester (FDME) Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Tartrazine Market