
 Global Adiponitrile Market | 2026-2036
Global Adiponitrile Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adiponitrile Market Foresight
Project finance tied to integrated petrochemical complexes is tilting competitive access toward capital-heavy conglomerates. INVISTA leverages its Gulf Coast hexamethylenediamine backward link to sustain margin capture across the nylon chain. Ascend Performance Materials anchors North American supply through its Chocolate Bayou facility. Butachimie competes from the European platform with a specialized butadiene-based route.
Adiponitrile is a dinitrile compound with the formula NC(CH2)4CN, produced industrially via hydrocyanation of butadiene or electrodimerization of acrylonitrile, serving as the essential precursor to hexamethylenediamine for nylon 6,6 polymerization. Liquid grade dominates volume flows into continuous nylon polymerization trains where thermal stability and low moisture content govern reactor throughput. Nylon 6,6 production absorbs the majority of merchant supply while polyamide fibers for industrial textiles represents the fastest-growing application segment as tire cord and airbag specifications tighten. High purity grades command premium positioning in electronic-grade polyamide films where ionic contamination thresholds sit below ten parts per billion.
EPA hazardous air pollutant standards under the Clean Air Act shape US plant emissions profiles and capital allocation toward scrubber and abatement retrofits. REACH registration requirements in Europe constrain non-European producers seeking direct material import, while China's MEE enforces dual carbon emissions intensity caps that favor newer butadiene-route assets over legacy acrylonitrile dimerization. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where capacity additions face permitting friction versus accelerated approval.
Market Dynamics
Integrated petrochemical conglomerates are consolidating backward into captive adiponitrile production, locking merchant supply access and compressing margin capture for standalone polymerizers who lack hydrocyanation assets.
Growth Catalysts
- EPA emissions tightening:Under-hood nylon 6,6 specifications for lightweight intake manifolds are hardening material requirements, pulling adiponitrile into automotive supply chains.
- China dual carbon enforcement:MEE emissions intensity caps are favoring newer butadiene-route capacity expansions over legacy acrylonitrile dimerization circuits.
- Industrial textile specifications:Tire cord and airbag fiber standards are intensifying polyamide purity requirements, channeling demand toward electronic-grade adiponitrile streams.
Market Restraints
- Butadiene feedstock volatility:Crude-linked naphtha cracking economics transmit price swings directly into butadiene-based adiponitrile cost structures.
- Supply concentration in China:Sinopec and domestic compounders are internalizing merchant volumes, thinning spot market liquidity for external buyers.
- REACH registration barriers:Non-European producers face direct import constraints into the European Economic Area without full substance dossier compliance.
Strategic Opportunities
- India polyamide compounding:PLI scheme incentives for synthetic fiber manufacturing are creating first-mover openings for adiponitrile-to-polymer integration.
- Electronic-grade films:Semiconductor packaging and flexible circuit substrates are absorbing ionic-contamination-sensitive polyamide grades at premium positioning.
- Green hydrogen-cyanide pathways:Renewable ammonia cracking is converging with bio-based acrylonitrile routes to enable carbon-intensity-labeled adiponitrile production.
Industry Challenges
- Process safety expertise scarcity:Hydrogen cyanide handling and hydrocyanation reactor operations require specialized chemical engineering talent pools that are thinning across the industry.
- Abatement capex cycles:EPA Clean Air Act scrubber retrofits and MEE dual carbon compliance installations are demanding capital allocation that competes with capacity expansion budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adiponitrile Market |
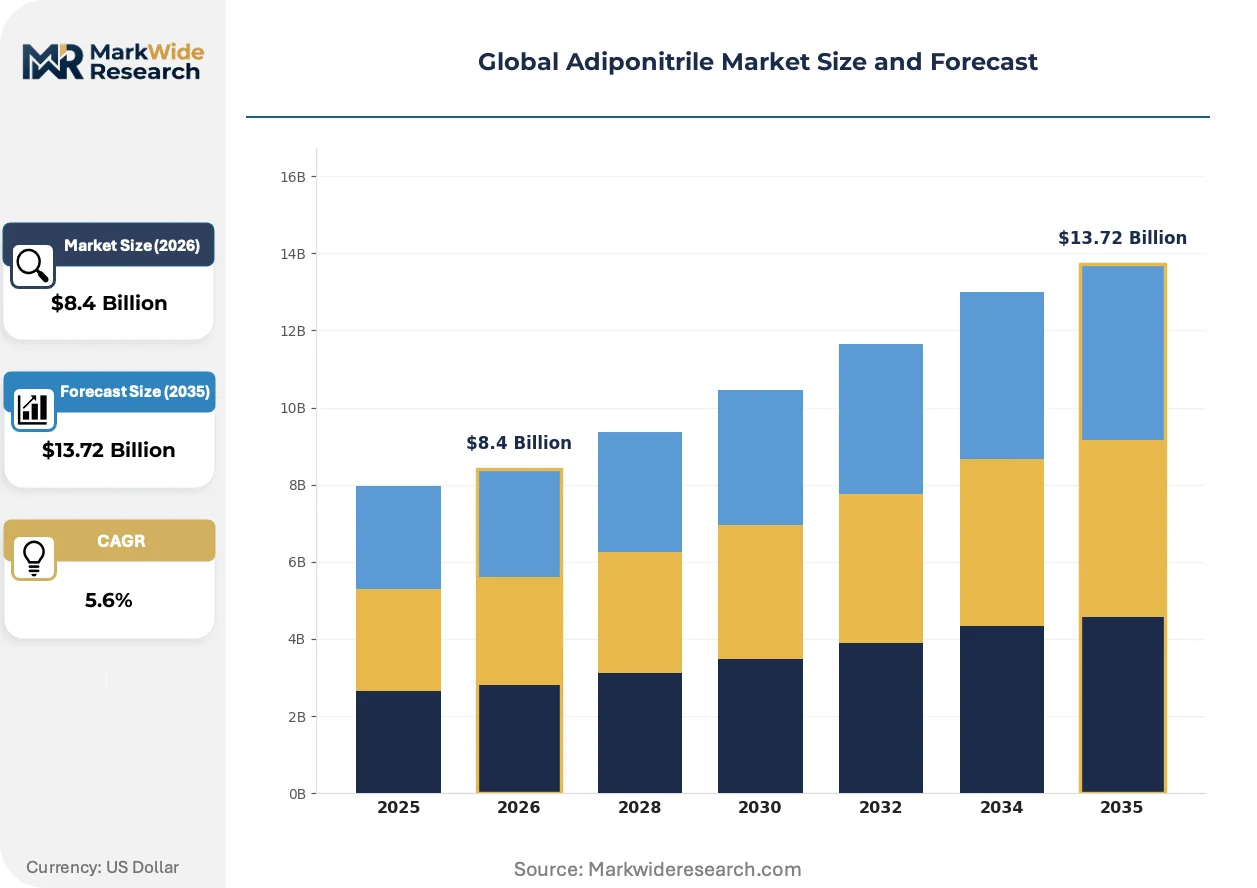
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.72 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Grade, Solid Grade, High Purity, Industrial Grade Application: Nylon 6,6 Production, Polyamide Fibers, Coatings, Adhesives, Plasticizers End Use Industry: Textile Manufacturing, Automotive Suppliers, Packaging Manufacturers, Electrical Components, Consumer Goods Distribution Channel: Direct Sales, Distributors, Online Platforms, Wholesale Markets |
| Companies Covered | Asahi Kasei Corp, Toray Industries, INVISTA, Sinopec, Lanxess, Ascend Performance Materials, Mitsubishi Chemical, Butachimie, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adiponitrile Market Shifts & Advancements
Process intensification and regulatory chemistry are compressing legacy production economics while opening differentiation pathways through purity grades and carbon accounting.
Membrane-based acrylonitrile electrodimerization is collapsing the energy intensity gap between traditional routes and butadiene hydrocyanation. Automotive polymerizers in Germany and Japan are piloting these units for on-site hexamethylenediamine integration. The technology is collapsing the historical scale minimums that favored 300-kiloton world-scale plants, enabling 50-kiloton regional units.
REACH authorization list expansion is tightening diisocyanate and cyanide derivative handling protocols across the European Economic Area. Downstream polyamide compounders are restructuring supply agreements to transfer regulatory compliance liability upstream. Electronic-grade film manufacturers are demanding batch-level substance origin documentation to preempt SVHC screening failures.
Compounders are consolidating procurement around certified low-carbon-intensity adiponitrile tiers with embedded emissions accounting. Tier-1 automotive suppliers in Michigan and Stuttgart are inserting carbon footprint clauses into nylon 6,6 offtake contracts. The shift is most visible in electric vehicle under-hood component sourcing, where OEM sustainability scorecards are overriding pure price competition.
Global Adiponitrile Market Segmentation
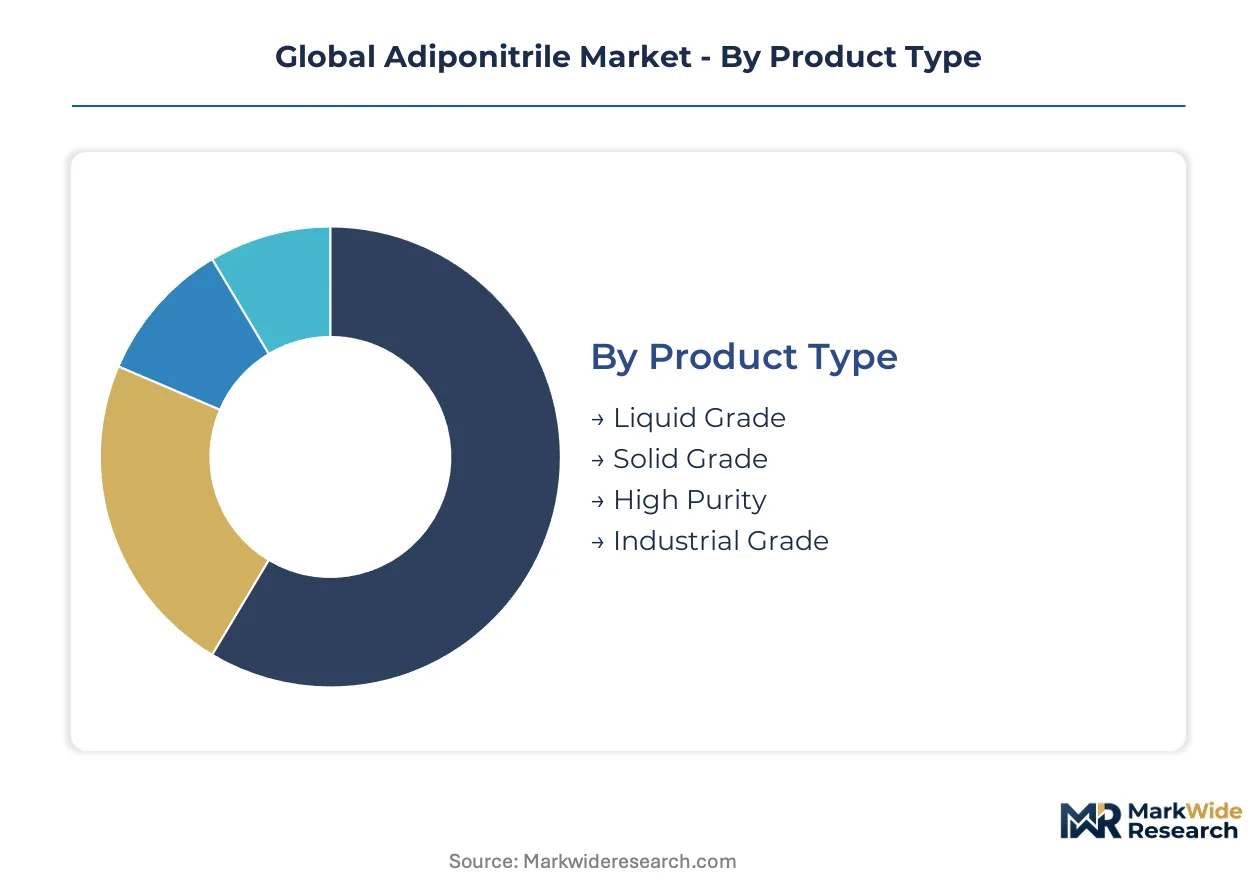
Adiponitrile segmentation tracks how purity grades, application chemistry, and procurement channels partition margin capture across the nylon value chain. Technical specifications govern reactor compatibility while regulatory compliance shapes channel access in key consuming regions.
Product Type:
Cost tiers separate commodity-grade flows from contamination-sensitive electronic applications where ionic thresholds sit below ten parts per billion.
- Liquid Grade:Continuous polymerization trains favor this specification for thermal stability and low moisture content that maximizes reactor throughput. Automotive suppliers in Michigan and Stuttgart specify liquid grade for under-hood nylon 6,6 intake manifolds where EPA emissions rules harden material requirements.
- High Purity:Semiconductor packaging and flexible circuit substrates demand batch-level ionic contamination controls. Electronic-grade film manufacturers in Japan and Germany are consolidating procurement around certified low-carbon-intensity high purity tiers with embedded emissions accounting.
- Solid Grade:Regional compounders in India use solid grade for batch polymerization where logistics favor stable storage and handling.
- Industrial Grade:Coatings and adhesives formulators absorb this tier where purity thresholds relax and price sensitivity dominates.
Liquid grade commands the established base. The steepest expansion runs through high purity.
Application:
Application chemistry determines whether adiponitrile flows into polymerization reactors or specialty formulation tanks.
- Nylon 6,6 Production:Hexamethylenediamine precursor demand absorbs the majority of merchant supply through continuous polymerization circuits. INVISTA's Gulf Coast hexamethylenediamine backward link and Ascend's Chocolate Bayou facility anchor this segment.
- Polyamide Fibers:Tire cord and airbag specifications are intensifying purity requirements, channeling demand toward electronic-grade streams. Industrial textile standards in Germany and Japan are climbing fastest.
- Coatings:Solvent-resistant barrier films use adiponitrile-derived polyamides where chemical exposure resistance matters.
- Adhesives:High-temperature bonding applications in automotive assembly absorb formulated grades.
- Plasticizers:Flexible polymer modification for packaging films represents a smaller volume outlet.
Nylon 6,6 production commands the established base. Polyamide fibers are climbing the fastest.
End Use Industry:
Customer type segmentation reveals where specification power concentrates versus where price competition dominates.
- Automotive Suppliers:Tier-1 manufacturers in Michigan and Stuttgart are inserting carbon footprint clauses into nylon 6,6 offtake contracts. Electric vehicle under-hood component sourcing now overrides pure price competition through OEM sustainability scorecards.
- Textile Manufacturing:Tire cord and airbag fiber producers in China and India are scaling captive adiponitrile-to-polymer circuits. PLI scheme incentives for synthetic fiber manufacturing are creating first-mover openings.
- Packaging Manufacturers:Flexible circuit substrates and semiconductor packaging absorb high purity grades at premium positioning.
- Electrical Components:Electronic-grade film specifications demand REACH-compliant batch documentation.
- Consumer Goods:Appliance housings and durable goods represent a price-sensitive outlet for standard grades.
Automotive suppliers command the established base. Textile manufacturing is gaining share fastest.
Distribution Channel:
Supply concentration dictates whether procurement runs through direct contracts or fragmented wholesale layers.
- Direct Sales:Integrated petrochemical conglomerates are consolidating backward into captive adiponitrile production, locking merchant supply access through long-term offtake agreements. Sinopec and domestic Chinese compounders internalize volumes through direct channels.
- Distributors:Regional compounders lacking hydrocyanation assets rely on distributor networks for spot market liquidity.
- Online Platforms:Standard grade spot transactions are migrating to digital procurement in India and Southeast Asia.
- Wholesale Markets:Legacy trading hubs in Rotterdam and Singapore handle residual volumes outside contract structures.
Direct sales command the established base. Distributor channels are expanding most quickly as standalone polymerizers seek supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive suppliers in Michigan and Stuttgart anchor premium-grade procurement, while Chinese compounders internalize merchant flows through captive adiponitrile-to-polymer circuits. Textile manufacturers in India and Japan are scaling specialized fiber-grade offtake as tire cord specifications tighten.
United States
EPA Clean Air Act enforcement is hardening scrubber requirements for adiponitrile producers serving automotive under-hood applications. INVISTA leverages Gulf Coast hexamethylenediamine backward integration to sustain margin capture across the nylon chain. Chocolate Bayou facilities in Texas anchor North American supply security for Tier-1 polymerizers.
China
MEE dual carbon emissions intensity caps favor newer butadiene-route capacity expansions over legacy acrylonitrile dimerization circuits. Sinopec and domestic polyamide compounders scale captive production, thinning spot market liquidity for external buyers. Yangtze River Delta clusters concentrate integrated petrochemical complexes with adiponitrile-to-nylon 6,6 circuits.
Germany
REACH registration requirements constrain non-European producers seeking direct material import without full substance dossier compliance. Butachimie competes from the European platform with a specialized butadiene-based production route. Stuttgart automotive suppliers insert carbon footprint clauses into nylon 6,6 offtake contracts for electric vehicle components.
India
PLI scheme incentives for synthetic fiber manufacturing create first-mover openings for adiponitrile-to-polymer integration. Maharashtra and Gujarat industrial corridors attract polyamide compounding investments seeking regional supply security. Domestic textile producers scale tire cord and airbag fiber capacity to serve export markets.
Japan
METI industrial standards govern electronic-grade polyamide specifications for semiconductor packaging applications. Toray Industries and Mitsubishi Chemical anchor high-purity adiponitrile demand for flexible circuit substrates. Kansai and Chubu industrial zones concentrate membrane-based electrodimerization pilot units for on-site hexamethylenediamine integration.
Global Adiponitrile Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market consolidating around integrated petrochemical conglomerates with captive hydrocyanation assets. Standalone polymerizers lacking backward integration face compressed margin capture as merchant supply access tightens. Three archetypes dominate: integrated petrochemical conglomerates, regional nylon specialists, and electronic-grade purity providers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure feedstock access and regulatory compliance capabilities.
Among integrated petrochemical conglomerates, INVISTA and Sinopec exemplify channel-controlling archetypes with captive adiponitrile-to-polymer circuits. Ascend Performance Materials occupies a position within the North American regional specialist tier, anchoring supply security through dedicated production infrastructure. Butachimie represents the European platform specialist, leveraging route-specific process technology to serve contamination-sensitive applications.
| Leading Market Players |
|---|
| Asahi Kasei Corp |
| Toray Industries |
| INVISTA |
| Sinopec |
| Lanxess |
| Ascend Performance Materials |
| Mitsubishi Chemical |
| Butachimie |
| BASF SE |
| Others |
Supply & Pricing Matrix
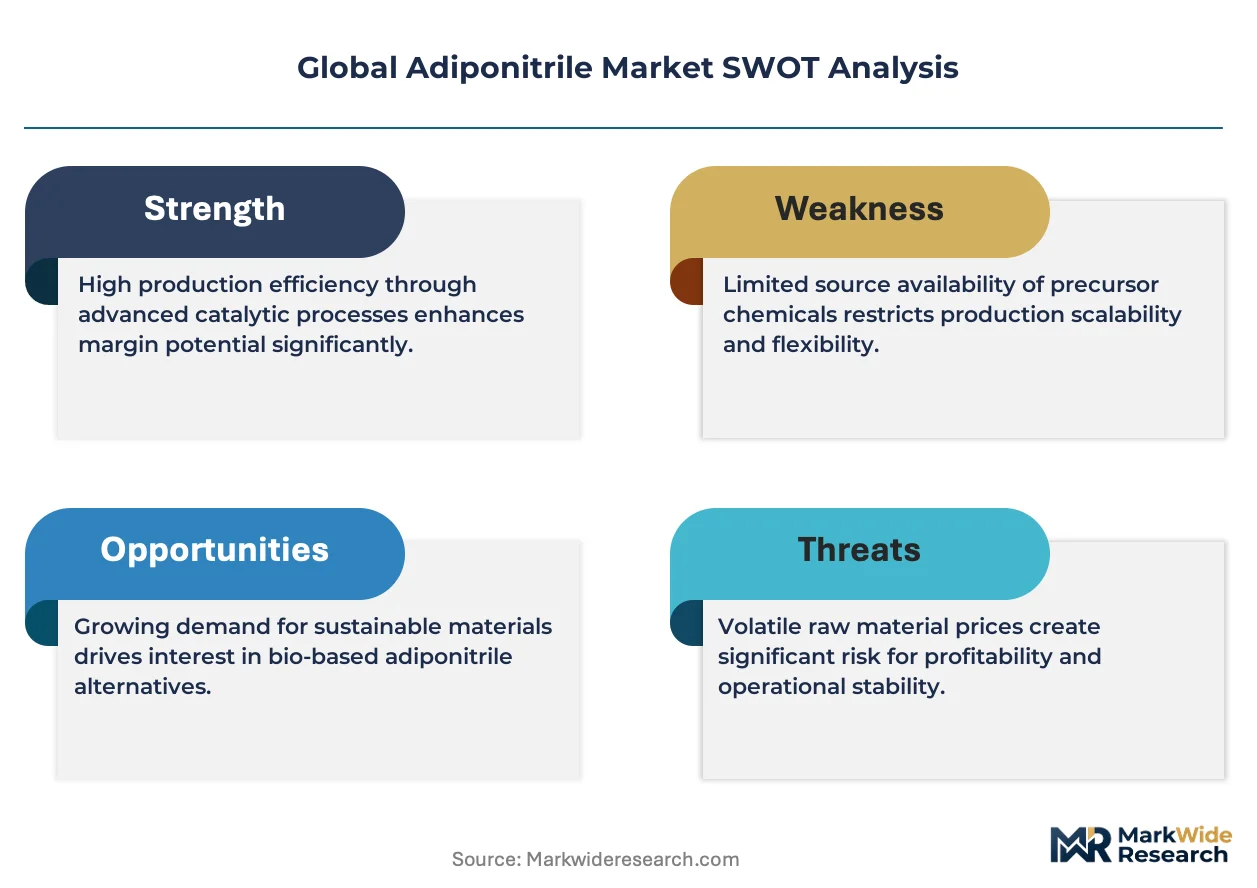
Butadiene feedstock volatility tied to crude-linked naphtha cracking economics determines both contract indexation spreads and the geographic shape of adiponitrile supply networks. This single-source dependency on petrochemical cracking margins compresses pricing power for butadiene-route producers while favoring electrodimerization assets with acrylonitrile flexibility.
Pricing Analysis
Cost-plus contracts indexed to butadiene and acrylonitrile spot benchmarks dominate long-term offtake agreements between integrated producers and automotive polymerizers. Price differentiation separates electronic-grade high purity streams with carbon-intensity certification from commodity liquid grades where volume scale governs negotiations. Pricing pressure stems from Sinopec's captive internalization thinning merchant spot liquidity. Tier-1 automotive suppliers in Stuttgart and Michigan show least price sensitivity due to sustainability scorecard requirements, while regional compounders in India absorb maximum cost compression.
Supply Chain Analysis
Export-control restrictions on hydrogen cyanide handling technology limit technology transfer to non-integrated entrants, concentrating capacity in China, the United States, and Germany. Raw material flows draw from butadiene extraction units at naphtha crackers, ammonia cracking facilities, and acrylonitrile polymerization trains. Single-source vulnerability runs through Yangtze River Delta clusters where Sinopec internalization eliminates merchant buffer stocks. Distribution runs through direct sales channels for integrated conglomerates and fragmented distributor networks for standalone polymerizers lacking hydrocyanation assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against bio-based polyamide precursors and recycled nylon feedstocks that threaten to displace virgin adiponitrile in automotive sustainability scorecards.
For Market Incumbents: Entrench backward integration into hexamethylenediamine production to lock margin capture against merchant supply compression from Sinopec's captive expansion. Prioritize carbon-intensity certification investments to defend premium positioning against bio-based substitute threats in electric vehicle under-hood specifications. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized synthetic fiber corridor where domestic adiponitrile-to-polymer integration remains underdeveloped. Target electronic-grade high purity segments in Japan and Germany where membrane-based electrodimerization enables smaller-scale regional units below legacy world-scale minimums. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated petrochemical conglomerates with captive hydrocyanation and regulatory compliance infrastructure. Acquisition targets should screen for REACH-registered European assets or MEE-compliant Chinese butadiene-route capacity. Watch bio-based polyamide pilot announcements as the inflection signal forcing accelerated carbon-intensity repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | INVISTA's Gulf Coast hexamethylenediamine link secures margin capture across the nylon chain. |
| Capacity Expansion | Sinopec's Yangtze River Delta additions internalize merchant volumes and thin spot liquidity. |
| Green Manufacturing Transition | Renewable ammonia cracking converges with bio-acrylonitrile to enable carbon-labeled production. |
| Long-term Supply Agreement | Tier-1 automotive suppliers in Michigan insert carbon footprint clauses into nylon 6,6 contracts. |
| Joint Venture | Butachimie's European platform leverages specialized butadiene technology for contamination-sensitive applications. |
Research Methodology
Operator-level perspectives from plant managers at adiponitrile facilities, procurement leads at Tier-1 automotive suppliers, technical R&D directors at polyamide compounders, and distribution channel partners anchored the qualitative base. Secondary validation drew from customs and trade flow databases, American Chemistry Council and Cefic industry reports, SEC 10-K filings of listed petrochemical conglomerates, and EPA Clean Air Act enforcement records. Bottom-up capacity modeling triangulated against top-down nylon 6,6 demand projections to ensure consistency.
Scenario-bracketing around butadiene price volatility bands and regulatory compliance cost trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry application, and regional production hub configuration. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive lightweighting intensity and textile fiber specification tightening. Forecast inputs specifically tracked EPA emissions rule evolution and China MEE dual carbon enforcement timelines.
Macroeconomic conditions sit as an overlay; deviation in crude oil price regimes, naphtha cracking spreads, or carbon credit valuation would shift the trajectory. Forecasts reflect documented assumptions on technology substitution rates and regulatory enforcement intensity. Material shifts in bio-based polyamide commercialization timelines or REACH authorization list expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Global Methylal Market
Functional Chemicals
Amino Acids Market
Functional Chemicals
Adipamide Market
Functional Chemicals
Succinic Acid Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
Serine Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
Asparagine Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Sodium Lauroyl Glutamate Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
Europe Formic Acid Market