
 Propylparaben Market | 2026-2036
Propylparaben Market Size, Share, and Industry Trends Forecast 2026-2036
Propylparaben Market Analytics
China's Jiangsu province is fragmenting as new paraben capacity comes online near Nantong and Taizhou chemical parks. BASF SE leverages its Ludwigshafen integrated aromatics complex to sustain captive p-hydroxybenzoic acid supply for propylparaben output. Zhejiang Shengxiao Chemicals Co., Ltd. anchors export volumes through dedicated cosmetic-grade purification lines serving Japanese and ASEAN formulators.
Propylparaben, the propyl ester of p-hydroxybenzoic acid (CAS 94-13-3), functions as a broad-spectrum antimicrobial preservative effective against molds and yeasts in the pH range 4-8, manufactured primarily via Fischer esterification of the acid with n-propanol under acid catalysis. Its primary commercial purpose centers on extending shelf stability in water-based personal care formulations where gram-negative bacterial contamination risks dominate. Cosmetics applications lead absolute consumption, while pharmaceutical-grade specifications command the steepest purity premiums and tightest batch certification. Skincare segments within the application dimension grow fastest as K-beauty and clean-label moisturizers multiply SKUs requiring reliable preservation without formaldehyde donors.
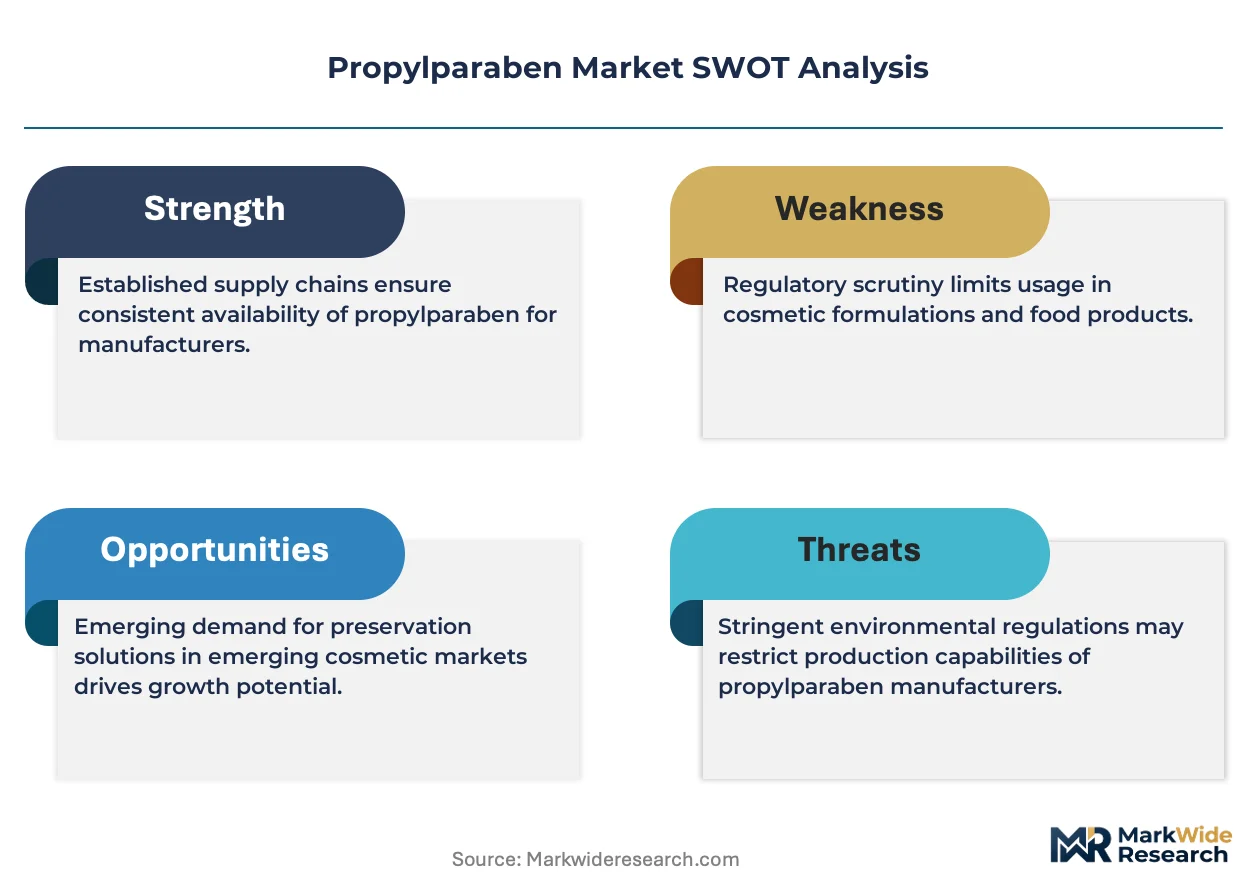
EMA's Committee for Medicinal Products for Human Use and FDA's Inactive Ingredient Database jointly constrain pharmaceutical-grade propylparaben specifications, while REACH Annex XVII restrictions on paraben concentrations in cosmetic leave-on products reshape European formulation demand toward alternative preservatives or reduced-concentration blends. China's SAMR enforces GB standards for food-grade paraben use that remain more permissive than EU EFSA limits, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor pending EU Green Deal chemical sustainability criteria and evolving state-level preservative disclosure mandates in California and New York to anticipate reformulation cascades before they disrupt existing supply contracts.
Market Dynamics
REACH Annex XVII restrictions on paraben concentrations in cosmetic leave-on products are forcing European formulators toward reduced-concentration blends and alternative preservative systems, compressing traditional demand pools while elevating compliance costs across the value chain.
Growth Catalysts
- K-beauty export surge:South Korean cosmetics manufacturers are expanding propylparaben consumption as moisturizers and essences multiply SKUs requiring reliable preservation without formaldehyde donors.
- GB standards permissiveness:China's SAMR enforces food-grade paraben limits that remain more lenient than EU EFSA thresholds, creating divergent compliance pathways that favor multinational suppliers with dual-certification capabilities.
- Fischer esterification optimization:Acid-catalyzed production refinements near Nantong and Taizhou chemical parks are lowering unit costs for cosmetic-grade material serving ASEAN formulators.
Market Restraints
- p-hydroxybenzoic acid supply concentration:Captive aromatics complexes at Ludwigshafen and select Chinese integrated sites control upstream feedstock, limiting independent propylparaben producers' margin flexibility.
- EMA/FDA specification divergence:Pharmaceutical-grade certification requires reconciling divergent purity thresholds between European and American regulators, extending batch approval timelines.
- Phenoxyethanol substitution:Clean-label marketers are displacing parabens in premium skincare with alternative preservatives that bypass consumer perception challenges.
Strategic Opportunities
- Clean-label blend formulations:Low-concentration propylparaben combinations with organic acids are opening positioning in "preservative-free" marketing claims for Japanese and South Korean skincare brands.
- EU Green Deal chemical sustainability criteria:Pending carbon-footprint disclosure mandates favor producers with bio-based propanol feedstock or renewable energy-integrated esterification.
- Pharmaceutical-grade purity premiums:Injectable and ophthalmic specifications command the steepest batch certification margins, rewarding investment in dedicated GMP purification lines.
Industry Challenges
- Dual-certification talent scarcity:Formulation chemists capable of navigating simultaneous REACH, FDA Inactive Ingredient Database, and GB standard compliance remain concentrated at multinational headquarters.
- California and New York disclosure mandates:State-level preservative reporting requirements are fragmenting labeling strategies and forcing SKU proliferation for US market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propylparaben Market |
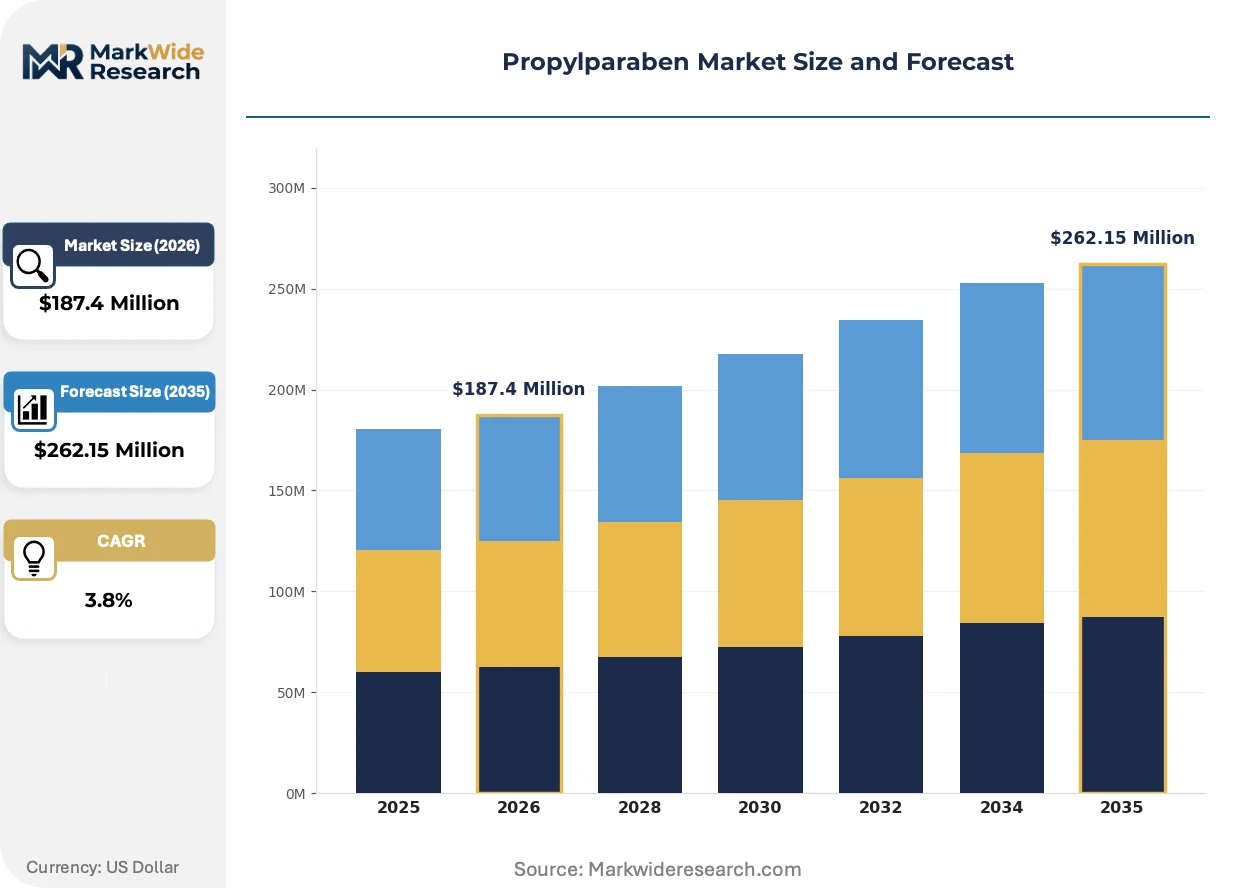
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Pharmaceuticals, Personal Care Products, Food Preservatives Application: Skincare, Haircare, Makeup, Oral Care End User: Manufacturers, Retailers, Laboratories, Brands Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Ashland Global Holdings Inc., BASF SE, Clariant AG, Akema Fine Chemicals, Salicylates and Chemicals Pvt. Ltd., Zhejiang Shengxiao Chemicals Co., Ltd., Alta Laboratories Ltd., Anhui Leafchem Co., Ltd., UENO Fine Chemicals Industry Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propylparaben Market Evolving Landscape
Digitalization of quality assurance and batch certification is compressing verification timelines while regulatory fragmentation across major economies is multiplying compliance architectures. Formulators are responding with modular preservation systems.
Encapsulation technology using cyclodextrin or lipid-based delivery systems is virtualizing propylparaben release profiles, enabling time-delayed antimicrobial action in water-based emulsions. Premium skincare brands in Japan and South Korea are adopting these systems to reduce total preservative load while maintaining shelf stability. The technology is virtualizing traditional concentration-based preservation models toward performance-based dosing architectures that satisfy clean-label positioning.
REACH authorization procedures for existing cosmetic preservatives are tightening substance evaluation protocols, forcing suppliers to submit enhanced safety dossiers or face concentration restrictions. The European Chemicals Agency's accelerated assessment timeline is compressing reformulation windows for leave-on products. Multinational cosmetics houses are responding by diversifying preservation portfolios across manufacturing sites to ensure regulatory continuity.
Direct procurement relationships between cosmetic brand technical teams and Chinese chemical park producers are disintermediating traditional distributor networks for cosmetic-grade material. Japanese and South Korean formulators are establishing technical liaison offices in Jiangsu province to secure dedicated purification line capacity. This channel restructuring is most visible in moisturizer and essence categories where batch consistency requirements exceed standard commodity specifications.
Propylparaben Market Segmentation
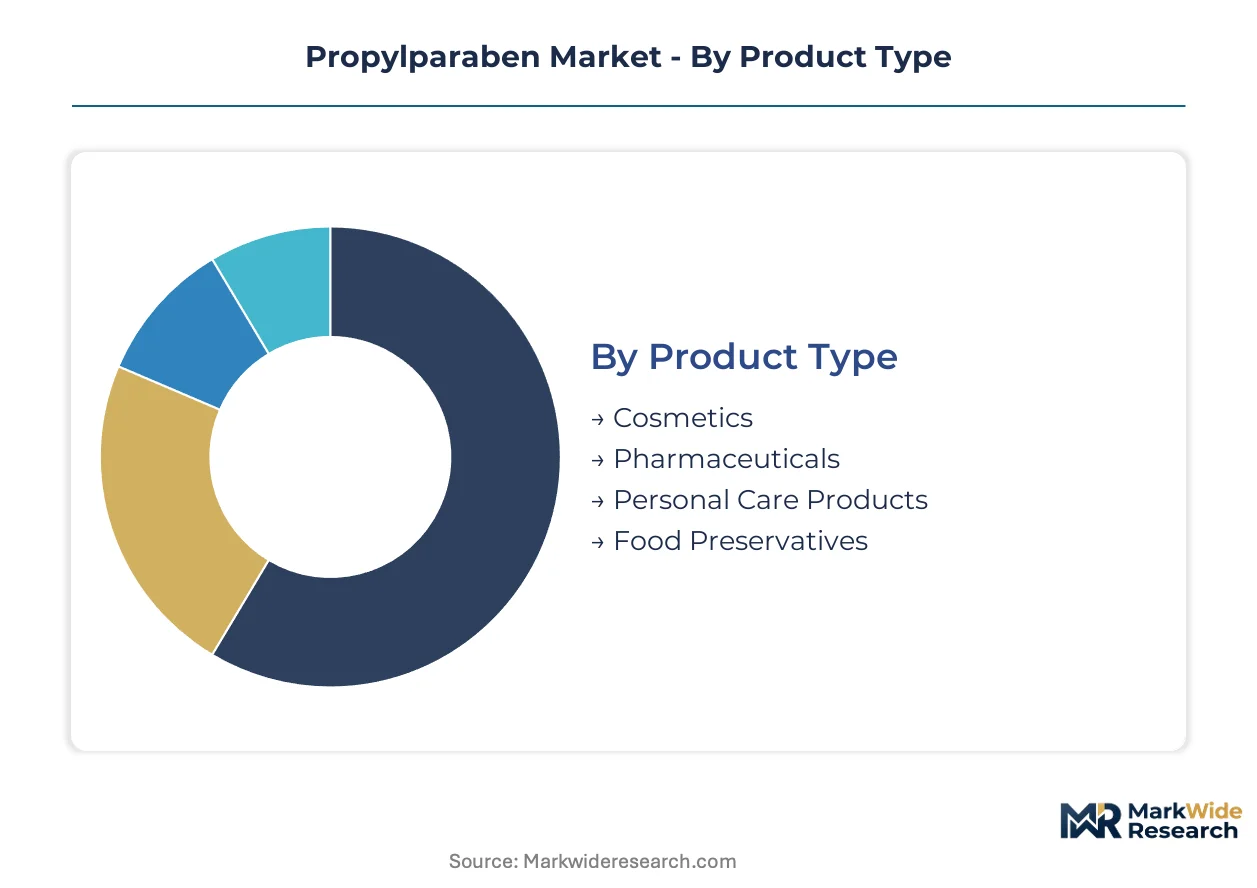
Propylparaben demand fragments across preservation intensity tiers, with after-sales technical support requirements varying sharply between pharmaceutical certification and commodity cosmetic supply. Segmentation reveals where formulation complexity and regulatory burden concentrate margin premiums.
Product Type:
After-sales service intensity peaks in pharmaceutical-grade supply chains, where batch certification failures trigger regulatory exposure and customer liability.
- Cosmetics:Cosmetic-grade propylparaben dominates absolute volume, serving water-based moisturizers and essences where K-beauty brands demand reliable mold inhibition without formaldehyde donor alternatives. South Korean formulators drive specification tightening as SKU multiplication strains preservation system stability.
- Pharmaceuticals:Injectable and ophthalmic grades command the steepest purity premiums, requiring reconciliation of EMA and FDA divergent specifications that extend batch approval timelines and elevate technical service intensity.
- Personal Care Products:Deodorants and wet wipes utilize standard cosmetic grades with moderate certification overhead.
- Food Preservatives:China's SAMR enforces GB standards more permissive than EU EFSA limits, creating dual-compliance complexity for multinational suppliers.
By volume, Cosmetics leads. By growth pace, Pharmaceuticals is climbing the fastest.
Application:
Cost tier stratification separates premium skincare formulations from mass-market haircare, with preservation system investment scaling directly with product positioning.
- Skincare:Moisturizers and essences multiply SKUs fastest, driving demand for encapsulation-enabled time-delayed release systems that reduce total preservative load while maintaining shelf stability in Japanese and South Korean premium positioning.
- Haircare:Shampoos and conditioners utilize standard paraben concentrations with lower reformulation frequency than leave-on skincare.
- Makeup:Color cosmetics face clean-label displacement pressure as phenoxyethanol substitutes penetrate premium segments.
- Oral Care:Toothpastes and mouthwashes employ food-grade adjacent specifications with SAMR GB standard compliance.
Skincare absorbs the highest preservation R&D investment per SKU; Haircare maintains the most stable procurement contracts.
End User:
Customer type determines specification authority, with brand technical teams increasingly disintermediating distributors to secure dedicated Chinese purification line capacity.
- Manufacturers:Integrated cosmetics houses in South Korea and Japan establish direct technical liaison offices in Jiangsu province, securing batch consistency for moisturizer and essence categories that exceed commodity specifications.
- Retailers:Private-label skincare programs demand modular preservation systems adaptable to California and New York state-level disclosure mandates.
- Laboratories:Contract manufacturers navigate dual-certification talent scarcity concentrated at multinational headquarters.
- Brands:Clean-label marketers displace parabens with alternative preservatives in premium positioning.
Manufacturers control the tightest specifications; Retailers generate the most SKU proliferation.
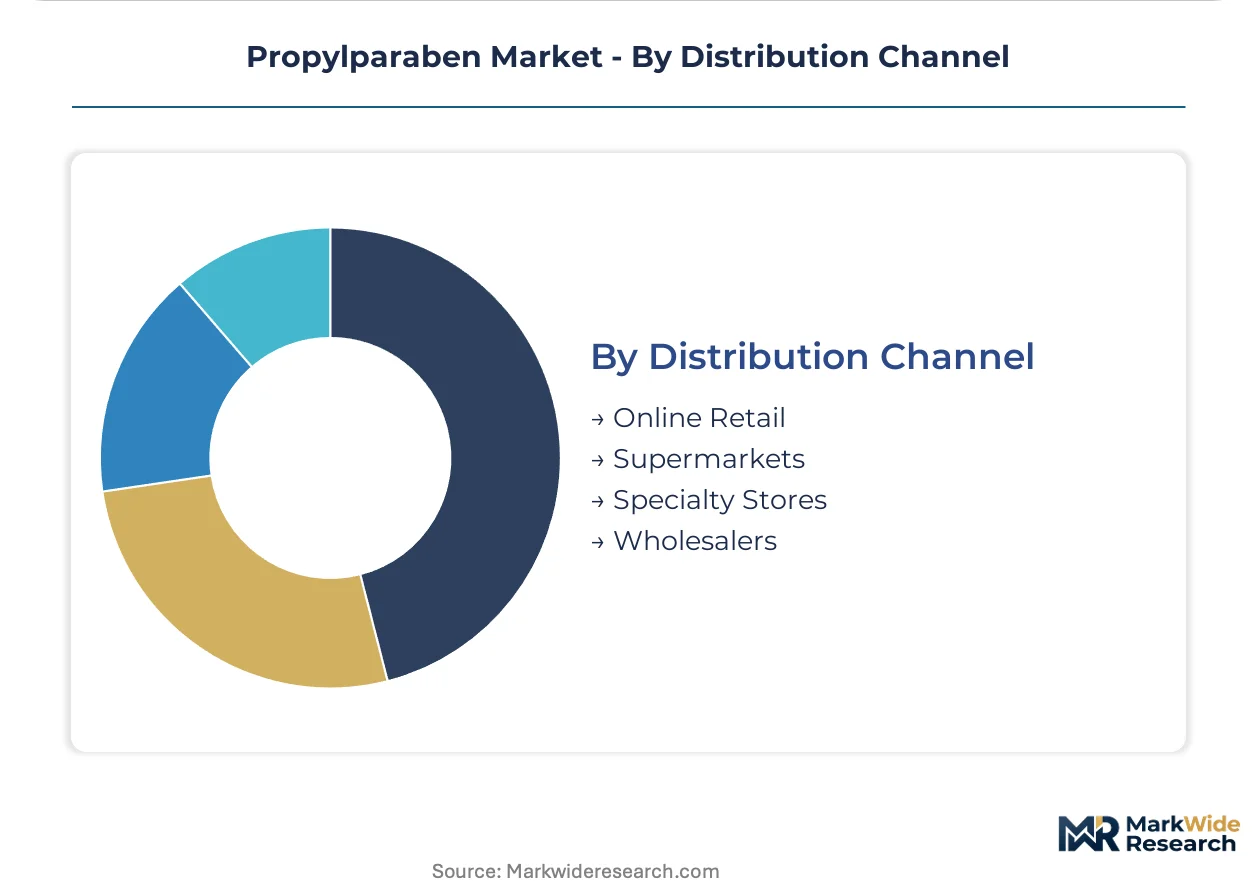
Distribution Channel:
Supply concentration near Shanghai and Nantong chemical parks shapes channel efficiency, with direct procurement restructuring traditional distributor networks.
- Online Retail:E-commerce platforms serving ASEAN formulators compress lead times for cosmetic-grade material through digitalized quality assurance and batch certification.
- Supermarkets:Mass-market personal care products flow through established wholesale networks with standardized specifications.
- Specialty Stores:Premium skincare boutiques demand traceability documentation for clean-label blend formulations.
- Wholesalers:Traditional distributors face margin compression as technical teams source directly from Taizhou chemical park producers.
Online Retail is expanding most quickly; Wholesalers retain the highest volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater port infrastructure underwrites China's dominance in paraben export logistics, while Ludwigshafen's Rhine corridor anchors European captive production. These arterial networks determine where formulation-grade material concentrates.
China
Jiangsu province's Nantong and Taizhou chemical parks fragment capacity as new esterification lines target ASEAN cosmetic formulators. SAMR enforces GB standards for food-grade applications that remain more permissive than EU EFSA thresholds. Direct procurement channels from these parks to Japanese and South Korean technical teams are disintermediating traditional distributors.
Germany
BASF SE leverages its Ludwigshafen integrated aromatics complex to sustain captive p-hydroxybenzoic acid supply for pharmaceutical-grade output. REACH Annex XVII restrictions on paraben concentrations in cosmetic leave-on products compress traditional demand pools while elevating compliance costs. The Rhine-Main corridor concentrates EMA-aligned batch certification capacity for injectable specifications.
South Korea
Seoul Capital Area cosmetics manufacturers drive expanding propylparaben consumption as K-beauty moisturizers and essences multiply SKUs. MFDS pharmaceutical-grade specifications align with EMA purity thresholds, enabling dual-certification exports. Technical liaison offices in Jiangsu province secure dedicated purification line capacity for premium skincare formulations.
United States
California and New York state-level preservative disclosure mandates fragment labeling strategies and force SKU proliferation for domestic market access. FDA Inactive Ingredient Database specifications diverge from EMA thresholds, extending batch approval timelines for pharmaceutical applications. West Coast formulators navigate dual-certification complexity for products serving both domestic and European markets.
Japan
Kanto region formulators adopt encapsulation-enabled time-delayed release systems to reduce total preservative load while maintaining shelf stability. PMDA pharmaceutical-grade requirements command steepest purity premiums for ophthalmic and injectable applications. Zhejiang Shengxiao Chemicals Co., Ltd. anchors export volumes through dedicated cosmetic-grade purification lines serving Japanese technical specifications.
Propylparaben Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and purification. The vendor base stratifies across integrated aromatics complexes, dedicated esterification specialists, and regional purification houses. Three archetypes dominate: captive producers with backward integration into p-hydroxybenzoic acid, independent esterification houses serving commodity cosmetic grades, and certification-focused specialists targeting pharmaceutical injectable specifications. Capacity expansion near Chinese chemical parks and portfolio diversification toward clean-label blend formulations constitute the dominant competitive moves.
Among European integrated producers, BASF SE exemplifies the captive-feedstock archetype through its Ludwigshafen aromatics complex. Zhejiang Shengxiao Chemicals Co., Ltd. occupies a position within the dedicated purification specialist tier, serving Japanese and ASEAN cosmetic-grade demand. UENO Fine Chemicals Industry Ltd. represents the certification-focused segment, anchoring pharmaceutical-grade supply alignment with PMDA specifications.
| Leading Market Players |
|---|
| Ashland Global Holdings Inc. |
| BASF SE |
| Clariant AG |
| Akema Fine Chemicals |
| Salicylates and Chemicals Pvt. Ltd. |
| Zhejiang Shengxiao Chemicals Co., Ltd. |
| Alta Laboratories Ltd. |
| Anhui Leafchem Co., Ltd. |
| UENO Fine Chemicals Industry Ltd. |
| Others |
Value Network & Pricing Analysis
REACH Annex XVII concentration restrictions determine both pricing tier spreads and supply chain shape by compressing European demand pools while elevating compliance costs that independent producers cannot absorb. Pharmaceutical-grade certification premiums widen against commodity cosmetic grades as EMA and FDA specification divergence extends batch approval timelines and concentrates technical service intensity.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with three-tier pricing stratification across pharmaceutical, cosmetic-grade, and food-grade certification levels. Price differentiation rests on purity thresholds and dual-certification capabilities, with injectable specifications commanding the widest premiums over standard moisturizers. Cost compression in commodity cosmetic grades is intensifying because Fischer esterification optimization near Nantong chemical parks expands ASEAN-facing capacity. Mass-market personal care manufacturers exhibit the highest price sensitivity, while ophthalmic and injectable formulators tolerate steep premiums for batch consistency.
Supply Chain Analysis
Export-control regimes on pharmaceutical-grade specifications limit flows between regulatory jurisdictions, fragmenting supply architectures. Production concentrates in China, Germany, and South Korea, with Jiangsu province's Nantong and Taizhou chemical parks anchoring cosmetic-grade export capacity. Raw material dependencies center on p-hydroxybenzoic acid feedstock, n-propanol, and acid catalysts. Single-source vulnerability runs through captive aromatics complexes at Ludwigshafen and select Chinese integrated sites controlling upstream supply. Distribution runs through direct procurement channels disintermediating traditional wholesalers, as Japanese and South Korean technical teams establish liaison offices in Jiangsu province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encapsulation-enabled time-delayed release systems are disrupting preservation architectures, creating white-space for performance-based dosing that satisfies clean-label positioning without abandoning paraben efficacy. REACH authorization acceleration compresses reformulation windows and favors suppliers with diversified preservation portfolios.
For Market Incumbents: Entrench pharmaceutical-grade certification barriers by investing in dedicated GMP purification lines for injectable and ophthalmic specifications. Deepen upstream control over p-hydroxybenzoic acid supply through captive aromatics integration or long-term offtake agreements with Ludwigshafen-aligned producers. Phenoxyethanol substitution in premium skincare threatens paraben volume; counter with low-concentration blend formulations positioned for "preservative-free" marketing claims.
For New Entrants and Emerging Players: Pursue clean-label blend formulations combining propylparaben with organic acids for Japanese and South Korean skincare brands seeking reduced total preservative load. Target ASEAN cosmetic formulators through digitalized quality assurance platforms compressing batch certification timelines. Establish technical liaison presence in Jiangsu province to secure dedicated purification line capacity bypassing traditional distributor networks.
For Investors and Strategic Acquirers: EU Green Deal chemical sustainability criteria reshapes the acquisition landscape toward producers with bio-based propanol feedstock or renewable energy-integrated esterification. Long-term viability over a five-to-ten year window favors certification-focused specialists with pharmaceutical-grade margins over commodity cosmetic-grade producers facing phenoxyethanol displacement. Monitor pending carbon-footprint disclosure mandates as the signal indicating which capacity expansions will retain regulatory permission to operate.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into p-hydroxybenzoic Acid | Captive feedstock supply at Ludwigshafen insulates BASF from aromatics price volatility. |
| Pharmaceutical-Grade GMP Line Investment | Dedicated purification capacity captures EMA-aligned injectable specification premiums. |
| Clean-Label Blend Formulation Development | Organic acid combinations open positioning in Japanese "preservative-free" skincare segments. |
| Jiangsu Province Technical Liaison Establishment | Direct procurement from Nantong chemical parks secures batch consistency for K-beauty formulators. |
| Bio-Based Propanol Feedstock Transition | Renewable esterification feedstock aligns with EU Green Deal carbon-footprint disclosure mandates. |
Research Methodology
Desk research of regulatory filings, customs trade databases, and chemical industry association reports preceded structured interviews with plant managers at Chinese esterification facilities, procurement leads at South Korean cosmetics houses, technical R&D directors, and distribution channel partners. Primary fieldwork combined with secondary validation from EMA safety dossiers, FDA Inactive Ingredient Database entries, and SAMR GB standard documentation. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Assumption sets held fixed the current REACH Annex XVII concentration limits and SAMR permissiveness while varying K-beauty export growth trajectories and phenoxyethanol substitution rates across the projection horizon. Segmentation dimensions modeled included grade tier, end-use industry, and regional regulatory cluster. CAGRs derived from weighted average of historical volume trends and forward-looking capacity expansion announcements, with specific inputs for encapsulation technology adoption curves and direct procurement channel penetration.
Macroeconomic conditions sit as an overlay; deviation in exchange rate volatility between euro and renminbi, or energy cost shocks affecting aromatics complexes, would shift the trajectory. Forecasts reflect documented assumptions on regulatory stability and substitution technology performance. Material shifts in EMA authorization timelines or California disclosure mandate enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Carbomer Market
Functional Chemicals
Global Sodium Lignosulfonate Market
Functional Chemicals
Amino Acids Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
Amino Acid Chelates Market
Functional Chemicals
Threonine Acids Market
Functional Chemicals
Sodium Malate Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
Thymolphthalein Market
Functional Chemicals
Calcium Citrate Malate Market
Functional Chemicals
Lauric Acid Market
Functional Chemicals
Chlorobutanol Market
Functional Chemicals
Functional Polymer Market