
 Ortho Phthalic Aldehyde Market | 2026-2036
Ortho Phthalic Aldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Ortho Phthalic Aldehyde Market Outlook
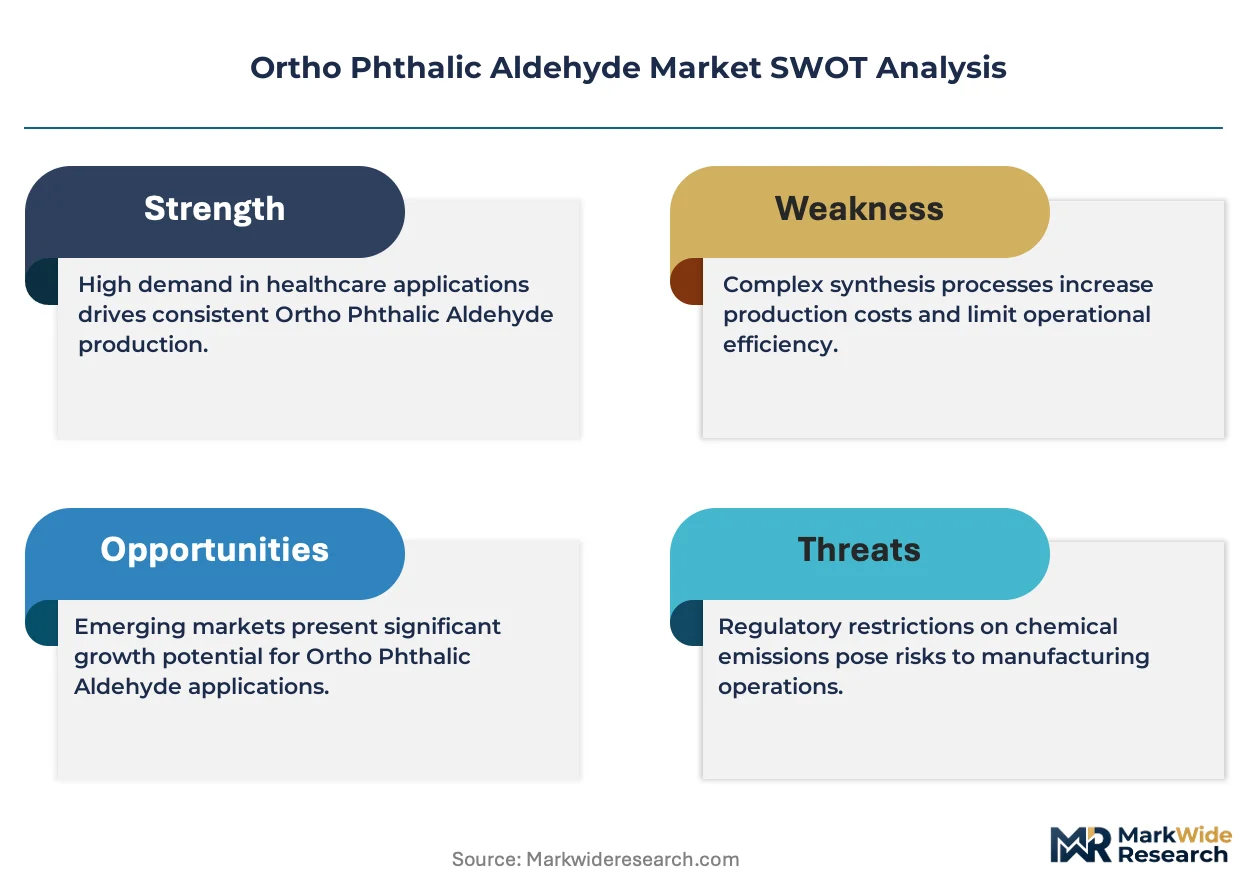
Aftermarket sterilization service revenue is reshaping margin distribution across the value chain. Mitsubishi Gas Chemicals Co. Inc. leverages its integrated gas-chemical platform to control feedstock costs for high-purity grades. Merck KGaA anchors its position through pharmaceutical-grade certification and stringent quality systems. Advanced Sterilization Products competes by concentrating on hospital and clinic channel relationships.
Ortho phthalic aldehyde is a dialdehyde aromatic compound with the molecular formula C8H6O2, manufactured primarily through controlled oxidation of o-xylene or naphthalene derivatives, and functions as a high-level disinfectant and chemical intermediate in industrial synthesis. The plasticizers segment dominates volume consumption due to entrenched PVC additive demand, while the resins category captures concentrated margin pools from specialty coating formulations. Pharmaceutical end users represent the fastest-growing demand vertical as sterilization protocols tighten across healthcare systems.
EPA registration requirements under FIFRA govern disinfectant efficacy claims and label specifications in the United States, while REACH authorization processes in Europe restrict hazardous substance thresholds and mandate substitution planning. The FDA's oversight of medical device sterilization validation creates additional compliance layers for suppliers serving healthcare applications. Stakeholders must monitor regulatory divergence between jurisdictions and calibrate product portfolios to maintain multi-market access without redundant certification burdens.
Market Dynamics
REACH authorization processes and EPA registration requirements under FIFRA are tightening purity benchmarks for ortho phthalic aldehyde suppliers, forcing qualification recalibrations across pharmaceutical sterilization and industrial chemical applications.
Growth Catalysts
- Healthcare disinfection protocols:Hospital sterilization departments are upgrading to high-level disinfectants as surgical site infection prevention standards tighten across OECD healthcare systems.
- REACH substitution mandates:European chemical manufacturers are reformulating coating intermediates to comply with hazardous substance thresholds and substitution planning requirements.
- India's phthalic anhydride expansion:Domestic chemical producers are scaling derivative output to serve regional coating and resin consumers, concentrating demand within the subcontinent.
Market Restraints
- o-Xylene feedstock volatility:Aromatic feedstock prices fluctuate with crude oil benchmarks, compressing margin predictability for oxidation-route manufacturers.
- Chinese supply concentration:Intermediate chemical production clusters in Shandong and Jiangsu provinces create geographic vulnerability for non-integrated buyers.
- Glutaraldehyde substitution threat:Alternative high-level disinfectants retain installed base in endoscope reprocessing due to lower per-use cost structures.
Strategic Opportunities
- Brazil's healthcare infrastructure:ANVISA regulatory alignment with international sterilization standards is opening qualification pathways for imported pharmaceutical-grade material.
- UV-activated disinfection convergence:Combination chemistries integrating ortho phthalic aldehyde with photo-catalytic activation are emerging in dental and ophthalmic instrument processing.
- Direct hospital procurement channels:Group purchasing organizations are consolidating sterilization chemical contracts, rewarding suppliers with integrated service capabilities.
Industry Challenges
- EPA FIFRA registration timelines:Efficacy claim validation and label approval processes extend 18-24 months, delaying market entry for reformulated products.
- Legacy equipment compatibility:Automated endoscope reprocessors from prior technology generations require material compatibility testing, fragmenting addressable volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ortho Phthalic Aldehyde Market |
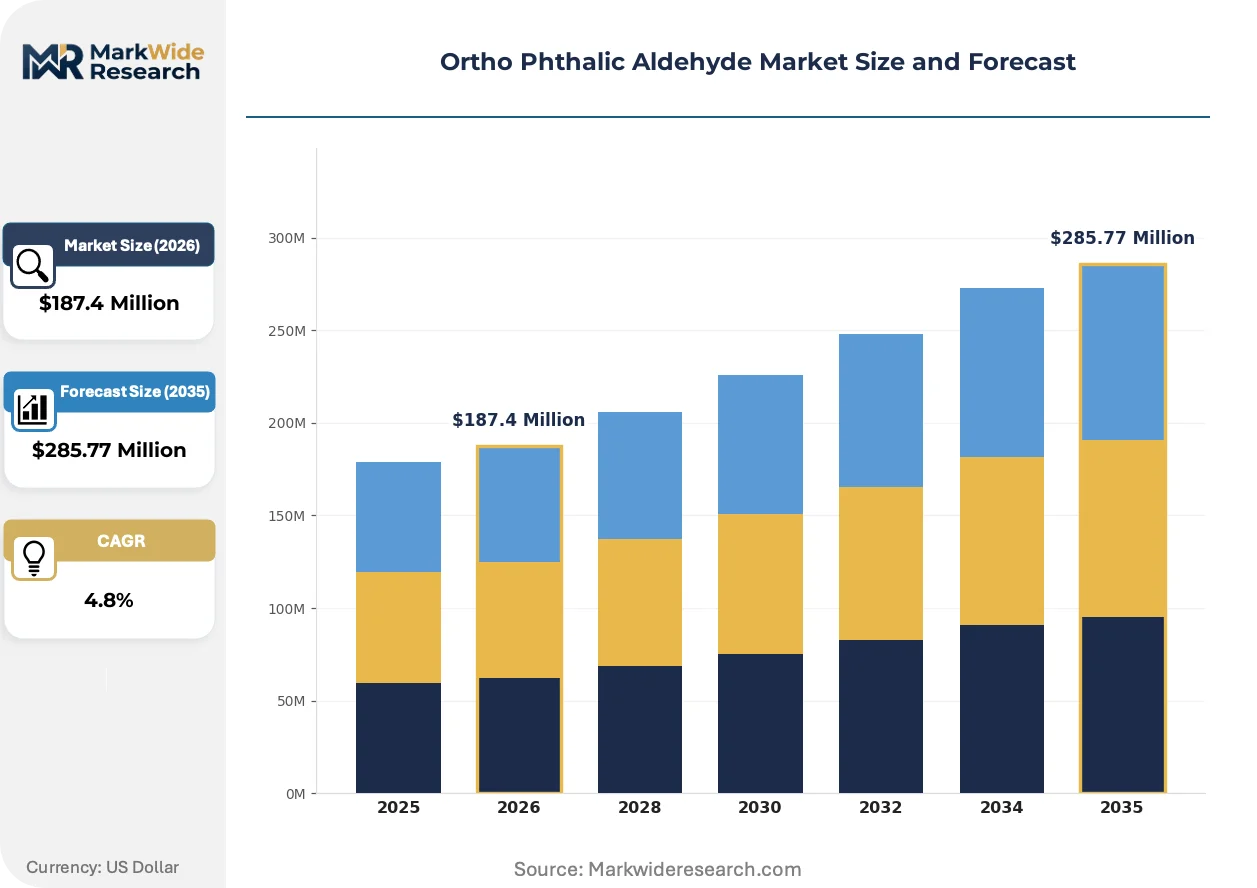
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Dyes, Resins, Intermediates Application: Coatings, Adhesives, Plastics, Personal Care End User: Construction, Automotive, Consumer Goods, Pharmaceuticals Technology: Chemical Synthesis, Distillation, Reaction Technology, Catalysis |
| Companies Covered | OCI Company Limited, Hanwha Chemical Corporation, Thirumalai Chemicals Ltd, LANXESS, Mitsubishi Gas Chemicals Co. Inc., Merck KGaA, Sigma-Aldrich, Tokyo Chemical Industry Co. Ltd., Advanced Sterilization Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ortho Phthalic Aldehyde Market Strategic Shifts
Sterilization chemistry is converging with digital validation systems and sustainability mandates, reshaping how suppliers demonstrate efficacy, traceability, and environmental compliance across healthcare and industrial channels.
Continuous flow oxidation technology is virtualizing batch manufacturing economics for high-purity ortho phthalic aldehyde. Pharmaceutical-grade producers in Germany and Switzerland are adopting microreactor platforms to reduce solvent intensity and improve lot-to-lot consistency. This process architecture is compressing capital requirements for entry-level pharmaceutical certification while raising barriers for legacy batch operators.
EPA's evolving framework for antimicrobial pesticide efficacy claims is tightening substantiation requirements for high-level disinfectant labels. Manufacturers must now generate expanded spectrum data against mycobacteria and spore-forming organisms, extending development cycles. Hospital infection control committees are responding by consolidating supplier relationships around registrants with comprehensive label portfolios.
Certificate-of-analysis driven procurement is displacing commodity spot purchasing in hospital pharmacy and central sterile supply departments. Buyers now require chromatographic purity documentation and endotoxin testing for every lot, transferring quality assurance burden upstream to chemical manufacturers. This specification escalation is most visible in academic medical centers and tertiary referral hospitals across the United States and Western Europe.
Ortho Phthalic Aldehyde Market Segmentation
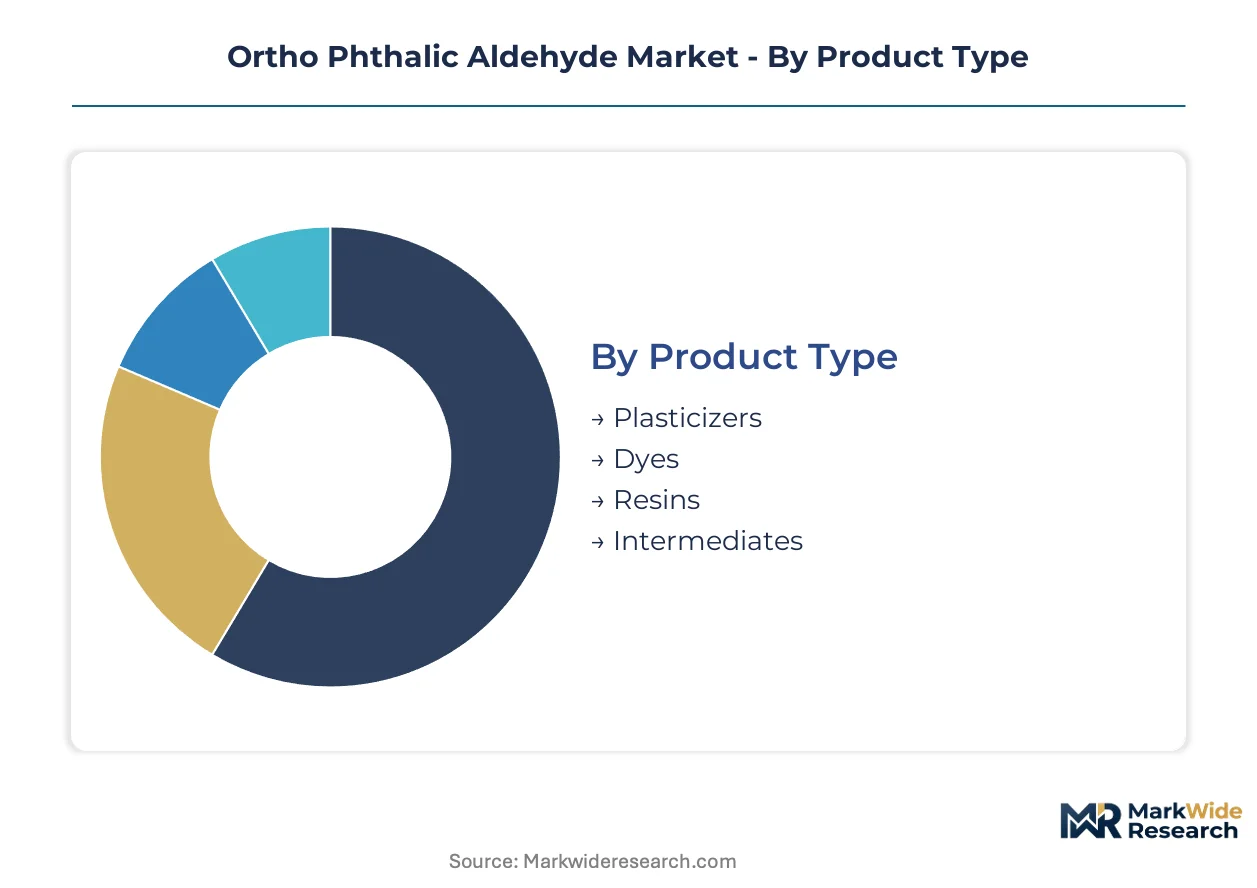
Ortho phthalic aldehyde demand fragments across distinct specification tiers, with pharmaceutical-grade batches commanding extended production cycles while industrial intermediates turn over rapidly. Understanding these velocity differentials helps suppliers calibrate inventory positioning and margin capture across the value chain.
Product Type:
Plasticizers and resins cycle through production fastest due to standardized purity requirements, while pharmaceutical intermediates sit in qualification queues for months.
- Plasticizers:These PVC additive formulations require technical-grade purity thresholds achievable through continuous oxidation routes. Demand concentrates in Gujarat and Maharashtra industrial corridors where domestic cable and flooring manufacturers are expanding compounding capacity.
- Resins:Specialty coating intermediates demand higher aldehyde content specifications and tighter moisture controls. German automotive OEMs are driving specification escalation through their tier-one coating supplier networks, compressing acceptable impurity bands.
- Dyes:Pigment intermediate applications consume technical-grade material through batch oxidation processes.
- Intermediates:Pharmaceutical-grade batches for sterilization chemistry require endotoxin testing and chromatographic certification.
Plasticizers anchors the volume base while Intermediates gains share at the steepest rate.
Application:
Coating formulations absorb the largest share of technical-grade output, though personal care applications are climbing the specification ladder fastest.
- Coatings:Automotive and industrial protective finishes utilize ortho phthalic aldehyde-derived alkyd resins for hardness and weather resistance. Japanese shipbuilders are reformulating marine coatings to reduce solvent emissions, tightening raw material purity requirements.
- Plastics:PVC processing relies on phthalate plasticizer precursors manufactured through aldehyde oxidation pathways. Indian pipe and profile extruders are scaling capacity to serve irrigation infrastructure programs.
- Adhesives:Structural bonding formulations employ aldehyde-modified phenolic resins for heat resistance.
- Personal Care:Cosmetic-grade specifications require heavy metal testing and microbial limits verification.
Coatings commands the revenue pool while Personal Care demonstrates the steepest expansion trajectory.
End User:
Automotive procurement cycles stretch longest due to qualification protocols, whereas construction spot purchasing turns inventory rapidly.
- Construction:Flooring, wall coverings, and waterproofing membranes consume plasticized PVC at scale. Saudi infrastructure contractors are importing prefabricated membrane systems, concentrating demand in Red Sea coastal developments.
- Pharmaceuticals:Sterilization departments in tertiary hospitals require pharmaceutical-grade material with full traceability documentation. ANVISA alignment with international standards is accelerating qualification pathways in Brazilian healthcare networks.
- Automotive:Interior trim and underbody coatings specify aldehyde-derived intermediates for durability.
- Consumer Goods:Packaging and household products utilize technical-grade material through distributor channels.
Construction drives absolute volume while Pharmaceuticals expands most quickly.
Technology:
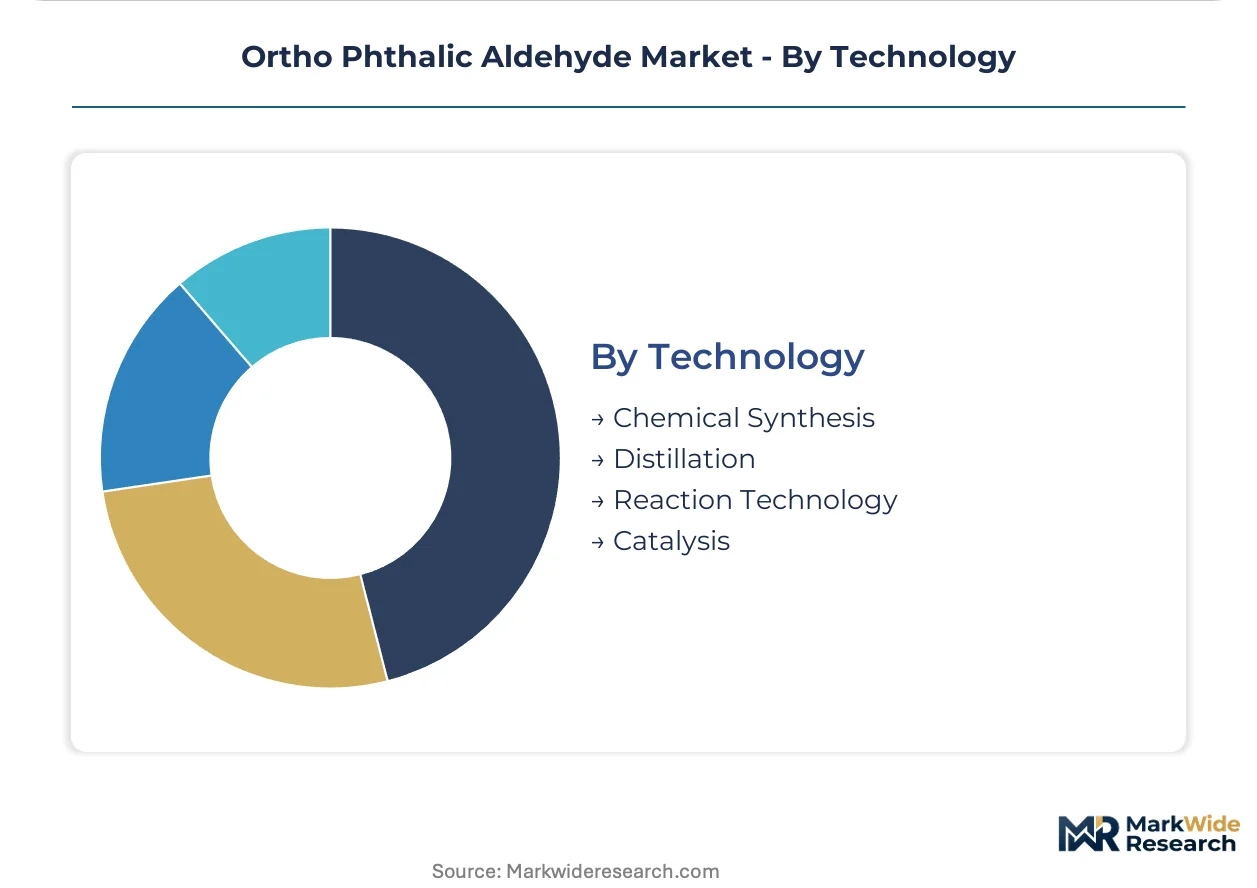
Distillation and catalysis platforms dominate throughput, though microreactor adoption is compressing cycle times for high-purity batches.
- Chemical Synthesis:Controlled o-xylene oxidation remains the baseline production architecture for technical-grade output. Shandong province producers operate at scale with legacy batch configurations.
- Catalysis:Heterogeneous catalyst systems improve selectivity and reduce byproduct formation in oxidation reactors. Swiss pharmaceutical-grade manufacturers are deploying noble metal catalysts for endotoxin-controlled production.
- Distillation:Fractional separation achieves commercial purity grades for industrial applications.
- Reaction Technology:Continuous flow microreactors enable pharmaceutical-grade lot consistency with reduced solvent intensity.
Chemical Synthesis underpins the installed base while Reaction Technology captures the steepest adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States channels material predominantly into hospital sterilization protocols, while China and India absorb volume through plasticizer and coating intermediate applications. European demand concentrates in REACH-compliant pharmaceutical grades with stringent substitution mandates.
United States
Hospital infection control committees drive specification escalation for high-level disinfectants. EPA registration under FIFRA governs efficacy claims and extends development cycles. Tertiary medical centers in Boston and Houston consolidate procurement around suppliers with comprehensive label portfolios.
Germany
Automotive OEMs demand aldehyde-derived coating intermediates with tightened impurity bands for durability specifications. ECHA REACH authorization restricts hazardous substance thresholds and mandates substitution planning. Industrial chemical clusters in North Rhine-Westphalia operate continuous oxidation platforms for technical-grade output.
China
Shandong and Jiangsu provinces host intermediate chemical production at scale for domestic PVC additive and coating resin manufacturers. NMPA alignment with international pharmaceutical standards remains partial, fragmenting qualification pathways for sterilization-grade imports. Legacy batch configurations dominate the installed production base.
India
Domestic cable and flooring manufacturers in Gujarat and Maharashtra expand compounding capacity for plasticized PVC. CDSCO pharmaceutical regulations tighten gradually, creating dual-track demand for technical and certified grades. Phthalic anhydride derivative output scales to serve regional coating consumers.
Brazil
Healthcare infrastructure investment accelerates qualification demand for imported pharmaceutical-grade material. ANVISA regulatory alignment with international sterilization standards opens pathway approvals for high-level disinfectant registrants. São Paulo hospital networks pilot centralized sterile processing departments.
Ortho Phthalic Aldehyde Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The vendor base stratifies between integrated gas-chemical platforms controlling feedstock costs and pharmaceutical-grade specialists anchoring positions through certification depth. Three archetypes dominate: oxidation-route commodity producers, high-purity batch operators, and hospital channel service integrators. Competitive moves center on capacity expansion in Indian chemical corridors and technology licensing for continuous flow microreactor platforms.
Within the integrated chemical platform tier, Mitsubishi Gas Chemicals Co. Inc. and OCI Company Limited occupy positions that exemplify feedstock-backward structures. Merck KGaA anchors the pharmaceutical-grade certification vector alongside Sigma-Aldrich, representing quality-system-dependent positioning. Advanced Sterilization Products exemplifies the service-integrated channel archetype, concentrating relationships with hospital procurement consolidators rather than manufacturing scale.
| Leading Market Players |
|---|
| OCI Company Limited |
| Hanwha Chemical Corporation |
| Thirumalai Chemicals Ltd |
| LANXESS |
| Mitsubishi Gas Chemicals Co. Inc. |
| Merck KGaA |
| Sigma-Aldrich |
| Tokyo Chemical Industry Co. Ltd. |
| Advanced Sterilization Products |
| Others |
Value Chain & Pricing Dynamics
o-Xylene feedstock volatility determines both the premium commanded by integrated producers and the geographic clustering of oxidation-route capacity. This commodity exposure compresses margin predictability for non-integrated buyers while rewarding backward-integrated platforms with pricing power across pharmaceutical and industrial grades.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical-grade procurement, locking in volume commitments from tertiary hospital networks and sterilization service providers. Price differentiation rests on endotoxin certification depth and chromatographic purity documentation, with academic medical centers paying premiums for lot-traceable material. Cost compression in technical-grade batches is intensifying because Shandong province producers are flooding spot markets with legacy oxidation output. Construction sector buyers exhibit highest price sensitivity, while pharmaceutical procurement committees prioritize label breadth over per-unit cost.
Supply Chain Analysis
Export-control regimes on dual-use chemical manufacturing equipment limit technology transfer for continuous flow microreactor platforms, constraining pharmaceutical-grade capacity expansion outside Germany and Switzerland. Geographic supply concentration centers on China, India, and Germany, with Shandong province and Gujarat industrial corridors anchoring technical-grade output. Raw material flows draw from naphthalene derivatives, o-xylene streams, and noble metal catalysts. Single-source vulnerability runs through Chinese intermediate clusters, where legacy batch configurations dominate. Distribution runs through group purchasing organizations consolidating hospital pharmacy contracts and specialty chemical distributors serving coating formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket sterilization service contracts are expanding faster than commodity chemical sales, creating attach-rate opportunities for suppliers bundling reprocessing validation with material supply.
For Market Incumbents: Harden certification depth against glutaraldehyde substitution threats by expanding EPA label claims to cover mycobacteria and spore-forming organisms. Deepen backward integration into o-xylene feedstocks to isolate margin from crude oil volatility. Anchor hospital channel control through integrated service capabilities that bundle chemical supply with reprocessor compatibility testing. For New Entrants and Emerging Players: Build out microreactor platforms targeting pharmaceutical-grade qualification gaps in Brazilian and Indian healthcare networks. Brazil's ANVISA alignment pathway offers the most penetrable regulatory entry point for imported sterilization-grade material. Pursue direct procurement relationships with São Paulo hospital systems piloting centralized sterile processing departments. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform acquirers with gas-chemical integration capabilities. Five-to-ten year viability hinges on REACH substitution mandate compliance and EPA FIFRA registration breadth. Target acquisition archetypes include pharmaceutical-grade batch operators with endotoxin-controlled production and established hospital GPO relationships. Monitor EPA efficacy claim substantiation timelines as the critical inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into o-Xylene Feedstocks | Mitsubishi Gas Chemicals and OCI control oxidation-route economics through captive aromatic supply. |
| Continuous Flow Microreactor Adoption | Swiss and German pharmaceutical-grade producers reduce solvent intensity and improve lot consistency. |
| EPA FIFRA Label Expansion | Advanced Sterilization Products broadens efficacy claims to capture hospital infection control committee consolidation. |
| Brazilian Healthcare Infrastructure Partnerships | ANVISA alignment opens qualification pathways for imported pharmaceutical-grade material in São Paulo networks. |
| Group Purchasing Organization Contract Consolidation | Hospital procurement centralization rewards suppliers with integrated sterilization service capabilities. |
Study Parameters
Initial hypotheses were tested against primary input from sterilization department managers, pharmaceutical procurement leads, coating formulator technical directors, and specialty chemical distribution channel partners and refined through secondary validation against EPA FIFRA registration databases, ECHA REACH authorization filings, customs trade flow records, and SEC 10-K disclosures from integrated chemical platforms. Bottom-up demand modeling triangulated against top-down capacity assessments across oxidation-route production clusters.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling across pharmaceutical grade tier, end-use application, and regional regulatory cluster. CAGRs were derived from installed base growth in automated endoscope reprocessors, REACH substitution mandate compliance timelines, and phthalic anhydride derivative capacity expansion trajectories in Indian chemical corridors.
Practitioners should monitor EPA efficacy claim substantiation delays and o-xylene feedstock price volatility for early signals of competitive repositioning. Forecasts reflect assumptions on regulatory alignment pace and hospital procurement centralization trends. Material shifts in REACH authorization scope or Brazilian ANVISA implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Adipamide Market
Functional Chemicals
Sodium Lauroyl Glutamate Market
Functional Chemicals
L-Alanyl-L-Glutamine Market
Functional Chemicals
Thiamine Market
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
Heptanoic Acid Market
Functional Chemicals
Citrulline Malate Market
Functional Chemicals
Urea Formaldehyde Market
Functional Chemicals
Glutamine Market
Functional Chemicals
Global Functional Fluids Market
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Chlorobutanol Market
Functional Chemicals
Phthalimide Market
Functional Chemicals
Sodium Malate Market