
 Middle East Formaldehyde Market | 2026-2036
Middle East Formaldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Formaldehyde Market Insights
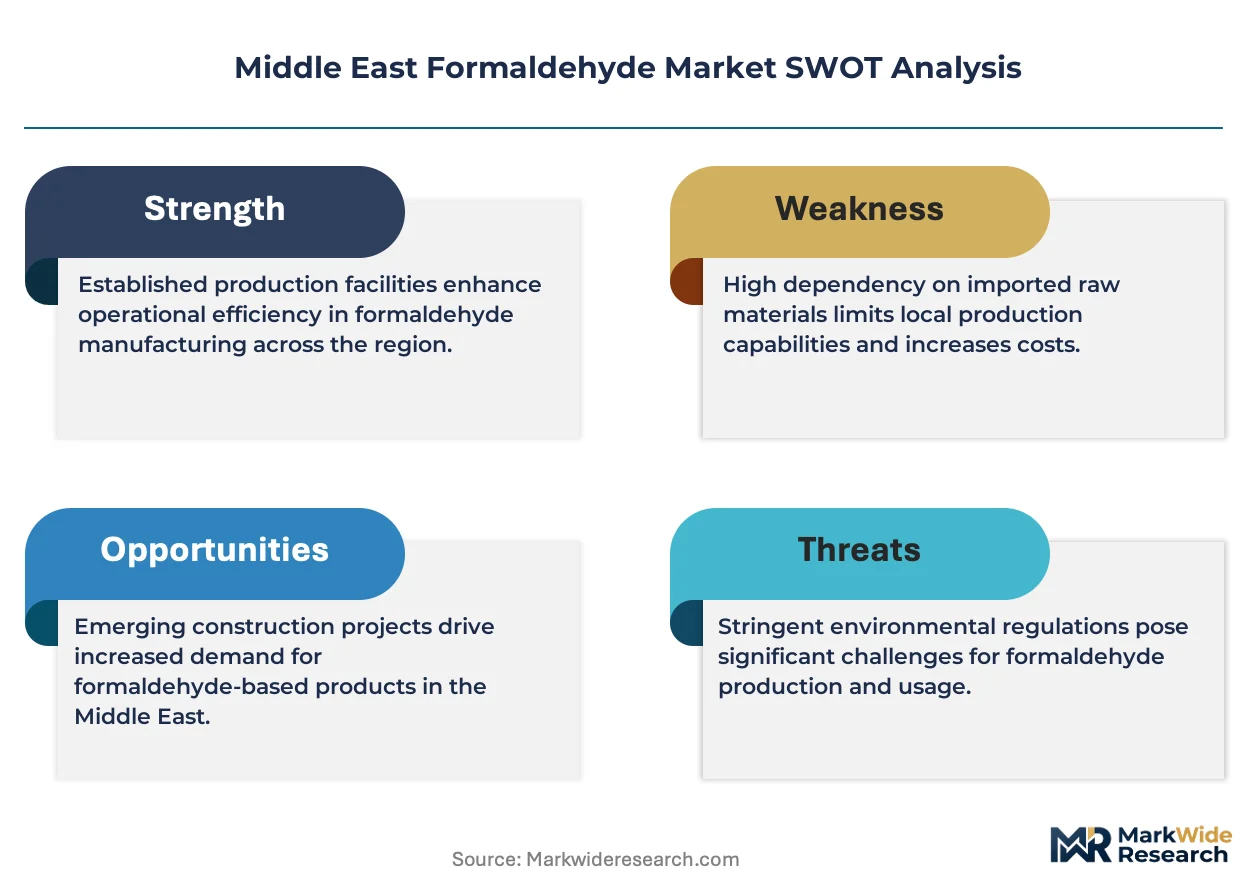
Construction adhesive demand is decoupling from traditional oilfield chemical offtake as the region's petrochemical diversification accelerates. SABIC leverages its integrated methanol-to-formaldehyde feedstock position across Jubail and Yanbu complexes. Chemanol anchors downstream specialty chemical production with captive formaldehyde supply for regional resin makers. Hexion competes through technology leadership in low-emission resin formulations tailored to Gulf Cooperation Council building standards.
Formaldehyde is a reactive aldehyde (CH₂O) produced via silver-catalyzed or metal-oxide-catalyzed oxidation of methanol, with aqueous solutions typically containing 37-55% formaldehyde by weight plus stabilizing methanol; it serves primarily as a chemical building block for thermosetting resins, preservatives, and intermediate synthesis. Urea-formaldehyde dominates volume flows through its entrenched role in particleboard and medium-density fiberboard binders for Saudi Arabia's furniture and fit-out sectors. Phenolic-formaldehyde occupies higher-margin niches in fire-resistant laminates and foundry applications where thermal performance commands price premiums over commodity adhesives.
Saudi Arabia's SFDA enforces residual formaldehyde limits in consumer goods and building materials, while the UAE's MOHAP monitors occupational exposure thresholds in manufacturing facilities; both frameworks push converters toward low-emission resin systems and certified product labeling. The EU Green Deal's carbon border adjustment mechanism and REACH-aligned substance restrictions increasingly shape export-oriented formaldehyde derivative production in Gulf chemical parks. Buyers must track how dual regulatory pressure from Gulf national standards and European import requirements will reshape supplier qualification criteria and capital allocation across the forecast horizon.
Market Dynamics
Formaldehyde demand across the Middle East is pivoting from oilfield chemical offtake toward construction adhesive consumption as Gulf petrochemical diversification accelerates. This structural reorientation concentrates investment in integrated methanol-formaldehyde-resin corridors anchored by Saudi Arabia's Jubail and Yanbu industrial cities.
Growth Catalysts
- UAE MOHAP VOC limits:Stricter emission caps for interior adhesives are forcing converters toward certified low-formaldehyde resin systems, expanding the addressable market for compliant binders.
- Particleboard sector expansion:Saudi furniture manufacturing clusters in the Eastern Province are scaling medium-density fiberboard output, pulling captive formaldehyde supply through dedicated pipeline infrastructure.
- Silver-catalyzed oxidation advances:Process efficiency gains in methanol-to-formaldehyde conversion are lowering unit production costs at integrated Gulf chemical parks.
Market Restraints
- Methanol feedstock volatility:Natural gas price swings in regional supply contracts transmit directly to formaldehyde production economics, compressing margin visibility for non-integrated operators.
- Jubail supply concentration:Over half of regional nameplate capacity sits within a fifty-kilometer radius, creating single-point vulnerability to feedstock disruption or logistics bottlenecks.
- SFDA residual limits:Saudi consumer goods testing protocols for formaldehyde emissions add compliance layers that extend product qualification timelines by four to eight weeks.
Strategic Opportunities
- Oman Sohar corridor development:Greenfield petrochemical zones at Duqm and Sohar offer untapped formaldehyde derivative potential with proximity to Indian Ocean shipping lanes.
- EU Green Deal alignment:Carbon border adjustment preparation is creating first-mover advantage for Gulf producers certifying low-carbon formaldehyde resin exports to European panelboard makers.
- Foundry phenolic niche expansion:Thermal-performance binders for metal casting applications command price premiums and remain underdeveloped relative to commodity urea-formaldehyde saturation.
Industry Challenges
- Process control engineering scarcity:Silver-catalyzed oxidation expertise concentrates among a handful of specialists, constraining operational debottlenecking and technology transfer.
- Dual certification complexity:Simultaneous compliance with Gulf national standards and REACH-aligned European import requirements demands parallel testing protocols that strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Formaldehyde Market |
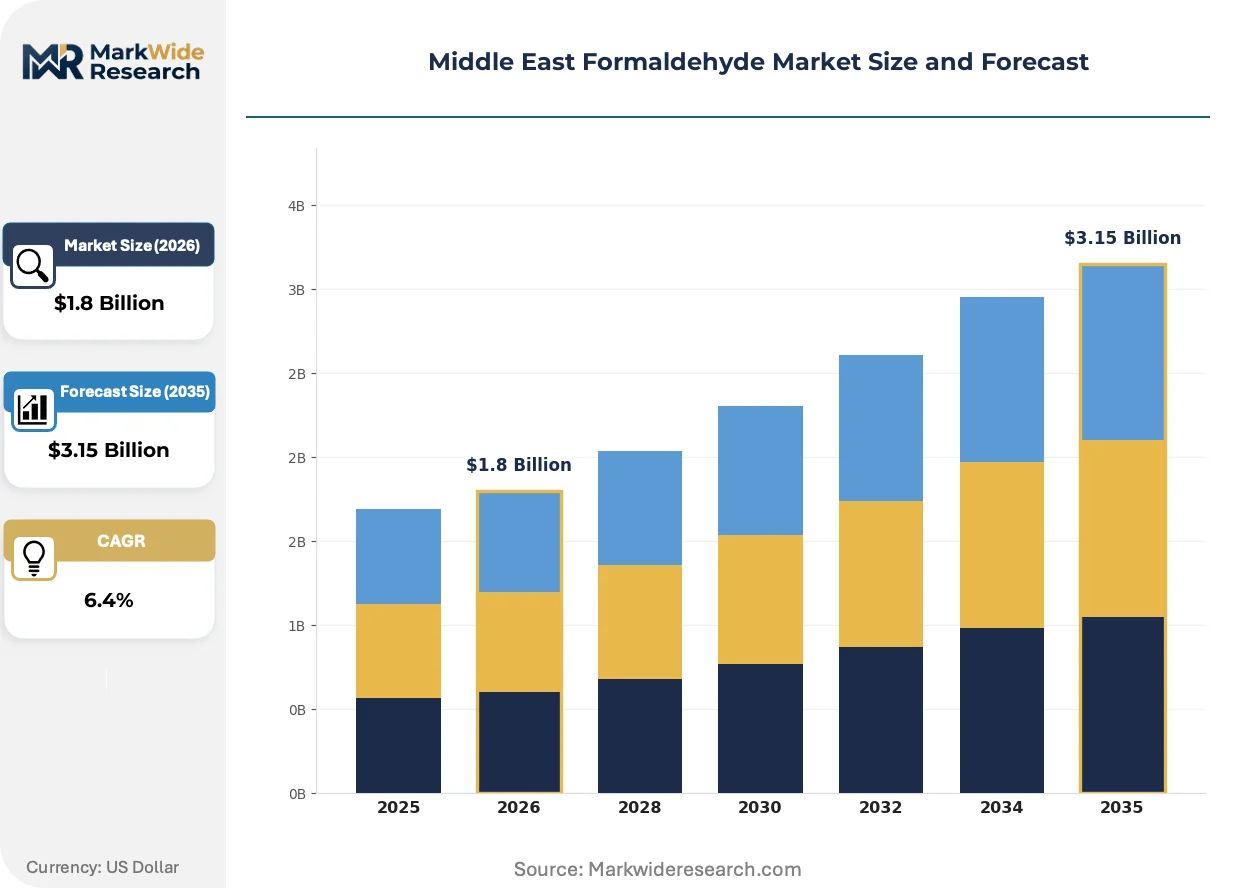
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea-Formaldehyde, Phenolic-Formaldehyde, Melamine-Formaldehyde, Polyoxymethylene End User: Wood Products, Textiles, Pharmaceuticals, Coatings Application: Adhesives, Resin Production, Chemical Intermediates, Foam Insulation Form: Liquid, Gas, Powder, Granules |
| Companies Covered | SABIC, BASF SE, Hexion, Perstorp, Dubichem, Chemanol, Dynea, Celanese Corporation, Al-Ahram Chemicals, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Formaldehyde Market Trends and Innovations
Low-emission resin chemistry and digital process control are converging to redefine formaldehyde value capture in Middle Eastern chemical parks. These shifts favor integrated producers with captive methanol supply and in-house formulation capabilities.
Silver-catalyzed oxidation with enhanced heat recovery is rewriting formaldehyde production economics at Gulf integrated sites. SABIC and regional chemical park operators are retrofitting existing methanol units with advanced catalytic systems that boost selectivity above ninety-four percent. This technology compression is enabling smaller-scale competitive entry that previously required metal-oxide process scale to achieve viable unit costs.
EU Green Deal carbon border adjustment mechanisms are reshaping export-oriented resin production qualification across Saudi and UAE chemical zones. Gulf producers serving European panelboard customers must now document embedded carbon intensity through certified supply chain audits. This regulatory friction is accelerating capital allocation toward combined heat and power integration and carbon capture feasibility studies at Yanbu and Jubail complexes.
Buyer concentration among Saudi furniture manufacturing groups is compressing procurement cycles and unbundling technical service from resin supply contracts. Large Eastern Province panelboard makers now demand dedicated formulation support and just-in-time delivery guarantees as table stakes. This purchasing pattern shift is most visible in Riyadh and Jeddah fit-out sectors where project-scale adhesive offtake dominates annual contracting.
Middle East Formaldehyde Market Segmentation
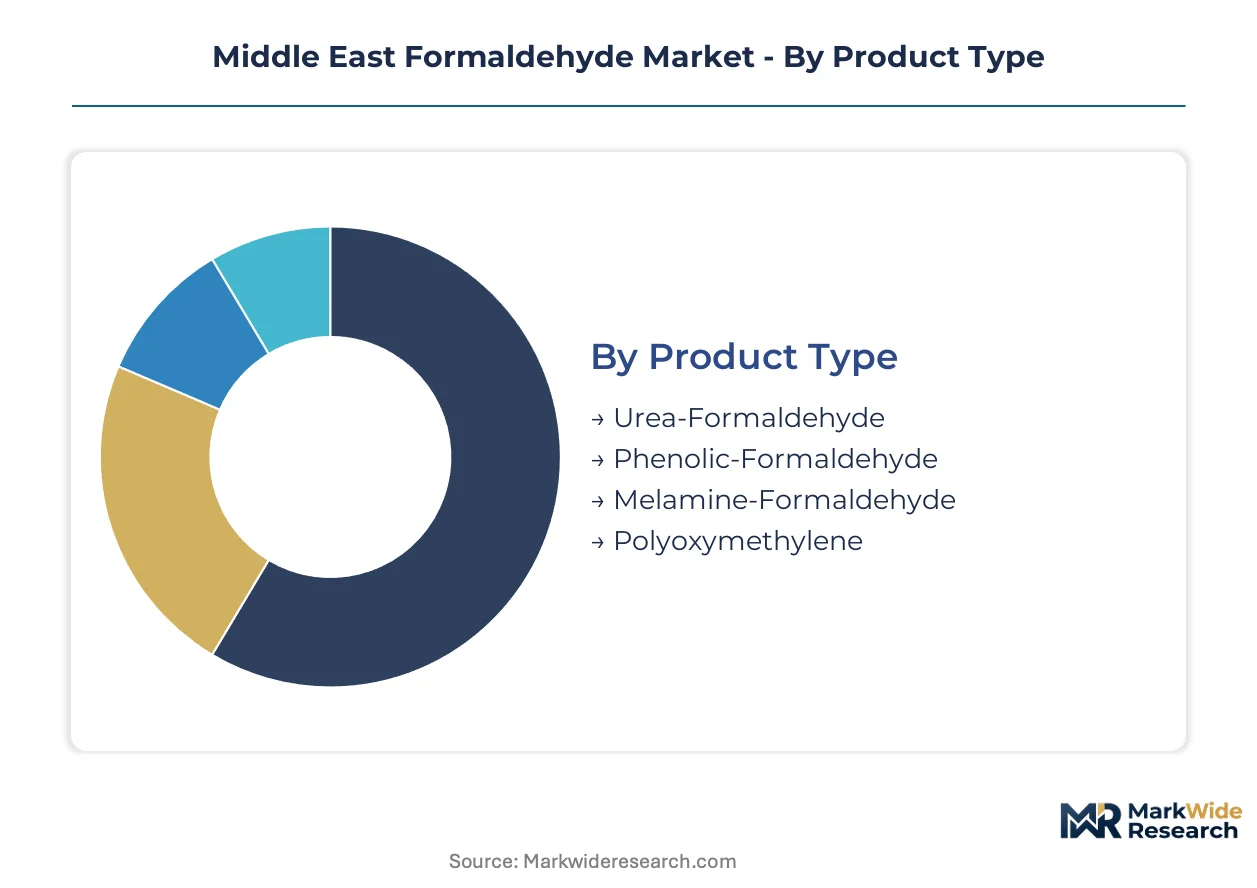
Formaldehyde value capture across the Middle East diverges sharply by derivative chemistry and end-use specification. Upgrade cycles in resin formulations and tightening emission standards are resegmenting procurement patterns among Saudi and UAE manufacturing clusters.
Product Type:
Replacement cycles favor lower-emission resin systems as SFDA and MOHAP protocols tighten across Gulf chemical parks.
- Urea-Formaldehyde:Aqueous thermosetting resin formed from urea and formaldehyde condensation, typically 60% solids content for particleboard binders. Saudi Arabia's Eastern Province furniture clusters consume the bulk of regional volume through dedicated pipeline supply from Jubail methanol-formaldehyde corridors. The segment faces pressure from stricter indoor air quality testing protocols.
- Phenolic-Formaldehyde:Cross-linked polymer with superior thermal stability and moisture resistance, synthesized via acid or base-catalyzed condensation. Demand concentrates in fire-resistant laminates and foundry binders across Yanbu industrial complexes, where thermal performance specifications command formulation premiums over commodity alternatives.
- Melamine-Formaldehyde:Highly durable thermoset with excellent surface hardness, cross-linked through methylolation chemistry. Decorative laminate producers in UAE fit-out sectors specify this chemistry for high-wear interior applications.
- Polyoxymethylene:Engineering thermoplastic derived from formaldehyde polymerization, offering dimensional stability and low friction. Regional automotive component molding represents the primary offtake channel.
Volume placements concentrate in Urea-Formaldehyde; the faster expansion belongs to Phenolic-Formaldehyde.
End User:
Cost-tier segmentation separates commodity panelboard makers from specialty pharmaceutical and coating formulators.
- Wood Products:Particleboard, medium-density fiberboard, and plywood manufacturers binding wood fibers with thermosetting resins. Saudi furniture manufacturing clusters in Riyadh and Jeddah drive captive formaldehyde consumption through vertically integrated supply chains.
- Textiles:Permanent-press fabric finishing and wrinkle-resistant treatment applications. UAE garment finishing houses represent the regional demand center for textile-grade formaldehyde derivatives.
- Pharmaceuticals:Vaccine preservation and disinfectant synthesis requiring high-purity formaldehyde grades. Saudi Arabia's SFDA enforces residual limit testing that extends qualification timelines for imported active pharmaceutical ingredients.
- Coatings:Industrial paint and varnish formulations leveraging formaldehyde as a cross-linking agent. Marine and protective coating producers in UAE and Oman specify low-VOC resin systems for export compliance.
Procurement scale favors Wood Products; margin capture concentrates in Pharmaceuticals.
Application:
Application mix tracks construction activity intensity versus specialty chemical diversification across Gulf industrial zones.
- Adhesives:Structural and decorative bonding systems for panelboard lamination, furniture assembly, and construction substrates. UAE MOHAP VOC limits are forcing converters toward certified low-emission formulations for interior fit-out projects.
- Resin Production:Intermediate synthesis of urea-formaldehyde, phenolic, and melamine resins for downstream formulation. Jubail's integrated methanol-to-resin corridors anchor regional capacity with pipeline delivery to Eastern Province converters.
- Chemical Intermediates:Building-block synthesis for pentaerythritol, methylene diphenyl diisocyanate, and hexamethylenetetramine. Chemanol and SABIC downstream units consume captive formaldehyde for regional specialty chemical output.
- Foam Insulation:Phenolic foam production for thermal insulation in building and industrial applications. Saudi construction codes are expanding specification of fire-resistant insulation materials in high-rise developments.
Adhesives dominate absolute tonnage; Chemical Intermediates show the steepest expansion trajectory.
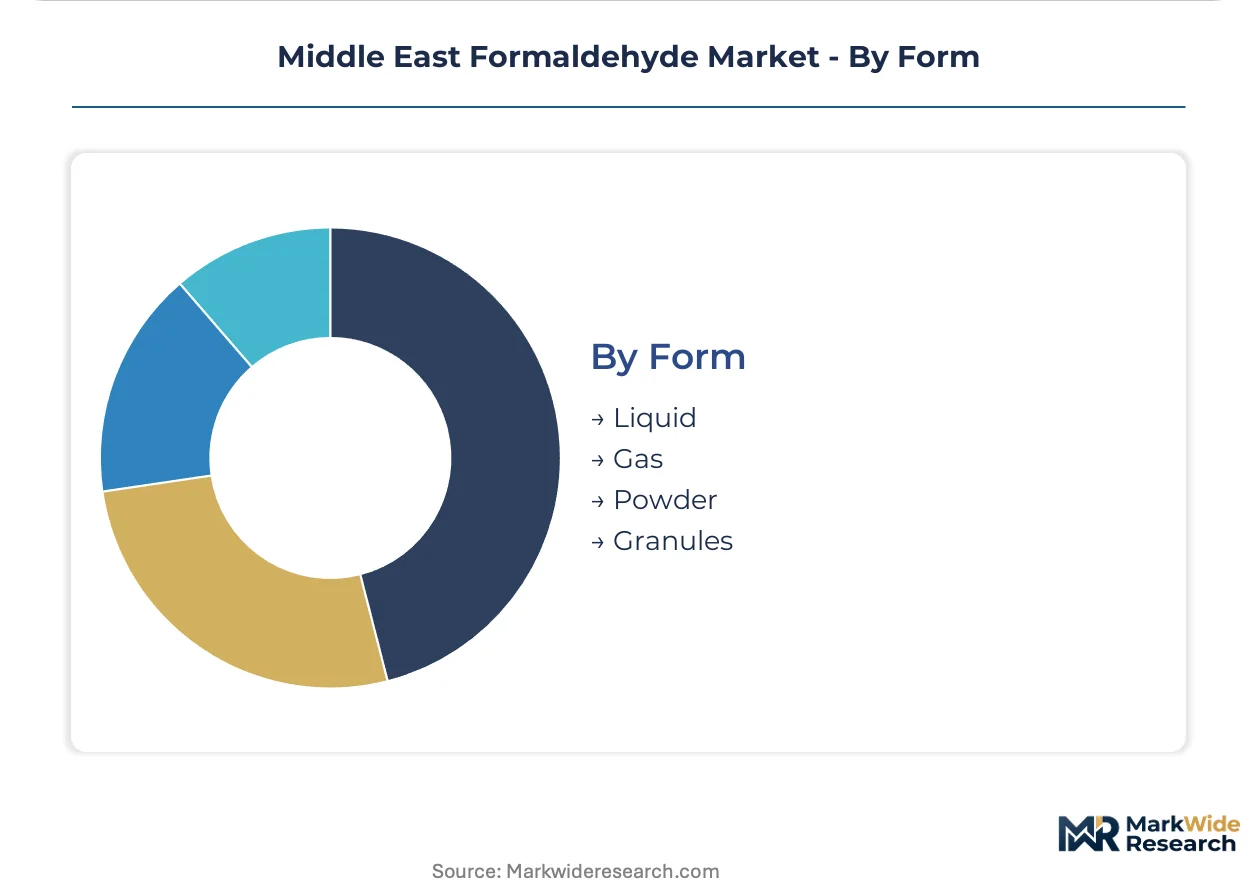
Form:
Physical form selection depends on transportation economics and downstream process integration.
- Liquid:Aqueous formaldehyde solutions at 37-55% concentration with methanol stabilizer, the standard delivery format for regional resin producers. Pipeline and tanker supply dominates Jubail-to-Eastern Province corridors.
- Gas:Anhydrous formaldehyde vapor for direct chemical synthesis and specialized polymerization. Limited regional demand concentrates in pharmaceutical and fine chemical synthesis.
- Powder:Paraformaldehyde solid with 91-93% formaldehyde content, enabling reduced transportation costs for remote formulation sites. Omani and UAE converters without pipeline access specify powder for inventory efficiency.
- Granules:Solid formaldehyde derivatives in controlled-release formats for agricultural and specialized industrial applications. Minimal regional penetration relative to liquid and powder alternatives.
Liquid form commands infrastructure advantage; Powder is gaining share fastest among non-integrated converters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City anchors regional formaldehyde capacity through integrated methanol-formaldehyde corridors, while petrochemical diversification incentives concentrate investment across Saudi Arabia's Eastern Province.
Saudi Arabia
Saudi furniture manufacturing clusters in Riyadh and Jeddah drive particleboard resin consumption through dedicated pipeline supply. The SFDA enforces residual formaldehyde limits in consumer goods, extending product qualification timelines. Yanbu and Jubail industrial complexes host integrated methanol-to-formaldehyde production with downstream captive resin synthesis.
United Arab Emirates
UAE construction codes mandate stricter volatile organic compound limits for interior adhesives, forcing converters toward certified low-emission systems. MOHAP monitors occupational exposure thresholds in manufacturing facilities. Dubai and Abu Dhabi fit-out sectors concentrate demand for decorative laminate applications with just-in-time delivery requirements.
Oman
Omani converters without pipeline access specify paraformaldehyde powder for inventory efficiency at remote formulation sites. The country's national chemical regulator aligns with Gulf standardization protocols for building material emissions. Sohar and Duqm petrochemical zones offer greenfield formaldehyde derivative potential with Indian Ocean shipping access.
Qatar
Qatar's construction sector pulls adhesive imports through regional supply chains rather than domestic production. The country's national standards body participates in Gulf Cooperation Council harmonization for interior air quality testing. Industrial zones near Doha concentrate downstream formulation for marine and protective coatings.
Middle East Formaldehyde Market Competitive Landscape
Top-tier vendors anchor integrated petrochemical corridors, while regional specialists and international traders occupy service and formulation niches. The market structure reflects concentration around methanol-formaldehyde-resin verticals in Saudi industrial cities. Three archetypes dominate: state-affiliated petrochemical majors with captive feedstock, European resin technology licensors, and regional distributors with blending capabilities. Capacity expansion and low-emission formulation licensing represent the dominant competitive vectors.
Within the integrated producer tier, SABIC and Chemanol anchor methanol-formaldehyde production across Jubail and Yanbu complexes. BASF SE and Hexion occupy positions as technology-focused resin specialists serving Gulf panelboard and laminate manufacturers. These named entities exemplify the bifurcation between feedstock-integrated Gulf operators and formulation-technology leaders from European chemical markets.
| Leading Market Players |
|---|
| SABIC |
| BASF SE |
| Hexion |
| Perstorp |
| Dubichem |
| Chemanol |
| Dynea |
| Celanese Corporation |
| Al-Ahram Chemicals |
| Others |
Pricing and Supply Chain Analysis
UAE MOHAP VOC limits for interior adhesives are compressing procurement cycles and forcing just-in-time delivery guarantees from formaldehyde resin suppliers, which concentrates pricing power among integrated Jubail producers with captive methanol supply and pipeline infrastructure to Eastern Province converters.
Pricing Analysis
Short lead-time premiums dominate formaldehyde resin contracting as Saudi furniture manufacturers demand certified low-emission formulations within compressed project timelines. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from methanol feedstock volatility in regional natural gas contracts, compressing margins for non-integrated operators. Small-scale Omani and UAE converters without pipeline access exhibit highest price sensitivity due to powder transportation cost premiums.
Supply Chain Analysis
Formaldehyde supply rests on Saudi methanol production anchored at Jubail and Yanbu industrial complexes, with secondary sourcing from UAE chemical zones and Omani greenfield developments. Silver catalysts, aqueous methanol feedstock, and specialized oxidation reactor vessels constitute critical input dependencies. Single-source vulnerability concentrates in the fifty-kilometer Jubail radius where over half of regional capacity operates. Distribution runs through dedicated pipeline corridors to Eastern Province panelboard clusters, supplemented by tanker and bulk powder shipments to remote formulation sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formaldehyde resin supply concentrates in integrated Saudi petrochemical corridors, where Jubail capacity bottlenecks prop pricing and create defensive moats for incumbent producers with captive methanol positions.
For Market Incumbents: Hedge methanol feedstock exposure through long-term natural gas supply contracts and carbon capture feasibility investments at Yanbu complexes. SABIC and Chemanol should accelerate low-emission resin certification to defend against European carbon border adjustment friction. Backward integration into specialty chemical intermediates captures margin expansion from pharmaceutical and coating formulators. For New Entrants and Emerging Players: Digital channel routes through e-procurement platforms serving mid-size UAE fit-out contractors offer white-space penetration without pipeline infrastructure requirements. Target Omani converters at Sohar and Duqm with paraformaldehyde powder formulations for inventory efficiency. Foundry phenolic binders for metal casting applications present underdeveloped premium niches relative to saturated urea-formaldehyde commodity supply. For Investors and Strategic Acquirers: The window for entry favors technology-licensed resin specialists with EU Green Deal alignment capabilities and Gulf regulatory certification expertise. Long-term viability centers on carbon-intensity documentation and combined heat and power integration at integrated chemical parks. Watch EU carbon border adjustment implementation timelines as inflection indicator for Gulf export-oriented capacity valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | SABIC's methanol-formaldehyde-resin verticals capture margin from feedstock through formulation at Jubail. |
| Green Manufacturing Transition | Carbon capture feasibility studies at Yanbu align Gulf production with EU Green Deal import requirements. |
| Long-term Supply Agreement | Dedicated pipeline contracts between Jubail producers and Eastern Province furniture clusters reduce price volatility exposure. |
| Joint Venture | Oman Sohar corridor partnerships with Indian Ocean shipping access diversify regional supply concentration risk. |
| Capacity Expansion | Silver-catalyzed oxidation retrofits boost selectivity above ninety-four percent at existing methanol units. |
Research Methodology
Trade databases, chemical industry association filings, and Gulf petrochemical park disclosure documents formed the secondary backbone of this analysis. Primary interviews with plant managers at Saudi and UAE formaldehyde production facilities, procurement leads at Eastern Province panelboard manufacturers, distribution channel partners serving Omani converters, and technical R&D directors at resin formulation houses were combined with secondary validation. Bottom-up capacity modeling and top-down demand estimation were triangulated across segmentation dimensions.
Historical trendline analysis of methanol-formaldehyde production economics and resin consumption patterns informed the projection framework across the analysis window. Segmentation modeling incorporated product type chemistry tiers, end-use industry specifications, physical form delivery requirements, and regional production hub configurations. CAGRs were derived from regression analysis of capacity utilization rates and downstream derivative demand trajectories. Silver-catalyzed oxidation efficiency gains and EU regulatory alignment timelines served as industry-specific forecast inputs.
The model holds under stable natural gas supply contracts and continued Gulf petrochemical diversification incentives; deviation in methanol feedstock volatility or EU carbon border adjustment acceleration would shift capacity investment trajectories. Forecasts reflect assumptions about regulatory harmonization across GCC markets and pipeline infrastructure completion schedules. A small set of named triggers—EU Green Deal implementation pace, SFDA emission limit tightening, and Jubail logistics bottlenecks—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Lithium Nitrate Market
Bulk Chemicals
Stilbene Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Sodium Perborate Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Global Nitrite Market
Bulk Chemicals
Sulfur Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Mexico Calcium Carbonate Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Vinyl Cyclohexane Market
Bulk Chemicals
Trimellitic Anhydride Market