
 Succinic Acid Market | 2026-2036
Succinic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Succinic Acid Market Analysis
The EU Green Deal is broadening the addressable market for low-carbon intermediates across European chemical value chains. BASF SE leverages its integrated Verbund production architecture to secure feedstock flexibility for bio-based output. Roquette Frères anchors its position through deep carbohydrate fermentation expertise and plant-derived feedstock partnerships. Mitsubishi Chemical Corporation dominates Asian supply corridors with dedicated biorefinery investments in Japan.
Succinic acid is a four-carbon dicarboxylic acid with molecular formula C4H6O4, produced through petrochemical oxidation of n-butane or anaerobic fermentation of renewable sugars, serving primarily as a platform chemical for polyesters, polyurethanes, and pharmaceutical intermediates. Petrochemical-based succinic acid still occupies the largest volume share due to established cost structures, though bio-based succinic acid is displacing conventional routes as carbon accounting becomes embedded in procurement contracts. The Food & Beverage end user segment sustains premium pricing through GRAS-certified supply chains, while Personal Care buyers navigate reformulation timelines tied to EU REACH substance evaluations.
EPA biofuel mandates and EU REACH substance restrictions are tightening purity specifications for succinic acid entering North American and European downstream channels. Japan's METI has issued bioplastics commercialization roadmaps that directly reference bio-based succinic acid as a priority feedstock, while China's MEE enforces dual carbon goals that penalize petrochemical pathway emissions in coastal chemical parks. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost competitiveness of regional production clusters before committing to capacity expansions.
Market Dynamics
The EU Green Deal's carbon intensity benchmarks are compressing petrochemical pathway margins while bio-based fermentation capacity scales across three continents. Buyers now embed carbon accounting into procurement contracts, forcing supply chain reconfiguration before 2030 compliance deadlines.
Growth Catalysts
- EU Green Deal packaging mandates:Germany's bioplastics manufacturers are accelerating bio-based succinic acid purchases to meet tightening carbon benchmarks for food-contact materials.
- Japan METI bioplastics commercialization roadmaps:Direct policy prioritization of bio-based succinic acid as feedstock is unlocking dedicated biorefinery investments in Japanese chemical corridors.
- China MEE dual carbon enforcement:Coastal chemical parks now face emissions penalties that disadvantage petrochemical oxidation routes against anaerobic fermentation alternatives.
Market Restraints
- Feedstock cost volatility:Renewable sugar prices fluctuate with agricultural commodity cycles, compressing fermentation economics against n-butane-derived supply.
- Purification infrastructure concentration:High-purity succinic acid processing clusters in Germany and Japan create single-point vulnerability for pharmaceutical-grade supply.
- EU REACH substance evaluation timelines:Extended reformulation windows for Personal Care buyers delay volume commitments to bio-based alternatives.
Strategic Opportunities
- India PLI scheme for bioplastics:Production-linked incentives for bio-based chemicals offer first-mover advantages in underdeveloped South Asian fermentation capacity.
- Pharmaceutical intermediate applications:GRAS-certified supply chains for Food & Beverage are creating certification spillover demand in drug synthesis pathways.
- Carbon border adjustment arbitrage:Early positioning in low-carbon production clusters before EU CBAM full implementation secures preferential market access.
Industry Challenges
- Fermentation scale-up engineering talent:Industrial microbiology and bioprocess optimization expertise remains concentrated in European and Japanese research institutions.
- Biorefinery capex intensity:Anaerobic fermentation facilities require specialized stainless steel reactors and contamination control systems that extend payback periods.
- ISO 17025 certification timelines:Third-party laboratory accreditation for purity testing creates six-to-twelve month delays for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Succinic Acid Market |
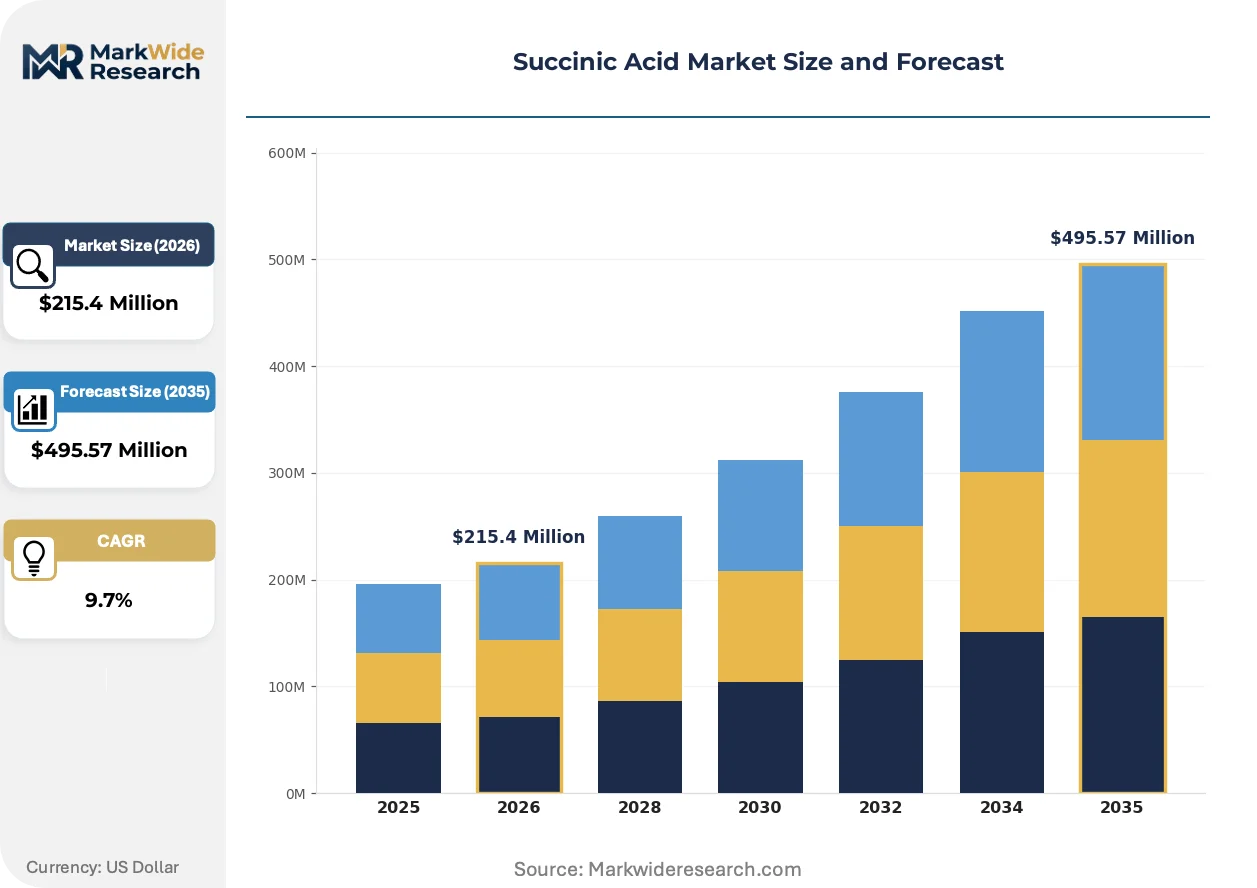
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $495.57 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-based Succinic Acid, Petrochemical-based Succinic Acid, Succinic Anhydride, Succinic Acid Salts Application: Solvents, Plasticizers, Food Additives, Cosmetics End User: Chemicals, Pharmaceuticals, Food & Beverage, Personal Care Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores |
| Companies Covered | BASF SE, Roquette Frères, Mitsubishi Chemical Corporation, Corbion N.V., Nippon Shokubai Co., Ltd., Air Water Inc., DSM-Firmenich, PTT Global Chemical Public Company Limited, Succinity GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Succinic Acid Market Emerging Trajectories
Continuous fermentation technology is collapsing batch cycle times while integrated biorefinery designs merge carbohydrate processing with downstream derivative synthesis. These shifts are compressing the cost gap between petrochemical and bio-based production economics.
Continuous fermentation systems using immobilized cell bioreactors are decentralizing production economics away from massive centralized petrochemical complexes. Specialty chemical buyers in the Asia-Pacific manufacturing belt are adopting these systems to reduce logistics exposure and secure just-in-time supply. The technology is decentralizing capital deployment patterns, enabling mid-scale facilities closer to agricultural feedstock sources.
EU REACH substance restrictions are tightening purity specifications for succinic acid entering European downstream channels. The regulation forces North American exporters to upgrade analytical testing protocols and documentation standards. Food & Beverage end users face the steepest compliance burden as GRAS certification requires contaminant thresholds below pharmaceutical-grade specifications.
Long-term offtake agreements are replacing spot market purchases as buyers seek supply security amid feedstock volatility. Polyurethane manufacturers are locking in five-to-seven year contracts directly with fermentation operators, bypassing traditional chemical distributors. This pattern is most pronounced in Germany where automotive sector demand for bio-based polyols concentrates purchasing power among three major compounders.
Succinic Acid Market Segmentation
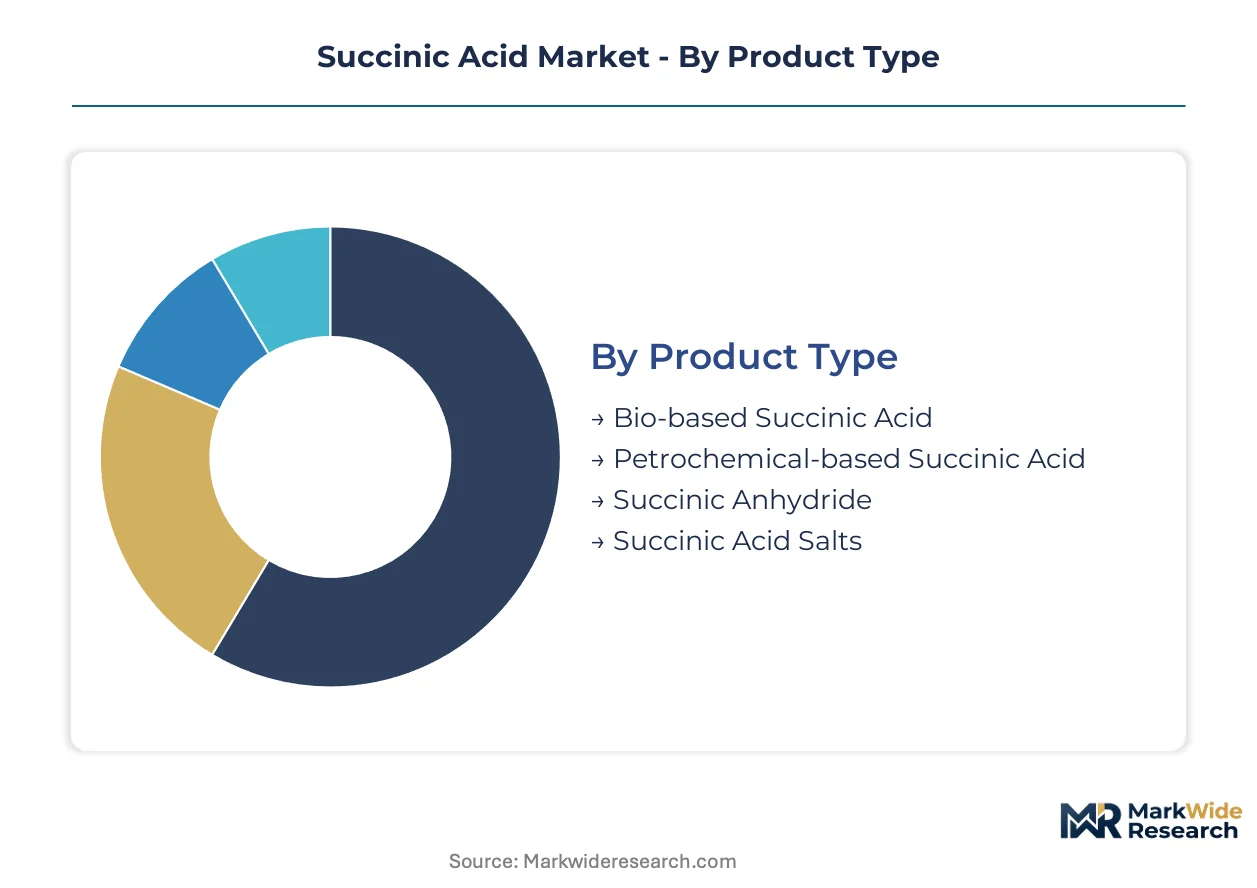
Succinic acid market segmentation reveals how production pathway choices and purity grades determine access to premium pricing tiers. Buyers sort supply pools by carbon intensity credentials and certification status rather than commodity specifications alone.
Product Type:
Supply concentration clusters around fermentation-derived output as EU carbon accounting rules harden procurement requirements.
- Bio-based Succinic Acid:Produced through anaerobic fermentation of renewable sugars using engineered bacterial strains. German bioplastics manufacturers and Japanese polyurethane compounders now specify this grade exclusively for automotive and packaging applications under tightening EU Green Deal benchmarks.
- Petrochemical-based Succinic Acid:Manufactured via catalytic oxidation of n-butane in integrated refinery complexes. Coastal chemical parks in China face MEE emissions penalties that erode cost advantages against fermentation alternatives.
- Succinic Anhydride:Dehydrated derivative serving pharmaceutical synthesis and specialty polyester production.
- Succinic Acid Salts:Neutralized forms including sodium and potassium variants for food buffering and pharmaceutical formulations.
Today's leader: Bio-based Succinic Acid. Tomorrow's challenger: Succinic Anhydride.
Application:
Cost tier stratification separates commodity solvent demand from premium food-grade and cosmetic-grade supply chains.
- Solvents:Polar aprotic solvent applications in coatings and resins. Chemical manufacturers in Asia-Pacific manufacturing belts favor bio-based grades for green chemistry compliance.
- Plasticizers:Ester derivatives soften PVC and biopolymer formulations. Automotive interior specifications now mandate bio-based content thresholds.
- Food Additives:GRAS-certified supply chains command contamination thresholds below pharmaceutical specifications. EU EFSA evaluations and FDA compliance documentation create multi-month qualification timelines.
- Cosmetics:Buffering agent and pH adjuster in skincare formulations. EU REACH substance restrictions force reformulation commitments that delay volume scaling.
Volume concentrates in Solvents. Margin expansion concentrates in Food Additives.
End User:
Customer type determines specification stringency, with pharmaceutical and food buyers imposing purity requirements that exclude general chemical grades.
- Chemicals:Platform chemical demand for polyesters, polyurethanes, and alkyd resins. BASF SE and Mitsubishi Chemical Corporation integrate captive succinic acid for downstream derivative production.
- Pharmaceuticals:Active pharmaceutical ingredient intermediate and excipient applications. ISO 17025 certification and FDA DMF filing requirements filter supplier pools.
- Food & Beverage:Acidulant, flavor enhancer, and pH control agent. GRAS self-affirmation and FSSAI registration in India create parallel compliance tracks.
- Personal Care:Cosmetic-grade specifications under EU REACH and MoCRA in the US. Extended reformulation windows delay bio-based substitution commitments.
Pharmaceuticals anchors premium pricing. Personal Care shows steepest expansion trajectory as clean beauty mandates harden.
Distribution Channel:
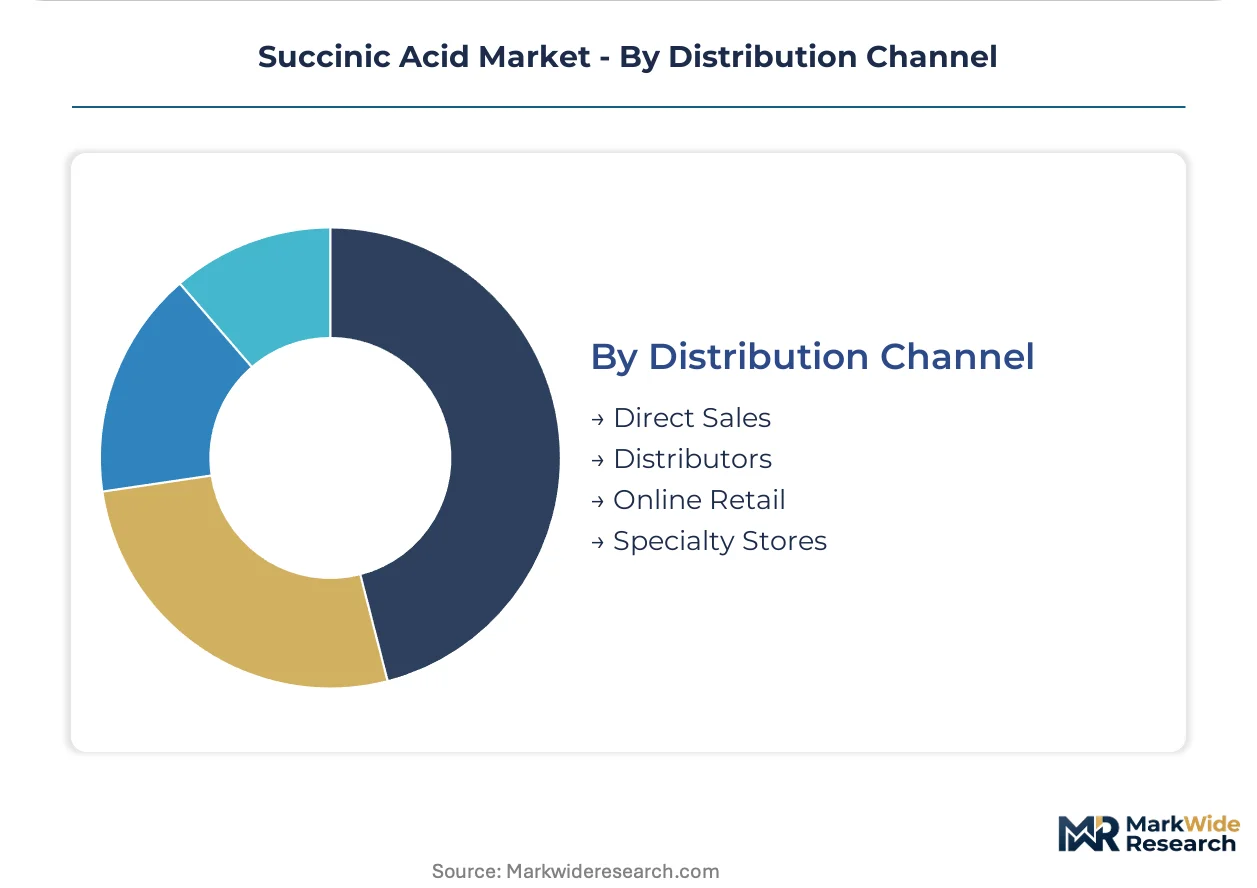
Geography of demand shapes channel selection, with concentrated manufacturing clusters favoring direct procurement over distributor intermediation.
- Direct Sales:Long-term offtake agreements between fermentation operators and polyurethane manufacturers. German automotive compounders lock in five-to-seven year contracts bypassing traditional distributors.
- Distributors:Regional chemical distributors serve fragmented specialty chemical buyers. Inventory pooling reduces working capital burdens for mid-scale processors.
- Online Retail:E-procurement platforms for laboratory-scale and research quantities. Academic and startup biotech customers favor digital channels for transparent pricing.
- Specialty Stores:Niche channels for food-grade and cosmetic-grade certified supply. Direct-to-formulator relationships in personal care verticals.
Direct Sales commands volume share. Online Retail gains fastest as digital procurement penetrates mid-tier chemical buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Succinic acid production originated in German chemical corridors during the early commercialization of petrochemical oxidation routes. The industry's geographic footprint now spans fermentation clusters in three continents as bio-based pathways displace conventional manufacturing.
Germany
Automotive polyurethane demand and bioplastics packaging specifications drive consumption in the Rhine-Ruhr industrial belt. The EU Green Deal's carbon intensity benchmarks for food-contact materials force compounders to source fermentation-derived grades exclusively. BASF SE operates integrated Verbund production at Ludwigshafen, securing captive succinic acid for downstream polyol synthesis.
China
Coastal chemical parks in Jiangsu and Zhejiang provinces face MEE dual carbon enforcement that penalizes n-butane oxidation emissions. Domestic polyurethane manufacturers are locking in long-term offtake agreements with fermentation operators to avoid carbon accounting penalties. The Yangtze River Delta concentrates specialty chemical demand from electronics and automotive coating sectors.
Japan
METI bioplastics commercialization roadmaps prioritize bio-based succinic acid as a strategic feedstock for domestic material security. Mitsubishi Chemical Corporation anchors supply through dedicated biorefinery investments in the Chubu region. Pharmaceutical-grade specifications from Tokyo-area drug manufacturers sustain premium pricing tiers for high-purity fermentation output.
United States
EPA biofuel mandates and state-level clean chemistry procurement rules reshape Midwest chemical manufacturing. The Ohio River Valley's historical petrochemical infrastructure competes with emerging fermentation capacity in agricultural states. Food & Beverage processors in California and Illinois impose GRAS certification requirements that filter supplier pools to ISO-accredited operators.
India
PLI scheme production-linked incentives for bio-based chemicals attract first-mover fermentation investments in Gujarat and Maharashtra. FSSAI registration requirements for food-grade acidulants create parallel compliance tracks alongside EU export standards. Specialty chemical demand from Mumbai-Pune industrial corridors concentrates purchasing power among mid-scale polyurethane processors.
Succinic Acid Market Vendor Landscape
Capital-heavy integrated chemical producers compete with asset-light fermentation specialists for differentiated supply contracts. The vendor base stratifies across three tiers: multinational conglomerates with captive petrochemical oxidation capacity, dedicated bio-based platform chemical operators, and regional distributors serving fragmented specialty buyers. Consolidation pressure intensifies as automotive and packaging end users consolidate purchasing power through direct procurement agreements. Dominant competitive moves include backward integration into agricultural feedstock partnerships and technology licensing for continuous fermentation scale-up.
Among European-based chemical conglomerates, BASF SE and Roquette Frères occupy positions at opposite ends of the production spectrum. BASF SE exemplifies integrated petrochemical-to-specialty manufacturing with Verbund architecture flexibility, while Roquette Frères represents carbohydrate fermentation expertise rooted in plant-derived feedstock partnerships. Mitsubishi Chemical Corporation anchors Asian supply corridors through biorefinery investments that exemplify national industrial policy alignment. These three entities represent distinct strategic archetypes: petrochemical integration, agricultural biotechnology specialization, and state-supported biorefinery development.
| Leading Market Players |
|---|
| BASF SE |
| Roquette Frères |
| Mitsubishi Chemical Corporation |
| Corbion N.V. |
| Nippon Shokubai Co., Ltd. |
| Air Water Inc. |
| DSM-Firmenich |
| PTT Global Chemical Public Company Limited |
| Succinity GmbH |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade purity premiums versus commodity solvent grades split the succinic acid market into divergent value capture zones, with GRAS certification and ISO 17025 accreditation functioning as pricing gatekeepers that simultaneously concentrate supply chain control among accredited German and Japanese fermentation clusters.
Pricing Analysis
Contract-based long-term offtake agreements dominate volume transactions, replacing spot market exposure as polyurethane manufacturers seek supply security. Price differentiation rests on carbon intensity certification and FDA DMF filing status, with pharmaceutical buyers absorbing premiums while coating solvent purchasers drive cost compression. Margins are tightening in petrochemical-derived grades as China's MEE emissions penalties erode n-butane oxidation economics. Food & Beverage processors show least price sensitivity due to GRAS compliance barriers; commodity chemical buyers exhibit highest elasticity.
Supply Chain Analysis
EU Green Deal domestic-content benchmarks for food-contact materials are redirecting procurement toward European fermentation capacity. Supply concentrates in Germany, Japan, and coastal China, with high-purity processing clusters creating single-point vulnerability for pharmaceutical-grade output. Feedstock dependencies center on corn-derived glucose, sugarcane sucrose, and lignocellulosic biomass. Tariff exposure looms as EU CBAM implementation approaches. Distribution runs through direct sales channels for automotive compounders, with regional distributors serving fragmented specialty buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The succinic acid market functions as a geographic-arbitrage play where EU carbon border adjustments widen cost differentials against Chinese petrochemical production, rewarding early positioning in low-carbon fermentation clusters.
For Market Incumbents: Anchor carbon-negative positioning through backward integration into agricultural feedstock partnerships in corn-belt states and Brazilian sugarcane regions. Defend against emerging continuous fermentation specialists by securing exclusive offtake with German automotive compounders before 2030 compliance deadlines. Prioritize ISO 17025 laboratory accreditation investments to maintain pharmaceutical-grade supply access.
For New Entrants and Emerging Players: Enter via India's PLI scheme production-linked incentives for bio-based chemicals, targeting underdeveloped South Asian fermentation capacity with first-mover advantages. White-space concentrates in pharmaceutical intermediate applications where GRAS certification spillover creates certification arbitrage. Pursue joint development agreements with Mumbai-Pune polyurethane processors seeking supply diversification.
For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation scale-up engineering talent concentrates in European and Japanese research institutions, fragmenting technical capability across sub-scale operators. Five-to-ten year viability favors asset-light continuous fermentation technology licensors over capital-heavy fixed-reactor installations. Target acquisition archetype: mid-scale Indian or Southeast Asian fermentation operators with FSSAI registration and EU export pathway development. Signal to watch: EU CBAM tariff schedule publication triggering contract renegotiation waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Partnerships | Roquette Frères leverages plant-derived carbohydrate sourcing to secure fermentation economics against agricultural commodity cycles. |
| Continuous Fermentation Technology Licensing | Immobilized cell bioreactor deployments decentralize production capital toward mid-scale facilities closer to agricultural inputs. |
| Long-term Supply Agreement with Automotive Compounders | German polyurethane manufacturers lock in five-to-seven year contracts bypassing traditional chemical distributors. |
| Green Manufacturing Transition | EU Green Deal carbon intensity benchmarks force bioplastics packaging manufacturers to specify fermentation-derived grades exclusively. |
| Joint Venture with Regional Biorefinery Operators | Mitsubishi Chemical Corporation anchors Asian supply corridors through METI-aligned investments in Japanese chemical corridors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, polyurethane procurement leads at automotive OEMs, chemical distribution channel partners, and technical R&D directors at bioplastics manufacturers. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA biofuel mandate documentation. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across production pathways.
Segment-weighting approaches modeled bio-based versus petrochemical production routes, purity grades from technical to pharmaceutical, end-use industries spanning automotive, packaging, food, and pharmaceuticals, and regional production hub clusters. CAGRs were derived through growth driver elasticity modeling and substitution rate analysis across the projection horizon. Forecast inputs incorporated EU CBAM implementation timelines, MEE dual carbon enforcement stringency, and METI bioplastics commercialization funding allocations.
Inputs from fermentation operators and downstream compounders were available through the study window; gaps in proprietary continuous fermentation yield data introduce uncertainty bands around cost parity projections. Forecasts reflect documented assumptions regarding regulatory implementation schedules and feedstock price trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Threonine Acids Market
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Global Glutamic Acid Market
Functional Chemicals
Citrulline Malate Market
Functional Chemicals
Phthalimide Market
Functional Chemicals
Sodium Lauroyl Glutamate Market
Functional Chemicals
Thiamine Market
Functional Chemicals
Global Peptide Synthesis Market
Functional Chemicals
Calcium Citrate Malate Market
Functional Chemicals
Carbomer Market
Functional Chemicals
Jellyfish-Derived Peptide Ingredient Concepts Market
Functional Chemicals
Imidazole Market
Functional Chemicals
Chlorobutanol Market
Functional Chemicals
Global Functional Fluids Market
Functional Chemicals
Transfluthrin Market