
 Sodium Citrate Market | 2026-2036
Sodium Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Citrate Market Analysis
Skilled fermentation technologists familiar with citric acid cycle biochemistry is unwinding capacity constraints across sodium citrate supply chains. Jungbunzlauer Suisse AG leverages its Swiss biotech heritage to dominate pharmaceutical-grade output. Fuso Chemical Co. Ltd. anchors Asian supply through integrated citric acid-to-citrate conversion. Gadot Biochemical Industries Ltd. specializes in Dead Sea-derived mineral buffers for diagnostic applications.
Sodium citrate, the sodium salt of citric acid with molecular formula Na₃C₆H₅O₇, functions primarily as a buffering agent, emulsifier, and anticoagulant in industrial and clinical settings. Food-grade material commands stable volume through processed cheese and beverage stabilization, though pharmaceutical-grade material captures superior margins in blood collection tube formulations. Diagnostic applications within the application dimension are expanding fastest as point-of-care testing platforms multiply. Direct sales channels serving drug manufacturers concentrate value capture away from fragmented wholesale distributors.
FDA purity standards for blood anticoagulants and EMA's Medical Device Regulation jointly elevate barrier thresholds for sodium citrate suppliers seeking clinical market access. REACH chemical safety protocols in Europe and China's GB standards for food additives are diverging compliance architectures that multinational producers must navigate simultaneously. Stakeholders should monitor how diagnostic platform miniaturization reshapes volume requirements and specification tolerances across regional procurement frameworks.
Market Dynamics
Pharmaceutical-grade sodium citrate specifications are tightening as diagnostic platform miniaturization compresses volume tolerances and purity thresholds simultaneously across blood collection tube supply chains.
Growth Catalysts
- EMA Medical Device Regulation:Blood collection tube manufacturers in Europe must source higher-purity citrate buffers, pulling pharmaceutical-grade material demand upward.
- Point-of-care testing platforms:Diagnostic device makers are expanding anticoagulant buffer volumes as decentralized testing infrastructure proliferates.
- Processed cheese stabilization:Food-grade sodium citrate maintains steady offtake through emulsification requirements in dairy processing corridors.
Market Restraints
- Citric acid feedstock volatility:Fermentation substrate costs fluctuate with molasses and corn syrup pricing, squeezing citrate converter margins.
- Swiss-German supply concentration:Pharmaceutical-grade output clusters in Central European biotech corridors, creating single-source vulnerability for qualified suppliers.
- REACH compliance escalation:ECHA registration requirements and evolving safety data sheets impose documentation burdens that favor larger chemical houses over specialty producers.
Strategic Opportunities
- India's diagnostic manufacturing:CDSCO-registered blood collection tube producers represent underpenetrated demand for USP-grade citrate buffers.
- Cell therapy preservation media:Emerging bioprocessing applications require GMP-certified citrate formulations for cryopreservation protocols.
- Direct API-supplier contracting:Drug manufacturers are bypassing wholesale distributors to secure long-term citrate supply agreements with fermentation specialists.
Industry Challenges
- Fermentation biochemist scarcity:Citric acid cycle optimization expertise is concentrated among aging technical workforces in European and Japanese producers.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EMA, and NMPA filings for pharmaceutical-grade material extend qualification periods beyond eighteen months.
- Legacy batch record systems:Paper-based manufacturing documentation at mid-tier citrate converters impedes real-time quality tracking demanded by diagnostic OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Citrate Market |
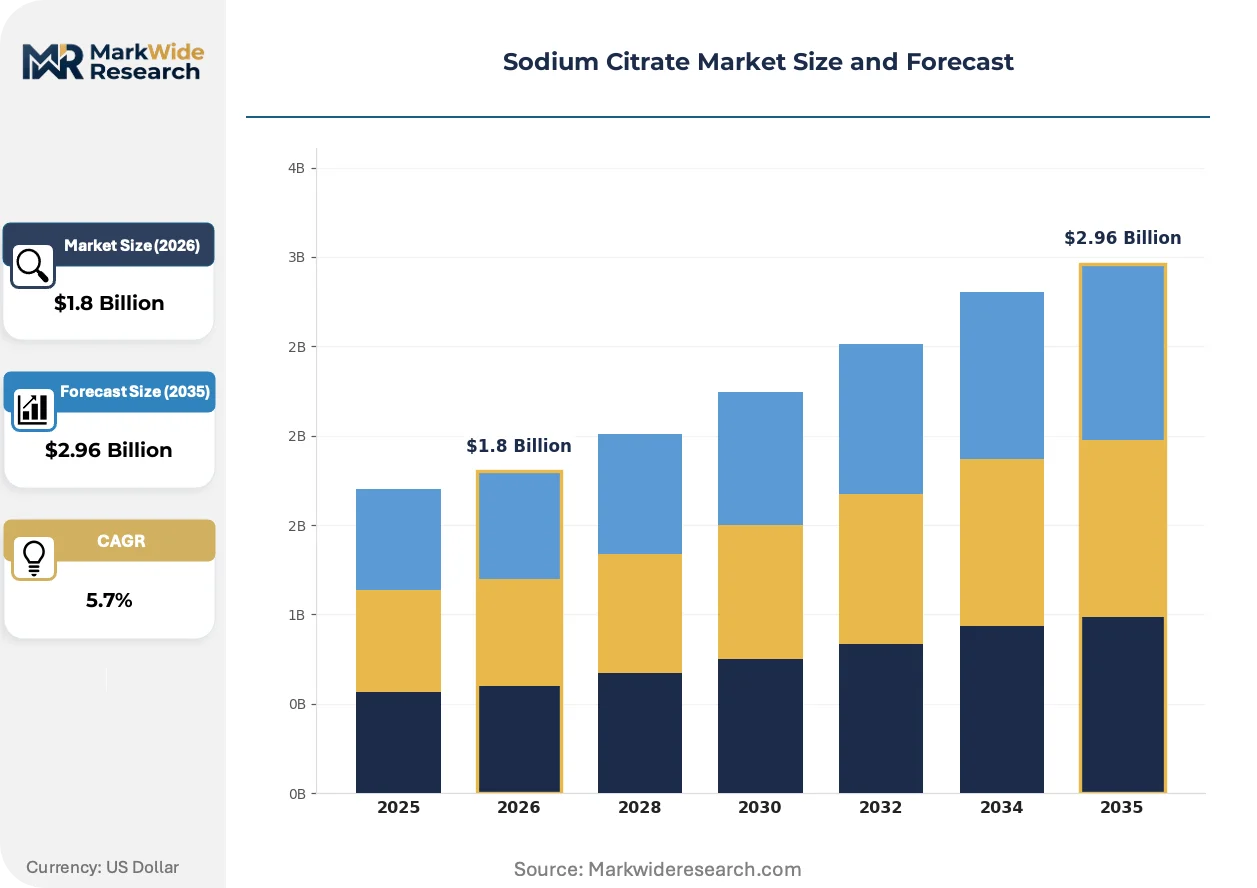
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Laboratory Grade Application: Food & Beverage, Pharmaceuticals, Diagnostics, Personal Care End User: Food Manufacturers, Drug Manufacturers, Research Laboratories, Cosmetic Companies Distribution Channel: Direct Sales, Wholesale Distributors, Online Retail, Specialty Stores |
| Companies Covered | Archer-Daniels-Midland Company, Fuso Chemical Co. Ltd., Jungbunzlauer Suisse AG, S.A. Citrique Belge N.V., Gadot Biochemical Industries Ltd., Pan Chem Corporation, ATPGroup, FBC Industries, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Citrate Market Emerging Trajectories
Continuous fermentation systems and automated downstream purification are compressing unit economics for pharmaceutical-grade citrate while regulatory data integrity requirements reshape supplier qualification protocols.
Single-use bioreactor technology is displacing stainless-steel fermentation trains in citric acid production. Contract manufacturers serving diagnostic buffer markets are adopting disposable contact surfaces to reduce cross-contamination risk during campaign switches. This shift is displacing capital-intensive permanent infrastructure investments among mid-scale citrate converters.
REACH authorization requirements for Substances of Very High Concern are tightening impurity thresholds for citrate salts entering European clinical applications. ECHA's 2024 updated guidance on citric acid derivatives demands expanded toxicological dossiers from importers. Blood collection tube manufacturers in Germany and the Netherlands are consolidating supplier lists to pre-qualified domestic converters with complete SVHC documentation.
Diagnostic OEMs are compressing supplier qualification cycles from multi-year frameworks to eighteen-month rapid onboarding protocols. Point-of-care device makers in North America are demanding real-time certificate of analysis data streams via API integration. This behavioral shift is most visible among mid-cap tube manufacturers seeking second-source citrate security outside traditional Swiss-German supply channels.
Sodium Citrate Market Segmentation
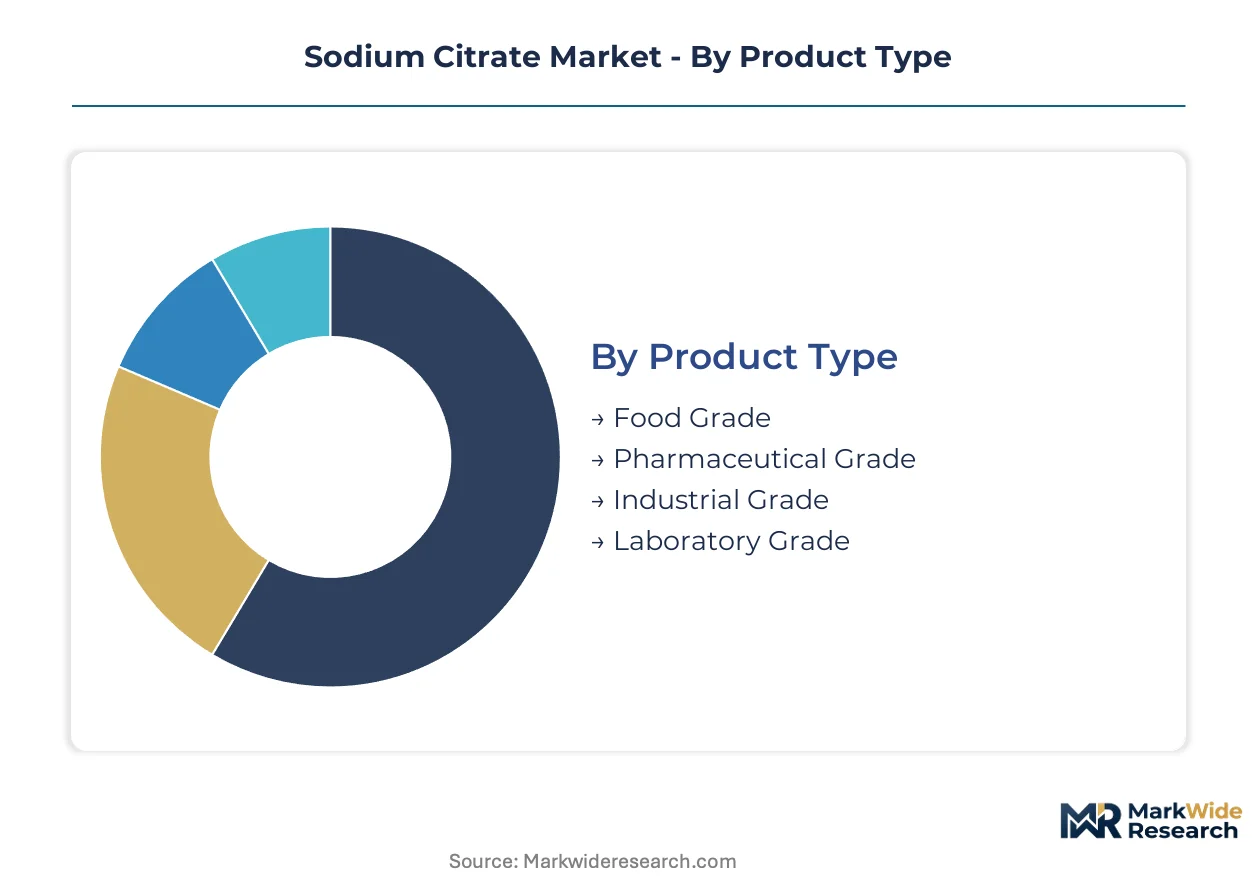
Sodium citrate specifications diverge sharply across end-use contexts, with pharmaceutical and diagnostic applications demanding USP-grade purity while food-grade material competes on cost against citric acid derivatives. Segmentation discipline separates margin-rich clinical buffers from commodity emulsifiers facing substitution pressure.
Product Type:
Pharmaceutical-grade and laboratory-grade segments face the strongest substitution threat from synthetic anticoagulant alternatives and non-citrate buffering systems in cell culture media.
- Food Grade:Sodium citrate dihydrate meeting FCC specifications serves as an emulsifying salt in processed cheese and acidity regulator in beverages. Dairy processors in Germany and the Netherlands maintain steady offtake for sliceable cheese formulations despite citric acid competition.
- Pharmaceutical Grade:USP/EP-compliant material with endotoxin limits below 2.5 EU/g dominates blood collection tube anticoagulant formulations. Swiss and German diagnostic OEMs specify this grade exclusively for vacuum tube buffers, with EMA Medical Device Regulation tightening impurity thresholds.
- Industrial Grade:Technical specification citrate serves detergent builders and metal plating applications. Water treatment facilities in Belgium and France utilize this grade for boiler scale inhibition where purity tolerances permit higher sulfate content.
- Laboratory Grade:ACS-grade material supports molecular biology buffer preparation and electrophoresis applications. Research institutions in Switzerland and Austria procure this segment for PCR-compatible formulations.
Food-grade material anchors the volume base while pharmaceutical-grade material gains share at the steepest rate.
Application:
Cost tier stratification separates premium diagnostic buffers from commodity food additives, with clinical applications commanding fivefold price multiples over industrial uses.
- Food & Beverage:Emulsification in processed cheese and acidity control in soft drinks constitute the largest volume outlet. German dairy cooperatives and French beverage bottlers specify citrate for shelf-stable emulsion stability.
- Pharmaceuticals:Active pharmaceutical ingredient in oral solutions and excipient in effervescent tablets drives formulation demand. Oral rehydration salt manufacturers in India source pharmaceutical-grade material for WHO-prequalified products.
- Diagnostics:Anticoagulant buffer in blood collection tubes and coagulation assay reagents represents the highest-margin application. Point-of-care device makers in the Netherlands and Germany are expanding citrate buffer volumes for decentralized testing platforms.
- Personal Care:pH buffering in shampoos and cosmetic creams utilizes technical-grade material. Cosmetic formulators in France and Italy incorporate citrate for mild acidity adjustment in rinse-off products.
Food and beverage applications absorb the bulk of tonnage while diagnostics climbs the fastest on value expansion.
End User:
Customer type determines procurement sophistication, with drug manufacturers imposing GMP audit requirements that exclude commodity distributors from qualified supplier lists.
- Food Manufacturers:Dairy processors and beverage bottlers procure food-grade citrate through annual volume contracts. Cheese stabilization requirements in Germany and the Netherlands sustain predictable offtake patterns.
- Drug Manufacturers:Pharmaceutical companies demand validated supply chains with complete batch documentation. EMA-registered firms in Switzerland and Germany require ICH Q7-compliant manufacturing for excipient qualification.
- Research Laboratories:Academic and commercial R&D facilities purchase laboratory-grade material in smaller quantities. Biotechnology clusters in Basel and Cambridge specify ACS-grade citrate for reproducible buffer preparation.
- Cosmetic Companies:Personal care formulators prioritize cost-competitive technical-grade supply. Cosmetic manufacturers in France and Italy source citrate through chemical distributors rather than direct fermentation specialists.
Food manufacturers dominate procurement volume while drug manufacturers drive specification escalation.
Distribution Channel:
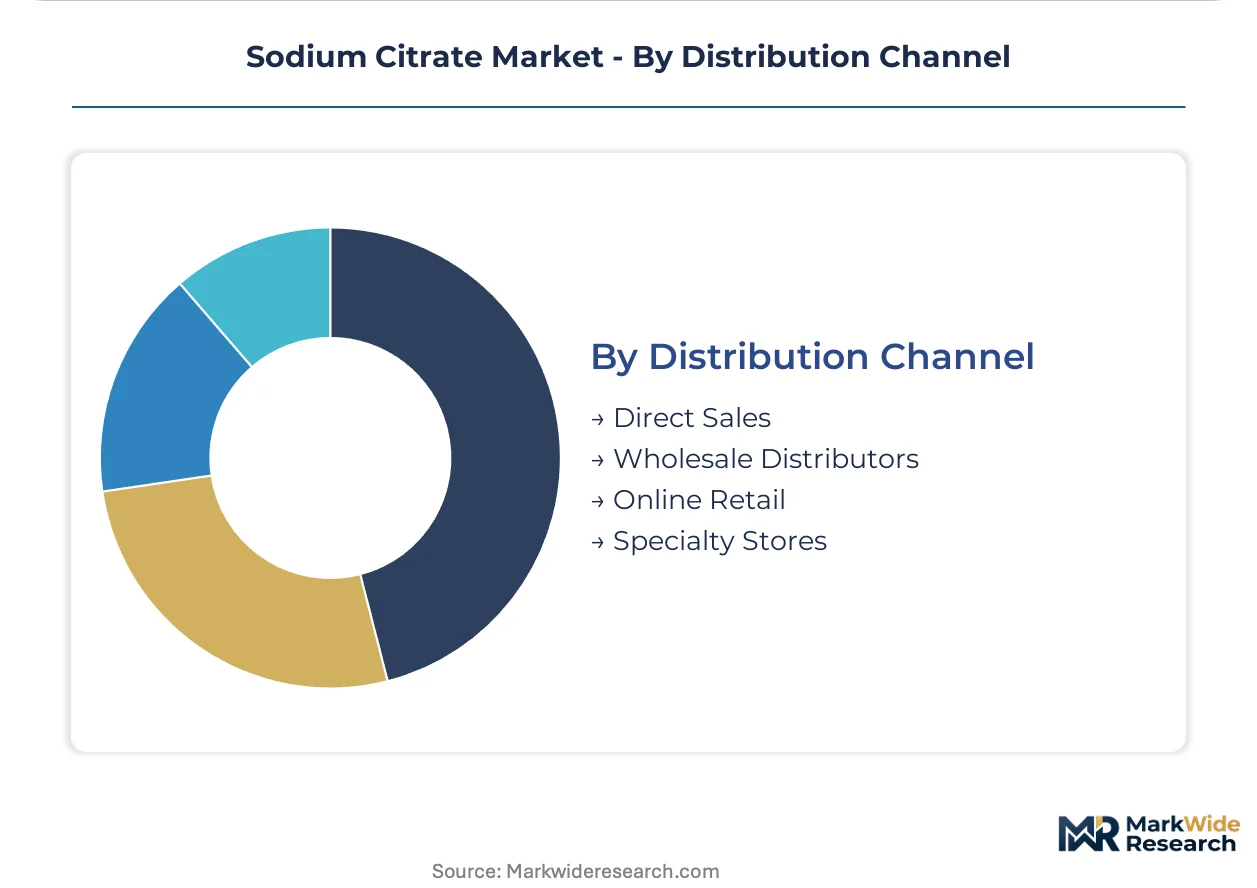
Supply concentration in Central European fermentation corridors shapes channel economics, with direct relationships capturing value from diagnostic OEMs while distributors serve fragmented food-grade demand.
- Direct Sales:Long-term supply agreements between citrate converters and drug manufacturers eliminate distributor margins. Swiss and German diagnostic tube makers contract directly with Jungbunzlauer for pharmaceutical-grade security.
- Wholesale Distributors:Chemical distributors aggregate fragmented food-grade and industrial-grade demand. Benelux-based distributors serve mid-scale dairy processors lacking volume for direct converter contracts.
- Online Retail:E-commerce platforms supply laboratory-grade material to small research facilities. German academic institutions utilize specialty chemical marketplaces for urgent buffer component procurement.
- Specialty Stores:Regional chemical suppliers serve cosmetic compounders and artisan food producers. Italian cosmetic ingredient boutiques stock technical-grade citrate for formulator sample batches.
Direct sales concentrate value capture with pharmaceutical customers while wholesale distributors retain food-grade volume dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss-German pharmaceutical corridors command 40-50% price premiums over Indian and Chinese food-grade supply basins, creating a bifurcated procurement landscape where specification tolerance determines geography.
Germany
Blood collection tube manufacturers in the Rhine-Ruhr industrial belt drive pharmaceutical-grade sodium citrate consumption for EMA-compliant diagnostic buffers. REACH authorization protocols under ECHA's 2024 citric acid derivative guidance tighten impurity documentation requirements for imported material. Heidelberg and Mannheim host specialized fermentation converters supplying Jungbunzlauer-affiliated distribution networks.
Switzerland
Basel's pharmaceutical cluster sustains demand for USP-grade citrate in oral rehydration and effervescent tablet formulations. Swissmedic enforces ICH Q7 manufacturing standards that exclude non-audited Asian suppliers from qualified vendor lists. Jungbunzlauer Suisse AG anchors production in the Swiss biotech corridor with integrated citric acid-to-citrate conversion capacity.
India
CDSCO-registered blood collection tube producers in Maharashtra and Gujarat represent underpenetrated demand for pharmaceutical-grade material as domestic diagnostic manufacturing scales. FSSAI food additive standards govern citrate imports for processed cheese emulsification in dairy cooperatives. Mumbai-Pune pharmaceutical corridors are attracting direct converter contracts bypassing traditional European supply channels.
China
NMPA-regulated drug manufacturers in Jiangsu and Zhejiang provinces consume pharmaceutical-grade citrate for WHO-prequalified oral rehydration salts. GB standards for food additives diverge from REACH protocols, forcing multinational producers to maintain parallel certification dossiers. Yangtze River Delta chemical processors dominate industrial-grade output for detergent and water treatment applications.
United States
FDA purity standards for blood anticoagulants elevate barrier thresholds for citrate suppliers seeking clinical market access in vacuum tube formulations. Point-of-care diagnostic device makers in Massachusetts and California are compressing supplier qualification cycles to eighteen-month rapid onboarding protocols. Boston-Cambridge biotechnology clusters demand GMP-certified citrate for emerging cell therapy preservation media applications.
Sodium Citrate Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with Swiss-German fermentation specialists commanding specification premiums while Asian integrated converters capture volume scale. The market structure concentrates pharmaceutical-grade supply among three qualified European houses while fragmenting food-grade procurement across regional chemical distributors. Player archetypes separate into heritage biotech fermenters, integrated citric acid converters, and mineral-buffer specialists sourcing from non-fermentation feedstocks. Dominant competitive moves include backward integration into molasses and corn syrup supply chains, plus capacity expansion into single-use bioreactor systems for campaign-switch flexibility.
Within the heritage fermentation tier, Jungbunzlauer Suisse AG exemplifies Swiss pharmaceutical-grade dominance through citric acid cycle biochemistry expertise, while Fuso Chemical Co. Ltd. represents Japanese integrated conversion scale and Gadot Biochemical Industries Ltd. occupies a specialized position in Dead Sea-derived mineral buffers for diagnostic applications.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company |
| Fuso Chemical Co. Ltd. |
| Jungbunzlauer Suisse AG |
| S.A. Citrique Belge N.V. |
| Gadot Biochemical Industries Ltd. |
| Pan Chem Corporation |
| ATPGroup |
| FBC Industries |
| Cargill Incorporated |
| Others |
Supply Flow & Price Mechanics
Fermentation capacity utilization above 85% across Swiss-German biotech corridors anchors price floors for pharmaceutical-grade material while squeezing margins for mid-scale food-grade converters in Asia. Scale concentration in Central Europe creates asymmetric pricing power where diagnostic OEMs absorb premium markups for qualified supply security.
Pricing Analysis
Configured-to-order pricing for USP-grade citrate buffers commands 40-50% premiums over standard food-grade spot contracts. Contract-based long-term offtake dominates pharmaceutical procurement, with price differentiation resting on endotoxin certification tiers and GMP audit completion. Cost compression in food-grade tiers is intensifying because citric acid feedstock volatility squeezes converter margins. Food manufacturers exhibit highest price sensitivity, while blood collection tube OEMs prioritize supply security over unit cost.
Supply Chain Analysis
Molasses and corn syrup sourcing through Black Sea agricultural corridors constitutes a chokepoint for European fermentation specialists dependent on substrate quality consistency. Supply concentrates in Switzerland, Germany, and Belgium for pharmaceutical-grade output, while China and India anchor food-grade volume. Raw material dependencies include fermentation substrates, downstream purification resins, and sterile packaging components. Single-source vulnerability runs through Swiss-German qualified supplier networks. Distribution runs through direct converter relationships for pharmaceutical customers and wholesale chemical distributors for fragmented food-grade demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care diagnostic platform proliferation signals early-cycle expansion for anticoagulant buffer demand, with decentralized testing infrastructure penetration still below 30% in underdeveloped diagnostic manufacturing clusters.
For Market Incumbents: Shield pharmaceutical-grade margin pools by accelerating backward integration into captive molasses supply and securing ECHA REACH authorization dossiers ahead of 2024 citric acid derivative guidance implementation. Synthetic anticoagulant substitutes from peptide chemistry specialists threaten citrate dominance in next-generation blood collection formulations. For New Entrants and Emerging Players: Differentiate on CDSCO-registered supply to Maharashtra and Gujarat diagnostic tube manufacturers, where qualified citrate security remains underpenetrated. India's domestic manufacturing scale-up represents the most penetrable geography. A go-to-market angle anchored in rapid eighteen-month qualification cycles with real-time certificate of analysis API integration bypasses incumbent documentation advantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation specialists with single-use bioreactor conversion capability and complete SVHC documentation. Long-term viability rests on continuous processing adoption and regulatory data integrity infrastructure. Acquisition target archetype: mid-cap citrate converters with legacy batch record systems ripe for digital quality tracking retrofit. The signal to watch is diagnostic OEM consolidation of supplier lists to pre-qualified domestic converters with complete toxicological dossiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Substrates | Captive molasses and corn syrup supply secures margin stability against agricultural commodity volatility. |
| Single-Use Bioreactor Conversion | Disposable contact surfaces reduce cross-contamination risk for campaign-switch flexibility in diagnostic buffer production. |
| CDSCO Registration Investment | Indian diagnostic manufacturing scale-up creates qualified supplier entry barriers for unregistered importers. |
| Real-Time CoA Data Stream Integration | API-connected certificate of analysis delivery compresses OEM qualification cycles below traditional multi-year frameworks. |
| REACH SVHC Documentation Completion | ECHA authorization requirements for citric acid derivatives consolidate supplier lists toward compliant domestic converters. |
Methodological Framework
The analysis maps pharmaceutical-grade, food-grade, industrial-grade, and laboratory-grade sodium citrate specifications, each validated through fermentation plant managers, diagnostic OEM procurement leads, pharmaceutical regulatory affairs directors, and chemical distribution channel partners. Primary interview data triangulates against customs trade databases, ECHA registration filings, FDA drug master files, and SEC 10-K disclosures from listed chemical producers. Bottom-up grade-specific volume estimates and top-down regional demand aggregation cross-validate through the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models grade tier, end-use industry, packaging format, and regional production hub segmentation dimensions. CAGRs derive from fitted growth curves applied to grade-specific baseline volumes and penetration rate assumptions. Forecast inputs include point-of-care diagnostic platform deployment trajectories and REACH authorization timeline probabilities.
Material uncertainties — fermentation substrate cost spikes, synthetic anticoagulant substitution acceleration, multi-jurisdiction certification delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory data integrity adoption rates and diagnostic OEM supplier consolidation behavior. Practitioners should keep alternative scenarios live as ECHA guidance implementation and CDSCO registration enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Glutaraldehyde Market
Functional Chemicals
Asparagine Market
Functional Chemicals
Jellyfish-Derived Peptide Ingredient Concepts Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Acrylamide Monomer Market
Functional Chemicals
L-Cysteine Market
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
Citrulline Malate Market
Functional Chemicals
Threonine Acids Market
Functional Chemicals
Chlorobutanol Market
Functional Chemicals
Ortho-Phthalaldehyde Market
Functional Chemicals
Heptanoic Acid Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
Trimer Acid Market