
 Lauric Acid Market | 2026-2036
Lauric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Lauric Acid Market Outlook
Fractional crystallization of palm kernel oil is tilting cost structures toward high-yield C12 extraction, reducing reliance on coconut oil feedstocks. Wilmar International Ltd. leverages integrated palm operations across Indonesia and Malaysia to anchor raw material security. KLK OLEO competes through backward integration into plantation assets and oleochemical conversion capacity. IOI Corporation Berhad specializes in fatty acid distillation technology leadership for pharmaceutical-grade output.
Lauric acid is a saturated medium-chain fatty acid with a twelve-carbon backbone, typically refined to purity levels exceeding 99% for pharmaceutical applications through hydrolysis and fractional distillation of laurin-rich oils. It serves primarily as a surfactant precursor and antimicrobial agent across consumer and industrial formulations. Food-grade lauric acid dominates volume throughput, though cosmetic-grade material captures disproportionate margin pools due to certification overhead and formulation complexity. Emulsifier applications lead end-use consumption, while surfactant demand in sulfate-free personal care is expanding fastest. Powder and crystal forms command price premiums over liquid variants in pharmaceutical and cosmetic channels.
REACH in Europe and FDA food-contact regulations in the United States enforce divergent purity and traceability standards, fragmenting compliance costs across export-oriented producers. ECHA's evolving restrictions on palm oil sustainability claims are reshaping certification requirements for European-bound shipments. BIS standards in India and GB standards in China add further layer complexity for multinational suppliers. Stakeholders must monitor feedstock substitution economics as palm kernel oil price volatility intersects with tightening EU deforestation due diligence rules.
Market Dynamics
Fractional crystallization advances in palm kernel oil processing are compressing C12 extraction costs below coconut oil parity, redrawing feedstock economics and supplier power across Southeast Asian oleochemical clusters.
Growth Catalysts
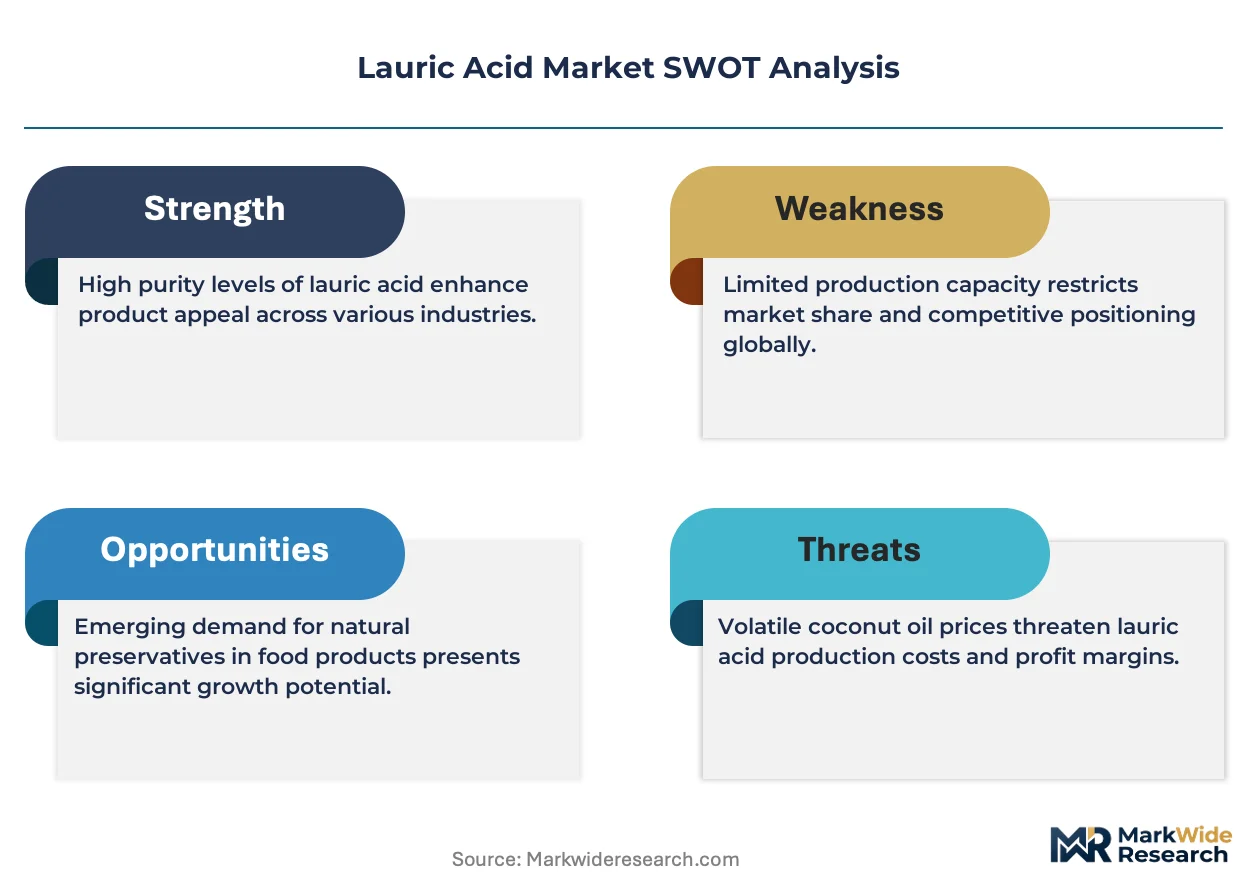
- Sulfate-free surfactant mandates:Personal care formulators in North America and Europe are reformulating cleansing systems around lauric acid-derived mild surfactants to meet clean-label consumer expectations.
- REACH purity escalation:ECHA's tightening cosmetic-grade specifications are creating certified supply scarcity that rewards compliant producers with margin expansion.
- Malaysia-Indonesia processing concentration:Integrated oleochemical complexes in Port Klang and Surabaya are capturing economies of scale in hydrolysis and distillation capacity.
Market Restraints
- Palm kernel oil price volatility:El Niño-driven harvest variability and biodiesel policy competition in Indonesia are injecting raw material cost instability into C12 fraction economics.
- EU deforestation due diligence:The EUDR is imposing traceability documentation burdens that disqualify non-certified plantation sources from European-bound shipments.
- Caprylic-capric acid substitution:MCT oil processors are blending C8-C10 fractions into surfactant applications where lauric acid traditionally dominated emulsification performance.
Strategic Opportunities
- Pharmaceutical-grade distillation:Ultra-high purity specifications for intravenous emulsions and API synthesis are opening premium pricing tiers above cosmetic-grade material.
- India BIS standardization:Emerging domestic food-contact and personal care regulations are creating first-mover advantages for certified suppliers in Mumbai and Ahmedabad formulation hubs.
- Biotechnology convergence:Microbial fermentation of C12 fatty acids from sugar feedstocks is promising supply decoupling from plantation agriculture and EUDR exposure.
Industry Challenges
- Fractional distillation engineering scarcity:Specialized process design expertise for pharmaceutical-grade lauric acid purification is concentrated among a limited pool of oleochemical technology vendors.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of REACH registration, FDA food-contact notification, and BIS compliance is stretching regulatory affairs bandwidth at mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lauric Acid Market |
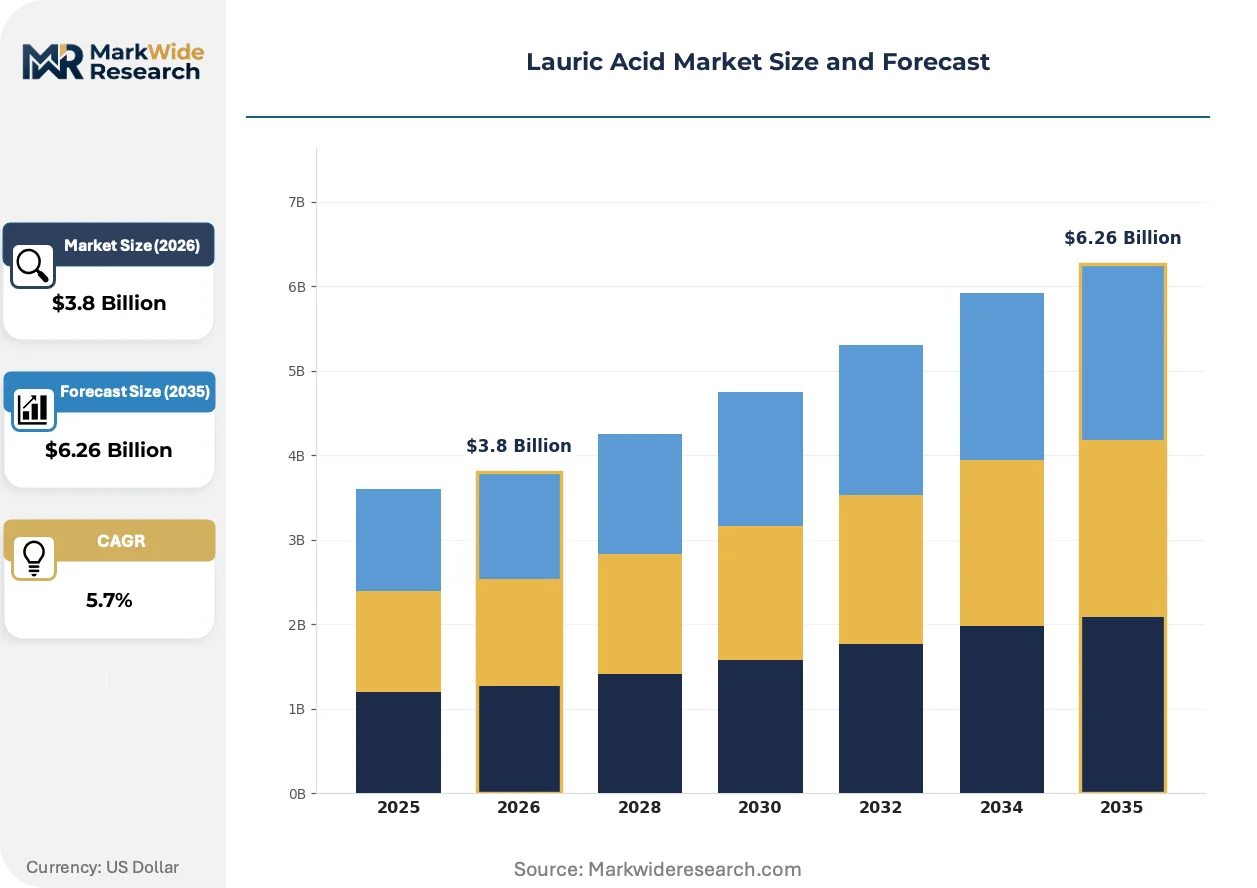
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Cosmetic Grade, Pharmaceutical Grade End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Chemicals Application: Emulsifier, Surfactant, Preservative, Conditioner Form: Liquid, Powder, Crystals, Beads |
| Companies Covered | Wilmar International Ltd., KLK OLEO, IOI Corporation Berhad, Musim Mas Holdings Pte. Ltd., Emery Oleochemicals, Kao Corporation, Godrej Industries, AAK AB, Acme-Hardesty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lauric Acid Market Strategic Shifts
Enzymatic interesterification and membrane filtration technologies are displacing conventional chemical hydrolysis in lauric acid production, while regulatory sustainability mandates and procurement restructuring are rewriting value capture rules.
Membrane-based separation systems are achieving C12 fraction purity above 99.5% without thermal degradation of heat-sensitive triglycerides. Pharmaceutical and high-end cosmetic manufacturers in Germany and Switzerland are qualifying these enzymatic routes for certified supply chains. Conventional acid-catalyzed hydrolysis is rendering obsolete for premium-grade applications where oxidation stability and color specifications are non-negotiable.
EUDR due diligence requirements are mandating geolocation verification and deforestation-free attestation for every plantation hectare supplying European oleochemical converters. Compliance infrastructure investments are favoring integrated plantation-processor operators with captive traceability systems over merchant traders. Cosmetic-grade lauric acid shipments bound for Rotterdam and Hamburg are experiencing documentation processing delays that spot-market suppliers cannot absorb.
Formulator direct-procurement contracts are displacing traditional oleochemical distributor networks in North American personal care. Large multinational brands in New Jersey and California are establishing multi-year offtake agreements with Malaysian and Indonesian producers, bypassing regional chemical distributors. This channel compression is visible most acutely in sulfate-free shampoo and body wash segments where supply security and certification transparency outweigh price flexibility.
Lauric Acid Market Segmentation
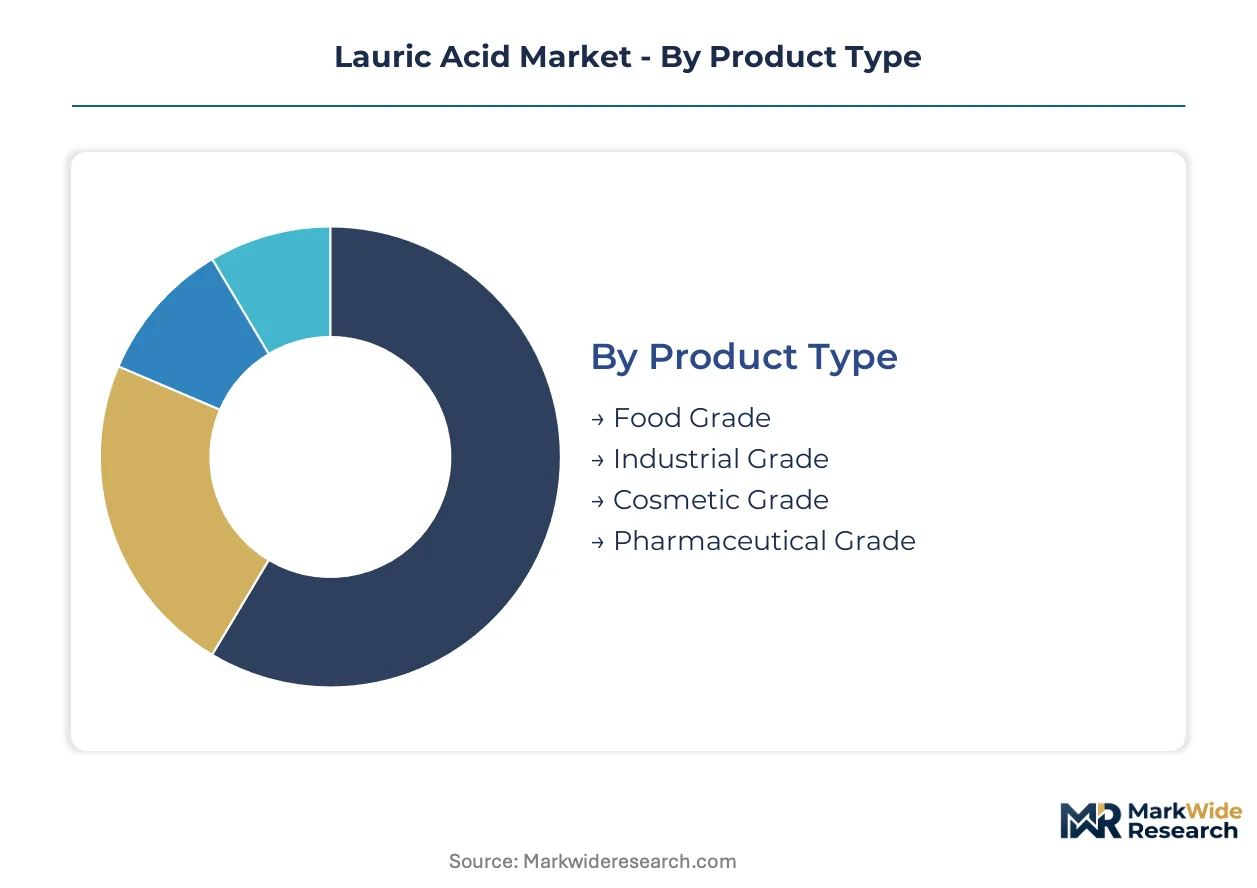
Lauric acid value capture diverges sharply across purity tiers and formulation channels. Grade specifications determine regulatory burden and margin structure, while application chemistry dictates procurement relationships with end-use formulators.
Product Type:
Cost tier stratification separates commodity throughput from certified premium material, with each grade commanding distinct compliance overhead and customer qualification timelines.
- Food Grade:Refined to meet FDA food-contact and FSSAI standards for direct consumption applications. Volume concentrates in Southeast Asian oleochemical clusters serving packaged food manufacturers in India and Indonesia, where clean-label emulsifier demand is tightening specification requirements.
- Cosmetic Grade:Purified beyond 99% with controlled oxidation parameters and color specifications for skin-contact formulations. REACH-registered supply from Malaysian integrated producers is capturing margin expansion as ECHA tightens impurity limits for European personal care shipments.
- Industrial Grade:Standard hydrolysis output serving lubricant and plasticizer manufacturing with minimal certification overhead.
- Pharmaceutical Grade:Ultra-high purity material for intravenous emulsions and active pharmaceutical ingredient synthesis, produced through fractional distillation under GMP conditions.
Food grade commands the established base. The steepest expansion runs through cosmetic grade.
End Use Industry:
Application maturity varies across customer sectors, with personal care and pharmaceutical channels driving specification escalation while food and industrial segments prioritize cost efficiency.
- Personal Care:Sulfate-free surfactant reformulation in North American and European cleansing products is concentrating demand for mild, lauric-derived surfactants. Formulators in New Jersey and California are establishing direct procurement relationships with Indonesian producers to secure certified supply chains.
- Pharmaceuticals:Intravenous fat emulsion and lipid nanoparticle applications require pharmaceutical-grade material with batch-level traceability. Swiss and German manufacturers are qualifying enzymatic production routes for reduced thermal degradation risk.
- Food & Beverage:Emulsifier and coating applications in processed foods, with India and Indonesia representing volume concentration.
- Chemicals:Intermediate consumption for derivative fatty acid production and industrial surfactant manufacturing.
Food and beverage commands the established base. The steepest expansion runs through personal care.
Application:
Functional chemistry determines value capture, with emulsification performance and antimicrobial efficacy driving differentiated pricing across use cases.
- Surfactant:Primary feedstock for sodium lauryl sulfate alternatives in sulfate-free personal care. Formulators are reformulating cleansing systems around mild lauric-derived surfactants to meet clean-label consumer expectations in Germany and the United States.
- Emulsifier:Stabilizes oil-water interfaces in food, cosmetic, and pharmaceutical formulations. Demand concentrates in processed food manufacturing across India and Indonesia, where packaged food expansion is tightening emulsifier specification requirements.
- Preservative:Antimicrobial activity against gram-positive bacteria in cosmetic and food preservation applications.
- Conditioner:Hair and skin conditioning properties in rinse-off and leave-on personal care products.
Emulsifier commands the established base. The steepest expansion runs through surfactant.
Form:
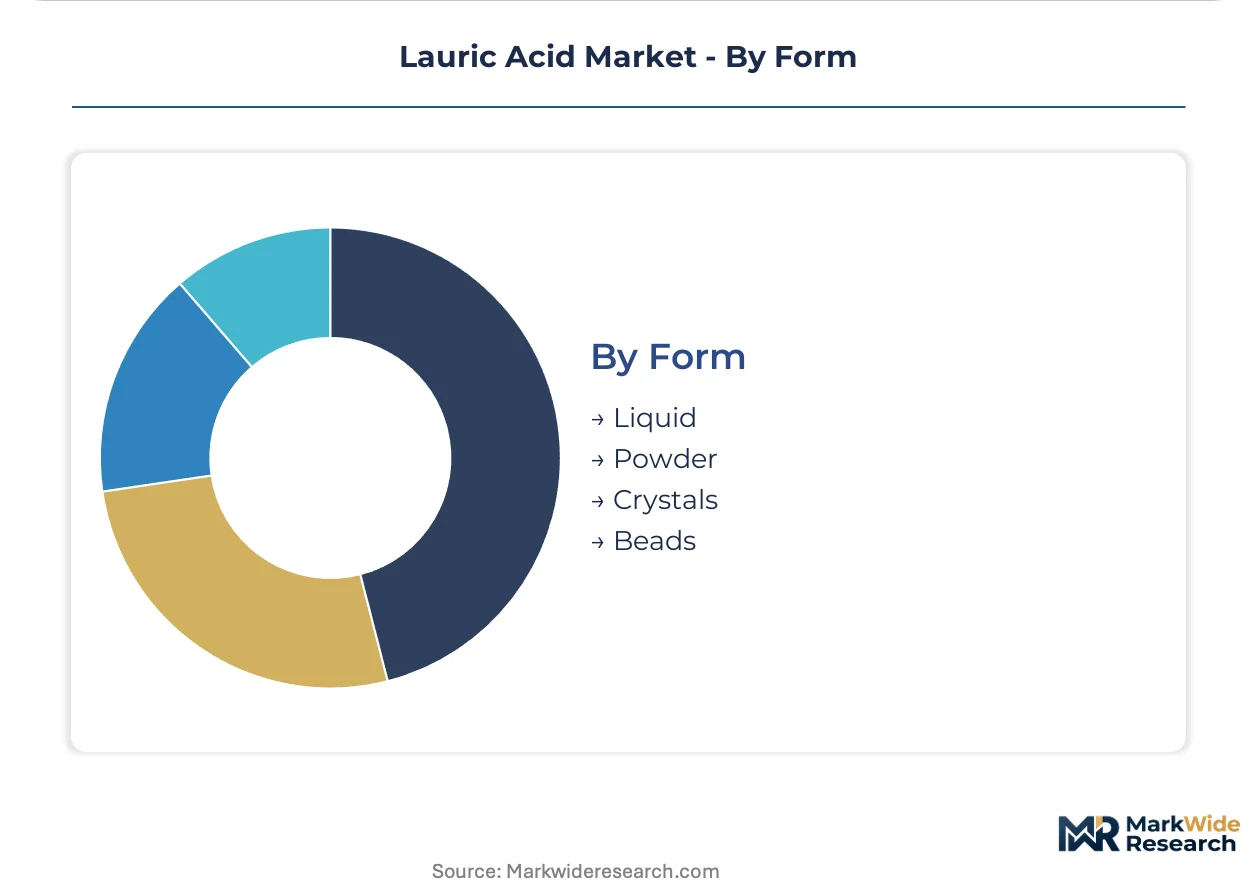
Physical presentation determines handling economics and end-use compatibility, with solid forms commanding premiums for pharmaceutical and cosmetic channels.
- Crystals:High-purity solid form with defined melting point for pharmaceutical compounding and premium cosmetic formulation. German and Swiss manufacturers specify crystalline material for intravenous emulsion production where dissolution kinetics are critical.
- Powder:Micronized solid for dry blend compatibility in food and cosmetic powder formulations. Processing in Port Klang and Surabaya is achieving particle size distributions optimized for direct compression tableting.
- Liquid:Standard hydrolysis output in bulk tanker shipments for industrial surfactant and chemical derivative manufacturing.
- Beads:Prilled form for controlled dissolution in hot-melt and extrusion applications.
Liquid commands the established base. The steepest expansion runs through crystals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian and Indonesian oleochemical exports flow primarily to European personal care formulators and North American food manufacturers, with Rotterdam and Hamburg serving as the principal European entry points for certified cosmetic-grade material.
Indonesia
Surabaya and Medan house integrated palm kernel oil processing complexes that supply C12 fractions to German cosmetic manufacturers. EUDR due diligence requirements are forcing plantation-to-port traceability investments that favor vertically integrated operators over merchant traders. Port facilities in North Sumatra are expanding refrigerated storage capacity for pharmaceutical-grade material bound for Swiss manufacturers.
Malaysia
Port Klang oleochemical clusters dominate high-purity lauric acid output for REACH-registered European shipments. KLK OLEO and IOI Corporation Berhad leverage backward integration into plantation assets to secure raw material security. The Malaysian Palm Oil Board certification schemes are becoming mandatory prerequisites for Rotterdam-bound cosmetic-grade consignments.
United States
New Jersey and California formulation hubs are establishing direct procurement contracts with Southeast Asian producers, bypassing traditional chemical distributors. FDA food-contact regulations govern emulsifier applications in processed foods, while clean-label consumer preferences are accelerating sulfate-free surfactant reformulation. Gulf Coast oleochemical importers are expanding tanker receiving infrastructure for industrial-grade liquid shipments.
Germany
REACH compliance costs are concentrating demand among ECHA-registered suppliers with documented purity above 99%. BASF and Evonik formulation facilities in Ludwigshafen specify crystalline material for pharmaceutical emulsion production. Hamburg port authorities are implementing EUDR documentation checkpoints that delay non-certified palm kernel oil derivatives.
India
Mumbai and Ahmedabad serve as formulation centers for domestic packaged food and personal care manufacturers expanding emulsifier consumption. BIS standards for food-contact applications are tightening specification requirements that favor certified imports over unregistered local material. Godrej Industries operates integrated oleochemical capacity serving both export and domestic pharmaceutical-grade demand.
Lauric Acid Market Competitive Environment
On the supply side, the industry is consolidating around integrated plantation-processor operators with captive traceability systems capable of satisfying EUDR documentation requirements. The competitive terrain separates into three strategic archetypes: Southeast Asian integrated giants with upstream plantation control, European specialty distributors with REACH registration expertise, and Indian domestic producers serving price-sensitive food-grade applications. Capacity expansion in Indonesian hydrolysis facilities and strategic partnerships between Malaysian producers and German formulators represent the dominant competitive moves reshaping supply relationships.
Among Southeast Asian integrated operators, Wilmar International Ltd., KLK OLEO, and IOI Corporation Berhad exemplify the plantation-to-oleochemical conversion model that dominates pharmaceutical and cosmetic-grade output. Wilmar International Ltd. represents the scale-driven archetype with operations spanning Indonesian and Malaysian processing clusters. KLK OLEO occupies a position within the backward-integrated tier, leveraging captive plantation assets to secure raw material security. IOI Corporation Berhad exemplifies the technology-specialist archetype, with fractional distillation capabilities serving ultra-high purity specifications for intravenous emulsion manufacturers in Germany and Switzerland.
| Leading Market Players |
|---|
| Wilmar International Ltd. |
| KLK OLEO |
| IOI Corporation Berhad |
| Musim Mas Holdings Pte. Ltd. |
| Emery Oleochemicals |
| Kao Corporation |
| Godrej Industries |
| AAK AB |
| Acme-Hardesty |
| Others |
Value Chain & Pricing Dynamics
The Port Klang-Rotterdam maritime corridor anchors cost dynamics for pharmaceutical-grade shipments, with refrigerated container rates compressing margins on high-purity material while concentrating pricing power among integrated Malaysian producers capable of absorbing documentation overhead for EUDR-compliant consignments.
Pricing Analysis
Conventional acid-catalyzed hydrolysis, enzymatic membrane filtration, and emerging microbial fermentation routes command widening price spreads as German formulators qualify enzymatic output at premiums exceeding standard material. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades reflects certification burden and purity specification divergence. Cost compression in food-grade material is intensifying because Indonesian biodiesel policy competition for palm kernel oil feedstock is tightening C12 fraction availability. Industrial-grade buyers in Indian emulsifier manufacturing exhibit highest price sensitivity, while Swiss intravenous emulsion producers accept substantial premiums for batch-traceable crystalline material.
Supply Chain Analysis
Tariff exposure between Southeast Asian producers and European Union jurisdictions dominates strategic planning as EUDR documentation requirements extend customs processing timelines. Malaysia, Indonesia, and India concentrate upstream hydrolysis capacity, with downstream formulation drawing from Philippine coconut oil and Indonesian palm kernel oil as primary laurin-rich inputs. Single-source vulnerability concentrates in Port Klang distillation complexes serving REACH-registered cosmetic-grade demand. Distribution runs through direct-procurement contracts between Malaysian integrated operators and North American personal care formulators, displacing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lauric acid market operates as a regulatory entrenchment story where EUDR traceability infrastructure and REACH registration timelines create switching costs that protect incumbent positions against merchant trading competitors.
For Market Incumbents: Insulate pharmaceutical-grade margin pools through captive plantation-processor traceability systems that preempt EUDR disqualification risks. Expand enzymatic production capacity in Malaysian complexes to capture premium qualification timelines from German and Swiss formulators. Counter caprylic-capric acid substitution threats in surfactant applications by deepening technical service relationships with sulfate-free personal care brands in California and New Jersey. For New Entrants and Emerging Players: Pharmaceutical-grade distillation capability gaps among mid-scale Indian processors represent the most penetrable entry point for certified supply to domestic Mumbai and Ahmedabad formulation hubs. Microbial fermentation of C12 from sugar feedstocks offers technology-differentiated positioning that decouples from plantation agriculture and EUDR exposure entirely. Pursue joint development agreements with European cosmetic brands seeking supply security outside traditional Southeast Asian channels. For Investors and Strategic Acquirers: Specialist oleochemical technology vendors with fractional distillation engineering expertise for GMP pharmaceutical production constitute the priority acquisition archetype. Long-term viability hinges on feedstock flexibility and certification breadth across FDA, REACH, and emerging BIS standards. Monitor biotechnology convergence timelines as the critical inflection signal for plantation-dependent model obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | KLK OLEO and IOI Corporation Berhad secure raw material security through captive Indonesian and Malaysian palm kernel oil supply. |
| Enzymatic Production Route Qualification | Membrane filtration technology achieves pharmaceutical-grade purity without thermal degradation, displacing acid-catalyzed hydrolysis in German and Swiss markets. |
| EUDR Traceability Infrastructure Investment | Geolocation verification systems become mandatory for Rotterdam and Hamburg port entry, favoring integrated operators over merchant traders. |
| Direct Procurement Contract Establishment | North American personal care formulators in New Jersey and California bypass distributors to secure multi-year offtake agreements with Indonesian producers. |
| Pharmaceutical-Grade Distillation Capacity Expansion | Ultra-high purity output for intravenous emulsions commands premium pricing tiers above cosmetic-grade material in Swiss and German demand centers. |
Study Parameters
A standing panel of oleochemical plant managers, personal care formulator procurement leads, pharmaceutical emulsion technical directors, and Southeast Asian plantation operations executives provided ongoing calibration against operating reality. Primary interview insights combined with secondary validation from customs trade databases, Malaysian Palm Oil Board certification records, ECHA REACH registration filings, and SEC disclosures from listed oleochemical processors. Bottom-up capacity and utilization estimates triangulated against top-down demand segmentation across grade tiers and end-use industries.
Scenario-bracketing around feedstock substitution economics and regulatory enforcement intensity bounded the projection horizon. Segmentation modeling incorporated grade tier, end-use industry, physical form, and regional production hub dimensions. CAGRs derived from volume trajectory analysis intersecting with price evolution assumptions across pharmaceutical, cosmetic, food-grade, and industrial material. Palm kernel oil price volatility coefficients and EUDR compliance cost structures served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in biodiesel policy competition for vegetable oil feedstocks or El Niño-driven harvest variability would shift the trajectory substantially. Forecasts reflect documented assumptions regarding enzymatic technology adoption curves and biotechnology fermentation scale-up timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Lauric Arginate Market
Functional Chemicals
Transfluthrin Market
Functional Chemicals
Global Peptide Synthesis Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
Para-Aminophenol Market
Functional Chemicals
2-Propylheptanol Market
Functional Chemicals
Threonine Acids Market
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
Global Sodium Lignosulfonate Market
Functional Chemicals
US Potassium Methylate Market
Functional Chemicals
Europe Formic Acid Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
Soy-Based Chemical Market
Functional Chemicals
Global Functional Fluids Market