
 Global Thermosetting Polymer Market | 2026-2036
Global Thermosetting Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermosetting Polymer Market Analysis
The EU Green Deal is broadening the addressable market for low-emission thermoset formulations across European automotive supply chains. INEOS leverages its integrated phenolic resin platform to serve insulation and composites demand in Germany and the UK. BASF SE anchors its position through proprietary polyurethane systems tailored to electric vehicle battery encapsulation. Sumitomo Bakelite Co Ltd dominates Asian phenolic resin supply for semiconductor packaging substrates.
Thermosetting polymers are macromolecular materials that undergo irreversible chemical crosslinking when exposed to heat, catalysts, or radiation, forming rigid three-dimensional networks with high thermal stability and chemical resistance; epoxy systems typically cure through amine or anhydride hardeners at temperatures between 25°C and 180°C depending on application requirements. Epoxy formulations lead the product type landscape due to their adhesion strength and electrical insulation properties in aerospace laminates and printed circuit boards. Polyurethane segments compete on flexibility and impact absorption in automotive seating and construction sealants where energy efficiency standards tighten. Phenolic resins occupy mature positions in friction materials and foundry binders where cost-performance ratios remain decisive for industrial buyers.
REACH registration requirements in Europe, EPA toxics release standards in the United States, and China's GB standards for formaldehyde emissions in wood adhesives collectively shape formulation chemistry and market access conditions for resin producers. The EU F-Gas Regulation and evolving state-level chemical disclosure laws in California and New York are forcing reformulation of blowing agents and curing catalysts across polyurethane value chains. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure type approvals for next-generation thermoset platforms.
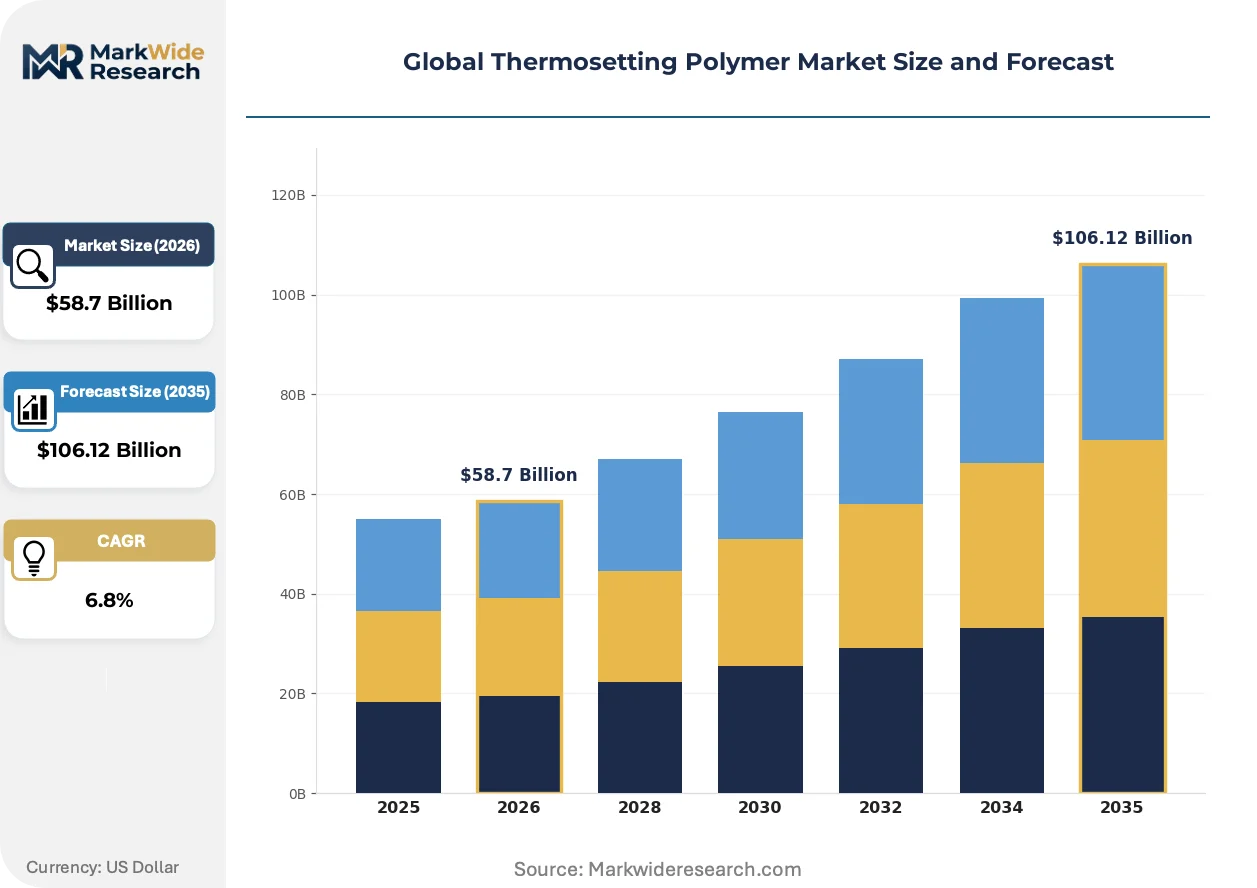
Market Dynamics
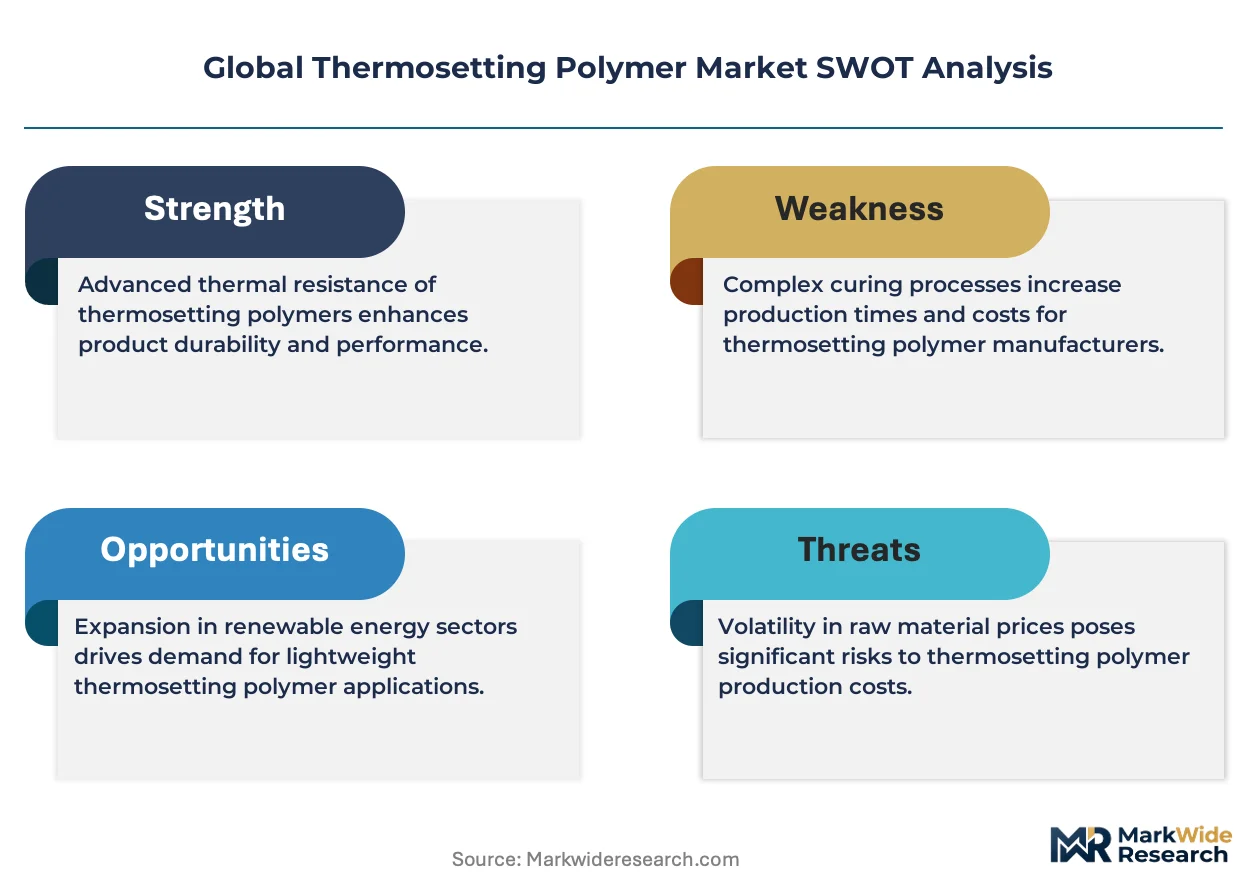
EU REACH chemical standards and the EU Green Deal are forcing simultaneous reformulation of curing agents and acceleration of recyclable thermoset development, compressing product development cycles while opening premium positioning for compliant suppliers.
Growth Catalysts
- REACH compliance mandates:European automotive OEMs now require low-emission phenolic and epoxy systems in structural components, pulling investment toward compliant resin platforms.
- Electric vehicle battery encapsulation:Polyurethane thermal management systems are displacing conventional potting compounds as cell energy densities rise and fire safety standards tighten.
- China's eastern coastal manufacturing belt:Concentrated automotive and electronics clusters in Jiangsu and Guangdong provinces generate sustained volume demand for high-performance laminates and semiconductor packaging substrates.
Market Restraints
- Petrochemical feedstock volatility:Benzene and propylene price swings directly compress margins for phenolic and polyurethane producers without long-term offtake agreements.
- Curing agent supply concentration:Specialty amine and anhydride hardener production concentrates in Germany and the United States, creating single-source vulnerabilities for Asian compounders.
- Thermoset recyclability limitation:Irreversible crosslinking chemistry blocks mechanical recycling pathways, exposing producers to landfill diversion costs and extended producer responsibility fees under evolving EU waste frameworks.
Strategic Opportunities
- India's electronics manufacturing incentives:PLI scheme subsidies for semiconductor and PCB fabrication are attracting phenolic resin suppliers to establish local compounding capacity.
- Vitrimer chemistry convergence:Dynamic covalent network polymers combining epoxy processing with thermoplastic reprocessability are opening closed-loop manufacturing models for aerospace tooling.
- California chemical disclosure laws:SB 1015 and related state-level mandates are creating first-mover advantage for suppliers with pre-registered, fully characterized formulation portfolios.
Industry Challenges
- Formulation toxicologist scarcity:REACH registration deadlines and state-level disclosure requirements have outpaced training pipelines for regulatory compliance specialists.
- Multi-jurisdiction certification timelines:Simultaneous EPA toxics release, ECHA SVHC, and China GB standard approvals extend product launch cycles by 18-24 months.
- Legacy equipment retrofit costs:Existing compression molding and resin transfer infrastructure requires capital-intensive modification to process bio-based or low-VOC thermoset formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermosetting Polymer Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Phenolic, Polyurethane, others Application: Aerospace, Automotive, Electrical & Electronics, Construction End User: Manufacturers, Contractors, Distributors, Fabricators Technology: Compression Molding, Injection Molding, Transfer Molding, Pultrusion |
| Companies Covered | INEOS, Polynt S.p.A., BASF SE, Sumitomo Bakelite Co Ltd, Asahi Kasei Corporation, Lanxess AG, Solvay, Daicel Corporation, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermosetting Polymer Market Emerging Trajectories
Automation of curing process control and real-time quality monitoring is compressing defect rates and enabling closed-loop manufacturing in high-value aerospace and electronics applications.
Continuous fiber-reinforced thermoplastic-thermoset hybrid processing is automating layup and consolidation steps previously dependent on manual labor. Aerospace tier-1 suppliers in Germany and the United States are deploying these systems for wing skin and fuselage panel production. The technology is automating throughput scaling while reducing skilled technician dependence in cleanroom environments.
The EU F-Gas Regulation and its 2024 phasedown schedule for hydrofluorocarbon blowing agents are forcing polyurethane foam producers to qualify hydrocarbon and hydrofluoroolefin alternatives. Construction insulation and appliance manufacturers face reformulation deadlines that compress qualification windows. Cold chain equipment suppliers in Northern Europe are responding fastest due to earlier national implementation timelines.
OEMs are consolidating resin procurement under single-source technical partnership models rather than transactional spot purchasing. Tier-1 automotive and aerospace buyers are displacing fragmented distributor networks with direct mill relationships supported by vendor-managed inventory systems. This concentration is most visible in Germany's automotive supply chain and Japan's electronics substrate sector.
Global Thermosetting Polymer Market Segmentation
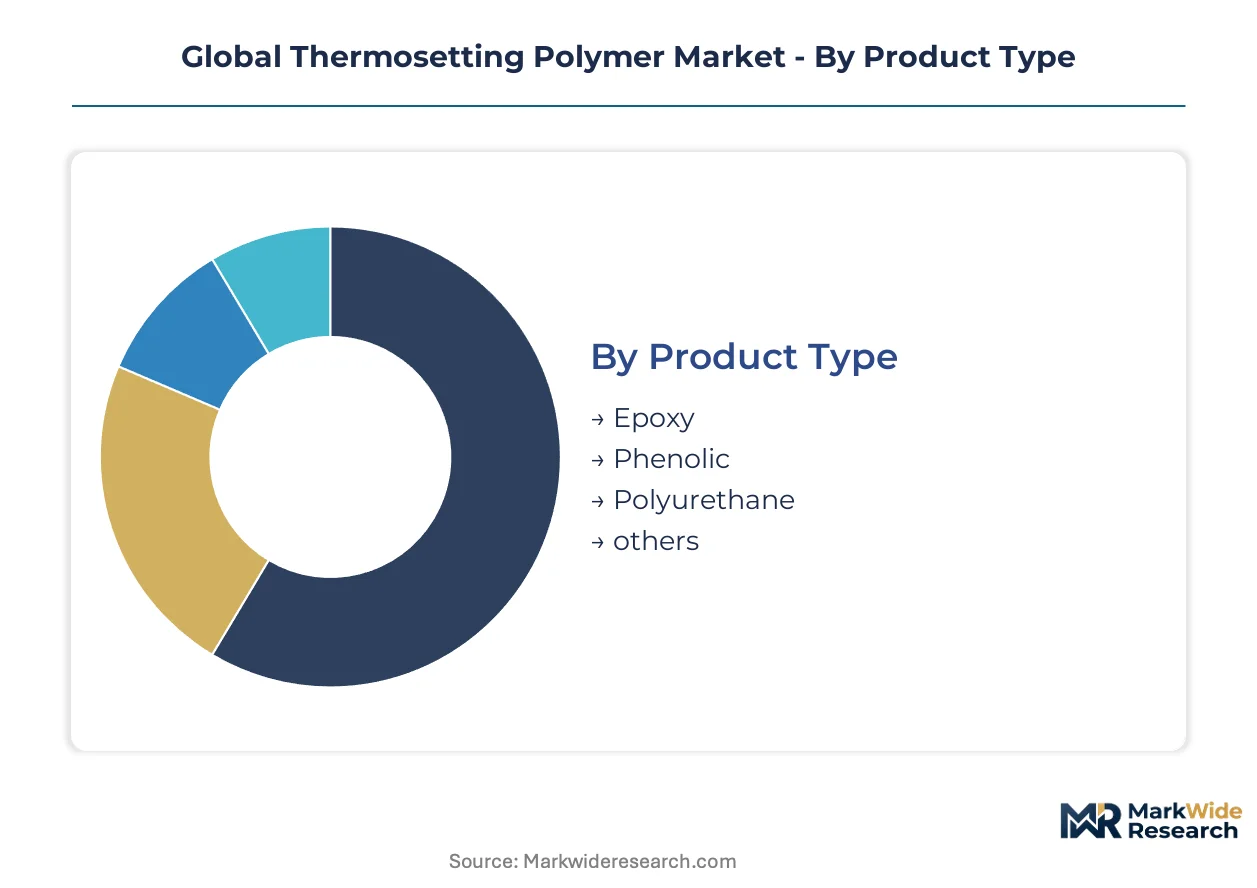
Thermosetting polymer procurement splits across four dimensions that determine formulation chemistry, processing infrastructure, and regulatory exposure. Each segmentation axis carries distinct certification burdens and margin profiles that shape supplier positioning.
Product Type:
REACH registration requirements in Europe, EPA toxics release standards in the United States, and China's GB formaldehyde emission limits impose divergent substance restrictions across these resin platforms.
- Epoxy:Amine or anhydride-cured systems form rigid networks with superior adhesion strength and electrical insulation. Aerospace laminates in Germany and printed circuit board fabrication in China's Jiangsu province concentrate demand as fire safety standards tighten and cell energy densities rise.
- Phenolic:Formaldehyde-condensed resins deliver high thermal stability and flame resistance at low cost. Friction materials and foundry binders in India's automotive supply chain absorb volume, though GB standard compliance for wood adhesive applications constrains formulation flexibility in Chinese export markets.
- Polyurethane:Isocyanate-cured systems dominate flexible foam and thermal management applications.
- Others:Unsaturated polyester and vinyl ester resins serve corrosion-resistant tanks and marine composites.
Leading the category by volume: Epoxy. Growing fastest: Polyurethane.
Application:
End-use sectors diverge sharply in performance specifications, batch sizes, and supplier qualification timelines.
- Aerospace:FAA and EASA type certification mandates drive multi-year qualification cycles for structural composite prepregs. Boeing and Airbus tier-1 suppliers in the United States and Germany specify toughened epoxy systems for wing skins and fuselage panels, with automation of fiber placement compressing defect rates.
- Automotive:Battery encapsulation and lightweight body-in-white applications pull polyurethane and epoxy volumes. OEMs in Germany consolidate procurement under direct mill relationships with vendor-managed inventory, displacing fragmented distributor networks.
- Electrical & Electronics:Semiconductor packaging substrates and printed circuit boards demand ultra-pure phenolic and epoxy formulations with tight ionic contamination controls.
- Construction:Insulation foam and structural adhesives face EU F-Gas Regulation phasedown deadlines for hydrofluorocarbon blowing agents.
Aerospace commands the highest specification premiums. Automotive delivers the steepest expansion trajectory as electric vehicle production scales.
End User:
Procurement authority and technical capability vary substantially across the value chain, determining pricing leverage and formulation co-development depth.
- Manufacturers:Tier-1 automotive and aerospace OEMs with in-house compounding expertise negotiate direct resin supply agreements. BASF SE and INEOS serve these accounts through integrated platforms with dedicated technical service teams.
- Contractors:Construction and infrastructure installers purchase formulated systems through distributor networks with limited specification influence.
- Distributors:Regional chemical distributors hold inventory risk and provide blending services for small-batch industrial customers.
- Fabricators:Composite part producers operate resin transfer molding and compression presses, selecting formulations based on cure kinetics and equipment compatibility.
Manufacturers capture the deepest supplier relationships. Fabricators generate the most fragmented demand patterns.
Technology:
Processing method determines capital equipment requirements, cycle time economics, and workforce skill intensity.
- Compression Molding:Matched metal tooling under heat and pressure forms thermoset sheets and bulk molding compounds. Automotive brake pads and electrical switch housings in Germany and Japan rely on this mature, high-throughput approach.
- Injection Molding:Screw plastication and high-pressure injection enable complex geometry with tight tolerances. Electronics connectors and appliance housings in China's Guangdong province absorb significant epoxy and phenolic volumes.
- Transfer Molding:Intermediate pressure and temperature conditions suit medium-complexity electrical components.
- Pultrusion:Continuous fiber pulling through resin baths and heated dies produces structural profiles for construction and infrastructure applications.
Compression molding retains the largest installed base. Injection molding is climbing the fastest as electronics miniaturization demands precision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of epoxy and phenolic resin feedstock while the United States and Germany absorb premium volumes for aerospace and automotive applications. This production-consumption divide shapes trade flows and regional pricing structures.
United States
Boeing and Lockheed Martin tier-1 suppliers in Washington State and Texas drive demand for toughened epoxy prepregs in wing skin fabrication. EPA toxics release standards constrain formaldehyde-based phenolic formulations in wood adhesive applications. The Southeast automotive corridor spanning Tennessee and South Carolina pulls polyurethane thermal management systems for electric vehicle battery plants.
Germany
Volkswagen and BMW consolidate resin procurement under direct mill agreements for lightweight body-in-white components. ECHA SVHC screening under REACH accelerates substitution of conventional curing agents in automotive supply chains. The Ruhr industrial cluster hosts integrated phenolic resin production serving insulation and friction material fabricators.
China
Jiangsu and Guangdong provinces concentrate electronics manufacturing demand for ultra-pure epoxy laminates in printed circuit board fabrication. GB standards for formaldehyde emissions in wood adhesives constrain phenolic resin export formulations. The Yangtze River Delta automotive cluster consumes polyurethane systems for seating and battery encapsulation.
Japan
Tokyo Electron and Shin-Etsu drive phenolic resin demand for semiconductor packaging substrates with tight ionic contamination controls. METI carbon neutrality roadmaps push reformulation of conventional thermosets in electronics applications. The Nagoya aerospace corridor qualifies epoxy prepregs for regional jet programs.
India
PLI scheme subsidies for semiconductor and PCB fabrication attract phenolic resin suppliers to establish local compounding capacity. BIS certification requirements for electrical insulation materials extend product qualification timelines. The Gujarat automotive cluster generates emerging demand for polyurethane seating and interior components.
Global Thermosetting Polymer Market Vendor Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive feedstock positions. Three tiers operate: global resin platforms with dedicated technical service teams, regional compounders serving distributor networks, and specialized prepregs suppliers for aerospace qualification. Capacity expansion and backward integration into petrochemical feedstocks represent the dominant competitive moves as producers defend margin positions against benzene and propylene volatility.
Among European integrated chemical groups, INEOS and BASF SE exemplify the platform archetype with broad phenolic and polyurethane portfolios. Sumitomo Bakelite Co Ltd represents the Asia-focused specialist model concentrated on semiconductor packaging substrates. These three companies anchor the competitive landscape across distinct geographic and application vectors.
| Leading Market Players |
|---|
| INEOS |
| Polynt S.p.A. |
| BASF SE |
| Sumitomo Bakelite Co Ltd |
| Asahi Kasei Corporation |
| Lanxess AG |
| Solvay |
| Daicel Corporation |
| Celanese Corporation |
| Others |
Supply Flow & Price Mechanics
REACH chemical standards in Europe gate qualified supply and premium-tier pricing access for thermosetting polymer producers serving automotive and aerospace OEMs. Compliance with ECHA SVHC screening and EPA toxics release requirements separates certified suppliers commanding formulation premiums from commodity resin traders facing margin compression.
Pricing Analysis
Yield-based pricing anchors premium tiers where epoxy and phenolic formulations demonstrate proven performance in FAA-certified aerospace laminates and semiconductor packaging substrates. Three-tier pricing structure across aerospace-grade, automotive-specification, and industrial-standard levels reflects certification burden and ionic contamination controls. Cost compression in industrial phenolic segments intensifies because benzene feedstock volatility transfers directly to spot-market buyers. Automotive OEMs in Germany exhibit lowest price sensitivity due to consolidated direct-mill procurement, while construction contractors through distributor networks show highest sensitivity to formulation cost swings.
Supply Chain Analysis
Specialty amine and anhydride hardener production concentrates in Germany and the United States, creating workforce-availability constraints for Asian compounders seeking qualified curing agent supply. China, Germany, and the United States anchor global epoxy and phenolic resin manufacturing, drawing from benzene, propylene, and formaldehyde feedstock streams. Single-source vulnerability in specialty hardener supply exposes compounders to allocation risk during capacity constraints. Distribution runs through integrated chemical conglomerates with captive technical service teams serving tier-1 OEMs directly, bypassing fragmented distributor networks for high-specification volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tight curing agent supply concentration in Germany and the United States props pricing for qualified formulations, creating durable margin pools for compliant producers. This supply-constrained structure favors incumbents with backward integration into petrochemical feedstocks and regulatory certification depth.
For Market Incumbents: Deepen backward integration into benzene and propylene supply chains to defend margin positions against feedstock volatility. Expand compounding capacity in China's Jiangsu province to capture electronics cluster demand for ultra-pure epoxy laminates. Invest in REACH registration completion ahead of SVHC screening deadlines to lock out non-compliant competitors from European automotive supply chains. For New Entrants and Emerging Players: Launch via distributor partnerships serving India's Gujarat automotive cluster and PLI-subsidized semiconductor fabrication facilities. Target phenolic resin compounding for PCB substrates where local BIS certification requirements extend qualification timelines for established suppliers. Pursue white-space in bio-based thermoset formulations for construction insulation facing EU F-Gas Regulation reformulation deadlines. For Investors and Strategic Acquirers: Vitrimer chemistry patent filings reaching critical mass is the leading indicator that reprocessable thermoset platforms will capture aerospace tooling retrofit cycles. Position for 5-10 year holding periods around integrated resin platforms with captive feedstock positions and established OEM technical partnerships. Monitor ECHA substance of very high concern candidate list expansions as signals for forced reformulation waves creating acquisition opportunities among distressed compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | Captive benzene and propylene supply shields margin from volatility in German and US phenolic production. |
| REACH Registration Completion | ECHA SVHC compliance secures type approval for European automotive OEM direct-mill supply agreements. |
| Capacity Expansion in Eastern China | Jiangsu and Guangdong positioning captures electronics cluster demand for ultra-pure epoxy laminates. |
| Vitrimer Chemistry Development | Dynamic covalent networks enable closed-loop manufacturing for aerospace tooling retrofit cycles. |
| Long-term Supply Agreement with Tier-1 OEMs | Vendor-managed inventory systems with Volkswagen and BMW displace fragmented distributor networks. |
Methodological Framework
Trade databases, SEC 10-K filings, and ECHA registration dossiers formed the secondary backbone of this analysis. Primary interviews with plant managers at integrated resin platforms, procurement leads at German automotive OEMs, distribution channel partners in Asian electronics supply chains, and technical R&D directors at specialty hardener producers validated demand assumptions. Bottom-up and top-down triangulation cross-checked volume estimates against customs data and downstream consumption patterns.
Bottom-up modeling of epoxy, phenolic, and polyurethane segments across aerospace, automotive, and electronics applications anchored the analytical framework. Grade tier, end-use industry, and regional production hub dimensions structured the segmentation. CAGRs derived from installed capacity expansion schedules, OEM platform launch timelines, and regulatory compliance deadline clustering across the projection horizon. Feedstock price elasticity and substitution coefficients for bio-based alternatives informed scenario boundaries.
Petrochemical feedstock volatility, regulatory divergence between REACH and EPA timelines, and curing agent supply allocation shocks are the dominant revision risks to forecast assumptions. Material deviation in benzene-propylene spreads or ECHA substance restriction pacing warrants pause and re-evaluation of volume and margin trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
South America Engineering Plastics Market
Polymers & Resins
Polyol Esters Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Ammonium Polyphosphate (Phase II) Market
Polymers & Resins
Oman PVC Products Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Thermosetting Plastics Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
Polylactic Acid Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Polyglycerol Market