
 Paraben Market | 2026-2036
Paraben Market Size, Share, and Industry Trends Forecast 2026-2036
Paraben Market Analytics
Clean-beauty retailers and pharmaceutical compounders are bifurcating the traditional buyer base for paraben preservatives. Ashland leverages its specialty chemical portfolio to serve reformulating cosmetics brands seeking blend-compatible alternatives. Dow Chemical Company anchors North American supply through integrated petrochemical feedstock access. Sharon Laboratories competes on tailored preservative systems that reduce paraben dependency without sacrificing shelf stability.
Parabens are alkyl esters of p-hydroxybenzoic acid synthesized via esterification of phenol with carboxylic acids, functioning primarily as broad-spectrum antimicrobial preservatives in aqueous formulations. Propylparaben and butylparaben dominate high-performance cosmetic applications where lipophilicity enhances efficacy against gram-positive bacteria. Methylparaben retains cost leadership in food preservation and over-the-counter pharmaceuticals where water solubility simplifies incorporation. The personal care application segment carries the deepest margin pools as brands absorb premium pricing for preservative blends that satisfy dual regulatory and consumer-perception requirements.
The FDA maintains paraben concentration limits in cosmetic formulations while the EPA monitors environmental accumulation through wastewater discharge pathways. ECHA classifies certain parabens as substances of very high concern under REACH, accelerating substitution investment among EU-facing suppliers. China's SAMR enforces GB standards for cosmetic preservatives that diverge from Western thresholds, creating compliance fragmentation for multinational formulators. Stakeholders must monitor regulatory divergence between preservative approval regimes when allocating R&D budgets across geographic markets.
Market Dynamics
Preservative substitution pressure from clean-label cosmetics brands is fragmenting demand between legacy paraben formulations and bio-based alternatives, forcing suppliers to maintain dual product portfolios without scale economies.
Growth Catalysts
- Domestic cosmetic production in China:Local manufacturers under GB standards are expanding preservative consumption as formulation volumes scale to serve domestic and export markets.
- REACH authorization timelines:ECHA's substance evaluation windows create temporary supply security for approved paraben grades while competitors await alternative approvals.
- Blended preservation systems:Synergistic combinations with phenoxyethanol and organic acids extend paraben efficacy at reduced concentrations, preserving technical relevance.
Market Restraints
- Phenol feedstock volatility:Benzene derivative pricing swings directly compress esterification margins for p-hydroxybenzoic acid production.
- Substitution pipeline depth:Sodium benzoate and potassium sorbate are capturing water-based cosmetic formulations previously served by methylparaben.
- REACH SVHC classification:ECHA's endocrine disruption listings for propylparaben and butylparaben trigger downstream user notification obligations across EU supply chains.
Strategic Opportunities
- India personal care manufacturing:CDSCO cosmetic registration pathways and PLI scheme incentives are attracting formulation investment that requires preservative supply localization.
- Pharmaceutical ophthalmic applications:Sterile multi-dose eye drops retain paraben dependency due to broad-spectrum efficacy against Pseudomonas contamination.
- Green chemistry certification alignment:USDA BioPreferred and EU Ecolabel criteria create positioning space for paraben alternatives that maintain performance parity.
Industry Challenges
- Cross-regulatory formulation complexity:Multinational brands must maintain separate SKU portfolios for FDA, ECHA, and SAMR compliance thresholds.
- Clean-label talent scarcity:Cosmetic chemists with dual expertise in traditional preservation and natural alternative stabilization command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paraben Market |
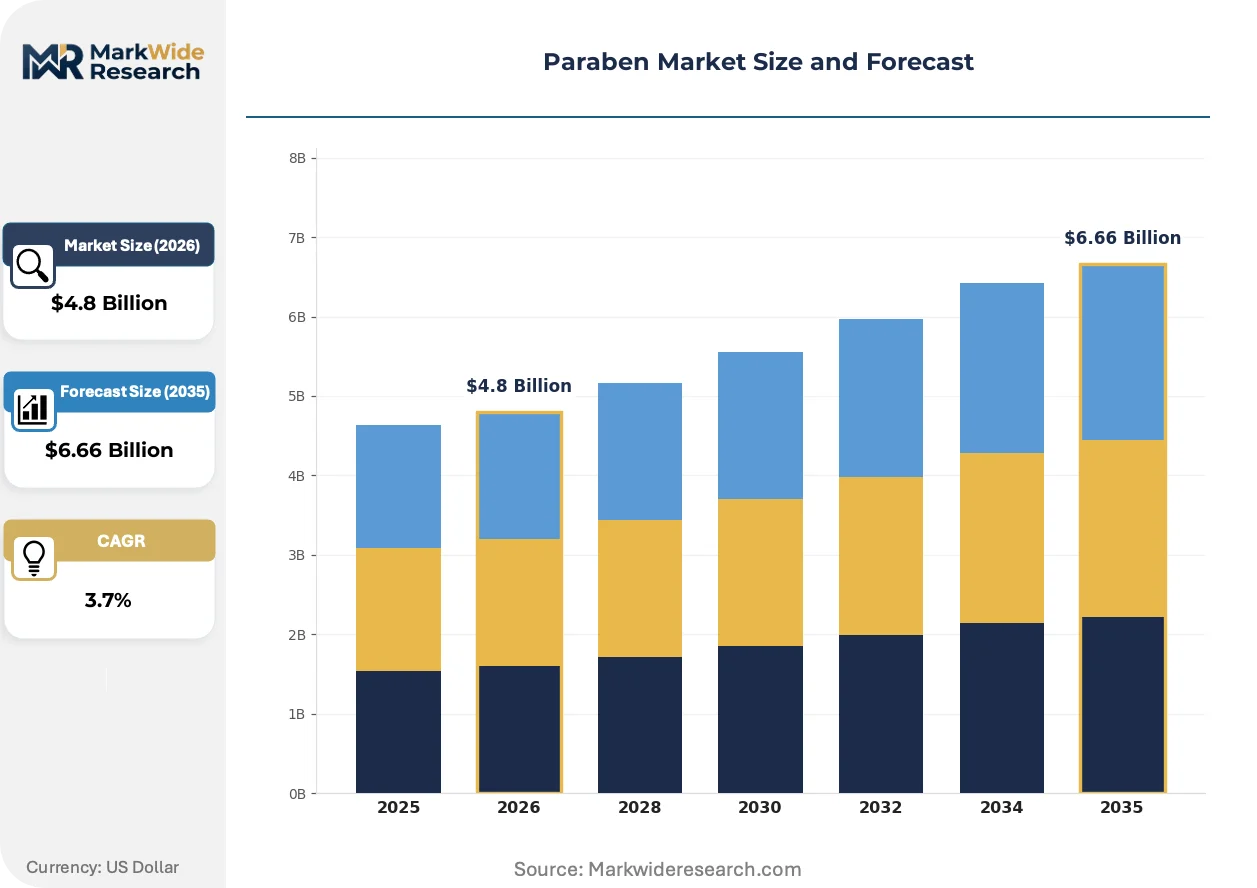
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methylparaben, Ethylparaben, Propylparaben, Butylparaben Application: Cosmetics, Pharmaceuticals, Food Preservatives, Personal Care End User: Beauty Industry, Healthcare Sector, Food Industry, Retailers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Ashland, Dow Chemical Company, Croda International Plc, DuPont, Clariant AG, Symrise AG, Lonza Group, Sharon Laboratories, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paraben Market Evolving Landscape
Preservation technology is bifurcating between optimized paraben blends for cost-sensitive applications and novel bioactive systems for premium positioning, with regulatory divergence accelerating portfolio complexity.
Enzymatic esterification processes are supplanting traditional acid-catalyzed synthesis for p-hydroxybenzoic acid derivatives. Specialty chemical producers in Germany and Japan are adopting lipase-mediated routes to achieve higher stereoselectivity and reduce solvent waste. This biotechnology transition is compressing capital intensity for mid-scale producers while raising technical barriers for commodity manufacturers.
REACH restriction proposals for additional paraben chain lengths are forcing reformulation timelines across EU-facing cosmetic brands. The industrial consequence is accelerated qualification of phenoxyethanol-caprylyl glycol combinations in rinse-off products. Hair care and skin care segments are most affected, with contract manufacturers expanding alternative preservation validation capacity.
Direct-to-consumer beauty brands are compressing supplier qualification cycles from 18 months to 6 months through digitalized technical documentation platforms. Traditional distributors are losing formulation advisory revenue to manufacturer-direct technical service teams. This channel restructuring is most visible in North American indie beauty, where brands bypass regional chemical distributors for global supplier relationships.
Paraben Market Segmentation
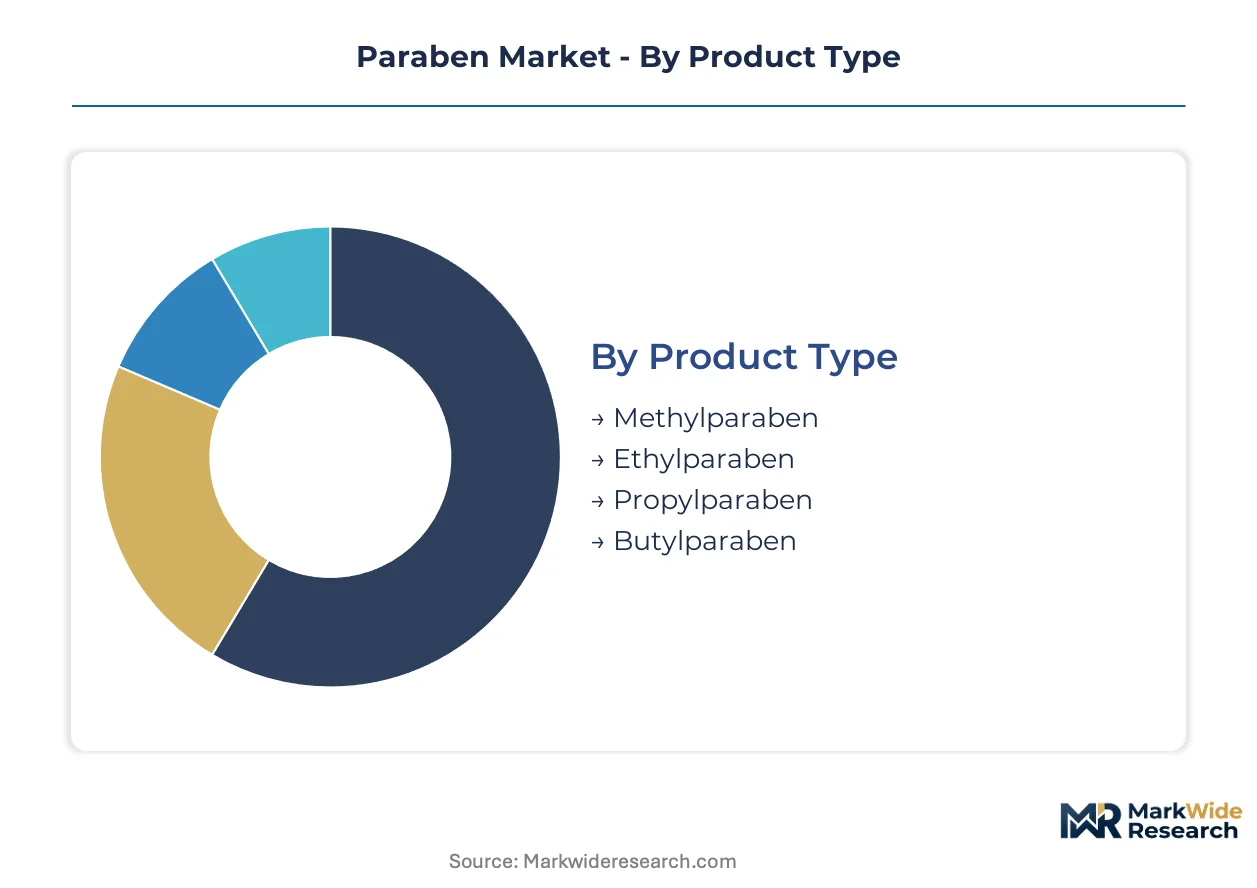
Paraben demand fragments across preservation chemistry variants, regulatory thresholds, and end-use performance requirements. Understanding segment boundaries reveals where formulation costs concentrate and which substitution pressures threaten incumbent positions.
Product Type:
Methylparaben and propylparaben anchor domestic pharmaceutical and food preservation supply chains, while butylparaben and specialized esters serve export-oriented cosmetics manufacturers seeking lipophilic efficacy.
- Methylparaben:Water-soluble short-chain ester dominating oral pharmaceutical formulations and aqueous food preservation. Demand concentrates in FDA-regulated over-the-counter drug manufacturing where cost-per-dose metrics override clean-label positioning. Substitution pressure from sodium benzoate is compressing volume in beverage applications.
- Propylparaben:Medium-chain ester balancing lipophilicity with regulatory acceptance across personal care emulsions. Export-led demand from Chinese cosmetics manufacturers under GB standards sustains volume despite ECHA SVHC classification triggering EU supply chain notifications.
- Ethylparaben:Intermediate solubility profile serving niche pharmaceutical coatings and veterinary preparations.
- Butylparaben:Highly lipophilic long-chain ester retained in premium color cosmetics and anhydrous formulations where gram-positive coverage justifies concentration limits.
Methylparaben commands the established base. The steepest expansion runs through propylparaben as blended preservation systems extend its utility at reduced concentrations.
Application:
Margin stratification separates high-volume food preservation from premium cosmetics where dual regulatory compliance absorbs pricing power.
- Cosmetics:Skin care, hair care, and color cosmetic formulations requiring broad-spectrum antimicrobial coverage in aqueous and emulsion bases. REACH authorization timelines for alternative preservatives create temporary supply security for incumbent paraben grades while phenoxyethanol-caprylyl glycol combinations accelerate qualification.
- Personal Care:Rinse-off and leave-on products spanning deodorants, sunscreens, and baby care where consumer-perception sensitivity drives fastest reformulation investment. Indie beauty brands compress supplier qualification cycles through digitalized technical documentation.
- Pharmaceuticals:Ophthalmic multi-dose preparations and topical antiseptics retaining paraben dependency due to Pseudomonas coverage requirements.
- Food Preservatives:Baked goods, sauces, and beverages where methylparaben competes on cost against benzoate and sorbate salts.
Food preservation absorbs volume concentration. Cosmetics and personal care capture margin expansion as clean-label premiums sustain blended system pricing.
End User:
Procurement sophistication varies from commodity-scale food industry tenders to cosmetics brands demanding preservative blend compatibility data and regulatory dossier support.
- Beauty Industry:Multinational cosmetics houses and contract manufacturers managing separate SKU portfolios for FDA, ECHA, and SAMR compliance thresholds. Direct-to-consumer brands bypass regional distributors for manufacturer-direct technical service relationships.
- Healthcare Sector:Hospital pharmacies and ophthalmic drug manufacturers where sterile formulation requirements preserve paraben relevance against substitution.
- Food Industry:Industrial bakeries and sauce processors prioritizing cost-per-kilogram preservation economics.
- Retailers:Private-label personal care brands and clean-beauty retailers bifurcating between legacy formulations and bio-based alternatives.
Healthcare sector procurement retains technical rigidity. Beauty industry demand is expanding most quickly as domestic manufacturing scales in China and India.
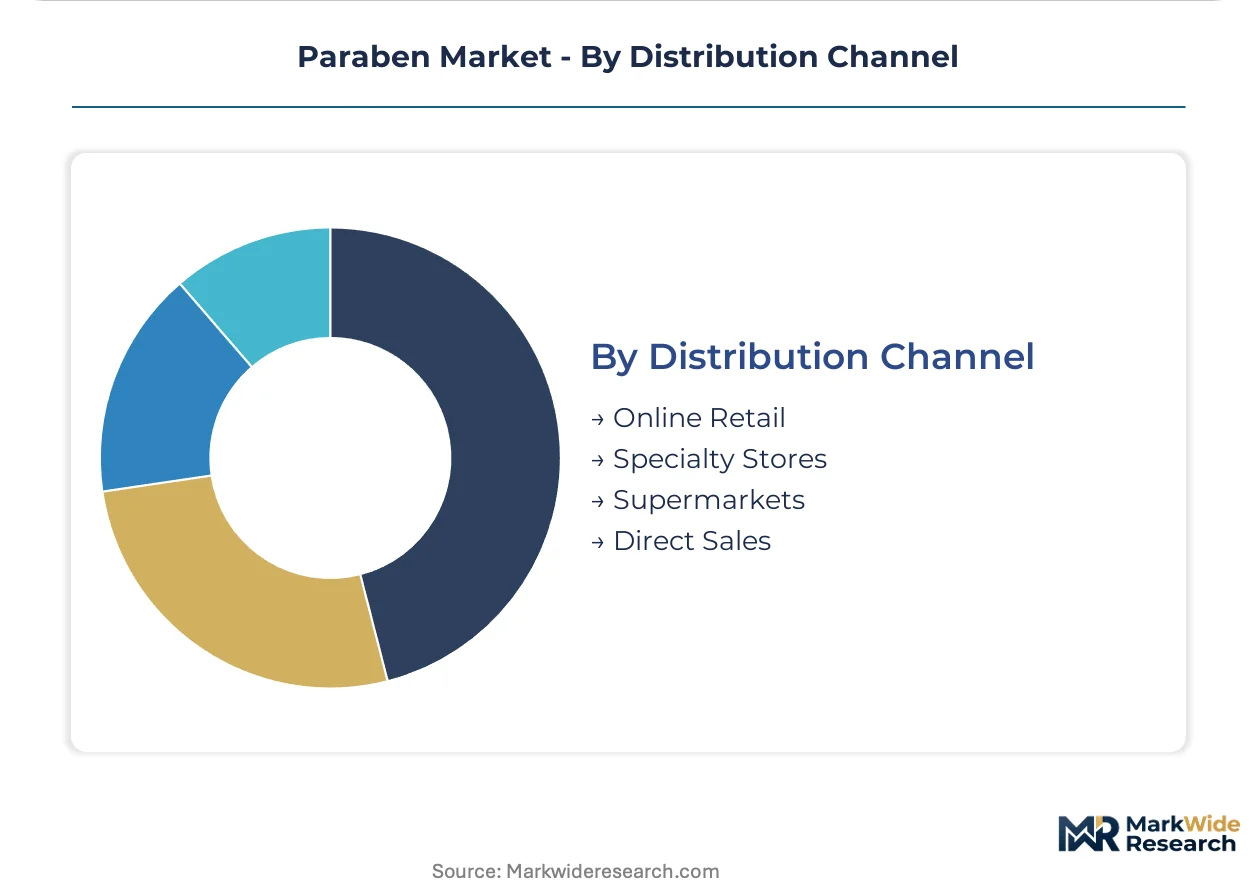
Distribution Channel:
Channel restructuring concentrates advisory value with manufacturer-direct technical teams, eroding traditional distributor formulation support revenue.
- Direct Sales:Global specialty chemical producers serving multinational cosmetics brands with integrated preservative blend supply and regulatory dossier management. Ashland and Dow Chemical Company anchor this channel through captive technical service capacity.
- Specialty Stores:Regional chemical distributors retaining relevance in mid-scale pharmaceutical and food industry procurement.
- Online Retail:E-procurement platforms capturing indie beauty and small-batch cosmetic manufacturer demand with compressed lead times.
- Supermarkets:Mass-market personal care private-label supply chains where price competition favors commodity preservative sourcing.
Direct sales commands relationship value. Online retail is climbing the fastest as digitalized qualification accelerates supplier selection velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty chemical exports supply EU cosmetic formulators while Chinese domestic production scales under GB standards. Indian PLI scheme incentives attract preservative localization investment. Brazilian ANVISA pathways preserve paraben relevance in Latin American pharmaceutical supply chains.
United States
FDA concentration limits and EPA wastewater monitoring shape formulation compliance costs for domestic cosmetics manufacturers. The agency maintains paraben approval for over-the-counter pharmaceuticals while tracking environmental accumulation pathways. New Jersey and California host contract manufacturing clusters serving indie beauty brands with compressed supplier qualification cycles.
Germany
ECHA SVHC classifications for propylparaben and butylparaben trigger downstream notification obligations across EU supply chains. REACH authorization timelines create temporary supply security for approved grades while alternatives await qualification. The Rhine-Ruhr chemical corridor anchors enzymatic esterification capacity for higher-stereoselectivity p-hydroxybenzoic acid derivatives.
China
SAMR enforces GB cosmetic preservative standards that diverge from Western thresholds, forcing multinational formulators to maintain separate SKU portfolios. Domestic cosmetic production volumes scale to serve both local consumption and export markets. The Yangtze River Delta concentrates formulation manufacturing under tightening ingredient disclosure rules.
India
CDSCO cosmetic registration pathways and PLI scheme incentives attract personal care manufacturing investment requiring preservative supply localization. Domestic brands expand formulation volumes as contract manufacturers qualify alternative preservation systems. Maharashtra and Gujarat host emerging specialty chemical production serving regional beauty industry demand.
Brazil
ANVISA pharmaceutical registration preserves paraben dependency in sterile multi-dose ophthalmic preparations where Pseudomonas coverage requirements block substitution. Regional cosmetics manufacturers balance cost-sensitive formulation against clean-label positioning pressures. São Paulo state anchors Latin American distribution infrastructure for preservative blend supply.
Paraben Market Competitive Landscape
Listed leaders compete with private specialists across integrated petrochemical feedstock access versus tailored preservative system design. The vendor base stratifies between scale-driven commodity ester producers and formulation-advisory specialty houses. Three archetypes dominate: integrated chemical conglomerates with captive phenol supply, independent preservative blend specialists, and cosmetics-house captive technical service teams. Capacity expansion and portfolio diversification toward bio-based alternatives represent the dominant competitive moves.
Within the integrated chemical tier, Dow Chemical Company anchors North American supply chain positioning through petrochemical feedstock integration. Ashland occupies the specialty advisory position serving reformulating cosmetics brands with blend-compatible alternatives. Sharon Laboratories exemplifies the independent preservative system specialist competing on tailored formulations that reduce paraben dependency without sacrificing shelf stability.
| Leading Market Players |
|---|
| Ashland |
| Dow Chemical Company |
| Croda International Plc |
| DuPont |
| Clariant AG |
| Symrise AG |
| Lonza Group |
| Sharon Laboratories |
| Procter & Gamble |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day inventory cycles for phenol-derived feedstocks concentrate pricing power among German and Chinese esterification specialists with backward-integrated phenol access, while spot-market buyers absorb benzene derivative volatility through compressed margins.
Pricing Analysis
Technology-generation pricing gaps separate acid-catalyzed legacy esters from enzymatic-process premium grades and next-generation bio-based alternatives. Three-tier pricing structure across premium enzymatic, standard chemical-grade, and economy commodity esters dominates procurement contracts. Price differentiation hinges on REACH compliance certification and volume scale commitments. Pricing pressure stems from sodium benzoate substitution in beverage applications. Food industry buyers exhibit highest price sensitivity; ophthalmic pharmaceutical manufacturers show lowest.
Supply Chain Analysis
Inventory lead-times for p-hydroxybenxybenzoic acid derivatives stretch 45-75 days for non-integrated buyers. Supply concentrates in Germany, China, and India for esterification capacity. Raw material dependencies center on phenol, methanol, and carboxylic acid feedstocks. Single-source vulnerability runs through benzene derivative supply from integrated petrochemical complexes. Distribution runs through manufacturer-direct technical service teams for cosmetics formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection arrives as digitalized technical documentation platforms enable indie beauty brands to bypass regional distributors, collapsing supplier qualification cycles and redefining advisory value capture.
For Market Incumbents: Consolidate formulation advisory capabilities through captive technical service teams that deliver regulatory dossier management across FDA, ECHA, and SAMR thresholds. Deepen backward integration into phenol feedstock supply to defend margin position against benzene derivative volatility. Prioritize enzymatic esterification capacity expansion in the Rhine-Ruhr corridor to capture green chemistry certification premiums.
For New Entrants and Emerging Players: Anchor in India's CDSCO-registered cosmetic manufacturing clusters under PLI scheme incentives where preservative supply localization lags formulation investment. Target pharmaceutical ophthalmic applications where Pseudomonas coverage requirements block substitution. Deploy digitalized qualification platforms to compress 18-month supplier cycles toward 6-month benchmarks for indie beauty penetration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzymatic esterification sub-segments as biotechnology transitions compress capital requirements for mid-scale producers. Long-term viability favors specialty preservative blend specialists with dual portfolio capability across legacy parabens and bio-based alternatives. Watch ECHA REACH authorization timelines as inflection signal for temporary supply security windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Esterification Capacity Expansion | Lipase-mediated routes in Germany and Japan reduce solvent waste while raising technical barriers for commodity competitors. |
| Backward Integration into Phenol Supply | Captive benzene derivative access insulates margin compression from feedstock volatility swings. |
| Digitalized Technical Documentation Platforms | Compressed qualification cycles from 18 months to 6 months capture indie beauty brand procurement velocity. |
| Dual Portfolio Development | Parallel paraben and bio-based preservative systems address clean-label bifurcation without sacrificing scale economies. |
| Regional Manufacturing Localization | India PLI scheme and China domestic production scaling require preservative supply proximity to formulation hubs. |
Research Methodology
The analysis maps preservative chemistry variants, regulatory compliance thresholds, and end-use performance requirements, each validated through formulation chemists, procurement leads at cosmetics manufacturers, regulatory affairs directors, and specialty chemical distributors. Primary fieldwork combined structured interviews with secondary validation against customs trade data, ECHA substance registration databases, SEC 10-K filings, and CDSCO cosmetic registration records. Bottom-up demand modeling and top-down supply capacity assessments were triangulated for convergence.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include ester chain length, application sector, regulatory compliance tier, and regional production hub. CAGRs were derived from demand elasticity analysis and substitution rate projections. Industry-specific forecast inputs incorporated REACH authorization timeline probabilities and GB standard disclosure rule tightening trajectories.
Material uncertainties — regulatory reclassification events, feedstock price dislocations, and clean-label substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about preservation technology adoption curves and regional manufacturing investment patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Trimer Acid Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Global Potassium Citrate Market
Functional Chemicals
Fumaric Acid Market
Functional Chemicals
Glutaraldehyde Market
Functional Chemicals
Global L-Arginine Market
Functional Chemicals
Acrylamide Monomer Market
Functional Chemicals
Amino Acid Chelates Market
Functional Chemicals
Propylparaben Market
Functional Chemicals
Thiamine Market
Functional Chemicals
Global Peptide Synthesis Market
Functional Chemicals
Phthalimide Market
Functional Chemicals
Glutamine Market
Functional Chemicals
Ortho-Phthalaldehyde Market
Functional Chemicals
Potassium Methylate Market