
 Global Potassium Citrate Market | 2026-2036
Global Potassium Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Potassium Citrate Market Foresight
Buyer concentration in pharmaceutical contract manufacturing is recalibrating procurement volumes across the potassium citrate value chain. Jungbunzlauer Suisse AG leverages its Swiss fermentation infrastructure to dominate European pharmaceutical-grade supply. Gadot Biochemical Industries Ltd anchors Middle Eastern and Asian distribution through its Dead Sea brine extraction operations. Cargill, Incorporated competes via backward integration into corn-derived citric acid feedstock, securing cost advantages in food-grade monohydrate production.
Potassium citrate is the potassium salt of citric acid, typically manufactured through neutralization of citric acid with potassium carbonate or hydroxide to yield a white crystalline powder with pH buffering capacity between 7.5 and 9.0. The compound functions primarily as an alkalizing agent in pharmaceuticals, an acidity regulator in food systems, and a chelating agent in industrial water treatment. Monohydrate grades command premium positioning in pharmaceutical applications where controlled moisture content ensures tablet stability, while anhydrous variants lead food and beverage volumes due to extended shelf-life performance. Powdered formats dominate dietary supplement packaging lines, whereas granular specifications sustain animal feed blending operations where dust control determines handler safety compliance.
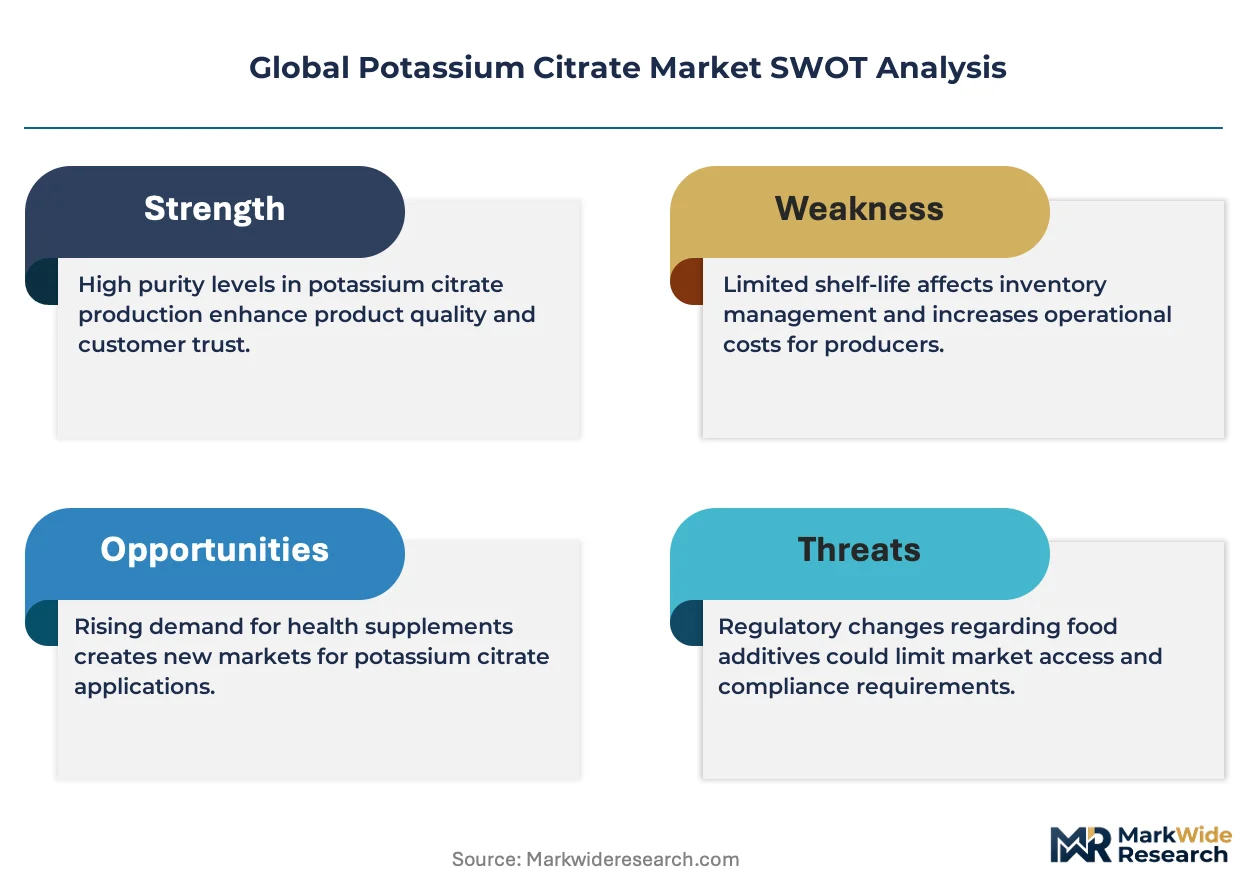
The US FDA enforces Current Good Manufacturing Practice standards for excipient purity that directly determine market access for potassium citrate entering drug formulations. EMA's REACH compliance requirements and the EU Green Deal chemical sustainability frameworks are reshaping manufacturing process disclosures and carbon accounting across European suppliers. China's NMPA and GB standards govern import specifications for citrate salts used in domestic pharmaceutical production. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs, as divergence in heavy metal limits and microbial specifications threatens to fragment qualification protocols and inflate testing costs for multi-territory suppliers.
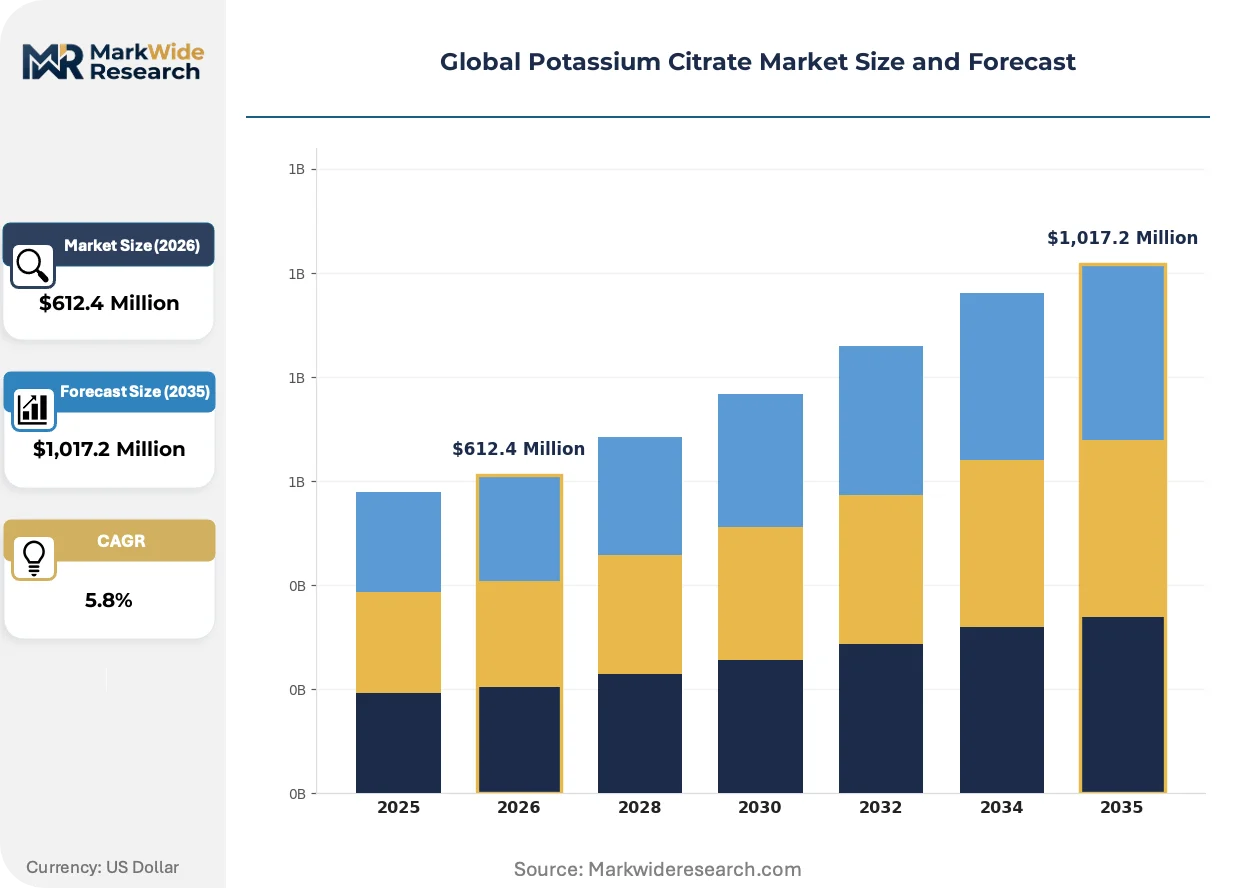
Market Dynamics
Pharmaceutical formulators are consolidating citrate buffer procurement around excipient purity standards tightened by the US FDA and EMA, forcing filtration upgrades that reshape supplier qualification protocols across the value chain.
Growth Catalysts
- Renal Health Therapies:Pharmaceutical contract manufacturers are expanding alkalizing agent volumes for kidney stone prevention formulations, pulling monohydrate-grade demand through hospital and retail pharmacy channels.
- EU Green Deal Chemical Sustainability:REACH compliance disclosures and carbon accounting mandates are accelerating process transparency investments among European suppliers, creating preference premiums for verified low-carbon production.
- Dead Sea Brine Extraction:Israel's mineral processing corridor leverages unique evaporite geology to supply pharmaceutical-grade material with inherent heavy metal purity advantages for injectable formulations.
Market Restraints
- Citric Acid Feedstock Volatility:Corn-derived and fermentation-based citric acid supply faces agricultural commodity price swings that transmit directly to potassium salt production economics.
- Swiss-German Supply Concentration:Jungbunzlauer's fermentation infrastructure and Ludwigshafen's chemical processing cluster control disproportionate European pharmaceutical-grade capacity, creating single-source vulnerability.
- Acetate and Gluconate Substitution:Alternative alkalizing agents compete in parenteral nutrition and dialysis applications where citrate-specific metabolic effects are not clinically required.
Strategic Opportunities
- India's CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are qualifying citrate excipients for export to regulated markets, creating new demand nodes outside traditional supply orbits.
- Cell Culture Media:Biopharmaceutical serum-free formulations are adopting citrate buffering for pH stability in monoclonal antibody production, opening high-specification pharmaceutical-grade volumes.
- China's NMPA Harmonization:Convergence of GB standards with ICH guidelines is streamlining import qualification for foreign suppliers meeting dual USP-EP pharmacopeial specifications.
Industry Challenges
- Pharmacopeial Divergence Testing:Heavy metal limits and microbial specifications still vary between USP, EP, and JP monographs, inflating multi-territory qualification costs for suppliers seeking broad market access.
- Continuous Manufacturing Retrofit:Tablet formulators adopting FDA-promoted continuous processing require citrate excipients with tighter particle size distribution controls than batch-processed material typically delivers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Potassium Citrate Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monohydrate, Anhydrous, Granular, Powdered Application: Pharmaceuticals, Food & Beverage, Agriculture, Chemical Processing End User Industry: Dietary Supplements, Baking, Animal Feed, Water Treatment Packaging Type: Bulk Bags, Drums, Pouches, Cartons |
| Companies Covered | Cargill, Incorporated, Jungbunzlauer Suisse AG, Gadot Biochemical Industries Ltd, Archer Daniels Midland Company, Tate & Lyle PLC, FBC Industries, Inc., Huangshi Xinghua Biochemical Co. Ltd., Dr. Paul Lohmann GmbH KG, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Potassium Citrate Market Shifts & Advancements
Process analytical technology and real-time release testing are compressing batch approval timelines for pharmaceutical-grade material, while sustainability disclosure requirements penetrate deeper into citric acid fermentation supply chains.
Membrane filtration technology is unifying upstream clarification and downstream polishing steps that previously required discrete centrifugation and activated carbon treatments. Pharmaceutical-grade producers in Germany and Switzerland are retrofitting multi-stage tangential flow systems to meet tightened endotoxin specifications. This consolidation is unifying quality assurance workflows and reducing hold times between fermentation harvest and crystallization initiation.
EMA's expanded REACH substance evaluation program is requiring granular process descriptions and worker exposure assessments from citrate salt importers into the European Economic Area. Manufacturers must now submit full supply chain substance flow analyses that extend to corn glucose feedstock origins for fermentation-derived material. Pharmaceutical excipient distributors are responding by pre-qualifying suppliers with complete dossier packages to avoid customs delays at Rotterdam and Hamburg.
Hospital procurement consortia in the United States are consolidating alkalizing agent purchasing through group purchasing organizations that demand certificate of analysis standardization across multiple suppliers. This concentration is displacing fragmented direct-manufacturer relationships that previously allowed formulation-specific custom specifications. The shift is most visible in parenteral product lines where FDA inspection history and drug master file availability now dominate supplier selection criteria over unit price negotiation.
Global Potassium Citrate Market Segmentation
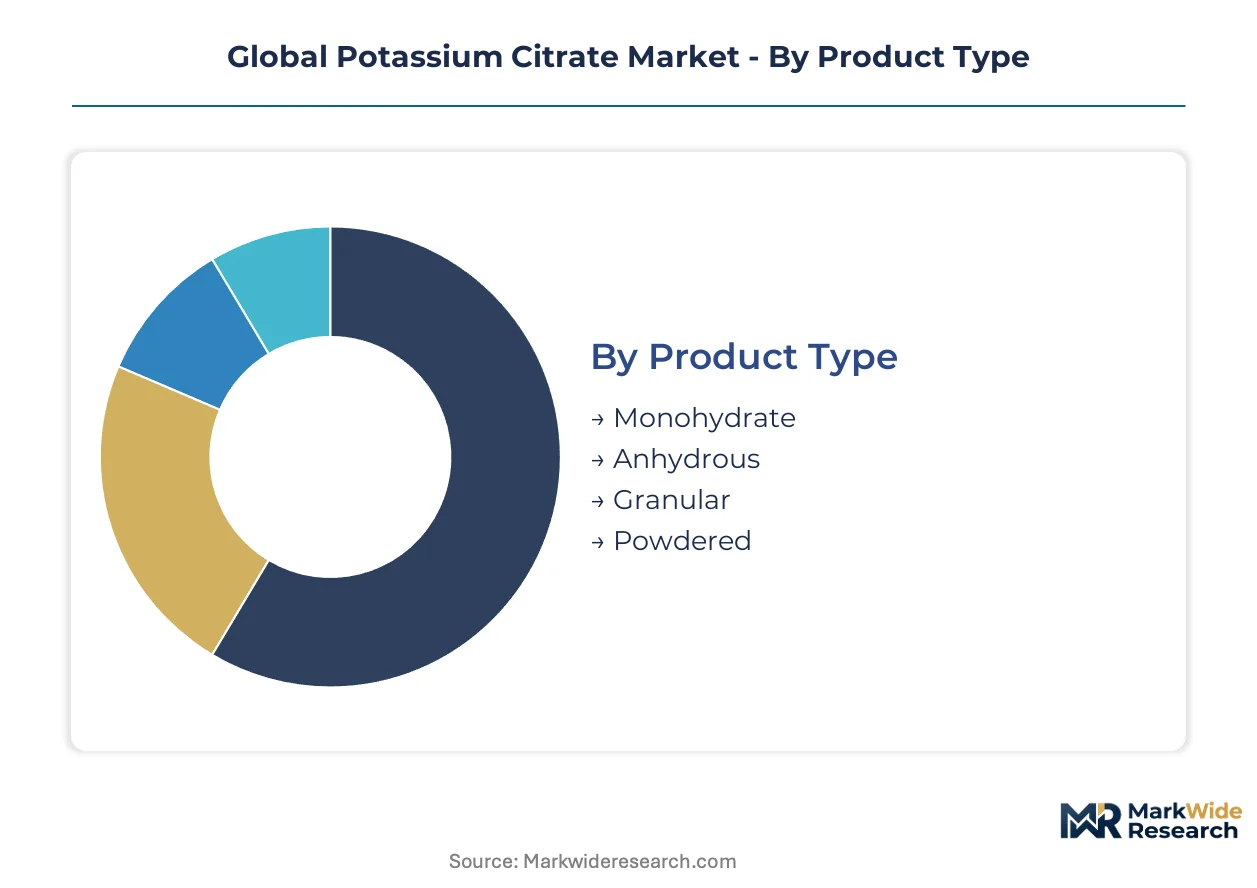
Potassium citrate manufacturers configure production lines around crystallization control and moisture management specifications that vary sharply across pharmaceutical, food, and industrial grades. Segmentation discipline separates premium excipient qualification from commodity chemical economics, with capital allocation decisions locking in multi-year capacity commitments.
Product Type:
Capital intensity peaks in monohydrate production, where controlled crystallization environments and pharmaceutical-grade filtration infrastructure demand the heaviest upfront investment.
- Monohydrate:Crystalline structure binds one water molecule per citrate unit, delivering precise moisture content between 4.0-7.5% that ensures tablet stability in renal health formulations. Hospital procurement consortia in the United States concentrate demand through group purchasing organizations that enforce USP-grade specifications and drug master file availability.
- Anhydrous:Dehydrated powder eliminates residual moisture through thermal processing, extending shelf-life performance for food acidity regulators and beverage fortification. European food manufacturers in Germany's chemical processing corridor around Ludwigshafen absorb the largest volumes, driven by EU Green Deal carbon accounting requirements that favor verified low-carbon fermentation sourcing.
- Granular:Agglomerated particles reduce dust generation during mechanical handling, supporting animal feed blending operations where OSHA-compliant worker safety protocols govern facility design.
- Powdered:Fine particle distribution enables rapid dissolution in dietary supplement sachets and effervescent tablets, with Hyderabad-based CDMOs qualifying material for export to regulated markets.
Monohydrate absorbs the bulk of installed capacity; anhydrous is expanding most quickly.
Application:
Application selection determines regulatory pathway complexity, with pharmaceutical qualification requiring the most extensive documentation and longest approval timelines.
- Pharmaceuticals:Citrate buffers stabilize pH in parenteral nutrition and kidney stone prevention therapies, with EMA's REACH compliance disclosures and FDA Current Good Manufacturing Practice standards forcing filtration upgrades across supplier networks. Jungbunzlauer Suisse AG leverages Swiss fermentation infrastructure to dominate European pharmaceutical-grade supply.
- Food & Beverage:Acidity regulators and potassium fortification agents serve beverage manufacturers and processed food formulators seeking clean-label mineral enhancement. Gadot Biochemical Industries Ltd anchors Middle Eastern distribution through Dead Sea brine extraction operations with inherent heavy metal purity advantages.
- Agriculture:Soil amendment applications leverage citrate chelation properties to improve micronutrient bioavailability in alkaline soils, with demand clustering in Israel's mineral processing corridor.
- Chemical Processing:Industrial water treatment applications deploy citrate salts for scale inhibition and metal ion sequestration in cooling systems and boiler feedwater.
Pharmaceuticals commands the steepest margin premium; food and beverage is climbing the fastest as clean-label fortification accelerates.
End User Industry:
End user selection reveals diverging purity requirements, with injectable pharmaceutical applications demanding the most stringent endotoxin and heavy metal controls.
- Dietary Supplements:Capsule and tablet formulators source powdered grades for mineral fortification products targeting renal health and electrolyte balance positioning.
- Baking:Leavening system acidulants and dough conditioners utilize food-grade anhydrous material in commercial bakery operations.
- Animal Feed:Granular specifications sustain poultry and swine nutrition formulations where dust control determines handler safety compliance and blending uniformity.
- Water Treatment:Municipal and industrial facilities deploy citrate salts for corrosion inhibition and calcium scale prevention in distribution networks.
Dietary supplements concentrate value-chain attention; animal feed is gaining share fastest as livestock mineral nutrition intensifies.
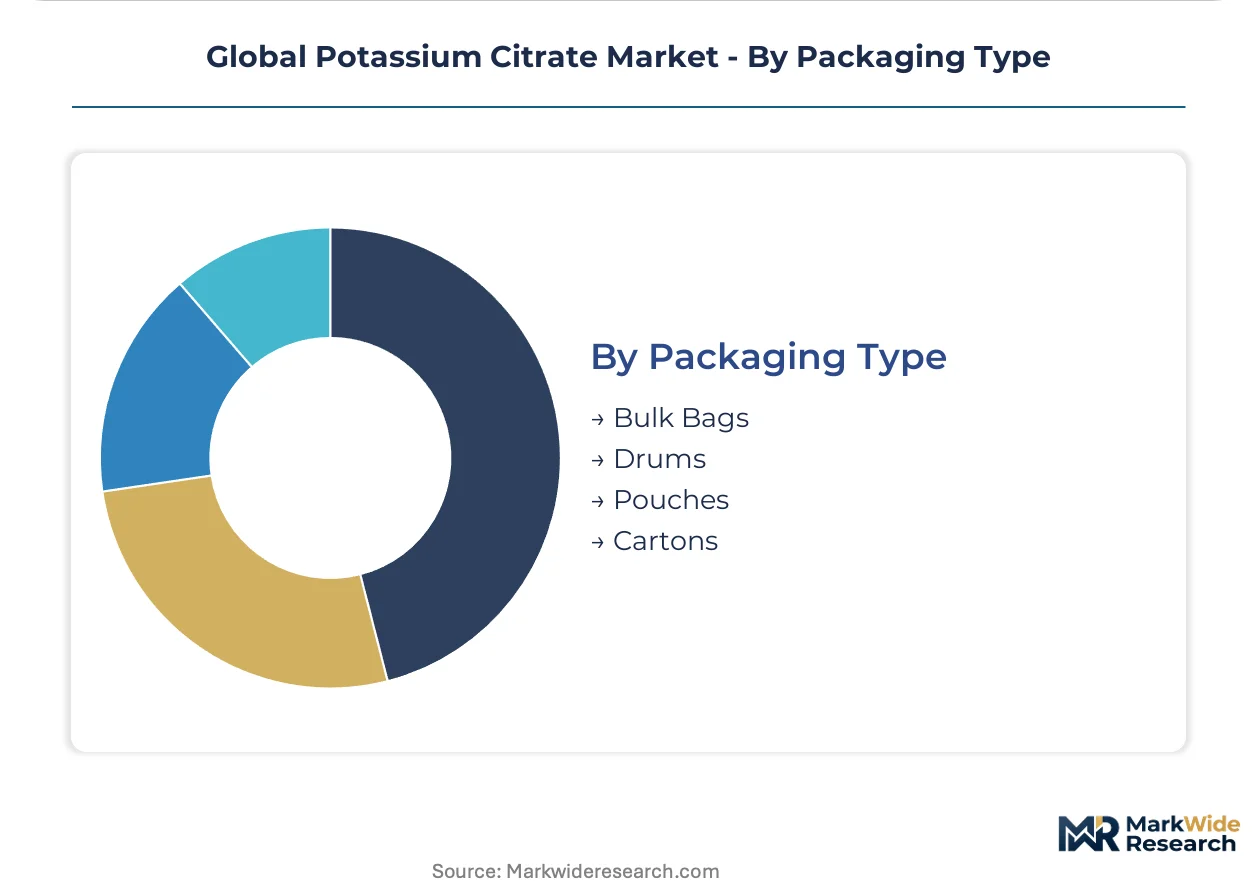
Packaging Type:
Packaging configuration reflects handling economics and contamination risk, with pharmaceutical applications requiring the most rigorous barrier protection and traceability systems.
- Bulk Bags:Flexible intermediate bulk containers serve high-volume food and chemical processing customers with integrated pneumatic conveying systems.
- Drums:Steel and fiber drums protect pharmaceutical-grade material from moisture ingress during extended storage and international shipment.
- Pouches:Multi-layer barrier films support dietary supplement contract packagers with just-in-time dispensing and retail-ready presentation.
- Cartons:Paperboard containers with inner liners serve retail baking and consumer-facing mineral supplement channels.
Bulk bags dominate tonnage throughput; pouches are expanding most quickly as direct-to-consumer supplement channels proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dead Sea evaporite deposits and Swiss fermentation infrastructure anchor geographic supply differentiation, while regulatory tightening across multiple jurisdictions reshapes qualification requirements for citrate salt manufacturers.
United States
Hospital procurement consortia concentrate alkalizing agent purchasing through group purchasing organizations demanding standardized certificates of analysis. FDA Current Good Manufacturing Practice enforcement drives filtration upgrades among excipient suppliers seeking drug master file availability. New Jersey and Pennsylvania chemical corridors host pharmaceutical contract manufacturers expanding citrate buffer volumes for parenteral nutrition formulations.
Germany
Ludwigshafen's chemical processing cluster absorbs the largest European volumes of anhydrous grades for food acidity regulation. EMA REACH compliance disclosures and EU Green Deal carbon accounting mandates accelerate process transparency investments among fermentation-based suppliers. Bavarian pharmaceutical-grade producers retrofit multi-stage tangential flow filtration systems to meet tightened endotoxin specifications for injectable applications.
China
NMPA harmonization with ICH guidelines streamlines import qualification for foreign suppliers meeting dual USP-EP pharmacopeial specifications. Yangtze River Delta contract development and manufacturing organizations qualify citrate excipients for export to regulated markets. Shandong Peninsula fermentation facilities face GB standards scrutiny for heavy metal limits diverging from international monographs.
India
Hyderabad and Ahmedabad CDMOs drive new demand nodes outside traditional supply orbits as they qualify citrate excipients for regulated market export. CDSCO oversight of pharmaceutical raw material imports intensifies testing protocols for microbial specifications. Gujarat's specialty chemical corridor attracts investment in pharmaceutical-grade crystallization capacity serving dietary supplement formulators.
Israel
Dead Sea brine extraction operations leverage unique evaporite geology to supply pharmaceutical-grade material with inherent heavy metal purity advantages. Ministry of Health pharmaceutical regulations align with European pharmacopeial standards for regional export qualification. Negev mineral processing facilities expand output for injectable formulation markets where citrate-specific metabolic effects are clinically preferred.
Global Potassium Citrate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade specialization and regional distribution partnerships. The supplier base concentrates around fermentation-derived and mineral-extraction archetypes with divergent feedstock economics. Three strategic archetypes dominate: Swiss-German fermentation specialists, Dead Sea brine processors, and agricultural commodity-integrated multinationals. Competitive moves center on backward integration into citric acid feedstock and multi-territory pharmacopeial qualification investments.
Within the fermentation-specialist tier, Jungbunzlauer Suisse AG represents European pharmaceutical-grade supply concentration through Swiss infrastructure. Gadot Biochemical Industries Ltd exemplifies mineral-extraction positioning anchored to Dead Sea geology. Cargill, Incorporated occupies the agricultural-commodity-integrated archetype with corn-derived feedstock control. These three entities illustrate how geographic feedstock advantages translate into differentiated qualification capabilities across USP, EP, and JP monograph compliance.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Jungbunzlauer Suisse AG |
| Gadot Biochemical Industries Ltd |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| FBC Industries, Inc. |
| Huangshi Xinghua Biochemical Co. Ltd. |
| Dr. Paul Lohmann GmbH KG |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Backward integration into citric acid feedstock anchors both supply security and pricing power for fermentation-based producers, with corn-derived raw material control insulating Jungbunzlauer and Cargill from agricultural commodity swings that transmit directly to potassium salt production economics. This upstream positioning allows integrated players to maintain margin stability while spot-market-dependent competitors face cost compression during harvest volatility.
Pricing Analysis
Certificate of analysis standardization bundles quality assurance with base product pricing, unbundling customization for formulation-specific particle size distributions or endotoxin specifications. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates USP-certified monohydrate from commodity anhydrous material, with pharmaceutical buyers showing lowest price sensitivity due to drug master file availability requirements and FDA inspection history weighting. Pricing pressure stems from hospital procurement consortia consolidating alkalizing agent purchasing through group purchasing organizations that displace fragmented direct-manufacturer relationships.
Supply Chain Analysis
Container freight rates from Israel's Dead Sea processing corridor and Switzerland's Basel pharmaceutical hub determine landed cost differentials for European and Asian buyers. Supply concentrates in Germany's Ludwigshafen chemical cluster, Switzerland's Jungbunzlauer fermentation infrastructure, and Israel's Negev mineral processing facilities, with raw material dependencies spanning corn glucose feedstock, Dead Sea brine evaporites, and potassium carbonate reagents. Single-source vulnerability in Swiss-German pharmaceutical-grade capacity creates structural risk, while distribution runs through Rotterdam and Hamburg port pre-qualification hubs for EMA REACH compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory tightening across FDA, EMA, and NMPA jurisdictions is forcing filtration upgrades and pharmacopeial qualification investments that weaker capitalized suppliers cannot absorb, accelerating consolidation toward integrated fermentation specialists and mineral-extraction incumbents.
For Market Incumbents: Deploy multi-stage tangential flow filtration retrofits to meet tightened endotoxin specifications for injectable applications, while securing drug master file availability across USP, EP, and JP monographs to defend against acetate and gluconate substitution threats in parenteral nutrition formulations. Capacity addition in India's Gujarat specialty chemical corridor captures CDMO export demand outside traditional supply orbits. For New Entrants and Emerging Players: Launch via pharmaceutical-grade specialization targeting cell culture media buffering for monoclonal antibody production, where serum-free formulation adoption creates specification gaps incumbent fermentation suppliers have not fully addressed. White-space concentration sits in Hyderabad and Ahmedabad CDMO qualification programs for regulated market export, with go-to-market leverage through pre-qualified supplier dossier packages that avoid Rotterdam customs delays. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of Dead Sea brine extraction operations with inherent heavy metal purity advantages for injectable formulations, as mineral-extraction positioning commands premium multiples over fermentation commodity exposure. Long-term viability favors suppliers with verified low-carbon production credentials under EU Green Deal carbon accounting mandates. Watch for NMPA-ICH harmonization completion as inflection signal for China import qualification streamlining.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citric Acid Feedstock | Corn-derived raw material control insulates margin stability from agricultural commodity price transmission. |
| Multi-Territory Pharmacopeial Qualification Investment | Dual USP-EP drug master file availability unlocks hospital procurement consortia and CDMO export channels. |
| Continuous Manufacturing Particle Size Retrofit | Tighter distribution controls meet FDA-promoted tablet processing requirements displacing batch material. |
| Dead Sea Brine Extraction Capacity Expansion | Evaporite geology delivers inherent heavy metal purity for injectable formulation preference premiums. |
| REACH Compliance Supply Chain Disclosure | Granular process descriptions and carbon accounting secure EMA import clearance at Rotterdam and Hamburg. |
Research Methodology
Trade databases, pharmacopeial monograph filings, and customs export records formed the secondary backbone, combined with primary interviews spanning pharmaceutical contract manufacturing procurement leads, citric acid fermentation plant managers, EMA regulatory affairs specialists, and hospital group purchasing organization contracts managers. Bottom-up volume triangulation across monohydrate, anhydrous, granular, and powdered product grades reconciled against top-down value estimates derived from excipient distributor pricing disclosures.
Historical trendline analysis of renal health therapy formulation volumes, beverage fortification adoption patterns, and animal feed mineral nutrition intensity informed baseline calibration across the projection horizon. Segmentation dimensions modeled include pharmaceutical grade tier, food and beverage end-use industry, packaging format configuration, and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand drivers incorporating FDA Current Good Manufacturing Practice enforcement trajectories and EU Green Deal carbon accounting implementation timelines.
Citric acid feedstock price volatility, pharmacopeial divergence between USP and EP heavy metal limits, and NMPA regulatory harmonization delays are the dominant revision risks that could compress or extend forecast ranges. Stakeholders should weight assumptions against their own operating context and supplier qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Succinic Acid Market
Functional Chemicals
Ortho-Phthalaldehyde Market
Functional Chemicals
Potassium Methylate Market
Functional Chemicals
Amino Acid Chelates Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
Europe Fumaric Acid Market
Functional Chemicals
Sodium Citrate Market
Functional Chemicals
2-Propylheptanol Market
Functional Chemicals
Sodium Methylate Market
Functional Chemicals
Asia-Pacific Amino Acids Market
Functional Chemicals
Glutamine Market
Functional Chemicals
Imidazole Market
Functional Chemicals
Serine Amino Acid Market
Functional Chemicals
Furan Dicarboxylic Methyl Ester (FDME) Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
L-Citrulline Market