
 South Korea Methanol Market | 2026-2036
South Korea Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Methanol Market Insights
Industrial-grade methanol purity specifications is unwinding legacy procurement patterns across South Korean chemical corridors. Lotte Chemical leverages its Yeosu complex integration to sustain captive methanol supply for formaldehyde derivatives. Hyundai Chemical anchors large-volume contracts with domestic energy utilities seeking cleaner-burning fuel alternatives. SK Global Chemical differentiates through specialized solvent-grade output targeting pharmaceutical and electronics precursors.
Methanol is a light, volatile alcohol with chemical formula CH3OH, typically manufactured via steam methane reforming or coal gasification followed by catalytic synthesis; it serves as foundational feedstock for formaldehyde, acetic acid, and methyl tert-butyl ether production. Chemical Methanol dominates volume flows into plastics and resin manufacturing, while Fuel Methanol captures policy-driven substitution interest from power generators and marine bunkering trials. Energy Sector end users command the largest demand block, though Automotive Sector interest in methanol-to-hydrogen pathways is expanding pilot offtake.
MFDS maintains purity and handling standards for methanol entering pharmaceutical and consumer goods channels, while KGS enforces pressure vessel and pipeline safety codes across Korea Gas Corporation distribution networks. The country's national environmental regulator imposes emission caps that push industrial boilers toward methanol blending. Stakeholders must track KOGAS infrastructure buildout and evolving carbon intensity rules to secure feedstock positions.
Market Dynamics
Korea Gas Corporation pipeline expansions and MFDS purity mandates are compressing informal supply channels while formalizing methanol procurement around certified, traceable bulk delivery systems.
Growth Catalysts
- Formaldehyde derivative demand:Plastics manufacturers in Ulsan and Yeosu clusters are expanding methanol offtake for resin and composite feedstock production.
- MFDS pharmaceutical-grade protocols:Tightened purity specifications for solvent applications are redirecting technical-grade supply toward higher-margin pharmaceutical precursor channels.
- Marine bunkering trials:Port authorities in Busan and Incheon are piloting methanol fuel infrastructure for container shipping decarbonization pathways.
Market Restraints
- Natural gas feedstock volatility:Steam methane reforming economics hinge on LNG import pricing from Qatar and Australia, exposing margins to currency and commodity swings.
- Yeosu-Ulsan supply concentration:Over seventy percent of domestic production capacity sits within fifty kilometers of coastline, creating single-point vulnerability to typhoon disruption.
- Coal-to-methanol substitution limits:Carbon intensity benchmarks under national emission trading schemes restrict coal gasification pathway expansion despite feedstock cost advantages.
Strategic Opportunities
- Automotive methanol-to-hydrogen conversion:Hyundai Motor Group pilot programs are validating onboard reforming systems for fuel cell commercial vehicle deployment.
- Electronics-grade solvent certification:Semiconductor fabs in Pyeongtaek and Icheon are qualifying ultra-high-purity methanol for photoresist stripping and wafer cleaning applications.
- KOGAS hydrogen blending infrastructure:Pipeline network retrofits for methanol-hydrogen co-transport are creating dedicated offtake agreements with power sector buyers.
Industry Challenges
- Process safety engineer scarcity:Specialized expertise for high-pressure catalytic synthesis operations is concentrating among retiring cohorts at established Yeosu complexes.
- Legacy storage tank retrofit costs:KGS pressure vessel code updates are forcing substantial capital expenditure for corrosion-resistant lining replacement across coastal terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Methanol Market |
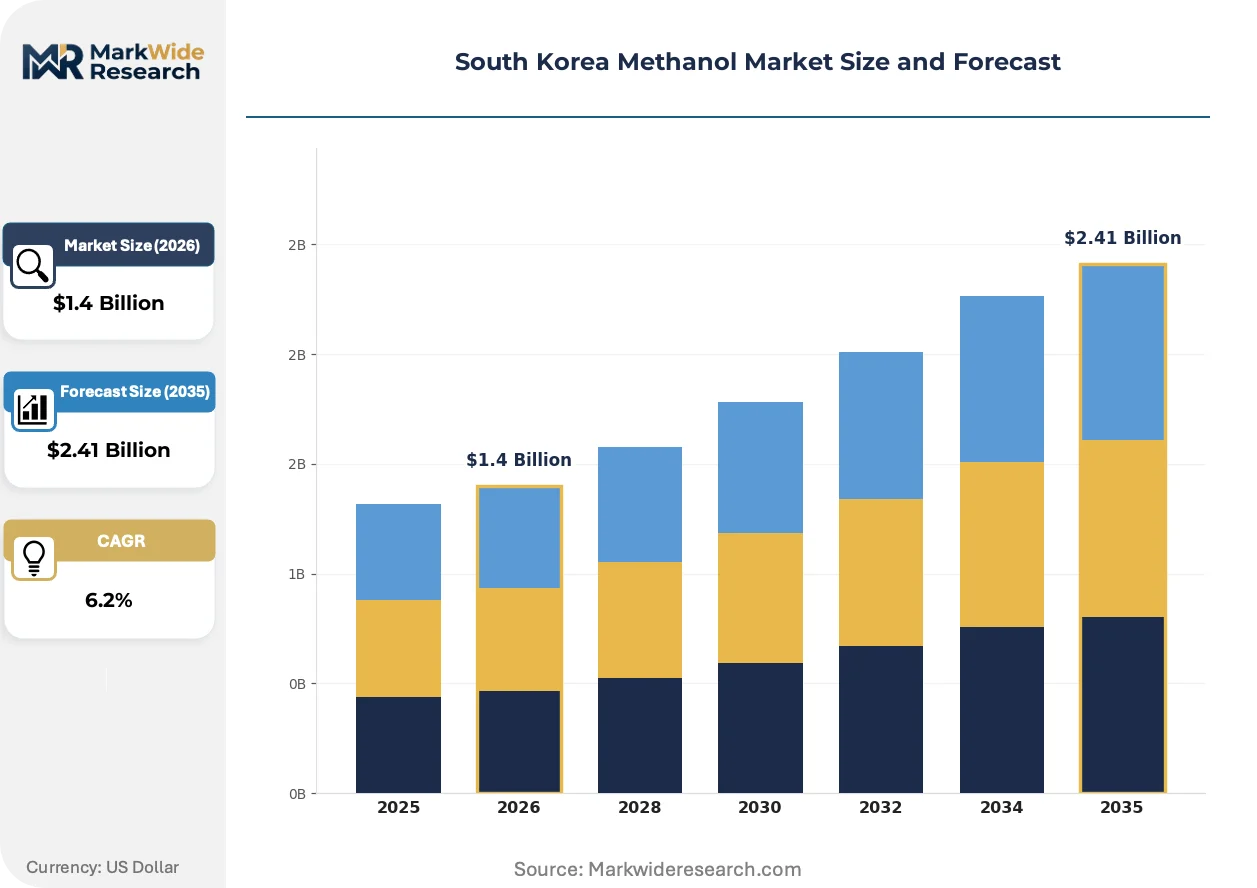
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Methanol, Chemical Methanol, Industrial Methanol, Acetic Acid Application: Energy, Solvents, Plastic Production, Pharmaceuticals End User: Energy Sector, Chemical Industries, Automotive Sector, Consumer Goods Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail Outlets |
| Companies Covered | Daelim Industrial, LG Chem, Korea Gas Corporation, Hyundai Chemical, Korea Petrochemical Ind, Lotte Chemical, SK Global Chemical, Lotte Advanced Materials, Kumho P and B Chemicals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Methanol Market Trends and Innovations
Electrification of methanol synthesis and carbon capture integration are reconfiguring process economics while regulatory carbon accounting tightens around conventional production pathways.
Electrolysis-fed methanol synthesis is displacing conventional steam methane reforming in pilot installations. Power utilities seeking grid-balancing revenue streams are offtaking renewable electricity for e-methanol demonstration plants. This pathway is displacing fossil-derived product in premium fuel certification schemes where lifecycle carbon intensity determines contract eligibility.
National emission trading scheme expansion is tightening free allowance allocations for chemical sector participants. Industrial boiler operators face escalating carbon cost exposure that accelerates methanol blending trials for compliance purposes. Refinery-methanol complexes in Ulsan are responding by integrating carbon capture units to preserve margin structures under tightening caps.
Long-term contracting is supplanting spot market purchasing among formaldehyde derivative manufacturers. Chemical conglomerates are negotiating five-year supply agreements with fixed-volume, indexed-price structures to hedge feedstock volatility. This pattern is most visible in Yeosu cluster procurement where integrated producers seek captive supply security for downstream acetic acid expansion projects.
South Korea Methanol Market Segmentation
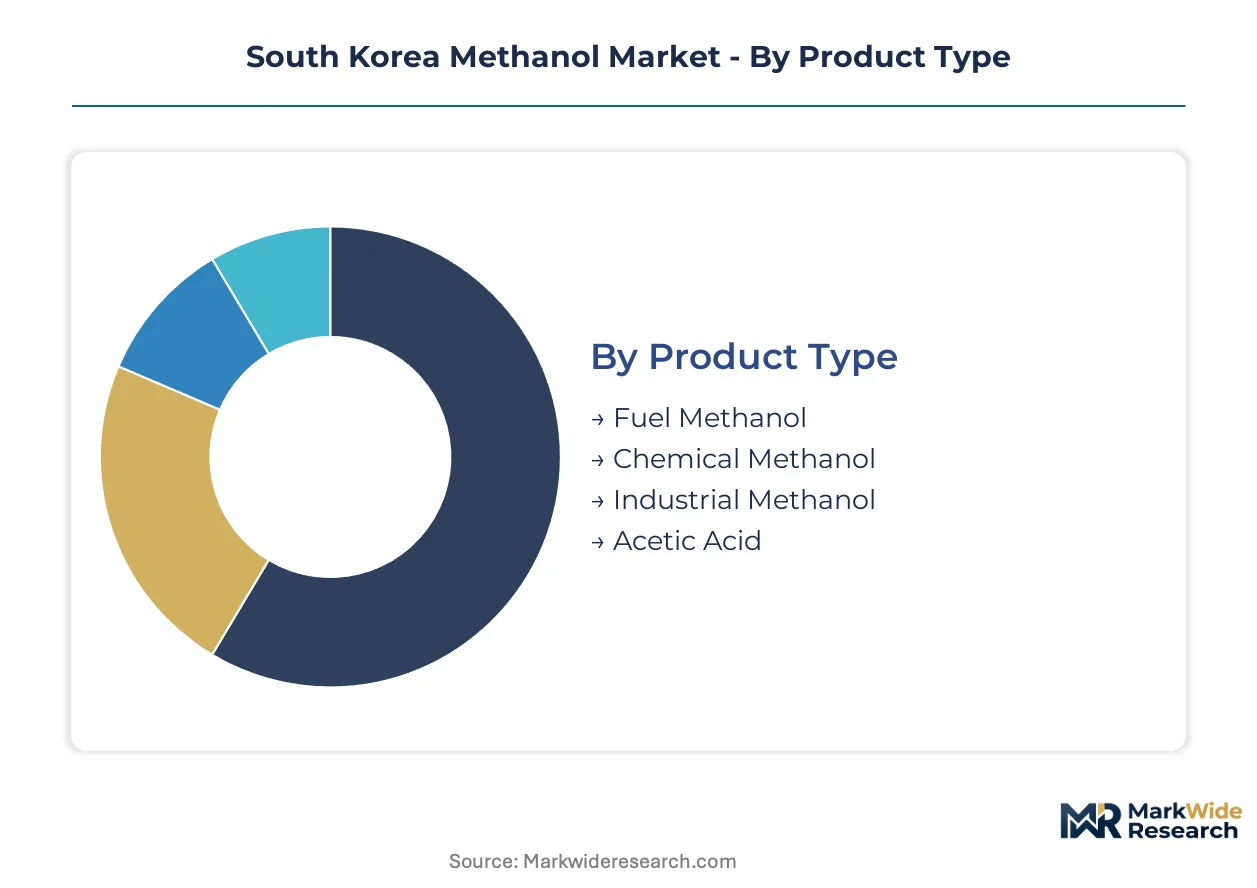
Segmentation reveals how methanol demand fragments across purity grades and end-use specifications in South Korea. Each category exposes distinct margin pressures and regulatory exposure that reshape procurement patterns.
Product Type:
Fuel Methanol faces the strongest substitution threat from LNG and ammonia bunkering alternatives, while chemical grades defend position through specification lock-in.
- Chemical Methanol:High-purity feedstock meeting MFDS pharmaceutical solvent standards and acetic acid synthesis requirements. Demand concentrates in Yeosu and Ulsan petrochemical clusters where integrated complexes consume captive volumes for formaldehyde derivative chains.
- Fuel Methanol:Blending-grade product for industrial boilers and marine bunkering trials, characterized by lower purity tolerance and carbon intensity benchmarking. Busan port authorities pilot infrastructure for container shipping decarbonization, though ammonia competition threatens long-term offtake.
- Industrial Methanol:Technical-grade solvent for coatings and adhesives manufacturing, typically sourced through distributor networks rather than direct refinery contracts.
- Acetic Acid:Derivative product segment capturing methanol feedstock conversion for vinyl acetate and PTA production, tied to textile and packaging resin demand cycles.
Chemical Methanol retains volume leadership; Fuel Methanol holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity energy buyers from premium pharmaceutical and electronics solvent purchasers.
- Energy:Power utilities and marine operators seeking lower-carbon combustion alternatives, subject to national emission trading scheme carbon cost exposure. KOGAS pipeline infrastructure investments in Ulsan and Incheon anchor bulk delivery systems for this segment.
- Pharmaceuticals:Ultra-high-purity solvent applications for active pharmaceutical ingredient synthesis and excipient production, governed by MFDS GMP certification requirements and batch traceability mandates.
- Plastic Production:Formaldehyde resin feedstock for construction and automotive composite materials, concentrated in downstream manufacturing corridors near Yeosu.
- Solvents:General-purpose industrial degreasing and coating applications, competing with petrochemical alternatives on price and volatility.
Energy commands the largest volume block; Pharmaceuticals climbs the fastest on margin expansion.
End User:
Customer type divergence splits procurement between integrated chemical conglomerates and fragmented automotive and consumer goods assemblers.
- Energy Sector:Korea Gas Corporation utility networks and independent power producers blending methanol for emission compliance. Long-term contracting dominates with five-year indexed supply agreements replacing spot purchasing.
- Chemical Industries:Lotte Chemical and SK Global Chemical operations consuming captive methanol for acetic acid and formaldehyde derivative production, representing the most concentrated demand block.
- Automotive Sector:Hyundai Motor Group pilot programs for methanol-to-hydrogen onboard reforming systems in commercial fuel cell vehicles.
- Consumer Goods:Household product and personal care manufacturers sourcing pharmaceutical-grade solvent for fragrance and preservative applications.
Chemical Industries anchor volume concentration; Automotive Sector gains share fastest on technology validation.
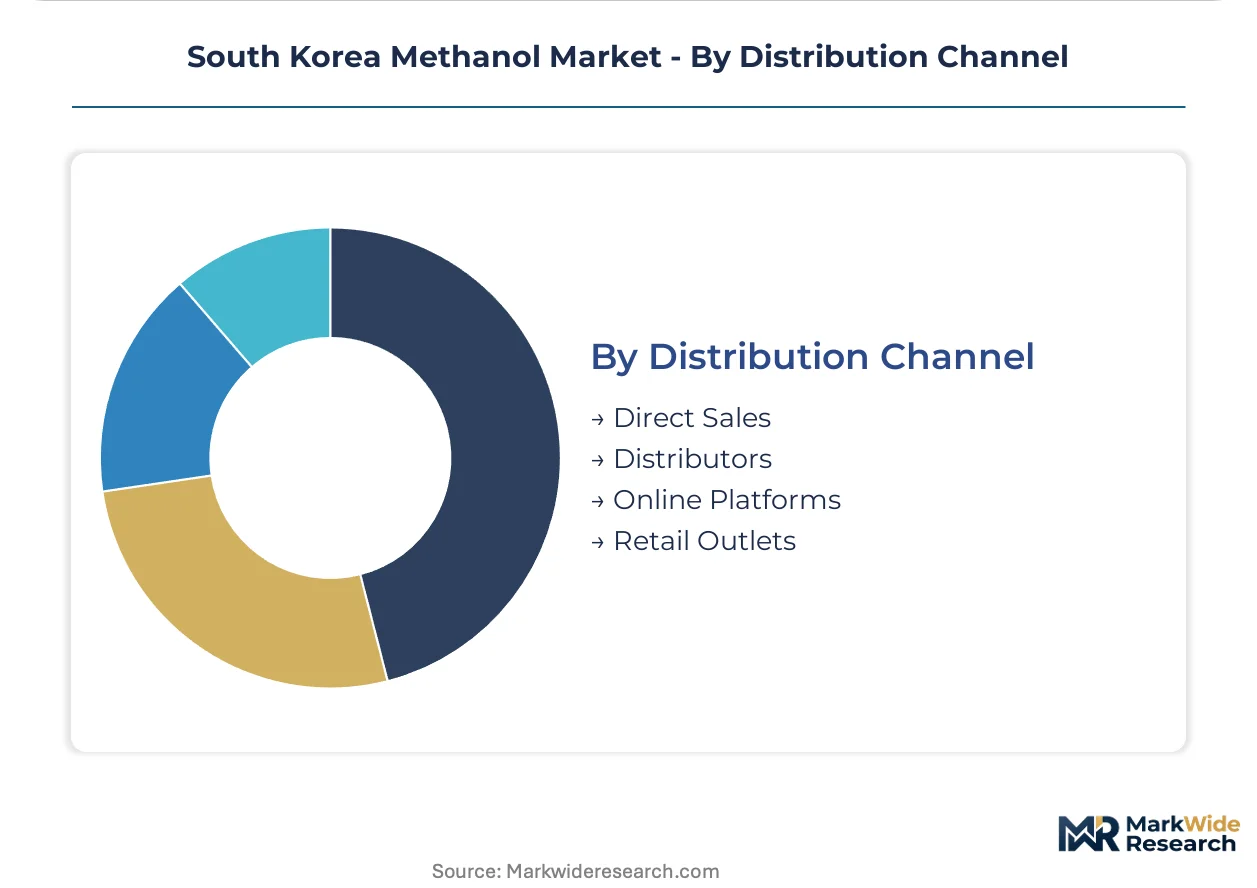
Distribution Channel:
Supply concentration along the southern coastline dictates logistics economics and channel selection for each customer tier.
- Direct Sales:Refinery-complex producers supplying integrated chemical manufacturers through dedicated pipeline and vessel delivery, capturing seventy percent of domestic volume flows.
- Distributors:Regional bulk handlers serving mid-scale pharmaceutical and electronics solvent buyers with certified storage and batch documentation.
- Online Platforms:Emerging procurement channel for small-volume industrial solvent purchasers, limited by hazardous material shipping regulations.
- Retail Outlets:Specialty chemical suppliers serving laboratory and artisan manufacturing segments with packaged product.
Direct Sales dominates volume leadership; Distributors expand most quickly on pharmaceutical qualification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Methanol production capacity clusters along South Korea's southern coastline, with Yeosu and Ulsan anchoring over seventy percent of domestic output. This geographic concentration shapes logistics economics and creates single-point exposure to coastal weather disruption. Regional demand patterns split between petrochemical feedstock consumption and emerging fuel-blending applications.
Seoul Capital Area
Pharmaceutical manufacturers and electronics assemblers drive high-purity methanol demand for solvent applications. MFDS GMP certification requirements govern batch traceability for active pharmaceutical ingredient synthesis. Pyeongtaek semiconductor fabs qualify ultra-high-purity grades for photoresist stripping, creating premium-tier procurement channels distinct from bulk chemical flows.
Busan-Ulsan Corridor
Integrated refinery-methanol complexes serve formaldehyde derivative production for automotive and construction plastics. Korea Gas Corporation pipeline infrastructure anchors bulk delivery systems for power sector blending trials. Ulsan petrochemical clusters consume captive volumes for acetic acid expansion, locking in long-term supply contracts with indexed pricing structures.
Yeosu Industrial Complex
Lotte Chemical operations exemplify backward integration into captive methanol supply for resin manufacturing. National emission trading scheme caps push boiler operators toward methanol blending for compliance. The coastal complex faces KGS pressure vessel code updates requiring corrosion-resistant storage retrofits.
Daegu-Gyeongbuk
Textile and packaging resin manufacturers source methanol feedstock for PTA and vinyl acetate production. Regional distributors serve mid-scale solvent buyers with certified storage and documentation. Daegu-based coatings formulators consume technical-grade product for adhesives manufacturing.
Gwangju-Honam
Marine bunkering trials at Mokpo port test methanol fuel infrastructure for coastal shipping decarbonization. Agricultural chemical blenders source industrial-grade product for pesticide formulation. The Honam region's smaller demand base relies on distributor networks rather than direct refinery contracts.
South Korea Methanol Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the South Korea methanol market. Integrated petrochemical conglomerates dominate volume production through captive consumption models, while specialized distributors capture margin in pharmaceutical and electronics qualification channels. Three archetypes define competitive positioning: refinery-integrated producers with backward control over feedstock, regional bulk handlers with certified storage infrastructure, and technology licensors enabling process efficiency gains. Capacity expansion and long-term contracting represent the dominant competitive moves, with players securing five-year indexed supply agreements to hedge feedstock volatility.
Among integrated chemical producers, Lotte Chemical, Hyundai Chemical, and SK Global Chemical exemplify the refinery-complex archetype. Lotte Chemical occupies a position within the Yeosu cluster where captive methanol supply feeds formaldehyde derivative chains. Hyundai Chemical anchors large-volume contracting relationships with domestic energy utilities. SK Global Chemical sits within the specialized solvent-grade tier, targeting pharmaceutical and electronics precursor applications where MFDS purity mandates create specification lock-in.
| Leading Market Players |
|---|
| Daelim Industrial |
| LG Chem |
| Korea Gas Corporation |
| Hyundai Chemical |
| Korea Petrochemical Ind |
| Lotte Chemical |
| SK Global Chemical |
| Lotte Advanced Materials |
| Kumho P and B Chemicals |
| Others |
Pricing and Supply Chain Analysis
Long-term indexed supply agreements with Korea Gas Corporation utility networks lock in both feedstock access and price visibility for formaldehyde derivative manufacturers, compressing spot market liquidity while formalizing procurement around five-year contracting structures.
Pricing Analysis
MFDS dictates the pricing tier structure across pharmaceutical-grade, electronics-grade, and industrial-grade methanol segments. Three-tier pricing structure across premium, standard, and economy levels separates ultra-high-purity solvent certified for semiconductor fabs from technical-grade boiler fuel. Cost compression in fuel-grade supply is intensifying because ammonia bunkering trials threaten methanol's marine fuel positioning. Energy utilities demonstrate highest price sensitivity due to carbon cost exposure under emission trading schemes, while pharmaceutical manufacturers accept premium pricing for batch-traceable GMP certification.
Supply Chain Analysis
Inventory cycles at Yeosu and Ulsan coastal terminals run 15-20 days for integrated chemical producers, extending to 45 days for distributor-served pharmaceutical buyers. Domestic production draws from natural gas feedstock anchored in Qatar and Australia LNG contracts, with coal gasification capacity constrained by carbon intensity benchmarks. Single-source vulnerability concentrates in the Busan-Ulsan corridor where typhoon disruption risks pipeline and vessel delivery. Distribution runs through KOGAS pipeline networks for bulk energy sector offtake, with certified distributors handling pharmaceutical and electronics solvent qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea methanol market sits at a platform-economics inflection where KOGAS hydrogen blending infrastructure creates interoperability between methanol carriers and hydrogen distribution networks, rewiring competitive moats around pipeline access rather than standalone production scale.
For Market Incumbents: Compound backward integration into carbon capture units at Ulsan refinery-methanol complexes to preserve margin structures under tightening emission trading caps. Secure five-year indexed supply agreements with formaldehyde derivative expansion projects before ammonia bunkering alternatives mature. Lock in process safety engineering talent through structured knowledge transfer programs as retiring cohorts concentrate at Yeosu facilities. For New Entrants and Emerging Players: Lead with electronics-grade solvent certification for Pyeongtaek semiconductor fabs, where ultra-high-purity methanol demand outpaces qualified domestic supply. Target pharmaceutical distributor networks serving Seoul Capital Area API manufacturers, bypassing integrated chemical conglomerates' captive supply dominance. Anchor go-to-market strategy around MFDS GMP batch-traceability documentation that incumbent industrial-grade producers lack. For Investors and Strategic Acquirers: Regional bulk handlers with certified storage infrastructure and pharmaceutical qualification capabilities represent the most defensible acquisition archetype, capturing margin expansion as solvent-grade demand fragments from commodity chemical flows. Long-term viability hinges on positioning for hydrogen economy interoperability through KOGAS pipeline network retrofits. Watch Hyundai Motor Group methanol-to-hydrogen pilot validation as inflection signal for automotive sector demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Preserves margin structures at Ulsan refinery-methanol complexes under tightening emission trading scheme caps. |
| Electronics-Grade Certification | Unlocks premium-tier procurement channels with Pyeongtaek semiconductor fabs for photoresist stripping applications. |
| KOGAS Pipeline Access Agreement | Secures dedicated offtake positioning for hydrogen blending infrastructure retrofits across Ulsan and Incheon networks. |
| Process Safety Talent Retention | Mitigates operational risk as specialized high-pressure catalytic synthesis expertise concentrates among retiring cohorts. |
| Long-Term Supply Contracting | Locks in formaldehyde derivative demand from Yeosu acetic acid expansion projects before feedstock volatility intensifies. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with petrochemical plant managers, downstream formaldehyde derivative procurement leads, KOGAS utility planning officers, pharmaceutical solvent qualification specialists, and marine bunkering infrastructure developers. Secondary validation drew from Korea Customs Service trade statistics, Korea Petrochemical Industry Association capacity reports, MFDS regulatory filings, and KGS pressure vessel certification databases. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning purity grade tier, end-use industry application, distribution channel structure, and regional production hub concentration. CAGRs were derived from trend extrapolation of historical demand elasticities and forward projection of regulatory-driven substitution effects. Forecast inputs incorporated LNG import pricing volatility assumptions, carbon intensity benchmark evolution, and marine fuel certification pathway competition between methanol and ammonia alternatives.
Forecasts assume regulatory continuity in MFDS pharmaceutical-grade protocols and national emission trading scheme allocation methodologies; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Benzoyl Alcohol Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Benzhydrol Market
Chemicals
Concrete Surface Treatment Chemicals Market
Chemicals
India Anhydrous Hydrogen Fluoride Market
Chemicals
Bronopol Market
Chemicals
Calcium Carbide Market
Chemicals
Solder Flux Market
Chemicals
Fine Chemicals Market
Chemicals
Chromium Trioxide Market
Chemicals
Africa Mining Chemicals Market
Chemicals
Coal Tar Market
Chemicals
Methanol to Gasoline Market
Chemicals
Methidathion (CAS 950-37-8) Market
Chemicals
Ferric Fluoride Market