
 Canada White Glove Delivery Service Market | 2026-2036
Canada White Glove Delivery Service Market Size, Share, and Industry Trends Forecast 2026-2036
Canada White Glove Delivery Service Market Insights
Ontario's warehouse expansion is rewriting last-mile logistics economics across the country. XPO leverages its cross-border network to anchor fulfillment capacity in the Toronto-Montreal corridor. SEKO Logistics specializes in healthcare-compliant white glove handling, sustaining premium positioning through temperature-validated fleets. FedEx competes on brand strength and integrated tracking infrastructure, extending its express dominance into high-touch delivery segments.
Canada white glove delivery service encompasses premium freight handling involving specialized equipment, trained personnel, and inside-home or inside-facility placement with debris removal, typically requiring liftgate trucks, two-person crews, and real-time appointment scheduling. The service serves industries where product damage tolerance approaches zero and customer experience directly ties to brand equity. Residential service dominates volume as e-commerce furniture and appliance purchases normalize white glove expectations, while medical delivery commands the highest margins due to Health Canada compliance burdens and cold-chain requirements. Same-day and scheduled models are gaining fastest in urban corridors where density justifies dedicated fleet investment, though next-day retains scale advantages in secondary markets.
Health Canada, Transport Canada, and provincial occupational safety regulators shape fleet specifications, driver certification, and liability frameworks for inside-delivery operations. Compliance with the Transportation of Dangerous Goods Regulations and provincial workers compensation requirements elevates operational costs while creating barriers to informal competitors. Stakeholders must monitor how carbon pricing mechanisms and zero-emission vehicle mandates reshape fleet procurement decisions and route economics across provincial jurisdictions.
Market Dynamics
Healthcare infrastructure concentration in Ontario's Golden Horseshoe is compressing last-mile delivery radiuses while elevating compliance burdens for temperature-validated fleets serving hospital networks and specialty clinics.
Growth Catalysts
- Health Canada TDG Regulations:Mandated chain-of-custody documentation and cold-chain protocols for medical device transport are forcing healthcare facilities toward certified white glove providers with validated fleet capabilities.
- E-commerce furniture penetration:Urban condominium dwellers in Vancouver and Toronto now expect inside-home placement and debris removal as standard for large-format purchases, normalizing premium service tiers.
- Quebec's aging population density:Montreal's concentration of seniors in high-rise residential towers creates concentrated demand for assisted delivery with assembly and installation services.
Market Restraints
- Diesel price volatility:Fuel represents 28-34% of operating costs for liftgate-equipped fleets, with carbon pricing mechanisms in British Columbia and Alberta adding incremental pressure per kilometer.
- Driver certification scarcity:Provincial workers compensation requirements for two-person crew operations and dangerous goods handling create recruitment bottlenecks in secondary markets.
- Real estate concentration:Toronto-Montreal corridor warehousing costs have doubled since 2021, compressing margins for regional operators without cross-border freight diversification.
Strategic Opportunities
- Alberta's energy sector pivot:Calgary and Edmonton medical device hubs serving oil patch occupational health clinics remain underserved by Health Canada-certified white glove specialists.
- Zero-emission vehicle mandates:British Columbia's ZEV mandate and federal carbon pricing create first-mover advantage for electric liftgate fleet operators securing provincial green procurement contracts.
- Pharmacy network consolidation:Shoppers Drug Mart and Rexall centralization of specialty medication distribution creates contracted white glove opportunities for temperature-controlled last-mile segments.
Industry Challenges
- Two-person crew coordination:Synchronized scheduling of certified handlers for inside-delivery operations generates 15-20% deadhead time versus standard freight, eroding asset utilization rates.
- Real-time tracking integration:Hospital procurement departments demand API-connected visibility platforms that legacy dispatch systems cannot support without substantial middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada White Glove Delivery Service Market |
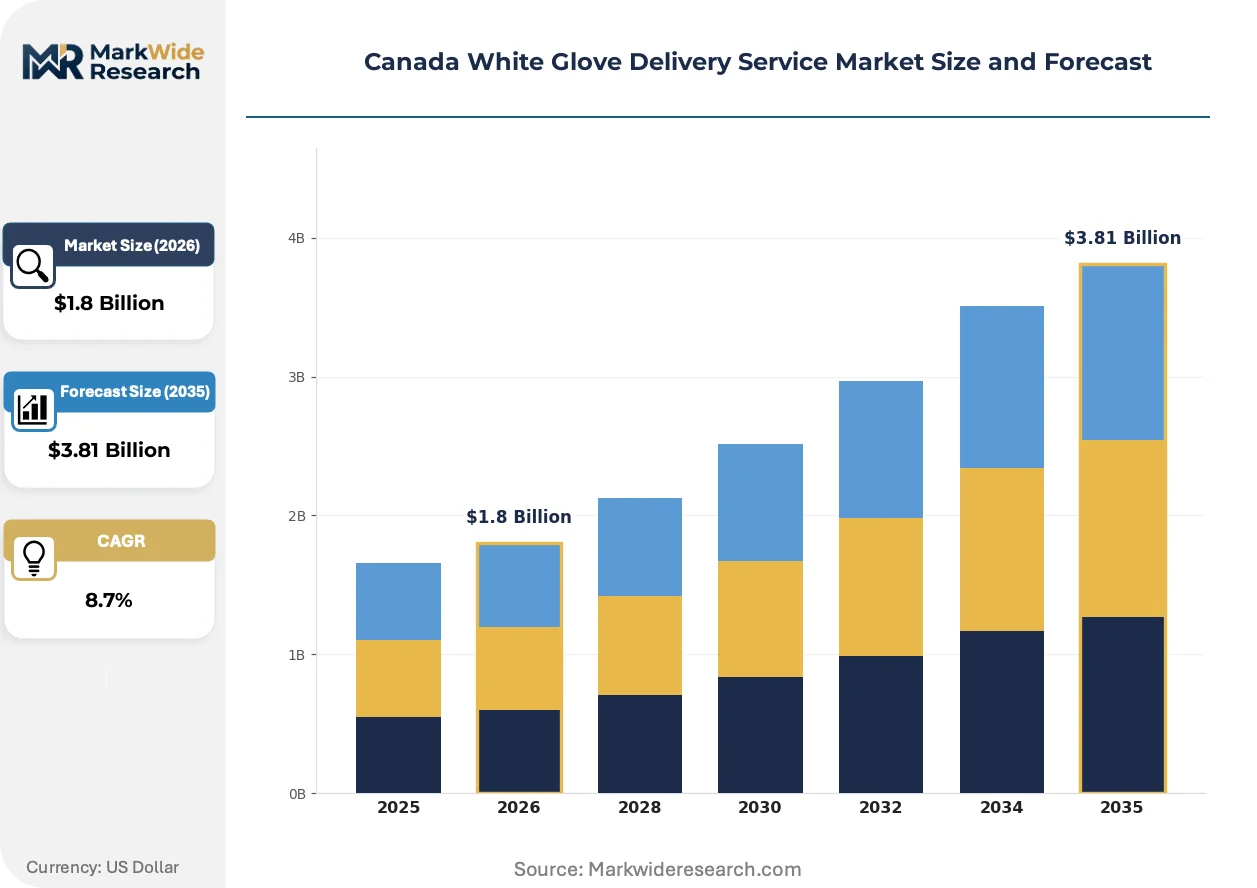
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential, Commercial, Retail, Medical Delivery Model: Same Day, Next Day, Scheduled, On-Demand Product Category: Furniture, Electronics, Appliances, Artwork Client Type: Individuals, Businesses, Government, Non-Profits |
| Companies Covered | QRC Logistics, NLI International, Fidelitone Last Mile Inc, XPO, SEKO Logistics, Werner U.S. and Canada Logistics, Ryder, UPS, FedEx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada White Glove Delivery Service Market Trends and Innovations
Telematics convergence with predictive routing algorithms is compressing delivery windows while Health Canada enforcement of the Safe Food for Canadians Regulations extends cold-chain accountability deeper into last-mile operations.
Electric liftgate trucks with regenerative braking and onboard battery-powered climate control are rendering obsolete diesel auxiliary units for medical deliveries in urban corridors. Hospital procurement departments in Ottawa and Hamilton are specifying electric fleet percentages in RFPs. The technology is compressing total cost of ownership calculations for operators with depot charging infrastructure.
Health Canada's 2023 update to the Transportation of Dangerous Goods Regulations imposes stricter documentation for lithium battery shipments in medical devices. Courier operators must now deploy dedicated compliance officers for route planning. The regulatory friction falls heaviest on same-day medical delivery segments in Ontario where shipment frequency outpaces administrative capacity.
Buyers now unbundle after-sales service from product purchase, selecting white glove providers through competitive tender rather than defaulting to retailer-arranged delivery. Furniture e-commerce platforms in British Columbia are responding by offering customer-selected delivery windows with independent provider ratings. This behavioral shift concentrates volume with multi-brand logistics platforms possessing transparent pricing interfaces.
Canada White Glove Delivery Service Market Segmentation
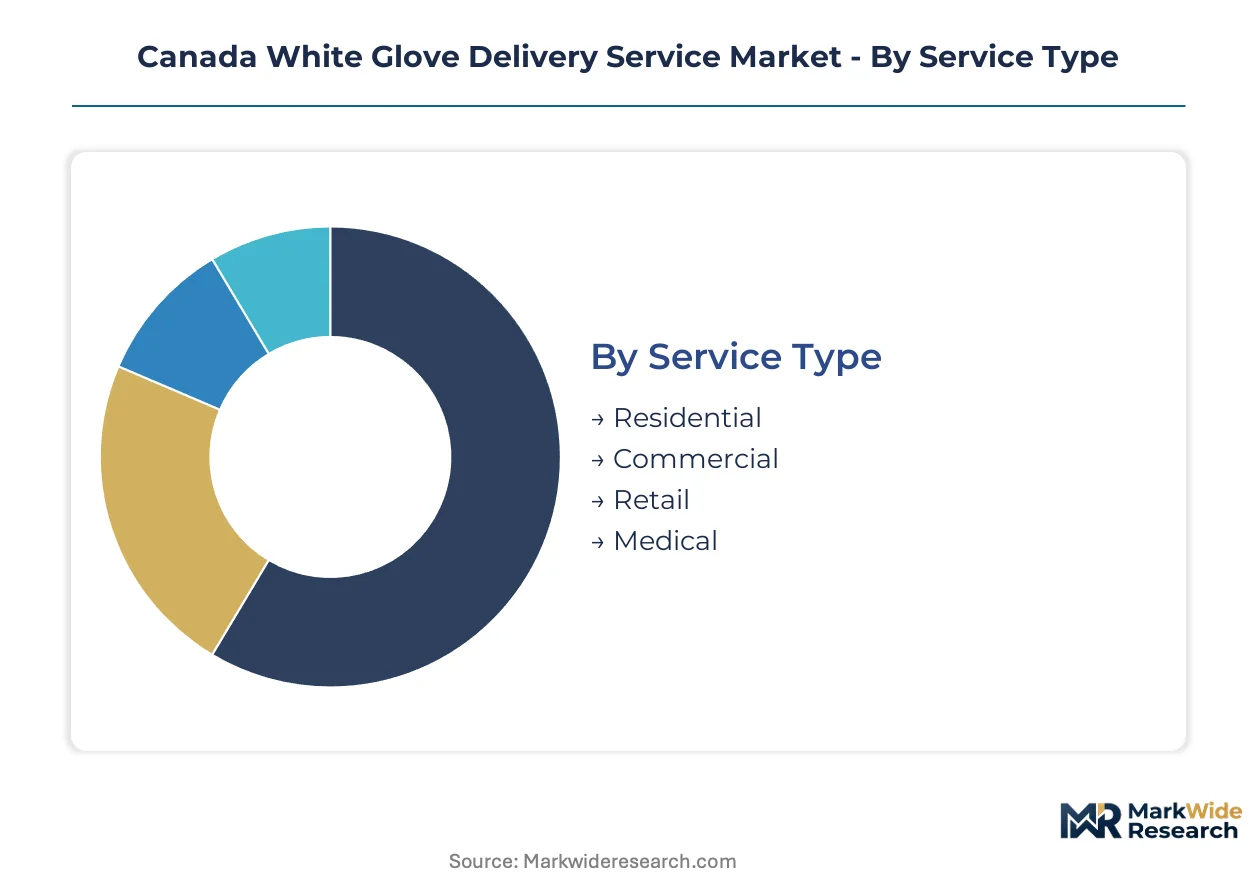
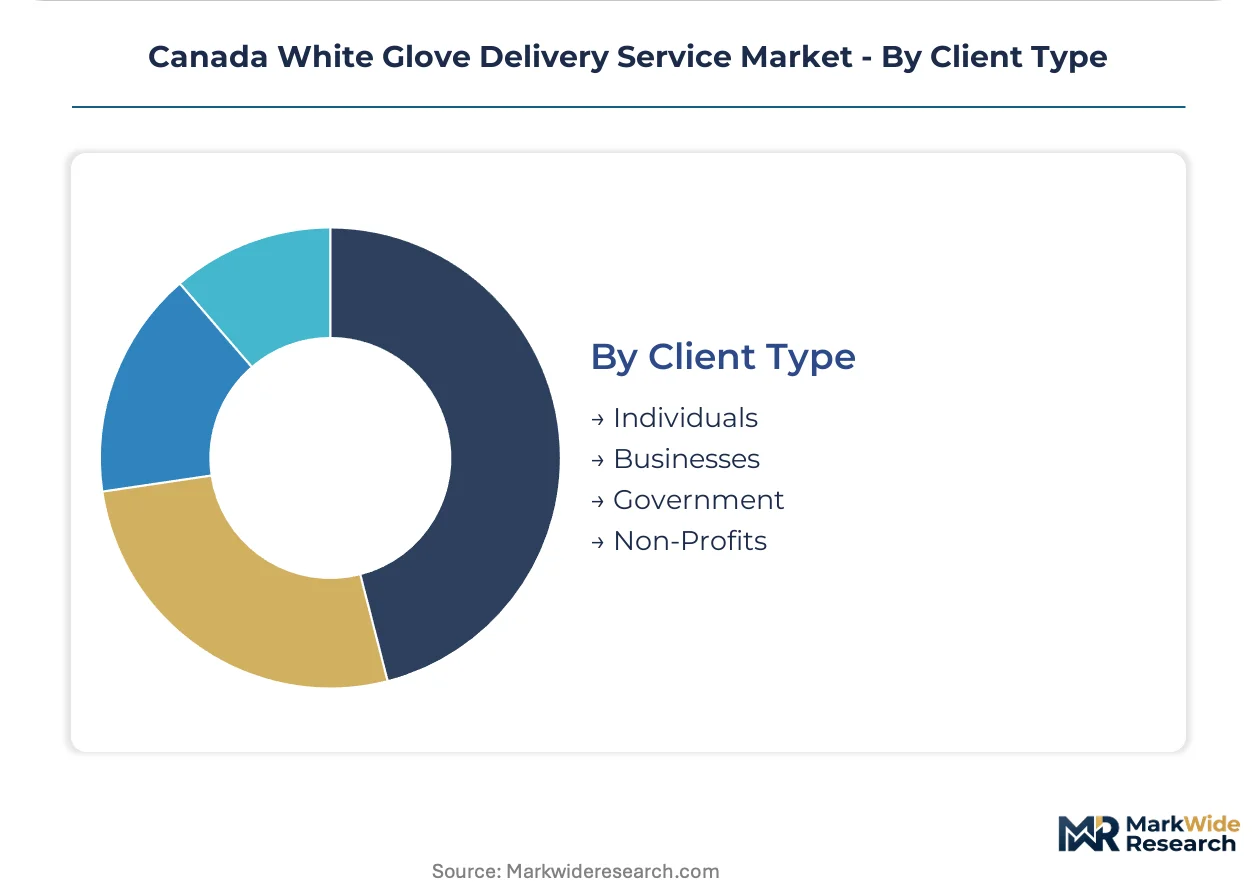
White glove delivery economics diverge sharply across service tiers and client profiles. Cycle times, compliance burdens, and crew certification requirements create distinct operational models that reshape carrier specialization and fleet deployment strategies.
Service Type:
Residential turns inventory fastest with predictable volume patterns, while Medical stretches cycle times through validation protocols and documentation checkpoints.
- Residential:Inside-home placement with debris removal dominates unit economics across Greater Toronto Area condominium corridors. E-commerce furniture normalization has compressed delivery windows to same-day or next-day expectations in Vancouver and Toronto urban cores.
- Commercial:Business-to-business white glove handling for office furniture and equipment requires after-hours scheduling flexibility and loading dock coordination. Demand concentrates in Calgary and Edmonton energy sector headquarters refresh cycles.
- Retail:Store fixture installation and visual merchandising delivery demands assembly capabilities and fixture-specific training. Luxury retail clustering in Montreal's Golden Square Mile sustains premium pricing for specialized handling.
- Medical:Health Canada TDG compliance and cold-chain validation impose the longest preparation cycles. Hospital procurement departments in Ottawa and Hamilton mandate temperature-logged transport with chain-of-custody documentation.
Residential anchors the volume base while Medical gains share at the steepest rate.
Delivery Model:
Cost tiers separate capital-light broker models from asset-heavy dedicated fleet operations with diverging margin profiles.
- Same Day:Premium positioning requires urban depot density and real-time dispatch systems. Toronto-Montreal corridor operators justify dedicated fleet investment through healthcare and luxury retail contract concentration.
- Next Day:Standard freight networks with white glove upgrade modules dominate secondary market coverage. This model retains scale advantages in Quebec City and Halifax where density insufficiently supports same-day infrastructure.
- Scheduled:Appointment-based routing with two-hour windows optimizes crew utilization for furniture and appliance delivery. British Columbia's Lower Mainland operators leverage this model for multi-stop residential consolidation.
- On-Demand:Broker-mediated last-mile matching connects independent certified handlers with immediate delivery requests. Artwork and antique segments in Montreal sustain this model through irregular volume and extreme handling sensitivity.
Next Day captures the widest geographic footprint while Same Day climbs fastest in revenue concentration.
Product Category:
Application-specific damage tolerance dictates equipment specifications and insurance layering across carrier portfolios.
- Furniture:Large-format residential and commercial pieces require liftgate trucks and two-person crews for stairwell navigation. Ontario's warehouse expansion has compressed last-mile radiuses for this segment.
- Electronics:Fragile components and anti-static handling protocols dominate medical imaging and server equipment transport. Health Canada lithium battery documentation requirements add compliance friction.
- Appliances:Hookup and installation services extend white glove scope beyond placement into utility connection. Quebec's aging high-rise population density sustains demand for assisted installation.
- Artwork:Climate-controlled transport with vibration damping commands the highest per-unit pricing. Private gallery networks in Vancouver and Toronto sustain specialized carrier specialization.
Furniture generates the highest absolute shipment counts while Artwork commands the steepest per-unit margin expansion.
Client Type:
Procurement sophistication separates price-sensitive volume buyers from specification-driven compliance purchasers.
- Individuals:Direct-to-consumer e-commerce delivery expectations normalize premium service tiers. British Columbia furniture platforms now offer customer-selected delivery windows with independent provider ratings.
- Businesses:Corporate procurement departments negotiate annual contracts with service level agreements and API-connected visibility. Hospital networks in Ontario's Golden Horseshoe specify electric fleet percentages in RFPs.
- Government:Federal and provincial procurement frameworks prioritize Health Canada certification and carbon pricing compliance. Green procurement contracts in British Columbia favor zero-emission fleet operators.
- Non-Profits:Donation-driven logistics for medical equipment and furniture redistribution requires flexible scheduling and reduced-rate structures. Alberta's energy sector pivot creates underserved demand from occupational health clinics.
Businesses anchor contract value concentration while Government procurement expands most quickly through compliance mandate tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warehouse capacity concentrates in the Toronto-Montreal corridor, compressing last-mile delivery radiuses while elevating compliance burdens for temperature-validated fleets serving hospital networks and luxury retail clusters.
Ontario
Healthcare infrastructure density in the Golden Horseshoe drives demand for Health Canada-certified white glove handling. The province's Transportation of Dangerous Goods enforcement mandates chain-of-custody documentation for medical device transport. Ottawa and Hamilton hospital procurement departments specify electric fleet percentages in RFPs, accelerating zero-emission vehicle adoption among certified providers.
Quebec
Montreal's aging high-rise population concentration creates sustained demand for assisted delivery with assembly and installation services. The province's occupational safety regulators enforce strict two-person crew certification requirements for inside-delivery operations. Luxury retail clustering in the Golden Square Mile sustains premium pricing for specialized fixture handling and visual merchandising delivery.
British Columbia
Vancouver's condominium-dense urban core normalizes same-day white glove expectations for e-commerce furniture purchases. The provincial zero-emission vehicle mandate creates first-mover advantage for electric liftgate fleet operators securing green procurement contracts. Lower Mainland operators leverage scheduled appointment-based routing for multi-stop residential consolidation.
Alberta
Calgary and Edmonton medical device hubs serving oil patch occupational health clinics remain underserved by Health Canada-certified specialists. Federal carbon pricing mechanisms add incremental cost pressure per kilometer for diesel-dependent liftgate fleets. Energy sector headquarters refresh cycles in both cities generate commercial white glove demand for office furniture and equipment.
Atlantic Canada
Halifax anchors regional demand through hospital network procurement and residential construction activity. Next-day delivery models retain scale advantages where population density insufficiently supports same-day infrastructure. Provincial workers compensation requirements for dangerous goods handling create recruitment bottlenecks limiting market entry.
Canada White Glove Delivery Service Market Competitive Landscape
Integrated express networks and specialized healthcare logistics providers split the market between scale-driven standardization and compliance-certified premium positioning. Cross-border freight diversification separates national operators with warehousing economies from regional players facing margin compression. Three archetypes dominate: asset-heavy dedicated fleet operators, broker-mediated last-mile platforms, and healthcare-specialized compliance handlers. Consolidation pressures manifest through warehouse network expansion and electric fleet procurement mandates.
Within the healthcare-specialized tier, SEKO Logistics exemplifies temperature-validated fleet positioning through Health Canada compliance infrastructure. XPO anchors the cross-border corridor strategy with fulfillment capacity concentrated in the Toronto-Montreal axis. FedEx occupies the integrated express position, extending brand strength and tracking infrastructure into high-touch delivery segments. These three represent distinct strategic postures rather than direct substitution competitors.
| Leading Market Players |
|---|
| QRC Logistics |
| NLI International |
| Fidelitone Last Mile Inc |
| XPO |
| SEKO Logistics |
| Werner U.S. and Canada Logistics |
| Ryder |
| UPS |
| FedEx |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Health Canada-certified cold-chain fleets across Ontario's Golden Horseshoe is compressing delivery windows while elevating rate premiums for hospital procurement departments. Fleet operators respond by concentrating assets in corridor depots and passing certification compliance costs through to buyers with limited substitution options.
Pricing Analysis
Health Canada's Transportation of Dangerous Goods Regulations dictates the pricing tier structure across medical, commercial, and residential service segments. Three-tier pricing structure across premium, standard, and economy levels separates temperature-validated medical deliveries from scheduled furniture placement and on-demand broker-mediated matching. Cost compression in the residential tier is intensifying because e-commerce platforms normalize free shipping expectations. Individual consumers exhibit highest price sensitivity while hospital procurement departments demonstrate lowest elasticity due to compliance mandate rigidity.
Supply Chain Analysis
Diesel fuel procurement, electric liftgate chassis, and specialized climate-control units feed from upstream suppliers concentrated in the United States, China, and Germany. Component sourcing rests on battery cell manufacturers for auxiliary power units and hydraulic liftgate fabricators serving commercial vehicle upfitters. Single-source vulnerability concentrates in semiconductor-dependent telematics modules for real-time tracking integration. Distribution runs through depot-based hub operations radiating into urban corridor last-mile networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare infrastructure investment cycles are lifting demand for certified white glove handling as hospital networks consolidate procurement around validated fleet operators. Equipment refresh timelines at Ontario's Golden Horseshoe medical campuses create predictable contract windows for compliant providers.
For Market Incumbents: Pre-empt margin erosion by securing exclusive depot capacity in Toronto-Montreal corridor warehousing clusters and accelerating electric fleet certification ahead of British Columbia's zero-emission vehicle mandate tightening. Channel control through direct hospital procurement relationships defends against broker-mediated disintermediation threatening rate transparency.
For New Entrants and Emerging Players: Pursue Alberta's energy sector medical device hubs serving Calgary and Edmonton occupational health clinics, where Health Canada-certified specialist coverage remains sparse. Broker-mediated matching platforms for on-demand artwork and antique segments in Montreal offer lowest capital entry barriers with irregular volume tolerance.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric liftgate fleet deployment as provincial green procurement contracts favor zero-emission operators. Long-term viability centers on depot network density and compliance infrastructure rather than asset-light brokerage models. Acquisition target archetype: regional operators with Health Canada certification and cross-border freight diversification. Signal to watch: hospital RFP electric fleet percentage specifications as inflection indicator for mandated transition timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Certification | Health Canada hospital procurement departments specify zero-emission percentages in competitive tenders. |
| Depot Network Expansion | Toronto-Montreal corridor warehousing concentration compresses last-mile radiuses for same-day medical delivery. |
| Compliance Infrastructure Investment | Temperature-validated fleet capabilities create barrier against informal competitors lacking TDG documentation systems. |
| API-Connected Visibility Platform | Hospital procurement departments mandate real-time tracking integration unavailable through legacy dispatch systems. |
| Cross-Border Freight Diversification | XPO leverages transnational network to anchor fulfillment capacity against regional margin compression. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, fleet operations directors, healthcare logistics coordinators, and e-commerce platform fulfillment heads. Secondary validation drew from Health Canada regulatory filings, Transport Canada enforcement bulletins, provincial workers compensation requirements, and customs trade data on commercial vehicle imports. Bottom-up shipment volume modeling and top-down market sizing triangulated segment-level estimates.
Calibration against historical fleet deployment patterns and hospital capital expenditure cycles anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include service type, delivery model, product category, and client procurement sophistication tier. CAGRs derived from equipment replacement cycles, regulatory compliance mandate phasing, and e-commerce penetration curves specific to large-format residential purchases.
Sensitivities concentrate around diesel price volatility, zero-emission vehicle mandate acceleration, and hospital procurement centralization timing. Forecasts embed assumptions regarding certification cost pass-through elasticity and fleet utilization recovery in secondary markets. Cross-checking against Canadian Vehicle Manufacturers' Association commercial vehicle registration data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Europe Van Rental Market
Transportation Services
China Vehicle Rental Market
Transportation Services
Drayage Services Market
Transportation Services
Online Bus Ticketing Service Market
Transportation Services
Car Rental Market
Transportation Services
Cross Docking Services Market
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
Bulk Transportation Services Market
Transportation Services
Compact Road Sweepers Market
Transportation Services
Spain Car Rental Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Vietnam Car Rental Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Refrigerated Truck Rental Market