
 Enclosed Car Transportation Service Market | 2026-2036
Enclosed Car Transportation Service Market Size, Share, and Industry Trends Forecast 2026-2036
Enclosed Car Transportation Service Market Insights
Modular service bundling is shifting buyer choice in enclosed car transportation as carriers combine guaranteed pickup windows, enclosed trailer capacity locks, and condition documentation into single-quote packages. Montway Auto Transport leverages its national carrier network to sustain volume density across major interstate corridors. A1 Auto Transport anchors its position through specialized classic car handling protocols and white-glove loading procedures. Sherpa Auto Transport differentiates via fixed-price guarantee structures that eliminate post-delivery balance billing.
Enclosed car transportation service denotes the movement of automobiles within fully covered trailers, typically employing hydraulic lift gates, soft-tie wheel nets, and climate-controlled compartments to eliminate road debris exposure and weather damage during transit. This service primarily serves owners, dealers, and collectors requiring preservation of paint integrity, mechanical condition, and resale value across distances exceeding five hundred miles. Enclosed transport commands premium positioning within the service type dimension as collectors and exotic vehicle owners absorb higher per-mile costs for damage-risk reduction. The vehicle type dimension shows classic cars generating disproportionate margin contribution despite lower shipment frequency, while SUVs sustain volume throughput through dealership relocation contracts. Subscription pricing models remain nascent but attract corporate fleet managers seeking predictable logistics expenditures across quarterly vehicle redistribution cycles.
FMCSA hours-of-service rules and DOT interstate carrier authority requirements shape fleet utilization rates and driver availability for enclosed operators crossing state lines. EPA emissions standards for heavy-duty tractors influence equipment replacement cycles and capital deployment timing among carriers maintaining modern enclosed trailer fleets. Stakeholders must monitor pending autonomous trucking regulations and their compatibility with high-value cargo liability frameworks before committing to long-haul route automation investments.
Market Dynamics
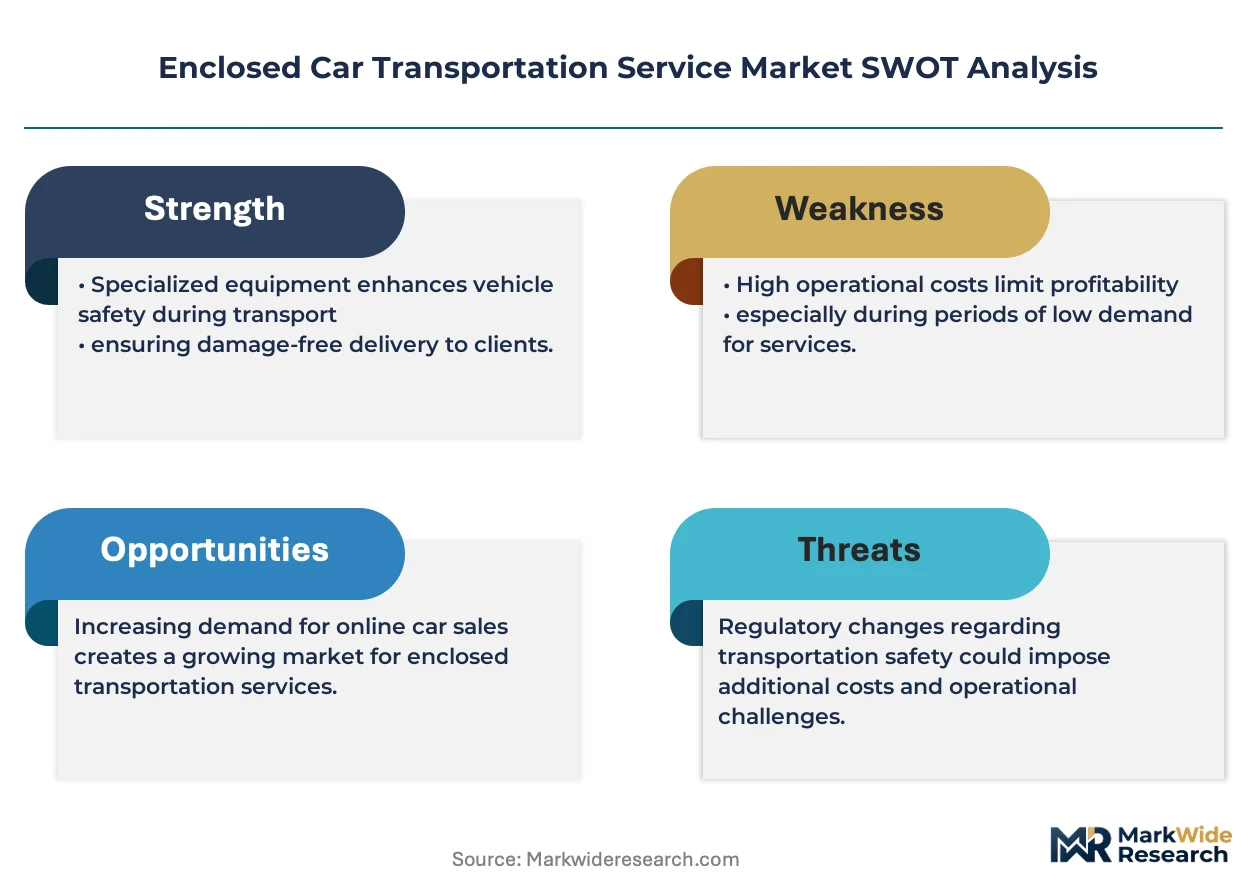
FMCSA hours-of-service enforcement and DOT interstate carrier authority requirements are compressing driver availability and fleet utilization rates for enclosed operators crossing state lines, forcing carriers to reconfigure route density models around regulatory constraints rather than pure demand optimization.
Growth Catalysts
- Collector vehicle auction volume:Classic car auction houses in Arizona and Florida are generating concentrated outbound shipment demand, requiring enclosed capacity locks during peak seasonal windows.
- EPA heavy-duty tractor emissions standards:Equipment replacement cycles among carriers maintaining modern enclosed fleets are accelerating capital deployment into aerodynamic trailer designs and low-emission tractors.
- Hydraulic lift gate adoption:Soft-tie wheel net systems paired with hydraulic loading platforms are reducing damage claims and expanding service eligibility for lowered suspension vehicles.
Market Restraints
- Driver labor scarcity:CDL-A holder availability constraints in Texas and California are limiting fleet expansion velocity for enclosed specialists requiring hazmat endorsements.
- Insurance premium escalation:Cargo liability coverage for vehicles exceeding $500,000 declared value has compressed margins on high-end classic car routes.
- Trailer manufacturing concentration:Enclosed car hauler production concentrates among three domestic fabricators, creating equipment delivery backlogs during Q2-Q3 peak ordering periods.
Strategic Opportunities
- Subscription fleet redistribution:Corporate fleet managers are piloting quarterly vehicle rotation contracts with locked enclosed capacity, converting spot demand into recurring revenue.
- Climate-controlled compartment retrofit:Existing enclosed trailers are receiving HVAC module installations to capture exotic vehicle transport contracts requiring temperature stabilization.
- Autonomous trucking liability frameworks:Early regulatory clarity from NHTSA on high-value cargo autonomous operations would enable long-haul route automation investments.
Industry Challenges
- Condition documentation standardization:Pre- and post-transport photographic protocols vary across carriers, creating dispute resolution friction with high-value vehicle owners.
- Cross-dock coordination complexity:Multi-vehicle enclosed loads requiring driver changes at intermediate terminals face handoff liability allocation ambiguities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enclosed Car Transportation Service Market |
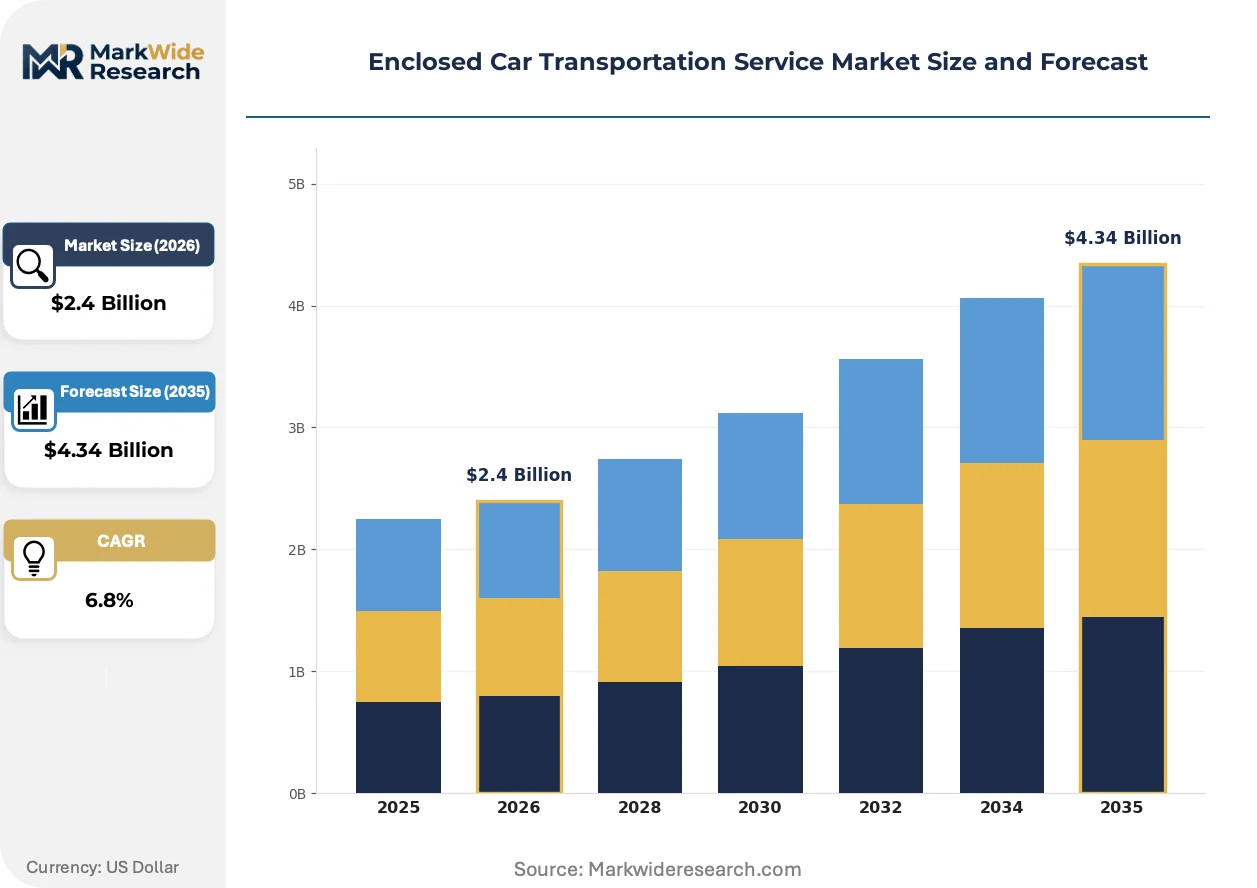
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Open Transport, Enclosed Transport, Luxury Transport, Oversized Transport Vehicle Type: SUV, Sedan, Coupe, Classic Cars End User: Retail Customers, Dealerships, Collectors, Corporations Pricing Model: Flat Rate, Per Mile, Subscription, Auction-Based |
| Companies Covered | Montway Auto Transport, A1 Auto Transport, Ship A1 Auto Transport, Road Runner Auto Transport, SGT Auto Transport, Sherpa Auto Transport, Nexus Auto Transport, Safeport Inc, Shippers Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enclosed Car Transportation Service Market Trends and Innovations
Real-time cargo monitoring systems and predictive maintenance algorithms are reconfiguring how enclosed carriers manage in-transit risk and asset utilization, shifting competitive advantage toward data-integrated operations.
Telematics-enabled trailer tracking is expanding into enclosed car transportation as carriers deploy GPS-integrated door sensors and interior climate monitors. Classic car collectors and exotic vehicle dealers are demanding continuous visibility as a baseline service element. This capability compression is expanding into premium service tiers as a standard inclusion rather than surcharge option.
FMCSA electronic logging device mandates have tightened enforcement of hours-of-service rules for interstate enclosed operators. Fleet dispatch systems are compressing route planning around driver availability windows rather than pure mileage optimization. Sun Belt corridor carriers are responding by concentrating terminal assets near auction house clusters to minimize deadhead positioning.
Buyers are consolidating transport procurement around bundled service packages that combine guaranteed pickup windows, enclosed capacity locks, and condition documentation into single-quote structures. Traditional spot-rate brokerage relationships are fragmentating as high-value vehicle owners prioritize predictability over per-mile cost minimization. This preference shift is most visible among dealership relocation contracts and collector auction logistics.
Enclosed Car Transportation Service Market Segmentation
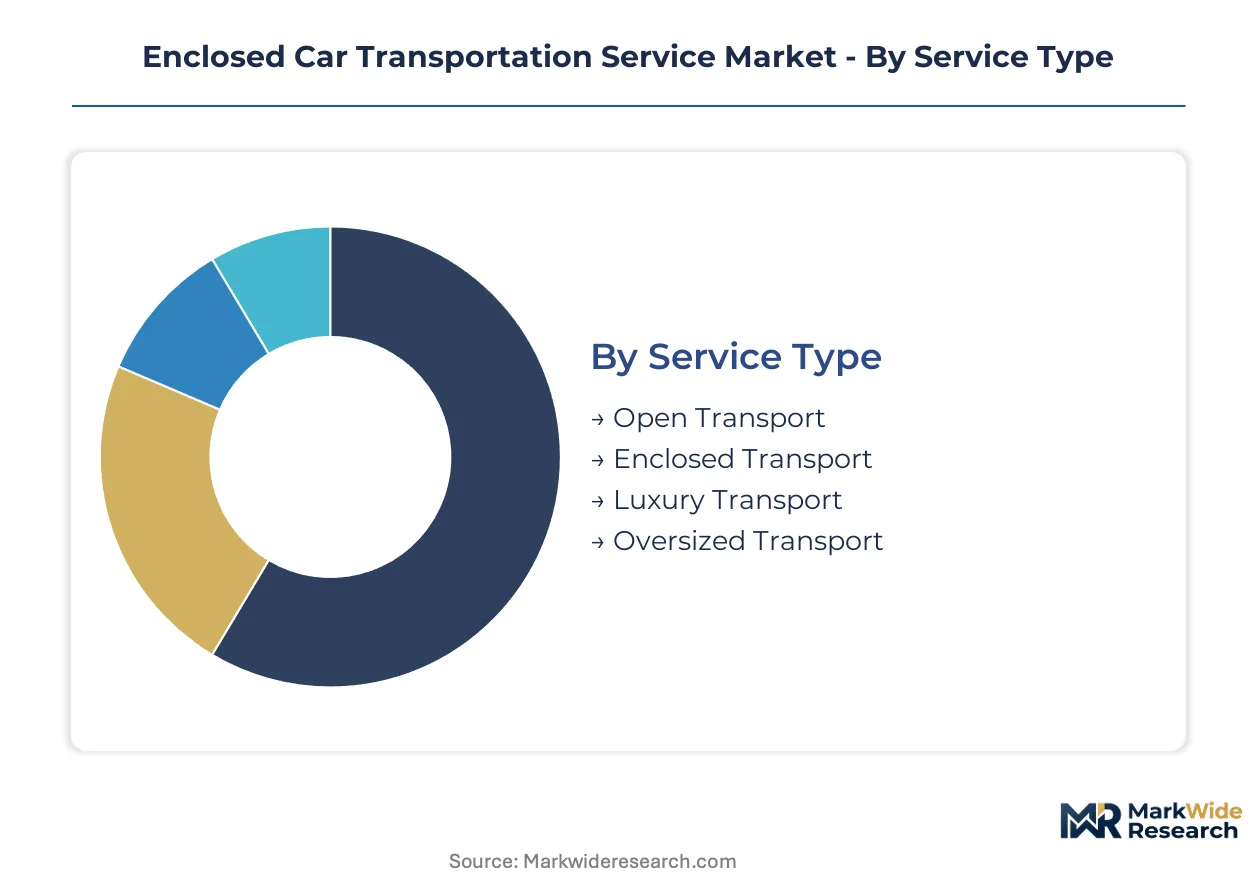
Segmentation in enclosed car transportation determines carrier equipment configuration, liability coverage tiers, and route density planning. Each dimension creates distinct operational requirements that shape fleet investment and pricing architecture.
Service Type:
Trailer construction specifications and cargo protection levels differentiate service tiers across the market.
- Open Transport:Vehicles travel on exposed multi-level carriers with no weather or debris shielding. Fleet operators in Texas and Florida deploy open trailers for high-volume dealership relocation contracts where cost minimization outweighs cosmetic risk.
- Enclosed Transport:Fully covered trailers with hydraulic lift gates and soft-tie wheel nets eliminate road exposure. Sun Belt auction houses generate concentrated demand during seasonal peaks, requiring capacity locks and guaranteed pickup windows.
- Luxury Transport:Climate-controlled compartments with single-vehicle capacity and white-glove loading protocols. Exotic vehicle dealers in Arizona absorb premium per-mile costs for temperature stabilization and dedicated driver assignments.
- Oversized Transport:Extended trailers and reinforced flooring accommodate lifted trucks and modified suspensions. Custom fabrication shops in California drive specialized routing around height clearance restrictions.
Enclosed Transport leads on scale; Luxury Transport leads on momentum.
Vehicle Type:
Dimensional constraints and value density determine trailer configuration and insurance loading across vehicle categories.
- SUV:Elevated rooflines and weight distribution require reinforced hydraulic platforms. Dealership redistribution contracts sustain volume throughput across interstate corridors despite lower per-unit margins.
- Sedan:Standardized dimensions enable maximum trailer density with stacked loading configurations. Corporate fleet managers favor sedans for subscription-based quarterly rotation programs.
- Coupe:Lowered suspensions and aerodynamic profiles demand specialized wheel net spacing. Sports car collectors in Florida generate seasonal outbound shipment surges following auction events.
- Classic Cars:Irreplaceable paint integrity and mechanical originality command white-glove handling. Arizona auction houses concentrate high-value declared value shipments requiring enhanced cargo liability coverage.
SUV dominates volume throughput; Classic Cars command margin contribution.
End User:
Procurement sophistication and risk tolerance vary sharply across customer categories, reshaping carrier sales architecture.
- Retail Customers:Individual owners relocating single vehicles with variable timing flexibility. Online quote platforms aggregate spot demand across dispersed geographies with limited contract loyalty.
- Dealerships:Franchise networks require predictable capacity for inventory redistribution between lots. Locked quarterly contracts with guaranteed pickup windows are displacing transactional brokerage relationships.
- Collectors:Auction participants and restoration hobbyists demand condition documentation and enclosed capacity locks. Pre- and post-transport photographic protocols are becoming non-negotiable service elements.
- Corporations:Fleet managers pilot subscription pricing models for predictable logistics expenditures across vehicle redistribution cycles. Multi-year agreements convert volatile spot demand into recurring revenue streams.
Dealerships anchor volume stability; Corporations are expanding most quickly.
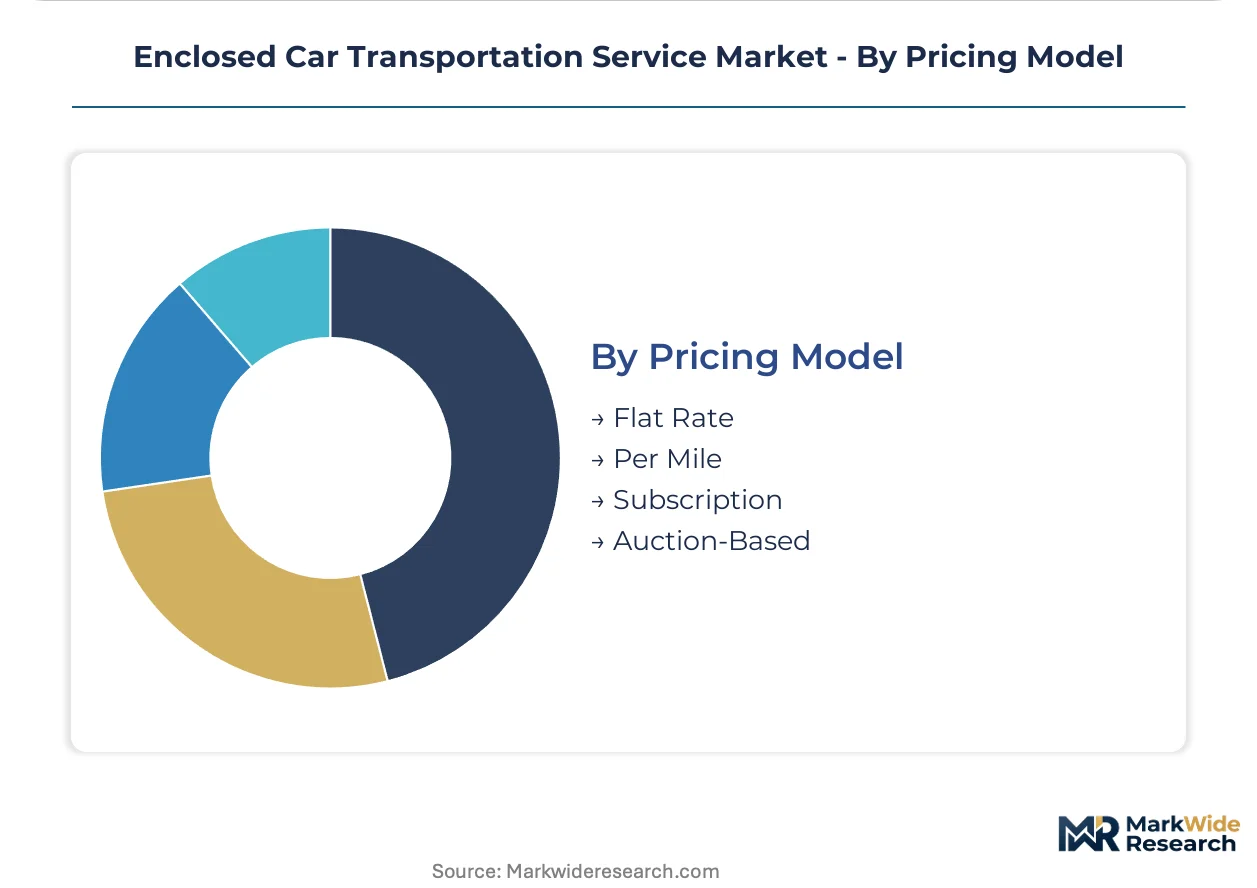
Pricing Model:
Revenue predictability and customer commitment levels differentiate pricing architectures across the market.
- Flat Rate:Fixed origin-destination pricing eliminates post-delivery balance billing disputes. Retail customers favor transparent all-in quotes for cross-country relocations.
- Per Mile:Distance-based calculation with fuel surcharge adjustments. Dealership contracts incorporate mileage bands with volume discounts for frequent shippers.
- Subscription:Quarterly vehicle rotation agreements with locked enclosed capacity. Corporate fleet managers absorb premium rates for guaranteed availability during peak windows.
- Auction-Based:Dynamic pricing responding to seasonal capacity constraints around Arizona and Florida auction calendars. Collector demand spikes trigger surge multipliers during concentrated outbound periods.
Flat Rate sustains broadest adoption; Subscription shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enclosed car transportation service originated in the United States during the post-war classic car restoration boom of the 1950s, with specialized haulers emerging around Los Angeles and Detroit to protect high-value vehicles from highway debris damage.
United States
Arizona and Florida auction houses generate concentrated seasonal demand spikes requiring capacity locks during winter collector events. FMCSA hours-of-service enforcement through electronic logging devices compresses driver availability for interstate operators. Scottsdale and Palm Beach anchor high-value declared value shipments with white-glove handling protocols.
Germany
Luxury vehicle manufacturers in Bavaria and Baden-Württemberg sustain outbound enclosed demand for dealership transfers across European corridors. KBA vehicle type approval standards influence trailer construction specifications for cross-border operations. Stuttgart and Munich concentrate specialized carriers serving Porsche and Mercedes-Benz distribution networks.
United Kingdom
London-based classic car collectors and restoration specialists drive premium enclosed bookings for continental European routes. DVSA operator licensing requirements shape fleet compliance structures for carriers maintaining international authority. The Cotswolds and Home Counties cluster high-net-worth owners requiring climate-controlled transport.
United Arab Emirates
Exotic vehicle imports through Jebel Ali Port generate inbound enclosed demand for Dubai and Abu Dhabi showrooms. MOHAP commercial vehicle regulations align with GCC standardization efforts for heavy-duty equipment. Dubai's Al Quoz industrial district hosts specialized handlers serving Lamborghini and Ferrari dealerships.
Australia
Interstate classic car relocation between Melbourne and Perth sustains long-haul enclosed routes across the Nullarbor Plain. NHVR fatigue management laws constrain driver scheduling for transcontinental operators. Sydney's Eastern Suburbs and Melbourne's Bayside concentrate collector demand requiring enclosed protection from road train debris.
Enclosed Car Transportation Service Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service bundling sophistication, with national networks commanding rate premiums over regional spot brokers. The vendor base fragments across three tiers: integrated carriers with owned trailer fleets, asset-light brokers aggregating independent operator capacity, and specialized classic car handlers with white-glove protocols. Consolidation pressure concentrates among mid-scale brokers seeking route density through acquisition. Strategic moves center on guaranteed capacity contracts with auction houses and technology investments in real-time cargo visibility.
Within the national network tier, Montway Auto Transport and A1 Auto Transport occupy positions exemplifying scale-driven route density models across major interstate corridors. Sherpa Auto Transport anchors the fixed-price guarantee segment, representing transparency-focused positioning that eliminates post-delivery billing disputes. These three carriers collectively illustrate the strategic divergence between volume throughput optimization and premium service predictability.
| Leading Market Players |
|---|
| Montway Auto Transport |
| A1 Auto Transport |
| Ship A1 Auto Transport |
| Road Runner Auto Transport |
| SGT Auto Transport |
| Sherpa Auto Transport |
| Nexus Auto Transport |
| Safeport Inc |
| Shippers Inc |
| Others |
Pricing and Supply Chain Analysis
Aluminum sheet price indices cascade through enclosed trailer manufacturing costs into three-tier pricing structures across premium, standard, and economy service levels. Steel coil volatility and hydraulic component lead times compress margins for carriers sourcing equipment from concentrated domestic fabricators. Buyers absorb these input fluctuations through fuel surcharge mechanisms and capacity-lock premiums during seasonal demand windows.
Pricing Analysis
Flat-rate guaranteed pricing with fixed origin-destination quotes anchors the dominant structure, eliminating post-delivery balance billing disputes for retail customers. Price differentiation rests on declared value tiers and climate-control certification levels, with exotic vehicle contracts commanding premium positioning. Cost compression in standard enclosed tiers intensifies because insurance premium escalation for high-value cargo erodes carrier margins. Dealership procurement teams show highest price sensitivity through volume-negotiated mileage bands, while collector auction participants absorb premium rates for white-glove handling protocols.
Supply Chain Analysis
Direct-to-auction-house channels handle concentrated seasonal demand from Scottsdale and Palm Beach collector events. Trailer manufacturing concentrates in Indiana, Ohio, and Texas among three domestic fabricators. Aluminum extrusions, hydraulic lift systems, and soft-tie wheel assemblies draw from automotive and aerospace supplier networks. Single-source vulnerability in specialized axle components creates equipment delivery backlogs during Q2-Q3 peak ordering periods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FMCSA electronic logging device mandates compound regulatory pressure on driver availability, accelerating carrier investment in terminal density and route optimization technology. DOT interstate carrier authority requirements tighten compliance thresholds, favoring scaled operators with dedicated safety departments.
For Market Incumbents: Deepen terminal asset concentration near Arizona and Florida auction clusters to minimize deadhead positioning under hours-of-service constraints. Expand captive maintenance capabilities for hydraulic lift gate systems to reduce third-party service dependencies. Driver labor scarcity in Texas and California threatens fleet expansion velocity; locked quarterly contracts with dealership networks defend revenue predictability against spot-rate volatility.
For New Entrants and Emerging Players: The mid-tier price gap between white-glove luxury transport and standard enclosed service creates entry space for technology-enabled transparency plays. Corporate fleet managers seeking subscription pricing models represent the most penetrable segment, with pilot quarterly rotation contracts converting volatile demand into recurring revenue. A go-to-market angle anchored in real-time cargo visibility APIs differentiates against legacy brokerage relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale brokers lack route density to absorb regulatory compliance costs. Long-term viability favors carriers with owned trailer fleets and direct driver employment models over asset-light aggregation plays. Acquisition targets should display locked capacity contracts with auction houses or dealership networks. The signal to watch is NHTSA regulatory clarity on autonomous trucking liability frameworks for high-value cargo.
| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Density Expansion | Scottsdale and Palm Beach hub investments compress deadhead miles under FMCSA hours-of-service rules. |
| Climate-Controlled Retrofit Program | HVAC module installations capture exotic vehicle contracts from Arizona and Florida dealers. |
| Subscription Fleet Contracting | Quarterly rotation agreements with corporate fleet managers convert spot demand into recurring revenue streams. |
| Real-Time Visibility Platform | GPS-integrated door sensors and interior climate monitors meet collector demands for continuous cargo monitoring. |
| Driver Retention Infrastructure | Direct employment models with guaranteed home-time windows address CDL-A scarcity in Texas and California corridors. |
Research Methodology
Bottom-up fleet operator modeling reconciled against top-down carrier capacity tracking forms the analytical core of this study. Primary interviews with enclosed transport dispatch managers, classic car auction logistics coordinators, dealership fleet procurement directors, and FMCSA compliance officers combined with secondary validation from DOT carrier authority databases, EPA heavy-duty emissions filings, and auction house shipment manifests. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped trailer manufacturing capacity, driver availability constraints, and seasonal demand patterns across the projection horizon. Segmentation dimensions modeled include service type tier, vehicle class, end-user procurement sophistication, and pricing architecture. CAGRs derived from equipment replacement cycle timing, auction calendar density, and corporate fleet redistribution contract velocity. Insurance premium trajectories and hydraulic component supply lead times fed industry-specific forecast adjustments.
Caveats apply where autonomous trucking regulatory rulings or aluminum price volatility could materially shift the outlook. Forecasts reflect assumptions about driver labor market conditions and auction house volume trends. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Corporate Car Sharing Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Benchmarking Services for Transportation Rates Market
Transportation Services
Car Rental Service Market
Transportation Services
Airport Handling Service Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Brazil Vehicle Rental Market
Transportation Services
Equipment Relocation Service Market
Transportation Services
Russia Car Rental Market
Transportation Services
Compact Road Sweepers Market
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
Refuse Truck Market
Transportation Services
Truck Sharing Market
Transportation Services
Spain Car Rental Market
Transportation Services
Drayage Services Market