
 Benchmarking Services for Transportation Rates Market | 2026-2036
Benchmarking Services for Transportation Rates Market Size, Share, and Industry Trends Forecast 2026-2036
Benchmarking Services for Transportation Rates Market Insights
Digital freight brokerages is reshaping how transportation rate data reaches shippers, collapsing traditional information asymmetries between carriers and cargo owners. DAT Freight & Analytics leverages its load board infrastructure to aggregate billions of annual rate transactions into benchmarkable datasets. Cass Information Systems anchors its position through payment processing relationships that yield proprietary spend data across thousands of shipper accounts. Freightos competes by democratizing ocean and air rate visibility through its online marketplace, extending benchmarking logic beyond over-the-road freight.
Benchmarking services for transportation rates comprise systematic methodologies for collecting, normalizing, and comparing carrier pricing across lanes, modes, and service levels against statistically valid peer groups. These services apply regression models that control for distance, weight, fuel indices, and accessorial charges to produce actionable rate fairness assessments. Rate comparison and performance evaluation segments command the deepest margin pools because they require continuous data feeds and algorithmic refinement rather than static report generation. E-commerce and retail verticals now drive the fastest expansion as these sectors grapple with parcel and last-mile rate complexity that outstrips in-house analytical capacity.
The US Surface Transportation Board governs rail rate disputes under the Staggers Rail Act framework, while the Federal Motor Carrier Safety Administration shapes truckload pricing indirectly through hours-of-service rules that constrain effective capacity. European shippers navigate the EU Green Deal's emissions trading requirements, which embed carbon costs into rate benchmarking calculations for cross-border movements. Stakeholders must monitor how the Securities and Exchange Commission's supply chain disclosure mandates for public filers transform rate benchmarking from operational tool to governance necessity.
Market Dynamics
Digital freight brokerages have collapsed traditional information asymmetries between carriers and cargo owners, forcing benchmarking providers to compete on real-time data velocity rather than static quarterly reports. This structural compression demands continuous algorithmic refinement and API-first delivery architectures.
Growth Catalysts
- E-commerce logistics complexity:Parcel and last-mile rate structures have outgrown in-house analytical capacity at mid-market retailers, creating pull for third-party normalization services.
- STB rate reasonableness proceedings:The US Surface Transportation Board's ongoing rail disputes push shippers toward independent validation of carrier pricing claims.
- Gulf Coast petrochemical corridor:Volatile fuel surcharge structures across Houston-to-New Orleans lanes generate acute demand for benchmarkable peer comparisons.
Market Restraints
- Carrier data withholding:Large asset-based providers restrict transactional detail, forcing benchmarkers to rely on indirect spend proxies rather than direct rate feeds.
- API standardization gaps:Inconsistent data formats across TMS platforms require expensive manual normalization before regression modeling.
- Shipper IT integration costs:ERP connectivity for continuous benchmarking feeds demands six-figure implementation investments that freeze mid-market adoption.
Strategic Opportunities
- EU Green Deal carbon accounting:Embedded emissions costs in cross-border movements create demand for rate benchmarks that incorporate carbon pricing differentials.
- SEC supply chain disclosure:Mandates for public filers transform rate benchmarking from operational tool to governance necessity, expanding buyer base to compliance officers.
- Freightos marketplace model extension:Ocean and air rate visibility platforms demonstrate viability of democratized benchmarking beyond over-the-road modes.
Industry Challenges
- Data science talent scarcity:Benchmarking providers compete with fintech and ad-tech for regression modelers capable of controlling for lane-specific accessorial variables.
- Legacy TMS integration friction:Shippers running on-premise transportation management systems face 12-18 month upgrade cycles before API-enabled benchmarking deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benchmarking Services for Transportation Rates Market |
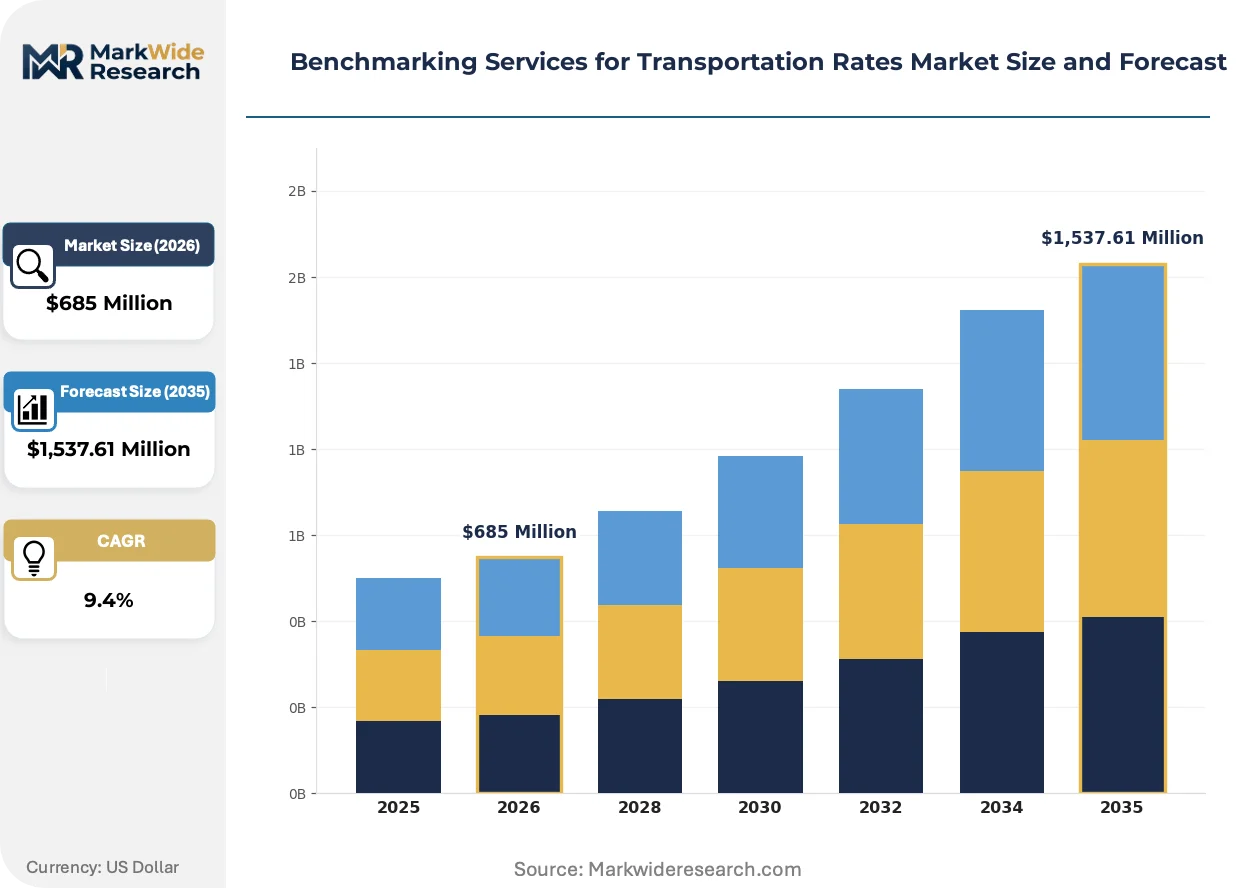
| Market Size in 2026 | $685 Million |
| Market Size in 2035 | $1,537.61 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cost Analysis, Rate Comparison, Performance Evaluation, Market Insights Customer Type: Freight Forwarders, Shippers, Carriers, Logistics Providers Industry Vertical: Retail, Manufacturing, Healthcare, E-Commerce Delivery Model: Online Platform, Consulting Services, Reports, Workshops |
| Companies Covered | DAT Freight & Analytics, Cass Information Systems, SONAR, Freightos, nVision Global, Transporeon, Starlight Analytics, SIS International Research, The Logit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benchmarking Services for Transportation Rates Market Trends and Innovations
Machine learning architectures are compressing the latency between rate transaction capture and benchmark publication from weeks to hours. This velocity shift redefines competitive positioning around data freshness rather than historical depth.
API-first benchmarking infrastructure is migrating from batch-file delivery to real-time streaming architectures. Large retail shippers with dedicated data engineering teams now demand sub-hour latency on lane-rate updates. This compression enables dynamic procurement workflows where RFP cycles collapse from quarterly to continuous.
The EU Green Deal's emissions trading requirements embed carbon costs into cross-border rate calculations. European chemical and automotive shippers now require benchmarks that normalize for carbon intensity differentials across carrier fleets. German and Dutch logistics teams have begun rejecting rate comparisons that exclude Scope 3 emissions data.
Continuous procurement models are displacing annual RFP cycles in parcel and less-than-truckload segments. E-commerce fulfillment teams now run always-on tender processes that auto-accept rates within benchmark-derived fairness bands. This shift concentrates most visibly among US apparel retailers managing volatile direct-to-consumer volume spikes.
Benchmarking Services for Transportation Rates Market Segmentation
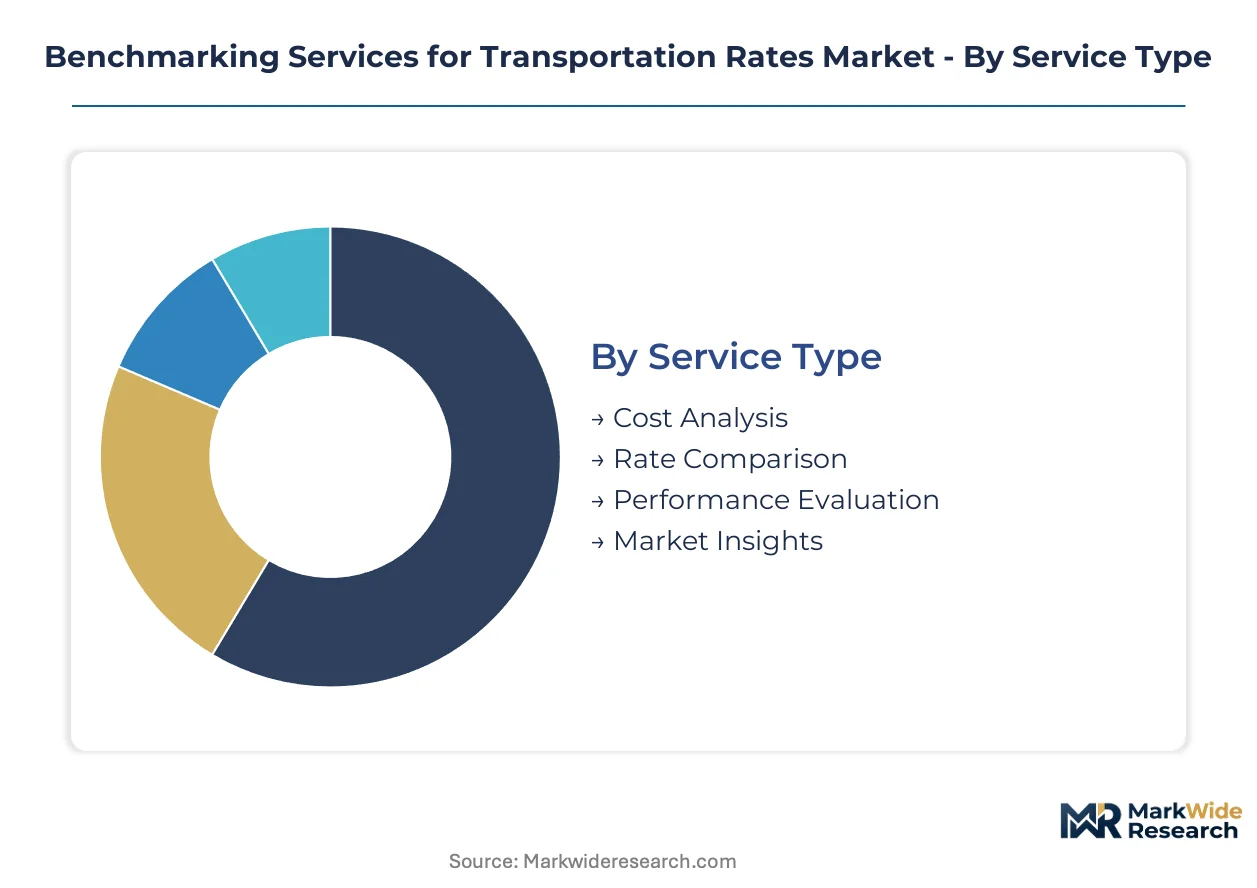
Transportation rate benchmarking services fragment across service intensity, buyer sophistication, and data delivery mechanisms. Each segmentation axis reveals distinct margin structures and competitive moats that shape provider positioning strategies.
Service Type:
Shippers deploy these services across a spectrum from tactical procurement support to strategic network design, with complexity and pricing scaling accordingly.
- Rate Comparison:Systematic normalization of carrier pricing across lanes, modes, and service levels against statistically valid peer datasets. E-commerce fulfillment teams in the US Gulf Coast petrochemical corridor drive concentrated demand as volatile fuel surcharge structures outstrip in-house analytical capacity.
- Performance Evaluation:Continuous monitoring of carrier service quality against benchmarked rate fairness bands, requiring API-first infrastructure and real-time data feeds. Large retail shippers with dedicated data engineering teams now demand sub-hour latency updates, collapsing traditional quarterly review cycles.
- Cost Analysis:Regression modeling that controls for distance, weight, fuel indices, and accessorial charges to isolate true cost drivers.
- Market Insights:Periodic report generation on macro rate trends without continuous data integration requirements.
The dominant share belongs to Rate Comparison, while Performance Evaluation is closing the gap fastest.
Customer Type:
Buyer sophistication varies sharply across the value chain, with data access privileges and procurement authority determining service tier adoption.
- Shippers:Cargo owners with direct rate exposure who require third-party validation for carrier negotiations and STB dispute proceedings. Mid-market retailers running on-premise transportation management systems face 12-18 month upgrade cycles before API-enabled benchmarking deployment.
- Freight Forwarders:Intermediaries aggregating demand across multiple shipper accounts, creating volume-based data contributions that strengthen benchmark statistical validity.
- Logistics Providers:Third-party operators managing outsourced transportation functions on behalf of shippers.
- Carriers:Asset-based providers seeking competitive intelligence, though many restrict transactional detail sharing.
Shippers command the deepest penetration, while Freight Forwarders are expanding their share most aggressively through multi-account data consolidation.
Industry Vertical:
Rate complexity and procurement sophistication diverge markedly across end-use sectors, with parcel and last-mile density driving service differentiation.
- E-Commerce:Direct-to-consumer fulfillment networks grappling with zone-based parcel pricing and last-mile accessorial proliferation. US apparel retailers managing volatile volume spikes now run always-on tender processes that auto-accept rates within benchmark-derived fairness bands.
- Retail:Omnichannel distribution networks requiring normalized comparisons across private fleet, dedicated contract carriage, and common carrier alternatives.
- Manufacturing:Raw material inbound and finished goods outbound movements with predictable lane densities and established carrier relationships.
- Healthcare:Temperature-controlled and time-definite shipments with compliance documentation requirements that complicate pure rate benchmarking.
E-Commerce claims the steepest expansion trajectory, while Retail maintains the largest installed base of benchmarking subscriptions.
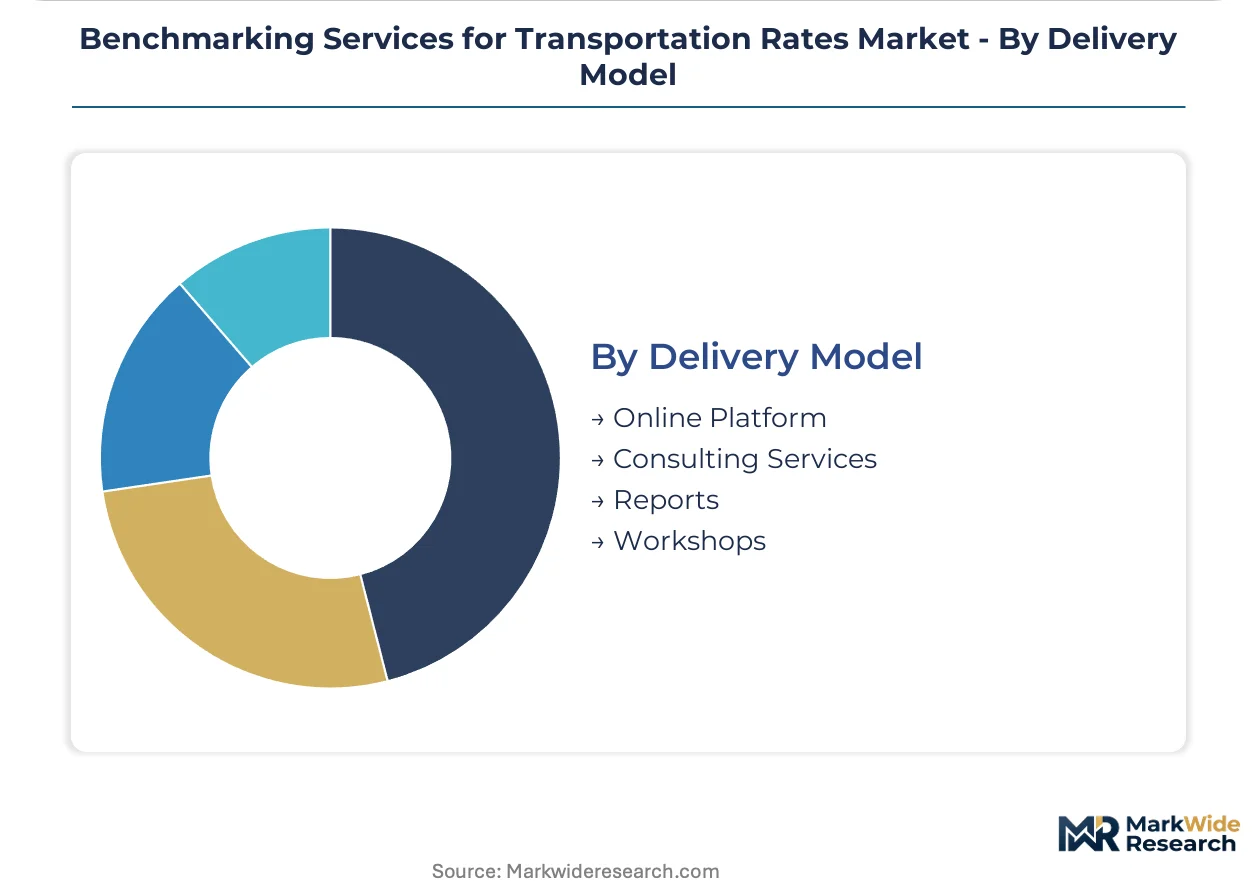
Delivery Model:
Data velocity and integration depth separate modern platform offerings from legacy consulting engagements, with buyer technical maturity dictating model selection.
- Online Platform:Self-service interfaces with API connectivity for continuous data ingestion and real-time benchmark updates. Machine learning architectures now compress latency from weeks to hours, redefining competitive positioning around freshness rather than historical depth.
- Consulting Services:High-touch engagements for complex network redesign and carrier negotiation support, commanding premium pricing but lower recurring revenue.
- Reports:Static periodic deliverables suitable for governance documentation and board-level reporting.
- Workshops:Training and knowledge transfer sessions building internal benchmarking capabilities at shipper organizations.
Online Platform subscriptions generate the highest recurring revenue, though Consulting Services still captures the largest average contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Surface Transportation Board anchors the regulatory framework shaping transportation rate benchmarking demand across North America, while the EU Green Deal and emerging disclosure mandates in Asia-Pacific create parallel compliance pressures.
United States
E-commerce fulfillment networks and petrochemical shippers drive concentrated demand for real-time rate validation. The Surface Transportation Board's ongoing rail rate reasonableness proceedings push cargo owners toward independent benchmarking services. The Gulf Coast corridor from Houston to New Orleans generates acute benchmarking needs as volatile fuel surcharge structures outstrip in-house analytical capacity.
Germany
Automotive and chemical shippers require carbon-adjusted rate comparisons under emissions trading requirements. The EU Green Deal embeds Scope 3 emissions costs into cross-border freight calculations, forcing benchmark normalization for carbon intensity differentials. The Rhine-Ruhr industrial cluster and Port of Hamburg logistics hubs now reject rate comparisons lacking embedded carbon pricing data.
United Kingdom
Omnichannel retailers and pharmaceutical distributors seek parcel and last-mile benchmarking for post-Brexit customs complexity. The Financial Conduct Authority's climate disclosure expectations extend to supply chain rate transparency for listed filers. The Midlands distribution belt and London orbital freight corridors concentrate demand for continuous procurement validation tools.
China
Cross-border e-commerce platforms and electronics manufacturers drive demand for multimodal rate visibility across Belt and Road corridors. The Ministry of Transport's digital logistics initiatives accelerate API standardization for freight data exchange. The Yangtze River Delta and Pearl River Delta manufacturing belts generate dense transaction flows requiring real-time benchmark updates.
Netherlands
Rotterdam-centric petrochemical and agribusiness shippers require benchmarked rate fairness for barge, rail, and road modal splits. The EU CSRD mandates supply chain cost disclosure that elevates rate benchmarking to governance necessity. The Randstad logistics cluster and Maasvlakte port complex concentrate demand for carbon-adjusted intermodal rate comparisons.
Benchmarking Services for Transportation Rates Market Competitive Landscape
Load-board aggregators and payment-data incumbents split the market between transaction-velocity and spend-depth competitive vectors. The vendor base concentrates around three strategic archetypes: infrastructure-leveraged data aggregators, financial-services-anchored spend analysts, and marketplace-native visibility platforms. Consolidation pressures favor API-first providers with continuous data feeds over static report generators. Competitive moves center on machine-learning latency reduction and cross-modal expansion beyond over-the-road freight.
Among infrastructure-leveraged aggregators, DAT Freight & Analytics and SONAR occupy positions exemplifying load-board-derived transaction density. Cass Information Systems anchors the payment-data archetype through spend-processing relationships yielding proprietary shipper account datasets. Freightos represents the marketplace-native model, extending benchmarking logic from ocean and air cargo visibility into broader multimodal rate transparency.
| Leading Market Players |
|---|
| DAT Freight & Analytics |
| Cass Information Systems |
| SONAR |
| Freightos |
| nVision Global |
| Transporeon |
| Starlight Analytics |
| SIS International Research |
| The Logit Group |
| Others |
Pricing and Supply Chain Analysis
The Houston-to-New Orleans petrochemical corridor anchors North American supply capacity for transportation rate benchmarking services, with data engineering talent pools concentrated in this Gulf Coast cluster translating directly into pricing power for API-first platform providers. Volatile fuel surcharge structures across these lanes force shippers toward premium-priced real-time validation tools that collapse procurement cycles from quarterly to continuous.
Pricing Analysis
Price spreads between US Gulf Coast and Midwest logistics hubs reveal a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command differentiation through sub-hour latency updates and dedicated API infrastructure, while standard offerings rely on batch-file delivery with 24-48 hour refresh cycles. Cost compression in economy tiers is intensifying because carrier data withholding forces benchmarkers toward expensive indirect spend proxies. Mid-market retailers running legacy TMS platforms prove most price-sensitive, whereas large e-commerce fulfillment teams with dedicated data engineering capacity absorb premium pricing for real-time feeds.
Supply Chain Analysis
Extended payment terms from enterprise shippers now stretch to 90-120 days, forcing benchmarking providers to secure supply-chain finance facilities or cede working capital to larger platform competitors. Data science talent concentrates in the United States, Germany, and the Netherlands, with regression modelers drawing from fintech and ad-tech labor pools. Raw material inputs rest on proprietary carrier transaction feeds, TMS integration middleware, and cloud compute infrastructure. Single-source vulnerability runs through DAT Freight & Analytics and Cass Information Systems, whose load-board and payment-processing data networks lack close substitutes. Distribution runs through direct enterprise sales teams and systems integrator partnerships serving mid-market shippers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across service intensity tiers creates entry niches as e-commerce logistics teams outgrow in-house analytical capacity and seek specialized parcel benchmarking tools. This demand-side shift rewards focused challengers over broad-platform incumbents.
For Market Incumbents: Build switching-cost moats through deep TMS integration and proprietary data network effects. Incumbents should secure exclusive payment-processing relationships that yield shipper spend data unavailable to competitors, while embedding machine-learning latency reduction that collapses benchmark publication from hours to minutes. Digital freight brokerages pose the most acute substitution threat as they collapse information asymmetries natively. For New Entrants and Emerging Players: Southeast Asia's cross-border e-commerce corridors offer the most penetrable white-space opportunity, with Chinese electronics manufacturers and ASEAN fulfillment networks lacking localized rate visibility tools. New entrants should target EU Green Deal carbon-adjusted benchmarking as a differentiated wedge, embedding Scope 3 emissions normalization that German automotive and Dutch chemical shippers now reject comparisons without. A channel partnership go-to-market with regional freight forwarders accelerates data network buildout without direct enterprise sales overhead. For Investors and Strategic Acquirers: Long-term, this sits as a data-network-effects play because continuous benchmarking feeds exhibit increasing returns to scale that compound over the projection horizon. Acquisition targets should display API-first infrastructure with sub-hour latency capabilities and existing carrier data partnerships that would take 18-24 months to replicate organically. The signal to watch is STB rate reasonableness proceeding volume, which transforms benchmarking from operational convenience to litigation necessity and expands addressable spend.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Migration | Real-time streaming architectures enable dynamic procurement workflows that collapse RFP cycles from quarterly to continuous. |
| Carbon-Adjusted Benchmark Development | EU Green Deal compliance positions providers for German automotive and Dutch chemical shipper contracts requiring Scope 3 normalization. |
| TMS Integration Partnership | Deep ERP connectivity locks in mid-market retailers facing 12-18 month upgrade cycles before independent deployment. |
| Load Board Data Exclusivity | Proprietary transaction feeds from DAT Freight & Analytics yield statistically valid peer datasets competitors cannot replicate. |
| Cross-Modal Expansion | Ocean and air rate visibility extension captures Freightos-demonstrated demand beyond over-the-road freight benchmarking. |
Research Methodology
Desk research of SEC supply chain disclosure filings, STB rate reasonableness dockets, EU emissions trading registries, and TMS vendor technical documentation preceded structured interviews with logistics procurement directors, carrier pricing strategists, freight forwarder operations leads, and benchmarking platform product managers. Primary fieldwork combined with secondary validation across customs transaction databases, load board aggregation records, and payment processing spend reports. Bottom-up segmentation modeling triangulated against top-down market sizing from disclosed vendor revenue ranges.
Forecasts reflect assumptions of continued API standardization progress, sustained e-commerce logistics complexity growth, and stable regulatory enforcement of disclosure mandates across the analysis window. Segmentation dimensions modeled include service type intensity, buyer sophistication tier, industry vertical procurement patterns, and delivery model technical maturity. CAGRs derived from regression-fitted adoption curves incorporating shipper IT integration cycle times and carrier data sharing willingness indices.
Macroeconomic conditions sit as an overlay; deviation in freight volume cyclicality, fuel price volatility, or interest rate environments would shift the trajectory. Forecasts reflect documented assumptions without scenario-weighted probability distributions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
India Taxi Market
Transportation Services
Waste Collection Vehicle Market
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
ASEAN Taxi Market
Transportation Services
United States Vehicle Rental Market
Transportation Services
Thailand Car Rental Market
Transportation Services
Truck Sharing Market
Transportation Services
North America International Express Service Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Airline Passenger Service System Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Global Garbage Truck Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
Vietnam Car Rental Market
Transportation Services
Full-Service Carrier Market