
 Drayage Services Market | 2026-2036
Drayage Services Market Size, Share, and Industry Trends Forecast 2026-2036
Drayage Services Market Analysis
Telematics integration with automated dispatch platforms is fragmenting traditional drayage operating models into digital-first and legacy-dependent tiers. Schneider National leverages proprietary freight-matching algorithms to optimize container turns at major ports. J.B. Hunt Transport Services, Inc. anchors its drayage network through intermodal terminal ownership along the US Gulf and Atlantic corridors. XPO Logistics, Inc. competes on density, concentrating chassis pools near high-volume rail ramps to reduce empty-mile ratios.
Drayage services constitute short-haul trucking movements—typically under 100 miles—connecting maritime ports and intermodal rail terminals to distribution centers, warehouses, and final receivers, using specialized chassis, flatbeds, or refrigerated units designed for ISO container compatibility. The primary commercial purpose centers on bridging the first and last miles of international supply chains where ocean or rail handoffs occur. Container drayage dominates service volume due to structural dependence on port throughput, while intermodal drayage captures expanding margin pools as railroads push for extended gate-to-gate service commitments. Refrigerated units within equipment type represent the fastest-growing segment, driven by temperature-sensitive pharmaceutical and fresh-produce flows through ports like Savannah and Miami.
The Federal Motor Carrier Safety Administration enforces hours-of-service limits and electronic logging device mandates that constrain driver availability and shape fleet sizing decisions across US drayage operations. The Environmental Protection Agency, alongside California Air Resources Board, imposes escalating emissions standards that force carrier capital allocation toward electric or near-zero-emission tractors, particularly at Los Angeles-Long Beach and Oakland. Stakeholders must monitor how port authority clean-truck programs and pending federal zero-emission corridor designations reshape equipment replacement cycles and terminal access rules.
Market Dynamics
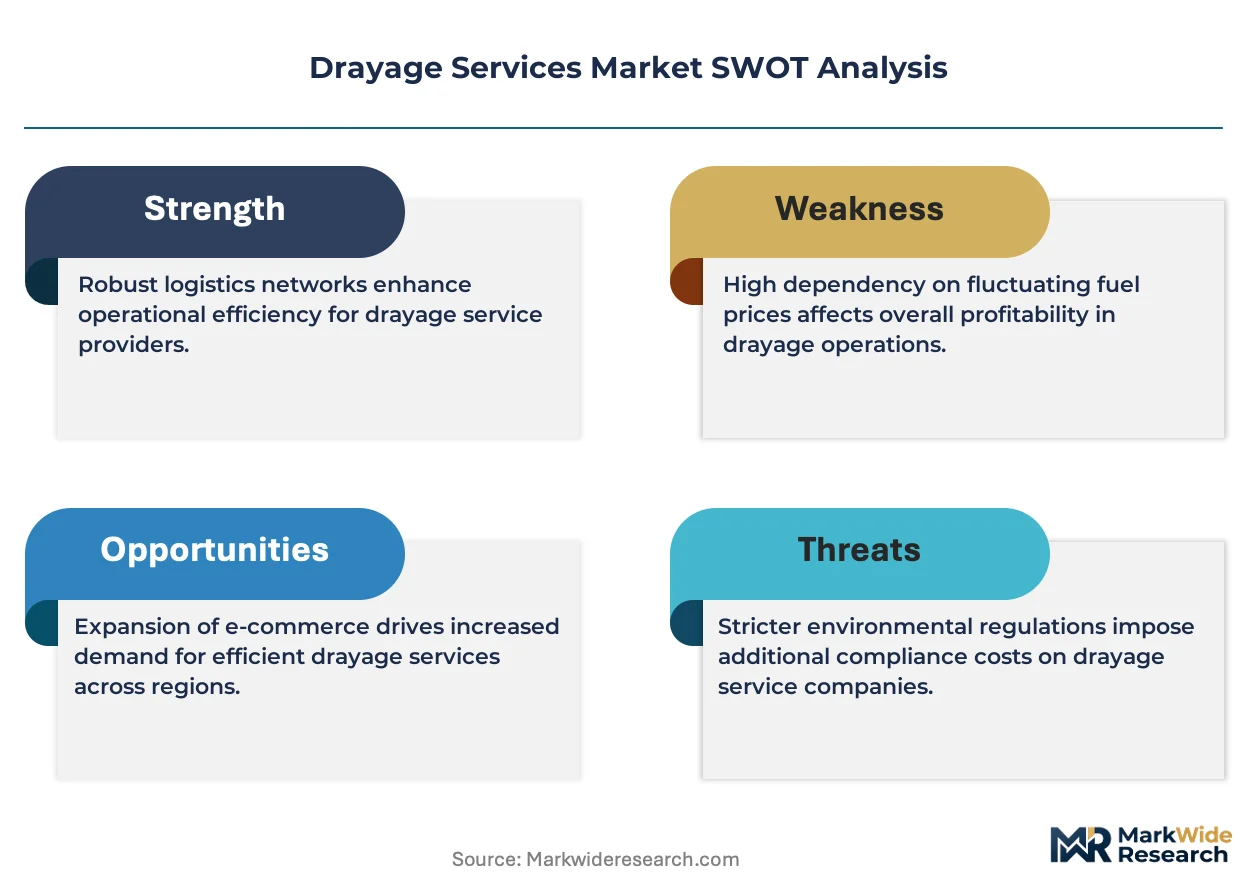
Telematics-enabled dispatch automation is bifurcating drayage operations into algorithm-optimized fleets and legacy-dependent carriers, compressing turn times at maritime terminals and forcing capital reallocation toward digital infrastructure.
Growth Catalysts
- Port Authority Clean-Truck Programs:Los Angeles-Long Beach and Oakland mandate near-zero-emission chassis, accelerating fleet turnover and creating equipment financing demand.
- Refrigerated Container Flows:Pharmaceutical cold-chain requirements through Savannah and Miami drive specialized chassis deployment with telematics monitoring.
- E-commerce Fulfillment Density:Port-to-warehouse container movements concentrate in the US Southeast, where Savannah and Charleston expansions absorb trans-Pacific volume diversion from West Coast congestion.
Market Restraints
- Driver Availability Constraints:FMCSA hours-of-service limits and ELD mandates cap fleet utilization rates, forcing carriers to overstaff to maintain lane coverage.
- Chassis Pool Fragmentation:Equipment ownership disperses across ocean carriers, leasing pools, and motor carriers, creating coordination friction at high-volume ramps.
- Emissions Compliance Capital Burden:EPA Clean Trucks Plan and CARB regulations impose tractor replacement cycles that strain mid-size carrier balance sheets.
Strategic Opportunities
- Intermodal Gate-to-Gate Contracts:Railroads seek extended service commitments, allowing drayage operators to capture margin pools beyond terminal drayage.
- Electric Tractor Early-Mover Positioning:Federal zero-emission corridor designations favor carriers with charging infrastructure at port-adjacent yards.
- Density-Based Chassis Positioning:Concentrating equipment near high-volume rail ramps reduces empty-mile ratios and improves asset turns.
Industry Challenges
- Telematics-Legacy System Integration:Automated dispatch platforms require API connectivity with port terminal operating systems, which vary by maritime authority.
- Certified Technician Shortage:Electric and near-zero-emission tractors demand specialized maintenance skills that vocational pipelines have not yet scaled.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drayage Services Market |
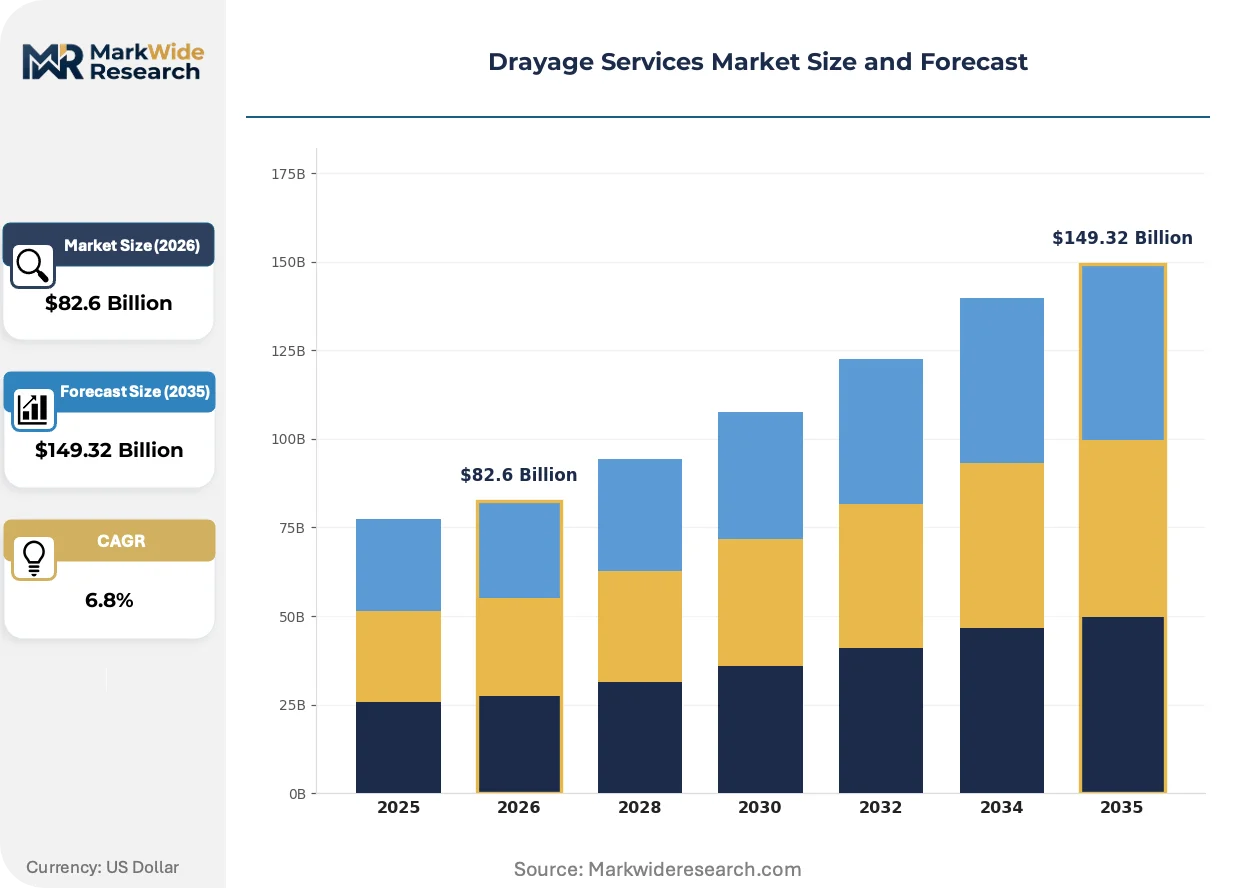
| Market Size in 2026 | $82.6 Billion |
| Market Size in 2035 | $149.32 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Port Drayage, Intermodal Drayage, Last-Mile Drayage, Container Drayage End User: Manufacturers, Distributors, Retailers, Freight Forwarders Equipment Type: Flatbed Trucks, Chassis, Container Trailers, Refrigerated Units Delivery Model: Direct Delivery, Scheduled Delivery, On-Demand Delivery, Contractual Delivery |
| Companies Covered | Schneider National, NFI, J.B. Hunt Transport Services, Inc., RoadOne Intermoda Logistics, Inc., IMC Companies, XPO Logistics, Inc., Landstar System, ContainerPort Group, Hub Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drayage Services Market Emerging Trajectories
Digital freight-matching platforms are compressing dispatcher-to-driver communication cycles, while regulatory emissions mandates and buyer procurement consolidation reshape equipment investment and service contracting models.
Cloud-based dispatch software is virtualizing traditional broker-carrier relationships by algorithmically matching container availability with chassis position and driver hours. Mid-size fleets adopt these platforms to compete with integrated carriers on turn-time visibility. The technology is virtualizing manual dispatch functions into automated load-tendering workflows that compress empty-mile ratios.
California's CARB regulations and the EPA Clean Trucks Plan impose escalating NOx and particulate standards that force diesel tractor retirement ahead of normal depreciation cycles. Carriers operating at Los Angeles-Long Beach and Oakland face 2024-2035 phase-in timelines that compress capital planning horizons. The refrigerated drayage segment responds fastest, as pharmaceutical and produce shippers demand emissions documentation for Scope 3 reporting.
Large retailers consolidate drayage procurement under single-source contracts with gate-to-gate liability terms, displacing fragmented spot-market arrangements. This procurement compression favors carriers with intermodal terminal ownership and proprietary chassis pools. The US Southeast exhibits the sharpest consolidation, where Savannah port expansion has attracted integrated logistics providers seeking captive drayage capacity.
Drayage Services Market Segmentation
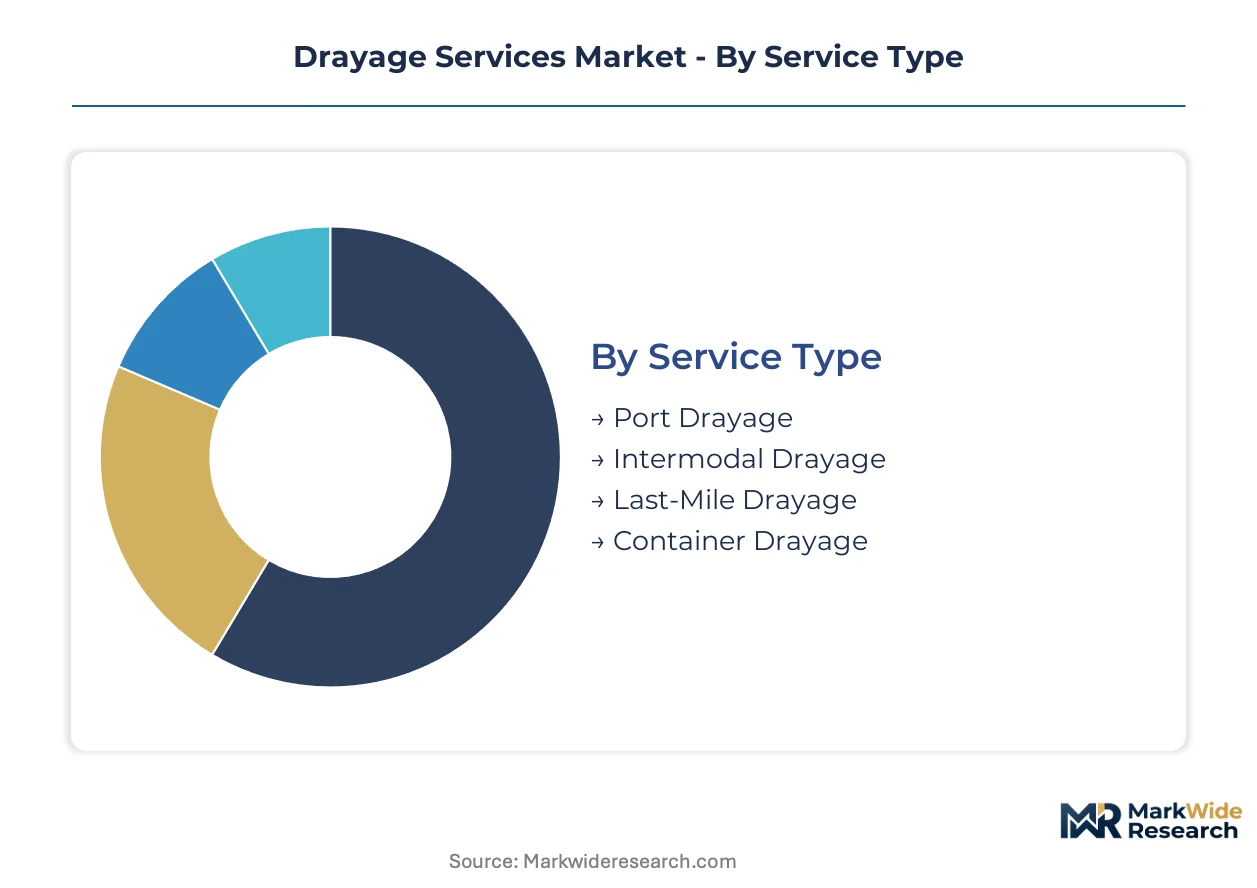
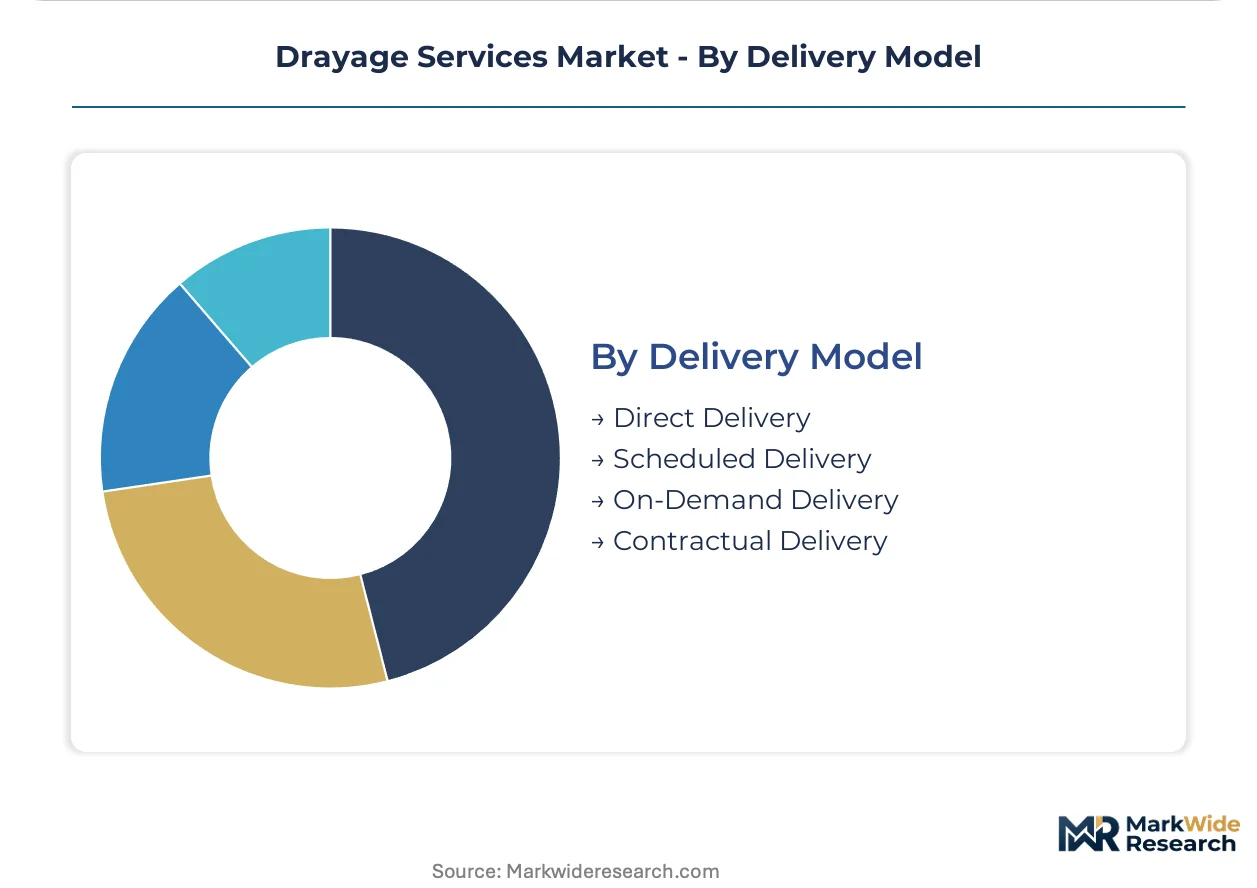
Drayage service segmentation reveals how operational specialization, equipment configuration, and contracting structures determine carrier economics. Each dimension carries distinct margin profiles and capital requirements that shape competitive positioning.
Service Type:
Application focus distinguishes revenue stability and asset utilization patterns across drayage operations.
- Port Drayage:Maritime terminal-to-warehouse movements using specialized chassis for ISO container handoffs. Demand concentrates at Los Angeles-Long Beach and Savannah where ocean carrier volume creates predictable lane density.
- Intermodal Drayage:Rail ramp connections extending railroad service commitments to final receivers. Shippers at Chicago and Memphis intermodal terminals drive expansion as Class I railroads push gate-to-gate contracts.
- Last-Mile Drayage:Short-haul final delivery from distribution centers to end receivers.
- Container Drayage:Standardized box movements dominating transaction volume.
Port Drayage commands the established base. The steepest expansion runs through Intermodal Drayage.
End User:
Customer type determines contract structure, payment terms, and service level requirements.
- Retailers:Large-format merchants consolidating procurement under single-source agreements with gate-to-gate liability. E-commerce fulfillment density through Savannah and Charleston drives chassis pool investment.
- Freight Forwarders:Intermediaries bundling drayage with ocean and air cargo coordination. Pharmaceutical cold-chain flows through Miami create specialized equipment demand with telematics documentation.
- Manufacturers:Industrial shippers with just-in-time production schedules.
- Distributors:Wholesale intermediaries requiring flexible scheduling.
Retailers anchor volume concentration. The steepest expansion trajectory belongs to Freight Forwarders.
Equipment Type:
Asset configuration dictates maintenance protocols, regulatory compliance timelines, and per-mile operating economics.
- Refrigerated Units:Temperature-controlled chassis with integrated gensets for pharmaceutical and produce flows. CARB and EPA Clean Trucks Plan mandates accelerate electric reefer deployment at California ports for Scope 3 reporting compliance.
- Chassis:Specialized frames for container mounting, subject to port authority clean-truck programs. Pool ownership fragmentation across ocean carriers and leasing companies creates coordination friction at high-volume ramps.
- Flatbed Trucks:Open-deck equipment for oversized or non-containerized cargo.
- Container Trailers:Standard skeletal frames for dry box transport.
Chassis represent the installed base. Refrigerated Units are gaining share fastest.
Delivery Model:
Contracting structure shapes revenue predictability, driver scheduling, and empty-mile exposure.
- Contractual Delivery:Long-term agreements with dedicated capacity and fixed pricing. Large retailers in the US Southeast favor this structure for Savannah port expansion volumes.
- Scheduled Delivery:Recurring appointments with predetermined windows. Intermodal ramps at Chicago and Memphis use this model to align with train arrival patterns.
- Direct Delivery:Point-to-point movements without intermediate handling.
- On-Demand Delivery:Spot-market dispatch responding to immediate container availability.
Contractual Delivery holds the volume base. Scheduled Delivery shows the steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States container exports to Asia-Pacific manufacturing hubs drive chassis positioning along trans-Pacific corridors. European pharmaceutical cold-chain flows through Rotterdam and Hamburg reshape refrigerated equipment deployment. Southeast Asian manufacturing relocation accelerates port-to-warehouse movements through Singapore and Vietnam.
United States
Savannah and Charleston port expansions absorb West Coast volume diversion for e-commerce fulfillment density. EPA Clean Trucks Plan and California CARB regulations mandate near-zero-emission tractor replacements at Los Angeles-Long Beach through 2035. The Southeast logistics corridor from Georgia to South Carolina attracts integrated providers seeking captive drayage capacity.
Germany
Ruhr industrial manufacturing and Rhine chemical flows sustain intermodal rail ramp demand at Duisburg and Cologne. EU Green Deal emissions standards accelerate electric tractor pilot programs through national freight decarbonization incentives. Hamburg port cold-chain pharmaceutical exports drive specialized chassis telematics deployment.
China
Yangtze River Delta manufacturing exports to North America sustain Shanghai and Ningbo container throughput volumes. MEE dual carbon goals impose port-adjacent fleet electrification timelines at Shenzhen and Qingdao. Pearl River Delta electronics assembly clusters generate high-frequency port-to-bonded-warehouse movements.
Netherlands
Rotterdam pharmaceutical distribution and re-export flows to Middle Eastern markets concentrate refrigerated container movements. EU CSRD supply-chain disclosure requirements pressure carriers to document emissions for Scope 3 reporting compliance. Randstad logistics clustering around Venlo and Rotterdam creates density for automated dispatch platform adoption.
Singapore
Transshipment hub status connecting Southeast Asian manufacturing to European and North American consumer markets sustains high container turnover. Maritime Port Authority clean-vessel incentive schemes extend to terminal tractor electrification commitments. Tuas port megaproject expansion concentrates next-generation automated container handling and drayage coordination systems.
Drayage Services Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tiering. Integrated logistics providers with intermodal terminal ownership capture gate-to-gate contract margin pools. Asset-light brokers and digital freight platforms represent the second archetype, compressing dispatcher-to-driver cycles through algorithmic matching. Competitive moves concentrate on chassis pool densification near high-volume ramps and proprietary telematics integration with port terminal operating systems.
Among integrated North American carriers, Schneider National, J.B. Hunt Transport Services, Inc., and XPO Logistics, Inc. exemplify distinct strategic positioning archetypes. Schneider National occupies the algorithm-optimized fleet tier through proprietary freight-matching technology. J.B. Hunt Transport Services, Inc. anchors the intermodal terminal ownership model along Gulf and Atlantic corridors. XPO Logistics, Inc. represents density-based chassis positioning near high-volume rail ramps to reduce empty-mile exposure.
| Leading Market Players |
|---|
| Schneider National |
| NFI |
| J.B. Hunt Transport Services, Inc. |
| RoadOne Intermoda Logistics, Inc. |
| IMC Companies |
| XPO Logistics, Inc. |
| Landstar System |
| ContainerPort Group |
| Hub Group, Inc. |
| Others |
Supply Flow & Price Mechanics
The Los Angeles-Long Beach corridor compresses drayage pricing through chassis pool fragmentation and driver hour constraints, while EPA Clean Trucks Plan compliance costs differentiate contract rates between emission-compliant and legacy fleets serving e-commerce fulfillment centers.
Pricing Analysis
Legacy diesel tractor pricing, near-zero-emission premium tiers, and projected electric fleet rates stratify drayage contracting structures. Three-tier pricing structure across premium, standard, and economy levels reflects CARB compliance certification, chassis telematics integration, and gate-to-gate liability bundling. Cost compression in the standard tier intensifies because mid-size carriers absorb premature tractor depreciation to maintain port terminal access. E-commerce retailers exhibit highest price sensitivity due to consolidated procurement volumes, while pharmaceutical cold-chain shippers accept premium rates for emissions documentation.
Supply Chain Analysis
Chassis manufacturing concentrates in China, South Korea, and domestic US assembly plants serving port authority specifications. Electric tractor powertrains draw from lithium-ion cell production anchored in China, South Korea, and Japan, while telematics hardware sources from Taiwan semiconductor foundries. Single-source vulnerability runs through battery management system suppliers facing MEE dual carbon export licensing. Distribution runs through ocean carrier leasing pools, motor carrier owned fleets, and neutral chassis pool cooperatives at high-volume maritime terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drayage services operate through a cyclical recovery as trans-Pacific volume diversion from West Coast congestion to Southeast ports resets lane density economics and equipment positioning requirements.
For Market Incumbents: Entrench proprietary chassis pools near Savannah and Charleston expansion zones to capture e-commerce fulfillment density. Lock intermodal terminal ownership along Gulf and Atlantic corridors before railroads consolidate gate-to-gate contract awards. The EPA Clean Trucks Plan phase-in timeline compresses capital planning horizons for mid-size competitors, creating acquisition opportunities for carriers with balance sheet capacity to accelerate electric tractor deployment ahead of 2035 mandates. For New Entrants and Emerging Players: Port-to-warehouse refrigerated movements through Miami pharmaceutical corridors represent the most penetrable entry point for specialized chassis operators lacking legacy fleet conversion burdens. On-demand dispatch platforms serving fragmented spot-market drayage at Oakland and Long Beach offer second-tier white-space for algorithm-native fleets without intermodal terminal sunk costs. A telematics-first go-to-market angle bypasses dispatcher-heavy legacy cost structures. For Investors and Strategic Acquirers: CARB's 2024-2035 phase-in timeline reshapes the acquisition landscape toward carriers with early electric fleet positioning and port-adjacent charging infrastructure. Long-term viability across the analysis window favors integrated operators with density-based chassis positioning rather than asset-light brokers facing margin compression from automated dispatch platforms. Monitor federal zero-emission corridor designation announcements as the inflection signal for charging infrastructure subsidy access and terminal priority rules.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Tractor Fleet Conversion | EPA Clean Trucks Plan compliance secures port terminal access ahead of CARB phase-out deadlines. |
| Chassis Pool Densification | Concentrating equipment near Savannah rail ramps reduces empty-mile ratios below legacy network benchmarks. |
| Telematics Platform Integration | API connectivity with port terminal operating systems compresses dispatcher-to-driver communication cycles. |
| Intermodal Terminal Acquisition | Gate-to-gate contract eligibility captures margin pools beyond maritime terminal drayage. |
| Refrigerated Equipment Specialization | Pharmaceutical cold-chain flows through Miami generate premium rates with emissions documentation. |
Methodological Framework
A spread of perspectives from fleet operations managers, port authority procurement directors, intermodal terminal supervisors, and chassis pool administrators converged on the working assumptions. Primary interviews with motor carrier executives and railroad logistics planners combined with secondary validation from FMCSA enforcement data, EPA regulatory filings, port authority throughput statistics, and ocean carrier equipment leasing disclosures. Bottom-up triangulation across carrier fleet composition and top-down reconciliation against port container volume data anchored the modeling framework.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning service type, equipment configuration, end-user contract structure, and regional port cluster. CAGRs derived from equipment replacement cycle analysis, driver availability constraints, and emissions compliance capital requirements. Forecast inputs incorporated chassis pool utilization rates and telematics adoption curves by fleet size tier.
Practitioners should monitor CARB enforcement intensity, federal zero-emission corridor designation pace, and trans-Pacific shipping lane diversion patterns for early signals. Forecasts reflect assumptions around emissions technology cost curves and port authority clean-truck program adherence timelines. Quarterly review of chassis pool fragmentation indices and electric tractor deployment rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Asia Pacific Tourism Vehicle Rental Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Water Truck Rental Market
Transportation Services
Bike Rental Market
Transportation Services
Russia Car Rental Market
Transportation Services
Vehicle Management System Market
Transportation Services
Cross Docking Services Market
Transportation Services
Brazil Car Rentals Market
Transportation Services
Car Rental Service Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Multispace Parking Meter Market
Transportation Services
Airline Passenger Service System Market
Transportation Services
Middle East Car Rental Market
Transportation Services
Brazil Vehicle Rental Market