
 Sanitation Vehicle Market | 2026-2036
Sanitation Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitation Vehicle Market Insights
Modular body-on-chassis configurations is restructuring procurement patterns across municipal and contractor fleets. Zoomlion leverages its integrated manufacturing base to offer standardized module packages that reduce field assembly time. Dongfeng Motor anchors its position through captive diesel and electric powertrain production. Bucher Municipal differentiates via specialized high-pressure jetting and vacuum combinations for combined sewer cleaning operations.
A sanitation vehicle is a purpose-built motorized unit engineered for waste collection, transport, street cleaning, or liquid waste extraction, typically featuring reinforced steel or aluminum alloy bodies with compaction ratios between 3:1 and 6:1, hydraulic lift mechanisms, and sealed containment systems designed to prevent leachate discharge during transit. Compactor trucks dominate volume demand due to universal deployment across residential waste streams, while electric fuel-type variants represent the fastest-expanding segment as battery energy density improvements enable full-route operation without midday charging. Municipal end users command the largest share of fleet orders, though private contractors are capturing margin-rich specialized services in airport and industrial park sanitation.
EPA and NHTSA jointly govern emissions compliance and vehicle safety standards for sanitation vehicles operating in the United States, while the EU Green Deal and F-Gas Regulation constrain refrigerant and hydraulic fluid chemistries across European fleets. India's CEA and state pollution control boards are enforcing noise and particulate thresholds that accelerate CNG and electric adoption in metro jurisdictions. Stakeholders must monitor how battery-electric range performance under stop-start urban duty cycles affects total cost of ownership calculations against compressed natural gas alternatives.
Market Dynamics
Powertrain electrification is compressing total cost of ownership calculations across municipal fleets, with battery-electric platforms now achieving route parity against CNG alternatives in dense urban environments.
Growth Catalysts
- Smart Cities Mission (India):Central government allocations for mechanized waste collection are displacing manual cart systems in metro jurisdictions.
- Battery energy density gains:Lithium-ion cell improvements enable full-shift operation without midday charging, expanding electric compactor truck viability.
- Euro VI-equivalent standards:Emissions benchmarks across Southeast Asian markets are compelling fleet operators to retire legacy diesel platforms ahead of schedule.
Market Restraints
- Chassis supply concentration:Heavy-duty truck platform availability tightens when commercial vehicle OEMs prioritize long-haul freight over specialized municipal configurations.
- Copper and rare-earth price volatility:Electric powertrain motor windings and battery cathodes expose manufacturers to commodity input cost swings.
- Refueling infrastructure asymmetry:CNG station networks remain sparse outside tier-1 Indian and Chinese cities, constraining fleet expansion into secondary markets.
Strategic Opportunities
- Secondary city penetration (India):Tier-2 and tier-3 municipal corporations are initiating first-time mechanized collection tenders with lower entry barriers for new suppliers.
- Combined sewer cleaning specialization:High-pressure jetting and vacuum integration creates margin-rich service packages for airport and industrial park operators.
- Modular body standardization:Interchangeable compaction and liquid waste modules allow contractors to reconfigure single chassis across seasonal demand shifts.
Industry Challenges
- Electric vehicle technician scarcity:Municipal maintenance depots lack trained personnel for high-voltage battery diagnostics and thermal management system repair.
- Homologation timeline compression:Rapid regulatory iteration between EPA, Euro VI-equivalent, and state-level Indian standards forces redundant certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitation Vehicle Market |
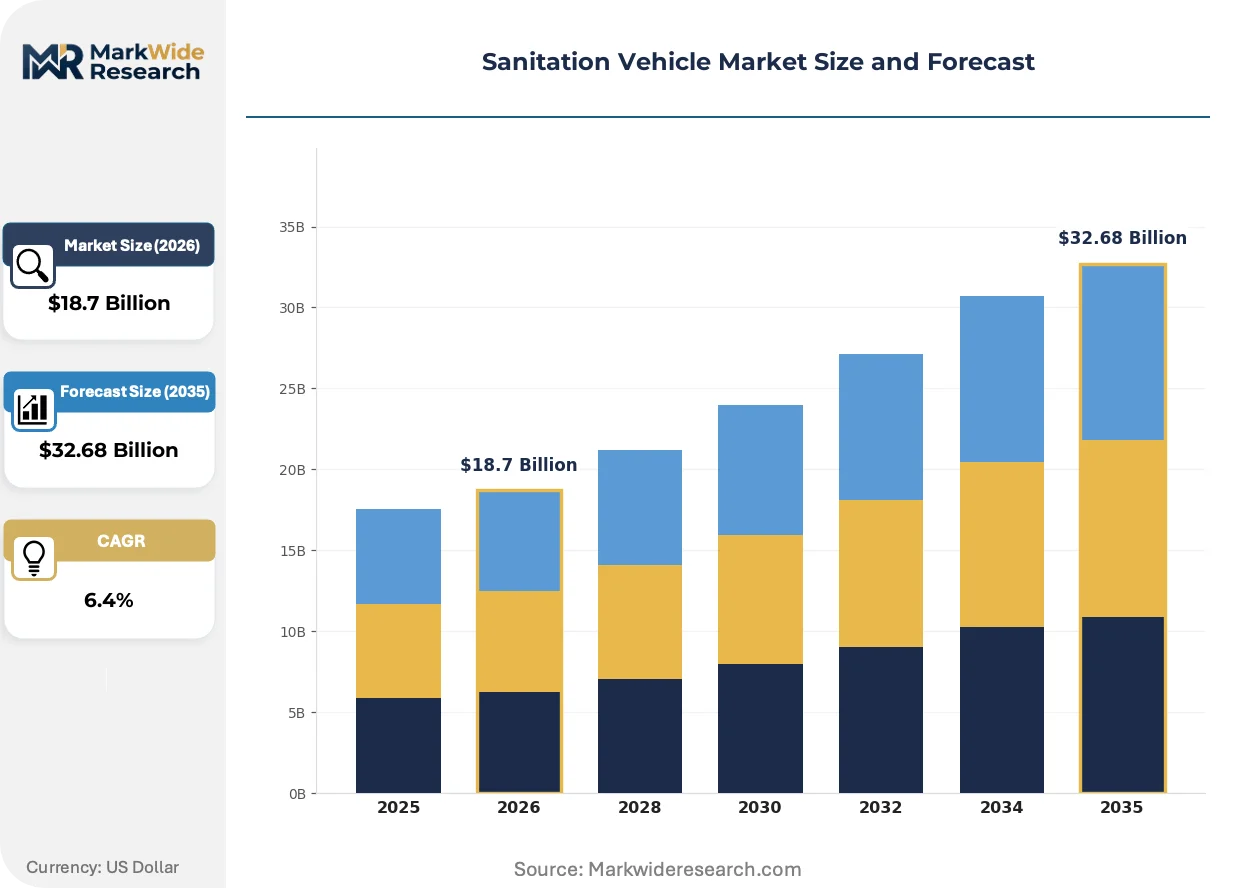
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Compactor Trucks, Vacuum Trucks, Street Sweepers, Liquid Waste Trucks Fuel Type: Diesel, CNG, Electric, Hybrid End User: Municipalities, Private Contractors, Waste Management Firms, Facility Managers Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Zoomlion, Dongfeng Motor, Cheng Li, Dennis Eagle, Labrie Enviroquip, McNeilus Truck & Manufacturing, Bucher Municipal, Fujian Longma Sanitation, Faun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitation Vehicle Market Trends and Innovations
Telematics integration and predictive maintenance algorithms are transforming fleet management economics, while powertrain diversification accelerates platform specialization across climate zones.
Modular battery-swapping architectures are unifying urban sanitation operations with last-mile logistics fleets, enabling shared infrastructure investments. Municipal procurement officers in Shenzhen and Delhi are piloting interchangeable pack standards that compress capital deployment timelines. This convergence is unifying previously siloed vehicle categories under common energy service company models.
India's CEA noise and particulate thresholds are accelerating CNG and electric adoption in metro jurisdictions, forcing OEMs to redesign exhaust after-treatment systems. State pollution control boards are conducting unannounced roadside emissions testing that raises non-compliance penalties. Fleet operators in Mumbai and Bengaluru are responding by front-loading electric platform procurement despite higher upfront capital requirements.
Lifecycle service contracting is displacing traditional equipment purchase models among private sanitation contractors. Performance-based agreements that bundle vehicle, maintenance, and operator provision are capturing share in airport and industrial park segments. This transition is most visible in Southeast Asian markets where labor cost arbitrage supports outsourced fleet operation economics.
Sanitation Vehicle Market Segmentation
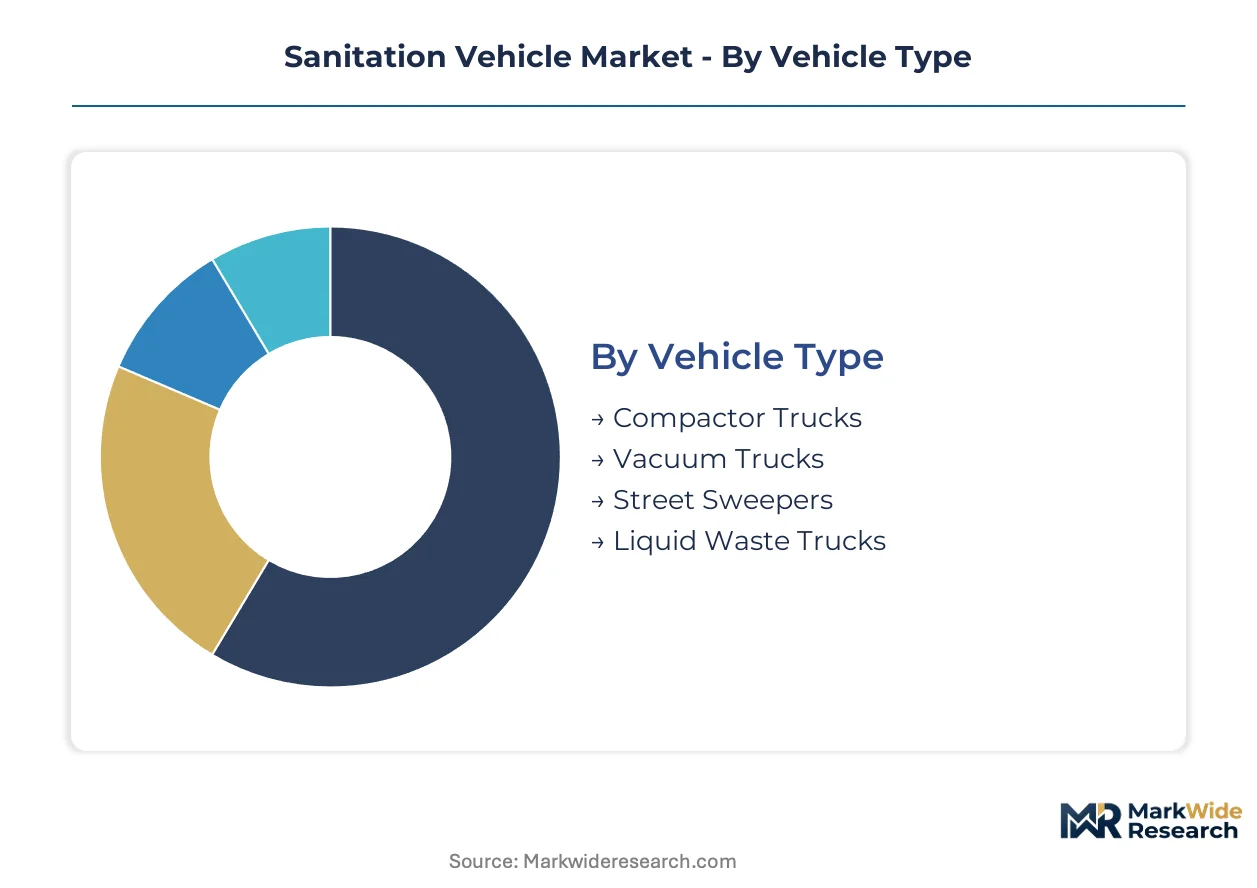
Segmentation in the sanitation vehicle market determines fleet procurement economics and technology deployment strategies. Municipal buyers prioritize route efficiency and emissions compliance, while private operators optimize for asset utilization across contract types. Understanding these divergent purchase criteria illuminates where manufacturers must configure modular platforms versus specialized builds.
Vehicle Type:
Application intensity and waste stream composition differentiate buyer requirements across vehicle categories.
- Compactor Trucks:Reinforced steel bodies with hydraulic compaction mechanisms achieve 3:1 to 6:1 volume reduction ratios for residential waste streams. Demand concentrates in Indian metro municipalities where Smart Cities Mission funding displaces manual collection systems; EPA and Euro VI-equivalent emissions standards accelerate fleet replacement cycles.
- Vacuum Trucks:High-capacity suction systems with sealed containment prevent leachate discharge during liquid waste extraction. Airport and industrial park operators in Southeast Asia drive specialized procurement for combined sewer cleaning operations where service bundling captures margin-rich contracts.
- Street Sweepers:Mechanical and regenerative air systems remove debris from urban road surfaces. European cities under EU Green Deal constraints favor electric variants for noise-sensitive central districts.
- Liquid Waste Trucks:Corrosion-resistant tankage and pump systems transport non-hazardous effluent. Secondary Indian cities initiate first-time mechanized collection tenders with lower capital barriers.
Volume sits with compactor trucks; growth tilts toward vacuum trucks.
Fuel Type:
Total cost of ownership calculations now hinge on energy infrastructure maturity and duty cycle predictability rather than upfront capital alone.
- Diesel:Legacy powertrain with established service networks dominates existing fleet bases. Euro VI-equivalent standards across Southeast Asia force premature retirement in dense urban jurisdictions.
- CNG:Compressed natural gas offers interim emissions reduction where electric charging infrastructure remains undeveloped. Indian state pollution control boards enforce particulate thresholds that accelerate CNG adoption in Mumbai and Bengaluru.
- Electric:Battery-electric platforms with lithium-ion cell architectures now achieve full-shift route operation without midday charging. Shenzhen and Delhi pilot modular battery-swapping standards that unify sanitation with last-mile logistics fleets.
- Hybrid:Dual powertrain configurations bridge range anxiety and emissions compliance for variable route lengths. Early deployment concentrates in Japanese metro areas under METI decarbonization guidelines.
Diesel retains installed base dominance; electric platforms are climbing the fastest.
End User:
Contract structure and operational risk allocation determine whether buyers favor capital purchase or performance-based service models.
- Municipalities:Public sector fleet operators command largest order volumes through centralized procurement. India's tier-2 and tier-3 municipal corporations are expanding mechanized collection coverage with standardized tender specifications.
- Private Contractors:Outsourced operators capture specialized service segments through lifecycle contracting that bundles vehicle, maintenance, and labor provision. Southeast Asian airport sanitation contracts exhibit this transition most visibly.
- Waste Management Firms:Integrated collection and processing operators optimize fleet composition for transfer station logistics. CNG station network density constrains their expansion beyond tier-1 Indian and Chinese cities.
- Facility Managers:On-site sanitation for industrial parks and commercial campuses demands compact, maneuverable configurations. Electric variants gain preference for indoor and noise-restricted environments.
Volume concentrates with municipalities; growth momentum favors private contractors.
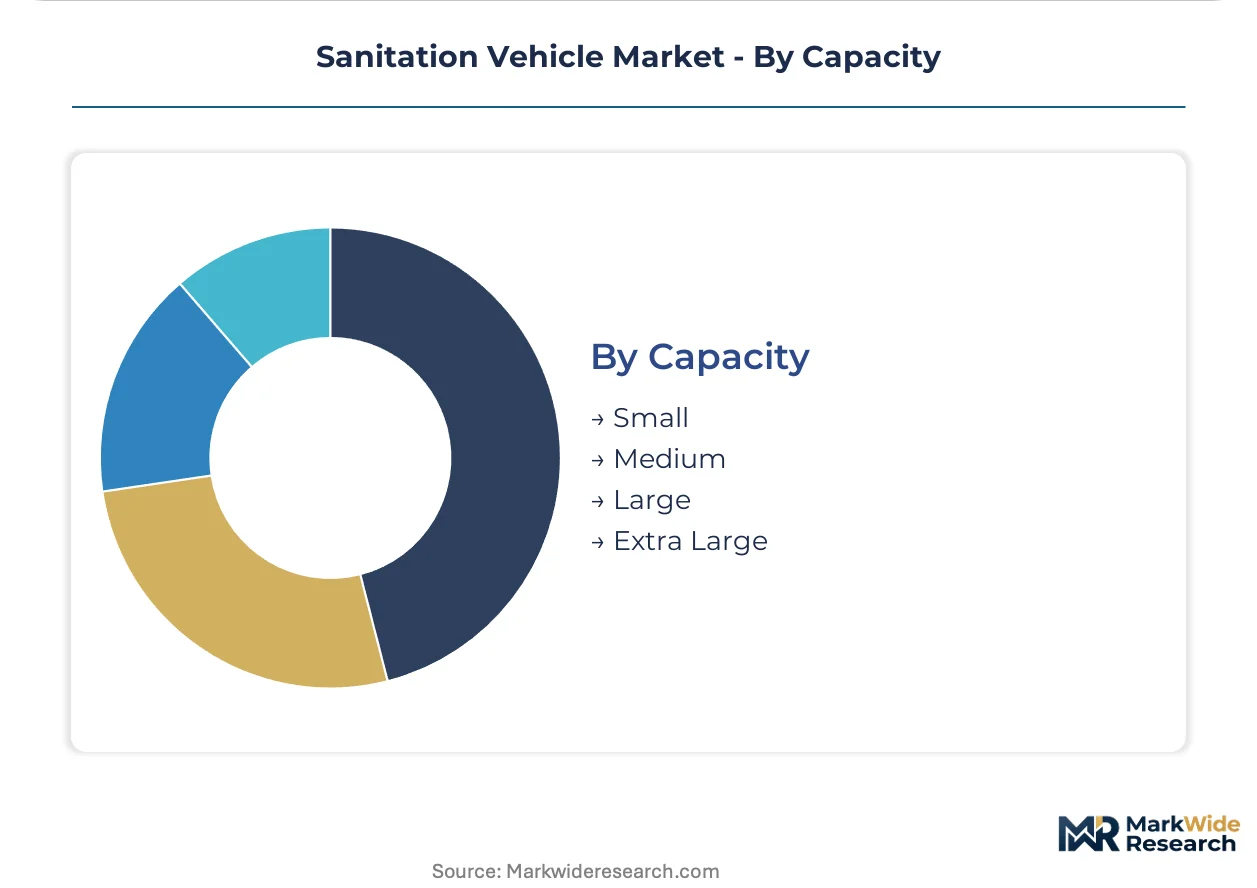
Capacity:
Route density and collection frequency dictate payload requirements that cascade into chassis specification and powertrain selection.
- Small:Narrow-body configurations navigate historic European city centers and confined industrial facilities. Battery-electric variants suit predictable short-loop routes with overnight depot charging.
- Medium:Balanced payload and maneuverability serve standard residential collection rounds. Indian Smart Cities Mission procurement favors this tier for primary metro deployment.
- Large:High-volume compaction for dense urban corridors and commercial waste streams. Chassis supply tightens when commercial vehicle OEMs prioritize long-haul freight platforms.
- Extra Large:Maximum payload configurations for regional transfer and bulk collection routes. Limited to markets with adequate road infrastructure and minimal bridge weight restrictions.
Medium capacity dominates current procurement; large formats are expanding most quickly in high-density Asian metros.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of sanitation vehicle chassis and compaction systems, while India and Southeast Asian markets absorb expanding fleet volumes through municipal procurement programs. This production-consumption divide shapes trade flows and technology transfer patterns across the sector.
China
Domestic OEMs control integrated supply chains from chassis stamping to body assembly, serving both municipal fleets and export markets. MIIT dual carbon goals and GB standards for commercial vehicle emissions accelerate electric platform development in Shenzhen and Beijing-Tianjin-Hebei industrial corridors. Yangtze River Delta manufacturers pilot modular battery-swapping architectures that unify sanitation with logistics vehicle specifications.
India
Smart Cities Mission central allocations drive mechanized waste collection procurement across Mumbai, Delhi-NCR, and Bengaluru metro jurisdictions. CEA noise and particulate thresholds enforced by state pollution control boards compel CNG and electric adoption ahead of diesel retirement schedules. Tier-2 municipal corporations in Gujarat and Tamil Nadu initiate first-time fleet tenders with standardized specifications.
United States
EPA emissions benchmarks and NHTSA safety standards govern heavy-duty chassis certification for refuse collection applications. Municipal fleet operators in California and New York Metro prioritize electric compactor trucks under state-level zero-emission vehicle mandates. Midwest manufacturing clusters supply specialized hydraulic systems for automated side-loader configurations.
Germany
EU Green Deal constraints and F-Gas Regulation limits on hydraulic fluid chemistries reshape powertrain architecture decisions. KBA type-approval processes enforce Euro VI-equivalent standards that eliminate legacy diesel platforms from urban service contracts. Bavaria-based engineering clusters develop combined sewer cleaning systems for airport and industrial park operators.
Japan
METI decarbonization guidelines accelerate hybrid powertrain deployment in Tokyo and Osaka metro collection fleets. JIS standards for commercial vehicle durability influence chassis specification for high-frequency stop-start urban duty cycles. Nagoya industrial corridor manufacturers supply compact electric sweepers for noise-restricted central district operations.
Sanitation Vehicle Market Competitive Landscape
The competitive structure tilts toward integrated manufacturing conglomerates with captive chassis and body production capabilities. Market concentration remains moderate, with regional specialists commanding procurement relationships through localized service networks. Three archetypes dominate: diversified heavy-equipment conglomerates with sanitation divisions, commercial vehicle OEMs with municipal chassis specialization, and dedicated environmental equipment fabricators. Consolidation pressure manifests through backward integration into battery and hydraulic component supply, alongside geographic expansion via distributor acquisition in secondary Indian and Southeast Asian markets.
Among Chinese integrated manufacturers, Zoomlion and Dongfeng Motor exemplify the conglomerate archetype through captive powertrain and chassis production. Bucher Municipal occupies a position within the European specialist tier, representing engineering-intensive configurations for combined vacuum and jetting applications. Dennis Eagle anchors UK-based municipal vehicle fabrication, serving refuse collection fleet operators through standardized body-on-chassis packages.
| Leading Market Players |
|---|
| Zoomlion |
| Dongfeng Motor |
| Cheng Li |
| Dennis Eagle |
| Labrie Enviroquip |
| McNeilus Truck & Manufacturing |
| Bucher Municipal |
| Fujian Longma Sanitation |
| Faun |
| Others |
Pricing and Supply Chain Analysis
Copper and rare-earth price volatility cascades through electric powertrain motor windings and battery cathodes, compressing margins in premium-tier compactor trucks while tier-2 Indian municipalities absorb cost-down pressure through standardized CNG configurations.
Pricing Analysis
Cost-down pressure on mid-tier compactor trucks accelerates because chassis supply tightens when commercial vehicle OEMs prioritize long-haul freight over municipal configurations. Three-tier pricing structure across premium, standard, and economy levels separates electric platforms with battery-swapping compatibility from CNG interim solutions and legacy diesel retirements. Price differentiation hinges on Euro VI-equivalent certification grade and after-sales service bundling. Private contractors in Southeast Asian airport segments exhibit lowest price sensitivity due to lifecycle contracting models, while tier-3 Indian municipal corporations drive hardest bargain on upfront capital.
Supply Chain Analysis
Euro VI-equivalent and EPA certification gates chassis and body assembly sourcing, favoring integrated manufacturers with captive homologation capabilities. Supply concentrates in China for lithium-ion cell production, India for CNG powertrain integration, and Germany for high-pressure hydraulic systems. Raw material dependencies span copper motor windings, rare-earth permanent magnets, and specialized hydraulic fluid chemistries constrained by EU F-Gas Regulation. Single-source vulnerability concentrates in battery cell supply from Yangtze River Delta producers. Distribution runs through municipal procurement officers and private contractor fleet managers with divergent tender specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive battery and hydraulic component supply determines margin defense against commodity input swings and homologation timeline compression.
For Market Incumbents: Acquire battery-swapping infrastructure assets to lock in recurring revenue streams from municipal fleet operators. Secure chassis allocation agreements with commercial vehicle OEMs before long-haul freight demand peaks. Defend against emerging electric powertrain specialists by deepening in-house production of thermal management systems and high-voltage diagnostics capability. For New Entrants and Emerging Players: Tier-2 and tier-3 Indian municipal corporations with first-time mechanized collection tenders represent the most penetrable buyer archetype. Target combined sewer cleaning specialization for airport and industrial park operators where service bundling captures margin-rich contracts. Enter through modular body standardization partnerships that allow single-chassis reconfiguration across seasonal demand shifts. For Investors and Strategic Acquirers: Unannounced roadside emissions testing by Indian state pollution control boards is the leading indicator that electric platform procurement will front-load despite higher upfront capital requirements. Long-term viability centers on manufacturers with integrated chassis-body capabilities and captive powertrain production. Monitor CNG station network density expansion beyond tier-1 Indian and Chinese cities as inflection signal for interim technology investment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Captive lithium-ion production insulates Zoomlion and Dongfeng Motor from copper and rare-earth price volatility. |
| Modular Body Standardization | Interchangeable compaction and liquid waste modules allow contractors to reconfigure single chassis across seasonal demand shifts. |
| Combined Sewer Cleaning Specialization | High-pressure jetting and vacuum integration creates margin-rich service packages for Bucher Municipal in airport segments. |
| Battery-Swapping Infrastructure Partnership | Shenzhen and Delhi pilot shared pack standards that compress capital deployment timelines for municipal procurement officers. |
| Lifecycle Service Contracting Transition | Performance-based agreements bundling vehicle, maintenance, and operator provision capture share in Southeast Asian private contractor segments. |
Research Methodology
Trade databases, regulatory filings with EPA and EU type-approval authorities, and municipal tender documentation formed the secondary backbone, validated through primary interviews with fleet procurement officers, aftermarket service heads, and powertrain engineering directors. Bottom-up unit shipment estimates triangulated against top-down municipal budget allocation analysis across the analysis window.
Historical trendline analysis of compactor truck and vacuum truck deployment patterns informed projection modeling across vehicle type, fuel architecture, end-user contract structure, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation against macro fleet replacement cycles and Smart Cities Mission allocation trajectories. Forecast inputs incorporated battery energy density improvement curves and CNG station network density expansion assumptions.
Revisions become necessary when EPA or Euro VI-equivalent regulatory iteration accelerates homologation timelines, or when copper and rare-earth commodity price swings exceed historical volatility bands. A model refresh is warranted upon material change in Indian state pollution control board enforcement intensity or modular battery-swapping standard adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Germany Car Rental Market
Transportation Services
Drayage Services Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
MUV Rental Market
Transportation Services
Airport Handling Service Market
Transportation Services
Car Rental Market
Transportation Services
Bird Carriers Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
Bulk Transportation Services Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Middle East Car Rental Market
Transportation Services
Bike Rental Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
Global Taxi Market