
 Malaysia Car Rental Market | 2026-2036
Malaysia Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Car Rental Market Outlook
Integrated telematics and AI-driven fleet management platforms are reshaping how Malaysian operators deploy, maintain, and price vehicle inventories. SOCAR Malaysia leverages real-time utilization data to optimize per-hour car sharing yields across Kuala Lumpur and Penang. Hawk Rent A Car sustains its position through deep channel control at Sultan Abdul Aziz Shah Airport and Langkawi ferry terminals. GoCar Malaysia differentiates via in-house production of its proprietary keyless entry hardware, reducing third-party dependency.
Car rental denotes a commercial service where vehicle ownership temporarily transfers to a user for a defined period, typically governed by mileage caps, insurance riders, and fuel policies. Fleet operators manage asset depreciation through standardized maintenance intervals, GPS immobilizers, and centralized reservation architectures that match vehicle class to customer profile. Self-drive rentals anchor revenue volume across Malaysian operators, while long-term corporate contracts generate the densest margin pools due to predictable utilization and bulk negotiation leverage. Chauffeur-driven services occupy a premium tier concentrated around diplomatic zones, luxury hospitality clusters, and executive airport transfers in Putrajaya and KL Sentral.
Malaysia's Land Public Transport Agency (APAD) regulates commercial vehicle permits, while the Road Transport Department (JPJ) enforces safety inspection standards and driver qualification protocols. The Ministry of Transport's e-hailing and car-sharing framework amendments are tightening insurance mandates and vehicle age limits, which elevates compliance costs for smaller fleet holders. Stakeholders must monitor how JPJ's proposed real-time emissions monitoring integration reshapes fleet renewal cycles and capital deployment timing.
Market Dynamics
Malaysia's car rental sector is undergoing structural compression as APAD licensing reforms accelerate peer-to-peer fleet formalization while telematics platforms rewrite asset utilization economics across the Klang Valley corridor.
Growth Catalysts
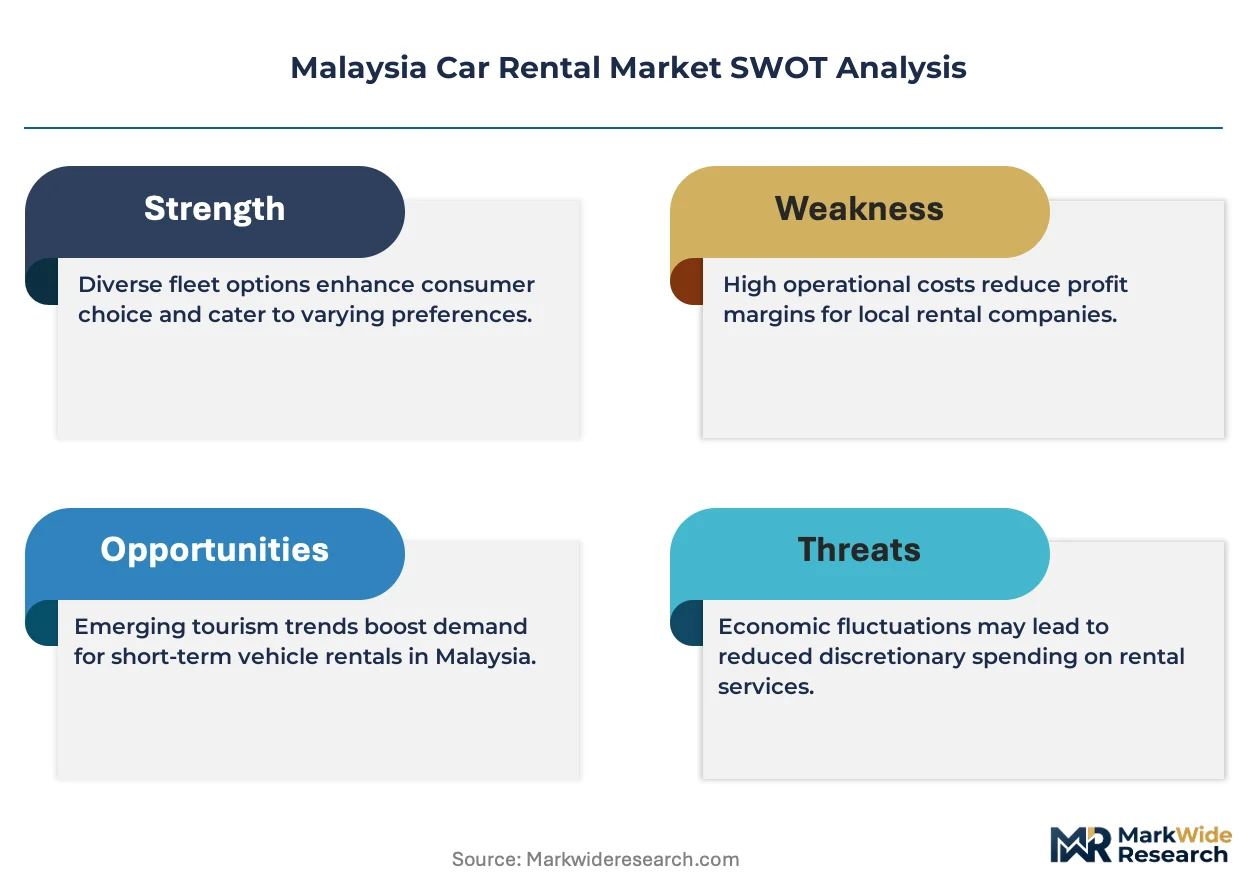
- APAD Licensing Reforms:Streamlined peer-to-peer vehicle approvals are dissolving regulatory friction for private fleet monetization, expanding supply-side participation beyond traditional commercial operators.
- Corporate Mobility Budgets:Selangor-based enterprises are consolidating ground transportation spend under centralized procurement platforms, generating predictable long-term contract volumes for fleet holders.
- AI-Driven Fleet Management:Real-time utilization analytics are optimizing vehicle deployment cycles, reducing idle depreciation and enabling dynamic pricing granularity across airport and urban micro-zones.
Market Restraints
- JPJ Emissions Integration:Proposed real-time emissions monitoring mandates are elevating compliance capital requirements for smaller fleet holders unable to absorb retrofit costs.
- Insurance Mandate Escalation:Ministry of Transport amendments to e-hailing and car-sharing frameworks are compressing margins through tightened coverage requirements and vehicle age ceiling reductions.
- Fleet Depreciation Velocity:Accelerated model turnover cycles in the domestic automotive market are shortening residual value windows, pressuring asset financing structures.
Strategic Opportunities
- Langkawi Ferry Terminal Channel Control:Underexploited tourism arrival points outside Kuala Lumpur-Penang axes offer first-mover positioning for integrated rental-ferry booking partnerships.
- Keyless Hardware Convergence:Proprietary IoT entry systems combined with mobile wallet integration are opening subscription-based mobility service architectures beyond transactional rental.
- Putrajaya Diplomatic Zone Premium Tier:Chauffeur-driven service gaps around federal administrative centers and KL Sentral executive transfer corridors remain underserved relative to volume potential.
Industry Challenges
- Telematics Talent Scarcity:Fleet operators face acute shortages of data engineers capable of translating utilization analytics into dynamic yield management algorithms.
- Legacy Reservation Architecture Integration:Established operators struggle to graft real-time pricing engines onto centralized booking systems designed for static rate card structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Car Rental Market |
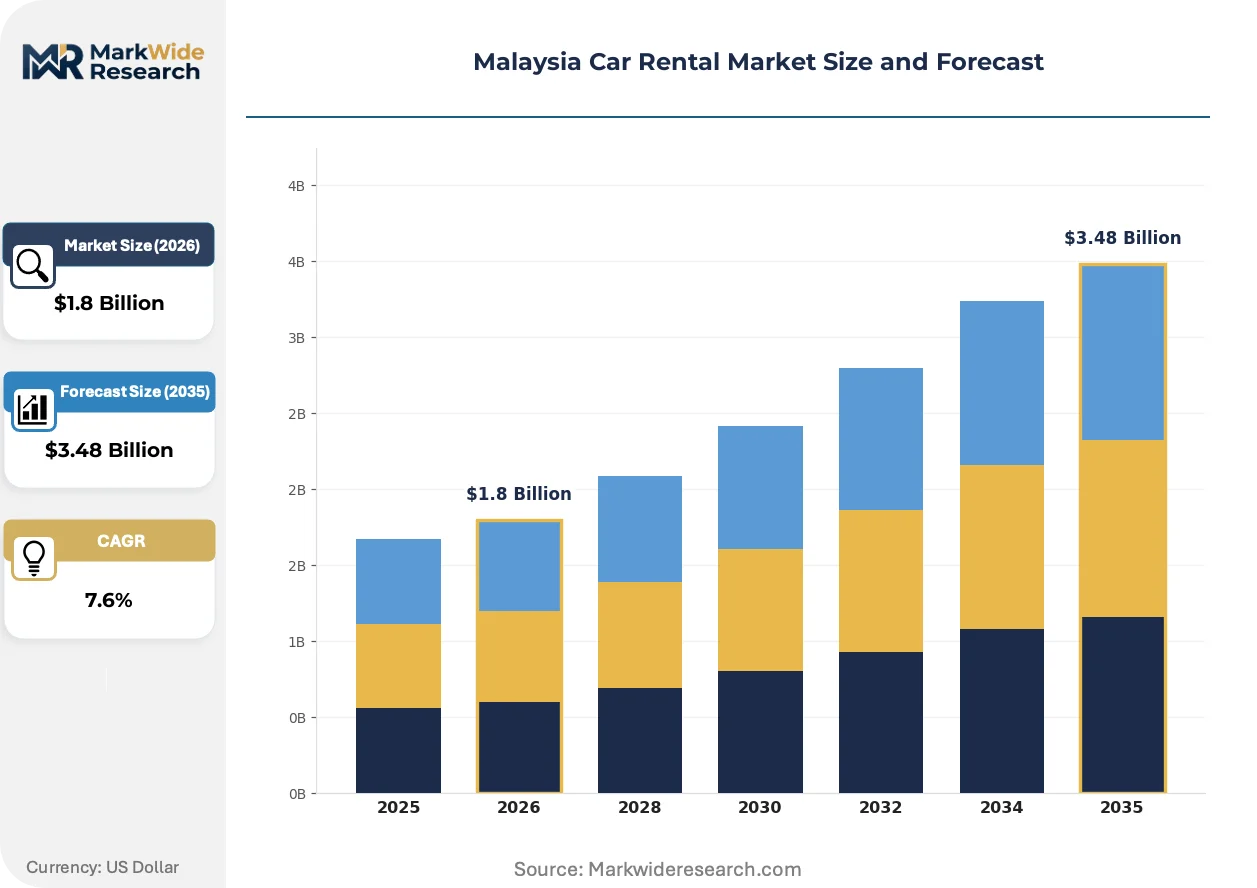
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Self-Drive, Chauffeur-Driven, Car Sharing, Ride-Hailing Vehicle Type: Luxury Cars, SUVs, Sedans, Vans Customer Type: Corporate Clients, Tourists, Locals, Event Planners Duration: Daily Rentals, Weekly Rentals, Monthly Rentals, Long-Term Rentals |
| Companies Covered | Sixt Rent a Car, Hawk Rent A Car, Hertz Malaysia, GoCar Malaysia, SOCAR Malaysia, Avis Malaysia, Mayflower Car Rental Sdn Bhd, Green Matrix Solutions, Europcar Malaysia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Car Rental Market Strategic Shifts
Digital infrastructure is compressing traditional fleet economics while regulatory digitization and shifting mobility procurement patterns rewrite competitive rules across Malaysian urban corridors.
Keyless entry hardware combined with mobile-native reservation platforms is digitizing vehicle access workflows, eliminating physical counter dependencies. Airport and hospitality sector fleet managers are deploying these systems at accelerating velocity to capture walk-up demand without staffing overhead. This technology stack is digitizing the entire pre-rental verification chain, collapsing pickup friction from thirty-minute counter queues to sub-sixty-second smartphone activation.
APAD's peer-to-peer vehicle framework amendments are mandating commercial insurance riders and standardized safety inspection protocols for previously informal fleet participation. The regulatory shift is forcing capital-light operators into formal compliance structures or exit. Selangor's Klang Valley corridor, where informal supply concentration was highest, is experiencing the most acute operator consolidation as enforcement timelines compress.
Corporate transportation procurement is fragmenting across specialized micro-providers rather than consolidating under legacy national fleet contracts. Multinational enterprise mobility managers in Kuala Lumpur are unbundling long-term leases from short-term rental and chauffeur services, selecting category-specialist vendors for each use case. This pattern is most visible in technology and financial services verticals, where procurement autonomy has devolved to regional facility managers with localized vendor selection authority.
Malaysia Car Rental Market Segmentation
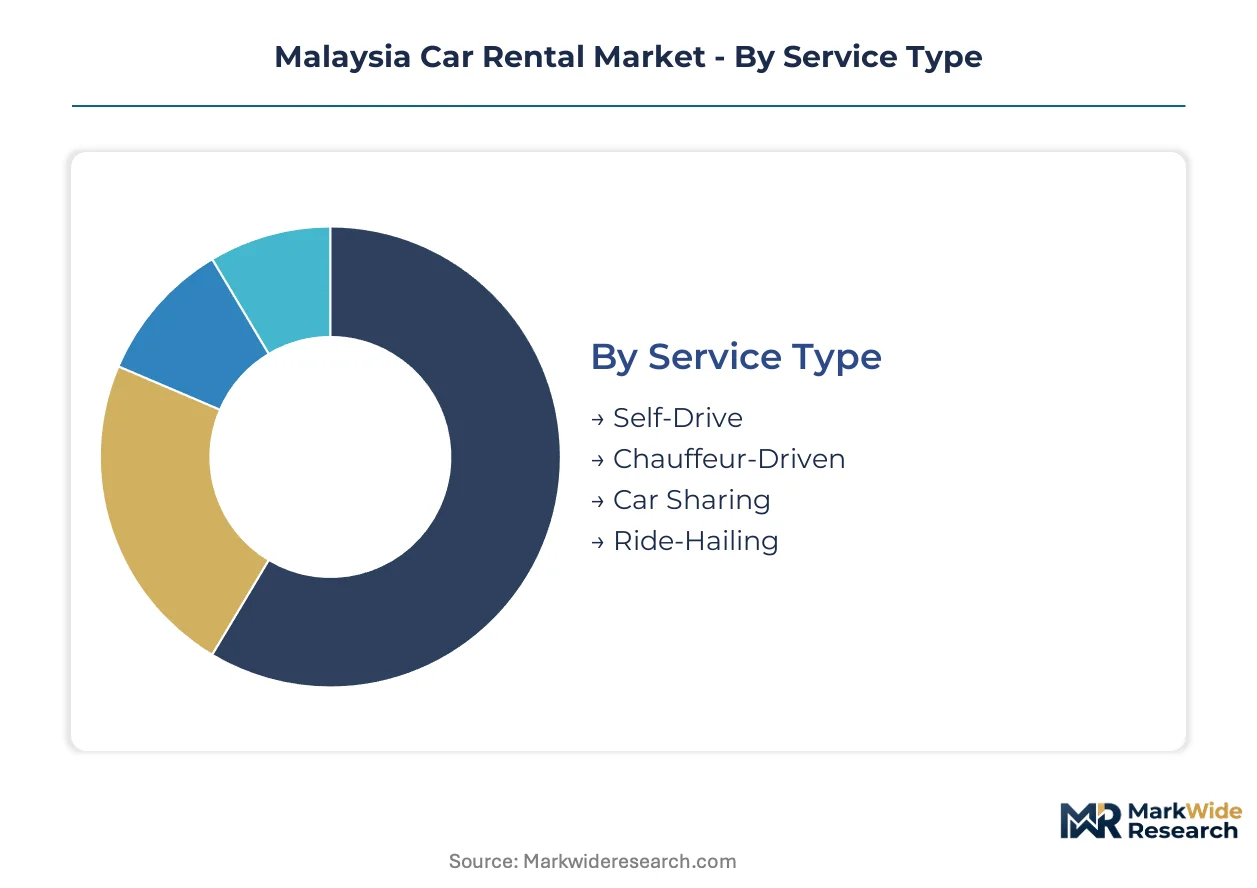
Malaysia's car rental market fragments across service modalities, asset classes, and procurement patterns that reshape how fleet operators deploy capital. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume scales.
Service Type:
Mature self-drive operations coexist with emerging mobility-as-a-service platforms, creating divergent capital intensity profiles across the Klang Valley corridor.
- Self-Drive:Direct vehicle custody transfers to end-users through standardized insurance riders and fuel-return protocols. Corporate procurement teams in Selangor favor this modality for predictable mobility budgeting, while airport transfer demand at Sultan Abdul Aziz Shah sustains walk-up revenue.
- Chauffeur-Driven:Professional driver provision bundled with vehicle access, concentrated around diplomatic zones in Putrajaya and executive hospitality clusters near KL Sentral. Premium tier pricing reflects driver certification costs and extended liability coverage.
- Car Sharing:Hourly and fractional access models enabled by proprietary keyless hardware and mobile-native reservation platforms. APAD licensing reforms are accelerating peer-to-peer fleet formalization in this segment.
- Ride-Hailing:On-demand driver-vehicle matching through digital dispatch platforms, subject to Ministry of Transport insurance mandate escalations that compress operator margins.
Self-Drive retains volume leadership; Car Sharing holds the steepest expansion curve.
Vehicle Type:
Cost tier differentiation separates premium asset depreciation profiles from high-utilization workhorse categories.
- Luxury Cars:Premium marques deployed for diplomatic protocol, executive airport transfers, and hospitality sector partnerships. Langkawi tourism corridors generate seasonal demand spikes that challenge fleet utilization planning.
- SUVs:Elevated ground clearance and passenger capacity suit intercity corporate travel and family tourism routes connecting Penang with highland destinations. Fleet holders optimize SUV deployment around weekend demand clustering.
- Sedans:Volume backbone for daily rental operations, with standardized maintenance intervals minimizing downtime across high-rotation urban deployments.
- Vans:Multi-passenger and light cargo configurations serving event logistics and group tourism movements, particularly around ferry terminal arrivals.
Sedans anchor fleet scale; Luxury Cars capture the widest margin spreads.
Customer Type:
Procurement autonomy patterns fragment vendor selection across centralized enterprise platforms versus dispersed individual decision-making.
- Corporate Clients:Centralized ground transportation procurement through Selangor-based enterprise mobility managers, generating long-term contract volumes with predictable utilization.
- Tourists:International and domestic leisure travelers concentrated at airport arrival points and Langkawi ferry terminals, driving seasonal demand volatility.
- Locals:Resident users accessing vehicles for intermittent needs, increasingly migrating to car-sharing platforms as urban parking scarcity intensifies.
- Event Planners:Temporary fleet requirements for conferences, weddings, and corporate gatherings, demanding flexible duration structures and coordinated multi-vehicle logistics.
Corporate Clients provide revenue predictability; Tourists generate the highest per-transaction yields.
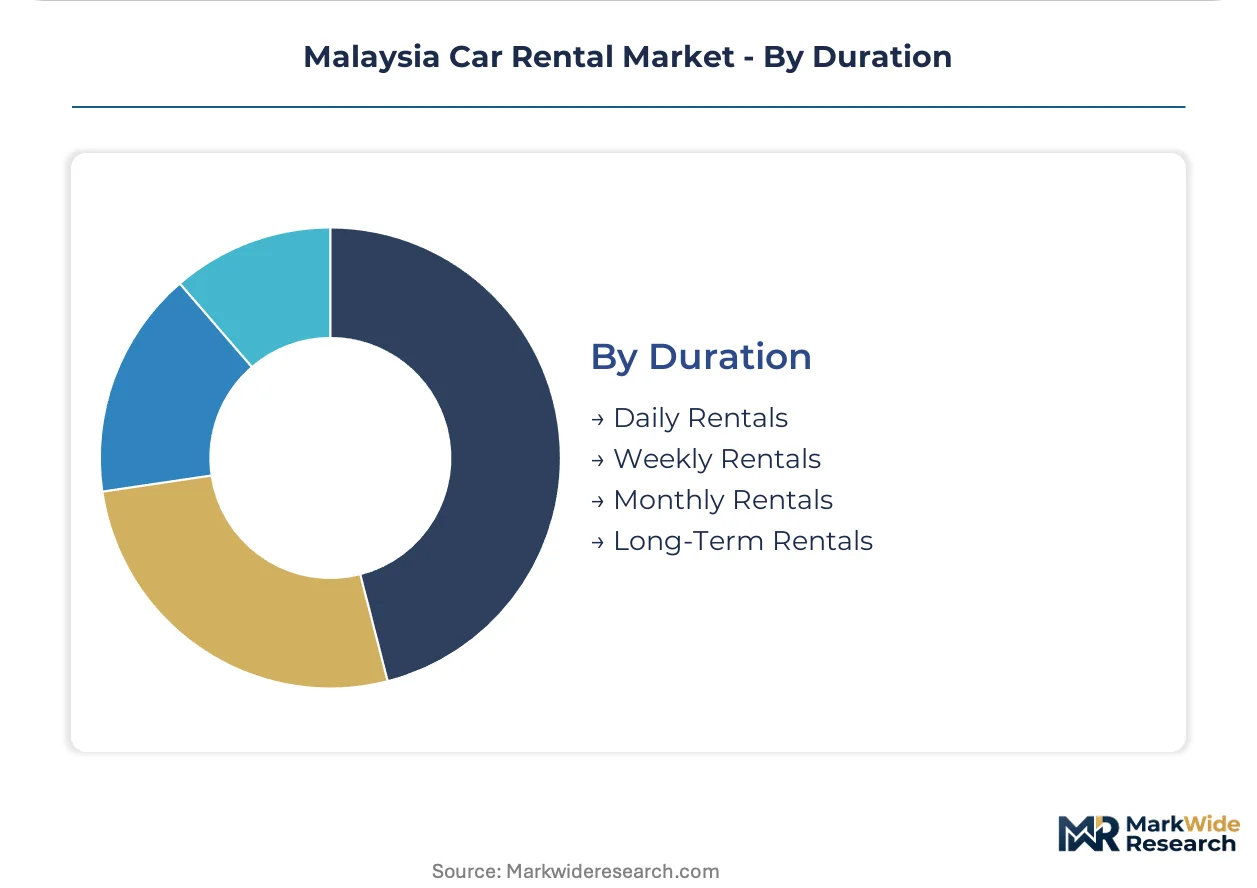
Duration:
Contract length directly determines depreciation risk allocation and pricing granularity.
- Daily Rentals:Transactional short-term access dominating airport and urban walk-up demand, with dynamic pricing responding to real-time utilization analytics.
- Weekly Rentals:Intermediate tenure bridging tourism itineraries and temporary corporate assignments, offering modest rate discounts against daily stacking.
- Monthly Rentals:Extended individual and small-business deployments where vehicle custody approaches lease-like characteristics without capital commitment.
- Long-Term Rentals:Enterprise contracts spanning multiple quarters with bundled maintenance and replacement vehicle provisions, generating the densest margin pools through utilization predictability.
Long-Term Rentals concentrate margin quality; Daily Rentals drive transaction velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore-based fleet operators export corporate mobility services into Johor Bahru and Iskandar Malaysia, capturing cross-border business travel demand through integrated booking platforms.
Selangor
Klang Valley corporate headquarters generate concentrated long-term rental contracts through centralized procurement platforms. Malaysia's Land Public Transport Agency (APAD) licensing reforms streamline peer-to-peer vehicle approvals across the state. Petaling Jaya and Subang Jaya host the densest telematics-enabled car-sharing deployments, where real-time utilization data optimizes hourly yield management.
Kuala Lumpur
Diplomatic zones and executive hospitality clusters near KL Sentral sustain premium chauffeur-driven demand. The Ministry of Transport's e-hailing and car-sharing framework amendments tighten insurance mandates for commercial operators. Bukit Bintang and KLCC districts concentrate keyless entry hardware deployments, eliminating physical counter dependencies for airport transfer corridors.
Penang
George Town tourism boards expand fleet partnerships with digital-first operators to capture international arrival flows. JPJ safety inspection standards enforce vehicle age limits that elevate compliance costs for informal fleet holders. Bayan Lepas and the ferry terminal corridor experience acute operator consolidation as enforcement timelines compress informal supply.
Langkawi
Seasonal tourism spikes challenge luxury vehicle utilization planning across resort and hospitality partnerships. The Road Transport Department enforces standardized safety protocols for commercial permits at ferry arrival points. Kuah town and Pantai Cenang anchor underexploited integrated rental-ferry booking opportunities outside mainland corridors.
Putrajaya
Federal administrative centers generate underserved chauffeur-driven demand around diplomatic protocol and executive transfers. APAD commercial vehicle permit regulations apply uniform standards across Putrajaya-Cyberjaya corridors. Precinct clusters near government complexes remain relatively open for premium-tier service positioning compared to saturated Klang Valley markets.
Malaysia Car Rental Market Competitive Environment
Channel-controlling players compete with product-specialist players across Malaysia's car rental sector, creating a tiered structure where airport and ferry terminal access separates volume leaders from urban micro-zone specialists. Three strategic archetypes dominate: legacy international brands with deep counter infrastructure, domestic fleet operators with proprietary technology stacks, and peer-to-peer platforms accelerated by regulatory formalization. Competitive moves concentrate on strategic partnerships with tourism boards and technology licensing for keyless entry systems.
Among international license holders, Sixt Rent a Car and Europcar Malaysia occupy positions representing established global reservation architectures. Domestic technology-integrated operators include GoCar Malaysia and SOCAR Malaysia, which exemplify the shift toward mobile-native platforms and real-time fleet analytics. Hawk Rent A Car anchors the channel-control archetype through concentrated presence at Sultan Abdul Aziz Shah Airport and Langkawi ferry terminals.
| Leading Market Players |
|---|
| Sixt Rent a Car |
| Hawk Rent A Car |
| Hertz Malaysia |
| GoCar Malaysia |
| SOCAR Malaysia |
| Avis Malaysia |
| Mayflower Car Rental Sdn Bhd |
| Green Matrix Solutions |
| Europcar Malaysia |
| Others |
Value Chain & Pricing Dynamics
Idle fleet compression across Selangor's Klang Valley corridor is forcing operators to rebalance asset deployment toward dynamic yield algorithms, while simultaneously pressuring procurement teams to shorten vehicle replacement cycles and renegotiate maintenance contract terms.
Pricing Analysis
Legacy telematics-enabled fleets command rate premiums against first-generation GPS-tracked inventory, while next-generation AI-driven utilization platforms remain in limited commercial deployment. Three-tier pricing structure across premium chauffeur-driven, standard self-drive, and economy car-sharing levels stratifies by service modality and insurance bundling. Cost compression in the economy tier is intensifying because APAD licensing reforms are flooding peer-to-peer supply into price-sensitive urban micro-zones. Corporate procurement managers demonstrate the lowest price sensitivity due to centralized mobility budgets, while individual tourists at ferry terminals exhibit acute rate elasticity.
Supply Chain Analysis
Extended payment terms from Japanese and South Korean OEMs are becoming decisive in fleet financing structures, particularly for operators scaling electric vehicle pilots. Vehicle procurement draws from Thailand, Japan, and South Korea as dominant assembly sources for Malaysian fleet holders. Keyless entry hardware, telematics control units, and commercial insurance riders constitute critical component dependencies. Single-source vulnerability concentrates in proprietary IoT firmware licensing from dominant technology vendors. Distribution runs through airport counter networks, hospitality partnerships, and mobile-native platforms in parallel channel architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's car rental sector reads as a service-attach opportunity where fleet maintenance subscriptions and insurance rider renewals are expanding faster than per-transaction rental yields.
For Market Incumbents: Entrench channel control at Sultan Abdul Aziz Shah Airport and Langkawi ferry terminals through exclusive tourism board partnerships, while accelerating proprietary telematics R&D to defend against digital-native entrants with AI-driven pricing engines. Deepen backward integration into keyless hardware production to capture margin pools currently flowing to third-party IoT vendors. For New Entrants and Emerging Players: Establish a beachhead in Putrajaya's diplomatic zone chauffeur-driven segment, where incumbent coverage gaps and premium pricing tolerance create viable entry economics. Target Langkawi's seasonal tourism corridor with integrated ferry-rental booking partnerships that legacy operators have underexploited. Lead with mobile-native reservation platforms and subscription-based mobility service architectures rather than transactional counter models. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across telematics-integrated fleet segments as APAD compliance mandates and emissions retrofit requirements elevate working capital demands. Acquisition candidates with established corporate contract books and proprietary technology stacks offer superior long-term viability against asset-heavy, technology-light fleet holders. Monitor JPJ enforcement timelines for real-time emissions monitoring as the critical signal for fleet renewal cycle acceleration and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Keyless Hardware Proliferation | GoCar Malaysia's in-house IoT production reduces third-party licensing costs and accelerates deployment velocity. |
| APAD Licensing Compliance | Formalized peer-to-peer frameworks are consolidating informal supply and elevating barriers for capital-light operators. |
| Corporate Mobility Platform Integration | SOCAR Malaysia's real-time utilization analytics optimize hourly yields across Kuala Lumpur's densest urban corridors. |
| Langkawi Ferry Terminal Channel Control | Hawk Rent A Car's concentrated presence captures seasonal tourism spikes with minimal competitive interference. |
| Telematics Talent Acquisition | Fleet operators securing data engineering capabilities translate utilization analytics into dynamic pricing algorithms faster. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet operations directors, corporate mobility procurement managers, APAD regulatory affairs leads, and tourism board partnership executives. Secondary validation incorporated APAD licensing amendment texts, JPJ safety inspection protocols, Ministry of Transport framework documents, and customs vehicle import registration data. Bottom-up fleet deployment modeling and top-down tourism arrival projections were triangulated to anchor market sizing.
Calibration against historical utilization rates and peer-to-peer fleet formalization timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service modality, vehicle class, customer procurement pattern, and contract duration structure. CAGRs were derived from fitted growth curves against regulatory enforcement schedules and corporate mobility budget expansion trajectories. Key inputs encompassed APAD licensing reform implementation timelines and JPJ emissions monitoring mandate progression.
Stress conditions across enforcement acceleration, insurance mandate escalation, and telematics adoption velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timelines and technology diffusion curves. Macroeconomic contraction, regulatory delay, or autonomous vehicle disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
MUV Rental Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Germany Car Rental Market
Transportation Services
Peer-To-Peer (P2P) Car-Sharing Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Global Garbage Truck Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Vietnam Car Rental Market
Transportation Services
Water Truck Rental Market
Transportation Services
Full-Service Carrier Market
Transportation Services
Online Bus Ticketing Service Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
Asia-Pacific Rickshaw Ride Hailing Service Market