
 Taxi and Ride-Hailing Services Market | 2026-2036
Taxi and Ride-Hailing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Taxi and Ride-Hailing Services Market Insights
The gap between premium black-car service and economy ride-pooling is hardening across urban mobility networks. Uber Technologies Inc. leverages its dual-platform architecture to capture both ends of this split, while Lyft Inc. anchors its position in North American commuter corridors with subscription loyalty programs. DiDi Global Inc. dominates regulatory complexity in China through direct municipal partnerships and localized compliance infrastructure.
Taxi and ride-hailing services constitute digitally dispatched passenger transportation operating through mobile application interfaces, GPS triangulation, and dynamic pricing algorithms calibrated to real-time supply-demand imbalances. The primary commercial purpose centers on reducing vehicle ownership friction while monetizing idle transport capacity through algorithmic matching. Ride-sharing and pooling segments lead volume generation in dense metropolitan zones where per-seat economics outperform solo rides, while electric vehicle deployments within fleet categories command premium positioning as cities tighten emissions enforcement. Corporate customer contracts sustain predictable revenue basins compared to volatile individual ride demand.
The EU Green Deal and F-Gas Regulation reshape fleet composition mandates across European operating territories, compelling platform operators to accelerate zero-emission vehicle integration or forfeit municipal licenses. In the United States, the EPA and state-level California Air Resources Board enforce divergent emissions trajectories that fragment national fleet standardization. Stakeholders must monitor how regulatory fragmentation between federal and sub-national authorities reconfigures capital allocation for vehicle procurement and charging infrastructure deployment.
Market Dynamics
Algorithmic dispatch systems and dynamic pricing engines are compressing driver earnings while concentrating trip volume toward platform-loyal operators, restructuring labor economics across metropolitan mobility corridors.
Growth Catalysts
- EU Green Deal fleet mandates:Zero-emission vehicle requirements in Paris, Berlin, and Amsterdam are accelerating electric taxi deployments and charging infrastructure buildouts.
- Urban density premiums:Megacity commuters in Mumbai, São Paulo, and Lagos generate disproportionate trip volume where per-seat pooling economics outperform private vehicle ownership.
- AI-powered route optimization:Machine learning models reduce deadhead mileage and passenger wait times, improving asset utilization for fleet operators.
Market Restraints
- Driver supply volatility:Earnings compression from algorithmic wage-setting creates chronic recruitment and retention friction in London, New York, and Singapore.
- Insurance cost escalation:Commercial liability premiums for ride-hail fleets have outpaced general auto insurance inflation, squeezing operator margins.
- Municipal licensing caps:New York City Taxi and Limousine Commission vehicle limits and similar quantity restrictions in Barcelona freeze market entry for new platforms.
Strategic Opportunities
- Corporate mobility contracts:Fortune 500 travel procurement departments are consolidating vendor relationships, creating predictable revenue basins distinct from volatile individual ride demand.
- Integrated multimodal platforms:Convergence of ride-hailing with bike-share, scooter, and public transit ticketing creates stickier user ecosystems in Stockholm and Vienna.
- India's tier-2 expansion:Jaipur, Lucknow, and Indore present underpenetrated corridors where smartphone penetration now supports app-based dispatch viability.
Industry Challenges
- EV charging infrastructure gaps:Fleet electrification timelines outpace grid capacity and fast-charger availability in São Paulo and Mexico City, forcing hybrid transition strategies.
- Cross-border data localization:Divergent privacy regimes between the EU's GDPR and India's draft data protection rules fragment cloud architecture and increase compliance engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taxi and Ride-Hailing Services Market |
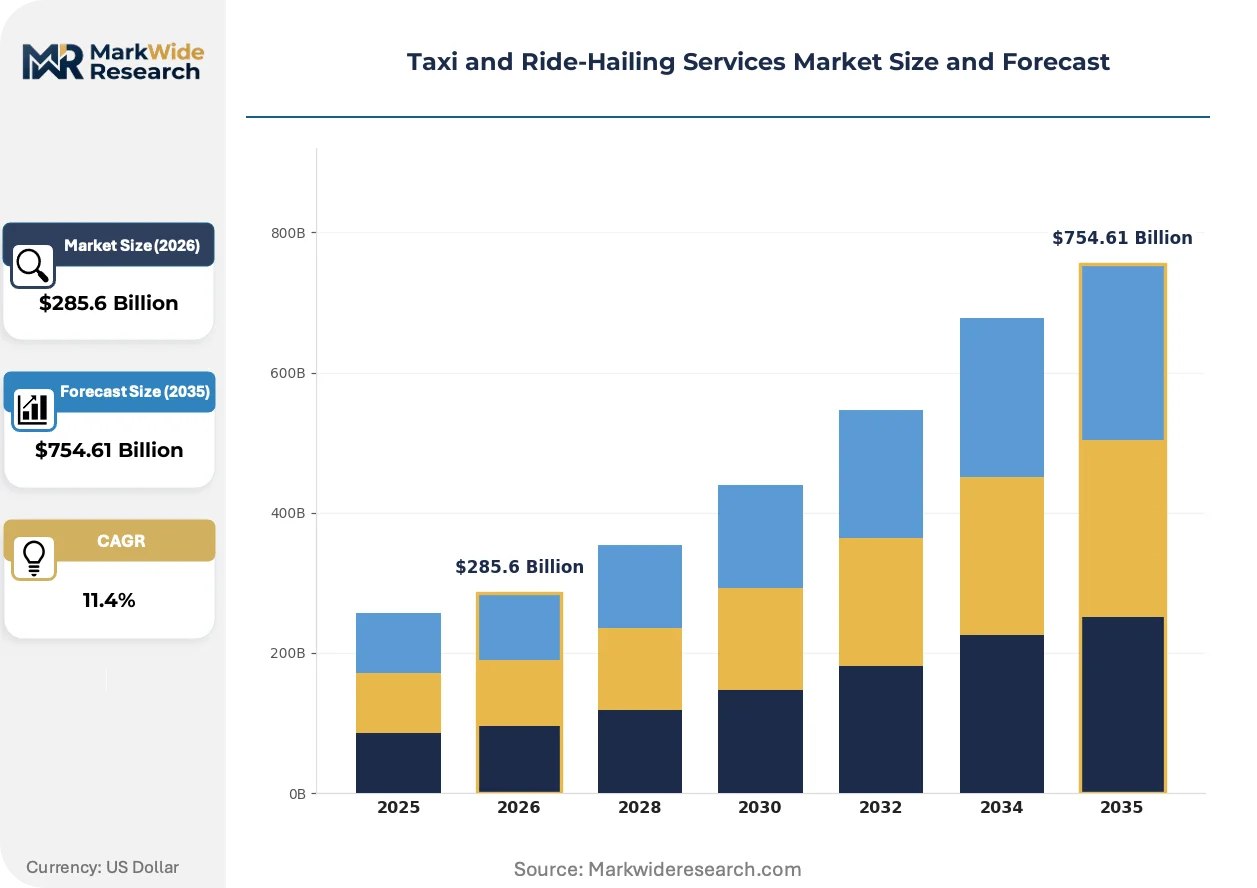
| Market Size in 2026 | $285.6 Billion |
| Market Size in 2035 | $754.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Sharing, Valet, Taxi, Pooling Customer Type: Corporate, Individual, Government, Tourist Technology: Mobile App, GPS, In-Car Payment, Route Optimization Vehicle Type: Standard Sedan, SUV, Luxury Car, Electric Vehicle |
| Companies Covered | Uber Technologies Inc., Lyft Inc., Grab Holdings Inc., DiDi Global Inc., Bolt Technology OÜ, Ola Cabs, Gett, inDrive, Careem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taxi and Ride-Hailing Services Market Trends and Innovations
Autonomous vehicle pilots and vehicle-to-grid integration are redrawing capital allocation patterns, while subscription mobility models displace per-trip purchasing among urban professionals.
Autonomous driving stacks are integrating into controlled geofenced deployments in Phoenix, San Francisco, and Shenzhen, with safety operators still mandated but remote monitoring reducing per-vehicle labor costs. Fleet operators in Dubai and Riyadh are piloting driverless airport and hotel zone shuttles to capture premium positioning ahead of regulatory expansion. This technology is integrating into platform roadmaps as a decade-long labor cost compression mechanism rather than near-term displacement.
The EU AI Act's risk classification framework imposes algorithmic transparency requirements on dynamic pricing and driver-routing systems, forcing platforms to document decision logic for regulatory audit. Operators must reengineer proprietary matching engines to satisfy explainability mandates or face service suspensions in German and French metropolitan zones. Ride-pooling algorithms face heightened scrutiny as high-risk automated decision systems under the Act's tiered compliance structure.
Subscription-based mobility passes are displacing per-trip purchasing among London and New York professionals who bundle ride-hail credits with public transit and bike-share access. Corporate travel managers negotiate annual platform commitments that guarantee capacity and standardize expense reconciliation, shifting procurement from ad-hoc reimbursement to centralized vendor management. This behavioral pivot is most visible in financial services and consulting verticals where employee mobility budgets consolidate under sustainability reporting requirements.
Taxi and Ride-Hailing Services Market Segmentation
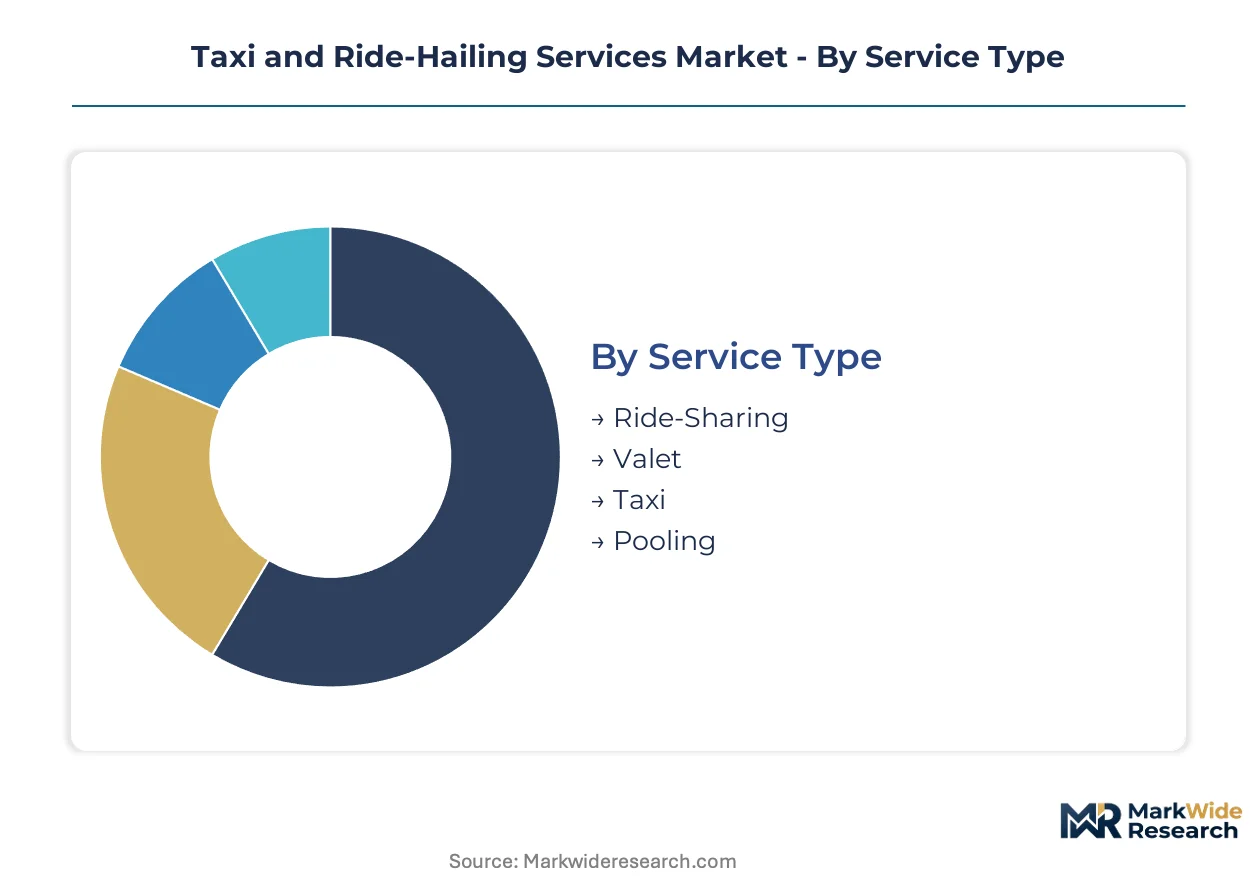
Segmentation in taxi and ride-hailing services reveals how platform operators allocate capital across divergent customer economics and regulatory environments. Each category reflects distinct technology requirements, margin profiles, and municipal compliance obligations that shape fleet procurement and driver recruitment strategies.
Service Type:
Service differentiation determines vehicle utilization rates, per-trip revenue, and driver earnings structures across metropolitan operating zones.
- Ride-Sharing:Peer-to-peer platforms match private vehicle owners with passengers through algorithmic dispatch, generating volume in suburban corridors where traditional taxi density remains thin. Demand concentrates in São Paulo and Jakarta where vehicle ownership costs outpace middle-class income growth.
- Pooling:Multi-passenger shared routes maximize per-vehicle revenue through dynamic pickup sequencing and detour tolerance algorithms. New York and London commuters accept longer trip durations in exchange for fare reductions, though regulatory caps on pooled-ride percentages limit penetration in some European capitals.
- Taxi:Medallion-based and app-dispatched traditional services retain airport and hotel contract dominance where regulatory familiarity accelerates permitting. Municipal licensing requirements in Tokyo and Singapore preserve incumbent operator positions against pure-play platforms.
- Valet:Driver-assisted parking and vehicle retrieval services attach to premium hospitality and healthcare verticals, commanding per-service fees that exceed standard ride-hail economics. Deployment concentrates in Dubai and Miami luxury districts where parking scarcity justifies concierge premiums.
Mature deployment sits with Taxi. Newer deployment is concentrated in Pooling.
Customer Type:
Customer segmentation separates predictable contractual revenue from volatile spot-market demand, dictating sales force allocation and pricing discipline.
- Corporate:Fortune 500 travel departments negotiate annual platform commitments with standardized expense reconciliation and sustainability reporting integration. Procurement managers in Frankfurt and Chicago prioritize vendors with Scope 3 emissions tracking and consolidated invoicing.
- Individual:Spontaneous trip demand drives peak-hour surge pricing and driver incentive programs, though earnings volatility creates chronic supply friction in London and Singapore. Smartphone penetration thresholds determine addressable market sizing in emerging metropolitan corridors.
- Government:Municipal and state contracts for paratransit, civil servant mobility, and emergency response services require accessibility compliance and audit-ready trip documentation. Procurement cycles extend 18-36 months with heavy weighting toward incumbent track records.
- Tourist:Airport-to-hotel corridors and destination city zones generate premium pricing tolerance among visitors unfamiliar with local transit alternatives. Seasonal demand spikes in Barcelona and Bali strain fleet availability during peak travel windows.
Volume concentrates with Individual. Margin expansion sits with Corporate.
Technology:
Technology infrastructure separates capital-light platform operators from asset-heavy fleet owners, determining scalability constraints and regulatory exposure.
- Mobile App:Native iOS and Android interfaces with real-time vehicle tracking, fare estimation, and digital wallet integration constitute the primary customer touchpoint. User experience investments in Mumbai and Mexico City focus on low-bandwidth optimization and multilingual support.
- GPS:Satellite and cellular positioning systems enable dispatch triangulation, route visualization, and arrival time prediction with 10-30 meter accuracy. Signal degradation in dense urban canyons of Hong Kong and Manhattan necessitates dead-reckoning algorithm supplementation.
- In-Car Payment:Integrated point-of-sale terminals and contactless readers reduce cash handling friction while generating transaction data for loyalty program optimization. Regulatory mandates in Stockholm and Amsterdam accelerate contactless adoption over legacy card-swipe hardware.
- Route Optimization:Machine learning models process traffic patterns, construction data, and historical trip times to minimize passenger wait and journey duration. Deadhead mileage reduction in São Paulo and Lagos improves driver hourly earnings and platform take rates simultaneously.
Commoditized deployment sits with GPS. Differentiation investment concentrates in Route Optimization.
Vehicle Type:
Fleet composition determines emissions compliance positioning, insurance cost structures, and customer willingness-to-pay across service tiers.
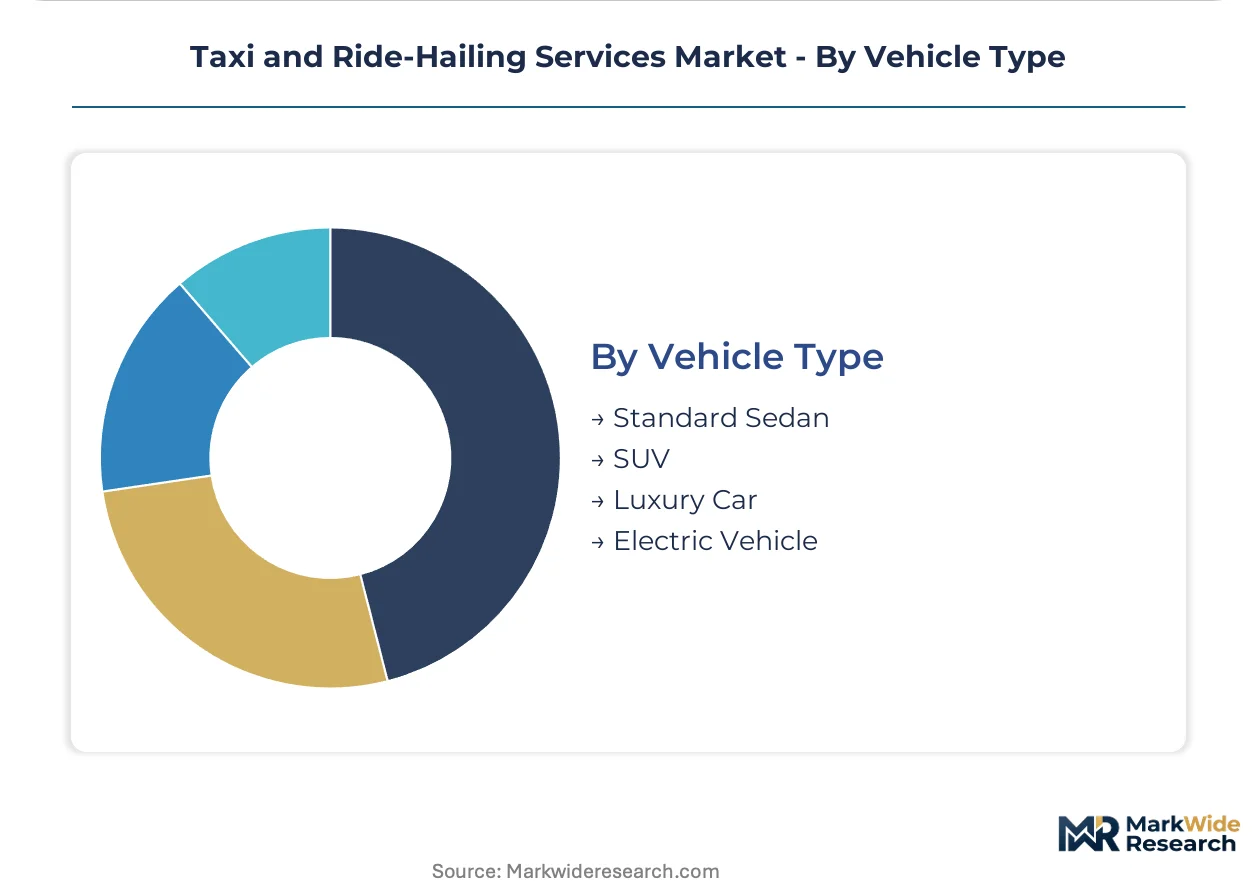
- Electric Vehicle:Battery-electric platforms satisfy EU Green Deal mandates and municipal zero-emission zone requirements in Paris, Berlin, and Amsterdam. Charging infrastructure gaps in São Paulo and Mexico City force hybrid transition strategies despite fleet electrification timelines.
- Standard Sedan:Four-door economy vehicles dominate trip volume in price-sensitive corridors where per-kilometer cost minimization outweighs comfort preferences. Toyota and Hyundai models concentrate in Southeast Asian and Latin American fleet procurement.
- SUV:Higher-capacity vehicles capture airport and group travel segments with luggage volume requirements that exclude sedan accommodation. Premium positioning in Middle Eastern and North American markets justifies elevated per-trip pricing.
- Luxury Car:Mercedes-Benz, BMW, and Tesla vehicles serve executive and hospitality contract segments where brand association reinforces platform positioning. Driver qualification standards and insurance minimums restrict supply in all operating territories.
Volume dominance sits with Standard Sedan. Regulatory tailwinds concentrate in Electric Vehicle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors algorithmic mobility innovation, while regulatory fragmentation across national capitals reshapes fleet deployment timelines and driver classification frameworks.
United States
Corporate travel procurement in Chicago and New York drives demand for consolidated mobility platforms with sustainability tracking. The EPA and California Air Resources Board enforce divergent emissions trajectories that fragment national fleet standardization. Phoenix and San Francisco host autonomous vehicle pilots where safety-operator mandates still govern geofenced deployments.
Germany
Munich and Frankfurt corporate clients prioritize vendors with Scope 3 emissions documentation and consolidated invoicing. The EU AI Act imposes algorithmic transparency requirements on dynamic pricing systems, forcing platforms to document decision logic for KBA audit. Berlin operators accelerate electric taxi deployments to satisfy EU Green Deal zero-emission zone mandates ahead of municipal deadlines.
India
Mumbai and Bangalore generate disproportionate trip volume where smartphone penetration now supports app-based dispatch in tier-2 corridors. The PLI scheme for automotive manufacturing indirectly supports fleet electrification through domestic battery assembly incentives. Jaipur and Lucknow present underpenetrated markets where driver incentive scaling by Ola Cabs and Uber Technologies Inc. concentrates platform investment.
Brazil
São Paulo commuters accept pooled-ride duration penalties in exchange for fare reductions that outpace private vehicle ownership costs. ANVISA oversight of medical transport categories creates specialized licensing requirements for hospital and clinic contract segments. Rio de Janeiro airport corridors sustain premium pricing tolerance among tourists unfamiliar with local transit alternatives.
United Arab Emirates
Dubai luxury hospitality verticals command concierge premiums for valet and chauffeured services exceeding standard ride-hail economics. MOHAP and municipal transport authorities coordinate autonomous shuttle pilots in airport and hotel zones ahead of regulatory expansion. Riyadh-based fleet operators capture premium positioning through driverless zone deployments targeting business traveler segments.
Taxi and Ride-Hailing Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory sophistication and fleet electrification timelines. The market structures around platform operators with dual-service-tier architectures, regional specialists with municipal partnership depth, and challenger platforms with price-disruption positioning. Consolidation pressure concentrates among North American and Asian operators seeking geographic diversification. Dominant competitive moves include strategic partnerships for charging infrastructure access and portfolio diversification into multimodal subscription bundles.
Within the dual-platform tier, Uber Technologies Inc. and Lyft Inc. occupy positions spanning premium black-car and economy pooling segments across North American metropolitan corridors. DiDi Global Inc. anchors regulatory complexity management through direct municipal partnerships in Asian operating territories. These three exemplify divergent strategic archetypes: Uber Technologies Inc. represents global scale with service-tier breadth, Lyft Inc. exemplifies regional concentration with loyalty-program differentiation, and DiDi Global Inc. occupies the position of regulatory-integrated local operator with compliance infrastructure depth.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| Lyft Inc. |
| Grab Holdings Inc. |
| DiDi Global Inc. |
| Bolt Technology OÜ |
| Ola Cabs |
| Gett |
| inDrive |
| Careem |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up fleet operators in São Paulo and Mexico City anchor supply behavior through leveraged vehicle procurement programs, connecting ownership structure to pricing discipline via captive financing terms that compress per-kilometer capital costs. Platform take rates adjust dynamically against driver earnings floors, feeding back into fleet composition choices between owned and driver-supplied vehicles.
Pricing Analysis
Value-based pricing anchored to trip throughput and asset utilization rates dominates platform economics, with dynamic algorithms calibrating fares to real-time supply-demand imbalances. Three-tier pricing structure across premium black-car, standard ride-hail, and economy pooling segments separates corporate contract rates from surge-adjusted spot pricing. Pricing pressure stems from driver supply volatility in London and New York, where earnings compression intensifies recruitment costs. Corporate travel departments exhibit lowest price sensitivity due to consolidated procurement mandates, while individual commuters in tier-2 Indian cities demonstrate highest elasticity.
Supply Chain Analysis
India's PLI scheme for automotive manufacturing and domestic battery assembly reshapes sourcing patterns, compelling platform operators to localize procurement. Vehicle assembly concentrates in India, China, and South Korea, while lithium-ion cell production draws from China, South Korea, and Japan. Charging infrastructure components hinge on semiconductor availability from Taiwan and South Korea. Single-source vulnerability runs through Chinese rare-earth processing for permanent magnet motors. Distribution runs through municipal fleet management partnerships and driver-owned vehicle networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Driver supply constraints prop pricing power across metropolitan corridors, with chronic recruitment friction in regulated markets sustaining platform take-rate elevation.
For Market Incumbents: Anticipate regulatory fragmentation between EPA and California Air Resources Board trajectories by diversifying fleet procurement across hybrid and electric vehicle categories. Consolidate charging infrastructure partnerships in European capitals ahead of EU Green Deal zero-emission zone deadlines. Vertical integration into driver incentive programs mitigates supply volatility threatening service reliability. For New Entrants and Emerging Players: Begin with underpenetrated tier-2 corridors in India where smartphone penetration now supports app-based dispatch viability. Jaipur and Lucknow present addressable white space with limited incumbent loyalty program penetration. Corporate mobility contracts offer predictable revenue basins distinct from volatile individual ride demand, accessible through sustainability reporting integration. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with municipal partnership depth in European capitals facing EU AI Act compliance engineering costs. Long-term viability centers on platforms with demonstrated regulatory navigation capabilities across divergent privacy regimes. Watch autonomous vehicle safety-operator mandate relaxations as inflection indicator for labor cost compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Secures charging infrastructure access ahead of EU Green Deal municipal deadlines in Paris and Berlin. |
| Corporate Mobility Contract Expansion | Captures Fortune 500 procurement consolidation with Scope 3 emissions tracking and consolidated invoicing. |
| Autonomous Vehicle Pilot Deployment | Positions platform for labor cost compression in Phoenix and San Francisco geofenced corridors. |
| Multimodal Platform Integration | Creates stickier user ecosystems through bike-share and public transit ticketing convergence in Stockholm. |
| Tier-2 Geographic Expansion | Penetrates underaddressed Indian corridors in Jaipur and Lucknow via driver incentive scaling. |
Research Methodology
Multi-period observation of driver supply indicators, fleet electrification timelines, and municipal regulatory filings anchored the trend analysis, supplemented by interviews with platform operations executives, fleet procurement managers, driver association representatives, and municipal transport authority officials. Secondary validation drew from EPA emissions filings, EU Green Deal implementation trackers, SEC 10-K disclosures, and vehicle registration databases. Bottom-up trip volume modeling and top-down market sizing triangulated demand estimates.
Segment-weighting across service type, customer type, technology infrastructure, and vehicle propulsion architecture structured the analytical framework. CAGRs derived from regression analysis of historical penetration rates and projected smartphone adoption curves across metropolitan corridors. Forecast inputs incorporated EU AI Act compliance cost estimates and charging infrastructure buildout schedules.
Regulatory enforcement delays, driver classification litigation outcomes, and autonomous vehicle safety incident responses are the dominant revision risks to modeled projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Two Wheeler Rental Market
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
Poland Car Rental Market
Transportation Services
Car Rental Service Market
Transportation Services
Middle East Car Rental Market
Transportation Services
Bulk Transportation Services Market
Transportation Services
Spain Car Rental Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Europe Light Commercial Vehicle Rental Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Scooter Rental Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Bird Carriers Market
Transportation Services
Global Taxi Market
Transportation Services
Full-Service Carrier Market