
 Middle East Car Rental Market | 2026-2036
Middle East Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Car Rental Market Foresight
Corporate fleet procurement consolidation among multinational energy and construction firms is repositioning contract negotiation power toward volume buyers in the Gulf. Lumi Rental Company anchors its position through long-term government and corporate agreements across Saudi Arabia. Sixt SE competes by leveraging premium airport locations and digital fleet management infrastructure. Theeb Rent A Car dominates the domestic Saudi market through extensive branch networks in secondary cities.
Middle East car rental denotes a service industry providing temporary vehicle access through daily, weekly, or monthly contracts, with fleets ranging from economy sedans to luxury SUVs maintained through centralized hubs and airport counters. Operators manage utilization rates, depreciation schedules, and insurance pools to balance asset turnover against per-unit profitability. Short-term and corporate service categories command the largest revenue pools due to business traveler density and event-driven demand spikes in Dubai and Doha. Online platforms represent the fastest-growing distribution channel as mobile-first booking displaces walk-in counter transactions. SUV vehicle types sustain premium pricing power among tourist segments seeking desert and highway mobility.
Saudi Arabia's General Authority for Civil Aviation and the UAE's Department of Economy and Tourism shape fleet standards through airport concession rules and consumer protection frameworks. Environmental commitments under Saudi Vision 2030 and UAE Net Zero 2050 are forcing operators to accelerate electrification timelines and secure charging infrastructure partnerships. Stakeholders must monitor regulatory divergence between Gulf states as emission standards and data localization requirements fragment compliance costs across national borders.
Market Dynamics
Fleet electrification mandates from Saudi Vision 2030 and UAE Net Zero 2050 are forcing operators to restructure capital deployment around charging infrastructure partnerships and battery depreciation models.
Growth Catalysts
- Visa facilitation programs:Gulf Cooperation Council tourism boards are streamlining entry protocols for international visitors, directly expanding the addressable tourist rental pool.
- Corporate mobility demand:White-collar employment expansion in Riyadh and Dubai finance and technology sectors is driving sustained long-term leasing contracts.
- SFDA and MOHAP fleet standards:Saudi and UAE aviation regulators are mandating newer vehicle age limits at airport concessions, accelerating fleet refresh cycles.
Market Restraints
- Charging infrastructure gaps:Desert highway corridors between Saudi cities lack reliable fast-charging networks, constraining electric vehicle deployment.
- Import duty volatility:GCC customs harmonization remains incomplete, fragmenting vehicle acquisition costs across national borders.
- Residual value uncertainty:Accelerated electrification timelines are compressing secondary market demand for internal combustion engine fleets.
Strategic Opportunities
- Secondary city networks:Saudi Arabia's tier-two urban centers outside Riyadh and Jeddah remain underserved by premium rental infrastructure.
- Event-driven demand spikes:Expo and Formula 1 calendars in Qatar and Abu Dhabi create temporary fleet utilization premiums.
- Subscription-to-lease conversion:Monthly flexible-use contracts are capturing corporate users seeking alternatives to capital-intensive ownership.
Industry Challenges
- Technician certification gaps:Electric vehicle maintenance protocols require retraining programs that outpace regional vocational pipeline capacity.
- Data localization compliance:Divergent national requirements for customer reservation data storage are multiplying IT infrastructure costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Car Rental Market |
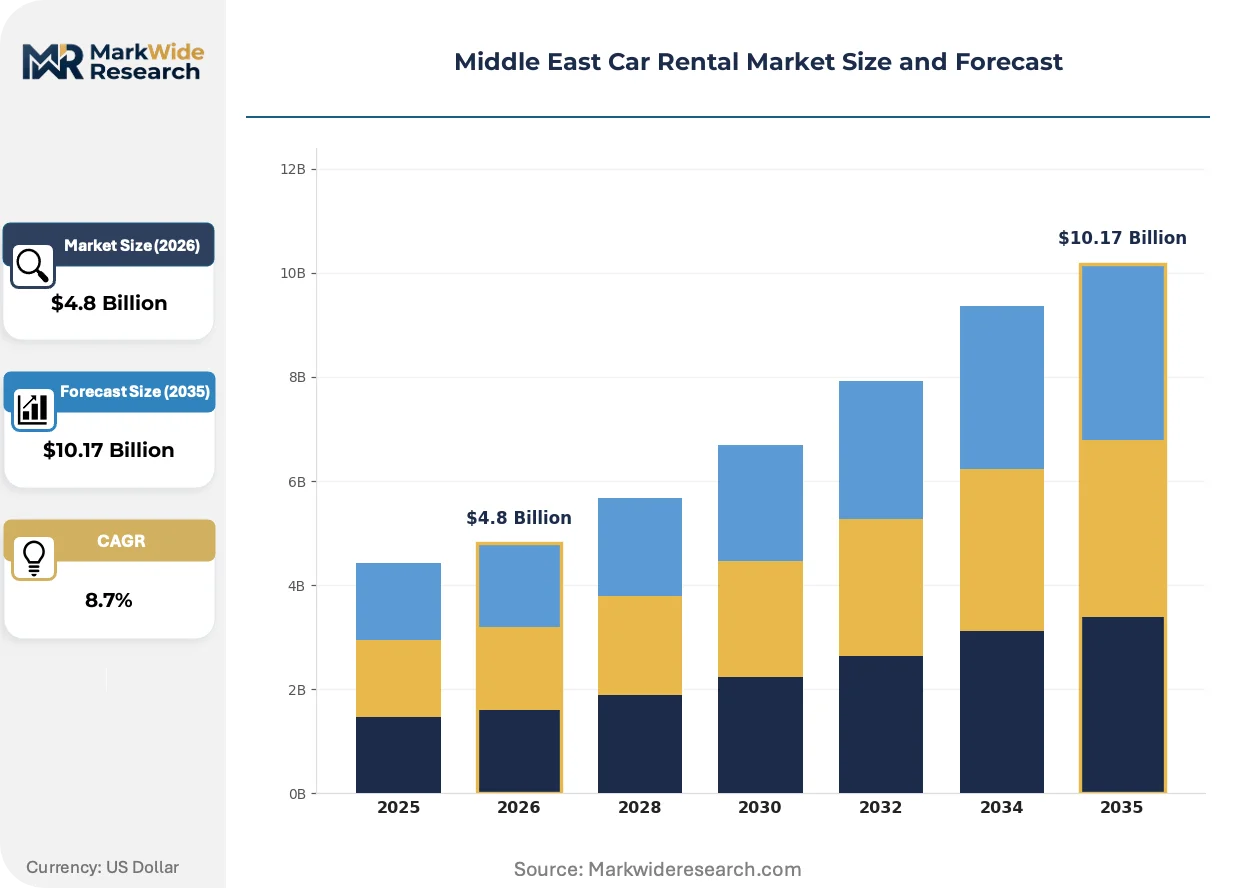
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-term, Long-term, Corporate, Leisure Vehicle Type: SUV, Sedan, Hatchback, Luxury Customer Type: Tourists, Business Travelers, Local Residents, Government Distribution Channel: Online Platforms, Travel Agents, Direct Booking, Affiliates |
| Companies Covered | Sixt SE, Europcar Mobility Group, Avis Budget Group, Fast Rent A Car, Lumi Rental Company, Hertz Corporation, Theeb Rent A Car, SHIFT, Enterprise Holdings Inc., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Car Rental Market Shifts & Advancements
Telematics integration and mobile-first booking platforms are compressing the traditional counter-based rental model, while regulatory pressure on emissions is accelerating powertrain diversification across operator fleets.
Connected fleet management systems are expanding into real-time vehicle health monitoring and predictive maintenance scheduling. Corporate fleet managers in Saudi Arabia and the UAE are adopting these platforms to minimize downtime and optimize utilization rates. The technology is expanding into dynamic pricing engines that adjust rates based on live demand signals and vehicle availability.
MOHAP and Saudi environmental regulators are implementing graduated emission standards that phase out older vehicle categories from airport concession agreements. Rental operators must accelerate fleet turnover to maintain access to premium location licenses. Dubai International Airport and King Khalid International Airport concessions are the first enforcement points, with operators pre-ordering hybrid SUVs to secure terminal counter positions.
Mobile application bookings are displacing walk-in counter transactions as the dominant reservation channel. Younger leisure travelers in Qatar and Kuwait expect seamless digital check-in and keyless vehicle access. This shift is most visible in Dubai, where airport operators report majority share of reservations originating through proprietary apps rather than third-party aggregators or physical queues.
Middle East Car Rental Market Segmentation
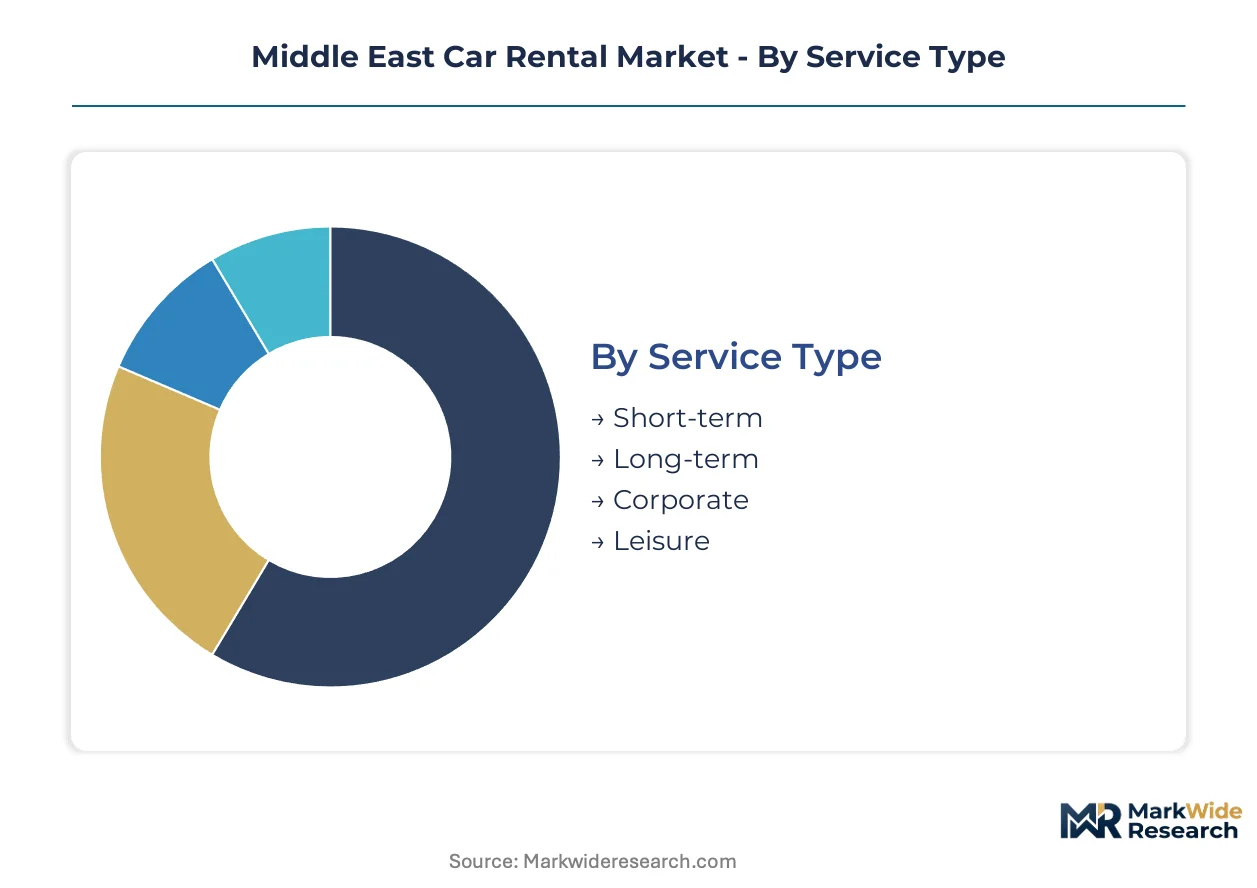
Middle East car rental operators structure pricing, fleet composition, and location strategy around distinct buyer profiles. Service duration, vehicle class, and booking channel each trigger divergent margin structures and capital deployment patterns across Saudi Arabia and the UAE.
Service Type:
Different contract durations separate transactional tourists from relationship-driven corporate accounts with diverging renewal economics.
- Short-term:Daily and weekly contracts targeting airport arrivals and event visitors. Dubai International and King Khalid terminals concentrate volume during Formula 1 and Expo calendars. Fleet utilization spikes create premium pricing windows that subsidize off-peak depreciation.
- Long-term:Monthly to annual leases with fixed mileage allowances and maintenance bundles. Riyadh corporate campuses and Dubai finance districts anchor demand as white-collar employment expands.
- Corporate:Negotiated fleet agreements with multinational energy and construction firms. Volume buyers consolidate procurement power, compressing per-unit margins while securing guaranteed utilization floors.
- Leisure:Flexible-use contracts for domestic tourists and weekend travelers. Secondary Saudi cities and UAE emirates outside Dubai generate intermittent demand requiring dynamic pricing algorithms.
Corporate contracts lead volumes today; online leisure bookings are climbing the fastest.
Vehicle Type:
Powertrain and cabin configuration directly determine residual value risk and charging infrastructure requirements under Saudi Vision 2030 and UAE Net Zero mandates.
- SUV:Body-on-frame and unibody configurations dominating desert highway mobility and family transport. Premium pricing power persists across tourist segments seeking wadi and dune access. MOHAP and Saudi aviation regulators are mandating hybrid variants for airport concession renewals.
- Sedan:Three-box configurations optimized for urban fuel efficiency and corporate fleet standardization. Riyadh and Dubai business districts sustain demand despite electrification-driven model transitions.
- Hatchback:Compact two-box designs serving price-sensitive local residents and short-haul commuters. Limited presence in premium airport concessions due to lower revenue per unit-day.
- Luxury:High-performance sedans and SUVs from European and regional premium marques. Abu Dhabi and Doha hotel partnerships generate concentrated demand during diplomatic and sporting events.
SUV configurations lead volumes today; electrified luxury variants are expanding most quickly.
Customer Type:
Documentation requirements and payment terms vary sharply between visa-holding visitors and domestic account holders.
- Tourists:International visitors utilizing streamlined GCC visa facilitation programs. Dubai and Doha absorb the majority share, with Qatar's hospitality expansion diverting some Gulf traffic.
- Business Travelers:Corporate-account road warriors with negotiated rates and express check-in protocols. Riyadh finance and technology sector growth is extending contract durations.
- Local Residents:Domestic users seeking temporary mobility during vehicle service or family expansion periods. Secondary Saudi cities show underpenetrated potential.
- Government:Ministry and state-owned enterprise fleets under procurement frameworks. Lumi Rental Company and Theeb Rent A Car have anchored positions through long-term public sector agreements.
Tourist and business traveler segments lead volumes today; government fleet electrification mandates are driving the steepest contract restructuring.
Distribution Channel:
Booking origination point determines customer acquisition cost and fleet allocation lead time.
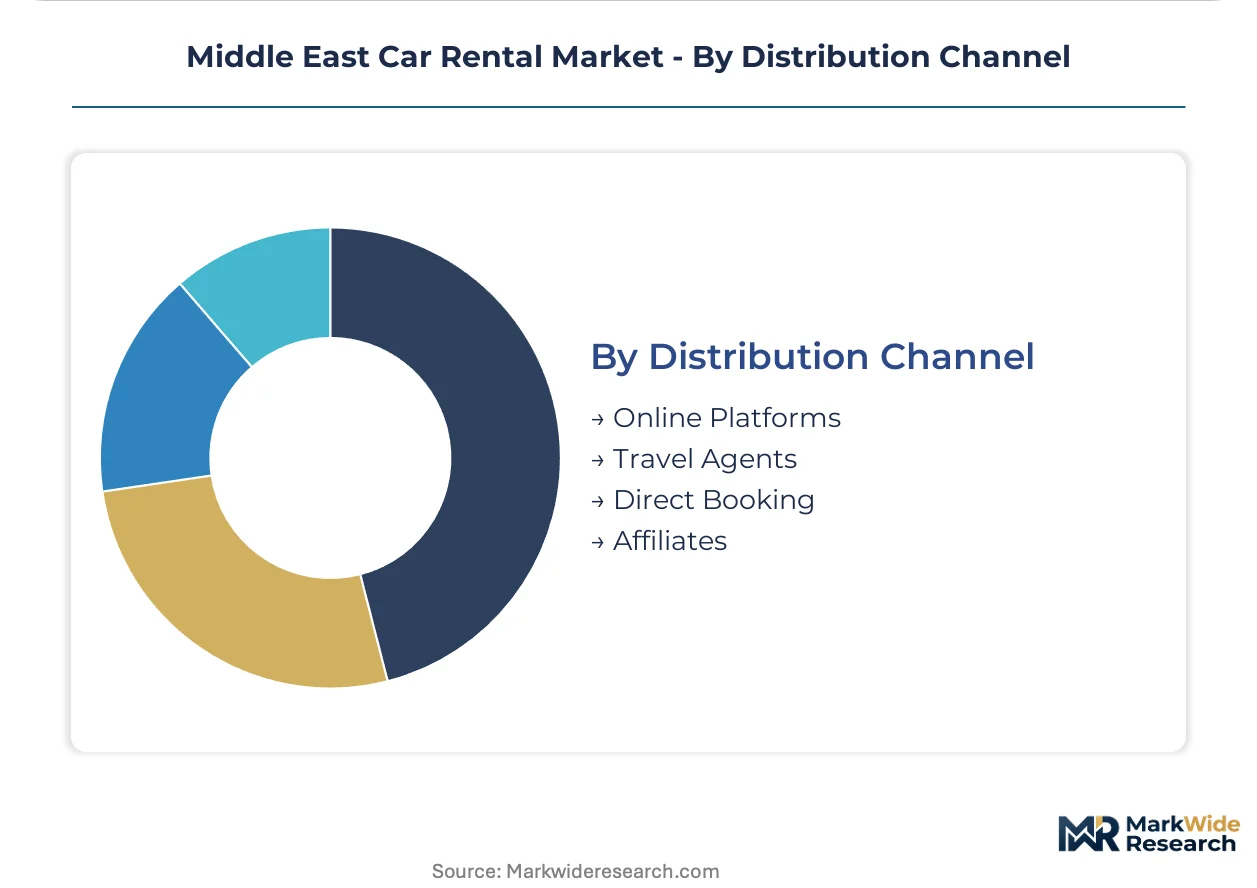
- Online Platforms:Proprietary mobile applications and third-party aggregators displacing physical queues. Dubai airport operators report majority share of reservations now originating through digital channels.
- Travel Agents:Traditional intermediaries packaging rental with hospitality and aviation bookings. Remains significant for inbound tour groups from South Asia and East Asia.
- Direct Booking:Counter and telephone reservations with walk-in availability. Concentrated at secondary locations with lower digital penetration.
- Affiliates:Hotel, airline, and credit card partnership programs generating referral volume. Premium property alliances in Abu Dhabi and Doha sustain this channel's relevance.
Online platforms lead volumes today; affiliate partnerships with hospitality chains are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finance and technology professionals cluster in Riyadh and Dubai, anchoring corporate fleet demand across the Gulf. White-collar employment expansion in these hubs sustains long-term leasing contracts and premium vehicle procurement.
Saudi Arabia
Energy sector executives and construction managers drive corporate mobility demand in the Eastern Province and Riyadh. SFDA and the General Authority for Civil Aviation enforce newer vehicle age limits at King Khalid International Airport concessions. Jeddah's hospitality corridor absorbs leisure rental spikes during Umrah seasons and Red Sea tourism expansion.
United Arab Emirates
Dubai International Airport processes the highest tourist rental volumes in the region, with MOHAP regulating fleet emission standards at terminal counters. Abu Dhabi's diplomatic and Formula 1 event calendars generate concentrated luxury vehicle demand. Sharjah and the Northern Emirates remain underpenetrated for digital-first booking platforms.
Qatar
Hospitality sector workers and World Cup legacy infrastructure teams sustain corporate leasing in Doha. The Qatar Tourism Authority streamlines visa protocols for GCC visitors. Lusail City and the Pearl-Qatar district concentrate premium rental infrastructure for business travelers.
Kuwait
Oil sector contractors and government employees anchor long-term fleet demand in Kuwait City. The Central Agency for Public Tenders governs state vehicle procurement frameworks. Ahmadi and Jahra industrial zones generate intermittent logistics rental requirements.
Oman
Muscat's port and logistics workers drive commercial vehicle leasing alongside tourism operators serving desert excursion markets. The Ministry of Transport enforces commercial fleet safety inspections. Salalah's seasonal monsoon tourism creates temporary utilization premiums for coastal rental locations.
Middle East Car Rental Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fleet composition and distribution channel strategies. Market structure tilts toward consolidation at the premium airport tier while fragmenting across secondary city networks. Three archetypes dominate: government-contracted national champions, premium airport specialists, and digital-native flexible-use platforms. Competitive moves concentrate on securing airport concession renewals and building charging infrastructure partnerships ahead of electrification mandates.
Within the government-contracted tier, Lumi Rental Company and Theeb Rent A Car exemplify operators anchored through long-term public sector agreements across Saudi Arabia. Sixt SE occupies a position among premium airport specialists leveraging digital fleet management infrastructure. These three represent distinct strategic postures: state-tethered scale, international premium positioning, and domestic network density.
| Leading Market Players |
|---|
| Sixt SE |
| Europcar Mobility Group |
| Avis Budget Group |
| Fast Rent A Car |
| Lumi Rental Company |
| Hertz Corporation |
| Theeb Rent A Car |
| SHIFT |
| Enterprise Holdings Inc. |
| Others |
Supply & Pricing Matrix
Sovereign-wealth-backed fleet lessors in Saudi Arabia and the UAE concentrate procurement power through multi-year government contracts, compressing per-unit margins while enforcing capital discipline across secondary-city distributors. This ownership pattern feeds directly into pricing structures that subsidize airport premium tiers through volume guarantees in public sector agreements.
Pricing Analysis
Bundled service packages combining insurance, maintenance, and mileage allowances dominate corporate long-term contracts, while unbundled daily rates prevail in tourist short-term segments. Three-tier pricing structure across premium, standard, and economy levels separates airport concession operators from secondary-city independents, with luxury SUV tiers commanding widest spreads. Price differentiation hinges on fleet age compliance with SFDA and MOHAP emission mandates, plus after-sales service bundling for corporate accounts. Cost compression in economy tiers is intensifying because volume buyers consolidate procurement across multinational energy and construction firms. Local residents in secondary Saudi cities exhibit highest price sensitivity; diplomatic and Formula 1 event segments show least.
Supply Chain Analysis
Freight costs for vehicle imports from Japan, South Korea, and Germany constitute the dominant landed cost component, with Red Sea routing disruptions periodically inflating delivery timelines. Manufacturing concentration in these three source markets draws from steel, semiconductors, and battery cell inputs. Single-source vulnerability in semiconductor-dependent advanced driver-assistance systems creates procurement risk for electrified fleet upgrades. Distribution runs through centralized hub-and-spoke models anchored at Dubai International and King Khalid airports, with secondary-city extensions via domestic road networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Middle East car rental rests on charging infrastructure partnerships reducing fleet operating costs and premium electrified tiers capturing corporate sustainability mandates.
For Market Incumbents: Anchor government concession renewals through pre-orders of hybrid SUVs meeting MOHAP and SFDA emission deadlines. Secure exclusive charging infrastructure partnerships along Riyadh-Jeddah and Dubai-Abu Dhabi corridors before regulatory enforcement tightens. Vertical integration into in-house maintenance certification programs addresses technician pipeline gaps threatening fleet uptime. For New Entrants and Emerging Players: Launch via mobile-first subscription platforms targeting underpenetrated secondary Saudi cities outside Riyadh and Jeddah. White-space concentration exists in tier-two urban centers lacking digital booking penetration. Event-driven demand spikes in Qatar and Abu Dhabi offer seasonal fleet utilization premiums through flexible-use corporate contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic network specialists with government contract anchors but limited electrification progress. Long-term viability favors operators with secured charging infrastructure partnerships and airport concession renewals under emission mandates. Watch SFDA and MOHAP enforcement calendars as inflection signals for fleet refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Secures corridor access between Riyadh and Jeddah under Saudi Vision 2030 mandates. |
| Airport Concession Renewal | Maintains terminal counter positioning at Dubai International and King Khalid under MOHAP rules. |
| Mobile-First Platform Launch | Captures leisure bookings displacing walk-in transactions among younger GCC travelers. |
| Corporate Fleet Electrification | Addresses government procurement frameworks requiring hybrid vehicle minimums. |
| Secondary City Network Expansion | Penetrates underserved tier-two Saudi markets beyond Riyadh-Jeddah-Dammam triangle. |
Research Methodology
Bottom-up fleet utilization modeling reconciled against top-down vehicle registration tracking forms the analytical core of this study. Primary interviews with fleet procurement managers at multinational energy firms, airport concession operators, corporate mobility directors, and charging infrastructure developers combined with secondary validation from customs import records, General Authority for Civil Aviation filings, and tourism board arrival statistics. Triangulation across these sources anchors volume estimates against actual fleet deployment patterns.
Input-output matrices map service type, vehicle class, and distribution channel against customer segments across the analysis window. Segmentation dimensions include contract duration, powertrain architecture, booking origination point, and geographic demand cluster. CAGRs derive from fitted trend extrapolation moderated by regulatory enforcement calendars and infrastructure buildout timelines. Forecast inputs incorporate SFDA and MOHAP emission phase-out schedules plus corporate employment growth in Riyadh and Dubai finance districts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under charging infrastructure delays or import duty harmonization failures across GCC borders. Forecasts reflect documented assumptions about regulatory enforcement timing and fleet turnover rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Vietnam Car Rental Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Driving Vacation Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
Poland Car Rental Market
Transportation Services
Brazil Car Rentals Market
Transportation Services
Compact Road Sweepers Market
Transportation Services
ASEAN Taxi Market
Transportation Services
Airport Handling Service Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
Multispace Parking Meter Market
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
Drayage Services Market
Transportation Services
Canada White Glove Delivery Service Market