
 Refrigerated Truck Rental Market | 2026-2036
Refrigerated Truck Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Truck Rental Market Analysis
India is rewriting fleet deployment patterns across the refrigerated truck rental sector as cold chain infrastructure expands to reduce post-harvest losses. Ryder System leverages its North American service center density to sustain short-term rental availability for food distributors. Fraikin Limited anchors European multi-temperature fleet operations through long-term contract structures with supermarket chains. Petit Forestier dominates French urban refrigerated logistics with specialized light-duty vehicles designed for dense delivery routes.
A refrigerated truck rental provides temperature-controlled commercial vehicle access without ownership, utilizing insulated cargo boxes with integrated refrigeration units typically maintaining ranges from minus 25 degrees Celsius to plus 25 degrees Celsius depending on payload requirements. The primary purpose centers on preserving perishable goods integrity across pharmaceutical, food, and chemical supply chains where thermal excursion risks compromise product value or safety. Light duty vehicles lead urban last-mile deployment due to maneuverability constraints in dense European and Asian city centers, while heavy duty configurations capture margin pools in long-haul pharmaceutical distribution where continuous temperature validation commands premium pricing. Vapor compression cooling technology occupies the mature installed base, though hybrid systems are gaining fastest adoption where diesel access restrictions multiply in low-emission zones across Germany, France, and the United Kingdom.
The EPA and California Air Resources Board shape United States fleet procurement through escalating emissions standards that accelerate diesel phase-out timelines for transport refrigeration units. The European Union F-Gas Regulation and ECHA REACH protocols restrict refrigerant chemistries and insulation materials, forcing rental operators to re-specify equipment for cross-border compliance. Stakeholders must monitor regulatory divergence between federal and state-level zero-emission mandates while calibrating fleet refresh cycles against uncertain battery-electric range performance under full refrigeration load.
Market Dynamics
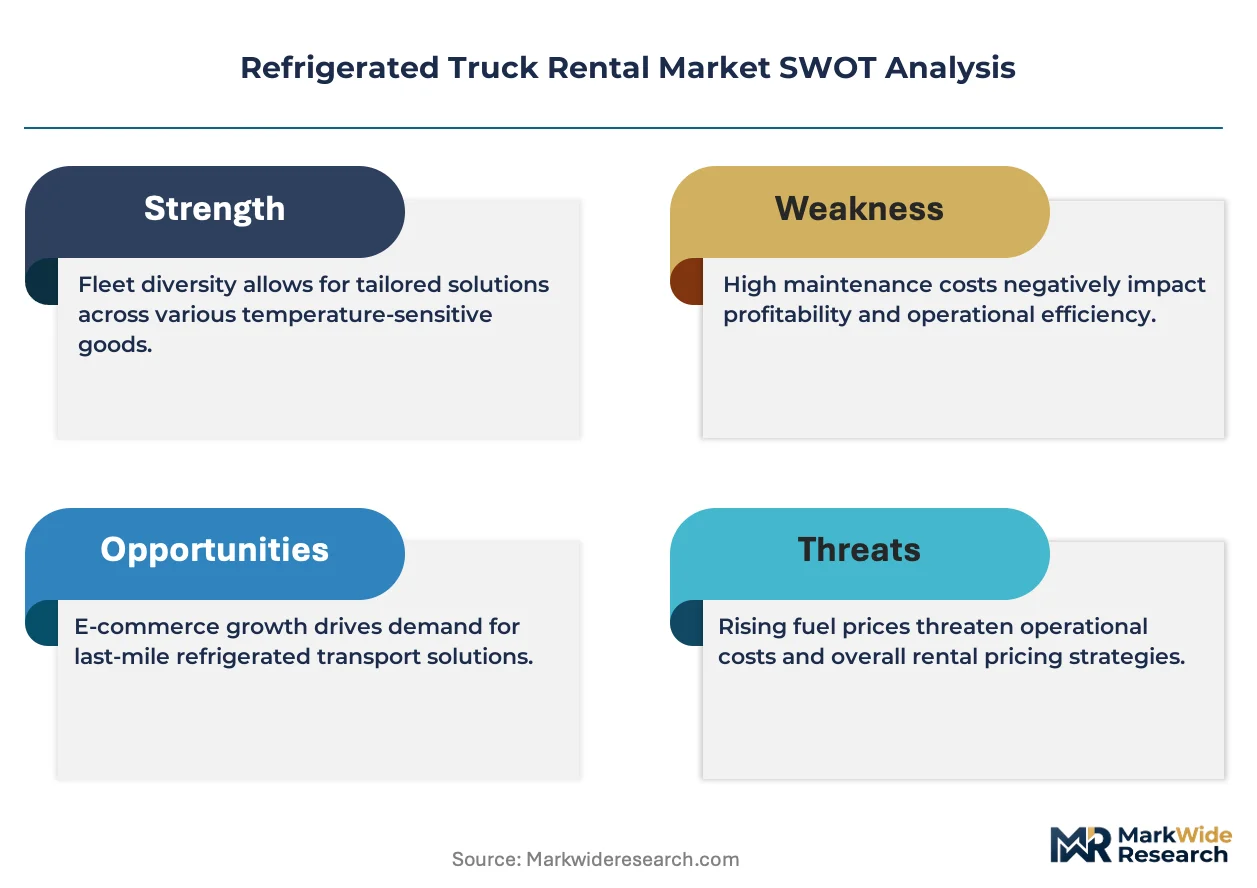
Stringent emissions mandates from the EPA Phase 3 standards and CARB Advanced Clean Trucks rule are forcing rental operators to compress diesel fleet lifecycles and reallocate capital toward electrified refrigeration architectures before total cost parity matures.
Growth Catalysts
- Biologics cold chain:Temperature-sensitive pharmaceutical payloads now require validated thermal containers across distribution networks, expanding rental commitments from vaccine and gene therapy manufacturers.
- EU F-Gas Regulation:Restrictions on hydrofluorocarbon refrigerants are accelerating fleet turnover toward low-GWP alternatives, creating replacement demand cycles for compliant transport refrigeration units.
- Food e-commerce fulfillment:Direct-to-consumer perishable delivery networks in the United States require flexible refrigerated capacity without long-term asset ownership, concentrating spot rental demand.
Market Restraints
- Battery-electric range uncertainty:Full refrigeration load draws degrade electric truck operating radius below viable thresholds for long-haul pharmaceutical routes, limiting zero-emission deployment.
- Refrigerant supply concentration:Production of approved low-GWP alternatives clusters among specialized chemical manufacturers, exposing rental operators to input cost volatility and allocation constraints.
- Cross-border regulatory friction:Divergent state-level zero-emission mandates in California versus federal EPA timelines complicate national fleet standardization for multi-state operators.
Strategic Opportunities
- India cold chain infrastructure:Government programs targeting post-harvest loss reduction are subsidizing refrigerated transport capacity expansion, opening fleet deployment opportunities in agricultural corridors.
- Hybrid refrigeration convergence:Integration of electric compressor systems with auxiliary battery packs enables diesel-free operation in urban low-emission zones while preserving range flexibility.
- Outcome-based rental models:Pharmaceutical shippers now contract for temperature-validated delivery rather than vehicle-hours, allowing operators to capture premium pricing through guaranteed performance.
Industry Challenges
- Technician skill scarcity:Maintenance of integrated electric refrigeration systems requires cross-training across high-voltage powertrains and HVAC systems, constraining service network expansion.
- Certification timeline compression:CARB compliance deadlines for transport refrigeration units are accelerating faster than equipment validation cycles, forcing premature asset retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Truck Rental Market |
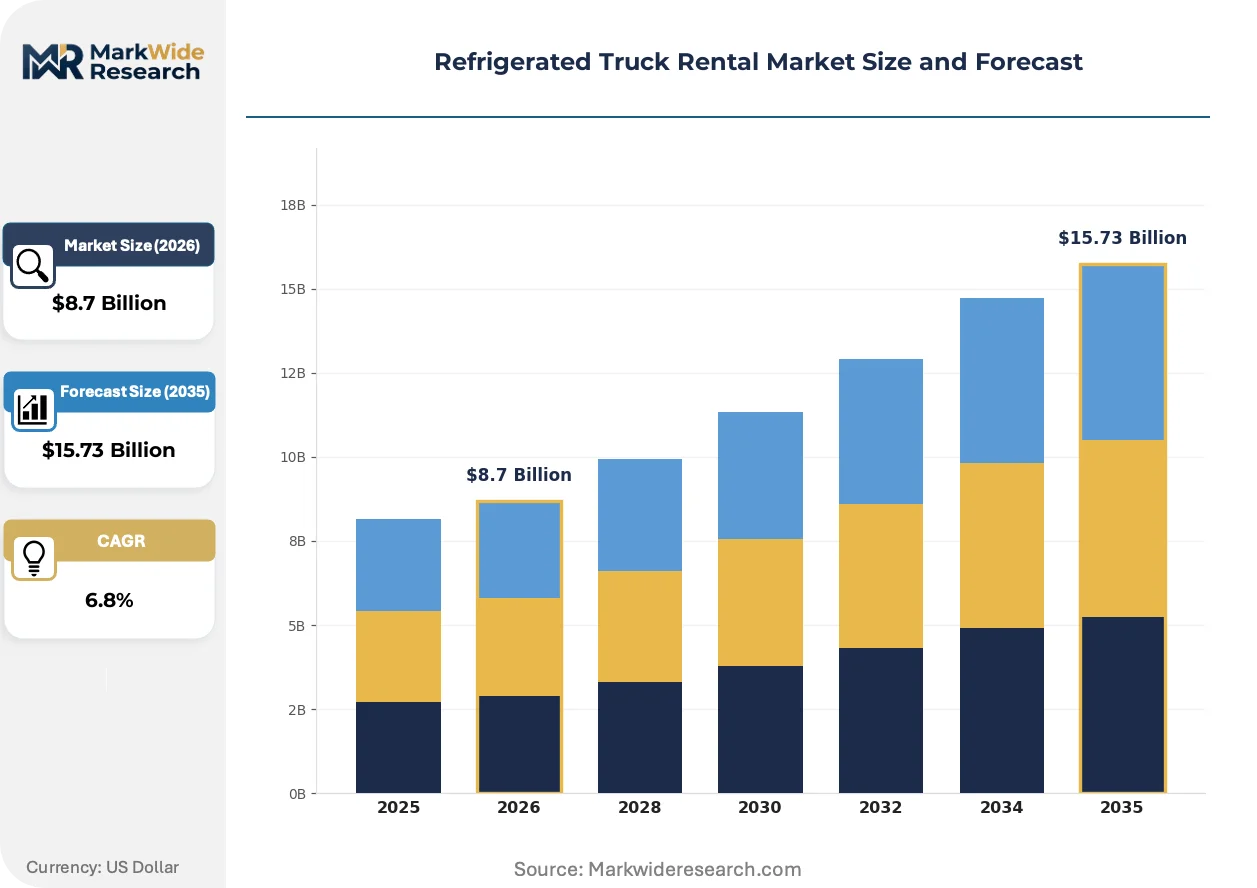
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty, Medium Duty, Heavy Duty, Ultra Heavy Duty Cooling Technology: Vapor Compression, Refrigerated Cargo, Cryogenic, Hybrid End User: Food & Beverage, Pharmaceutical, Agriculture, Chemicals Rental Duration: Short-Term, Long-Term, Seasonal, One-Way |
| Companies Covered | Petit Forestier, Lakeside International Trucks, Ryder System, Marten Transport, Prime Inc., Penske Corporation, Hertz Corporation, C.R. England, Fraikin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Truck Rental Market Emerging Trajectories
Refrigerated truck rental markets are experiencing simultaneous pressure from electrification mandates, thermal validation requirements, and demand volatility from perishable e-commerce, compressing traditional equipment lifecycles and service models.
Electric transport refrigeration units utilizing battery-powered compressors are rendering obsolete diesel-powered mechanical systems in last-mile food distribution. Urban supermarket chains in Germany and the United Kingdom are specifying electric-only refrigeration for new rental contracts. This shift is compressing residual values for conventional diesel units and forcing accelerated depreciation schedules across European fleets.
The EPA Phase 3 greenhouse gas standards impose progressively tighter CO2 limits on heavy-duty vehicles, including transport refrigeration unit emissions. Fleet operators must now procure zero-emission-capable chassis or face escalating compliance penalties. Long-haul pharmaceutical distributors in the United States are responding by piloting hybrid-electric configurations that preserve range while meeting interim standards.
Shippers now unbundle temperature monitoring and compliance documentation from base rental rates, purchasing validated cold chain data as a separate service tier. Food distributors and pharmaceutical logistics providers are selecting rental partners based on real-time telemetry capabilities rather than vehicle specifications alone. This behavioral shift is most pronounced in the United States, where FDA food safety modernization requirements mandate continuous temperature records for high-risk cargo.
Refrigerated Truck Rental Market Segmentation
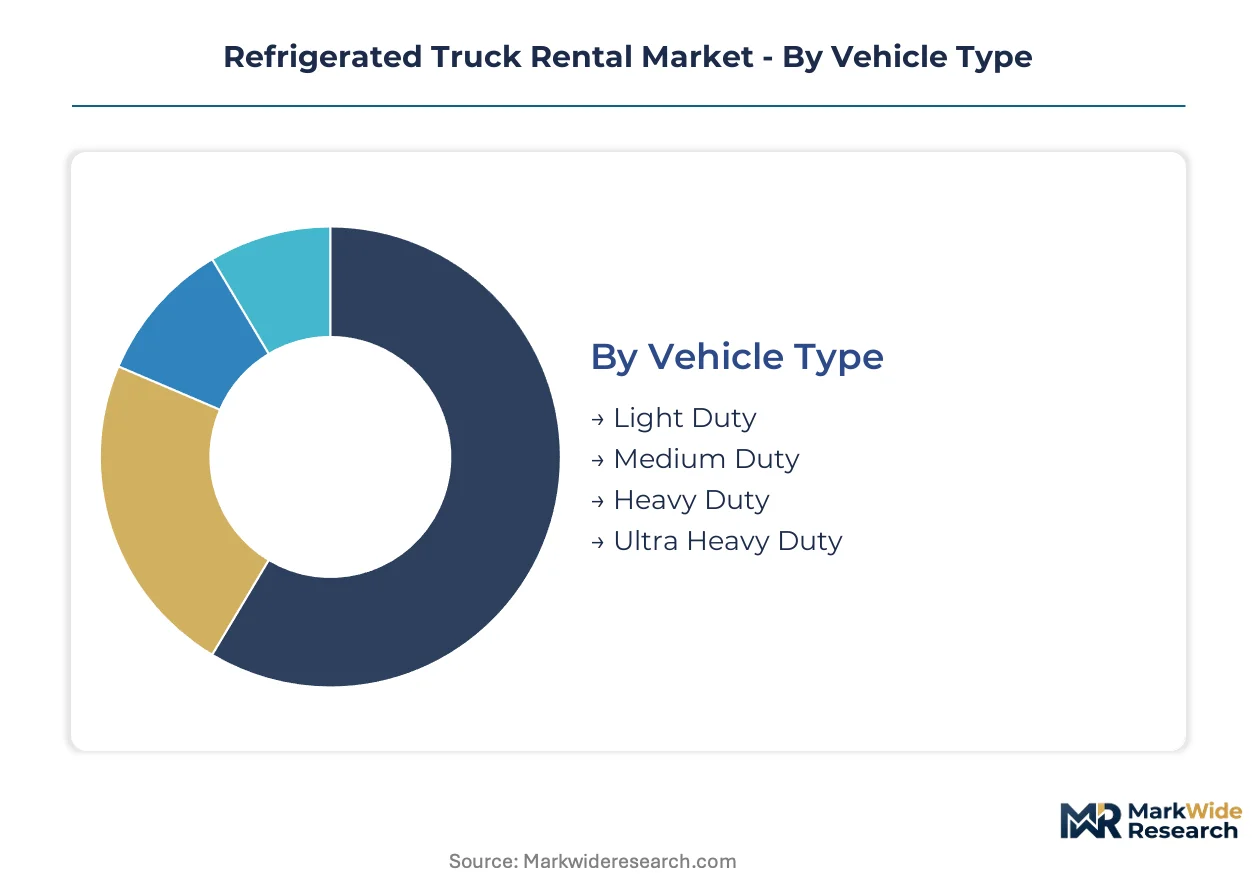
Refrigerated truck rental segmentation reveals divergent equipment lifecycles and service intensity profiles across vehicle classes and cooling architectures. Fleet operators calibrate depreciation schedules and maintenance protocols against the thermal validation requirements and utilization patterns inherent to each segment.
Vehicle Type:
After-sales service intensity escalates with vehicle mass as refrigeration unit complexity and chassis integration depth multiply across the duty spectrum.
- Light Duty:Compact insulated vans and small trucks dominate urban last-mile food delivery where maneuverability constraints in dense city centers dictate specifications. German supermarket chains and French urban logistics providers specify these units for multi-drop routes under 150 kilometers, with electric refrigeration penetration highest in this class due to depot charging feasibility.
- Heavy Duty:Articulated tractor-trailers with integrated transport refrigeration units serve long-haul pharmaceutical distribution where continuous temperature validation commands premium rental rates. The United States interstate corridor network concentrates demand for these configurations, though battery-electric range limitations under full refrigeration load constrain zero-emission deployment.
- Medium Duty:Regional distribution workhorses bridging urban and intercity routes, typically specified by food service distributors for hub-and-spoke networks.
- Ultra Heavy Duty:Specialized configurations for bulk chemical transport and deep-frozen cargo requiring extended autonomy from external power sources.
Heavy Duty holds the largest share; momentum sits with Light Duty as urban low-emission zones expand.
Cooling Technology:
Technology selection determines capital deployment timing as regulatory phase-outs compress residual values for conventional systems.
- Vapor Compression:The mature installed base utilizes mechanical refrigeration cycles with diesel-powered compressors, now facing accelerated obsolescence from EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants. Fleet operators in France and Germany are retiring these units ahead of depreciation schedules as low-emission zone access restrictions multiply.
- Hybrid:Electric compressor systems paired with auxiliary battery packs enable diesel-free operation in urban zones while preserving range flexibility for longer routes. United Kingdom supermarket rental contracts increasingly specify hybrid-only specifications for new fleet commitments.
- Cryogenic:Liquid nitrogen or carbon dioxide cooling systems for ultra-low temperature requirements in specialized pharmaceutical and chemical applications.
- Refrigerated Cargo:Passive thermal containers utilizing phase-change materials for short-duration protection without active mechanical systems.
Vapor Compression retains installed-base dominance; Hybrid is climbing the fastest as compliance deadlines tighten.
End User:
Customer type dictates contract structure as pharmaceutical shippers unbundle temperature validation from base vehicle rental.
- Pharmaceutical:Temperature-sensitive biologics and gene therapies require validated cold chain documentation with real-time telemetry, transforming rental relationships toward outcome-based performance contracts. FDA food safety modernization requirements in the United States mandate continuous temperature records, driving selection of rental partners based on data capabilities rather than vehicle specifications alone.
- Food & Beverage:Direct-to-consumer perishable delivery networks generate spot rental demand for flexible capacity without long-term asset ownership, particularly concentrated in United States e-commerce fulfillment corridors.
- Agriculture:Post-harvest loss reduction programs in India subsidize refrigerated transport capacity, opening fleet deployment opportunities in agricultural corridors.
- Chemicals:Hazardous material transport requiring specialized containment and temperature stability for reactive substances.
Food & Beverage generates the highest transaction volume; Pharmaceutical delivers the steepest expansion trajectory through biologics cold chain multiplication.
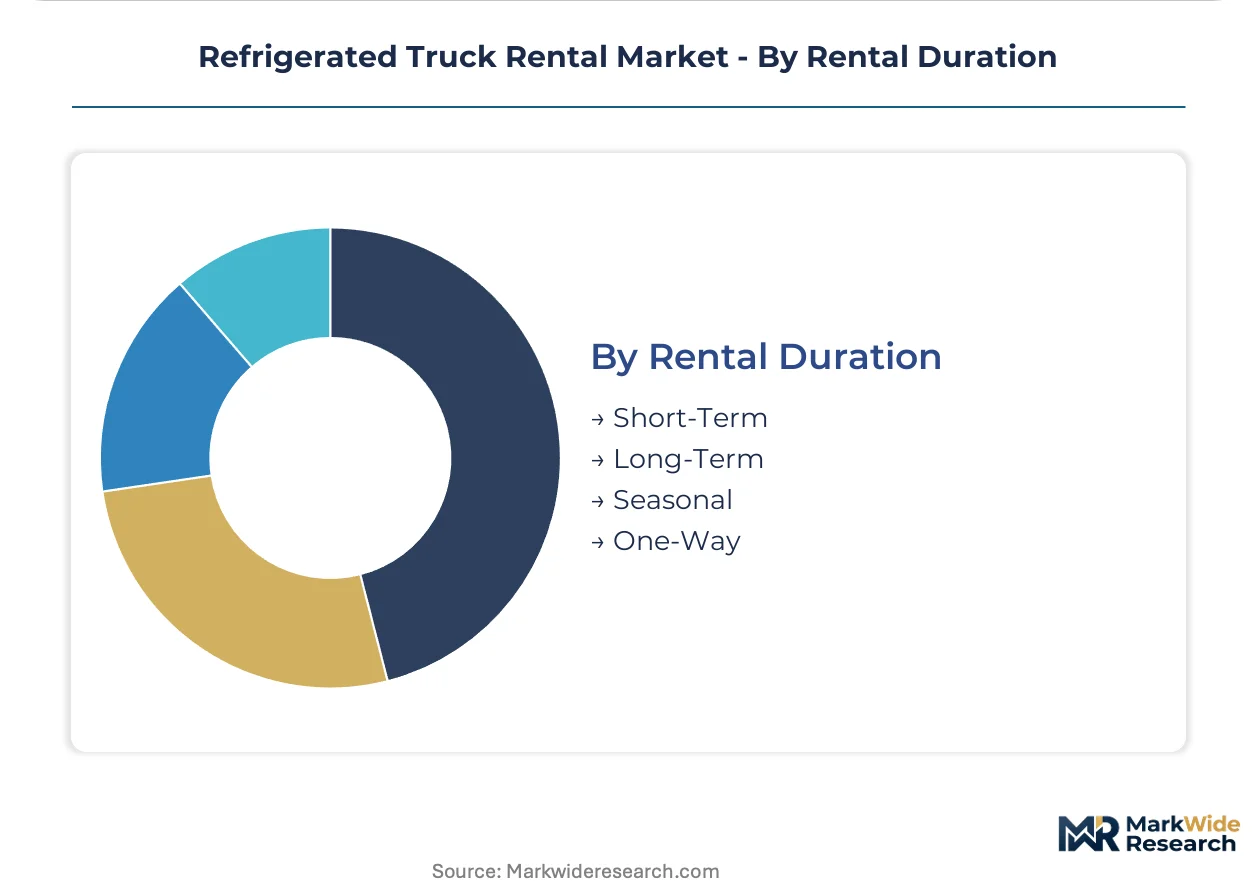
Rental Duration:
Contract length determines fleet utilization optimization approaches and working capital intensity for operators.
- Short-Term:Daily to weekly rentals for demand spikes, equipment failures, or seasonal overflow, requiring dense service center networks to sustain availability. Ryder System leverages North American service center density to capture this demand from food distributors.
- Long-Term:Multi-year contracts with supermarket chains and pharmaceutical distributors, enabling Fraikin Limited to anchor European multi-temperature fleet operations through structured asset planning.
- Seasonal:Harvest-period surges in agricultural regions with equipment repositioning challenges.
- One-Way:Point-to-point rentals for relocation or specialized moves without return logistics.
Long-Term contracts secure the revenue base; Short-Term rentals are gaining share fastest as food e-commerce volatility intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Phase 3 standards and CARB Advanced Clean Trucks rule are compressing fleet procurement timelines across the United States, while EU F-Gas Regulation accelerates equipment turnover in European corridors. India is subsidizing cold chain infrastructure to reduce agricultural losses. This divergence in regulatory pressure and subsidy intensity is fragmenting fleet deployment strategies by geography.
United States
Food e-commerce fulfillment networks in California and Texas generate spot rental demand for flexible refrigerated capacity without long-term asset ownership. FDA food safety modernization requirements mandate continuous temperature records for high-risk cargo, transforming vendor selection criteria. The Interstate 95 corridor from Boston to Miami concentrates pharmaceutical distribution fleets requiring validated cold chain documentation.
Germany
Urban supermarket chains in Berlin and Munich are specifying electric-only refrigeration for new rental contracts as low-emission zone access restrictions multiply. The EU F-Gas Regulation restricts hydrofluorocarbon refrigerants, forcing fleet operators to retire vapor compression units ahead of depreciation schedules. The Rhine-Ruhr industrial cluster anchors multi-temperature fleet operations serving pan-European distribution networks.
France
Specialized light-duty vehicles designed for dense delivery routes dominate Paris and Lyon urban logistics, where maneuverability constraints dictate specifications. ANSM pharmaceutical transport guidelines tighten thermal validation requirements for biologics distribution. The Petit Forestier network exemplifies urban-focused fleet architecture optimized for multi-drop routes under 150 kilometers.
India
Government PLI scheme subsidies for cold chain infrastructure are expanding refrigerated transport capacity in Maharashtra and Gujarat agricultural corridors. FSSAI food safety regulations mandate temperature monitoring for perishable cargo, elevating rental operator compliance burdens. The Delhi-Mumbai Industrial Corridor is attracting fleet deployment to serve processed food export hubs.
United Kingdom
Supermarket rental contracts increasingly specify hybrid-only refrigeration specifications to enable diesel-free operation in London and Birmingham low-emission zones. ECHA REACH protocols restrict insulation materials, forcing cross-border compliance recalibration for Irish Sea freight routes. The Midlands distribution triangle concentrates regional hub-and-spoke refrigerated networks serving grocery retail chains.
Refrigerated Truck Rental Market Vendor Landscape
Capability concentration sits with specialized temperature-control operators; scale advantage sits with diversified fleet leasing networks. The market structure tiers between premium-validated pharmaceutical specialists and volume-driven food distribution generalists. Three archetypes dominate: urban last-mile light-duty specialists, long-haul heavy-duty pharmaceutical validators, and multi-temperature European contract operators. Competitive moves center on hybrid-electric fleet refresh acceleration and outcome-based performance contracting that unbundles temperature validation from vehicle-hours.
Among North American diversified leasing networks, Ryder System and Penske Corporation exemplify scale-driven service center density strategies that capture short-term rental volatility from food distributors. Fraikin Limited anchors the European multi-temperature contract tier through structured long-term relationships with supermarket chains. Petit Forestier occupies the urban specialization niche with fleet architecture optimized for dense French delivery routes. Each represents a distinct competitive vector rather than direct overlap.
| Leading Market Players |
|---|
| Petit Forestier |
| Lakeside International Trucks |
| Ryder System |
| Marten Transport |
| Prime Inc. |
| Penske Corporation |
| Hertz Corporation |
| C.R. England |
| Fraikin Limited |
| Others |
Supply Flow & Price Mechanics
The Interstate 95 pharmaceutical corridor from Boston to Miami concentrates premium rental rates for validated cold chain capacity, where supply scarcity among EPA-compliant heavy-duty units enables operators to command three-tier pricing separation across pharmaceutical-grade, food-grade, and general cargo tiers while cross-border regulatory friction inflates procurement costs for multi-state fleets.
Pricing Analysis
United States spot rates diverge sharply from European contract structures, with California and Texas food e-commerce corridors showing widest spreads between peak and trough pricing. Premium-mid-economy pricing differentiation rests on thermal validation certification level and real-time telemetry capability, not vehicle specifications alone. Cost compression in diesel-powered units is intensifying because EPA Phase 3 compliance deadlines accelerate asset retirement ahead of depreciation schedules. Food distributors exhibit highest price sensitivity, while pharmaceutical shippers absorb premium pricing for guaranteed temperature performance.
Supply Chain Analysis
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants function as de facto export controls, limiting flows of conventional vapor compression units into European markets. Manufacturing concentration clusters in Germany, France, and the United States for transport refrigeration units, with battery-electric compressor systems drawing from South Korean and Chinese cell suppliers. Single-source vulnerability sits with specialized low-GWP refrigerant production. Distribution runs through OEM-integrated dealer networks and independent rental operators with regional service center density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification mandates across the United States and European Union are compressing equipment lifecycles and forcing capital reallocation before total cost parity matures, creating a high-growth disruption window for fleet operators who can bridge the hybrid transition.
For Market Incumbents: Pre-empt regulatory obsolescence by accelerating hybrid-electric fleet refresh ahead of CARB compliance deadlines for transport refrigeration units. Secure backward integration into battery-electric compressor maintenance capabilities to offset technician skill scarcity constraining service network expansion. Lock long-term pharmaceutical contracts through outcome-based performance guarantees that unbundle temperature validation from vehicle-hours. For New Entrants and Emerging Players: India's Maharashtra and Gujarat agricultural corridors offer fleet deployment white space where PLI scheme subsidies reduce capital barriers for refrigerated transport capacity. Target short-term rental volatility from United States food e-commerce fulfillment networks, where dense service center availability remains scarce. Lead with electric-only light-duty specifications for urban low-emission zone access in German and United Kingdom supermarket contracts. For Investors and Strategic Acquirers: Specialized temperature-control operators with validated pharmaceutical capabilities and integrated telemetry platforms represent the most defensible acquisition archetype. Monitor hybrid-electric range performance under full refrigeration load as the critical inflection signal for zero-emission deployment viability. Material improvements in battery energy density would accelerate diesel phase-out timelines and revalue conventional fleet residual positions.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Fleet Refresh Acceleration | EPA Phase 3 compliance deadlines compress diesel asset lifecycles and force premature capital deployment. |
| Outcome-Based Performance Contracting | FDA food safety modernization requirements enable premium pricing through guaranteed temperature-validated delivery. |
| India Cold Chain Infrastructure Expansion | PLI scheme subsidies in Maharashtra and Gujarat agricultural corridors reduce fleet deployment capital barriers. |
| Electric Compressor Maintenance Capability | Cross-training across high-voltage powertrains and HVAC systems addresses technician skill scarcity constraining growth. |
| Real-Time Telemetry Platform Integration | Pharmaceutical shippers now select rental partners based on continuous temperature monitoring data capabilities. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers at food distributors, pharmaceutical logistics directors, rental operator executives, and transport refrigeration unit OEM technical leads. Secondary validation drew from EPA regulatory filings, CARB compliance databases, EU F-Gas Regulation implementation reports, and refrigerated vehicle registration data. Bottom-up fleet deployment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Calibration anchored historical fleet penetration rates against regulatory deadline schedules and subsidy program disbursements. Segmentation dimensions spanned vehicle duty class, cooling technology architecture, end-user industry vertical, and rental contract duration structure. CAGRs were derived from equipment replacement cycle compression and demand elasticity across pharmaceutical biologics and food e-commerce channels. Forecast inputs incorporated battery-electric range degradation curves under full refrigeration load and low-GWP refrigerant supply allocation constraints.
Practitioners should monitor CARB transport refrigeration unit certification timelines and low-GWP refrigerant production allocation for early signals of supply constraint. Forecasts reflect assumptions around hybrid technology adoption rates and subsidy program continuity. Material shifts in battery energy density performance or federal-state regulatory divergence on zero-emission mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
Bulk Transportation Services Market
Transportation Services
Canada White Glove Delivery Service Market
Transportation Services
Bike Rental Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Multispace Parking Meter Market
Transportation Services
Waste Collection Vehicle Market
Transportation Services
Europe Van Rental Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
Spain Car Rental Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Third Party Logistics Services Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
Scooter Rental Market