
 Para Nitrophenol Market | 2026-2036
Para Nitrophenol Market Size, Share, and Industry Trends Forecast 2026-2036
Para Nitrophenol Market Analytics
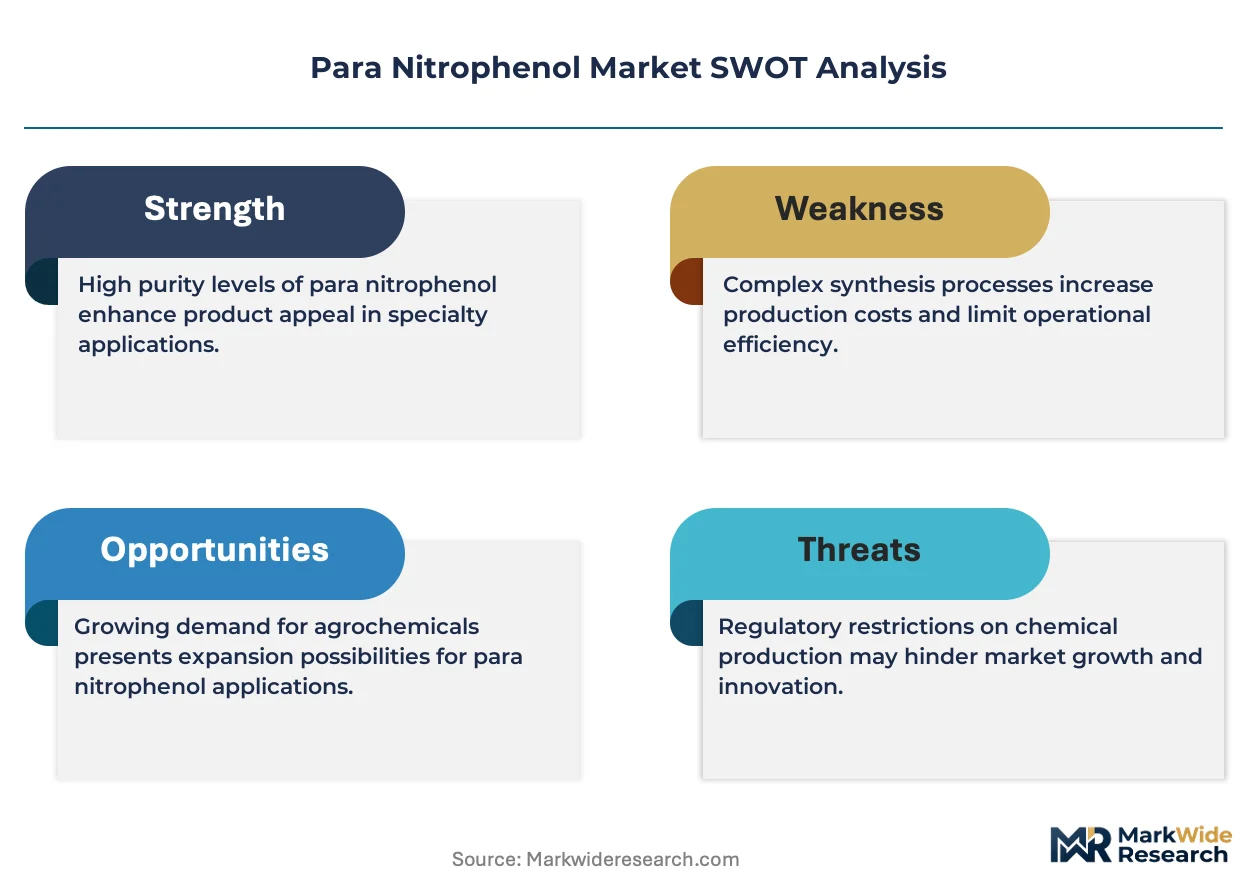
Multi-source procurement of nitroaromatic intermediates is recalibrating how chemical manufacturers secure para nitrophenol feedstock. BASF SE leverages its integrated aromatics chain to sustain European supply reliability for pharmaceutical-grade material. Deepak Nitrite Limited anchors South Asian volume through backward integration into nitrobenzene derivatives. Jiangsu Zhongdan Group competes on cost-optimized batch production for agricultural chemical applications.
Para nitrophenol is a nitro-substituted phenol with a para-directed hydroxyl group, typically synthesized via nitration of phenol or hydrolysis of para-nitrochlorobenzene, and functions as a critical intermediate for azo dyes, analgesic APIs, and organophosphorus pesticides. The analytical reagents segment leads value capture due to stringent purity certifications required by pharmaceutical quality control labs, while the pesticides application shows structural momentum from renewed agricultural chemical registration cycles in emerging production zones. Drug formulation channels generate concentrated margin pools because GMP-compliant para nitrophenol commands specification premiums over technical-grade material used in industrial dye synthesis.
REACH registration requirements in Europe and EPA toxic substance reporting in the United States elevate compliance costs for para nitrophenol importers, filtering market access toward producers with documented substance dossiers. India's CDSCO and China's NMPA both mandate residual solvent testing that shapes specification tiers across pharmaceutical versus industrial grades. Stakeholders must monitor evolving nitroaromatic hazard classifications under OECD chemical assessment frameworks to anticipate reformulation mandates and substitution pressures.
Market Dynamics
Pharmaceutical-grade para nitrophenol procurement is tightening around GMP-certified supply chains as India's CDSCO and China's NMPA enforce residual solvent testing that splits technical and pharmaceutical specification tiers into non-interchangeable categories.
Growth Catalysts
- CDSCO impurity profiling mandates:India's pharmaceutical regulator now requires documented nitroaromatic impurity thresholds for API registration, forcing domestic formulators toward certified para nitrophenol intermediates.
- Organophosphorus pesticide registration cycles:Agricultural chemical re-registration in Brazil and India is renewing demand for para nitrophenol-derived intermediates used in insecticide synthesis.
- Maharashtra chemical belt concentration:Specialty chemical clusters near Mumbai now integrate para nitrophenol production with downstream azo dye and API formulation capabilities.
Market Restraints
- Nitrobenzene feedstock volatility:Para nitrophenol producers face benzene derivative cost swings that compress margin predictability across batch production cycles.
- REACH registration cost barriers:ECHA substance dossier requirements filter European market access toward producers with documented toxicological profiles, excluding smaller technical-grade suppliers.
- Green chemistry substitution pressure:OECD hazard assessment frameworks are elevating nitroaromatic compound scrutiny, prompting agrochemical formulators to evaluate bio-based alternatives.
Strategic Opportunities
- Underpenetrated Southeast Asian pharma manufacturing:Vietnam and Indonesia lack domestic para nitrophenol capacity for API synthesis, creating import substitution openings for certified producers.
- Continuous flow nitration technology:Microreactor systems for phenol nitration are converging with quality-by-design protocols to enable smaller-batch pharmaceutical-grade output.
- EU Green Deal sustainable chemistry incentives:ECHA funding streams for hazard-reducing process innovation reward para nitrophenol producers adopting solvent recovery and waste minimization systems.
Industry Challenges
- GMP certification timeline compression:Pharmaceutical-grade para nitrophenol qualification requires 18-24 month CDSCO or NMPA approval cycles that strain working capital for mid-scale producers.
- Legacy batch reactor retrofit costs:Converting conventional nitration infrastructure to meet current OSHA and EPA process safety management standards demands capital outlays that fragment competitive tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Para Nitrophenol Market |
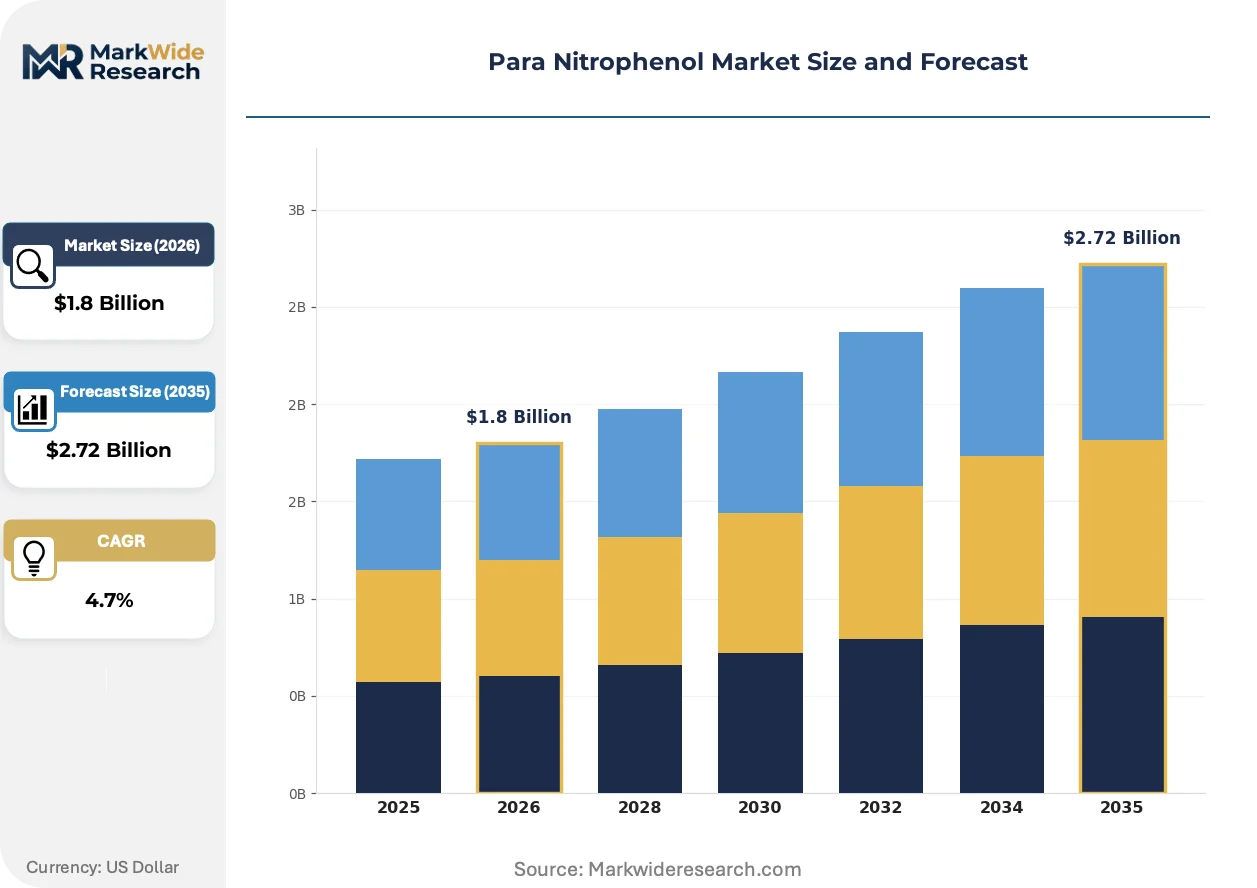
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical Reagents, Dyes, Pharmaceuticals, Pesticides End User: Chemical Manufacturers, Laboratories, Agricultural Sector, Healthcare Providers Application: Research & Development, Industrial Manufacturing, Quality Control, Drug Formulation Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Merck KGaA, Jiangsu Zhongdan Group, BASF SE, Haihang Industry Co., Ltd., Lianyungang Mupro Fi Chemical, Lanxess AG, Tokyo Chemical Industry, Deepak Nitrite Limited, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Para Nitrophenol Market Evolving Landscape
Process intensification and regulatory data transparency are restructuring how para nitrophenol producers compete across pharmaceutical and industrial grade segments.
Continuous flow microreactor technology for phenol nitration is converging with real-time analytical monitoring to enable pharmaceutical-grade para nitrophenol production in smaller, more frequent batches. European API manufacturers are adopting these systems to reduce solvent waste and accelerate CDSCO-compliant documentation. This convergence is compressing the minimum efficient scale for certified production, fragmenting volume concentration among specialized mid-cap producers.
China's NMPA tightened impurity profiling standards for imported chemical intermediates in 2023, forcing foreign para nitrophenol suppliers to submit comprehensive nitrosamine and residual solvent test data. The regulation is redirecting procurement toward producers with pre-established Chinese dossier documentation. Indian API exporters are responding by securing dual-certified supply chains that satisfy both CDSCO domestic and NMPA export requirements.
Long-term offtake contracts are displacing spot market purchasing among pharmaceutical formulators seeking supply security for para nitrophenol intermediates. This behavioral shift is consolidating procurement power with integrated API producers in Maharashtra and Gujarat who can guarantee multi-year GMP-compliant supply. The contract model is most visible in analgesic API manufacturing, where paracetamol producers lock in para nitrophenol feedstock to hedge against CDSCO inspection-driven supply interruptions.
Para Nitrophenol Market Segmentation
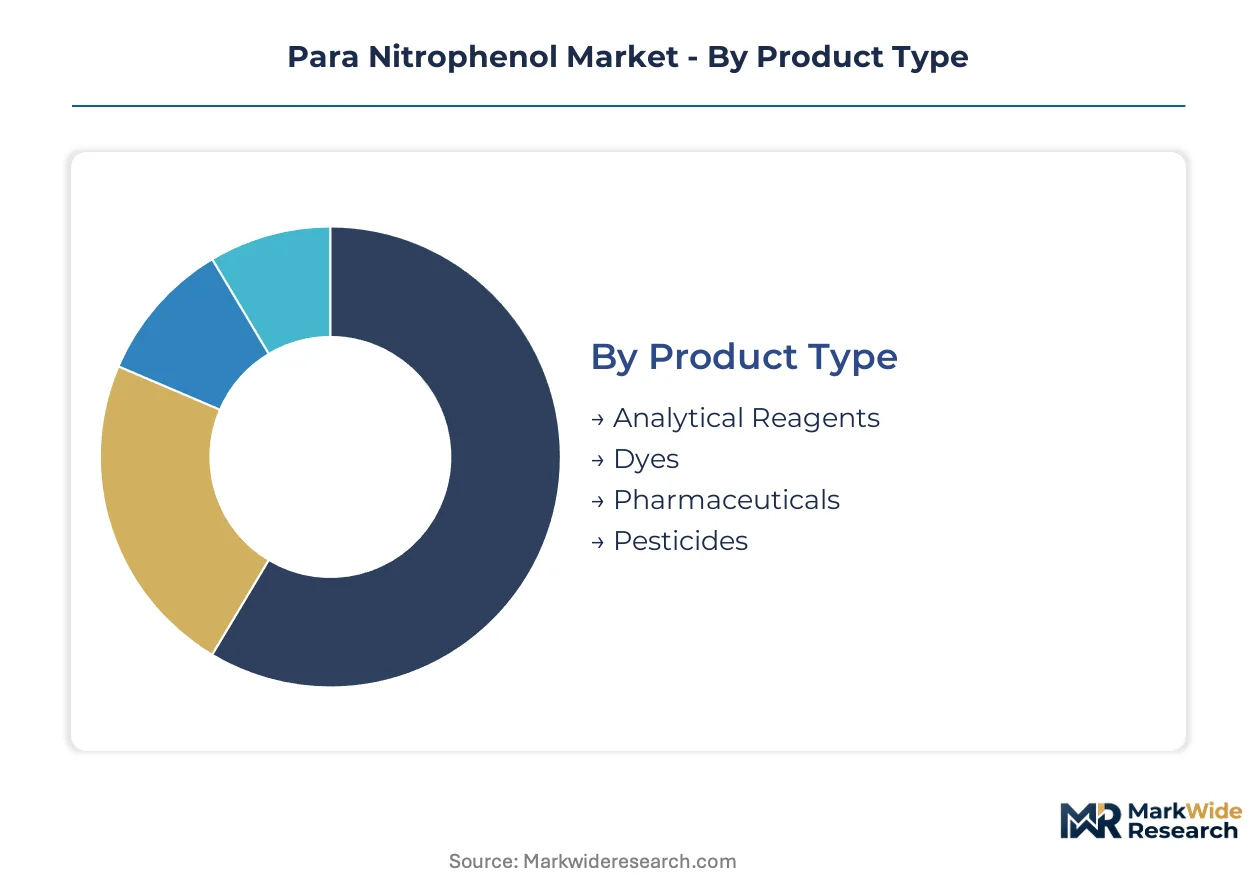
Segmentation in para nitrophenol markets tracks how specification tiers split across pharmaceutical, industrial, and analytical channels. Each axis reveals distinct margin structures and certification requirements that shape supplier competitive positioning.
Product Type:
Purity thresholds and documentation requirements define how para nitrophenol grades partition across value chains.
- Pharmaceuticals:GMP-certified material with documented impurity profiles for API synthesis commands specification premiums. CDSCO and NMPA residual solvent mandates concentrate procurement among dossier-qualified producers in Maharashtra and Jiangsu.
- Analytical Reagents:Ultra-high purity grades for quality control laboratories require certified reference material traceability. European pharmacopeia compliance elevates pricing power for producers with ECHA-registered substance dossiers.
- Dyes:Technical-grade material for azo dye intermediates competes on batch cost and color yield consistency. Maharashtra chemical belt clusters integrate this output with downstream textile chemical formulation.
- Pesticides:Organophosphorus insecticide precursors face renewal-driven demand cycles in Brazil and India. Registration timelines for agricultural chemical re-registration shape intermediate procurement patterns.
Pharmaceuticals leads on scale; analytical reagents leads on momentum.
End User:
Customer sophistication and regulatory exposure determine service intensity and contract structures.
- Healthcare Providers:Hospital and clinic laboratories driving analytical reagent consumption prioritize lot-to-lot consistency for diagnostic reliability. NMPA import documentation requirements redirect procurement toward pre-certified supply chains.
- Chemical Manufacturers:Integrated API and dye producers securing backward-anchored feedstock dominate volume absorption. CDSCO inspection readiness shapes supplier qualification timelines for this segment.
- Laboratories:Academic and industrial R&D facilities purchase smaller batches with heightened purity documentation. Real-time analytical monitoring capabilities differentiate preferred vendors.
- Agricultural Sector:Pesticide formulators face OECD hazard assessment pressures accelerating bio-based substitution evaluation. Registration renewal cycles in key production zones create demand pulsing.
Chemical manufacturers anchors volume concentration; healthcare providers shows steepest specification escalation.
Application:
Process stage and documentation burden segment para nitrophenol deployment across discovery-to-manufacturing workflows.
- Drug Formulation:Final-stage API manufacturing demands GMP-compliant intermediates with complete impurity profiling. Long-term offtake contracts are displacing spot purchasing among paracetamol producers hedging CDSCO inspection risk.
- Quality Control:Pharmaceutical release testing and environmental monitoring applications require certified reference materials. EMA and FDA pharmacopeial alignment elevates documentation costs for this segment.
- Research & Development:Discovery-phase consumption favors flexible procurement with rapid specification adjustment. Smaller batch microreactor production is penetrating this application tier.
- Industrial Manufacturing:Dye and agrochemical synthesis operates on cost-optimized technical grades with batch-to-batch variability tolerance. Continuous flow technology adoption remains limited in this price-sensitive tier.
Industrial manufacturing retains volume dominance; drug formulation captures margin expansion.
Distribution Channel:
Supply chain configuration and customer proximity shape channel economics and working capital intensity.
- Distributors:Regional chemical distributors bridge certified producers with fragmented laboratory and mid-scale manufacturing demand. Documentation custody and lot traceability capabilities determine competitive position.
- Direct Sales:Integrated API producers and large dye manufacturers secure dedicated supply relationships with Maharashtra and Gujarat producers. Multi-year contracts with price adjustment clauses characterize this channel.
- Wholesale:Volume aggregation for technical-grade material serves agricultural chemical and industrial dye formulators. Benzene derivative cost pass-through mechanisms vary across contract structures.
- Online Retail:Small-laboratory and research procurement through specialized chemical platforms grows for analytical reagent grades. Certificate of analysis accessibility and rapid fulfillment differentiate platform offerings.
Direct sales commands value concentration; online retail gains share fastest in analytical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing para nitrophenol production toward jurisdictions where compliance costs remain manageable relative to specification premiums. Producers migrate capacity to exploit gaps between REACH dossier requirements and emerging-market certification timelines.
China
NMPA impurity profiling mandates for imported intermediates are redirecting procurement toward domestic producers with pre-established dossier documentation. Yangtze River Delta chemical clusters near Shanghai now integrate para nitrophenol output with downstream API formulation for export markets. Jiangsu-based producers leverage backward integration into nitrobenzene derivatives to absorb benzene feedstock volatility.
India
CDSCO residual solvent testing requirements for API registration are forcing formulators toward certified para nitrophenol intermediates with documented nitroaromatic thresholds. Maharashtra's chemical belt near Mumbai anchors South Asian volume through specialty chemical clusters serving both domestic labs and export-oriented producers. Gujarat-based integrated API manufacturers now lock in multi-year offtake contracts to hedge inspection-driven supply interruptions.
Germany
EMA pharmacopeia alignment and REACH substance dossier requirements filter market access toward producers with documented toxicological profiles. BASF SE leverages its integrated aromatics chain in Ludwigshafen to sustain European supply reliability for pharmaceutical-grade material. ECHA funding streams for hazard-reducing process innovation reward solvent recovery system adoption among specialty chemical producers.
United States
EPA toxic substance reporting elevates compliance costs for para nitrophenol importers, concentrating procurement among producers with established substance dossiers. Gulf Coast petrochemical corridors provide feedstock proximity for nitrobenzene derivative production serving agricultural chemical applications. FDA pharmacopeial standards for API intermediates split technical and pharmaceutical specification tiers into non-interchangeable categories.
Brazil
ANVISA agricultural chemical re-registration cycles are renewing demand for para nitro phenol-derived intermediates used in organophosphorus insecticide synthesis. São Paulo state chemical clusters face OECD hazard assessment pressures accelerating bio-based substitution evaluation. Registration renewal timelines shape intermediate procurement patterns among pesticide formulators.
Para Nitrophenol Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue microreactor-based pharmaceutical-grade specialization. The vendor base stratifies across integrated aromatics majors, regional nitrobenzene derivative specialists, and contract manufacturers serving analytical reagent channels. Three archetypes dominate: backward-integrated feedstock controllers, GMP-certified pharmaceutical intermediates suppliers, and cost-optimized batch producers for industrial dyes. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing long-term offtake agreements to lock in CDSCO and NMPA-compliant supply chains.
Among European-integrated majors, BASF SE and Merck KGaA exemplify the dossier-qualified archetype serving pharmaceutical-grade demand. Deepak Nitrite Limited anchors South Asian volume concentration through regional nitrobenzene derivative integration. Jiangsu Zhongdan Group occupies the cost-optimized position for agricultural chemical applications.
| Leading Market Players |
|---|
| Merck KGaA |
| Jiangsu Zhongdan Group |
| BASF SE |
| Haihang Industry Co., Ltd. |
| Lianyungang Mupro Fi Chemical |
| Lanxess AG |
| Tokyo Chemical Industry |
| Deepak Nitrite Limited |
| Dow Chemical Company |
| Others |
Value Network & Pricing Analysis
CDSCO and NMPA residual solvent mandates for pharmaceutical-grade para nitrophenol are forcing procurement consolidation around GMP-certified producers, compressing supply alternatives and elevating specification premiums for dossier-qualified material. This regulatory-driven buyer consolidation grants pricing power to integrated manufacturers in Maharashtra and Jiangsu who can absorb nitrobenzene feedstock volatility through backward integration.
Pricing Analysis
Benzene derivative cost pass-through mechanisms dominate para nitrophenol pricing, with nitrobenzene feedstock swings compressing margin predictability across batch production cycles. Three-tier pricing structure across pharmaceutical, analytical, and technical grades reflects certification burden divergence: GMP-compliant material commands specification premiums over industrial dye grades, while analytical reagent purity tiers capture additional pharmacopeia compliance value. Cost compression in technical-grade batches is intensifying because agricultural chemical formulators face OECD hazard assessment pressures. Agricultural pesticide channels show highest price sensitivity; pharmaceutical API producers demonstrate lowest sensitivity due to CDSCO inspection risk hedging.
Supply Chain Analysis
Reverse-logistics flows for solvent recovery systems are gaining traction among European producers seeking ECHA Green Deal funding eligibility, creating circularity incentives that reshape procurement evaluation criteria. Supply concentrates in India, China, and Germany, with Maharashtra chemical belt clusters and Jiangsu nitrobenzene derivative corridors anchoring Asian volume. Feedstock dependencies on benzene, nitrochlorobenzene, and nitration catalysts expose producers to petrochemical commodity cycles. Single-source vulnerability around GMP-certified pharmaceutical-grade capacity constitutes the dominant structural risk. Distribution runs through direct sales channels for integrated API manufacturers and regional distributors serving fragmented laboratory demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Para nitrophenol markets present margin-expansion potential as continuous flow microreactor technology reduces solvent waste and batch rejection rates, lowering unit economics for certified pharmaceutical-grade production.
For Market Incumbents: Extend GMP certification coverage into dual CDSCO-NMPA compliance to capture Indian API export growth. Deepen backward integration into nitrobenzene derivatives to defend against feedstock cost volatility. Secure long-term offtake contracts with Maharashtra and Gujarat formulators to lock in volume concentration before microreactor entrants fragment pharmaceutical-grade tiers. For New Entrants and Emerging Players: Regional chemical distributors in Southeast Asia represent the most accessible channel partner type for penetrating Vietnam and Indonesia's API manufacturing gap. Target analytical reagent grades for European pharmacopeia compliance, where smaller batch microreactor output matches demand fragmentation. Pursue white-space positioning in certified reference material traceability, where documentation custody capabilities differentiate preferred vendors. For Investors and Strategic Acquirers: Asymmetric upside sits with microreactor-enabled mid-cap specialists possessing pre-established Chinese dossier documentation. Five-to-ten year viability favors producers combining continuous flow technology with solvent recovery infrastructure. Acquisition targets should demonstrate dual regulatory pathway readiness. Monitor NMPA impurity profiling enforcement intensity as the critical inflection signal for procurement redirection toward pre-certified supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrobenzene | Maharashtra producers absorb benzene volatility through captive feedstock supply. |
| Continuous Flow Microreactor Adoption | European API manufacturers reduce solvent waste while accelerating CDSCO documentation. |
| Dual CDSCO-NMPA Certification Investment | Indian exporters secure procurement preference for China-bound pharmaceutical intermediates. |
| Long-term Offtake Contract Structuring | Paracetamol producers hedge inspection-driven supply interruptions through multi-year agreements. |
| Solvent Recovery System Implementation | ECHA funding eligibility rewards hazard-reducing process innovation among specialty chemical producers. |
Research Methodology
Bottom-up pharmaceutical and agrochemical demand modeling reconciled against top-down nitrobenzene derivative production tracking forms the analytical core of this study. Primary interviews with plant managers at Indian and Chinese para nitrophenol facilities, procurement leads at downstream API manufacturers, distribution channel partners serving analytical reagent markets, and technical R&D directors at European specialty chemical producers combined with secondary validation. Secondary sources include customs and trade flow databases, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, ECHA substance dossier registries, and CDSCO drug master file repositories. Triangulation across these inputs ensures supply-side and demand-side estimates converge.
Historical trendline analysis of nitroaromatic intermediate consumption patterns informed projection frameworks across the analysis window. Segmentation modeling incorporated grade tier distinctions, end-use industry splits across pharmaceutical and agricultural channels, regional production hub concentration, and certification level differentiation. CAGRs were derived from fitted growth curves applied to validated baseline estimates. Industry-specific forecast inputs included agricultural chemical re-registration cycle timing and pharmaceutical inspection frequency trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to OECD hazard classification revisions and bio-based substitution technology maturation. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and feedstock cost pass-through elasticity. Practitioners should monitor NMPA dossier documentation requirements and ECHA Green Deal funding allocation patterns for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Phosphoric Acid Market
Bulk Chemicals
Benzyl Acetate Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Global Pitch Coke Market
Bulk Chemicals
Global Isobutanol Market
Bulk Chemicals
Middle East and Africa Ferric Chloride Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Mexico Calcium Carbonate Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Calcium Lactate Market
Bulk Chemicals
Barite Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Global Sodium Sulfate Market
Bulk Chemicals
US Magnesium Stearate Market