
 Sodium Ethylate Market | 2026-2036
Sodium Ethylate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Ethylate Market Analytics
China is reshaping sodium ethylate supply dynamics through capacity additions in Jiangsu and Shandong provinces. Evonik leverages its alkoxide technology leadership to sustain premium positioning in European pharmaceutical supply chains. BASF anchors large-volume contracts with agrochemical formulators across multiple continents. Changda Fine Chemical competes on cost-efficient solid-grade production for domestic dye intermediates.
Sodium ethylate is the sodium salt of ethanol, typically manufactured via direct reaction of metallic sodium with anhydrous ethanol under inert atmosphere, yielding a strong base with molecular formula CH3CH2ONa and purity grades ranging from 95% to 99% for industrial applications. It functions primarily as a condensation catalyst, ethylating agent, and strong base in organic synthesis across pharmaceutical, agrochemical, and fine chemical production. The liquid formulation dominates volume flows due to easier handling in continuous pharmaceutical processes, while solid sodium ethylate commands margin premiums from agrochemical producers seeking precise dosing control and extended shelf stability. Pharmaceutical application growth outpaces dye and biochemical segments, reflecting expanded generic API manufacturing in Asia.
REACH registration requirements in Europe mandate comprehensive toxicological dossiers for alkoxide importers, while EPA TSCA oversight in the United States governs new chemical notifications for modified sodium ethylate formulations. China's GB standards under SAMR authority specify moisture content and sodium hydroxide impurity limits that determine market access for domestic producers. Stakeholders must monitor evolving pharmaceutical cGMP catalyst specifications and alkoxide waste handling regulations as sustainability pressures intensify across manufacturing jurisdictions.
Market Dynamics
Pharmaceutical API manufacturing migration to Asian chemical clusters is compressing sodium ethylate supply chains and catalyzing capacity investments in Jiangsu and Gujarat production zones.
Growth Catalysts
- REACH compliance mandates:European pharmaceutical manufacturers are upgrading to higher-purity sodium ethylate grades to satisfy ECHA registration dossier requirements for alkoxide catalysts.
- Agrochemical condensation demand:Herbicide and fungicide formulators in Brazil and India are expanding sodium ethylate procurement for Claisen condensation reactions in active ingredient synthesis.
- Jiangsu Province capacity expansion:Chinese chemical producers are commissioning dedicated sodium ethylate lines to serve domestic pharmaceutical intermediate manufacturers.
Market Restraints
- Metallic sodium price volatility:Sodium ethylate production costs track London Metal Exchange sodium pricing, which fluctuates with chlor-alkali plant operating rates.
- Anhydrous ethanol supply concentration:Brazilian and US corn-based ethanol suppliers dominate feedstock flows, creating geographic dependency for European and Asian producers.
- Pyrophoric handling requirements:Sodium ethylate's spontaneous ignition risk in moist air necessitates nitrogen-blanketed storage infrastructure that limits small-batch user adoption.
Strategic Opportunities
- Solid-grade agrochemical penetration:Granular sodium ethylate formats offer extended shelf stability and precise dosing for Latin American formulators seeking supply chain simplification.
- Biocatalysis convergence:Enzymatic transesterification paired with sodium ethylate catalysis is opening novel routes to chiral pharmaceutical intermediates.
- India PLI scheme alignment:The country's production-linked incentive framework for active pharmaceutical ingredients is attracting sodium ethylate capacity co-location with API synthesis plants.
Industry Challenges
- Alkoxide waste handling compliance:Sodium ethylate quenching and neutralization protocols vary across EPA, MEE, and state pollution control jurisdictions, complicating multi-site manufacturing.
- cGMP catalyst certification timelines:Pharmaceutical-grade sodium ethylate qualification for FDA and CDSCO inspections requires 18-24 month stability documentation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Ethylate Market |
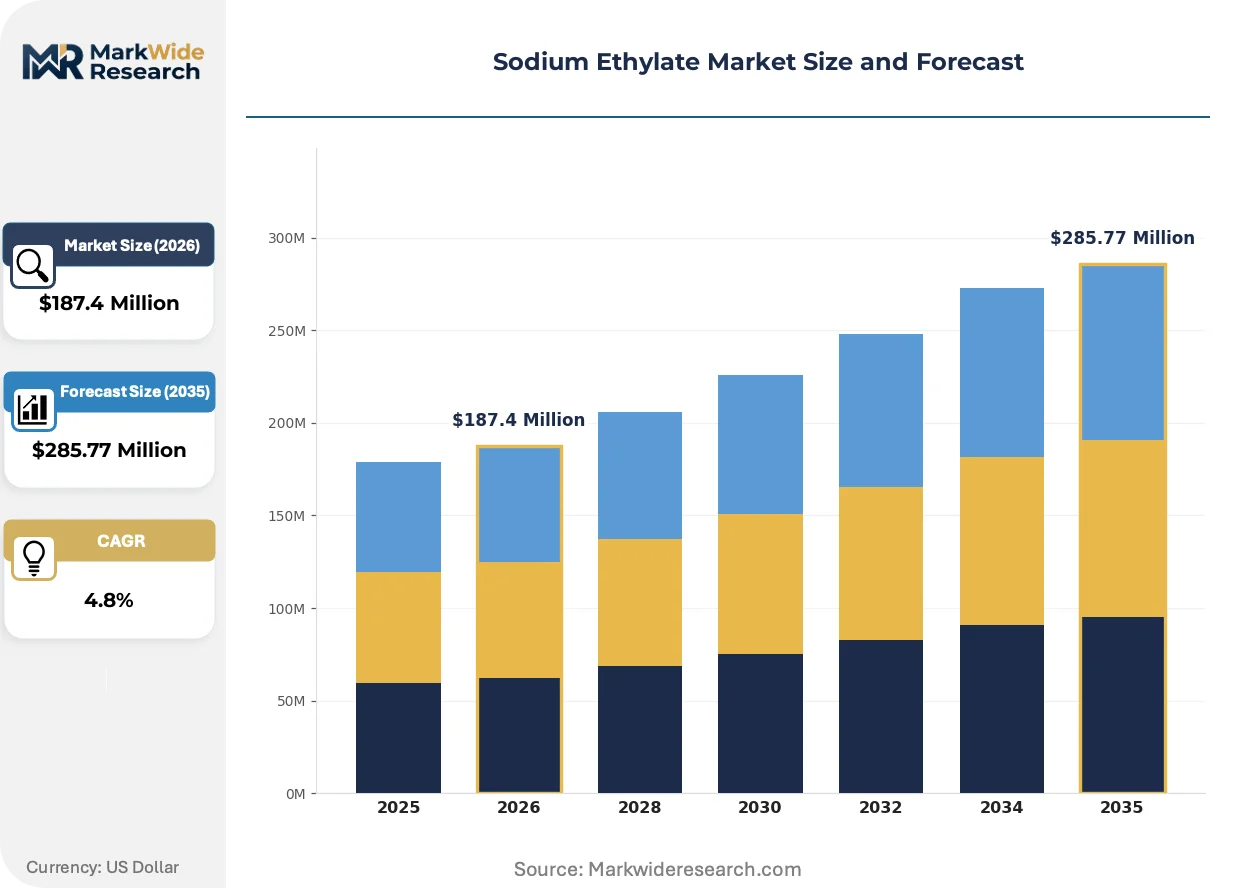
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Ethylate Liquid, Sodium Ethylate Solid, Sodium Ethylate Solution, Sodium Ethylate Powder Application: Pharmaceuticals, Agrochemicals, Dyes, Biochemical End User: Chemical Manufacturers, Research Institutions, Laboratories, Agriculture Distribution Channel: Online, Offline, Wholesale, Retail |
| Companies Covered | Evonik, BASF, Changda Fine Chemical, Xisace New Material Technology, Xusheng Chemical, Alkali Metals Ltd, American Elements, Gelest Inc., Oakwood Products, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Ethylate Market Evolving Landscape
Continuous flow chemistry adoption and regulatory purity escalation are forcing sodium ethylate formulation upgrades while digital supply tracking reshapes procurement relationships.
Membrane-based ethanol dehydration is rendering obsolete traditional azeotropic distillation for anhydrous ethanol production. Pharmaceutical manufacturers in Germany and Switzerland are adopting membrane-processed feedstocks for sodium ethylate synthesis to reduce energy intensity. This technology shift is compressing capital requirements for new alkoxide entrants and enabling modular plant designs.
China's GB standards under SAMR authority are tightening moisture content specifications for sodium ethylate used in pharmaceutical applications. Domestic producers must now certify sodium hydroxide impurity levels below 0.5% to access regulated drug intermediate supply chains. Jiangsu-based manufacturers are investing in automated titration systems to satisfy batch-release documentation requirements.
Long-term offtake agreements are displacing spot-market purchasing for sodium ethylate in agrochemical supply chains. Multinational formulators in Brazil and India are locking three-year supply contracts with fixed-volume escalators to secure catalyst availability. This behavioral shift is most pronounced among herbicide producers facing seasonal production windows and raw material synchronization pressures.
Sodium Ethylate Market Segmentation

Sodium ethylate procurement patterns diverge sharply across formulation types and end-use specifications, with pharmaceutical-grade purity requirements commanding fundamentally different supply chain configurations than agrochemical or dye intermediate applications. Understanding these segment boundaries clarifies why pricing spreads between liquid and solid grades persist despite feedstock commonality.
Product Type:
Mature liquid formulations dominate transaction volumes while solid and powder grades occupy emerging niches demanding precise handling characteristics.
- Sodium Ethylate Liquid:Standard 20-30% ethanol solution formulations enable continuous-flow pharmaceutical synthesis with minimal handling infrastructure. Jiangsu Province chemical manufacturers procure liquid grades in bulk tanker quantities for Claisen condensation reactions in generic API production, though pyrophoric storage requirements limit small-batch adoption.
- Sodium Ethylate Solid:Anhydrous granular or flake formats with 95-99% purity enable precise gravimetric dosing for agrochemical formulators. Brazilian herbicide manufacturers favor solid sodium ethylate for extended shelf stability during seasonal production windows, despite premium pricing over liquid equivalents.
- Sodium Ethylate Solution:Custom-concentration liquid preparations tailored to specific reactor loading specifications serve contract research organizations requiring flexibility.
- Sodium Ethylate Powder:Micronized particulate grades with enhanced flow properties address automated dosing systems in high-throughput screening laboratories.
Sodium Ethylate Liquid retains volume leadership; Sodium Ethylate Solid holds the steepest expansion curve.
Application:
Cost-tier stratification separates pharmaceutical-grade certification requirements from commodity-priced dye intermediate consumption.
- Pharmaceuticals:cGMP-compliant sodium ethylate catalyzes active pharmaceutical ingredient synthesis through Claisen condensation, transesterification, and alkylation pathways. CDSCO and FDA inspection protocols mandate 18-24 month stability documentation cycles for catalyst qualification, compressing supplier pools to REACH-registered alkoxide specialists.
- Agrochemicals:Herbicide and fungicide formulators deploy sodium ethylate for active ingredient condensation reactions, with Brazilian and Indian producers expanding procurement under seasonal production synchronization pressures.
- Dyes:Intermediate manufacturers in Gujarat State utilize technical-grade sodium ethylate for azo coupling and diazotization processes, prioritizing cost efficiency over certification overhead.
- Biochemical:Enzymatic transesterification paired with sodium ethylate catalysis enables chiral pharmaceutical intermediate production through emerging biocatalysis convergence.
Pharmaceuticals command margin premiums; Agrochemicals are expanding most quickly.
End User:
Customer-type differentiation separates large-volume chemical manufacturers from specification-sensitive research consumers.
- Chemical Manufacturers:Integrated pharmaceutical and agrochemical producers consume sodium ethylate in multi-ton quantities through long-term offtake agreements with fixed-volume escalators, displacing spot-market purchasing.
- Research Institutions:Academic and government laboratories require small-batch sodium ethylate with comprehensive certificate of analysis documentation for method development.
- Laboratories:Contract analytical and quality control facilities procure reagent-grade sodium ethylate for standardized testing protocols.
- Agriculture:Direct farm-level biocide formulators represent a nascent consumption channel with limited current penetration.
Chemical Manufacturers anchor procurement volumes; Research Institutions exhibit the steepest specification escalation.
Distribution Channel:
Supply concentration dictates channel viability, with hazardous material shipping regulations favoring established logistics networks over digital disruption.
- Online:Specialized chemical marketplaces serve research-scale purchasers with digitized certificate of analysis access and automated reordering systems.
- Offline:Direct manufacturer relationships dominate bulk pharmaceutical and agrochemical procurement through dedicated account management.
- Wholesale:Regional chemical distributors aggregate sodium ethylate with complementary alkoxide and catalyst portfolios for mid-tier manufacturers.
- Retail:Laboratory supply houses stock reagent-grade containers for immediate fulfillment of urgent research requirements.
Offline channels retain volume leadership; Online platforms are gaining share fastest.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA registration requirements in Europe anchor the most stringent compliance environment for sodium ethylate catalysts. Demand concentrates in pharmaceutical manufacturing clusters across Germany, China, India, Brazil, and the United States.
Germany
Evonik's alkoxide technology leadership sustains premium positioning in European pharmaceutical supply chains. REACH mandates comprehensive toxicological dossiers for alkoxide importers operating within German borders. Frankfurt-Rhine-Main chemical corridors host specialized sodium ethylate distribution networks serving contract API manufacturers.
China
Jiangsu Province capacity additions reshape sodium ethylate supply dynamics for domestic pharmaceutical intermediate producers. SAMR-enforced GB standards tighten moisture content specifications below 0.5% sodium hydroxide impurity thresholds. Shandong chemical manufacturers commission dedicated alkoxide lines to serve expanding generic API synthesis operations.
India
Gujarat State dye intermediate manufacturers procure technical-grade sodium ethylate for azo coupling processes. CDSCO inspection protocols mandate 18-24 month stability documentation cycles for catalyst qualification in pharmaceutical applications. The PLI scheme for active pharmaceutical ingredients attracts sodium ethylate capacity co-location with API synthesis plants in Maharashtra and Telangana.
Brazil
Herbicide formulators in São Paulo state expand sodium ethylate procurement for Claisen condensation reactions in active ingredient synthesis. ANVISA oversight governs import registration for alkoxide catalysts deployed in agrochemical manufacturing. Seasonal production windows drive long-term offtake agreements with three-year fixed-volume escalators among multinational formulators.
United States
EPA TSCA oversight governs new chemical notifications for modified sodium ethylate formulations entering commercial distribution. Corn-based ethanol feedstock dependency creates geographic concentration risk for domestic alkoxide producers. Gulf Coast chemical manufacturing clusters maintain nitrogen-blanketed storage infrastructure for pyrophoric handling compliance.
Sodium Ethylate Market Competitive Landscape
Specialized alkoxide technology leaders and diversified chemical conglomerates split the market along purity-grade and application vectors. The vendor base concentrates among European pharmaceutical-grade specialists, Asian cost-optimized producers, and North American reagent-grade suppliers. Three archetypes dominate: technology licensors commanding premium positioning in regulated supply chains, integrated chemical majors leveraging feedstock integration, and regional specialists competing on solid-grade production efficiency. Capacity expansion in Jiangsu and Gujarat production zones and strategic partnerships for cGMP certification acceleration represent the dominant competitive moves.
Within the technology-licensor tier, Evonik anchors European pharmaceutical supply chains through alkoxide expertise. BASF exemplifies the diversified chemical major archetype with large-volume contract positioning across multiple continents. Changda Fine Chemical occupies a cost-efficient production position serving domestic dye intermediate demand in China.
| Leading Market Players |
|---|
| Evonik |
| BASF |
| Changda Fine Chemical |
| Xisace New Material Technology |
| Xusheng Chemical |
| Alkali Metals Ltd |
| American Elements |
| Gelest Inc. |
| Oakwood Products, Inc |
| Others |
Value Network & Pricing Analysis
Shanghai-Ningbo port freight corridors anchor sodium ethylate cost structures, with container rates from Jiangsu Province chemical clusters compressing margin buffers for European pharmaceutical buyers while amplifying price differentiation between liquid bulk shipments and solid-grade specialty formats.
Pricing Analysis
Geographic price spreads between Jiangsu-manufactured technical grades and REACH-registered European pharmaceutical grades exceed three-to-one ratios, with contract-based long-term offtake agreements displacing spot-market purchasing across agrochemical supply chains. Price differentiation centers on cGMP certification overhead and sodium hydroxide impurity thresholds below 0.5%, with Brazilian herbicide formulators exhibiting highest price sensitivity due to seasonal production windows, while Swiss and German API manufacturers absorb premium positioning for alkoxide catalyst stability documentation. Cost compression in technical-grade segments is intensifying because Jiangsu capacity additions are feeding oversupply into dye intermediate channels.
Supply Chain Analysis
Dual-use chemical export-control regimes under OECD guidelines restrict alkoxide technology transfers to non-member jurisdictions, constraining capacity replication in emerging pharmaceutical manufacturing zones. Supply concentrates in China, India, and Germany, with raw material dependencies on metallic sodium from chlor-alkali producers and anhydrous ethanol from Brazilian and US corn-based suppliers. Single-source vulnerability runs through London Metal Exchange sodium pricing volatility, while distribution runs through nitrogen-blanketed tanker logistics for liquid grades and moisture-controlled containerization for solid formats.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium ethylate demand acceleration reflects pharmaceutical API manufacturing migration to Asian chemical clusters, with membrane-based ethanol dehydration and automated titration systems constituting the decisive technological inflection reshaping production economics.
For Market Incumbents: Insulate European pharmaceutical positioning through accelerated REACH-registered capacity expansion in Jiangsu Province, co-located with generic API synthesis plants under India's PLI scheme. Lock three-year offtake agreements with Brazilian agrochemical formulators before seasonal procurement windows compress pricing power. Prioritize backward integration into anhydrous ethanol production to neutralize Brazilian and US feedstock dependency risks. For New Entrants and Emerging Players: Gujarat State dye intermediate channels present the most penetrable white-space target, with technical-grade sodium ethylate procurement prioritizing cost efficiency over certification overhead. Solid-grade agrochemical penetration in Latin American herbicide formulation offers secondary entry, leveraging granular formats for precise dosing control. Pursue membrane-processed ethanol partnerships with Shandong chemical manufacturers to undercut legacy azeotropic distillation cost structures. For Investors and Strategic Acquirers: Alkoxide technology specialists with automated titration capabilities and SAMR-compliant batch-release systems represent the priority acquisition archetype for pharmaceutical-grade exposure. Long-term viability hinges on cGMP certification acceleration and biocatalysis convergence for chiral intermediate production. Watch for CDSCO inspection protocol harmonization with FDA timelines as the inflection signal for Indian pharmaceutical-grade capacity valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Jiangsu Province | Chinese chemical producers commission dedicated alkoxide lines serving domestic pharmaceutical intermediate demand. |
| Backward Integration into Anhydrous Ethanol | Membrane-based dehydration reduces energy intensity and compresses capital requirements for new entrants. |
| Long-term Supply Agreement | Brazilian herbicide formulators lock three-year contracts with fixed-volume escalators for seasonal synchronization. |
| Joint Venture for cGMP Certification | CDSCO-FDA harmonization accelerates 18-24 month stability documentation cycles for catalyst qualification. |
| Green Manufacturing Transition | Membrane-processed feedstocks displace traditional azeotropic distillation in German and Swiss pharmaceutical synthesis. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant managers at Jiangsu and Gujarat chemical facilities, procurement leads at downstream pharmaceutical and agrochemical OEMs, distribution channel partners specializing in nitrogen-blanketed logistics, and technical R&D directors at alkoxide technology licensors; combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of diversified chemical majors, and SAMR GB standard documentation. Bottom-up capacity assessments and top-down demand triangulation anchored volume estimates.
Forecast inputs considered formulation type segmentation across liquid, solid, solution, and powder grades; application tiering across pharmaceutical, agrochemical, dye, and biochemical end-uses; and regional production hub clustering across Jiangsu Province, Gujarat State, and Frankfurt-Rhine-Main corridors. CAGRs were derived from installed capacity run-rates and downstream procurement intensity modeling, with metallic sodium price volatility and anhydrous ethanol supply concentration incorporated as sensitivity parameters across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Shandong chemical manufacturers or accelerated PLI scheme disbursements in Maharashtra and Telangana would shift outcomes. Material shifts in ECHA REACH dossier requirements for alkoxide catalysts or EPA TSCA notification thresholds for modified formulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
3-Iodoaniline Market
Chemicals
Trifluoroacetic Acid (TFA) Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
Leather Tanning Chemicals Market
Chemicals
Morpholine Market
Chemicals
Europe Methanol Market
Chemicals
Aluminium Chloride Market
Chemicals
Sodium Tripolyphosphate (STPP) Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Waterborne Curing Agents Market
Chemicals
Carbon Tetrachloride Market
Chemicals
Europe Biguanide Market
Chemicals
South America Construction Chemicals Market
Chemicals
Tanning Agents Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Polyphosphoric Acid (PPA) Market