
 Ammonium Bicarbonate Market | 2026-2036
Ammonium Bicarbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Bicarbonate Market Analysis
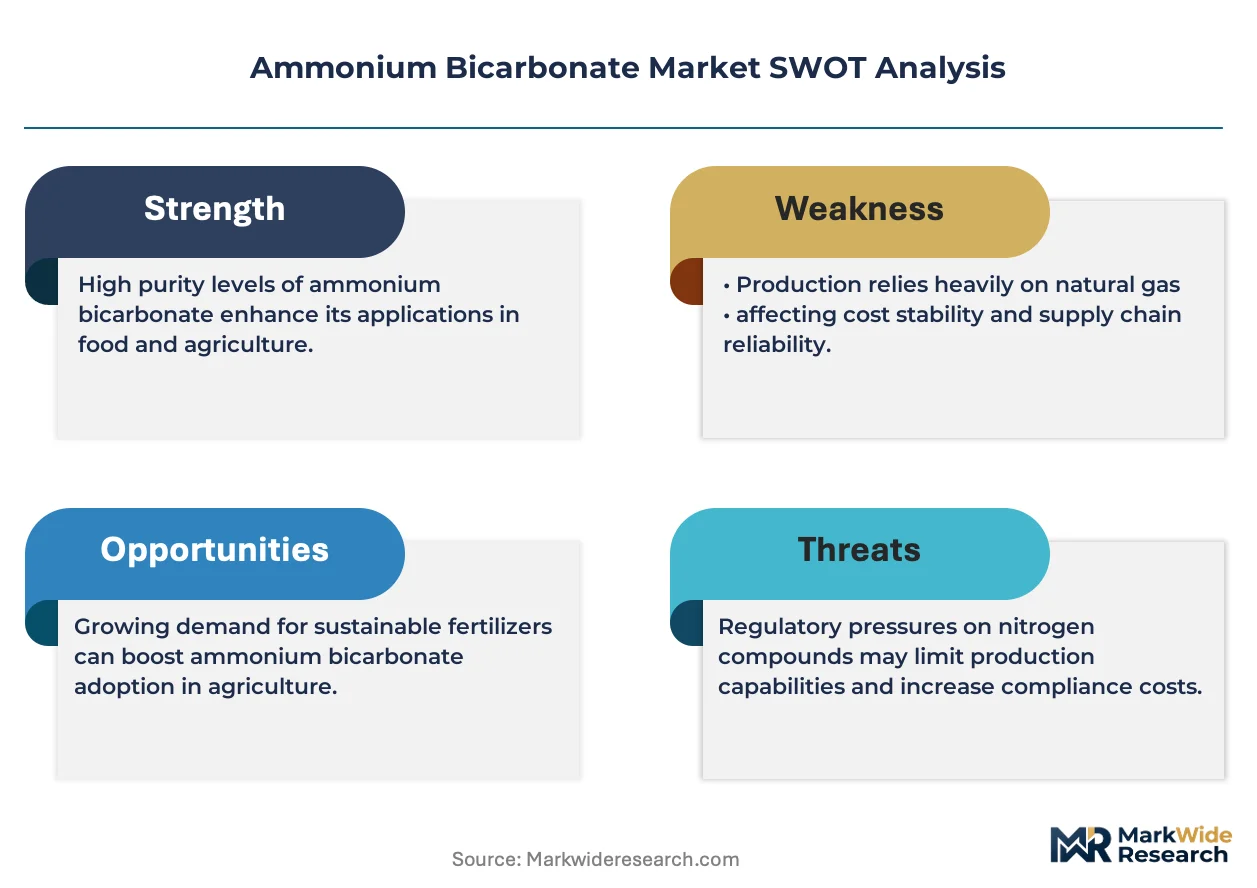
A capital-intensity divergence between integrated ammonia producers and standalone chemical processors is bifurcating competitive returns in the ammonium bicarbonate landscape. BASF SE leverages its Ludwigshafen ammonia backbone to sustain captive feedstock economics across European operations. Shijiazhuang Huiquan Chemical Group Co., Ltd. anchors its position through vertical integration into coal-gasification ammonia in Hebei province, while Church & Dwight Co., Inc. differentiates via pharmaceutical-grade purity standards for North American leavening applications.
Ammonium bicarbonate is a white crystalline salt with the chemical formula NH₄HCO₃, manufactured through the reaction of ammonia with carbon dioxide under controlled pressure and temperature conditions, typically yielding a product with 99% minimum purity and decomposition at 36–60°C to release ammonia, carbon dioxide, and water vapor. Its primary commercial purpose centers on serving as a nitrogen fertilizer and a chemical leavening agent that leaves no residual salt, making it preferable for thin, crisp baked goods in industrial food production. Food grade dominates value capture due to stringent purity certifications and premium pricing in packaged bakery chains, while industrial grade occupies the volume base through fertilizer blending and chemical synthesis feedstock. Pharmaceutical grade represents the fastest-growing margin pool, driven by excipient demand in effervescent tablet formulations across regulated health markets.
REACH registration requirements in Europe, FDA food additive regulations under 21 CFR 184.1135 in the United States, and China's GB 1888-2014 food-grade standard collectively elevate compliance costs and filter subscale producers from premium segments. The EU F-Gas Regulation indirectly shapes demand by restricting synthetic refrigerants, redirecting interest toward ammonia-based cooling systems where ammonium bicarbonate serves as a precursor chemical. Stakeholders must monitor tightening nitrogen emission caps in agricultural policy and evolving pharmaceutical excipient monographs to anticipate which purity grades will command sustainable margin premiums.
Market Dynamics
Feedstock ammonia supply concentration in coal-gasification corridors of Hebei and Shanxi provinces is compressing regional cost curves and forcing European carbamate producers into specialty-grade arbitrage. This upstream consolidation ripples through fertilizer blending, food leavening, and pharmaceutical excipient channels simultaneously.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on hydrofluorocarbon refrigerants redirect industrial cooling investment toward ammonia-based systems, elevating ammonium bicarbonate precursor demand in chemical synthesis chains across Germany and France.
- Commercial bakery consolidation:Packaged bread and cracker manufacturers in the United States prefer residue-free leavening for thin, crisp product specifications, sustaining food-grade volume through industrial channel contracts.
- Effervescent tablet expansion:Pharmaceutical formulators in regulated health markets specify pharmaceutical-grade purity for antacid and vitamin delivery systems, opening margin pools beyond commodity fertilizer applications.
Market Restraints
- Anhydrous ammonia price volatility:Natural gas and coal input swings transmit directly to ammonium bicarbonate production economics, eroding margin visibility for non-integrated processors lacking captive synthesis capacity.
- Hebei supply concentration:Overreliance on coal-gasification clusters in a single Chinese province exposes downstream buyers to logistics bottlenecks and environmental enforcement disruptions.
- Sodium bicarbonate substitution:Lower-cost alkaline leavening agents capture price-sensitive bakery segments where residual salt content is operationally tolerable, compressing standard-grade ammonium bicarbonate pricing power.
Strategic Opportunities
- India fertilizer subsidy reform:Nutrient-based subsidy schemes redirect nitrogenous fertilizer procurement toward efficiency-optimized blends, creating specification-grade entry points for imported ammonium bicarbonate with certified purity metrics.
- Continuous crystallization technology:Adoption of controlled cooling crystallizers by mid-scale processors enables pharmaceutical-grade output without batch-reactor capital intensity, narrowing purity gaps against established excipient suppliers.
- South Korean cosmetic effervescence:K-beauty sheet mask and bath tablet manufacturers specify food-grade ammonium bicarbonate for controlled gas-release formulations, opening personal care channels beyond traditional end-uses.
Industry Challenges
- REACH registration timelines:European Chemicals Agency substance dossier preparation consumes 18-24 months for new market entrants, delaying commercial access while incumbent registrants defend position through data-sharing consortia.
- Legacy packaging line compatibility:Ammonium bicarbonate's decomposition at 36-60°C demands humidity-controlled handling infrastructure that aging bakery and fertilizer blending facilities lack, forcing capital-intensive retrofit decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Bicarbonate Market |
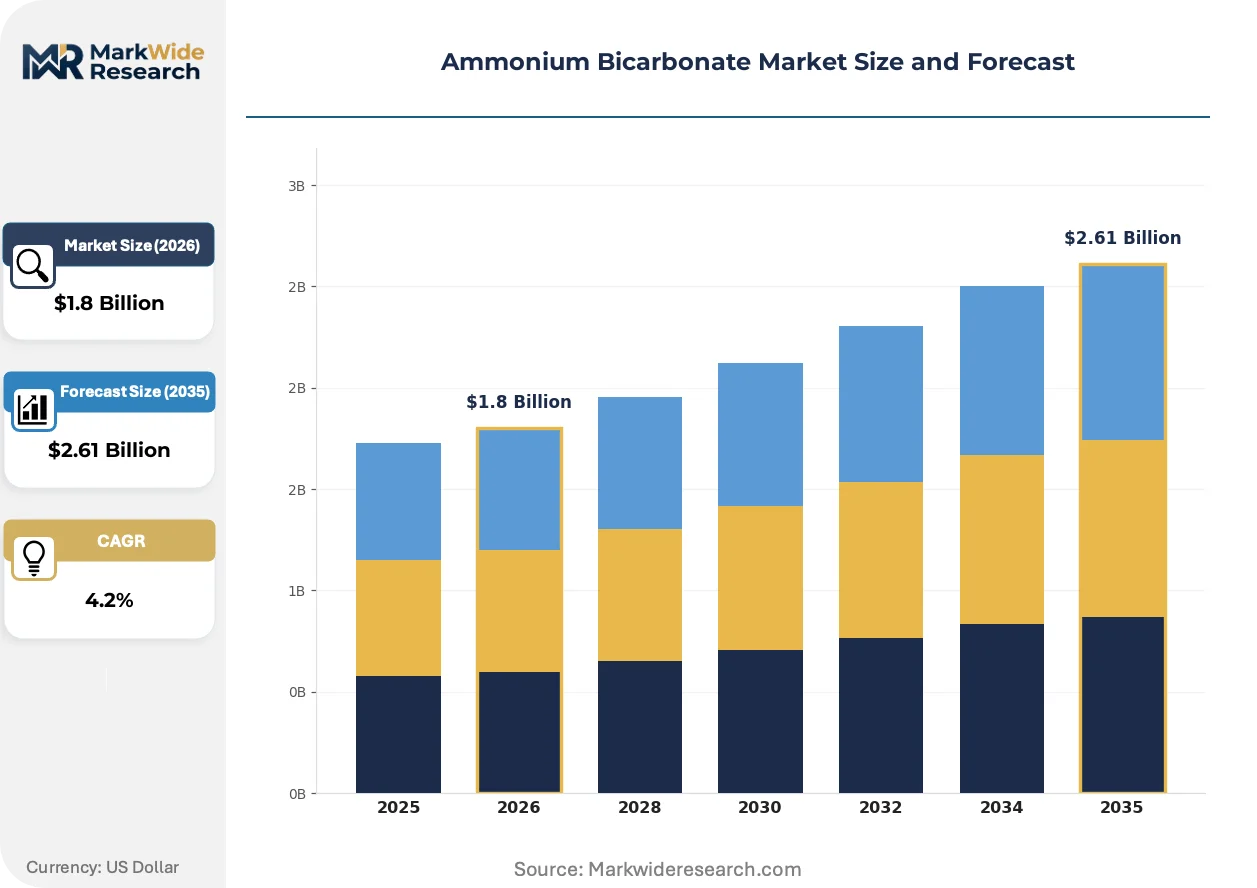
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Technological Grade Application: Baking, Fertilizers, Chemical Manufacturing, Refrigeration Packaging Type: Bags, Drums, Bulk, Containers Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Esseco UK, Shijiazhuang Huiquan Chemical Group Co., Ltd., BASF SE, Nissan Chemical Corporation, Church & Dwight Co., Inc., UBE Corporation, Shandong ShunTian Chemical Group, BINSA, Huaqiang Chemical Group Stock Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Bicarbonate Market Emerging Trajectories
Process intensification and regulatory chemistry are reshaping how ammonium bicarbonate is synthesized, certified, and consumed across industrial verticals. Three converging developments are altering competitive positioning.
Membrane-based carbon capture integration is displacing conventional amine scrubbing in ammonia plant tailgas treatment. BASF Ludwigshafen and Chinese coal-chemical complexes deploy hollow-fiber membrane systems to recover CO₂ for carbamate synthesis, compressing unit carbon costs and enabling Scope 1 emission claims for downstream food-grade buyers. This retrofit wave accelerates where EU carbon border adjustment mechanisms bite hardest.
REACH authorization requirements for Substances of Very High Concern are tightening impurity thresholds in ammonium bicarbonate destined for pharmaceutical excipient use. ECHA's 2024 updated guidance on residual heavy metals and aromatic amines forces reformulation of technical-grade stocks previously acceptable for fertilizer blending, bifurcating production campaigns and lengthening quality-assurance protocols for European suppliers.
Direct-to-mill procurement contracts are consolidating buyer power among North American industrial bakery chains. Large packaged goods manufacturers bypass regional distributors to negotiate annual tonnage agreements with Shijiazhuang and European producers, compressing intermediary margins and demanding lot-level traceability documentation that smaller compounders cannot provision. This channel shift concentrates volume with logistics-capable suppliers in China and Germany.
Ammonium Bicarbonate Market Segmentation
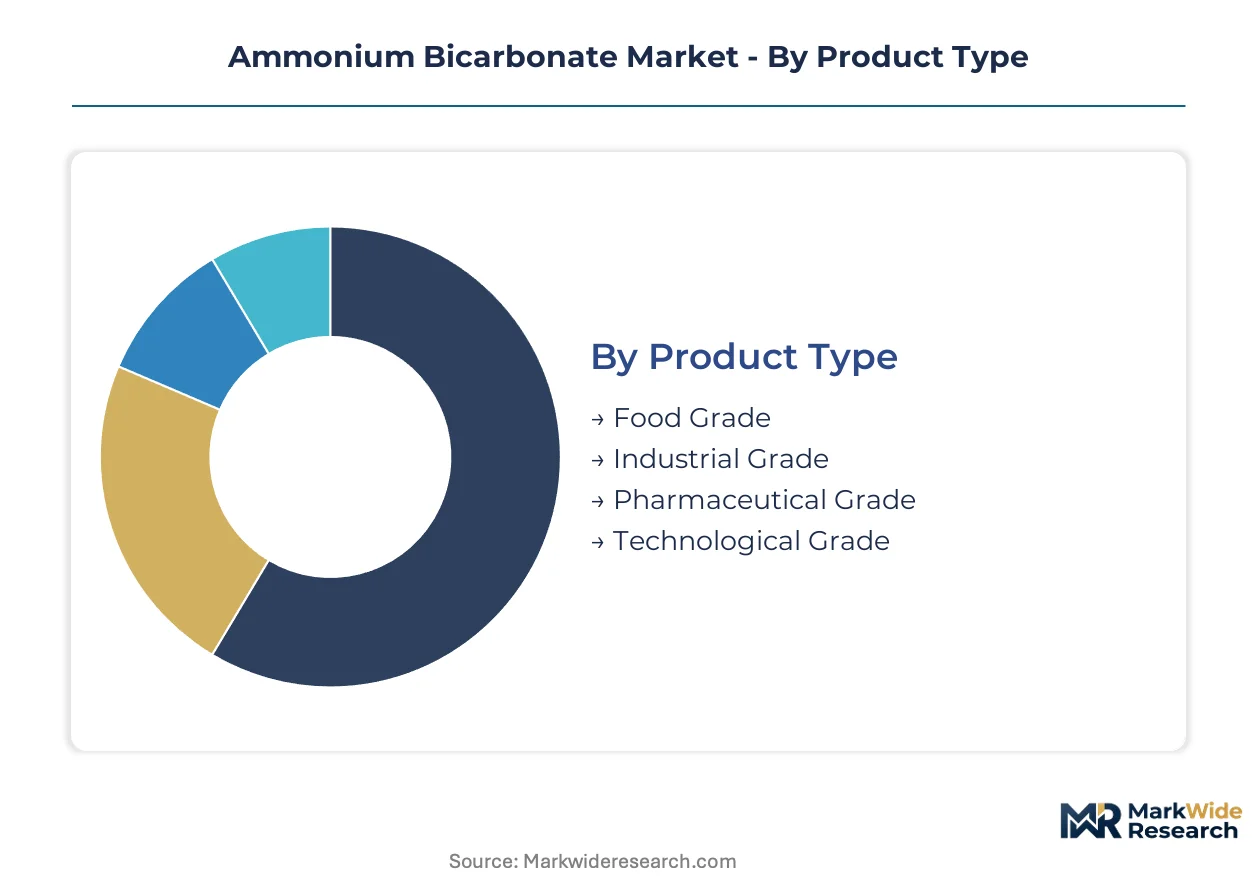
Segmentation in ammonium bicarbonate reveals how purity specifications and handling requirements fragment commercial pathways. Food-grade certifications command premium pricing through bakery chain procurement, while industrial-grade volume flows through fertilizer blending networks with minimal margin protection.
Product Type:
Sodium bicarbonate substitution pressure intensifies across lower-purity tiers, forcing ammonium bicarbonate producers to defend position through residue-free performance claims and pharmaceutical-grade certification barriers.
- Food Grade:Minimum 99% purity with heavy metal limits specified under FDA 21 CFR 184.1135 and China's GB 1888-2014. Commercial bakery chains in the United States specify this grade for thin cracker and biscuit production where residual salt would compromise texture. Decomposition at 36–60°C releases only ammonia, carbon dioxide, and water vapor, leaving no sodium residue.
- Industrial Grade:Standard nitrogen content for fertilizer blending applications, typically 17% nitrogen by weight. Hebei province coal-gasification corridors supply this tier through bulk rail and riverine logistics to domestic Chinese agriculture and Southeast Asian import markets. Price volatility in anhydrous ammonia feedstock compresses margins for non-integrated processors.
- Pharmaceutical Grade:Excipient purity for effervescent tablet formulations with certified impurity profiles meeting USP-NF and EP monographs.
- Technological Grade:Specialized specifications for chemical synthesis and laboratory applications requiring controlled particle size distribution.
Industrial Grade retains volume leadership; Pharmaceutical Grade holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity fertilizer consumption from premium food and pharmaceutical channels, with refrigeration applications occupying an intermediate position shaped by regulatory transition.
- Baking:Chemical leavening for industrial cracker, biscuit, and flatbread production. Packaged goods manufacturers in North America and Western Europe specify ammonium bicarbonate where product thickness below 3mm would concentrate sodium bicarbonate residues. Direct-to-mill procurement contracts now bypass regional distributors.
- Fertilizers:Nitrogen source for alkaline soils where rapid ammonia volatilization is acceptable. Indian nutrient-based subsidy schemes redirect procurement toward efficiency-optimized blends, creating specification-grade entry points for certified imports.
- Chemical Manufacturing:Precursor for dyes, pharmaceuticals, and ceramic processing with purity requirements varying by synthesis pathway.
- Refrigeration:Ammonia-based cooling system chemistry indirectly supported by EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants.
Fertilizers dominate tonnage throughput; Baking commands the highest per-kilogram realized pricing.
Packaging Type:
Customer type and handling infrastructure requirements segment packaging choices, with humidity sensitivity driving specification divergence between integrated processors and distributed compounders.
- Bags:Multi-layer laminated construction with moisture barriers for food-grade distribution through bakery ingredient suppliers. Standard 25kg units suit mid-scale compounders lacking bulk handling systems.
- Drums:Steel or fiber construction for pharmaceutical-grade shipments requiring lot-level traceability documentation and sealed containment during extended storage.
- Bulk:Pneumatic discharge railcars and hopper trucks for industrial-grade fertilizer blending operations with dedicated handling infrastructure.
- Containers:ISO tank and flexitank configurations for intermodal export shipments from Chinese production clusters to Southeast Asian and European ports.
Bulk captures the greatest tonnage; Drums sustain the most substantial packaging cost premium.
Distribution Channel:
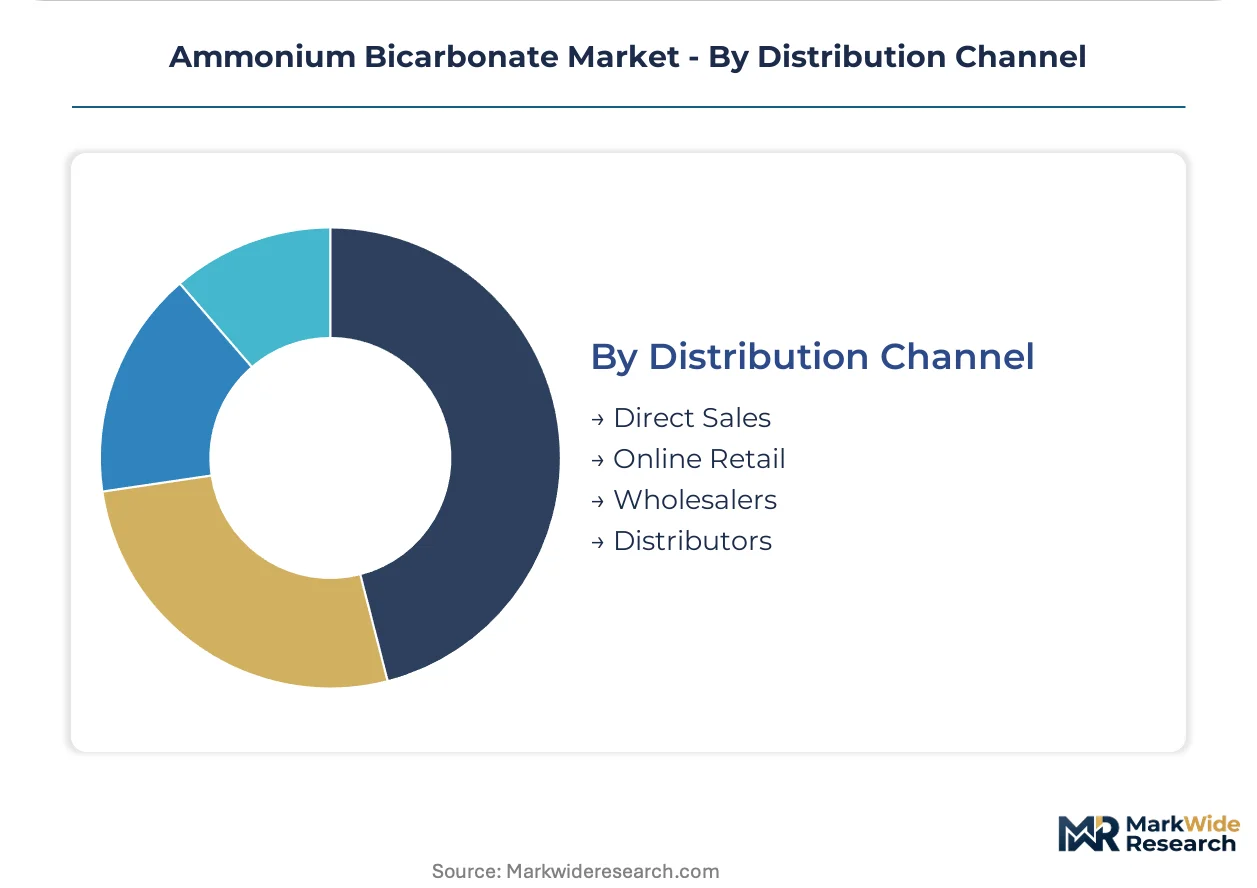
Supply concentration in Hebei and Shanxi provinces shapes channel power, with logistics-capable producers consolidating volume through direct relationships while regional distributors face margin compression.
- Direct Sales:Annual tonnage agreements between Chinese producers and North American industrial bakery chains, European fertilizer blenders, and Indian chemical traders. Lot-level traceability documentation and certified purity metrics are mandatory.
- Online Retail:Emergent channel for laboratory-scale quantities and specialty food ingredient suppliers serving artisan bakeries and research institutions.
- Wholesalers:Regional inventory aggregation for fertilizer cooperatives and mid-scale food processors lacking direct import capabilities.
- Distributors:Traditional channel for fragmented end-users with irregular demand patterns and limited storage infrastructure.
Direct Sales is expanding most quickly; Distributors face structural compression from procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian fertilizer procurement demonstrates the highest price elasticity, with buyers switching rapidly between nitrogen sources based on subsidy adjustments, while North American commercial bakeries exhibit inelastic demand for certified food-grade material where residue-free performance commands fixed specification premiums.
China
Hebei and Shanxi provinces concentrate coal-gasification ammonia production that feeds captive ammonium bicarbonate synthesis. GB 1888-2014 food-grade standards and tightening MEE environmental enforcement on nitrogen emissions reshape product specifications. Shijiazhuang chemical clusters face logistics bottlenecks during winter heating-season pollution controls.
United States
Industrial bakery chains drive food-grade consumption for thin cracker and flatbread production where sodium residue compromises texture. FDA 21 CFR 184.1135 additive regulations mandate heavy metal limits and purity documentation. Direct-to-mill procurement contracts now bypass regional distributors, consolidating volume with logistics-capable suppliers.
Germany
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants redirect industrial cooling investment toward ammonia-based systems. REACH registration requirements and ECHA authorization timelines for Substances of Very High Concern elevate compliance costs. BASF Ludwigshafen leverages integrated ammonia backbone to sustain captive feedstock economics across European operations.
India
Nutrient-based subsidy schemes redirect nitrogenous fertilizer procurement toward efficiency-optimized blends. FSSAI food safety standards and BIS certification requirements create specification-grade entry points for imported material with certified purity metrics. Gujarat and Maharashtra chemical traders increasingly source directly from Chinese producers.
Japan
Pharmaceutical excipient demand for effervescent tablet formulations drives pharmaceutical-grade imports. PMDA and METI regulations enforce USP-NF and EP monograph compliance for drug manufacturing inputs. Osaka and Tokyo formulation clusters specify certified impurity profiles that filter subscale suppliers from premium segments.
Ammonium Bicarbonate Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in ammonium bicarbonate manufacturing. Captive ammonia synthesis distinguishes the upper tier, where backward integration into coal-gasification or natural gas reforming secures feedstock cost visibility. The specialist tier competes through purity certification, regional logistics, and application-specific formulation. Dominant competitive moves include direct procurement contract consolidation with North American bakery chains and continuous crystallization technology licensing for pharmaceutical-grade output.
Among European-integrated chemical conglomerates, BASF SE anchors the ammonia-backbone archetype. Chinese coal-chemical processors exemplify the vertical-integration model, with Shijiazhuang Huiquan Chemical Group Co., Ltd. representing Hebei-based production concentration. North American specialty chemical houses occupy the purity-differentiation tier, where Church & Dwight Co., Inc. sits within pharmaceutical-grade and food-grade certification frameworks.
| Leading Market Players |
|---|
| Esseco UK |
| Shijiazhuang Huiquan Chemical Group Co., Ltd. |
| BASF SE |
| Nissan Chemical Corporation |
| Church & Dwight Co., Inc. |
| UBE Corporation |
| Shandong ShunTian Chemical Group |
| BINSA |
| Huaqiang Chemical Group Stock Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Hebei-based coal-gasification producers and North American industrial bakery chains lock in both supply access and price visibility across food-grade ammonium bicarbonate tiers. These agreements insulate integrated processors from anhydrous ammonia volatility while forcing non-captive competitors into spot-market exposure.
Pricing Analysis
After-sales technical service contracts for pharmaceutical-grade certification and lot-level traceability documentation drive lifetime value capture beyond base chemical margins. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates premium excipient purity from standard leavening performance. Cost compression in industrial-grade fertilizer blending is intensifying because sodium bicarbonate substitution captures price-sensitive agricultural buyers. Indian nutrient-based subsidy procurement demonstrates highest price elasticity, while North American commercial bakeries exhibit inelastic demand for certified food-grade material.
Supply Chain Analysis
China and Germany anchor ammonium bicarbonate production through divergent feedstock pathways—coal-gasification corridors in Hebei province versus natural gas-reforming integration at Ludwigshafen. Manufacturing draws from anhydrous ammonia, carbon dioxide recovery systems, and crystallization infrastructure. Single-source vulnerability concentrates in Hebei winter heating-season pollution controls that trigger forced production curtailments. Distribution runs through direct-to-mill procurement contracts bypassing regional distributors, with ISO tank and flexitank configurations handling intermodal export volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as REACH authorization timelines and pharmaceutical-grade certification requirements create defended niches that subscale competitors cannot penetrate. Specialty-grade specification divergence rewards focused players over commodity generalists.
For Market Incumbents: Consolidate procurement relationships with North American packaged goods manufacturers through multi-year tonnage agreements embedding lot-level traceability. Deepen upstream control over coal-gasification ammonia in Hebei to secure feedstock cost visibility against European natural gas volatility. Invest in continuous crystallization technology licensing to defend pharmaceutical-grade margin pools from mid-scale entrants.
For New Entrants and Emerging Players: Contract analytical services for REACH dossier preparation and USP-NF monograph compliance represent a service-layer gap where incumbents under-serve mid-scale processors lacking in-house regulatory capacity. Target South Korean cosmetic effervescence manufacturers seeking food-grade ammonium bicarbonate for K-beauty sheet mask formulations. Pursue direct technical partnership with Indian chemical traders in Gujarat bypassing established distribution hierarchies.
For Investors and Strategic Acquirers: Regional distributors with captive cold-chain logistics and pharmaceutical-grade warehousing certifications represent acquisition targets positioned for margin recovery as channel consolidation reverses. Long-term viability hinges on regulatory chemistry capabilities rather than commodity scale—watch for ECHA guidance updates on residual heavy metal thresholds as inflection indicator for which purity tiers command sustainable premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Synthesis | Captive coal-gasification capacity in Hebei insulates Shijiazhuang producers from feedstock volatility that erodes European carbamate margins. |
| Continuous Crystallization Technology Licensing | Controlled cooling systems enable mid-scale processors to produce pharmaceutical-grade output without batch-reactor capital intensity. |
| Direct-to-Mill Procurement Consolidation | Annual tonnage agreements between Chinese producers and North American bakery chains compress intermediary distributor margins. |
| REACH Dossier Data-Sharing Consortium Defense | Incumbent registrants leverage 18-24 month ECHA preparation timelines to delay new entrant commercial access. |
| Membrane-Based Carbon Capture Integration | Hollow-fiber systems at BASF Ludwigshafen recover CO₂ for carbamate synthesis while enabling Scope 1 emission claims. |
Methodological Framework
Cross-validation between primary interviews with plant managers at coal-gasification facilities and secondary validation through customs trade data, ACC and Cefic industry reports, and SEC 10-K filings anchors the qualitative findings. Technical R&D directors at pharmaceutical excipient formulators, procurement leads at North American industrial bakery chains, distribution channel partners in Indian chemical trading hubs, and regulatory affairs specialists navigating ECHA authorization timelines provided ground-level operational perspective. Bottom-up capacity assessments triangulate against top-down demand modeling across grade tier, end-use industry, packaging format, and regional production hub segmentation.
Sensitivity analysis frameworks stress-test volume and value outputs across the projection horizon against anhydrous ammonia price volatility scenarios and regulatory enforcement intensity variations. Segmentation dimensions modeled include pharmaceutical, food, industrial, and technological grades; baking, fertilizer, chemical manufacturing, and refrigeration applications; bags, drums, bulk, and container packaging formats; plus direct sales, online retail, wholesaler, and distributor channels. CAGRs derive from historical trajectory analysis adjusted for policy intervention effects and substitution elasticity parameters specific to sodium bicarbonate competitive dynamics.
Forecasts assume regulatory continuity in EU REACH authorization regimes and FDA food additive enforcement; material policy shifts would require re-modeling. Specific risk factors include Hebei environmental enforcement disruptions, Indian fertilizer subsidy scheme revisions, and ECHA impurity threshold updates. Recalibration cycles align with material shifts in nitrogen emission caps, pharmaceutical excipient monograph revisions, and F-Gas Regulation implementation phases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Glacial Methacrylic Acid Market
Bulk Chemicals
Global Ammonium Chloride Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
Bio Based Paraxylene Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
Clomiphene Citrate Market
Bulk Chemicals
Acrylamide Market
Bulk Chemicals
Formate Brine Market
Bulk Chemicals
Pyridine Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
Isovaleryl Chloride Market