
 Putty Powder Market | 2026-2036
Putty Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Putty Powder Market Intelligence
Aftermarket surface refinishing revenue is reshaping margin capture across the putty powder value chain. Sika AG leverages its waterproofing chemistry heritage to dominate exterior-grade formulations in European infrastructure repair. Asian Paints anchors India's decorative coatings ecosystem with captive putty production tied to its distribution network. Saint-Gobain competes through gypsum verticality, controlling raw material feedstock for interior wall finishing systems.
Putty powder comprises finely ground mineral fillers—typically gypsum, calcium carbonate, or dolomite—blended with polymer binders and additives to create a trowel-applied paste that smooths substrates before painting or wallpapering; standard interior grades achieve surface hardness of 3-4 MPa after 28 days of curing. Interior putty occupies the largest volume pool given universal new-build and renovation demand across residential and commercial verticals. Waterproof putty represents the fastest-expanding segment, driven by monsoon-prone geographies and rising basement-grade construction specifications. Acrylic material formulations command premium positioning due to superior elasticity and crack-bridging performance over gypsum alternatives.
China's SAMR enforces GB 18582 limits on volatile organic compounds in interior wall coatings, directly constraining binder chemistry choices for putty formulations sold in the Chinese market. India's BIS certification mandates IS 1542 compliance for gypsum building materials, creating a quality gate that filters informal manufacturers from organized supply channels. ECHA's REACH framework governs acrylic and silicone resin imports into Europe, adding registration cost burdens that favor established suppliers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving low-carbon building codes and binder substitution pathways as cement and gypsum face embodied-carbon scrutiny across major construction markets.
Market Dynamics
China's GB 18582 VOC limits and India's BIS IS 1542 certification are compressing informal supply channels while accelerating reformulation toward low-emission acrylic binders across Asia-Pacific construction markets.
Growth Catalysts
- GB 18582 Indoor Air Quality Mandates:China's SAMR enforcement of volatile organic compound limits is forcing gypsum putty manufacturers to adopt water-based acrylic binder systems, creating premium product tiers.
- Monsoon-Resistant Construction Specifications:Waterproof putty demand concentrates in Mumbai, Chennai, and Bangladesh's coastal zones where basement-grade waterproofing has become mandatory for urban high-rises.
- Southeast Asian Residential Construction:Vietnam's Ho Chi Minh City corridor and Indonesia's Greater Jakarta region are driving gypsum-based interior formulation consumption through mass housing programs.
Market Restraints
- Raw Material Concentration Risk:High-purity gypsum feedstock availability clusters in Rajasthan and Thailand's Nakhon Ratchasima province, exposing processors to logistics bottlenecks.
- Acrylic Resin Cost Volatility:Petrochemical-derived binder inputs fluctuate with naphtha cracking margins, compressing formulation economics for mid-tier producers.
- Cement-Based Substitution Threat:Skim-coat cementitious overlays are capturing exterior wall preparation share in Middle Eastern and African markets where gypsum durability fails.
Strategic Opportunities
- India's Tier-2 Urban Housing:Lucknow, Indore, and Kochi corridors remain underpenetrated by organized putty brands, offering volume expansion outside saturated Mumbai-Delhi-NCR markets.
- ECHA REACH Registration Tailwinds:European acrylic and silicone resin import compliance burdens favor established suppliers with dedicated regulatory affairs capacity.
- Prefabricated Construction Integration:Factory-applied putty layers in modular wall panels are converging with off-site construction methods in Japan and South Korea.
Industry Challenges
- Application Skill Scarcity:Trowel-grade finish quality depends on trained masons, a workforce segment shrinking across India's construction labor pool.
- BIS Certification Timeline Compression:IS 1542 testing protocols extend 4-6 months, delaying market entry for reformulated low-VOC products.
- Supply Chain Reconfiguration Friction:Binder substitution from gypsum to acrylic requires revalidation of entire additive packages, disrupting established procurement patterns.
Report Scope
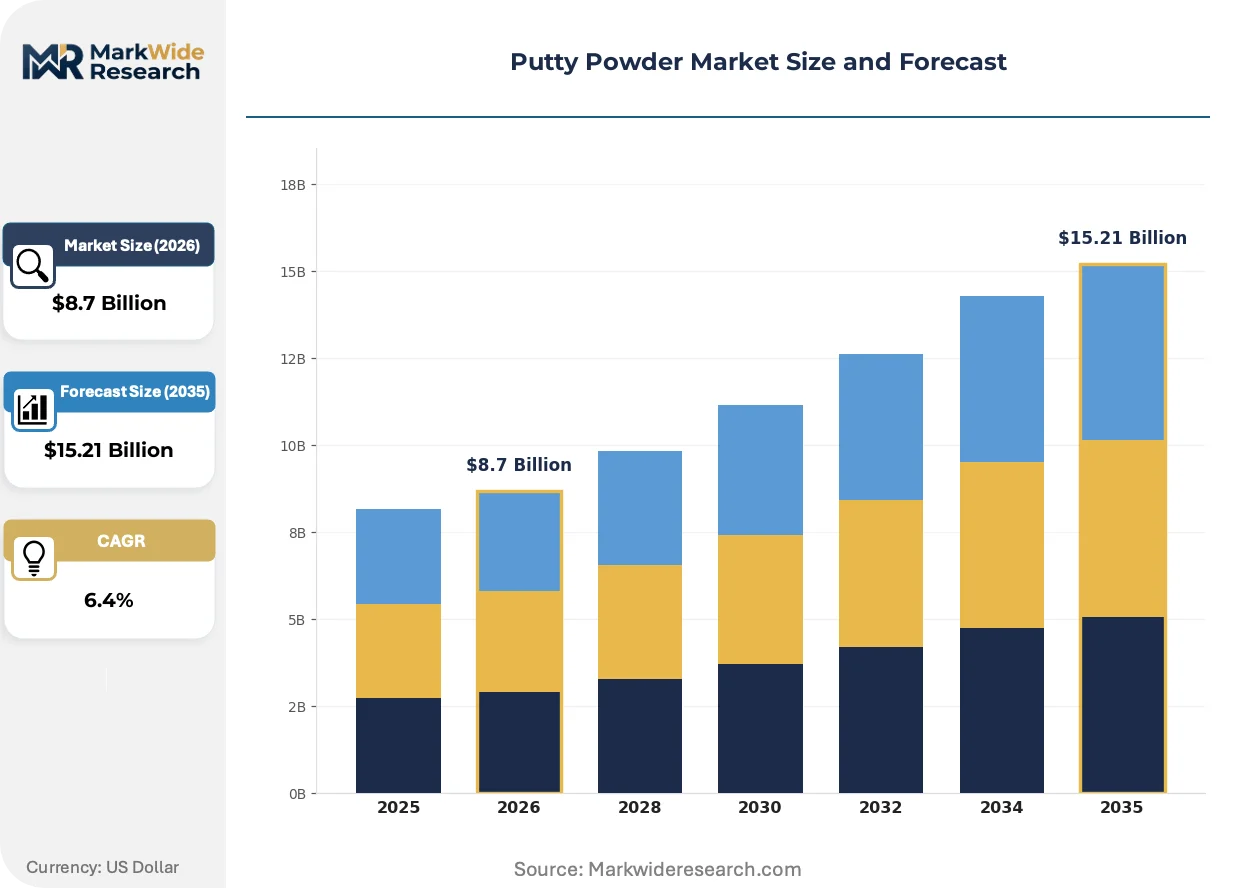
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Putty Powder Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Putty, Exterior Putty, Multi-purpose Putty, Waterproof Putty Application: Residential, Commercial, Industrial, DIY Material: Gypsum, Acrylic, Silicone, Latex Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, Asian Paints, Saint-Gobain, BASF SE, UltraTech Cement Limited, J.K. Cement Ltd, Nippon Paint Holdings Co., Ltd., Mapei SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Putty Powder Market Strategic Shifts & Innovations
Formulation chemistry, compliance architecture, and procurement modalities are undergoing simultaneous recalibration across the putty powder value chain. These shifts are compressing legacy product lifecycles while opening premium positioning for compliant suppliers.
Hybrid nano-silica modified acrylic binders are rendering obsolete conventional gypsum-lime formulations in high-humidity applications. Commercial developers in Singapore and Hong Kong are specifying these systems for podium-level and basement wall preparation. The technology is rendering obsolete traditional moisture-resistant grades that relied solely on hydrophobic additive packages.
REACH registration requirements for acrylic resin imports into Europe are fragmenting supplier bases. ECHA's substance evaluation protocols impose five-figure euro costs per chemical entity, filtering out trading houses and favoring manufacturers with in-house polymer synthesis. Western European infrastructure repair contractors are consolidating procurement around REACH-registered supply chains to avoid project delay risks.
Digital material procurement platforms are disintermediating traditional distributor networks in India's decorative coatings ecosystem. Asian Paints' dealer management systems and independent B2B marketplaces are enabling direct factory-to-contractor ordering for bulk putty volumes. This channel shift is most visible in Gujarat and Maharashtra where contractor concentration supports consolidated delivery logistics.
Putty Powder Market Segmentation
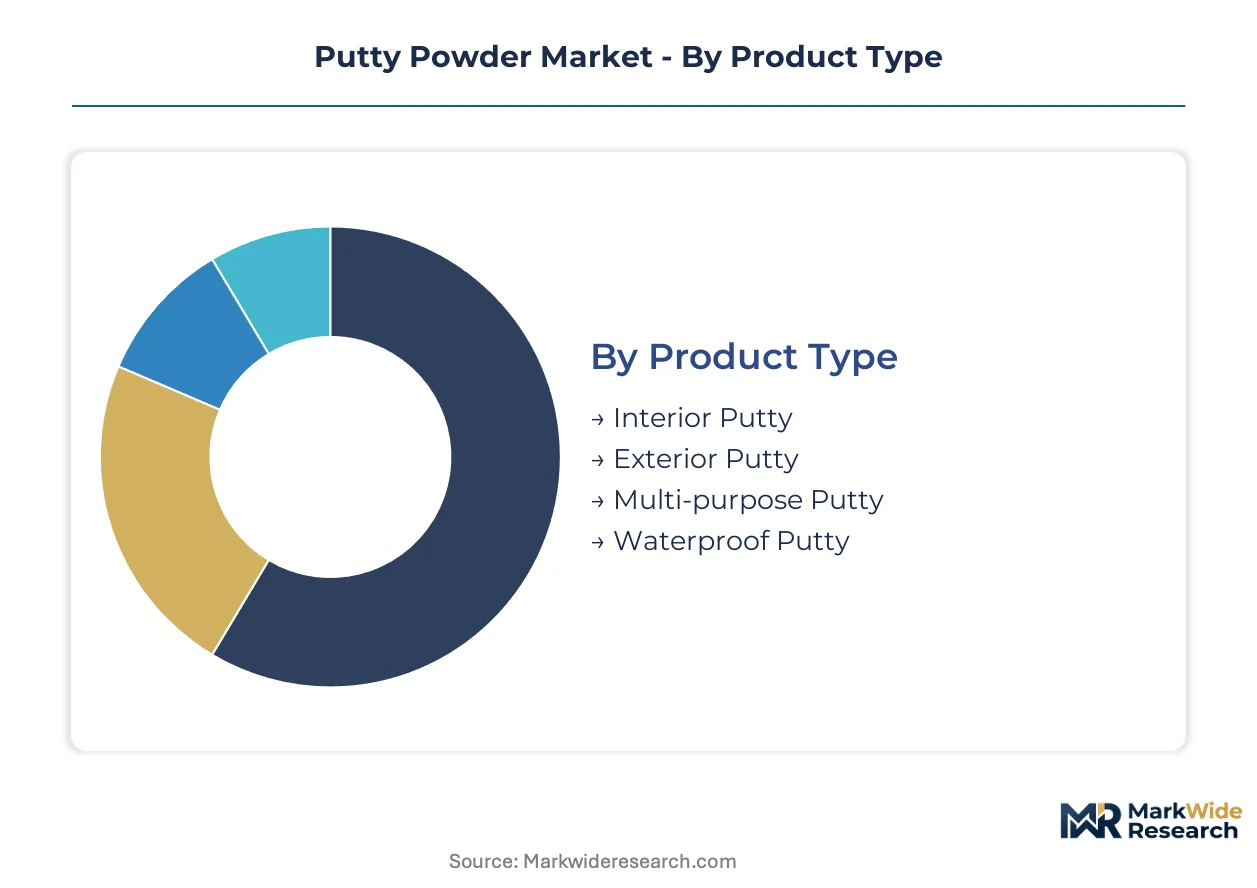
Putty powder segmentation reveals distinct performance requirements across surface preparation workflows. Product formulation, substrate exposure, and procurement modality each create separate competitive arenas with unique margin structures and compliance burdens.
Product Type:
Surface exposure conditions dictate binder chemistry selection and durability specifications across construction verticals.
- Interior Putty:Gypsum-based formulations with 3-4 MPa surface hardness after 28-day curing dominate new-build residential and commercial finishing. Demand concentrates in Vietnam's Ho Chi Minh City corridor and Indonesia's Greater Jakarta region through mass housing programs.
- Waterproof Putty:Hybrid nano-silica modified acrylic systems render obsolete traditional moisture-resistant grades in high-humidity applications. Singapore and Hong Kong commercial developers specify these for podium-level and basement wall preparation where hydrophobic additive packages alone prove insufficient.
- Exterior Putty:Cementitious and silicone-modified binders withstand thermal cycling and precipitation exposure on facade systems.
- Multi-purpose Putty:Intermediate formulations bridge interior and exterior performance tiers for mixed-use developments.
The dominant share belongs to Interior Putty, while Waterproof Putty is closing the gap fastest.
Application:
End-user sophistication and project scale separate specification-grade from commodity procurement patterns.
- Residential:Volume concentration in India's urban housing corridors around Mumbai and Delhi-NCR drives gypsum-based interior formulation consumption. Tier-2 cities including Lucknow, Indore, and Kochi remain underpenetrated by organized brands.
- Commercial:Waterproof specifications concentrate in Mumbai, Chennai, and Bangladesh's coastal zones where basement-grade treatment has become mandatory for urban high-rises.
- Industrial:Heavy-duty epoxy-modified systems serve manufacturing facility floor and wall preparation requirements.
- DIY:Pre-mixed, ready-to-use packaging formats target homeowner renovation segments in mature markets.
Residential applications command the largest volume pool, with Commercial specifications expanding most quickly on waterproofing mandates.
Material:
Raw material feedstock availability and regulatory pressure on volatile organic compound emissions are restructuring formulation economics.
- Gypsum:High-purity feedstock clusters in Rajasthan and Thailand's Nakhon Ratchasima province, exposing processors to logistics bottlenecks. India's BIS IS 1542 certification mandates quality compliance that filters informal manufacturers from organized supply channels.
- Acrylic:Water-based binder systems command premium positioning due to superior elasticity and crack-bridging performance. China's SAMR enforcement of GB 18582 VOC limits is forcing gypsum putty manufacturers to adopt these systems, creating premium product tiers.
- Silicone:Hydrophobic resin systems serve exterior-grade durability requirements in European infrastructure repair markets.
- Latex:Cost-competitive emulsion binders target mid-tier interior applications with moderate performance demands.
Acrylic formulations are gaining share fastest on regulatory tailwinds, though Gypsum retains volume leadership in cost-sensitive interior segments.
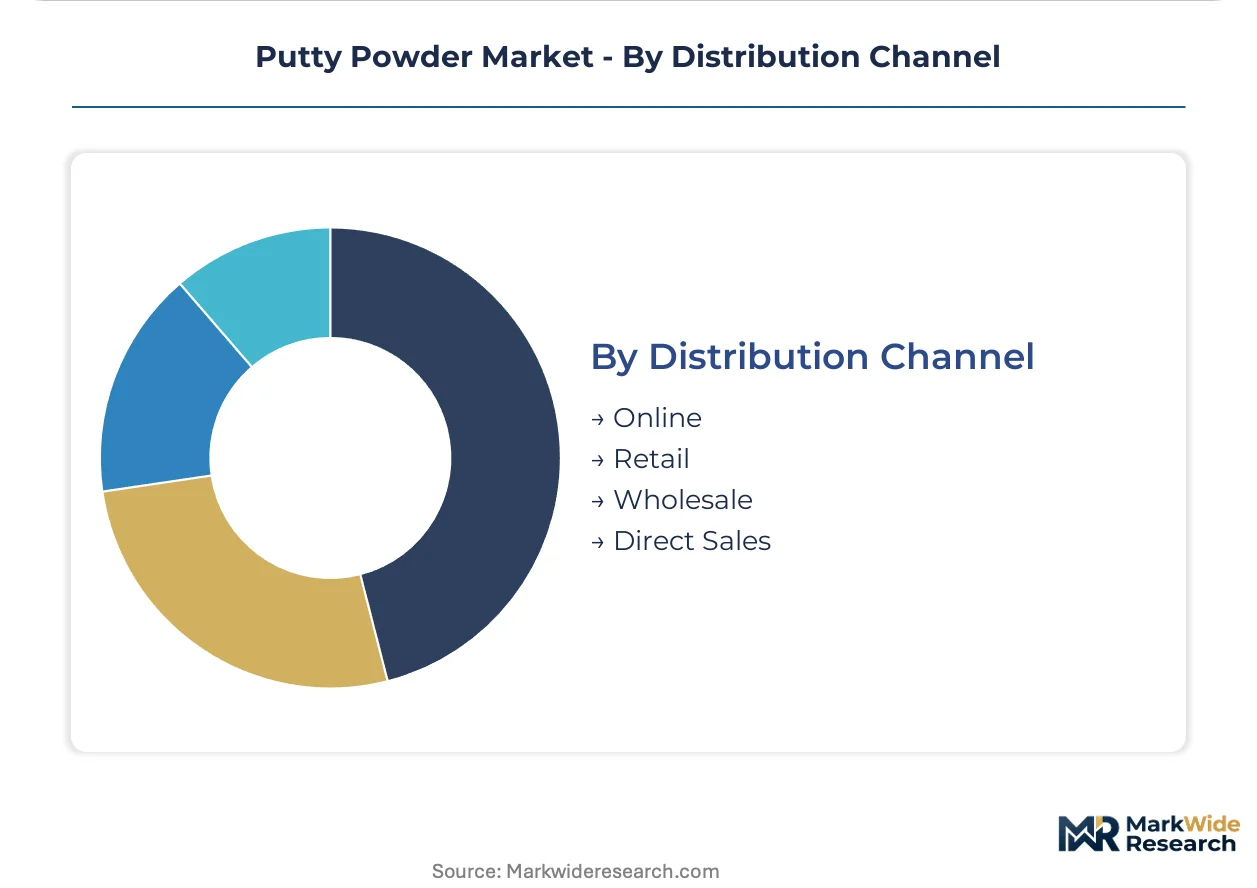
Distribution Channel:
Procurement modality fragmentation reflects contractor concentration patterns and digital platform penetration.
- Retail:Dealer management systems and physical storefront networks serve fragmented contractor bases in secondary markets.
- Wholesale:Bulk volume aggregation supports large-scale project procurement with consolidated logistics.
- Direct Sales:Factory-to-contractor ordering captures bulk putty volumes in Gujarat and Maharashtra where contractor concentration supports dedicated delivery.
- Online:Digital material procurement platforms are disintermediating traditional distributor networks in India's decorative coatings ecosystem.
Wholesale channels anchor volume throughput, while Online platforms are climbing the fastest on B2B marketplace expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across construction markets. India's cost-conscious residential buyers drive gypsum volume, while Singapore and Hong Kong developers absorb acrylic premiums for basement-grade specifications.
China
Urban housing stock renewal and commercial high-rise construction sustain putty consumption across the Yangtze River Delta. SAMR's GB 18582 VOC enforcement compels reformulation toward water-based acrylic systems. Shanghai and Hangzhou manufacturers are phasing out solvent-heavy legacy lines ahead of compliance deadlines.
India
Mass housing programs and interior finishing cycles in Mumbai and Delhi-NCR anchor gypsum-based demand. BIS IS 1542 certification requirements filter informal suppliers from organized channels. Lucknow and Indore corridors remain underpenetrated by branded distributors despite accelerating construction permits.
Vietnam
Ho Chi Minh City's residential tower pipeline and industrial park expansion drive interior wall preparation volumes. National technical standards for indoor air quality are tightening alongside green building certification adoption. Dong Nai and Binh Duong provinces concentrate manufacturing investment for construction materials.
Germany
Infrastructure repair specifications and facade renovation cycles sustain exterior-grade silicone-modified demand. ECHA REACH registration burdens filter acrylic resin imports to established suppliers with dedicated compliance capacity. The Rhine-Ruhr corridor anchors waterproofing formulation production for Central European distribution.
United Arab Emirates
Mega-project construction and hospitality sector refurbishment sustain premium interior finishing specifications. Dubai's building codes mandate moisture-resistant grades for basement and podium applications. Jebel Ali industrial zone hosts blending operations serving Gulf Cooperation Council export markets.
Putty Powder Market Key Industry Players
Capability concentration sits with specialty chemical formulators; scale advantage sits with integrated building materials conglomerates. The market structures around three tiers: multinational coating-chemical hybrids with polymer synthesis depth, regional cement-gypsum verticals with captive mineral feedstock, and national paint distributors with putty-as-captive-product strategies. Consolidation pressure runs through REACH compliance cost burdens and BIS certification timelines. Backward integration into high-purity gypsum mining and acrylic resin synthesis represents the dominant competitive vector.
Among European chemical specialists, Sika AG and BASF SE exemplify polymer-centric positioning, while Saint-Gobain anchors the mineral-vertical archetype through gypsum feedstock control. Asian Paints occupies the distribution-captive tier within India's decorative coatings ecosystem. These three archetypes—chemical synthesis, mineral verticality, and channel integration—define the competitive geometry across formulation, procurement, and specification influence.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| Asian Paints |
| Saint-Gobain |
| BASF SE |
| UltraTech Cement Limited |
| J.K. Cement Ltd |
| Nippon Paint Holdings Co., Ltd. |
| Mapei SpA |
| Others |
Cost & Logistics Intelligence
Overcapacity in Rajasthan's high-purity gypsum processing corridor is compressing feedstock premiums while forcing processors toward long-term offtake contracts to lock in utilization rates. This utilization-driven contracting posture shapes both supplier consolidation incentives and buyer negotiation leverage across Asian interior finishing markets.
Pricing Analysis
Long-term offtake agreements dominate bulk procurement between Rajasthan gypsum processors and Indian organized manufacturers, insulating against naphtha-cracking volatility in acrylic binder inputs. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered European acrylic imports from domestic water-based systems and unbranded gypsum-lime blends. Pricing pressure stems from cementitious skim-coat substitution in Middle Eastern exterior applications. Residential contractors in India's Tier-2 corridors exhibit highest price sensitivity, while Singapore commercial developers absorb nano-silica acrylic premiums for basement-grade specifications.
Supply Chain Analysis
Contract manufacturing concentration sits with Saint-Gobain's captive gypsum verticals in Rajasthan and Thailand's Nakhon Ratchasima province, plus Sika AG's polymer synthesis facilities in the Rhine-Ruhr corridor. Formulation economics draw from high-purity gypsum feedstock, petrochemical-derived acrylic resins, and nano-silica additive packages. Single-source vulnerability clusters in Rajasthan's mining concessions, where logistics bottlenecks cascade to Mumbai-Delhi-NCR distribution hubs. Distribution runs through Asian Paints' dealer management systems and emerging B2B digital platforms in Gujarat and Maharashtra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cementitious skim-coat overlays threaten gypsum-based putty in exterior applications, forcing incumbents to defend through formulation innovation and specification capture.
For Market Incumbents: Build regulatory moats through accelerated BIS IS 1542 certification timelines and REACH registration capacity for acrylic resin imports. Secure backward integration into Rajasthan gypsum mining to offset feedstock concentration risk. Prioritize hybrid nano-silica R&D to outpace cementitious substitution in waterproofing segments. For New Entrants and Emerging Players: Establish a beachhead in India's Lucknow and Indore corridors where organized brand penetration remains thin. Target waterproof putty specifications in Mumbai and Chennai basement-grade construction where monsoon mandates create specification windows. Deploy direct factory-to-contractor digital platforms to bypass entrenched distributor networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across acrylic binder synthesis and REACH compliance infrastructure, favoring scaled players with regulatory affairs depth. Acquisition targets should exhibit captive gypsum feedstock or in-house polymer production. Watch for BIS certification timeline compression as an inflection signal filtering informal suppliers from organized channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gypsum Mining | Rajasthan feedstock control insulates Saint-Gobain and J.K. Cement from logistics bottlenecks and price volatility. |
| REACH Registration Investment | ECHA compliance capacity filters European acrylic imports to Sika AG and BASF SE, excluding trading houses. |
| Hybrid Nano-Silica Formulation Launch | Singapore and Hong Kong commercial developers specify these systems for podium-level waterproofing mandates. |
| Direct Digital Procurement Platform | Asian Paints' dealer management systems and independent B2B marketplaces disintermediate traditional distributors in Gujarat. |
| Tier-2 City Distribution Expansion | Lucknow, Indore, and Kochi corridors offer volume expansion outside saturated Mumbai-Delhi-NCR markets for organized brands. |
Research Approach
Cross-validation between primary interviews with plant managers at Rajasthan gypsum processing facilities, procurement leads at Mumbai-based decorative coatings distributors, and technical R&D directors at acrylic resin formulators anchors the qualitative findings. Secondary validation draws from BIS certification databases, ECHA REACH registration filings, customs trade data for gypsum and acrylic resin imports, and SEC 10-K disclosures from listed building materials conglomerates. Bottom-up volume aggregation across product type, application, and material segments triangulates against top-down construction spending forecasts.
Calibration against historical gypsum consumption patterns in India's mass housing programs and Vietnam's Ho Chi Minh City corridor informs the projection framework. Segmentation dimensions span interior versus waterproof versus exterior grades, residential versus commercial versus industrial end-uses, and gypsum versus acrylic versus silicone material bases. CAGRs derive from elasticity-adjusted demand curves incorporating GB 18582 regulatory enforcement timelines and monsoon-resistant construction specification adoption across South Asian coastal zones.
Sensitivities concentrate around naphtha cracking margin volatility affecting acrylic binder economics, BIS certification timeline delays for reformulated low-VOC products, and cementitious substitution acceleration in Middle Eastern exterior markets. Quarterly review of Rajasthan mining concession utilization rates, REACH registration application backlogs, and Tier-2 city construction permit issuance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Zinc L-Pidolate Market
Bulk Chemicals
Ammonium Bromide Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
Cellulose Powder Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Global Acrylate Monomers Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
Carbon Disulfide Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Antimony Trioxide Market
Bulk Chemicals
Global Bio Based and Synthetic Dimethyl Ether (DME) Market
Bulk Chemicals
White Charcoal Powder Market
Bulk Chemicals
Global 2-Ethylhexanoic Acid Market
Bulk Chemicals
Isoprene Monomer Market