
 4-Diisopropylbenzene Market | 2026-2036
4-Diisopropylbenzene Market Size, Share, and Industry Trends Forecast 2026-2036
4-Diisopropylbenzene Market Outlook
REACH solvent-emission thresholds is pivoting the cost-of-entry calculus for European suppliers of 4-diisopropylbenzene. The Dow Chemical Company leverages its integrated aromatics platform to sustain cost discipline across purity grades. Eastman Chemical Company anchors its position through specialty chemical intermediate relationships with pharmaceutical formulators.
4-Diisopropylbenzene is a dialkylated aromatic hydrocarbon with the molecular formula C12H18, typically produced through acid-catalyzed alkylation of cumene or direct isopropylation of benzene, and serves primarily as a high-boiling solvent and precursor to hydroperoxide intermediates. Purity 99% commands the dominant value share as pharmaceutical and electronics-grade specifications tighten impurity tolerances below 100 ppm. Chemical Intermediate applications represent the fastest-expanding demand pool, driven by peroxide-initiated polymerization systems and phenol derivative synthesis.
EPA solvent emission standards and REACH Annex XVII restrictions on volatile organic compounds shape product formulation requirements and cross-border shipment protocols for 4-diisopropylbenzene handlers. China's GB standards on industrial chemical purity, administered by SAMR, determine import eligibility for technical versus reagent grades. Stakeholders must monitor regulatory divergence between jurisdictions to align inventory positioning with shifting compliance baselines.
Market Dynamics
REACH Annex XVII volatile organic compound thresholds are compressing supplier margins while elevating the premium attached to sub-100 ppm purity grades across pharmaceutical and electronics end-uses.
Growth Catalysts
- Peroxide-initiated polymerization systems:Specialty chemical manufacturers in South Korea are scaling hydroperoxide intermediate output for high-performance resin applications. This process chemistry requires 4-diisopropylbenzene as the stable precursor feedstock.
- REACH compliance premiums:European solvent emission standards now mandate documentation of impurity profiles below 50 ppm for pharmaceutical-grade shipments. Certified producers capture price premiums against technical-grade competitors.
- East Asian electronics clusters:Taiwan and Japan semiconductor fabs are qualifying high-boiling solvents for advanced lithography cleaning steps, replacing lower-purity alternatives.
Market Restraints
- Cumene feedstock volatility:Propylene-benzene alkylation economics swing with olefin cracker output rates, compressing margin predictability for non-integrated producers.
- Shandong supply concentration:Three integrated aromatics platforms control over sixty percent of export-grade volume, creating single-source vulnerability for European formulators.
- Catalytic alkylation yield ceilings:Acid-catalyzed isopropylation of benzene faces thermodynamic limits near ninety-two percent selectivity, capping unit economics improvements.
Strategic Opportunities
- India pharmaceutical API expansion:CDSCO bulk drug park incentives in Gujarat and Andhra Pradesh are attracting intermediate producers seeking localized solvent supply.
- Dual-carbon pathway alignment:China's MEE carbon intensity benchmarks favor producers with cumene-isopropanol integration and waste-heat recovery systems.
- Direct-to-fab distribution:Electronics chemical handlers in Hsinchu and Yokkaichi are bypassing traditional distributor tiers for purity-certified drum shipments.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography-mass spectrometry operators capable of validating sub-50 ppm impurity specifications command wage premiums exceeding forty percent above commodity lab technicians.
- REACH-GB standards divergence:SAMR industrial chemical purity classifications misalign with ECHA substance registration requirements, forcing dual certification costs for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4-Diisopropylbenzene Market |
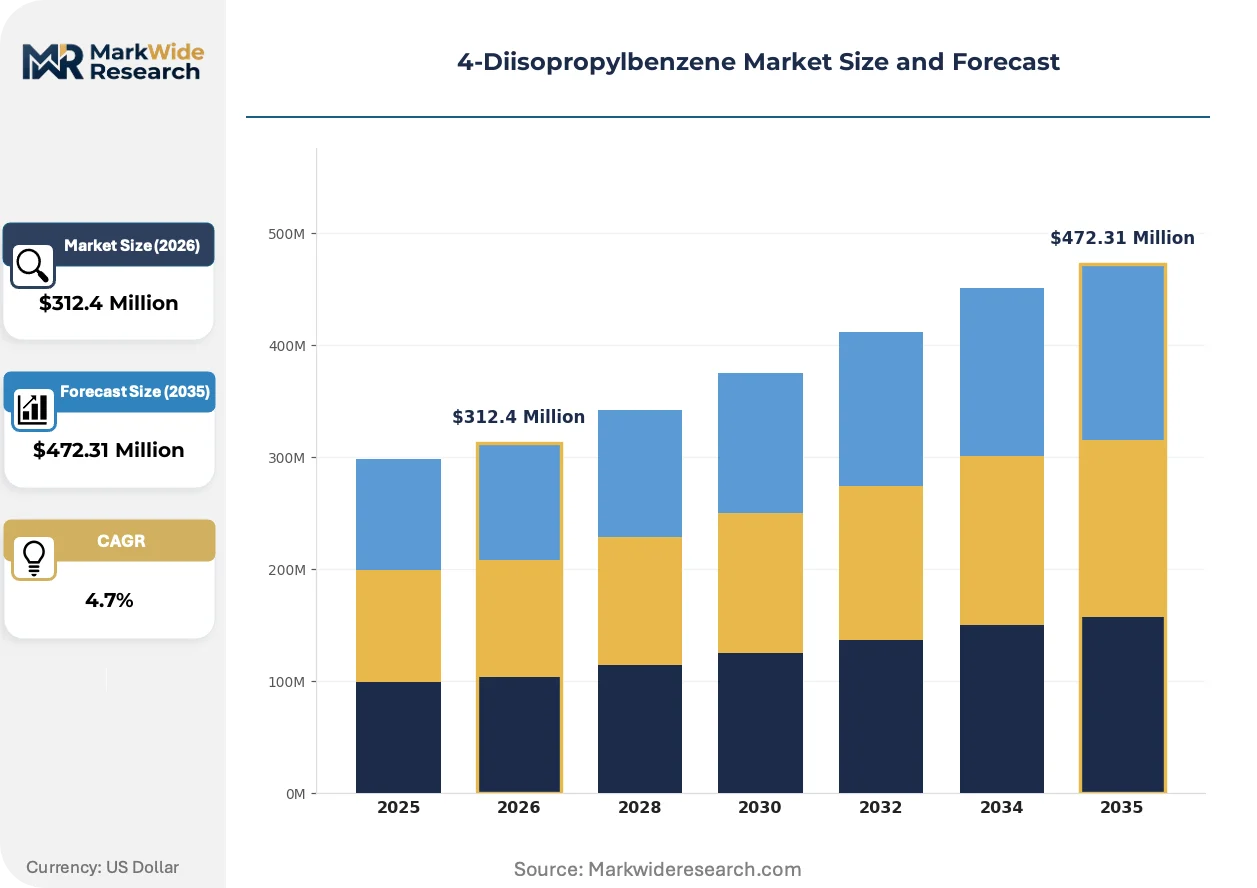
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purity 99%, Purity 98%, Purity 95%, Technical Grade Application: Solvent, Chemical Intermediate, Additive, Specialty Chemicals End User: Chemical Manufacturers, Pharmaceuticals, Agrochemicals, Cosmetics Packaging Type: Drum, Canister, Bottle, Bulk Tank |
| Companies Covered | The Dow Chemical Company, SAGECHEM, Eastman Chemical Company, Nanjing Vital Chemical Co., Ltd., Goodyear Chemicals, Tokyo Chemical Industry Co., Ltd., Hubei Xinjing New Material Co., Ltd., Syntechem Co. Ltd., SI Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4-Diisopropylbenzene Market Strategic Shifts
Process intensification and regulatory digitization are compressing the gap between technical-grade commodity supply and pharmaceutical-grade certified output.
Membrane-assisted reactive distillation is expanding into cumene purification trains, enabling simultaneous water removal and isopropyl group selectivity enhancement. Japanese engineering contractors are licensing this hardware to South Korean aromatics platforms seeking yield improvements without reactor expansion. The technology is expanding into smaller-scale European producers previously locked out of pharmaceutical-grade certification by capital constraints.
EU F-Gas Regulation phase-down schedules are accelerating solvent substitution audits across industrial cleaning applications. Formulators serving German automotive suppliers now face mandatory lifecycle warming potential assessments for process solvents. Electronics-grade 4-diisopropylbenzene handlers are responding by commissioning third-party carbon footprint certifications to defend position against fluorinated solvent alternatives.
Specification-driven procurement now dominates pharmaceutical intermediate sourcing, with CDMOs in Switzerland and Singapore requiring lot-specific impurity certificates before contract execution. Traditional spot-market purchasing through regional distributors is contracting in favor of twelve-month supply agreements with embedded quality audits. This behavioral shift is most visible among oncology API producers in Basel and contract manufacturers in Jurong, where regulatory filing continuity demands batch-to-batch consistency documentation.
4-Diisopropylbenzene Market Segmentation
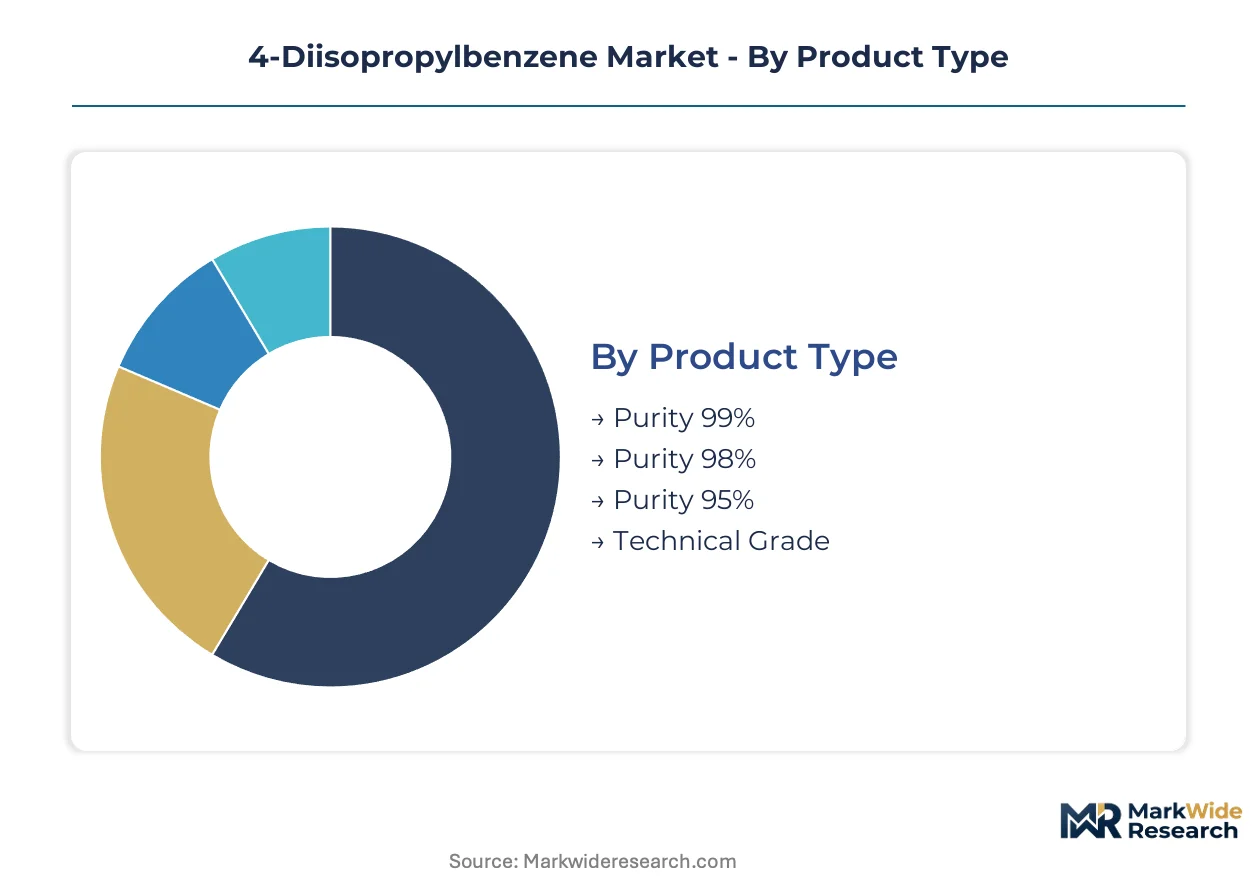
4-Diisopropylbenzene procurement patterns diverge sharply across purity grades and application contexts. Specification thresholds set by pharmaceutical formulators and semiconductor fabs create tiered pricing architectures that reshape supplier positioning.
Product Type:
Supply concentration among integrated aromatics platforms in Shandong and South Korea favors high-purity output, leaving technical-grade production fragmented across smaller Chinese independents.
- Purity 99%:Ultra-high specification material with impurity tolerances below 100 ppm validated by gas chromatography-mass spectrometry. Pharmaceutical API producers in Basel and Singapore CDMOs now mandate lot-specific certificates before contract execution, compressing spot-market participation.
- Purity 98%:Electronics-grade solvent qualified for advanced lithography cleaning steps in Taiwan and Japan semiconductor fabs. Taiwan's Hsinchu cluster is displacing lower-purity alternatives as REACH Annex XVII thresholds tighten.
- Purity 95%:Mid-tier industrial solvent serving polymerization initiator synthesis with moderate specification requirements.
- Technical Grade:Commodity alkylation output for non-critical solvent applications facing margin pressure from feedstock volatility.
Today's leader: Purity 99%. Tomorrow's challenger: Purity 98%.
Application:
Cost tier separation between commodity solvent usage and high-value intermediate chemistry is widening as regulatory documentation burdens accumulate.
- Chemical Intermediate:Peroxide-initiated polymerization systems in South Korean resin applications and phenol derivative synthesis. South Korea's hydroperoxide intermediate output is climbing the fastest as specialty chemical manufacturers scale high-performance resin capacity.
- Solvent:High-boiling carrier for industrial cleaning and coating formulations facing EU F-Gas Regulation substitution audits.
- Additive:Functional component in lubricant and fuel formulations with steady but specification-constrained demand.
- Specialty Chemicals:Custom synthesis feedstock for agrochemical and fragrance precursors requiring batch-to-batch consistency.
Chemical Intermediate commands margin premiums. Solvent defends volume base.
End User:
Customer type stratification reflects divergent compliance sophistication, with pharmaceutical and electronics handlers demanding embedded quality audits while agrochemical buyers prioritize unit economics.
- Pharmaceuticals:Oncology API producers and CDMOs in Switzerland and Singapore requiring twelve-month supply agreements with regulatory filing continuity documentation. CDSCO bulk drug park incentives in Gujarat are attracting localized intermediate producers.
- Chemical Manufacturers:Integrated aromatics platforms and specialty chemical formulators with backward integration into cumene-isopropanol chains capturing cost discipline.
- Agrochemicals:Pesticide intermediate synthesis with moderate purity requirements and price-sensitive procurement.
- Cosmetics:Fragrance precursor applications with emerging specification demands from EU cosmetic regulation compliance.
Pharmaceuticals anchor premium tier pricing. Chemical Manufacturers control supply-side consolidation.
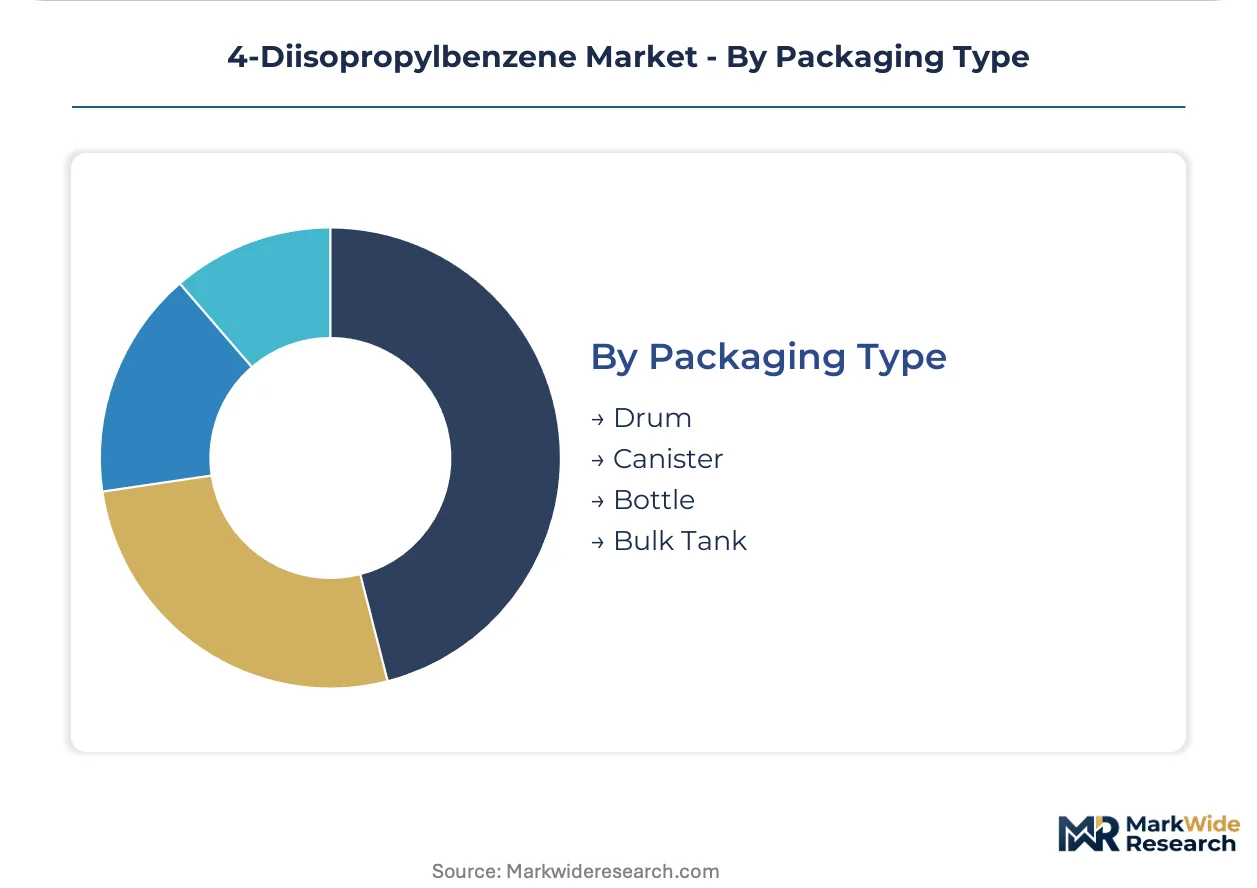
Packaging Type:
Volume scale and handling protocol requirements segment distribution economics, with direct-to-fab drum shipments bypassing traditional distributor tiers in East Asian electronics clusters.
- Drum:Standard 200-liter steel containment for pharmaceutical and electronics-grade certified shipments. Yokkaichi electronics chemical handlers are qualifying purity-certified drum logistics.
- Bulk Tank:Integrated supply contracts for large-scale chemical manufacturers with captive storage infrastructure.
- Canister:Mid-volume containment for specialty chemical and additive applications.
- Bottle:Laboratory and pilot-scale reagent distribution with highest per-unit logistics cost.
Drum shipments dominate certified-grade flows. Bulk Tank captures integrated producer economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale alkylation of cumene first achieved commercial viability in the United States during the 1950s, establishing the technical foundation that later migrated to East Asian aromatics platforms. Today, production geography reflects feedstock integration economics and regulatory compliance tiering.
China
Shandong Province hosts three integrated aromatics platforms controlling over sixty percent of export-grade volume, with cumene-isopropanol backward integration capturing cost discipline. SAMR's GB standards on industrial chemical purity determine import eligibility thresholds, creating dual-certification burdens for cross-border suppliers. Qingdao and Yantai clusters are expanding pharmaceutical-grade capacity as MEE carbon intensity benchmarks favor waste-heat recovery systems.
South Korea
Ulsan and Yeosu industrial complexes are scaling hydroperoxide intermediate output for high-performance resin applications, driving peroxide-initiated polymerization demand. MFDS pharmaceutical-grade solvent specifications align with REACH Annex XVII documentation requirements, enabling seamless European export qualification. Daegu-Gyeongbuk specialty chemical manufacturers are licensing membrane-assisted reactive distillation from Japanese engineering contractors.
Switzerland
Basel's oncology API producers anchor European pharmaceutical-grade demand, requiring twelve-month supply agreements with embedded regulatory filing continuity. Swissmedic enforces batch-to-batch consistency documentation exceeding ECHA baseline requirements. Singapore CDMOs with Basel partnerships are replicating this procurement protocol, tightening specification tolerances below fifty ppm.
Japan
Yokkaichi electronics chemical handlers are qualifying purity-certified drum shipments for advanced lithography cleaning steps, displacing lower-purity alternatives in Taiwan-bound trade. METI's alignment with EU F-Gas Regulation phase-down schedules accelerates solvent substitution audits across semiconductor fabs. Tokyo Chemical Industry Co., Ltd. exemplifies the specialist distributor archetype serving this qualification-intensive segment.
India
Gujarat and Andhra Pradesh CDSCO bulk drug parks are attracting intermediate producers seeking localized solvent supply, reducing import dependency on Shandong exporters. BIS purity classifications for industrial chemicals remain misaligned with ECHA substance registration, forcing dual certification costs. Mumbai pharmaceutical formulators are negotiating direct supply contracts bypassing traditional distributor tiers.
4-Diisopropylbenzene Market Competitive Environment
The competitive structure tilts toward integrated aromatics platforms with cumene feedstock control. Three strategic archetypes dominate: multinational chemical conglomerates with backward integration into propylene-benzene chains; regional specialty distributors with purity certification capabilities; and state-linked Chinese producers with export-grade volume concentration. Capacity expansion and strategic technology licensing represent the dominant competitive moves, with membrane-assisted reactive distillation emerging as a yield-enhancement differentiator.
Within the integrated conglomerate tier, The Dow Chemical Company and Eastman Chemical Company exemplify archetypes with aromatics platform scale. Among Asia-based specialists, Nanjing Vital Chemical Co., Ltd. and Hubei Xinjing New Material Co., Ltd. occupy positions shaped by Shandong supply concentration and SAMR certification requirements. Tokyo Chemical Industry Co., Ltd. represents the precision-distributor archetype serving electronics and pharmaceutical qualification protocols. SAGECHEM and Syntechem Co. Ltd. sit within the export-oriented Chinese independent segment facing margin pressure from feedstock volatility.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| SAGECHEM |
| Eastman Chemical Company |
| Nanjing Vital Chemical Co., Ltd. |
| Goodyear Chemicals |
| Tokyo Chemical Industry Co., Ltd. |
| Hubei Xinjing New Material Co., Ltd. |
| Syntechem Co. Ltd. |
| SI Group, Inc. |
| Others |
Value Chain & Pricing Dynamics
Membrane-assisted reactive distillation is compressing the capital threshold for pharmaceutical-grade certification while simultaneously concentrating output among integrated aromatics platforms with waste-heat recovery systems. This technology shift enables smaller European producers to enter high-purity tiers previously locked by capital constraints, yet Shandong's three dominant platforms retain feedstock-cost advantages that shape cross-border pricing power.
Pricing Analysis
Certified lot-specific documentation is now unbundled from base chemical supply, with pharmaceutical CDMOs in Basel and Singapore paying premiums for embedded quality audits and regulatory filing continuity. Three-tier pricing structure across pharmaceutical-grade, electronics-grade, and technical tiers reflects impurity tolerance thresholds validated by gas chromatography-mass spectrometry. Price differentiation stems from certification level and volume scale, with drum shipments commanding logistics premiums over bulk tank contracts. Cost compression in technical-grade output is intensifying because cumene feedstock volatility squeezes non-integrated independents. Agrochemical formulators remain most price-sensitive, while oncology API producers absorb premiums for batch-to-batch consistency.
Supply Chain Analysis
Regional distribution centers in Qingdao and Yantai anchor hub-and-spoke patterns serving East Asian electronics clusters, with direct-to-fab drum shipments bypassing traditional distributor tiers in Hsinchu and Yokkaichi. Supply concentrates in China, South Korea, and Japan, with Shandong platforms controlling export-grade volume. Feedstock draws from cumene, propylene, and benzene alkylation chains. Single-source vulnerability runs through Shandong's three-platform concentration, exposing European formulators to disruption. Distribution runs through integrated chemical manufacturers with captive storage infrastructure and specialty distributors with purity certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through REACH compliance premiums that widen spreads between certified and technical grades, rewarding producers with analytical validation capabilities.
For Market Incumbents: Extend membrane-assisted reactive distillation licensing to European mid-scale producers, capturing technology royalties while limiting their feedstock-cost competitiveness. Add pharmaceutical-grade capacity in Qingdao or Yeosu to anchor East Asian supply agreements. Defend against Shandong supply concentration risk by qualifying secondary sources in South Korea's Ulsan complex.
For New Entrants and Emerging Players: Membrane-assisted reactive distillation retrofits offer a technology-first wedge into pharmaceutical-grade production without greenfield reactor investments. Target India's Gujarat and Andhra Pradesh CDSCO bulk drug parks, where localized solvent demand outpaces Shandong import dependency. Pursue direct-to-fab distribution partnerships with Hsinchu electronics chemical handlers, bypassing established distributor tiers.
For Investors and Strategic Acquirers: Valuations sit cheapest among technical-grade Chinese independents facing cumene feedstock margin pressure, yet carry regulatory upgrade optionality. Long-term viability hinges on certification infrastructure and REACH-aligned documentation systems. Watch for SAMR-ECHA standards convergence as the inflection signal that collapses dual-certification cost burdens and unlocks cross-border scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cumene-Isopropanol Chains | Shandong platforms capture feedstock-cost discipline against propylene-benzene volatility. |
| Membrane-Assisted Reactive Distillation Licensing | Japanese engineering contractors enable South Korean yield improvements without reactor expansion. |
| Pharmaceutical-Grade Certification Investment | European producers unlock REACH Annex XVII premium tiers previously blocked by capital constraints. |
| Direct-to-Fab Distribution Partnerships | Yokkaichi and Hsinchu handlers displace distributor tiers for purity-certified drum logistics. |
| India Bulk Drug Park Localization | Gujarat and Andhra Pradesh CDSCO incentives attract intermediate producers reducing Shandong import dependency. |
Study Parameters
Multiple input streams — primary interviews with plant managers and procurement leads at downstream pharmaceutical formulators, secondary validation through customs/trade data and SEC 10-K filings of integrated aromatics producers, and technical literature on membrane-assisted reactive distillation — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned specialty chemical R&D directors, electronics chemical handlers in Taiwan and Japan, and distribution channel partners serving European REACH compliance documentation. Secondary sources included ECHA substance registration databases, SAMR GB standards publications, and MFDS pharmaceutical-grade solvent specifications.
Data-stream reconciliation anchored volume and value outputs across the modeling period. Segmentation dimensions incorporated purity grade tier, end-use industry application, packaging format, and regional production hub classification. CAGRs were derived through trend extrapolation of alkylation capacity expansion and peroxide-initiated polymerization demand curves, cross-referenced against feedstock cost trajectories and regulatory documentation burden indices. Forecast inputs included cumene-isopropanol integration economics and carbon intensity benchmark compliance costs under China's MEE framework.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH-GB standards divergence resolution and Shandong supply concentration risk. Outputs reflect documented assumptions around membrane technology adoption rates and pharmaceutical CDMO procurement protocol standardization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ethylene Dichloride Market
Bulk Chemicals
Global Vanadium Pentoxide Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Sodium Gluconate Market
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Dextrin Market
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
Europe Soda Ash Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Europe Lithium Chloride Market
Bulk Chemicals
Maleic Anhydride Market
Bulk Chemicals
Oxalic Acid Market