
 Europe Lime Market | 2026-2036
Europe Lime Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lime Market Foresight
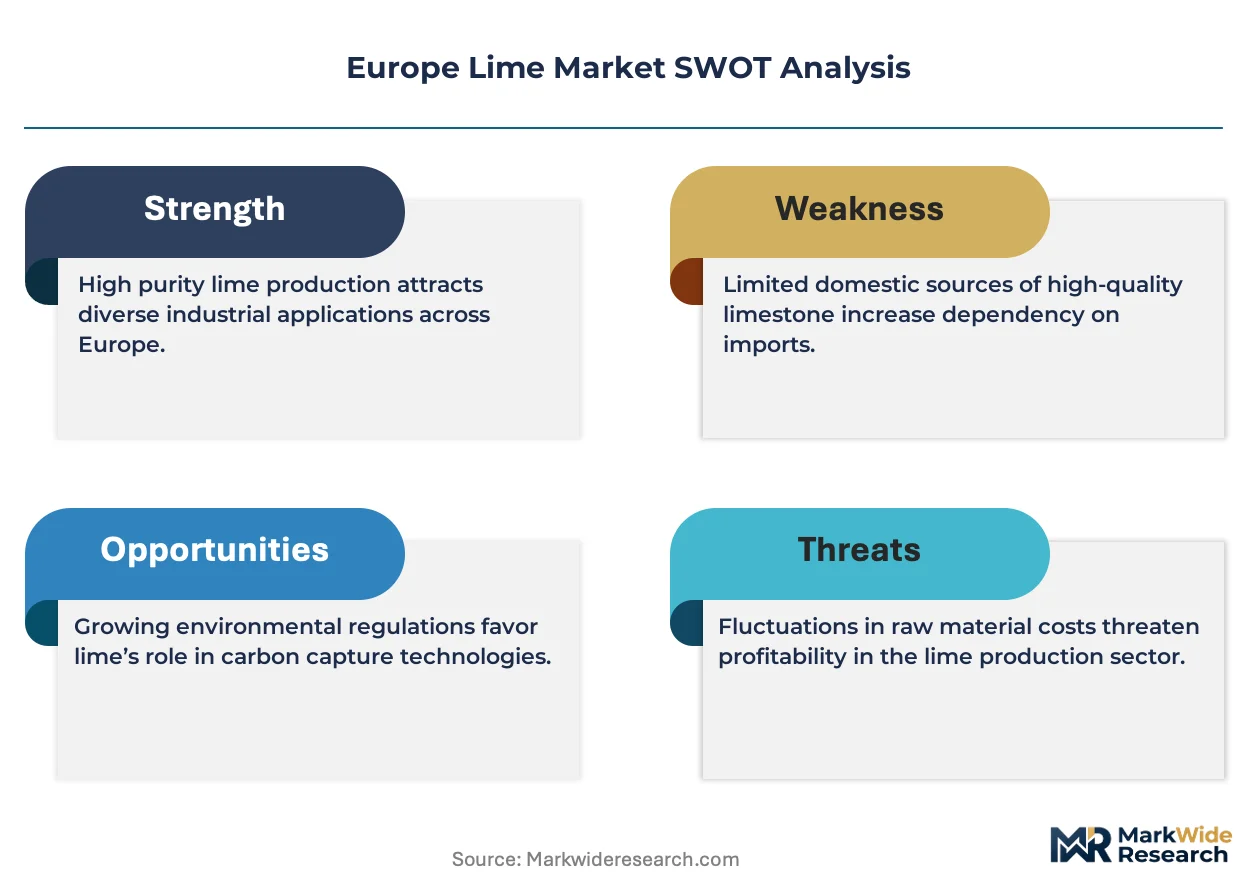
A capital-intensity divergence between vertically integrated kiln operators and regional distributors is bifurcating competitive returns across the Europe lime landscape. Lhoist Group leverages its captive limestone reserves and coastal logistics network to sustain margin structures that smaller competitors cannot replicate. Carmeuse Coordination Center SA anchors its position through dense rail-linked storage terminals serving the Benelux steel corridor. Singleton Birch Ltd. specializes in high-calcium quicklime for chemical synthesis, occupying a defensible niche against commodity-grade rivals.
Lime encompasses calcium oxide and calcium hydroxide compounds produced by calcining limestone at temperatures exceeding 900 degrees Celsius, with reactivity measured by available calcium oxide content and slaking rate. The material serves as a fundamental alkalizing agent across steel desulfurization, flue gas treatment, and construction mortar applications. Quicklime commands the largest volume share among product types due to its irreplaceable role in steel manufacturing flux chemistry, while hydrated lime is capturing accelerated growth in environmental applications where controlled reactivity reduces handling hazards. Water treatment and soil stabilization represent the most structurally attractive application segments, as EU Drinking Water Directive revisions tighten pH adjustment standards and infrastructure stimulus expands road base stabilization programs.
REACH registration requirements and the EU Emissions Trading System are tightening operational permits for lime kilns, elevating compliance costs for carbon-intensive producers while rewarding firms with biomass co-firing capabilities. The F-Gas Regulation and Industrial Emissions Directive collectively mandate continuous emissions monitoring, reshaping capital allocation toward regenerative kiln upgrades and waste heat recovery installations. Stakeholders must track evolving EU carbon border adjustment mechanisms and national building decarbonization roadmaps to anticipate demand shifts between construction-grade and industrial-specialty lime grades.
Market Dynamics
EU carbon border adjustment mechanisms and the EU Emissions Trading System are forcing lime producers to reconfigure kiln operations around biomass co-firing and waste heat recovery, compressing margins for carbon-intensive operators while rewarding decarbonization leaders.
Growth Catalysts
- EU Green Deal decarbonization mandates:Steel sector lime specifications are pivoting toward lower-carbon production pathways, sustaining offtake from metallurgical customers.
- Germany:Industrial cluster density supports sustained quicklime demand for chemical synthesis and flue gas treatment applications.
- EU Drinking Water Directive revisions:Tightened pH adjustment standards are accelerating municipal utility consumption of hydrated lime for water treatment.
Market Restraints
- Natural gas price volatility:Kiln fuel costs represent a substantial share of production economics, exposing operators to energy market swings.
- Captive limestone reserve concentration:Vertically integrated producers with coastal logistics networks control access to lowest-cost feedstock positions.
- Dolomitic lime substitution:Magnesium-bearing alternatives are capturing share in select soil stabilization and construction mortar applications.
Strategic Opportunities
- Eastern European infrastructure stimulus:Road base stabilization programs in Poland and Romania are expanding construction-grade lime absorption.
- F-Gas Regulation compliance:Continuous emissions monitoring mandates are creating aftermarket service revenue streams for kiln instrumentation providers.
- Regenerative kiln technology and digital process control convergence:Combined heat recovery and predictive maintenance platforms are opening efficiency upgrade cycles.
Industry Challenges
- REACH registration complexity:Chemical substance dossier maintenance demands specialized regulatory affairs capacity that smaller operators struggle to retain.
- Kiln refractory replacement cycles:Extended high-temperature operation accelerates lining degradation, requiring planned downtime that disrupts customer supply continuity.
- Biomass feedstock certification:Sustainability credentialing for alternative fuels adds procurement verification overhead without immediate cost recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lime Market |
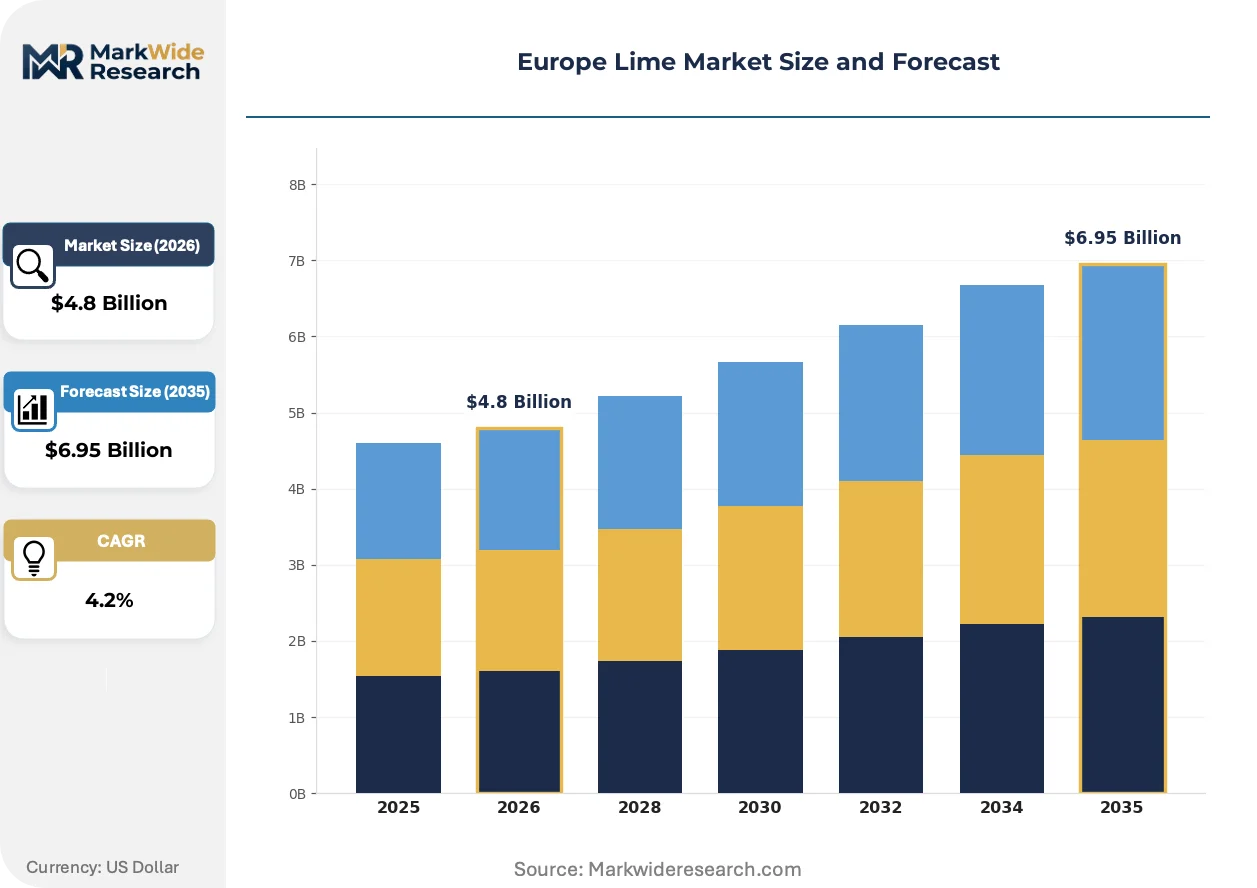
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrated Lime, Quick Lime, Agricultural Lime, Burnt Lime End Use Industry: Chemicals, Environmental, Construction, Agriculture Form: Powder, Granular, Slurry, Pellets Application: Soil Stabilization, Water Treatment, Steel Manufacturing, Pulp & Paper |
| Companies Covered | Minerals Technologies Inc., Calcis Lienen GmbH & Co. KG, Lhoist Group, Singleton Birch Ltd., Cales Pascual SL, CRH Plc, Nordkalk Corp., Marker Holding GmbH, Carmeuse Coordination Center SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lime Market Shifts & Advancements
Electrification of calcination processes, tightening emissions monitoring mandates, and evolving procurement specifications around embodied carbon are collectively restructuring how lime reaches industrial and municipal buyers.
Oxyfuel combustion technology is decomposing the conventional air-fired kiln architecture by enabling concentrated carbon dioxide capture from exhaust streams. Steel producers in the Benelux corridor are piloting these retrofits to secure low-carbon lime supply for scope 3 reduction targets. The technology is decomposing legacy kiln economics by adding capital intensity while compressing carbon compliance costs.
The EU Emissions Trading System and Industrial Emissions Directive collectively mandate continuous emissions monitoring with standardized reporting protocols. Lime kiln operators face stepped permit scrutiny that elevates operational transparency requirements. German and French facilities are responding fastest, deploying integrated stack monitoring and automated data transmission to regulatory portals.
Buyers are unbundling long-term supply agreements into shorter, index-linked contracts with explicit carbon intensity clauses. Large water utilities and steel mills are displacing fixed-price multi-year commitments with quarterly-adjusted arrangements tied to EU ETS carbon prices. This pattern is most visible in Germany, where municipal procurement boards now require embodied carbon disclosures alongside traditional quality specifications.
Europe Lime Market Segmentation
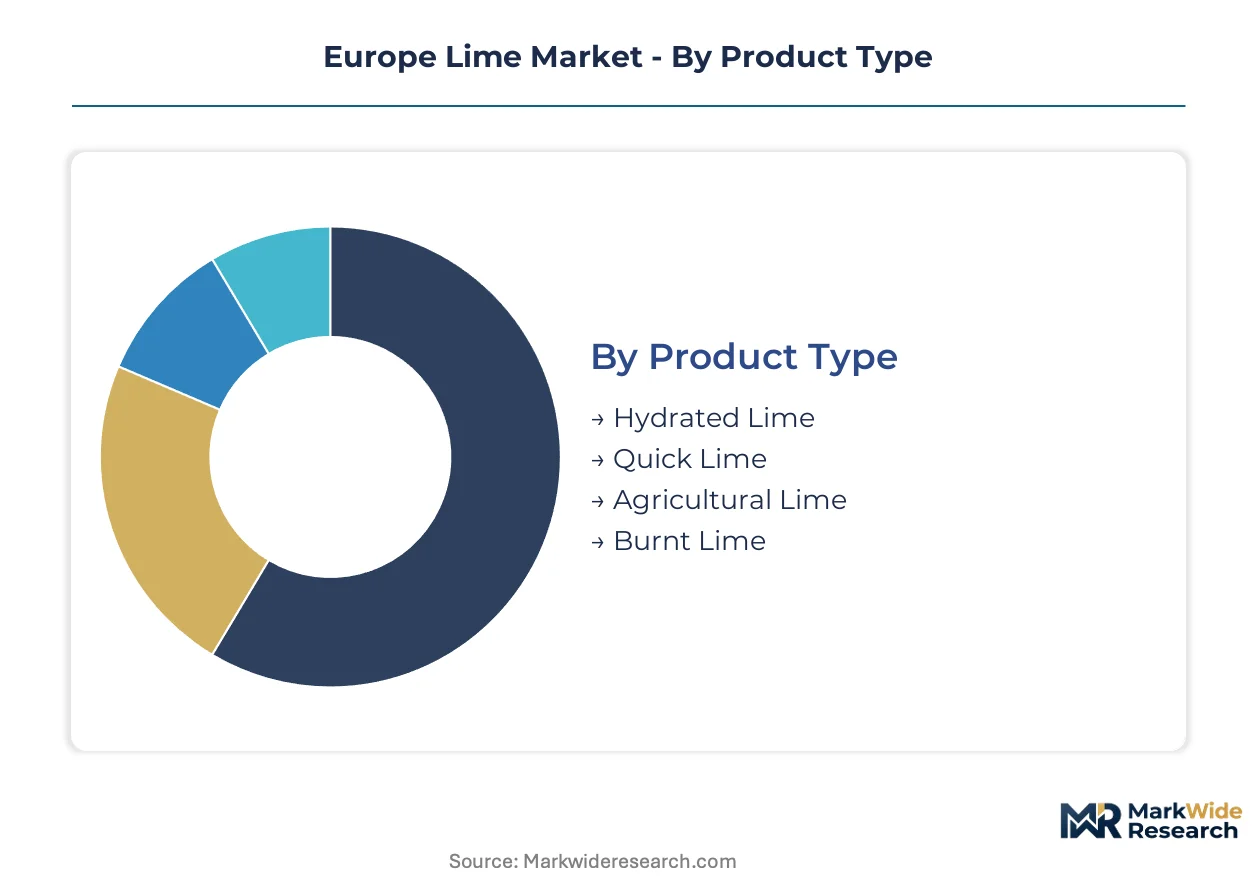
Segmentation in the Europe lime market reveals how product specifications, delivery forms, and end-use requirements fragment demand across distinct procurement channels. Buyers in Germany and Benelux steel corridors prioritize quicklime reactivity grades, while municipal utilities in France and Italy drive hydrated lime absorption for environmental compliance.
Product Type:
Domestic production concentrates quicklime and hydrated lime for regional steel and chemical clusters, while agricultural lime moves through cross-border trade into Poland and Romania.
- Quick Lime:Calcium oxide produced at temperatures exceeding 900 degrees Celsius, measured by available calcium oxide content and slaking rate. German steel desulfurization plants and Benelux flue gas treatment facilities anchor demand, with EU Green Deal decarbonization mandates sustaining metallurgical offtake despite carbon compliance cost pressure.
- Hydrated Lime:Calcium hydroxide formed through controlled slaking of quicklime, offering reduced handling hazards and precise reactivity control. Municipal utilities in France and water treatment operators across Italy are accelerating procurement as EU Drinking Water Directive revisions tighten pH adjustment standards.
- Agricultural Lime:Ground limestone or dolomitic lime for soil pH correction in farming applications.
- Burnt Lime:Traditional kiln-calcined product for construction mortar and historical restoration specialty applications.
Quicklime holds the largest share; momentum sits with hydrated lime as environmental compliance tightens across municipal procurement.
End Use Industry:
Cost tier differentiation separates premium-grade chemical synthesis lime from commodity construction material, with environmental applications commanding intermediate pricing.
- Chemicals:High-calcium quicklime for calcium carbide, acetylene, and organic synthesis intermediates. Specialty chemical producers in Germany's industrial clusters specify tight impurity tolerances that reward captive limestone reserve holders with margin premiums over commodity distributors.
- Environmental:Flue gas desulfurization, wastewater neutralization, and hazardous waste stabilization. Steel mills across the Benelux corridor and municipal utilities in France are driving the steepest expansion trajectory as F-Gas Regulation and Industrial Emissions Directive compliance mandates deepen.
- Construction:Mortar, plaster, and soil stabilization applications across infrastructure projects.
- Agriculture:Soil pH management and animal feed supplementation in farming regions.
Environmental applications are climbing the fastest; chemicals maintains the deepest margin structure.
Form:
Volume concentration favors powder and slurry for industrial continuous-process integration, while granular and pellet forms serve dispersed agricultural and construction customers.
- Powder:Fine-ground quicklime and hydrated lime for pneumatic conveying and precise dosing in chemical reactors. Steel desulfurization stations and flue gas treatment plants in Germany specify powder grades for automated injection systems.
- Slurry:Pre-slaked hydrated lime in aqueous suspension for water treatment and soil stabilization. French municipal utilities and Italian wastewater operators prefer slurry delivery to eliminate on-site dust handling and simplify regulatory compliance documentation.
- Granular:Coarse particle size for controlled-release agricultural and construction applications.
- Pellets:Compacted spherical form for precision spreading equipment and reduced transport dust.
Powder dominates industrial volume; slurry is gaining share fastest among environmental end-users.
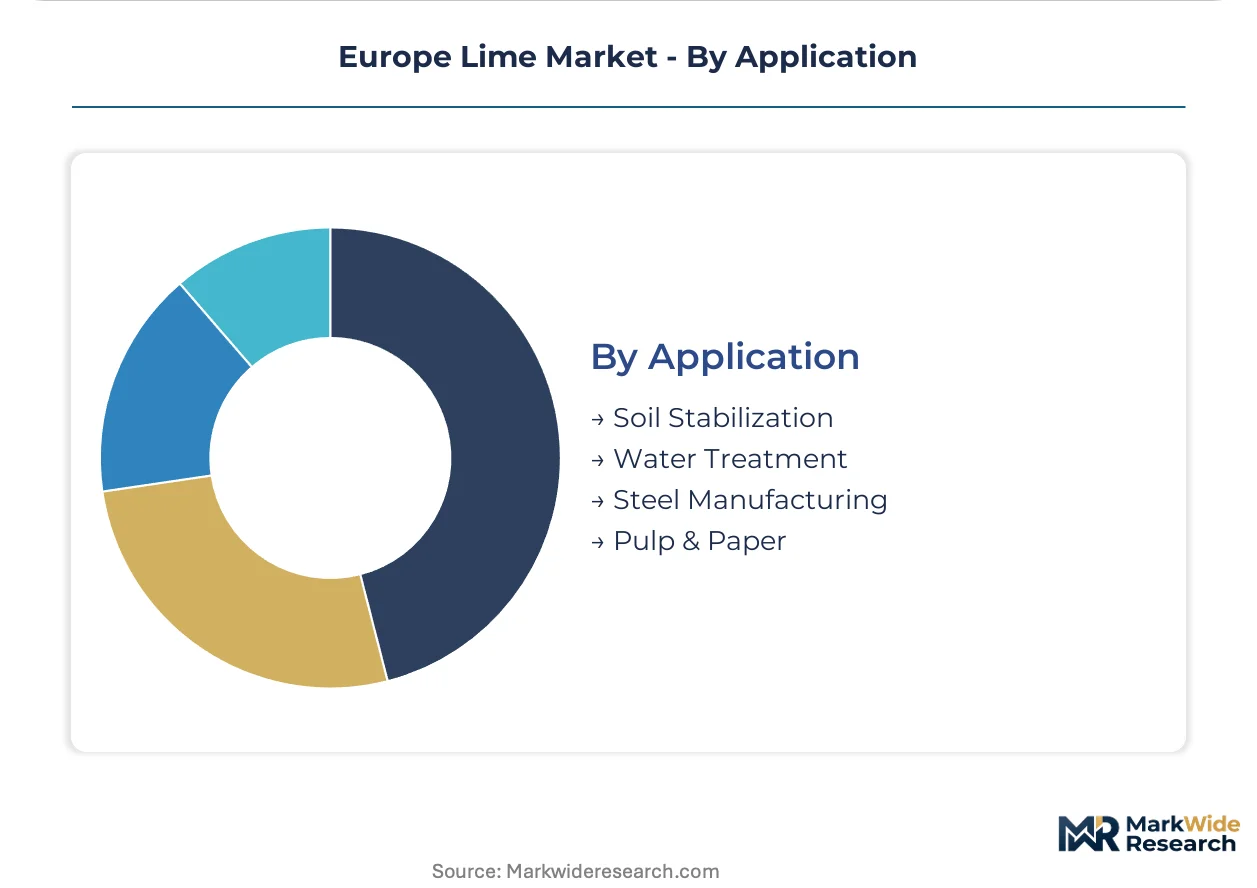
Application:
Customer type fragmentation separates large integrated steel mills with dedicated lime supply contracts from fragmented municipal utilities procuring through tender processes.
- Steel Manufacturing:Flux chemistry for impurity removal in basic oxygen furnaces and electric arc furnaces. German and Benelux steel producers specify quicklime reactivity grades that align with EU carbon border adjustment mechanism scope 3 reduction targets, pressuring suppliers toward biomass co-firing and oxyfuel retrofits.
- Water Treatment:pH adjustment, coagulation aid, and disinfection support in municipal and industrial wastewater systems. Utilities in France, Italy, and Poland are expanding procurement as infrastructure stimulus programs and directive revisions tighten discharge standards.
- Soil Stabilization:Road base modification and subgrade improvement for highway and railway construction.
- Pulp & Paper:Chemical recovery and bleaching process support in integrated mills.
Steel manufacturing retains the largest volume position; water treatment is expanding most quickly as municipal infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German steel mills consume quicklime for metallurgical flux at rates unmatched elsewhere in Europe, while French and Italian municipal utilities drive hydrated lime procurement for water treatment compliance.
Germany
Steel desulfurization plants in the Ruhr and chemical synthesis clusters in Ludwigshafen anchor quicklime offtake. The EU Emissions Trading System pressures kiln operators toward biomass co-firing retrofits. Industrial density in North Rhine-Westphalia sustains dedicated rail-linked supply contracts for metallurgical-grade material.
France
Municipal utilities in Paris and Lyon are expanding hydrated lime procurement for drinking water pH adjustment. EU Drinking Water Directive revisions mandate tighter discharge standards. The Rhône-Alpes corridor concentrates flue gas treatment installations serving petrochemical complexes.
Italy
Wastewater operators in Milan and Rome prefer slurry-form hydrated lime to eliminate on-site dust handling. The F-Gas Regulation drives continuous emissions monitoring upgrades at kiln facilities. Northern industrial zones around Brescia maintain specialty chemical lime demand for leather tanning applications.
Benelux
Steel mills across the Rotterdam-Antwerp corridor specify quicklime reactivity grades aligned with scope 3 reduction targets. The EU Green Deal's decarbonization mandates reshape procurement specifications toward lower-carbon production pathways. Dense rail-linked storage terminals support just-in-time delivery for continuous furnace operations.
Poland
Road base stabilization programs for EU-funded highway expansion absorb construction-grade lime volumes. Infrastructure stimulus directs public procurement toward soil modification contractors. The Silesian industrial region maintains metallurgical demand alongside emerging environmental applications.
Europe Lime Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive limestone reserve holders commanding margin structures that regional distributors cannot replicate. Three archetypes dominate: vertically integrated producers with coastal logistics networks, rail-linked storage terminal operators serving industrial corridors, and high-calcium specialty producers for chemical synthesis. Competitive moves concentrate on regenerative kiln technology upgrades and strategic partnerships with steel producers seeking scope 3 emissions reductions.
Among Benelux-anchored operators, Carmeuse Coordination Center SA exemplifies the rail-linked terminal archetype serving steel corridor demand. Lhoist Group represents the integrated leader tier with captive reserve positions. Singleton Birch Ltd. occupies a specialist position within the high-calcium chemical synthesis segment. These three entities illustrate how geographic positioning and product focus stratify competitive returns across the European lime landscape.
| Leading Market Players |
|---|
| Minerals Technologies Inc. |
| Calcis Lienen GmbH & Co. KG |
| Lhoist Group |
| Singleton Birch Ltd. |
| Cales Pascual SL |
| CRH Plc |
| Nordkalk Corp. |
| Marker Holding GmbH |
| Carmeuse Coordination Center SA |
| Others |
Supply & Pricing Matrix
Sixty-day inventory cycles at German steel mills concentrate purchasing power among metallurgical buyers, compressing margins for kiln operators without captive limestone reserves while amplifying price leverage for coastal logistics-integrated producers. This lead-time discipline binds supply chain structure directly to pricing outcomes across the European lime landscape.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between integrated steel mills and kiln operators, though municipal utilities are fragmenting toward quarterly-adjusted arrangements with EU ETS-linked carbon intensity clauses. Price differentiation rests on reactivity grade certification and volume scale, with high-calcium chemical synthesis lime commanding premiums over commodity construction material. Cost compression in metallurgical grades is intensifying because EU carbon border adjustment mechanisms transfer compliance burdens upstream. Municipal water treatment operators exhibit the lowest price sensitivity due to regulatory-mandated quality specifications, while road construction contractors face acute pressure from infrastructure tender competition.
Supply Chain Analysis
Just-in-time delivery preferences among Benelux steel producers favor rail-linked storage terminals over strategic stockpiles, leaving limited buffer against kiln refractory replacement downtime. Supply concentrates in Germany, France, and Belgium, where captive limestone reserves anchor production economics. Raw material dependencies center on high-carbonate limestone feedstock, natural gas or biomass kiln fuel, and refractory lining materials. Single-source vulnerability runs through coastal logistics networks controlling lowest-cost import positions. Distribution runs through dense terminal networks serving industrial corridors, with slurry-form hydrated lime gaining share for environmental applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among integrated steel producers and large municipal utilities, fragmenting procurement influence among smaller construction contractors and regional chemical distributors.
For Market Incumbents: Secure captive biomass feedstock certification to sustain margin structures under EU Emissions Trading System pressure, and anchor rail-linked terminal positions along the Rotterdam-Antwerp corridor to defend against oxyfuel-equipped entrants. Dolomitic lime substitution in soil stabilization applications threatens commodity-grade positioning, making regenerative kiln technology investment the critical defensive lever. For New Entrants and Emerging Players: Differentiate on slurry-form hydrated lime delivery to French and Italian municipal utilities, where dust-handling compliance burdens deter incumbent powder specialists. White-space targets include aftermarket emissions monitoring services for F-Gas Regulation compliance and construction-grade lime for Polish highway stimulus programs. The most penetrable entry point sits with water treatment operators seeking bundled slurry delivery and regulatory documentation support. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because kiln refractory replacement cycles and REACH registration complexity are forcing smaller operators toward exit. Acquisition targets should display coastal limestone reserve positions or established rail terminal networks. The signal to watch is EU carbon border adjustment mechanism implementation pace, which determines the premium for biomass co-firing capability.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Kiln Retrofit | EU ETS compliance costs reward heat recovery investments at German and Benelux facilities. |
| Biomass Co-firing Certification | Sustainability credentialing unlocks premium pricing from steel producers targeting scope 3 reductions. |
| Slurry Delivery Infrastructure | French municipal utilities prefer aqueous suspension to eliminate on-site dust handling liabilities. |
| Rail-Linked Terminal Expansion | Just-in-time steel mill supply contracts require dense storage networks along the Rotterdam-Antwerp corridor. |
| Oxyfuel Combustion Pilot | Concentrated carbon capture appeals to Benelux steel producers under EU Green Deal mandates. |
Research Methodology
Operator-level perspectives from kiln plant managers, steel procurement leads, municipal utility chemical buyers, and flue gas treatment engineers anchored the qualitative base, cross-referenced with customs trade data, EU ETS permit filings, Cefic sector reports, and national infrastructure stimulus disclosures. Bottom-up production capacity estimates triangulated against top-down end-use consumption models to validate volume figures across the analysis window.
Sensitivity analysis tested demand trajectories under varying EU carbon price assumptions and natural gas volatility scenarios throughout the forecast period. Segmentation dimensions modeled include product reactivity grade, end-use industry concentration, delivery form specification, and regional industrial cluster density. CAGRs were derived from slope-intercept fitting of annual production and consumption estimates, with steel output forecasts and water treatment capital expenditure plans serving as primary demand-side inputs.
Material uncertainties — regulatory enforcement intensity, biomass feedstock availability, and kiln fuel cost swings — sit outside the modeled envelope. Forecasts reflect documented assumptions about EU Green Deal implementation pace and infrastructure stimulus allocation. Revision becomes warranted when carbon border adjustment mechanism scope 3 accounting rules cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Antimony Trioxide Market
Bulk Chemicals
Global Ammonium Chloride Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
Nickel Nitrate Hexahydrate Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
Refined Naphthalene Market
Bulk Chemicals
Global Vinyl Chloride Monomer Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
Alunite Market
Bulk Chemicals
Europe Ammonium Nitrate Market