
 Caprylic Acid Market | 2026-2036
Caprylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Caprylic Acid Market Analysis
The caprylic acid market is repositioning around a widening split between pharmaceutical-grade material commanding purity premiums and commodity grades serving bulk industrial applications. Oleon NV leverages its integrated European oleochemical footprint to sustain high-purity output for regulated end uses. Wilmar International anchors volume production across Southeast Asian palm kernel supply chains. KLK OLEO differentiates through specialized fatty acid fractionation capabilities that serve nutraceutical customers.
Caprylic acid is an eight-carbon saturated fatty acid (C8:0) typically derived from coconut oil or palm kernel oil through hydrolysis and fractional distillation, valued for its antimicrobial properties and rapid metabolic conversion to ketone bodies. The liquid product type dominates current volume flows due to ease of handling in food processing and personal care formulation. Pharmaceutical and dietary supplement applications are capturing expanding margin pools as clinical validation of medium-chain triglyceride benefits accumulates. Food and beverage applications remain structurally mature but defend steady offtake through natural preservative substitution trends.
FDA food additive regulations and EFSA novel food assessments shape product qualification pathways for caprylic acid suppliers targeting ingestible applications. REACH registration requirements in Europe enforce comprehensive toxicological documentation that filters out non-compliant imports. ISO 22000 and HACCP certifications function as baseline market access credentials across major demand centers. Stakeholders must monitor evolving ketone body research and corresponding regulatory recategorization of caprylic acid in dietary supplement jurisdictions.
Market Dynamics
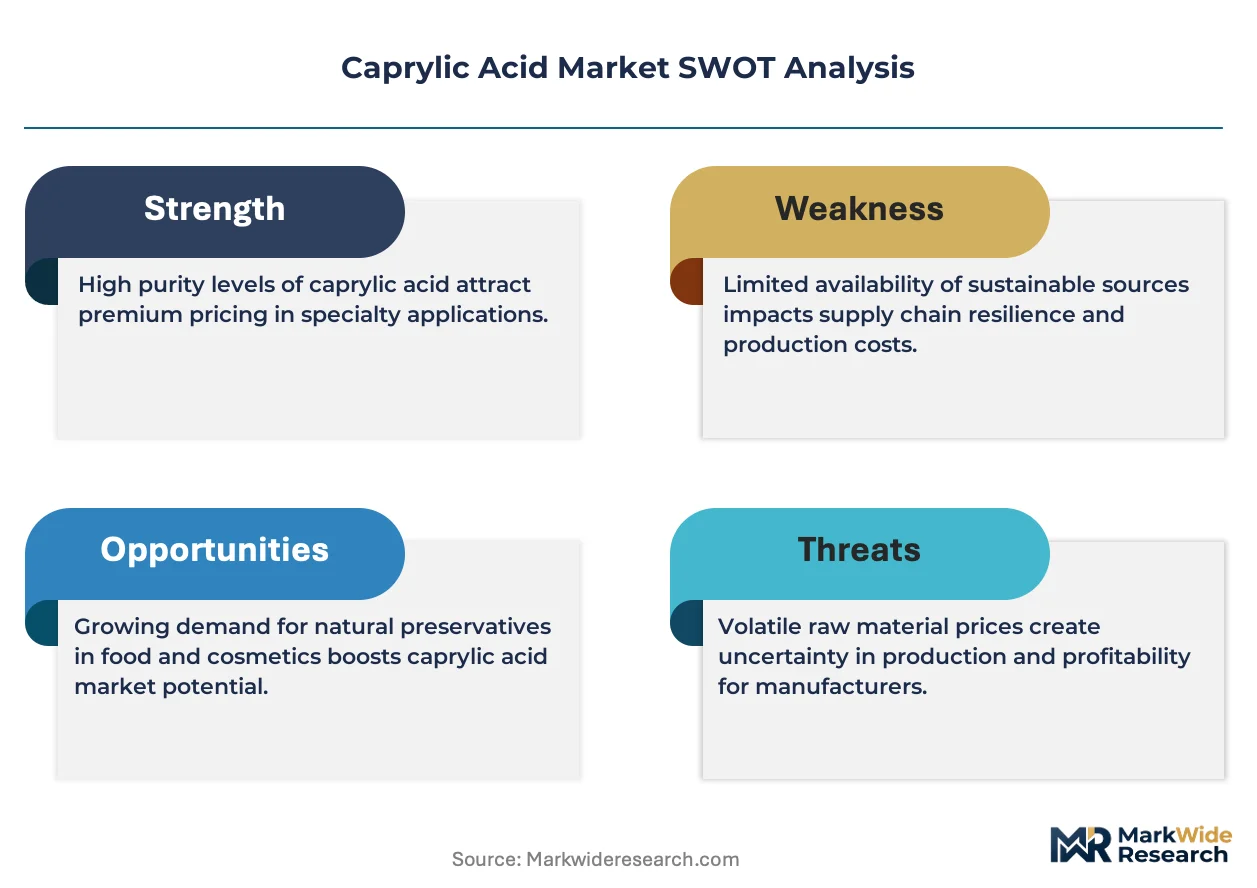
Pharmaceutical-grade purity requirements are splitting the caprylic acid value chain into parallel certification tracks, forcing suppliers to choose between capital-intensive fractionation upgrades and commodity volume plays. This divergence is compressing margins for undifferentiated producers while creating captive supply relationships for qualified pharmaceutical and nutraceutical buyers.
Growth Catalysts
- EFSA novel food assessments:Accelerated approvals for medium-chain triglyceride formulations in dietary supplements are opening ingestible application pathways previously restricted to technical grades.
- Natural preservative substitution:Food and beverage manufacturers are reformulating away from synthetic antimicrobials toward caprylic acid-derived solutions in clean-label product lines.
- Palm kernel oil concentration in Southeast Asia:Malaysia and Indonesia's dominance in C8-rich feedstock supply is reducing raw material costs for regional fractionation facilities.
Market Restraints
- Coconut oil price volatility:Weather-driven supply disruptions in Sri Lanka and the Philippines create input cost instability for non-palm derived production routes.
- REACH registration burden:Comprehensive toxicological documentation requirements filter out smaller importers from European pharmaceutical-grade markets.
- Medium-chain triglyceride oil substitution:Pre-formulated MCT oils are displacing pure caprylic acid in some ketogenic supplement applications.
Strategic Opportunities
- Clinical ketone body research:Expanding validation of C8 efficacy in cognitive and metabolic health applications is creating new prescription and OTC pharmaceutical demand segments.
- ISO 22000 certification gaps in India:Domestic food manufacturers seeking export qualification represent an underserved technical services market for certification-ready caprylic acid supply.
- Personal care microbiome formulations:Skincare brands are incorporating caprylic acid as a selective antimicrobial that preserves beneficial skin flora.
Industry Challenges
- Fractionation engineering talent scarcity:Specialized fatty acid distillation expertise is concentrated among a limited pool of oleochemical veterans approaching retirement.
- HACCP timeline compression:Accelerated supplier qualification cycles by major food manufacturers are stretching documentation and audit capacities.
- Legacy equipment retrofit costs:Pharmaceutical-grade purity upgrades require stainless steel system replacements that strain mid-cap producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caprylic Acid Market |
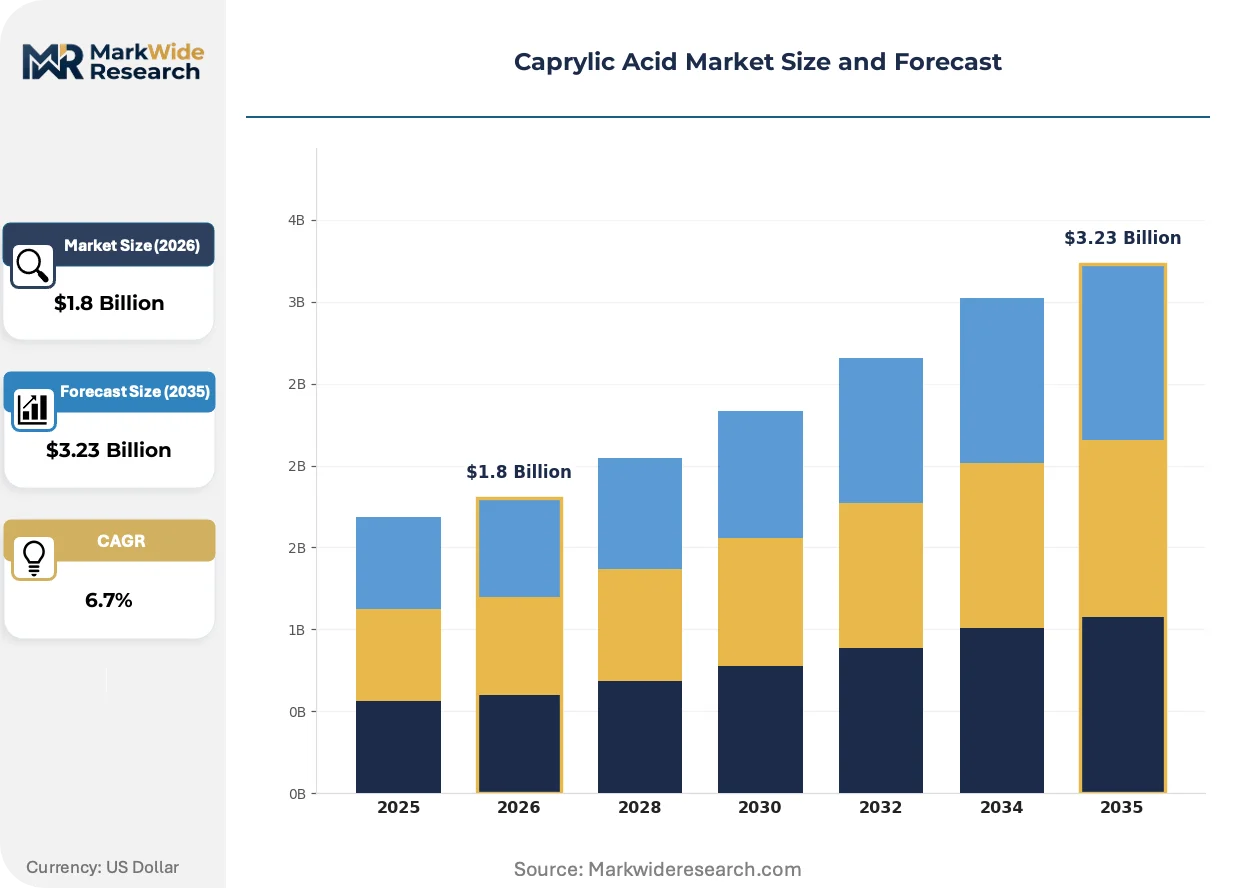
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Emulsions Application: Food & Beverage, Personal Care, Pharmaceuticals, Dietary Supplements End User: Consumers, Manufacturers, Food Businesses, Cosmetic Brands Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Oleon NV, VVF L.L.C., Wilmar International Ltd., Temix Oleo Srl, PT. Ecogreen Oleochemicals, KLK OLEO, Emery Oleochemicals, Pacific Oleochemicals Sdn. Bhd., Musim Mas Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caprylic Acid Market Emerging Trajectories
Enzymatic esterification processes are displacing traditional chemical routes in premium caprylic acid derivative production, enabling lower-temperature processing that preserves heat-sensitive bioactive properties. This technological pivot is reconfiguring capital deployment patterns across the supplier base.
Membrane filtration technology is expanding into caprylic acid purification workflows, replacing energy-intensive fractional distillation for select pharmaceutical-grade outputs. European nutraceutical contract manufacturers are adopting these systems to reduce carbon intensity disclosures under CSRD reporting requirements. The shift is compressing payback periods for sustainability-linked capital investments while creating technology licensing opportunities for filtration equipment suppliers.
REACH authorization amendments for medium-chain fatty acid derivatives are tightening impurity thresholds for reproductive toxicity endpoints. ECHA's revised guidance documents are forcing reformulation of legacy caprylic acid grades used in cosmetic applications. Suppliers serving the European personal care sector are accelerating analytical method upgrades to meet the new substance evaluation criteria.
Direct-to-brand ingredient sourcing is displacing traditional distributor intermediaries in the North American dietary supplement channel. Large contract manufacturers are building qualified supplier lists that bypass regional chemical distributors for volume caprylic acid procurement. This disintermediation is most visible among ketogenic and nootropic brands clustered in Utah and California, where vertical integration between finished goods and raw material sourcing is compressing lead times and certificate-of-analysis verification cycles.
Caprylic Acid Market Segmentation
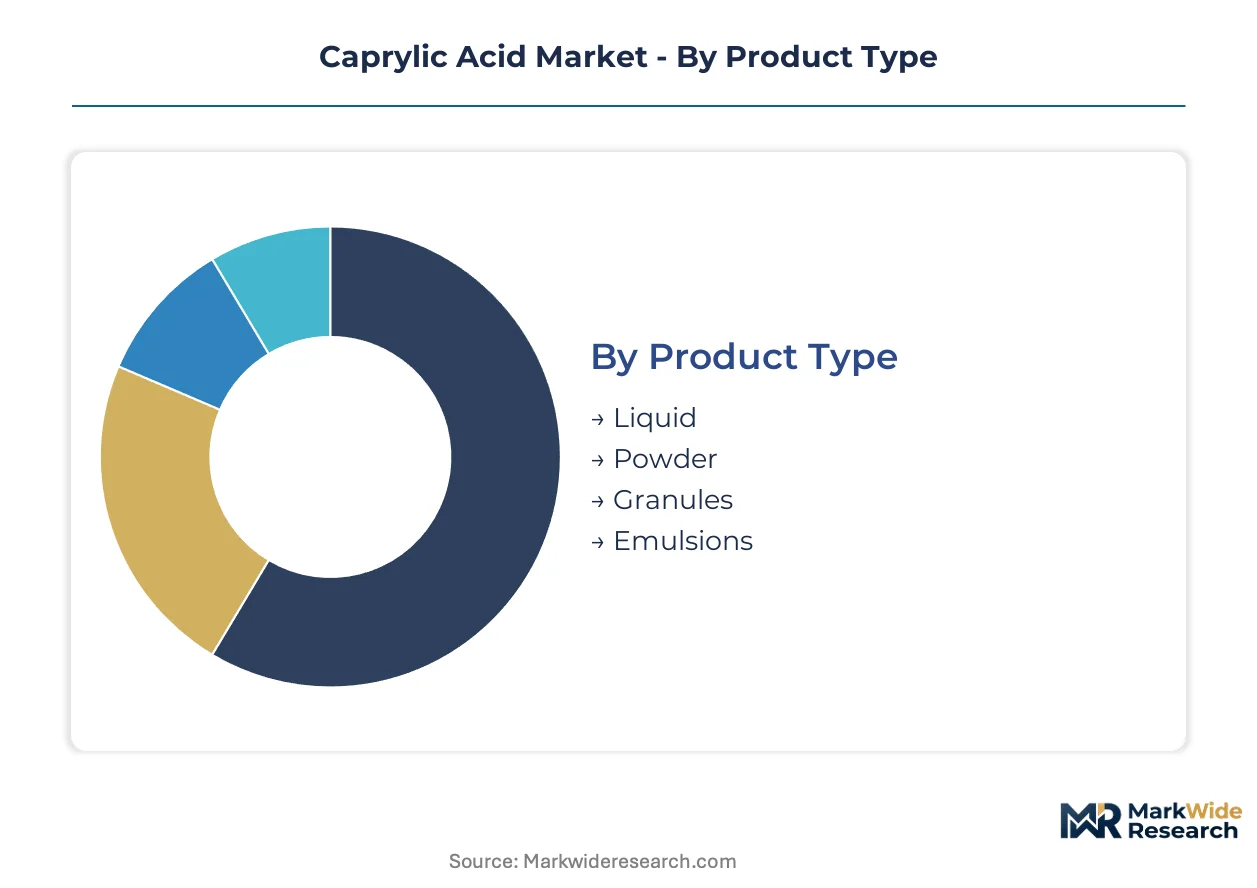
Caprylic acid segmentation reflects divergent purity benchmarks across pharmaceutical, food-grade, and industrial specifications. Each product form and application channel carries distinct regulatory documentation burdens that reshape supplier qualification requirements.
Product Type:
Liquid, powder, granules, and emulsions each demand specific FDA food additive certifications or REACH registrations depending on end-use classification. Pharmaceutical-grade liquid requires EMA-compliant documentation that powder and granule forms for technical applications can bypass.
- Liquid:Dominates current volume flows due to ease of handling in food processing and personal care formulation. Demand concentrates among Southeast Asian palm kernel fractionators serving pharmaceutical and nutraceutical contract manufacturers, driven by enzymatic esterification adoption for heat-sensitive bioactive preservation.
- Powder:Spray-dried or crystalline forms suit dietary supplement encapsulation and dry-mix food applications. Malaysian and Indonesian producers are expanding powder capacity for export to North American ketogenic supplement brands seeking direct-to-manufacturer sourcing relationships.
- Granules:Free-flowing particulate grades target industrial antimicrobial applications and feed additives. CDSCO registration requirements in India filter out non-compliant imports for this specification tier.
- Emulsions:Pre-dispersed aqueous systems reduce formulation complexity for cosmetic microbiome products. European personal care manufacturers favor emulsion forms to meet CSRD carbon intensity disclosure targets through reduced processing energy.
Liquid sits at the top of the volume ranking, with emulsions climbing the fastest.
Application:
Margin structure varies sharply across applications, with pharmaceutical and dietary supplement channels capturing premium pricing over mature food preservative segments.
- Food & Beverage:Natural preservative substitution drives reformulation away from synthetic antimicrobials in clean-label product lines. FDA food additive standards and EFSA novel food assessments govern qualification pathways for caprylic acid suppliers targeting ingestible applications in this mature but steady-demand segment.
- Personal Care:Skincare brands incorporate caprylic acid as a selective antimicrobial preserving beneficial skin flora. REACH authorization amendments for medium-chain fatty acid derivatives are tightening impurity thresholds for reproductive toxicity endpoints in European cosmetic applications.
- Pharmaceuticals:Clinical ketone body research validation creates new prescription and OTC demand segments for C8 efficacy in cognitive and metabolic health.
- Dietary Supplements:Direct-to-brand ingredient sourcing displaces traditional distributor intermediaries in the North American channel, with Utah and California ketogenic brands building qualified supplier lists bypassing regional chemical distributors.
Food & Beverage maintains the largest installed base, though Pharmaceuticals shows the steepest expansion trajectory.
End User:
Procurement sophistication divides end users between specification-driven manufacturers and price-sensitive consumer channels.
- Consumers:Direct purchasers of caprylic acid supplements through e-commerce platforms, typically seeking ketogenic or nootropic benefits with limited technical specification awareness.
- Manufacturers:Contract producers and finished goods makers requiring ISO 22000 and HACCP certifications as baseline market access credentials across major demand centers.
- Food Businesses:Restaurant chains and food service operators adopting caprylic acid-derived natural preservatives for clean-label menu positioning.
- Cosmetic Brands:Skincare and personal care companies targeting microbiome-friendly formulations with selective antimicrobial positioning.
Manufacturers command the highest procurement volumes, while Cosmetic Brands are gaining share fastest.
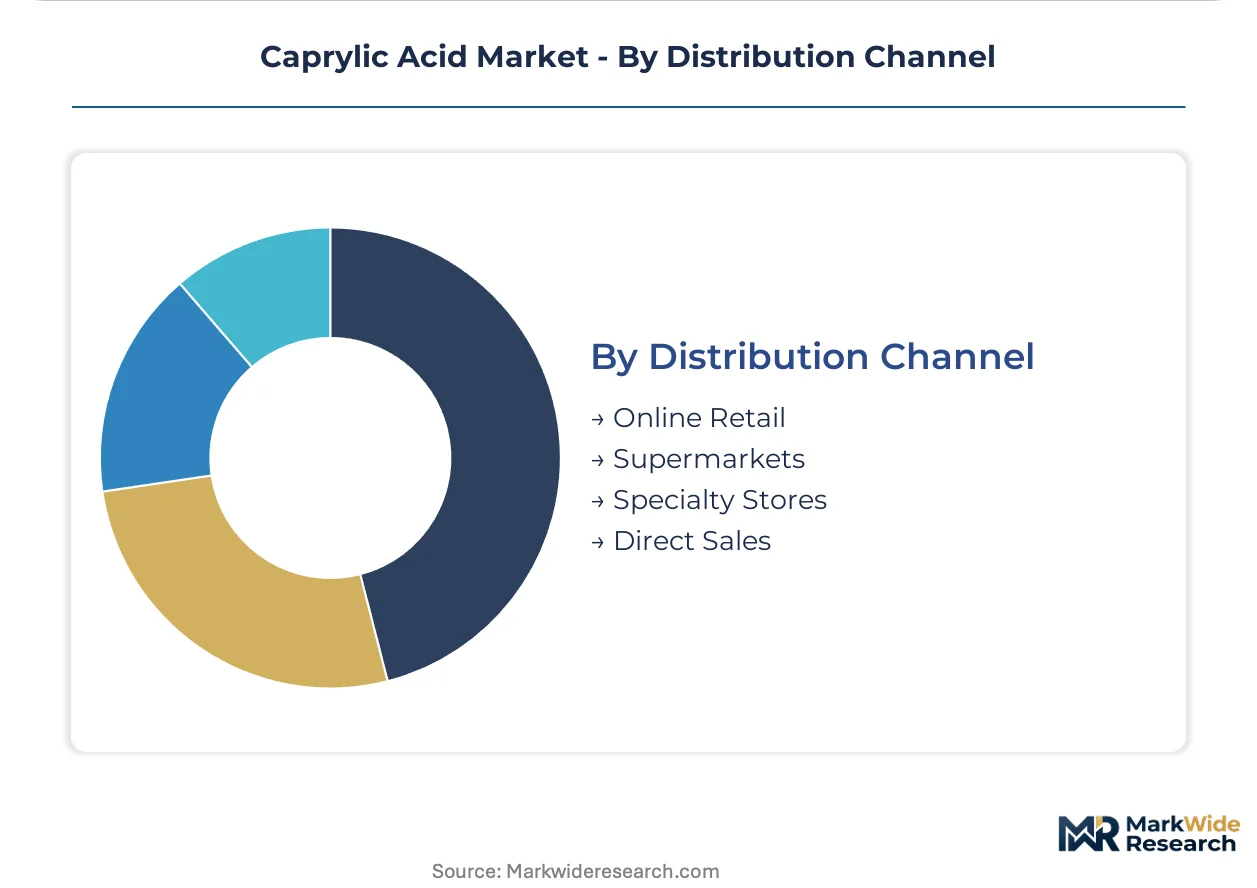
Distribution Channel:
Channel selection determines certificate-of-analysis verification cycles and lead time compression potential.
- Online Retail:E-commerce platforms serve consumer-direct supplement sales with compressed documentation requirements compared to B2B channels.
- Supermarkets:Mass retail placement for finished goods containing caprylic acid preservatives, with retailer-specific supplier qualification protocols.
- Specialty Stores:Health food and beauty retailers curating premium-positioned caprylic acid products for discerning ingredient-conscious buyers.
- Direct Sales:Large contract manufacturers building qualified supplier lists that bypass regional chemical distributors for volume procurement, most visible among Utah and California ketogenic and nootropic brands.
Direct Sales leads volume flows for pharmaceutical and nutraceutical grades, with Online Retail expanding most quickly in consumer supplement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized oleochemical engineering talent concentrates in Belgium and the Netherlands, where fractional distillation expertise anchors European pharmaceutical-grade production. Malaysian and Indonesian palm kernel processing clusters employ the largest regional workforce for C8 fractionation. North American ketogenic supplement formulation draws technical talent to Utah and California contract manufacturing hubs.
United States
Ketogenic and nootropic supplement brands in Utah and California drive pharmaceutical-grade caprylic acid demand through direct-to-manufacturer procurement relationships. FDA food additive standards and dietary supplement cGMP requirements govern qualification pathways for ingestible applications. The Wasatch Front corridor hosts contract manufacturers building qualified supplier lists that bypass traditional chemical distributors.
Malaysia
Palm kernel oil fractionation facilities in Klang Valley and Johor supply C8-rich feedstock for export-oriented caprylic acid production. The country's national pharmaceutical regulator enforces halal certification requirements that filter supply chains for Muslim-majority export markets. Port Klang logistics clusters coordinate bulk liquid shipments to North American and European nutraceutical contract manufacturers.
Indonesia
Sumatra and Kalimantan palm plantations feed Medan-based oleochemical complexes with high-volume C8 fractionation capacity. Ministry of Trade export licensing requirements shape documentation burdens for pharmaceutical-grade shipments to regulated markets. The Medan industrial zone anchors Southeast Asian production gravity for commodity-grade caprylic acid serving regional food preservative applications.
Germany
REACH registration requirements enforce comprehensive toxicological documentation that filters non-compliant caprylic acid imports from European pharmaceutical-grade markets. ECHA's revised guidance on medium-chain fatty acid derivatives tightens impurity thresholds for reproductive toxicity endpoints. The Ruhr industrial corridor hosts oleochemical engineering expertise for stainless steel system upgrades serving premium nutraceutical outputs.
India
Domestic food manufacturers in Maharashtra and Gujarat seek ISO 22000 certification for export qualification, creating technical services demand for certification-ready caprylic acid supply. FSSAI food safety standards and CDSCO registration requirements filter import channels for pharmaceutical and technical grades. The Mumbai-Pune industrial belt concentrates contract manufacturing capacity for personal care microbiome formulations incorporating selective antimicrobial positioning.
Caprylic Acid Market Vendor Landscape
Top-tier vendors anchor pharmaceutical-grade purity segments, while commodity-grade producers compete on palm kernel feedstock access and fractionation scale. The vendor base stratifies across three archetypes: integrated European oleochemical majors, Southeast Asian palm-based fractionators, and specialized nutraceutical-grade refiners. Competitive moves concentrate on enzymatic esterification technology licensing and stainless steel system upgrades for regulatory compliance.
Within the integrated European tier, Oleon NV anchors high-purity output for regulated end uses. Wilmar International and KLK OLEO occupy positions across Southeast Asian palm kernel supply chains, with the former anchoring volume production and the latter exemplifying specialized fatty acid fractionation capabilities. These three entities represent the dominant competitive archetypes: European regulatory compliance leadership, Asian feedstock-integrated scale, and premium nutraceutical specialization.
| Leading Market Players |
|---|
| Oleon NV |
| VVF L.L.C. |
| Wilmar International Ltd. |
| Temix Oleo Srl |
| PT. Ecogreen Oleochemicals |
| KLK OLEO |
| Emery Oleochemicals |
| Pacific Oleochemicals Sdn. Bhd. |
| Musim Mas Group |
| Others |
Supply Flow & Price Mechanics
Specialized fatty acid distillation expertise concentrated in Belgium and the Netherlands commands wage premiums that widen spreads between pharmaceutical-grade and commodity-grade caprylic acid tiers. This workforce scarcity in European fractionation hubs forces buyers to absorb labor-cost differentials through tiered pricing structures.
Pricing Analysis
Bundled certification-and-documentation services separate pharmaceutical-grade quotations from unbundled commodity spot transactions. Three-tier pricing structure across pharmaceutical, food-grade, and technical levels reflects REACH registration burdens and HACCP audit depth. Pricing pressure stems from pre-formulated MCT oils displacing pure caprylic acid in ketogenic supplements. Dietary supplement contract manufacturers show highest price sensitivity, while pharmaceutical buyers accept premiums for EMA-compliant documentation packages.
Supply Chain Analysis
Caprylic acid supply rests on Malaysian and Indonesian palm kernel oil fractionation clusters feeding C8-rich feedstock into global channels. Coconut oil from Sri Lanka and the Philippines provides secondary input routes vulnerable to monsoon disruptions. Single-source vulnerability concentrates in Southeast Asian port logistics, where Port Klang and Medan coordinate bulk liquid shipments. Distribution runs through direct-to-manufacturer procurement relationships displacing traditional chemical distributor intermediaries in North American nutraceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The caprylic acid market functions as a stable compounder anchored by irreversible clean-label reformulation trends in food preservation and validated clinical applications for cognitive health.
For Market Incumbents: Anchor pharmaceutical-grade purity positions through stainless steel system upgrades and captive supply relationships with EMA-compliant documentation capabilities. Defend against MCT oil substitution by deepening clinical ketone body research partnerships. Prioritize enzymatic esterification technology licensing to preserve heat-sensitive bioactive properties for premium nutraceutical outputs. For New Entrants and Emerging Players: Begin with ISO 22000 certification services for Indian food manufacturers seeking export qualification, an underserved technical services market. Target personal care microbiome formulations in European markets where REACH authorization amendments filter legacy suppliers. Pursue direct-to-brand sourcing relationships with Utah and California ketogenic supplement brands bypassing distributor intermediaries. For Investors and Strategic Acquirers: Nutraceutical contract manufacturers are the most active acquirer in this space, seeking backward integration into fractionation capacity. Five-to-ten year viability hinges on clinical validation pipelines for C8 efficacy in metabolic health. Watch EFSA novel food assessment timelines as inflection indicators for ingestible application expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Kernel Fractionation | Captive C8 feedstock supply secures margin control against Malaysian export licensing volatility. |
| Enzymatic Esterification Technology Licensing | Lower-temperature processing preserves bioactive properties for pharmaceutical-grade outputs. |
| REACH Registration Investment | Comprehensive toxicological documentation filters non-compliant imports from European markets. |
| Direct-to-Manufacturer Procurement Relationships | Bypassing distributor intermediaries compresses lead times for Utah and California supplement brands. |
| ISO 22000 Certification Gap Services | Indian food manufacturers seeking export qualification represent underserved technical demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with oleochemical plant managers, pharmaceutical procurement leads, nutraceutical contract manufacturing executives, and personal care R&D directors with secondary validation. Trade data from Malaysian and Indonesian export authorities, ECHA registration databases, FDA food additive filings, and SEC disclosures from listed oleochemical majors anchored supply-side estimates. Bottom-up capacity assessments and top-down demand triangulation converged on segment-level outputs.
Comparable historical periods anchored projections across the analysis window, with modeling spanning product type, application channel, purity grade tier, and regional production hub dimensions. CAGRs derived from segmented growth rate blending and cross-validation against feedstock availability forecasts. Ketogenic supplement formulation trends and EFSA novel food assessment pipelines served as industry-specific demand inputs.
Several conditions sit outside the modeled scope, including weather-driven coconut oil supply disruptions, abrupt REACH authorization amendments, and MCT oil formulation substitution acceleration. Forecasts reflect documented assumptions about clinical research validation timelines and regulatory recategorization pathways. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Bio Based Paraxylene Market
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
Europe Castor Oil Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
Global Basic Chemicals Market
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Granular Urea Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Zinc Chloride Market
Bulk Chemicals
Propionaldehyde Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market
Bulk Chemicals
Trona Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market