
 Sodium Hydrosulfide Market | 2026-2036
Sodium Hydrosulfide Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Hydrosulfide Market Analysis
Continuous improvements in hydrosulfide purification and crystallization technology are reshaping production economics across the sodium hydrosulfide value chain. Nouryon leverages integrated membrane filtration systems to sustain cost leadership in European supply. BASF SE anchors its position through backward integration into sulfur feedstock and captive caustic soda supply. Shandong Aojin Chemical Technology dominates regional export volumes from Shandong Province, while Silox India competes on technical grade specialization for domestic mining customers.
Sodium hydrosulfide (NaHS) is an inorganic salt produced via the reaction of hydrogen sulfide with sodium hydroxide, typically supplied as yellow flakes or aqueous solution with active NaHS content ranging from 70% to 72%. The compound functions primarily as a sulfur source, reducing agent, and flotation depressant across industrial process chemistry. Technical grade material leads volume shipments due to its role in mineral ore flotation circuits, where margin pools concentrate among suppliers with direct mine site delivery capability. Pulp and paper application demand is accelerating fastest as kraft mills substitute sodium hydrosulfide for elemental sulfur in select pulping chemistries. Water treatment end users represent a mature segment with stable offtake tied to municipal utility procurement cycles.
China's MEE enforces GB standards on industrial wastewater sulfide discharge, compelling mining operators to specify higher-purity NaHS with lower residual impurity profiles. REACH registration requirements in Europe restrict non-compliant imports and elevate documentation burdens for Asian exporters serving EU chemical manufacturers. OSHA permissible exposure limits in the United States govern handling protocols and personal protective equipment specifications across sodium hydrosulfide storage and transfer operations. Stakeholders must monitor evolving chemical substance inventories in major jurisdictions to anticipate registration deadlines and reformulation requirements that could redirect trade flows.
Market Dynamics
China's MEE enforcement of GB wastewater standards is forcing mining operators to upgrade from technical-grade to higher-purity sodium hydrosulfide, compressing margin pools for commodity suppliers while rewarding purification-capable producers.
Growth Catalysts
- Kraft pulping substitution:Pulp and paper mills in East China are replacing elemental sulfur with sodium hydrosulfide in select chemistries, expanding addressable volume for flake-grade suppliers with direct mill delivery networks.
- MEE sulfide discharge limits:China's Ministry of Ecology and Environment mandates tighter wastewater sulfide thresholds, compelling mining operators to specify low-impurity NaHS and sustain premium pricing for purified material.
- Membrane filtration scale-up:Integrated membrane systems at European production sites are lowering unit purification costs, enabling competitive export positioning against crystallization-dependent Asian supply.
Market Restraints
- Hydrogen sulfide feedstock volatility:Sodium hydrosulfide production economics hinge on H2S availability from petroleum refining and natural gas processing, exposing margins to upstream hydrocarbon cycle swings.
- Shandong supply concentration:Bulk chemical manufacturing clusters in Shandong Province dominate exportable surplus, creating single-geography risk for buyers dependent on spot market sourcing.
- Elemental sulfur substitution:Mining operators in cost-sensitive jurisdictions retain capability to revert to elemental sulfur in flotation circuits when NaHS premiums exceed operational benefit thresholds.
Strategic Opportunities
- India mining sector penetration:Domestic copper and zinc producers under CDSCO and IBM oversight represent underpenetrated demand for technical-grade flotation reagents with localized blending services.
- Water treatment application expansion:Municipal utilities in coastal Chinese cities are piloting NaHS for heavy metal precipitation, opening stable offtake channels outside cyclical mining demand.
- EU REACH registration tailwind:Full REACH dossier completion creates defensible positioning for compliant Asian exporters against documentation-deficient competitors serving European chemical manufacturers.
Industry Challenges
- H2S handling certification gaps:Mine site operators in developing markets lack trained personnel for toxic gas containment protocols, slowing adoption despite technical suitability.
- Legacy crystallization asset stranding:Producers with sunk investment in batch crystallization trains face capex-intensive retrofit decisions as membrane filtration achieves cost parity at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Hydrosulfide Market |
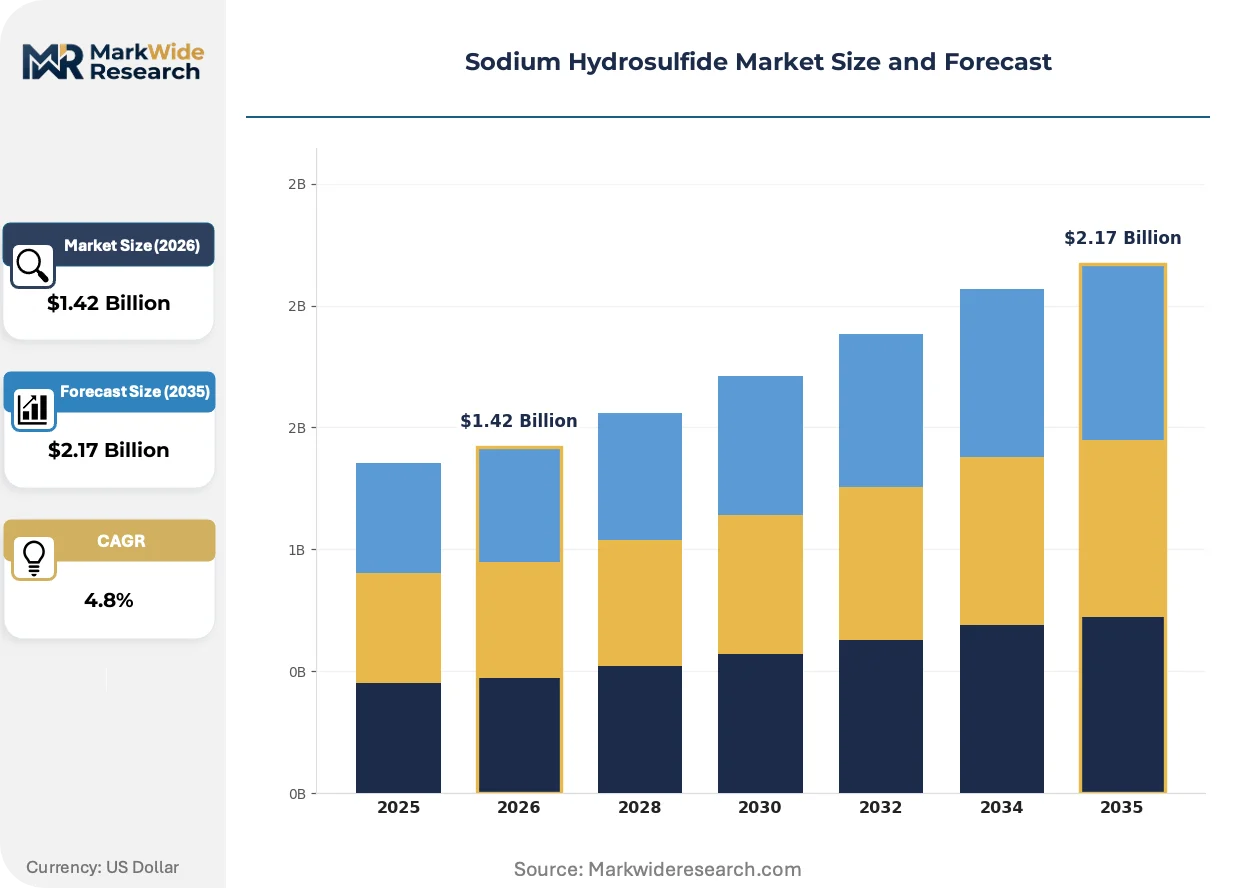
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Analytical Grade, Food Grade, Pharmaceutical Grade Application: Pulp & Paper, Mining, Textile, Water Treatment End User: Chemical Manufacturers, Mining Companies, Textile Manufacturers, Water Utilities Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Silox India, Haihang Industry, Domngying Sanxie, Shandong Aojin Chemical Technology, WEGO CHEMICAL GROUP, Chemical Products Corporation, Nouryon, COTEC, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Hydrosulfide Market Emerging Trajectories
Purification technology advances and regulatory enforcement patterns are restructuring competitive advantage around impurity control capabilities rather than raw capacity scale.
Membrane filtration systems for hydrosulfide purification are collapsing the cost differential between technical and high-purity grades. European producers with integrated membrane trains are capturing kraft mill specifications previously reserved for crystallization-derived material. The technology is collapsing traditional grade-based pricing stratification in pulp and paper procurement.
REACH registration requirements in Europe are elevating documentation burdens for Asian exporters serving EU chemical manufacturers. Non-compliant shipments face port detention and reformulation mandates for downstream users. Specialty chemical distributors in Germany and the Netherlands are consolidating sourcing around dossier-complete suppliers to mitigate regulatory friction.
Direct mine site delivery contracts are displacing distributor-mediated procurement in copper and zinc flotation markets. Large mining operators in Chile and Australia are unbundling reagent supply from equipment service packages, compressing margin capture for integrated suppliers. This pattern is most visible in South American contract structures where volume commitments now separate from technical service retainers.
Sodium Hydrosulfide Market Segmentation
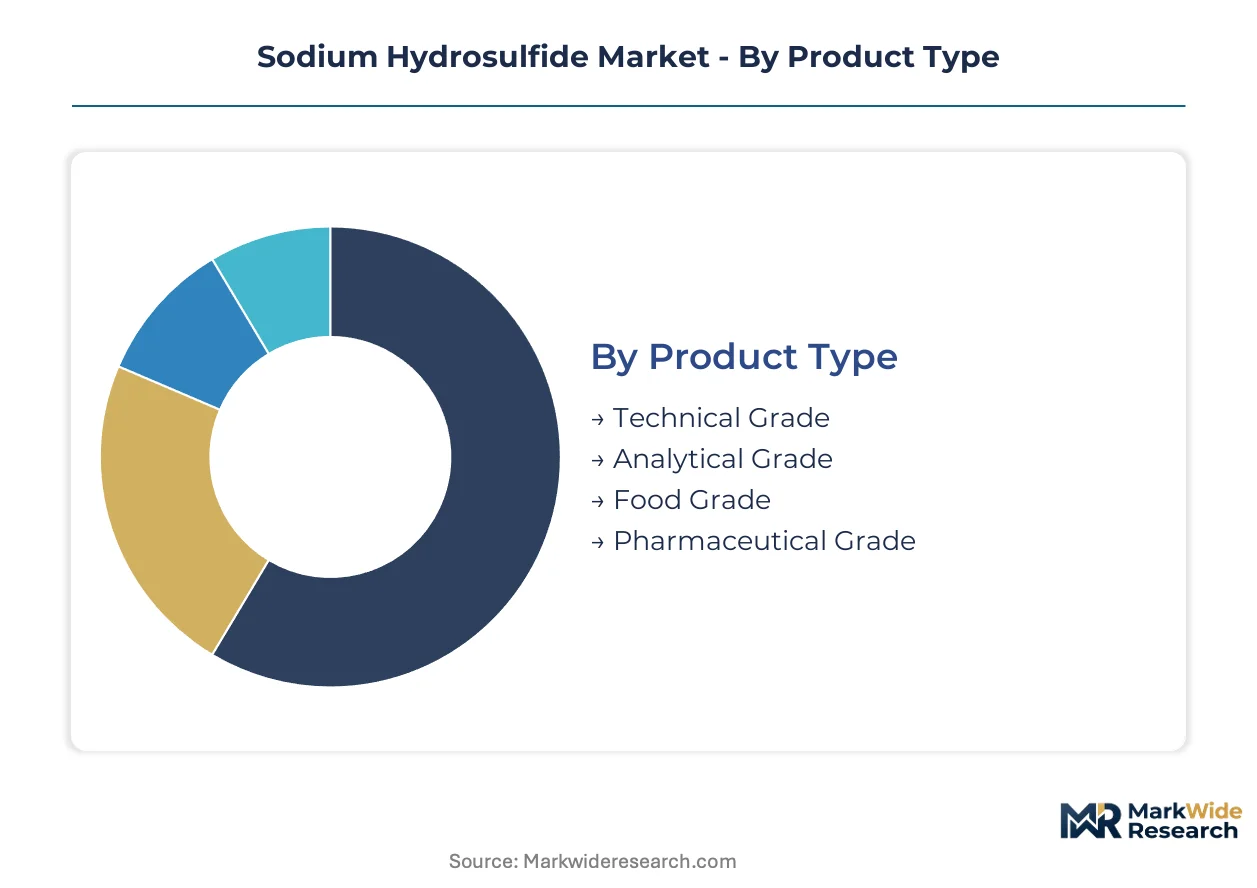
Sodium hydrosulfide procurement cycles vary sharply by purity tier and end-use criticality. Mining operators rotate technical-grade inventory rapidly against volatile metal prices, while pharmaceutical-grade contracts lock in multi-year supply security.
Product Type:
Cycle times compress as purity rises—food and pharmaceutical grades tie to annual certification renewals, while technical grade turns on quarterly mining demand pulses.
- Technical Grade:Yellow flakes or aqueous solution with 70-72% active NaHS content serve mineral ore flotation circuits. Demand concentrates in Shandong Province chemical clusters supplying copper and zinc operations across East China, with MEE wastewater enforcement pushing specification upgrades.
- Analytical Grade:Higher-purity material with controlled impurity profiles supports laboratory reagent and quality control applications. Procurement localizes around Shanghai and Beijing research institute clusters, where GB standard compliance documentation drives supplier selection.
- Food Grade:Refined material meeting additive safety thresholds for leather processing and food-contact applications.
- Pharmaceutical Grade:Ultra-pure NaHS for active pharmaceutical ingredient synthesis and specialized chemical intermediates.
Technical grade dominates installed base. Analytical grade is where expansion concentrates.
Application:
Margin pools stratify by process criticality—pulp and paper applications command premium flake pricing against elemental sulfur substitution economics.
- Pulp & Paper:Kraft mills in East China substitute sodium hydrosulfide for elemental sulfur in select pulping chemistries, requiring consistent flake morphology for digester feed systems. Direct mill delivery networks in Shandong and Jiangsu provinces capture volume against spot market volatility.
- Mining:Copper and zinc flotation circuits consume technical-grade aqueous solution as a sulfur source and flotation depressant. Chilean and Australian mine operators are unbundling reagent supply from equipment service packages, compressing distributor margins.
- Textile:Sulfur dye reduction and leather depilation processes drive stable offtake from integrated textile chemical manufacturers.
- Water Treatment:Municipal heavy metal precipitation pilots in coastal Chinese cities are opening stable procurement channels outside cyclical mining demand.
Mining anchors current volume. Pulp and paper is climbing the fastest.
End User:
Procurement sophistication separates integrated chemical manufacturers from price-sensitive mining procurement desks.
- Chemical Manufacturers:Integrated producers with captive caustic soda and sulfur feedstock leverage backward integration for cost leadership in European and Asian supply.
- Mining Companies:Large copper and zinc operators in Chile and Australia specify direct mine site delivery, displacing distributor-mediated procurement.
- Textile Manufacturers:Sulfur dye houses in India and Bangladesh source through regional chemical distributors with localized blending capability.
- Water Utilities:Municipal procurement cycles in coastal Chinese cities pilot NaHS for heavy metal precipitation, with stable offtake tied to annual budget approvals.
Mining companies dominate current procurement volume. Water utilities represent the steepest expansion trajectory.
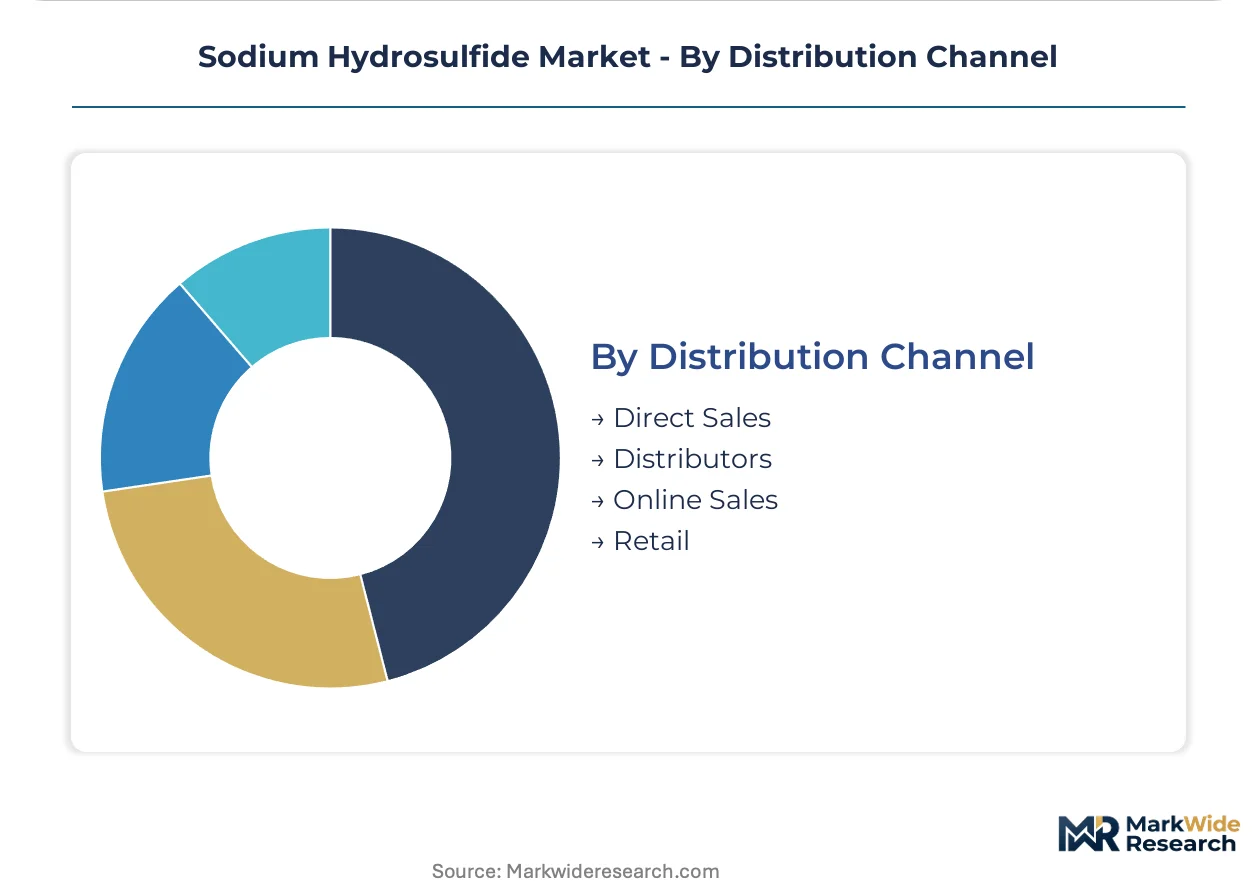
Distribution Channel:
Channel selection tracks shipment scale and technical service requirements—bulk flake moves direct, while small-lot aqueous solution flows through distributor networks.
- Direct Sales:Large-volume flake contracts to kraft mills and mining operators bypass distributor markups, with producers investing in dedicated logistics fleets for H2S containment protocols.
- Distributors:Regional chemical distributors in Germany and the Netherlands consolidate REACH-compliant sourcing for EU manufacturers, mitigating documentation friction.
- Online Sales:Laboratory and small-batch analytical grade procurement migrates to B2B platforms for specification transparency.
- Retail:Limited consumer-facing sales through industrial supply outlets for maintenance and repair applications.
Direct sales dominate value capture. Distributor consolidation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province chemical clusters export bulk sodium hydrosulfide through Qingdao port infrastructure to mining operations in Chile and Australia. East China manufacturing bases supply kraft mills across Jiangsu and Zhejiang provinces.
China
MEE enforcement of GB wastewater sulfide discharge limits compels mining operators to upgrade from technical-grade to purified NaHS. Shandong Province chemical clusters dominate exportable surplus production. Qingdao port infrastructure supports bulk chemical distribution to Australian and Chilean mining customers.
Germany
REACH registration requirements elevate documentation burdens for Asian exporters serving EU chemical manufacturers. Specialty chemical distributors in the Netherlands consolidate sourcing around dossier-complete suppliers. Membrane filtration adoption at production sites enables competitive positioning against crystallization-dependent supply.
United States
OSHA permissible exposure limits govern handling protocols and personal protective equipment specifications across storage and transfer operations. Pulp and paper mills in the Southeast substitute sodium hydrosulfide for elemental sulfur in select pulping chemistries. Gulf Coast petroleum refining provides hydrogen sulfide feedstock for domestic production.
India
Domestic copper and zinc producers under CDSCO and IBM oversight represent underpenetrated demand for technical-grade flotation reagents. Textile sulfur dye houses source through regional chemical distributors with localized blending capability. Maharashtra and Gujarat industrial corridors anchor procurement concentration.
Chile
Large copper operators unbundle reagent supply from equipment service packages, compressing distributor margins. Direct mine site delivery contracts displace spot market sourcing for aqueous solution procurement. Antofagasta and Santiago mining districts drive volume concentration.
Sodium Hydrosulfide Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply configurations. The vendor base separates into integrated chemical manufacturers with captive feedstock, regional export specialists with port-adjacent production, and technical-grade distributors with mine-site delivery capability. Two strategic archetypes dominate: backward-integrated producers leveraging sulfur and caustic soda control, and purification-capable specialists capturing MEE-driven specification upgrades. Competitive moves concentrate on membrane filtration scale-up and direct mill delivery network expansion.
Among European integrated producers, Nouryon anchors the membrane filtration archetype with cost leadership positioning. BASF SE exemplifies backward integration into sulfur feedstock and captive caustic soda supply. Shandong Aojin Chemical Technology occupies the regional export specialist position from Shandong Province, while Silox India represents technical-grade specialization for domestic mining customers.
| Leading Market Players |
|---|
| Silox India |
| Haihang Industry |
| Domngying Sanxie |
| Shandong Aojin Chemical Technology |
| WEGO CHEMICAL GROUP |
| Chemical Products Corporation |
| Nouryon |
| COTEC |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Qingdao port freight corridors anchor sodium hydrosulfide cost structures, with bulk shipping rates from Shandong Province directly shaping margin capture for technical-grade exporters serving Australian and Chilean mining customers. MEE wastewater enforcement compresses pricing power for commodity suppliers while rewarding purification-capable producers with premium positioning.
Pricing Analysis
Cost-plus contracts indexed to caustic soda and hydrogen sulfide feedstock benchmarks dominate long-term offtake agreements between Shandong producers and kraft mill buyers. Price differentiation rests on impurity profiles and GB standard compliance documentation, with purified grades commanding substantial premiums over technical material. Pricing pressure stems from membrane filtration scale-up at European sites collapsing traditional grade-based stratification. Mining procurement desks exhibit highest price sensitivity, while pharmaceutical-grade buyers prioritize supply security over unit cost.
Supply Chain Analysis
Upstream hydrogen sulfide availability from petroleum refining and natural gas processing feeds production economics across China, Germany, and the United States. Sodium hydroxide and elemental sulfur constitute critical raw material dependencies, with caustic soda sourcing patterns varying by regional chlor-alkali capacity. Single-geography concentration in Shandong Province creates vulnerability to port congestion and environmental compliance shutdowns. Distribution runs through direct sales for bulk flake contracts and regional chemical distributors for REACH-compliant EU supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium hydrosulfide sits in early-cycle expansion as kraft pulping substitution and MEE-driven purification upgrades accelerate specification shifts across East China manufacturing bases.
For Market Incumbents: Harden membrane filtration capabilities to defend margin capture against crystallization-dependent competitors facing asset stranding risk. Deepen backward integration into captive caustic soda supply to offset hydrogen sulfide feedstock volatility. Prioritize direct mill delivery network expansion in Jiangsu and Zhejiang provinces before distributor consolidation accelerates. For New Entrants and Emerging Players: Build out localized blending services for Indian copper and zinc flotation circuits, where CDSCO and IBM oversight creates documentation barriers for unqualified exporters. Target Maharashtra and Gujarat industrial corridors with technical-grade aqueous solution supply. Pursue mine site delivery contracts unbundled from equipment service packages to capture margin compression from integrated suppliers. For Investors and Strategic Acquirers: Purification-capable mid-scale producers with REACH dossier completion represent the most defensible acquisition profile in a market restructuring around impurity control. Long-term viability favors suppliers with demonstrated GB standard compliance and membrane filtration deployment. Watch MEE enforcement intensity in Shandong Province as the inflection signal for specification upgrade velocity and premium grade demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Scale-Up | European producers capture kraft mill specifications previously reserved for crystallization-derived material. |
| Backward Integration into Caustic Soda | Captive alkali supply hedges against chlor-alkali cycle swings and secures cost leadership positioning. |
| Direct Mine Site Delivery Networks | Unbundled reagent supply from equipment packages compresses distributor margins in Chilean copper districts. |
| REACH Dossier Completion | Compliant Asian exporters secure defensible positioning against documentation-deficient competitors serving EU manufacturers. |
| GB Standard Certification Investment | MEE wastewater enforcement compels mining operators toward verified low-impurity suppliers with audit documentation. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with plant managers, procurement leads at pulp and mining operators, distribution channel partners, and technical R&D directors; and secondary validation against customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE regulatory disclosures. Bottom-up volume modeling triangulated against top-down market sizing across grade tiers and end-use segments.
Forecast inputs considered capacity expansion timelines, kraft mill substitution rates, and MEE enforcement intensity across the analysis window. Segmentation dimensions modeled include purity grade, application criticality, packaging format, and regional production hub clustering. CAGRs derived from weighted average of demand driver elasticities and supply-side capacity absorption rates, with hydrogen sulfide feedstock availability and membrane filtration adoption curves as key chemical-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by backward-integrated European producers or accelerated MEE shutdowns in Shandong would shift outcomes substantially. Cross-checking against chlor-alkali industry capacity reports and kraft pulp production databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market
Bulk Chemicals
Chlor Alkali Market
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
Banlangen Granules Market
Bulk Chemicals
Rubidium Bromide Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Middle-East and Africa Carbon Black Market
Bulk Chemicals
Tin Fluoborate Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Barium Sulfite Market
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
Furfural Derivatives Market