
 North America Polyvinyl Chloride (PVC) Market | 2026-2036
North America Polyvinyl Chloride (PVC) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polyvinyl Chloride (PVC) Market Analytics
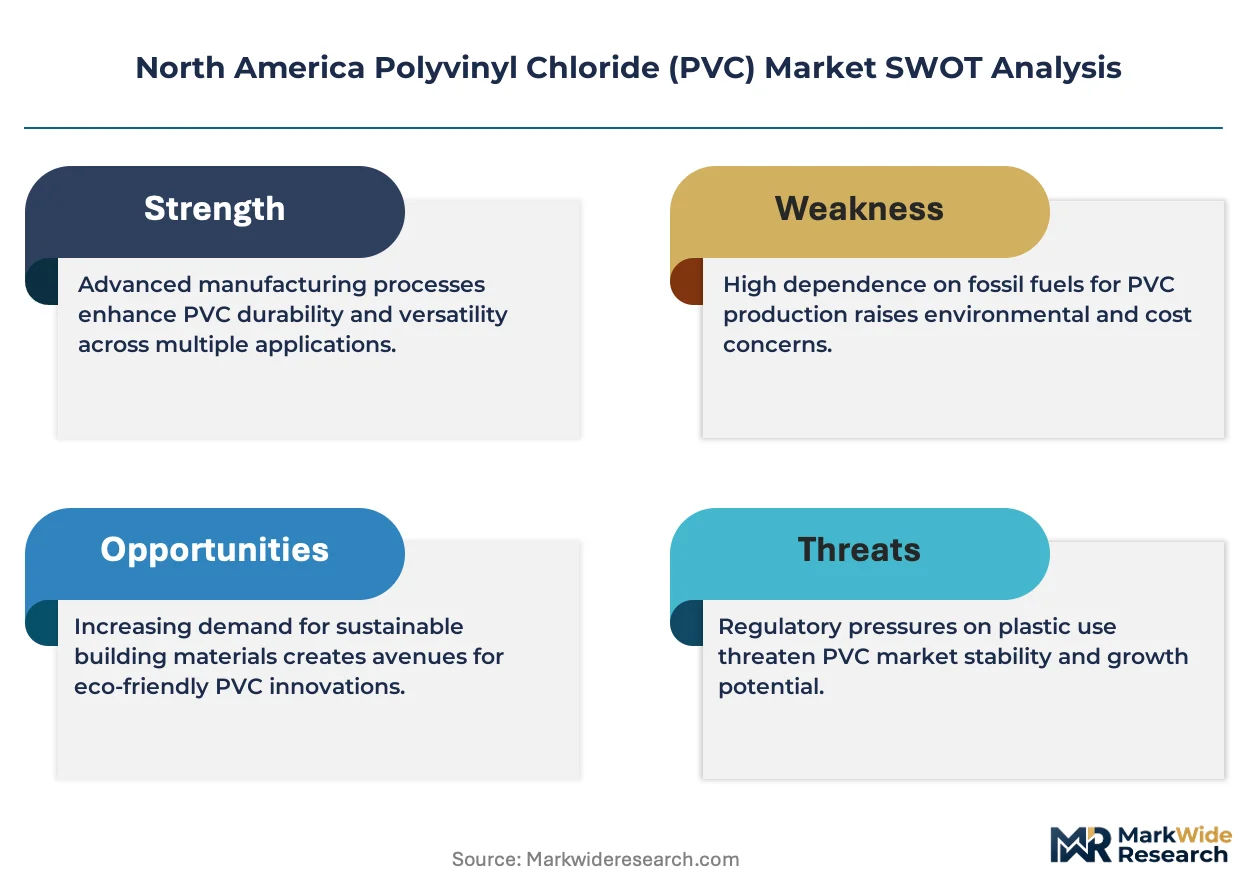
A capital-intensity divergence between integrated chlor-alkali producers and merchant feedstock buyers is reorganizing competitive tiers across the North America PVC landscape. Westlake Corporation leverages its captive ethylene and chlorine supply to sustain margin resilience through feedstock cycles. Formosa Plastics Corporation anchors its position through massive Gulf Coast manufacturing scale, while Orbia differentiates via vertical integration into specialty compounding and distribution networks.
Polyvinyl chloride is a thermoplastic polymer synthesized from vinyl chloride monomer through suspension, emulsion, or bulk polymerization, typically containing 56.7% chlorine by weight and exhibiting flame resistance, chemical stability, and mechanical durability across rigid and plasticized formulations. Its primary commercial purpose centers on durable construction materials, medical devices, automotive components, and electrical insulation requiring long service life. Rigid PVC dominates volume flows through pipe, siding, and window profile applications where structural performance commands premium positioning, while CPVC captures higher-margin opportunities in hot-water plumbing and industrial corrosive environments. Flexible PVC compounds serve automotive interior and healthcare segments where plasticizer selection determines regulatory compliance and end-market access.
The US EPA regulates vinyl chloride monomer emissions under the Clean Air Act National Emission Standards for Hazardous Air Pollutants, while OSHA mandates workplace exposure limits at manufacturing sites, and state-level California Proposition 65 requirements extend to finished product labeling for certain plasticizer chemistries. These overlapping frameworks elevate compliance costs for non-integrated producers while creating technical barriers for imported compounds lacking certified formulation documentation. Stakeholders must monitor evolving state-level building codes and green procurement standards that increasingly specify recycled content thresholds or restricted substance lists affecting material qualification.
Market Dynamics
US EPA emissions standards for vinyl chloride monomer production are forcing capital reallocation across the North America PVC landscape, with integrated chlor-alkali producers capturing structural advantage over merchant feedstock buyers.
Growth Catalysts
- Clean Air Act NESHAP compliance:The US EPA's tightening vinyl chloride monomer emission limits are accelerating plant modernization investments that favor larger, integrated producers with capital reserves.
- Construction sector piping demand:Municipal water infrastructure replacement cycles across the US Gulf Coast and Midwest are sustaining rigid PVC consumption for pressure pipes and storm drainage systems.
- Chlorine-alkali integration economics:Captive chlorine and ethylene supply at Gulf Coast petrochemical complexes is insulating margin structures from feedstock volatility that pressures non-integrated compounders.
Market Restraints
- Ethylene feedstock volatility:Crude oil and natural gas liquid price swings transmit directly to vinyl chloride monomer production costs, compressing margins for merchant buyers lacking long-term supply contracts.
- California Proposition 65 labeling requirements:Restricted substance lists for certain phthalate plasticizers create technical barriers for imported flexible PVC compounds lacking certified formulation documentation.
- Cross-linked polyethylene substitution:PEX piping systems are displacing PVC in residential hot-water plumbing applications where flexibility and freeze-resistance command specification preference.
Strategic Opportunities
- Recycled content mandates:Evolving state-level green procurement standards in California and New York are creating qualified supplier status for compounders with verified post-industrial PVC recycling streams.
- CPVC industrial corrosion applications:Chlorinated PVC formulations for chemical processing equipment represent an underpenetrated segment with premium pricing potential versus standard rigid grades.
- Digital distribution platforms:Specialty compounding customers are migrating toward direct procurement channels that bypass traditional distributor markups for technical grades.
Industry Challenges
- Process control engineering talent scarcity:Vinyl chloride monomer plant operations require specialized expertise in exothermic reactor management that is concentrating among retiring workforces.
- Multi-jurisdiction compliance synchronization:OSHA workplace exposure limits, EPA air standards, and state-level chemical disclosure requirements create overlapping audit obligations.
- Legacy formulation database migration:Decades of uncertified additive recipes must be reconstructed for REACH-equivalent documentation to maintain export qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polyvinyl Chloride (PVC) Market |
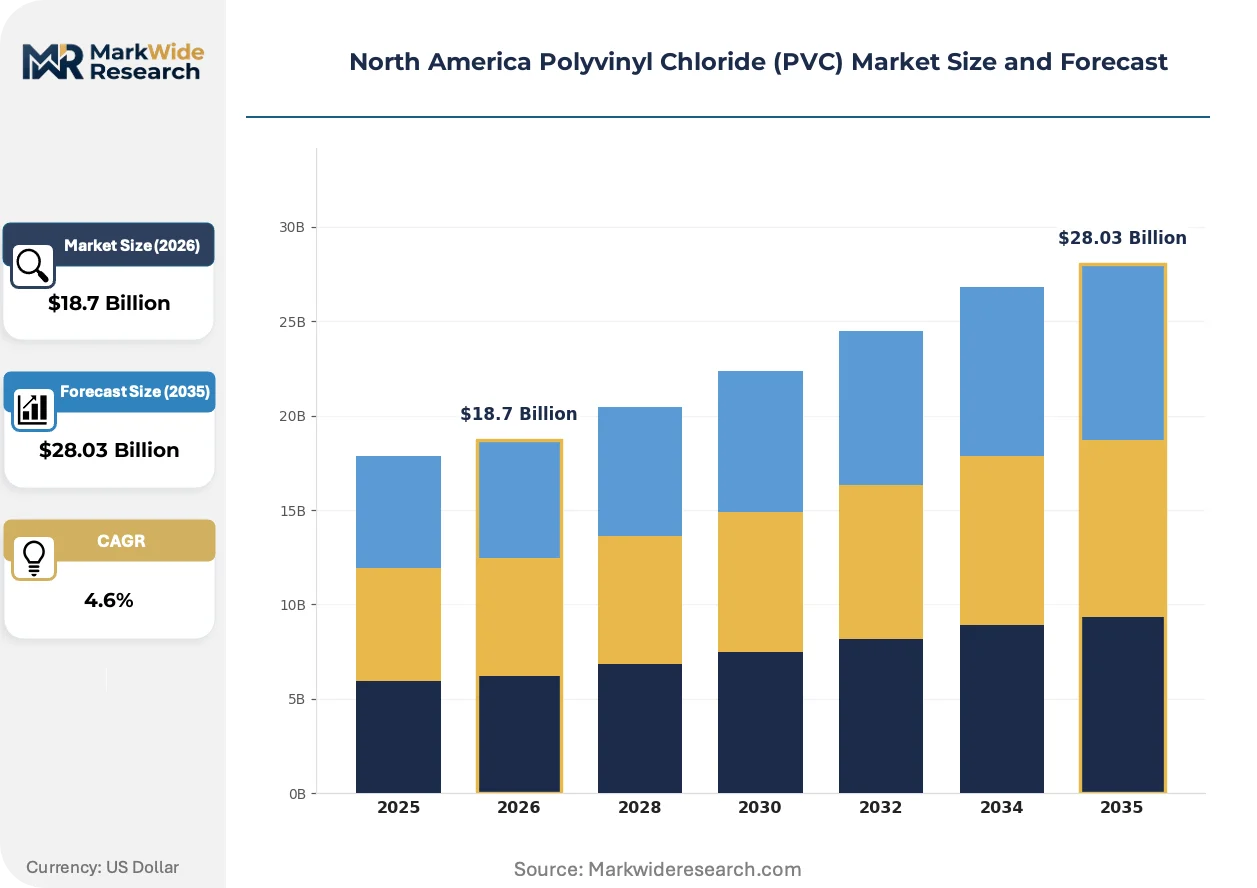
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid PVC, Flexible PVC, CPVC, UPVC Application: Construction, Healthcare, Automotive, Electrical Wiring End User: Manufacturers, Distributors, Contractors, Retailers Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | Westlake Corporation, Formosa Plastics Corporation, Orbia, Shin-Etsu Chemical Co., Ltd., Occidental Petroleum Corporation, INEOS, OxyVinyls, LP, Shintech Inc., The Chemours Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polyvinyl Chloride (PVC) Market Evolving Landscape
Digital formulation tools and bio-based plasticizer chemistries are fragmenting traditional PVC compounding value chains, while regulatory pressure on legacy additives accelerates technical substitution cycles across construction and healthcare end-uses.
Advanced process analytical technology is fragmenting quality assurance protocols in vinyl chloride monomer production. Real-time spectroscopic monitoring systems enable continuous emission compliance verification rather than batch sampling. US Gulf Coast integrated producers are deploying these systems fastest, compressing the compliance cost gap between large and mid-scale facilities.
The US EPA's evolving National Emission Standards for Hazardous Air Pollutants are mandating fenceline monitoring and community air quality disclosure for vinyl chloride monomer plants. This regulatory architecture is elevating capital requirements for emission control retrofits. Smaller non-integrated producers in Texas and Louisiana are consolidating or idling capacity rather than absorbing compliance investments.
Specification-driven procurement is consolidating buyer power among large construction contractors and municipal utilities. These entities are unbundling compound supply from fabrication services, forcing compounders to certify recycled content percentages and restricted substance compliance directly. The shift is most visible in California public works bidding where green procurement scoring determines contract awards.
North America Polyvinyl Chloride (PVC) Market Segmentation
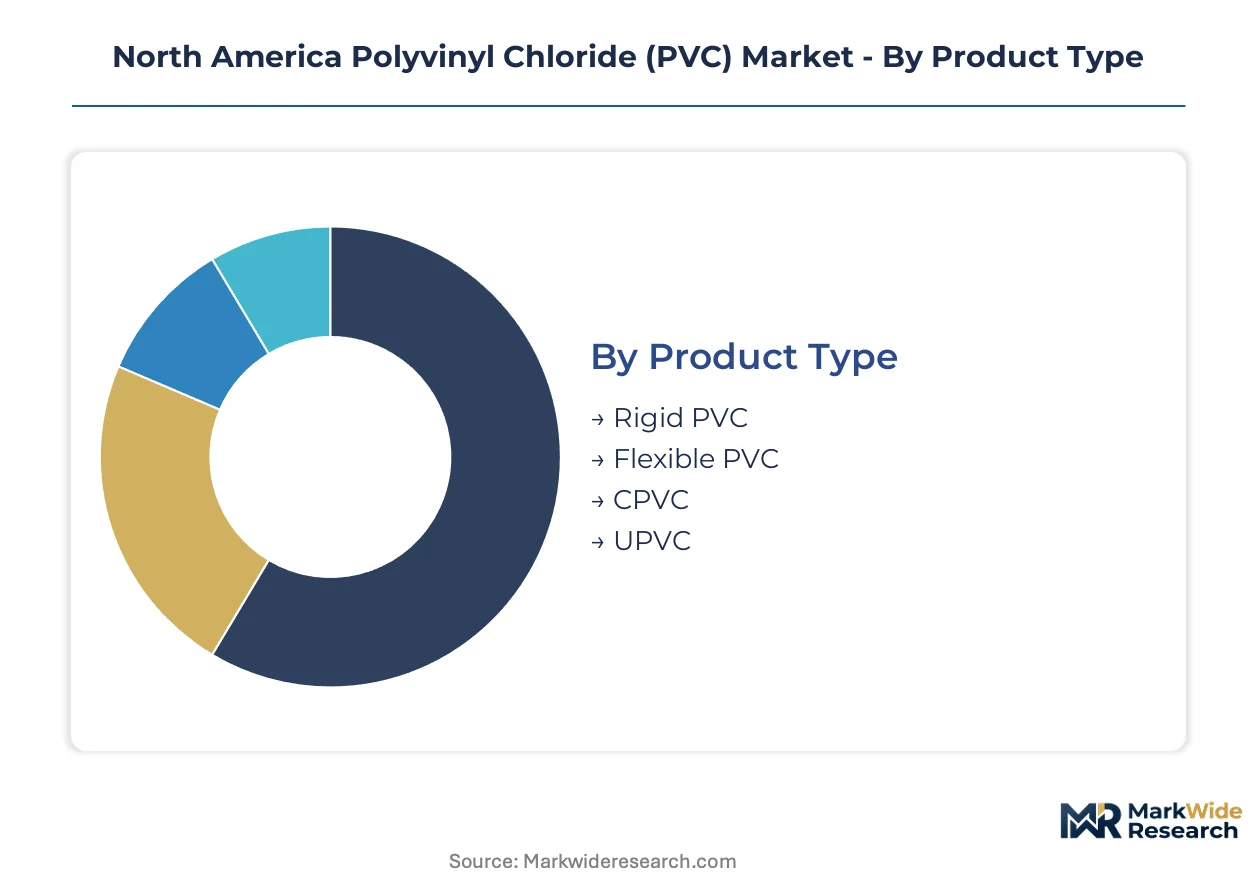
Segmentation in North American PVC markets reveals how formulation chemistry, application requirements, and procurement channels intersect to create distinct commercial battlegrounds. Each dimension carries implications for margin structure, compliance burden, and competitive positioning.
Product Type:
Channel mix varies sharply across product types, with rigid PVC flowing heavily through construction distributors while specialty compounds favor direct technical sales.
- Rigid PVC:Unplasticized formulations contain 56.7% chlorine by weight, delivering structural rigidity for pressure-bearing applications. Demand concentrates in municipal water infrastructure across Texas and Louisiana, where the US EPA's NESHAP compliance costs favor large integrated producers with captive chlorine supply.
- Flexible PVC:Plasticized compounds incorporate phthalate or bio-based alternatives to achieve Shore A hardness ratings from 60-90. Automotive interior and medical tubing specifications in California drive demand, though Proposition 65 labeling requirements for certain plasticizer chemistries create technical barriers for uncertified imports.
- CPVC:Chlorinated variants achieve higher heat distortion temperatures for hot-water plumbing and industrial corrosion environments.
- UPVC:Unplasticized grades serve window profiles and siding where weathering resistance commands premium positioning.
By volume, rigid PVC leads. By growth pace, CPVC is expanding most quickly.
Application:
Cost tier differentiation separates specification-grade medical and electrical applications from commodity construction volumes.
- Construction:Piping, siding, and window profiles consume the majority of regional PVC volume. Municipal infrastructure replacement cycles across the US Gulf Coast and Midwest sustain demand for pressure pipes and storm drainage systems.
- Healthcare:Medical-grade compounds require FDA-compliant plasticizers and extractables testing. Blood bags, tubing, and IV components demand certified formulation documentation that non-integrated compounders struggle to provide.
- Automotive:Interior trim and underhood applications specify low-VOC emissions and fogging resistance. OEMs are migrating toward direct procurement channels that bypass traditional distributor markups.
- Electrical Wiring:Insulation and jacketing compounds must meet UL flame-resistance standards. Wire and cable manufacturers prioritize suppliers with verified post-industrial recycling streams to satisfy green procurement scoring.
Construction generates the largest revenue pool. Healthcare commands the steepest pricing premium.
End User:
Customer type determines whether procurement emphasizes technical service, logistics reliability, or price minimization.
- Manufacturers:Compounders and fabricators with in-house extrusion or molding capability require consistent melt-flow indices and lot-to-lot uniformity. These buyers negotiate long-term supply contracts with integrated Gulf Coast producers.
- Distributors:Regional and national distribution networks stock standard grades for construction contractors. Inventory carrying costs and working capital requirements favor larger distributors with balance sheet capacity.
- Contractors:Installation-focused buyers prioritize availability and delivery speed over formulation customization.
- Retailers:Big-box and specialty retailers serve DIY and small contractor segments with pre-cut dimensional products.
Manufacturers capture the deepest volume discounts. Distributors are gaining share fastest as specification unbundling accelerates.
Distribution Channel:
Supply concentration in the Gulf Coast petrochemical corridor shapes logistics economics across all channels.
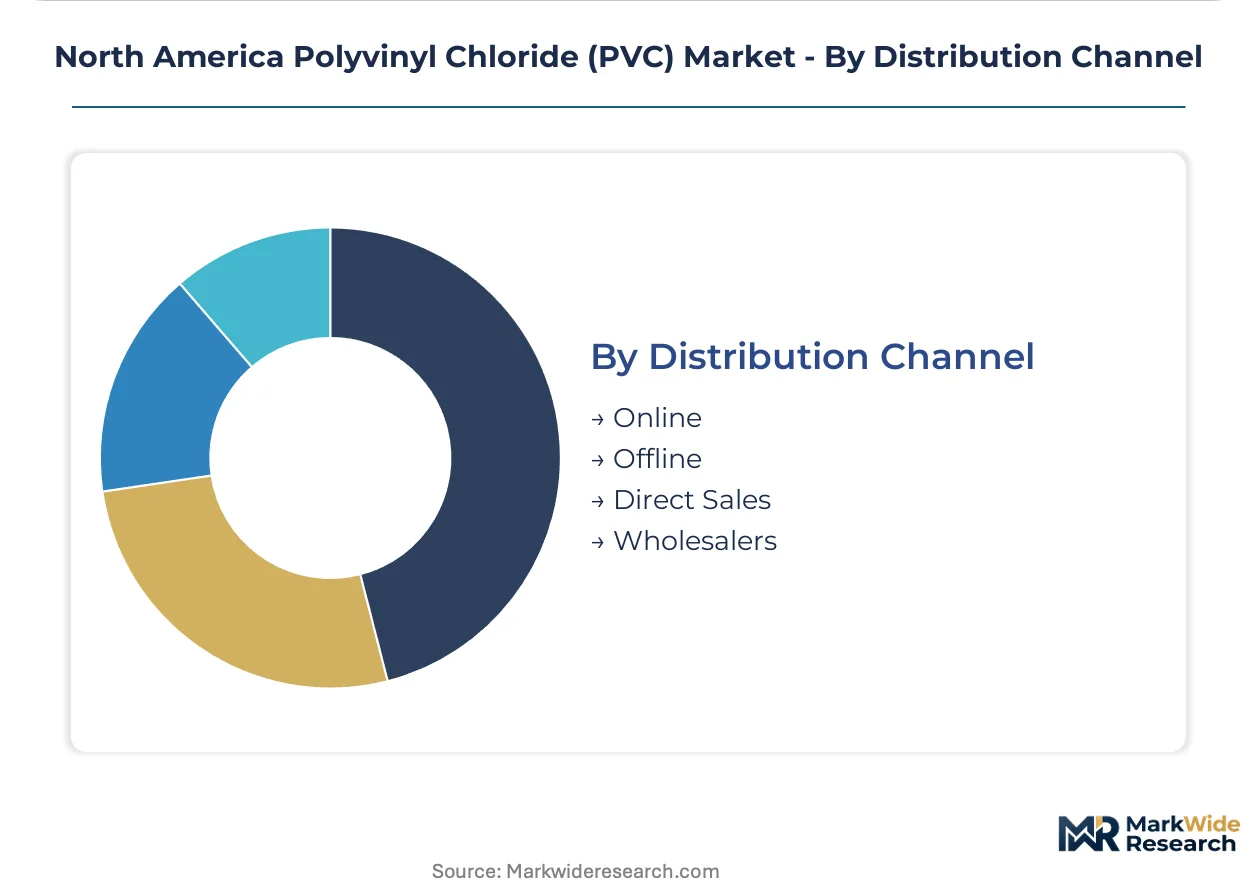
- Online:Digital platforms are fragmenting traditional distribution for specialty technical grades. Direct procurement portals enable compounders to certify recycled content and restricted substance compliance without intermediary documentation gaps.
- Offline:Bricks-and-mortar distribution remains dominant for construction-grade rigid PVC where immediate availability and local technical support command premium positioning.
- Direct Sales:Large municipal utilities and construction contractors are unbundling compound supply from fabrication services, forcing direct relationships with compounders.
- Wholesalers:Regional wholesalers aggregate fragmented contractor demand but face margin compression as digital alternatives proliferate.
Offline channels still handle the largest tonnage. Online is climbing the fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across North American PVC demand pools. Municipal utilities negotiate multi-year supply contracts with rigid volume commitments, while specialty medical compounders absorb premium pricing for certified formulations without volume elasticity.
United States
The US Gulf Coast petrochemical corridor hosts the densest concentration of integrated chlor-alkali-PVC capacity. EPA's National Emission Standards for Hazardous Air Pollutants for vinyl chloride monomer production are forcing capital-intensive plant retrofits that favor larger producers with balance sheet depth. Texas and Louisiana facilities are deploying real-time fenceline monitoring systems to satisfy community disclosure mandates ahead of smaller competitors.
Canada
Infrastructure replacement cycles in Ontario and Quebec sustain steady demand for pressure pipe and window profile grades. Health Canada's regulatory alignment with US FDA standards for medical-grade compounds simplifies cross-border qualification, though domestic fabrication capacity remains limited compared to US Gulf Coast scale. Alberta's petrochemical expansion projects are evaluating downstream PVC integration to capture chlorine value from oil sands byproduct chemistry.
Mexico
Construction activity in Mexico City and Monterrey drives consumption of rigid grades for drainage and electrical conduit applications. The country's national environmental regulator has begun harmonizing industrial air emission standards with US EPA frameworks, elevating compliance costs for legacy compounding facilities. Querétaro's automotive manufacturing cluster is generating specification-grade demand for low-VOC interior compounds.
North America Polyvinyl Chloride (PVC) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in North American PVC supply. Three to four Gulf Coast producers with captive chlorine and ethylene supply control the majority of commodity rigid volume, while mid-scale compounders compete for specialty medical and automotive grades. Strategic differentiation runs through backward integration depth, formulation certification capability, and recycling stream verification. Capacity consolidation and direct procurement channel development represent the dominant competitive vectors reshaping vendor-customer relationships.
Within the integrated producer tier, Westlake Corporation and Formosa Plastics Corporation exemplify scale-driven positioning anchored in Gulf Coast manufacturing density. Orbia occupies a position bridging commodity supply with specialty compounding and distribution network control. These three entities represent distinct archetypes: captive feedstock integration, massive single-site scale, and vertical network reach into technical grades and recycling infrastructure.
| Leading Market Players |
|---|
| Westlake Corporation |
| Formosa Plastics Corporation |
| Orbia |
| Shin-Etsu Chemical Co., Ltd. |
| Occidental Petroleum Corporation |
| INEOS |
| OxyVinyls, LP |
| Shintech Inc. |
| The Chemours Company |
| Others |
Value Network & Pricing Analysis
Sixty-day resin inventory cycles at Gulf Coast terminals signal how captive chlorine-alkali integration concentrates pricing power among integrated producers while forcing merchant buyers into volatile spot markets. This lead-time band reveals the structural asymmetry between feedstock-secure incumbents and compounders exposed to ethylene cost swings.
Pricing Analysis
After-sales technical service and certified formulation documentation drive lifetime value differentiation across customer tiers. Three-tier pricing structure across specification-grade medical compounds, certified construction grades, and commodity rigid PVC reflects divergent compliance burdens and volume scales. Cost compression in flexible compounds is intensifying because California Proposition 65 labeling requirements disqualify uncertified imports. Municipal utilities demonstrate lowest price sensitivity through multi-year offtake contracts, while construction distributors face margin erosion from digital procurement alternatives.
Supply Chain Analysis
The United States anchors vinyl chloride monomer production through Gulf Coast petrochemical complexes, while Canada and Mexico host downstream compounding and fabrication capacity. Chlorine from chlor-alkali operations, ethylene from steam crackers, and specialty plasticizers from merchant chemical producers constitute critical input dependencies. Single-source vulnerability concentrates around Louisiana-Texas corridor infrastructure exposed to hurricane disruption. Distribution runs through construction-grade distributors for commodity volumes and direct technical sales for medical and automotive specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized process control engineering for exothermic reactor management is concentrating among retiring workforces, creating capability scarcity that threatens operational continuity at mid-scale facilities. This talent gap favors incumbents with structured knowledge transfer programs and disadvantages entrants lacking apprenticeship pipelines.
For Market Incumbents: Consolidate through selective acquisition of distressed non-integrated compounders facing EPA NESHAP retrofit burdens, while deepening captive chlorine-alkali integration to insulate margin structures from ethylene volatility. Prioritize real-time fenceline monitoring deployment to satisfy community disclosure mandates ahead of regulatory deadlines. Channel control through direct procurement portal development defends position against distributor disintermediation. For New Entrants and Emerging Players: Anchor in CPVC industrial corrosion applications where specification complexity and premium pricing create defensible positioning against commodity rigid PVC competition. Target Querétaro automotive manufacturing clusters with low-VOC interior compound formulations bypassing established distributor relationships. Digital-native direct sales models enable rapid customer acquisition without legacy infrastructure investments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking portfolio simplification away from emissions-intensive vinyl chloride monomer operations. Five-to-ten year viability hinges on regulatory compliance cost absorption capacity and recycling infrastructure positioning. Monitor EPA enforcement action intensity against smaller Louisiana and Texas facilities as consolidation inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Capacity | Captive chlorine supply insulates margin structures from merchant feedstock volatility cycles. |
| Real-Time Fenceline Monitoring Deployment | Continuous emission verification satisfies EPA NESHAP disclosure mandates ahead of competitor compliance. |
| Post-Industrial Recycling Stream Certification | Verified recycled content qualifies compounders for California and New York green procurement scoring. |
| Direct Procurement Platform Development | Digital channels bypass distributor markups while capturing specification-grade customer relationships. |
| CPVC Formulation Technical Investment | Chlorinated PVC industrial applications command premium positioning in chemical processing equipment markets. |
Research Methodology
A standing panel of vinyl chloride monomer plant managers, construction distributor procurement leads, automotive OEM material engineers, and EPA regulatory affairs specialists provided ongoing calibration against operational realities. Primary interview insights combined with secondary validation from US EPA enforcement databases, ACC industry statistics, SEC 10-K filings, and customs trade records. Bottom-up volume modeling across grade tiers and top-down macroeconomic triangulation ensured convergent estimates.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, distribution channel structure, and regional production hub clustering. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and feedstock cost regime shifts. Vinyl chloride monomer capacity utilization rates and construction sector procurement contract durations served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained EPA enforcement intensity and Gulf Coast infrastructure resilience assumptions; material deviation would warrant model refresh. Specific risk factors include accelerated PEX substitution in residential plumbing, state-level recycled content mandate adoption timelines, and chlorine-alkali capacity retirement decisions. Recalibration cycles align with material shifts in Clean Air Act implementation schedules and ethylene feedstock cost regimes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
Crude Tall Oil Derivative Market
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Global Persulfates Market
Bulk Chemicals
2-Ethylhexanoyl Chloride Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
Rubidium Bromide Market
Bulk Chemicals
Trona Market
Bulk Chemicals
Sodium Selenite Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
White Charcoal Powder Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
North America Lactic Acid Market
Bulk Chemicals
Benzyl Chloroformate Market