
 Antipyretic Analgesic Active Pharmaceutical Ingredients Market | 2026-2036
Antipyretic Analgesic Active Pharmaceutical Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Antipyretic Analgesic Active Pharmaceutical Ingredients Market Insights
Consolidation among generic drug manufacturers is realigning procurement patterns for antipyretic analgesic APIs toward fewer, larger-volume contracts. Granules India Limited leverages its vertically integrated paracetamol operations to sustain cost leadership across regulated markets. BASF anchors European supply through specialized ibuprofen production with advanced continuous processing capabilities. IOL Chemicals and Pharmaceuticals dominates Indian acetylsalicylic acid output through backward integration into phenol-based feedstocks.
Antipyretic analgesic active pharmaceutical ingredients comprise synthetic organic compounds—primarily paracetamol, acetylsalicylic acid, ibuprofen, and naproxen—manufactured through multi-step chemical synthesis with specified pharmacopeial purity thresholds exceeding 99.0% and tight limits on genotoxic impurities per ICH M7 guidelines. These APIs serve as the functional core of oral and parenteral dosage forms targeting cyclooxygenase enzyme inhibition for fever reduction and pain management across prescription and over-the-counter channels. Paracetamol commands the largest production volume globally, while ibuprofen generates superior margin pools in regulated markets demanding advanced impurity control and DMF documentation. The pain relief application segment absorbs the majority of API volumes, though postoperative care formulations are gaining share as ambulatory surgical protocols expand multi-modal analgesia requirements.
FDA enforcement of enhanced elemental impurity limits under ICH Q3D and EMA's tightened nitrosamine risk assessments are elevating compliance costs for API exporters targeting US and European formulation clients. China's NMPA has aligned domestic GMP standards with PIC/S requirements, pressuring smaller Shandong and Hebei producers to consolidate or exit. India's CDSCO and state FDA inspectors are intensifying pre-approval facility audits for paracetamol manufacturers seeking export registration. Stakeholders must monitor evolving pharmacopeial monograph revisions and regulator data integrity expectations as determinants of supply contract eligibility.
Market Dynamics
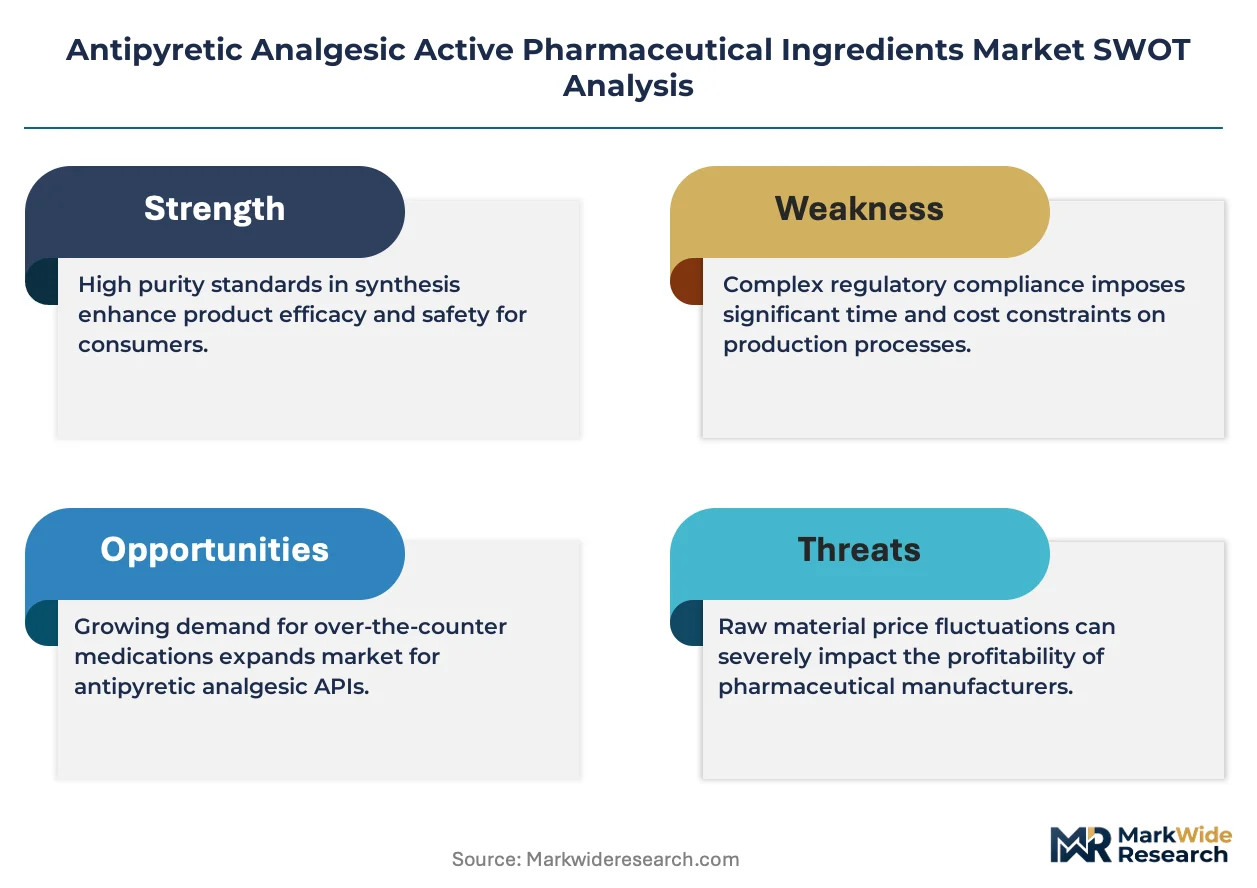
Consolidation among generic drug manufacturers is compressing supplier bases toward fewer, larger-volume contracts for paracetamol and ibuprofen APIs, while ICH Q3D impurity mandates force capital-intensive quality system upgrades across manufacturing networks.
Growth Catalysts
- OTC Channel Expansion:Retail pharmacy chains in India and China are scaling direct-to-consumer pain relief portfolios, pulling additional API volumes through formulation subsidiaries.
- ICH M7 Compliance:Genotoxic impurity assessment protocols are differentiating qualified suppliers from marginal producers, concentrating procurement among DMF-holding manufacturers.
- Ambulatory Surgical Protocols:Multi-modal analgesia requirements in same-day discharge settings are expanding demand for combination APIs in postoperative care formulations.
Market Restraints
- Phenol Feedstock Volatility:Acetylsalicylic acid production costs fluctuate with benzene derivative pricing, compressing margins for non-integrated manufacturers.
- Shandong-Hebei Supply Concentration:China's NMPA-aligned GMP standards are forcing smaller producers to consolidate, creating near-term supply tightness during transition periods.
- Nitrosamine Detection Thresholds:EMA's tightened risk assessments impose additional analytical burden and timeline uncertainty on batch release for European-bound exports.
Strategic Opportunities
- Latin American Formulation Partnerships:ANVISA-registered API supply contracts remain underpenetrated relative to patient population scale in Brazil and Mexico.
- Continuous Processing Adoption:Advanced flow chemistry integration offers step-change efficiency gains for ibuprofen synthesis, rewarding early capital deployers.
- PLI Scheme Alignment:India's production-linked incentive framework for bulk drugs subsidizes greenfield paracetamol capacity with export obligation structures.
Industry Challenges
- Analytical Chemistry Talent Scarcity:ICP-MS and LC-HRMS expertise for elemental impurity quantification commands premium compensation, constraining QC expansion timelines.
- Legacy DMF Migration Complexity:Converting paper-based drug master files to CTD-eCTD formats for FDA submission creates documentation bottlenecks for mid-tier exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antipyretic Analgesic Active Pharmaceutical Ingredients Market |
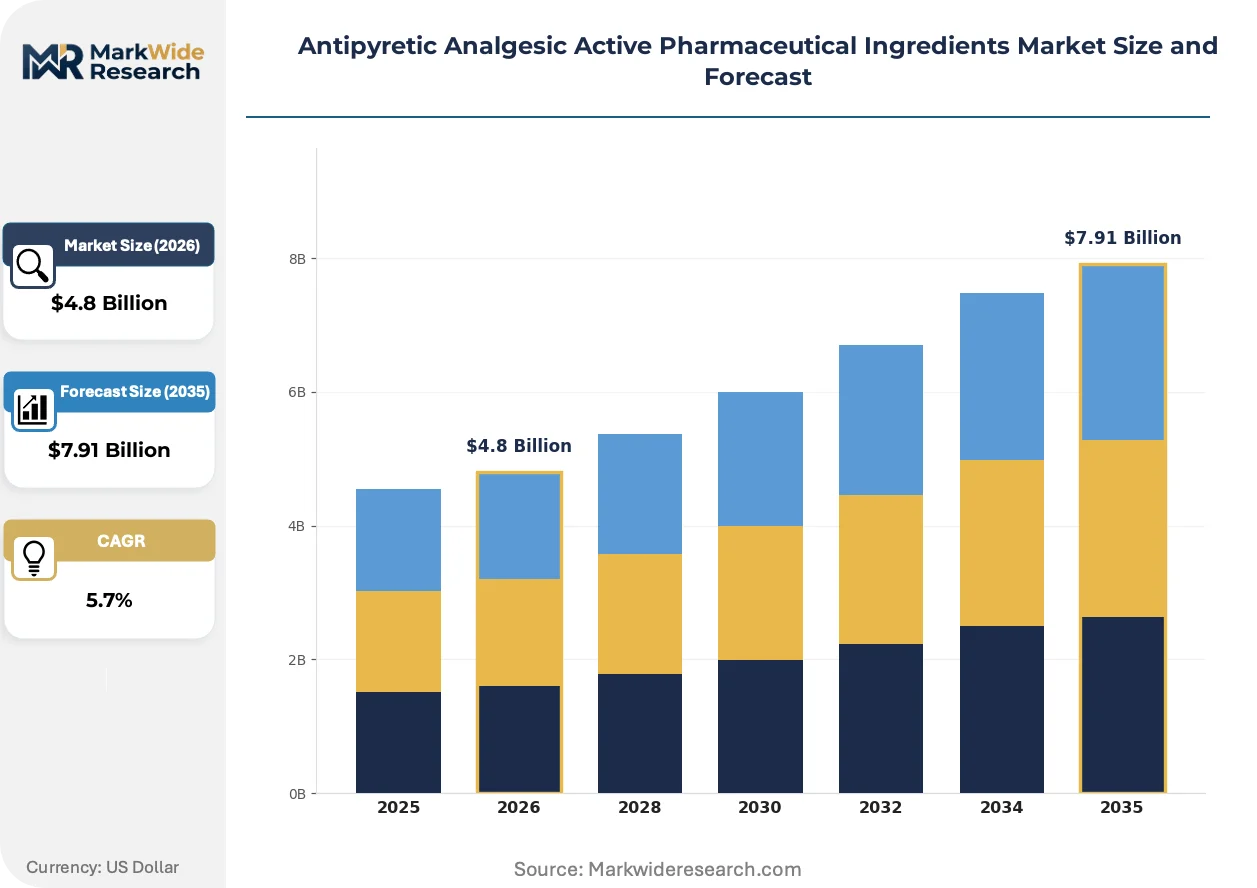
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paracetamol, Acetylsalicylic Acid, Ibuprofen, Naproxen Application: Fever Management, Pain Relief, Inflammation Control, Postoperative Care Form: Tablet, Liquid, Granule, Suppository End User: Hospitals, Clinics, Pharmacies, Home Care |
| Companies Covered | Mallinckrodt Pharmaceuticals, Granules India Limited, BASF, Anqiu Lu'an Pharmaceutical, IOL Chemicals and Pharmaceuticals, Anhui BBCA Pharmaceuticals, Novacyl, Hebei Jiheng Pharmaceutical, Zhejiang Kangle Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antipyretic Analgesic Active Pharmaceutical Ingredients Market Trends and Innovations
Process intensification and regulatory data integrity mandates are reshaping competitive advantage in antipyretic analgesic API manufacturing, favoring capital-rich operators with integrated quality systems over fragmented toll manufacturers.
Continuous flow reactor technology is unifying reaction, separation, and crystallization steps into single-unit operations for ibuprofen synthesis. BASF and select Indian producers are deploying these systems to compress batch cycle times and reduce solvent inventory exposure. The structural consequence is unifying capital efficiency with impurity profile consistency, squeezing batch-process competitors on cost and compliance simultaneously.
EMA's nitrosamine risk assessment framework is mandating retrospective evaluation of all chemically synthesized APIs for potential contamination pathways. Formulation clients in Germany and France now require enhanced supplier declarations and analytical certificates beyond standard pharmacopeial compliance. Small molecule API exporters are responding by investing in dedicated nitrosamine testing capabilities or risk losing qualified supplier status.
Hospital procurement consortia are consolidating antipyretic analgesic purchases under framework agreements with single-source API-qualified formulation partners. This channel compression is displacing spot-market purchasing for generic paracetamol injectables in Western European markets. The shift is most visible in Germany and the Netherlands, where hospital pharmacy centralization has advanced furthest.
Antipyretic Analgesic Active Pharmaceutical Ingredients Market Segmentation
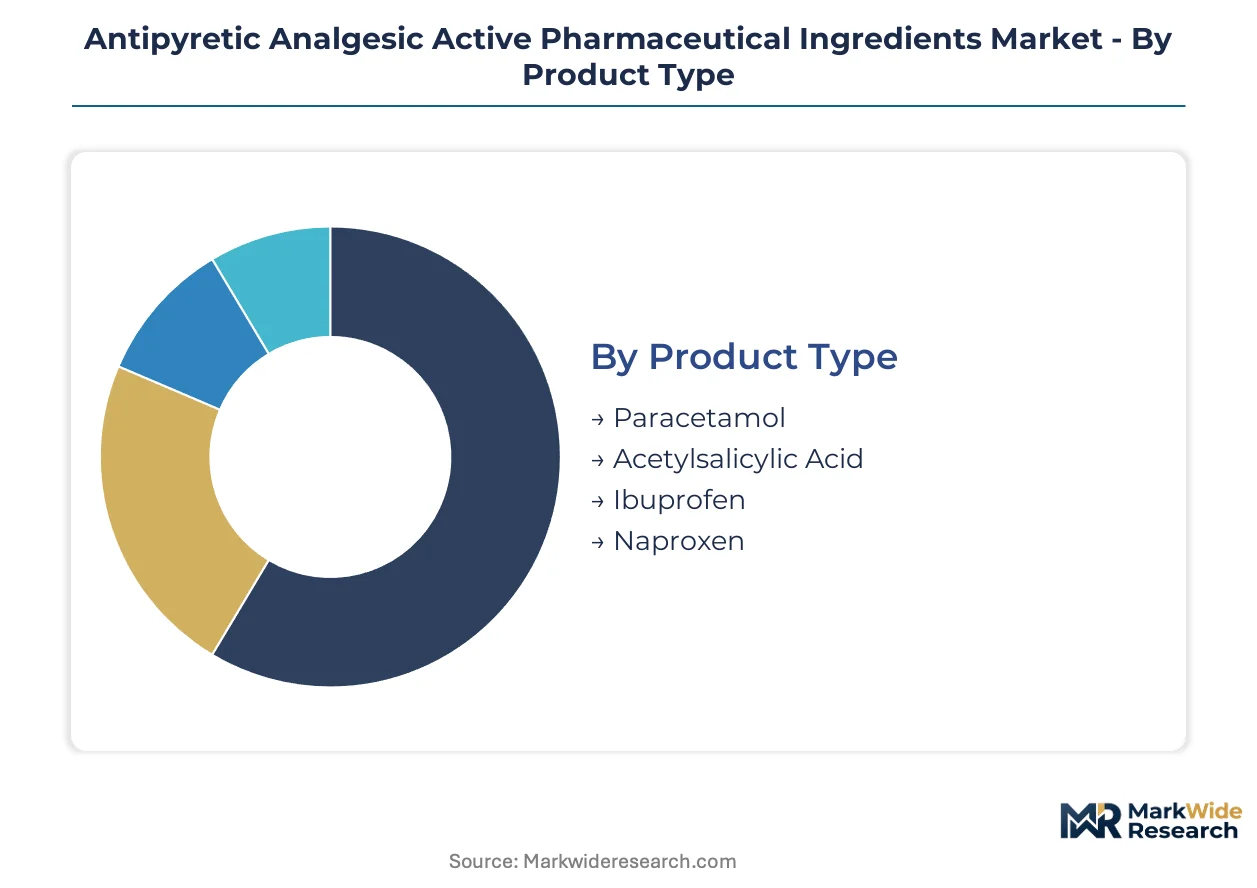
Antipyretic analgesic APIs fragment across molecular chemistry, therapeutic indication, dosage geometry, and care setting. Procurement patterns diverge sharply between high-volume paracetamol for retail pharmacy shelves and specialized ibuprofen grades for hospital formularies requiring enhanced impurity documentation.
Product Type:
Technical specifications around purity thresholds and genotoxic impurity profiles differentiate supplier qualification across these four molecular categories.
- Paracetamol:The acetaminophen molecule commands the largest production tonnage globally, synthesized through p-aminophenol acetylation with pharmacopeial purity exceeding 99.0%. Maharashtra's pharmaceutical corridor and Gujarat's bulk drug clusters are scaling export capacity to serve OTC formulation networks in Latin America and Southeast Asia. Demand concentrates in high-volume tablet and suspension formats where cost-per-kilogram procurement dominates supplier selection.
- Ibuprofen:The propionic acid derivative requires advanced continuous processing capabilities to achieve consistent chiral purity and meet ICH M7 genotoxic impurity limits. Regulated markets in Germany and France pull specialized grades through DMF-holding manufacturers with dedicated nitrosamine testing protocols. Superior margin pools accrue to suppliers with integrated quality systems and FDA/EMA pre-approval facility status.
- Acetylsalicylic Acid:Phenol-based feedstock integration determines cost competitiveness for this salicylate ester used in cardiovascular and analgesic formulations.
- Naproxen:The longer half-life propionic acid derivative serves prescription anti-inflammatory markets with stricter documentation requirements than OTC channels.
Mature deployment sits with paracetamol. Newer deployment is concentrated in ibuprofen continuous processing grades.
Application:
Therapeutic use case determines API specification stringency, with hospital-grade postoperative formulations demanding tighter impurity bands than retail fever reducers.
- Pain Relief:The largest volume absorption spans musculoskeletal, dental, and menstrual pain indications across both prescription and OTC channels. Indian generic manufacturers are expanding procurement of paracetamol and ibuprofen APIs to serve direct-to-consumer portfolios through retail pharmacy chains. Multi-modal analgesia protocols in ambulatory surgical settings are pulling combination API volumes.
- Postoperative Care:Same-day discharge surgical protocols require parenteral and oral dosage form flexibility with documented batch-to-batch consistency. Hospital procurement consortia in Germany and the Netherlands are consolidating purchases under framework agreements with single-source qualified suppliers. EMA's tightened nitrosamine risk assessments impose additional analytical burden on batch release.
- Fever Management:Pediatric and adult antipyretic applications dominate paracetamol consumption in tropical climate zones and seasonal influenza markets.
- Inflammation Control:Chronic rheumatologic and autoimmune indications favor naproxen and higher-dose ibuprofen with prescription-level documentation.
Volume concentration favors pain relief. Steepest expansion trajectory is visible in postoperative care as ambulatory protocols proliferate.
Form:
Dosage geometry dictates API physical properties including particle size distribution, polymorph stability, and excipient compatibility requirements.
- Tablet:Direct compression and wet granulation grades require specified bulk density and flow characteristics for high-speed rotary press operations. The dominant format for retail pharmacy distribution absorbs the majority of paracetamol and ibuprofen API volumes. Maharashtra and Gujarat producers optimize crystallization processes for tablet-grade specifications.
- Liquid:Suspension and solution formulations demand enhanced solubility profiles and microbial limit compliance for pediatric and geriatric populations. Home care and clinic channels in India and China are scaling liquid portfolio procurement. Taste masking and stability considerations drive API specification differentiation.
- Granule:Sachet and effervescent formats require rapid dissolution engineering with controlled hygroscopicity.
- Suppository:Rectal delivery systems for vomiting or unconscious patients necessitate specialized melting point and lipophilicity tuning.
Tablet formats anchor mature manufacturing infrastructure. Liquid deployment is climbing the fastest in emerging market pediatric segments.
End User:
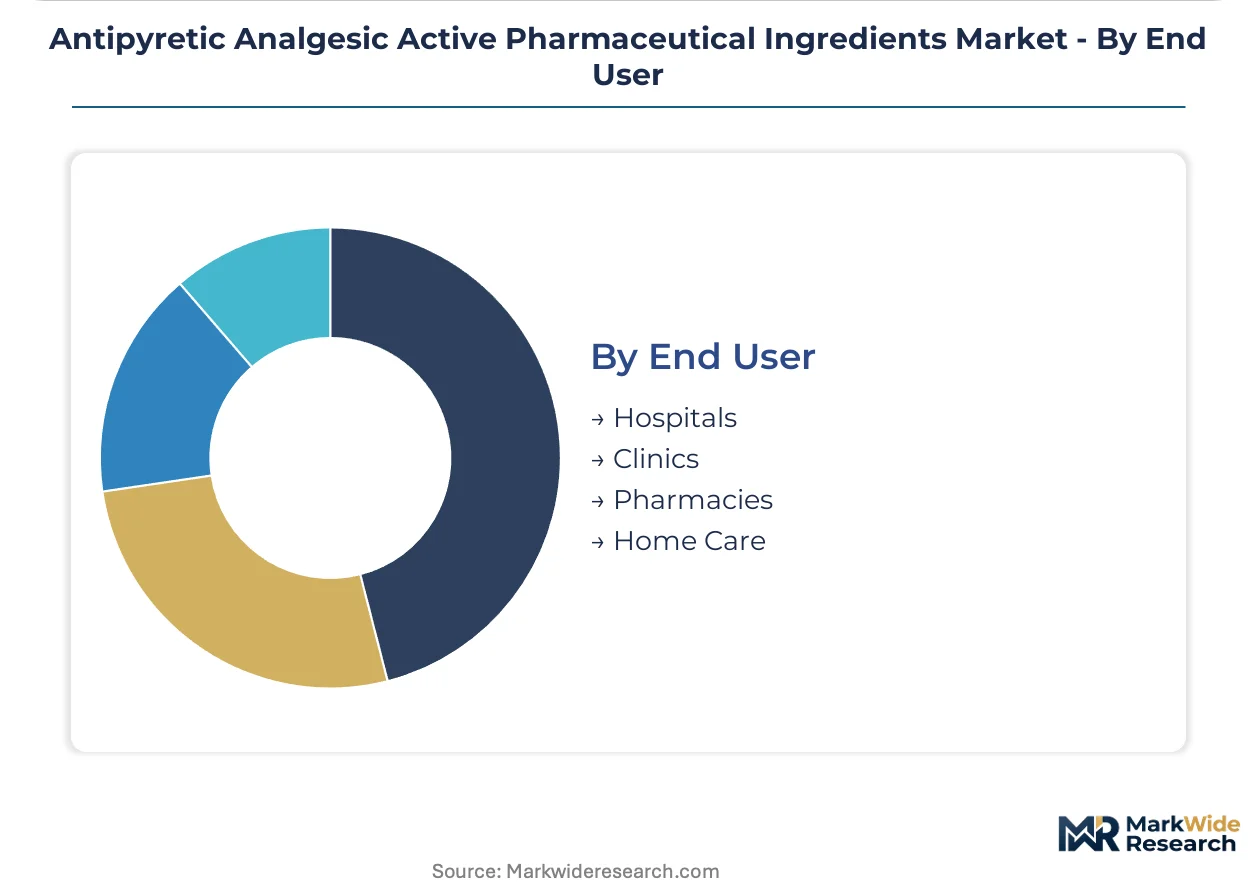
Channel structure determines procurement contract scale, with hospital consortia consolidating toward fewer, larger-volume agreements than fragmented retail pharmacy purchasing.
- Pharmacies:Retail chains and independent dispensaries drive OTC paracetamol and ibuprofen consumption through direct-to-consumer pain relief portfolios. India's pharmacy network expansion and China's retail pharmacy chain consolidation are pulling additional API volumes through formulation subsidiaries. Spot-market purchasing characteristics dominate this channel.
- Hospitals:Centralized pharmacy operations in Western Europe and tertiary care networks in India are consolidating antipyretic analgesic procurement under multi-year framework agreements. ANVISA-registered API supply contracts for Brazilian hospital systems remain underpenetrated relative to patient population scale. Documentation requirements exceed retail channel standards.
- Clinics:Outpatient and primary care settings bridge prescription and OTC consumption with intermediate volume and specification needs.
- Home Care:Post-discharge and chronic pain management applications are expanding with aging population demographics and telemedicine prescription flows.
Pharmacy channel concentration represents established volume. Hospital procurement consolidation is gaining share fastest in Western European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for antipyretic analgesic APIs concentrates in manufacturing corridors serving regulated export markets and high-volume domestic consumption centers. Procurement gravity pulls toward established pharmaceutical clusters with demonstrated compliance histories and backward-integrated feedstock access.
United States
Hospital procurement consortia and retail pharmacy chains drive formulation demand for ibuprofen and paracetamol APIs. FDA enforcement of ICH Q3D elemental impurity limits elevates documentation requirements for import suppliers. New Jersey and Puerto Rico host formulation operations that source qualified APIs through DMF-holding manufacturers.
Germany
Hospital pharmacy centralization in North Rhine-Westphalia and Bavaria consolidates purchasing under multi-year framework agreements. EMA's tightened nitrosamine risk assessments impose additional analytical burden on batch release for European-bound exports. BASF anchors specialized ibuprofen production with advanced continuous processing capabilities from Ludwigshafen.
India
Generic pharmaceutical manufacturers in Maharashtra and Gujarat scale procurement of paracetamol and ibuprofen APIs for OTC export markets. CDSCO and state FDA inspectors intensify pre-approval facility audits for manufacturers seeking US and European registration. The PLI scheme subsidizes greenfield paracetamol capacity with export obligation structures.
China
NMPA-aligned GMP standards with PIC/S requirements pressure smaller Shandong and Hebei producers to consolidate or exit. Shandong province's chemical synthesis base supplies acetylsalicylic acid derivatives through phenol-integrated operations. Near-term supply tightness emerges during transition periods as marginal producers shutter capacity.
Brazil
ANVISA-registered API supply contracts remain underpenetrated relative to patient population scale in São Paulo and Rio de Janeiro hospital systems. Retail pharmacy chain expansion pulls additional paracetamol volumes through formulation subsidiaries. Documentation requirements for hospital procurement exceed retail channel standards.
Antipyretic Analgesic Active Pharmaceutical Ingredients Market Competitive Landscape
Indian producers anchor the high-volume, cost-optimized tier; European and Chinese specialists hold differentiated positions in regulated-market grades and continuous processing capabilities. The vendor base structures across three tiers: DMF-holding integrated manufacturers, toll synthesis operators, and regional feedstock-integrated players. Strategic archetypes include backward-integrated phenol-based producers, vertically scaled paracetamol specialists, and flow-chemistry technology leaders. Capacity expansion and regulatory compliance upgrades constitute the dominant competitive moves as ICH Q3D and nitrosamine mandates reshape qualification thresholds.
Among India-based integrated manufacturers, Granules India Limited and IOL Chemicals and Pharmaceuticals exemplify the vertically scaled archetype with demonstrated export registration histories. BASF occupies the European specialist tier with continuous processing capabilities. Chinese producers including Anqiu Lu'an Pharmaceutical and Zhejiang Kangle Pharmaceutical represent the Shandong-Zhejiang manufacturing base serving domestic and emerging market formulation clients.
| Leading Market Players |
|---|
| Mallinckrodt Pharmaceuticals |
| Granules India Limited |
| BASF |
| Anqiu Lu'an Pharmaceutical |
| IOL Chemicals and Pharmaceuticals |
| Anhui BBCA Pharmaceuticals |
| Novacyl |
| Hebei Jiheng Pharmaceutical |
| Zhejiang Kangle Pharmaceutical |
| Others |
Pricing and Supply Chain Analysis
Analytical chemistry talent scarcity in Maharashtra's pharmaceutical corridor widens pricing spreads between DMF-holding integrated manufacturers and toll synthesis operators, with ICP-MS and LC-HRMS expertise commanding premium compensation that feeds into cost-per-kilogram differentials across export grades.
Pricing Analysis
High-volume paracetamol for retail pharmacy shelves compresses margins through commodity spot dynamics, while specialized ibuprofen grades for hospital formularies with enhanced impurity documentation capture superior margin pools. Price differentiation rests on certification level—FDA/EMA pre-approval facility status versus state-level registration—and volume scale with backward-integrated feedstock access. Cost compression in standard-grade paracetamol intensifies as Gujarat's bulk drug clusters expand export capacity. Retail pharmacy chains in India and China exhibit highest price sensitivity, whereas hospital procurement consortia in Germany and the Netherlands prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from formulation clients in regulated markets mandate multi-supplier qualification for critical APIs, compressing procurement toward DMF-holding manufacturers with demonstrated ICH Q3D compliance. Geographic supply concentration centers on India, China, and Germany, with Maharashtra and Gujarat scaling paracetamol export capacity while Shandong province supplies acetylsalicylic acid derivatives. Raw material dependencies draw from phenol-based feedstocks, p-aminophenol intermediates, and specialized solvents for continuous processing. Single-source vulnerability emerges from Shandong-Hebei consolidation under NMPA-aligned GMP standards. Distribution runs through formulation subsidiaries of generic manufacturers and hospital procurement consortia consolidating under multi-year framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacity bottlenecks in nitrosamine testing capabilities and ICP-MS analytical infrastructure prop pricing for qualified suppliers, constraining supply expansion timelines and sustaining margin premiums for compliant manufacturers.
For Market Incumbents: Acquire dedicated nitrosamine testing facilities and ICP-MS instrumentation to defend against emerging entrants with regulatory compliance gaps. Deepen backward integration into phenol-based feedstocks to offset raw material volatility compressing acetylsalicylic acid margins. Prioritize CTD-eCTD DMF migration to preempt documentation bottlenecks threatening US export eligibility.
For New Entrants and Emerging Players: Enter via ANVISA-registered API supply contracts for Brazilian hospital systems, where underpenetration relative to patient population scale creates white-space opportunity. Target continuous processing technology adoption for ibuprofen synthesis, where flow chemistry expertise remains concentrated among early capital deployers. Leverage India's PLI scheme subsidies for greenfield paracetamol capacity with export obligation structures as the go-to-market anchor.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically scaled paracetamol specialists given CDSCO audit intensity filtering marginal producers from export registration pathways. Long-term viability favors manufacturers with demonstrated FDA/EMA pre-approval facility status and integrated quality systems spanning five-to-ten year regulatory compliance cycles. Monitor EMA nitrosamine risk assessment framework revisions as the signal indicating qualification threshold inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Adoption | Flow chemistry integration compresses ibuprofen batch cycle times while tightening impurity profile consistency for EMA compliance. |
| DMF Migration to CTD-eCTD Format | FDA submission modernization eliminates documentation bottlenecks threatening qualified supplier status for mid-tier exporters. |
| Backward Integration into Phenol Feedstocks | Captive supply of benzene derivatives insulates acetylsalicylic acid margins from commodity price volatility in Shandong. |
| Nitrosamine Testing Capability Investment | Dedicated analytical infrastructure secures batch release eligibility for European-bound exports under tightened EMA risk assessments. |
| PLI Scheme Capacity Expansion | India's production-linked incentive framework subsidizes greenfield paracetamol installations with export obligation structures. |
Research Methodology
Document review covered FDA filings, EMA submissions, CDSCO audit reports, and ICH guideline revisions, complemented by interviews with API manufacturing executives, regulatory affairs leads at DMF-holding suppliers, hospital procurement managers in Western European consortia, and quality control directors overseeing ICP-MS implementation. Secondary validation drew from customs trade data, pharmacopeial monograph updates, and SEC filings of listed pharmaceutical manufacturers. Bottom-up volume estimates triangulated against top-down market sizing across molecular categories and therapeutic applications.
Cross-referencing historical production capacity expansions against panel input from formulation clients and feedstock suppliers anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed molecular chemistry, therapeutic indication, dosage geometry, care setting, and regional regulatory cluster. CAGRs derived from regression analysis of procurement volume trends and pricing trajectories, incorporating ICH Q3D compliance cost pass-through assumptions and PLI scheme subsidy effects on capacity addition timing.
Revisions become necessary when NMPA enforcement intensity accelerates Shandong-Hebei producer consolidation, when EMA nitrosamine detection thresholds tighten further, or when phenol feedstock volatility exceeds historical bands. Deviation in analytical chemistry talent availability or CDSCO audit throughput would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Small Molecule API Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Sterile Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market
Pharmaceutical Ingredients
Flurbiprofen Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Encapsulated Salicylic Acid Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Heparin Sodium API Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Active Ingredients Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market