
 Quantum Dot Sensor Market | 2026-2036
Quantum Dot Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Dot Sensor Market Intelligence
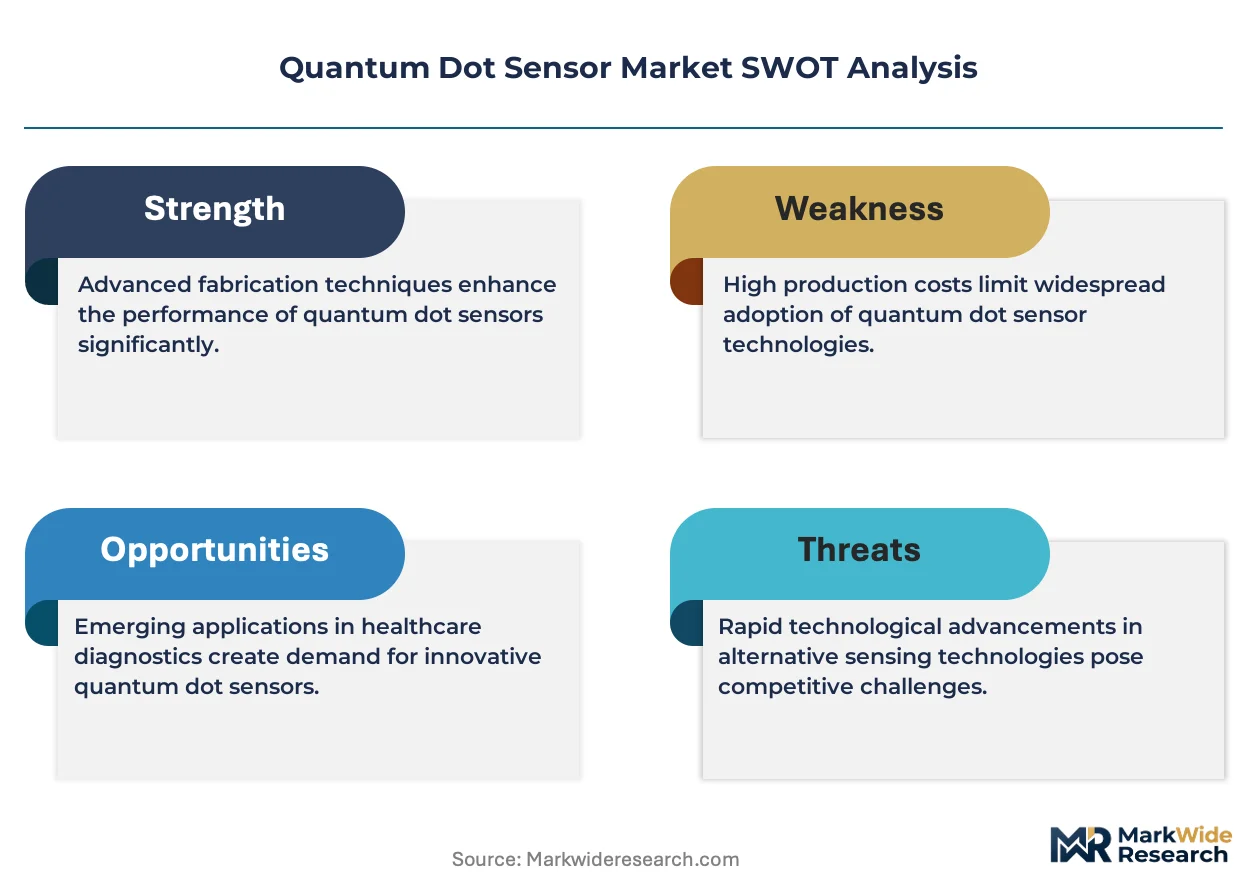
Buyer concentration in consumer electronics is broadening as smartphone and display OEMs diversify sensor suppliers beyond captive sources. Samsung Group (QD Vision) anchors quantum dot material supply through vertical control over epitaxial growth processes. Nanosys Inc. competes by specializing in heavy-metal-free quantum dot compositions for RoHS-sensitive European buyers. Apple Inc. (InVisage Technologies Inc.) leverages its acquired infrared-sensor architecture to differentiate imaging stacks in mobile devices.
Quantum dot sensors exploit size-tunable semiconductor nanocrystals—typically 2–10 nanometers in diameter—to achieve narrow emission bandwidths and high quantum yields for photodetection applications. These devices convert optical signals into electrical outputs with spectral precision unattainable by bulk silicon photodiodes, serving biomedical diagnostics, autonomous vehicle perception, and industrial quality control. Optical sensors dominate current revenue as display manufacturers embed quantum dot films for color-gamut expansion, while biological sensors represent the fastest-expanding margin pool as clinical laboratories adopt fluorescence-based assay platforms. Photodetection technology leads deployment volume, though electrochemical variants are gaining traction in portable environmental monitors where power constraints dominate design tradeoffs.
EPA guidelines on nanomaterial disposal and REACH substance restrictions are reshaping formulation roadmaps, compelling suppliers to eliminate cadmium and lead from commercial quantum dot recipes. FDA device classification rules for diagnostic fluorescence sensors create dual regulatory pathways that segment market access between clinical and research-grade products. ECHA authorization requirements for novel nanomaterials add compliance latency for European market entrants. Stakeholders must monitor evolving substance restrictions across multiple jurisdictions while positioning cadmium-free chemistries ahead of anticipated regulatory phase-outs.
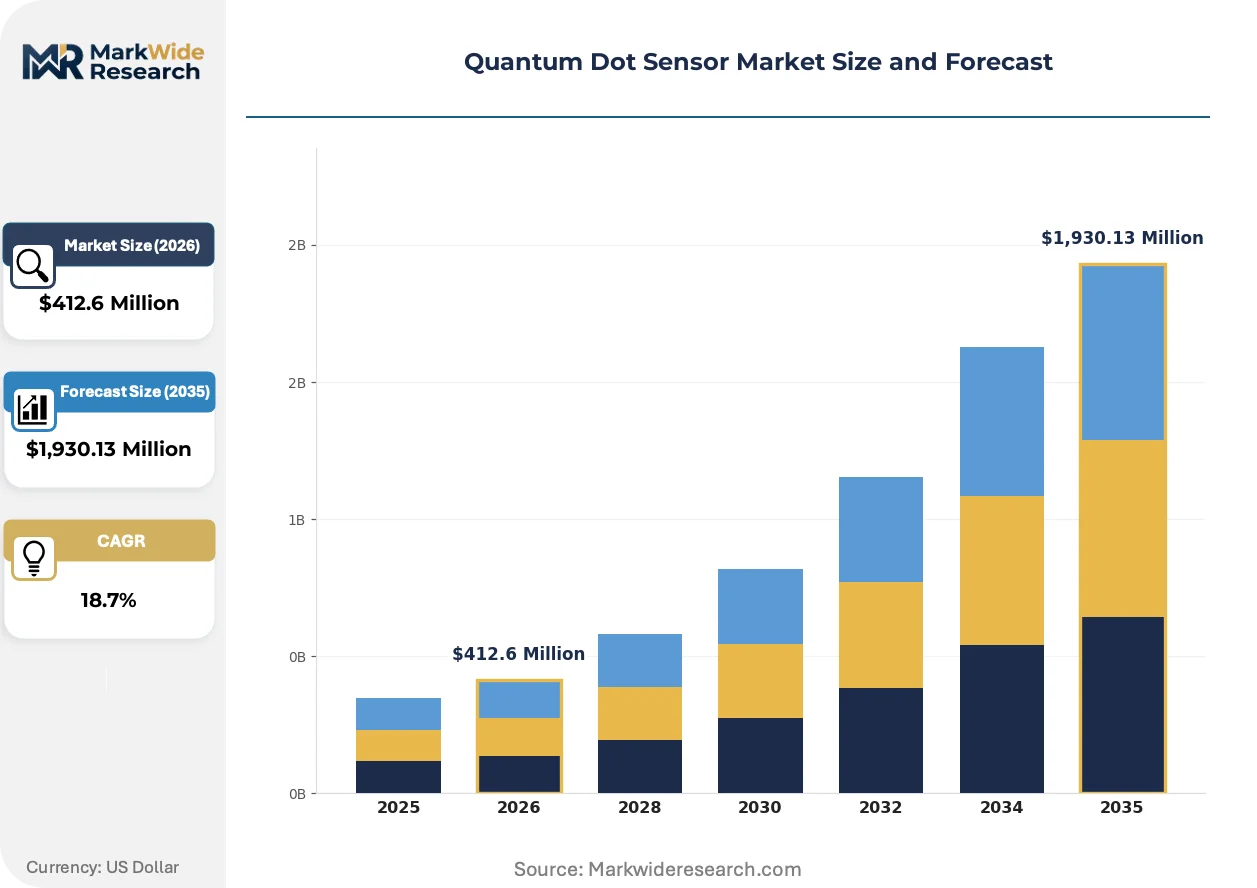
Market Dynamics
Material substitution mandates are compressing formulation timelines as cadmium-free quantum dot chemistries displace legacy heavy-metal compositions across display and biomedical sensor supply chains. Suppliers must simultaneously satisfy REACH substance restrictions, FDA device classifications, and RoHS compliance while scaling epitaxial growth capacity.
Growth Catalysts
- High-resolution imaging demand:Smartphone OEMs and display panel fabricators are embedding quantum dot sensors for expanded color gamut and infrared detection in camera modules.
- REACH and RoHS substance restrictions:European environmental regulations are accelerating procurement of cadmium-free quantum dot formulations for consumer electronics applications.
- Clinical fluorescence assay adoption:Biomedical laboratories are deploying quantum dot biological sensors for diagnostic platforms requiring spectral precision beyond conventional fluorophores.
Market Restraints
- Epitaxial growth input costs:Precursor materials for indium phosphide and perovskite quantum dot synthesis face price volatility tied to rare earth supply concentration.
- South Korean supply concentration:Display panel fabrication clusters in Suwon and Gumi create geographic dependency risk for quantum dot film integration.
- Heavy-metal disposal protocols:EPA nanomaterial guidelines impose end-of-life compliance burdens that elevate total cost of ownership for legacy cadmium-based formulations.
Strategic Opportunities
- India diagnostic infrastructure:CDSCO regulatory pathways for fluorescence-based medical devices create entry points for quantum dot biological sensor suppliers targeting clinical laboratory expansion.
- Autonomous vehicle perception stacks:Near-infrared quantum dot photodetectors are penetrating LiDAR and camera fusion architectures for automotive OEM qualification programs.
- Environmental monitor miniaturization:Electrochemical quantum dot variants are capturing design wins in portable air and water quality sensors where power constraints dominate.
Industry Challenges
- Nanocrystal synthesis expertise scarcity:Colloidal chemistry and surface functionalization talent pools remain shallow relative to expansion timelines for commercial-scale quantum dot production.
- FDA 510(k) pathway complexity:Dual regulatory tracks for clinical versus research-grade fluorescence sensors fragment market access and extend certification timelines for diagnostic applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Dot Sensor Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,930.13 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Sensors, Chemical Sensors, Biological Sensors, Environmental Sensors Technology: Fluorescence, Photodetection, Surface Plasmon Resonance, Electrochemical End User: Healthcare, Automotive, Consumer Electronics, Industrial Automation Application: Imaging, Sensing, Monitoring, Detection |
| Companies Covered | Apple Inc. (InVisage Technologies Inc.), Samsung Group (QD Vision), Nanoco Group PLC, Merck Group, Teradyne Inc., OSRAM Opto Semiconductors GmbH, Ocean NanoTech LLC, Nanosys Inc., Quantum Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Dot Sensor Market Strategic Shifts & Innovations
Epitaxial growth automation and heavy-metal-free formulation chemistry are compressing cost curves while regulatory substance restrictions are hardening material specifications across jurisdictions. These forces are reshaping competitive positioning around process control and environmental compliance.
Perovskite quantum dot synthesis is unifying solution-processed deposition with silicon CMOS compatibility for photodetection arrays. Display manufacturers in China and South Korea are adopting these formulations for next-generation quantum dot films. This convergence is unifying color conversion efficiency with backend integration economics, compressing the performance gap against epitaxial alternatives.
REACH authorization requirements for novel nanomaterials are extending compliance latency for European market entrants. ECHA substance evaluation processes are forcing reformulation roadmaps toward pre-registered chemistries. Cadmium-free quantum dot suppliers with existing SVHC dossiers are capturing procurement preference from RoHS-sensitive buyers in Germany and France.
Consolidated procurement contracts are displacing spot-market purchasing for quantum dot raw materials. Display panel OEMs are negotiating multi-year precursor supply agreements directly with specialty chemical producers. This pattern is most visible in Japan and South Korea, where Samsung and LG Display are securing indium phosphide supply through captive sourcing arrangements.
Quantum Dot Sensor Market Segmentation
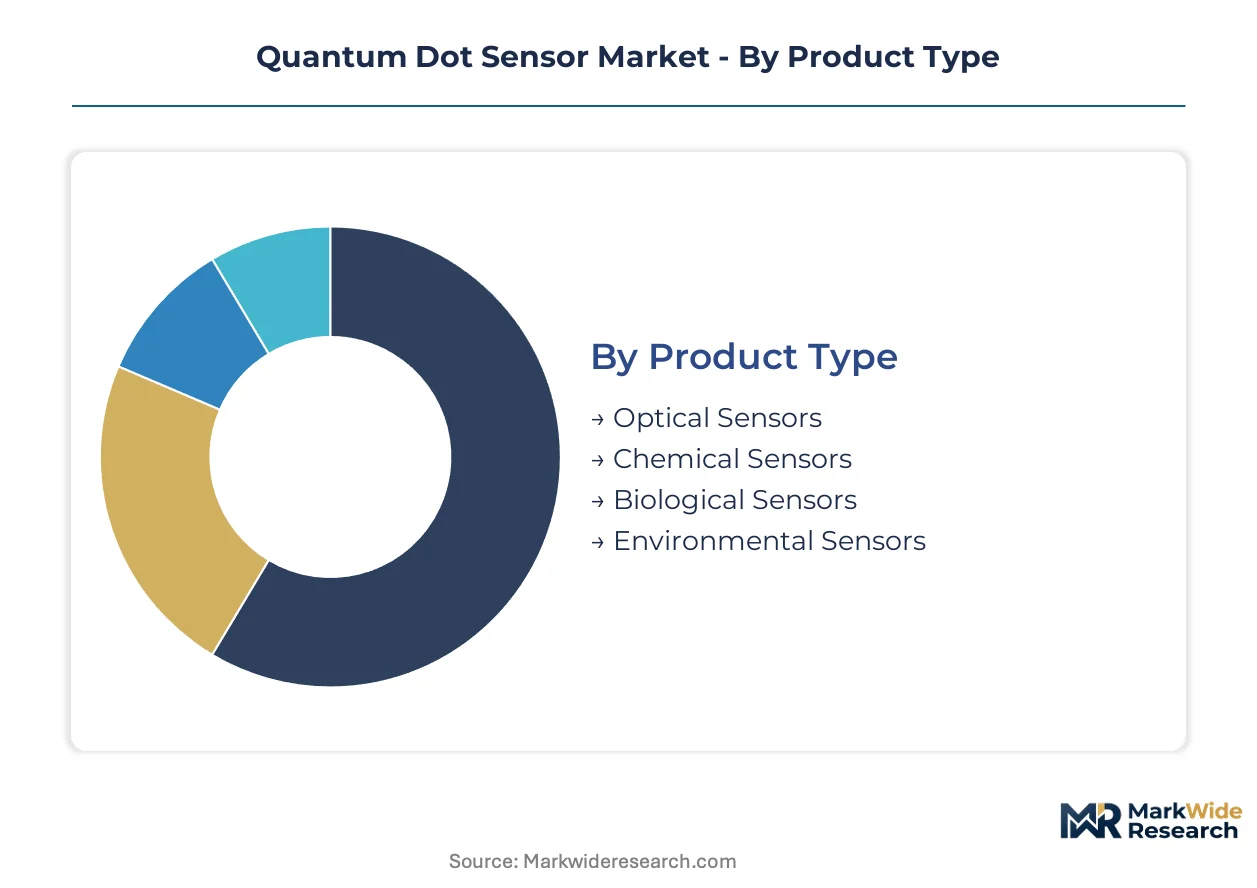
Quantum dot sensor procurement patterns diverge sharply across end-use verticals, with display manufacturers prioritizing optical precision while clinical laboratories demand biological specificity. Understanding these segment boundaries clarifies where formulation investments and regulatory compliance resources generate differentiated returns.
Product Type:
Buyers in this category separate by performance specification requirements and environmental compliance tolerance for heavy-metal content.
- Optical Sensors:These devices leverage size-tunable emission properties for color-gamut expansion in display panels and infrared detection in camera modules. Display fabricators in South Korea and China dominate procurement volume, driven by integration into quantum dot films for premium television and monitor segments.
- Biological Sensors:Fluorescence-based diagnostic platforms exploit narrow emission bandwidths for multiplexed assay detection beyond conventional fluorophore capabilities. Clinical laboratories in Germany and France are accelerating procurement ahead of REACH authorization deadlines for cadmium-free formulations.
- Chemical Sensors:Surface-functionalized nanocrystals detect target analytes through spectral shifts in industrial process monitoring.
- Environmental Sensors:Ruggedized quantum dot formulations monitor air and water quality parameters in portable field deployments.
Volume sits with Optical Sensors; growth tilts toward Biological Sensors.
Technology:
Technology selection tracks power budget constraints and silicon CMOS integration requirements across target applications.
- Photodetection:Quantum dot photodiodes convert optical signals with spectral precision unattainable by bulk silicon alternatives. Automotive LiDAR developers and smartphone OEMs concentrate demand in Japan and South Korea, where epitaxial growth capacity supports high-volume array production.
- Fluorescence:Emission-tunable nanocrystals enable multiplexed biomarker detection in clinical diagnostics and display color conversion. Biomedical laboratories in the US and Europe are expanding procurement as FDA 510(k) pathways mature for diagnostic fluorescence platforms.
- Electrochemical:Low-power quantum dot variants serve portable environmental monitors where battery life dominates design tradeoffs.
- Surface Plasmon Resonance:Plasmon-coupled nanocrystal architectures enable real-time molecular binding detection in research instrumentation.
Deployment scale favors Photodetection; steepest expansion trajectory belongs to Fluorescence.
End User:
End-user differentiation centers on regulatory pathway complexity and procurement contract structure.
- Consumer Electronics:Smartphone and display OEMs negotiate multi-year precursor supply agreements for quantum dot film integration. Samsung and LG Display in South Korea anchor volume through captive sourcing arrangements with specialty chemical producers.
- Healthcare:Clinical laboratories and diagnostic device manufacturers face dual FDA tracks for research versus clinical-grade fluorescence sensors. CDSCO regulatory pathways in India are creating entry points for suppliers targeting diagnostic infrastructure expansion.
- Automotive:Near-infrared quantum dot photodetectors are penetrating LiDAR and camera fusion architectures for autonomous vehicle perception stacks.
- Industrial Automation:Quality control and process monitoring applications demand ruggedized quantum dot formulations with extended operational lifetimes.
Contract value concentrates in Consumer Electronics; certification velocity favors Healthcare.
Application:
Application segmentation separates by resolution requirements and real-time processing demands.
- Imaging:High-resolution camera modules and display systems exploit quantum dot narrow emission for expanded color gamut and infrared sensitivity. Panel fabricators in China, South Korea, and Japan scale integration for next-generation television and mobile device displays.
- Sensing:Photodetection arrays serve biomedical, automotive, and industrial applications requiring spectral precision. Multiplexed fluorescence sensing is gaining share fastest in clinical diagnostic platforms.
- Monitoring:Continuous environmental and physiological parameter tracking employs low-power quantum dot variants.
- Detection:Single-molecule and trace analyte detection leverages quantum dot brightness advantages in research and security applications.
Revenue weight rests with Imaging; application expansion runs through Sensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display panel fabrication clusters in Suwon, Gumi, and Shenzhen concentrate procurement volume for quantum dot film integration. Smartphone OEMs in Cupertino and Seoul negotiate multi-year precursor supply agreements directly with specialty chemical producers.
United States
Apple Inc. leverages InVisage Technologies acquisitions for infrared-sensor differentiation in mobile imaging stacks. FDA device classification rules create dual regulatory pathways for clinical versus research-grade fluorescence sensors. Cupertino and Austin anchor design activity for quantum dot-integrated camera modules.
China
Panel fabricators in Shenzhen and Beijing scale quantum dot film integration for premium television segments. NMPA medical device pathways and GB standards on nanomaterial handling shape supplier compliance roadmaps. Yangtze River Delta display clusters drive volume procurement for color-gamut expansion applications.
South Korea
Samsung Group anchors global quantum dot material supply through vertical control over epitaxial growth processes. MFDS pharmaceutical regulations and RoHS-aligned substance restrictions accelerate cadmium-free formulation adoption. Suwon and Gumi fabrication facilities concentrate display panel integration capacity.
Germany
Automotive LiDAR developers in Stuttgart and Munich qualify near-infrared quantum dot photodetectors for perception stacks. REACH authorization requirements and ECHA substance evaluations extend compliance latency for novel nanomaterial entrants. Bavaria-based precision optics clusters drive photodetection array procurement.
Japan
Camera module OEMs in Tokyo and Osaka embed quantum dot sensors for expanded infrared detection capabilities. METI industrial standards and PMDA diagnostic device regulations segment market access pathways. Kanto region imaging equipment manufacturers concentrate high-resolution sensor procurement.
Quantum Dot Sensor Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue heavy-metal-free formulation differentiation and electrochemical variant miniaturization. The vendor base stratifies across three tiers: integrated display conglomerates with captive quantum dot supply, independent material specialists with RoHS-compliant portfolios, and diagnostic-focused fluorescence platform developers. Consolidation pressure intensifies as multi-year precursor supply agreements displace spot-market purchasing. Capacity expansion and strategic licensing dominate competitive moves as suppliers race to secure indium phosphide and perovskite synthesis scale.
Among Asia-Pacific-based technology conglomerates, Samsung Group and Apple Inc. exemplify vertical integration archetypes through upstream control over epitaxial growth and acquired sensor architecture assets. Nanosys Inc. represents the independent specialist tier, occupying a position defined by heavy-metal-free quantum dot compositions for European regulatory-sensitive buyers. These three anchors illustrate how competitive positioning diverges between scale-driven captive supply and compliance-focused formulation specialization.
| Leading Market Players |
|---|
| Apple Inc. (InVisage Technologies Inc.) |
| Samsung Group (QD Vision) |
| Nanoco Group PLC |
| Merck Group |
| Teradyne Inc. |
| OSRAM Opto Semiconductors GmbH |
| Ocean NanoTech LLC |
| Nanosys Inc. |
| Quantum Solutions |
| Others |
Cost & Logistics Intelligence
Perovskite quantum dot synthesis automation is compressing unit economics while concentrating production know-how in East Asian fabrication clusters. This dual compression simultaneously reduces marginal costs for cadmium-free formulations and reinforces pricing power among suppliers with captive epitaxial growth capacity.
Pricing Analysis
Volume concentrates in optical sensors for display integration, while margins concentrate in biological sensors for clinical diagnostics. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic platforms from research-grade fluorescence kits and commodity quantum dot films. Price differentiation rests on REACH compliance certification and volume scale, with cadmium-free formulations commanding premium positioning. Cost compression in standard-tier display materials is intensifying because Samsung and LG Display are negotiating multi-year precursor supply agreements that displace spot-market purchasing. Healthcare laboratories exhibit lowest price sensitivity due to regulatory compliance requirements, while consumer electronics OEMs drive hardest bargain through consolidated procurement contracts.
Supply Chain Analysis
Single-source vulnerability sits with indium phosphide precursor supply concentrated in South Korea, China, and Japan. Raw material dependencies draw from rare earth concentrates, specialty metal-organic precursors, and high-purity solvents for colloidal synthesis. Supply chain risk centers on regulatory restriction as ECHA authorization requirements extend compliance latency for European market entrants. Distribution runs through direct long-term offtake agreements between display panel fabricators and specialty chemical producers, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where REACH substance restrictions create a barrier-to-entry moat for cadmium-free quantum dot suppliers with existing SVHC dossiers.
For Market Incumbents: Cement upstream control over epitaxial growth capacity in Suwon and Gumi to defend against perovskite quantum dot entrants. Secure multi-year indium phosphide supply agreements before precursor price volatility intensifies. Invest in automation of heavy-metal-free formulation chemistry to maintain margin structure as RoHS-sensitive European buyers accelerate procurement shifts. For New Entrants and Emerging Players: The premium-to-economy price gap in biological sensors offers white-space entry for CDSCO-compliant fluorescence platform developers targeting Indian diagnostic infrastructure expansion. Target electrochemical quantum dot variants for portable environmental monitors where power constraints dominate design tradeoffs. Pursue licensing arrangements with established nanocrystal synthesis specialists rather than building captive colloidal chemistry expertise. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated display conglomerates seeking captive quantum dot supply. Long-term viability favors independent material specialists with RoHS-compliant portfolios and existing ECHA registrations. Watch FDA 510(k) pathway maturation for diagnostic fluorescence platforms as inflection indicator for biological sensor segment consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cadmium-Free Formulation Transition | REACH compliance locks in procurement preference from German and French buyers ahead of regulatory phase-outs. |
| Epitaxial Growth Capacity Expansion | Samsung's vertical control over QD Vision processes forces competitors to secure indium phosphide supply through captive arrangements. |
| Perovskite Synthesis Scale-Up | Solution-processed deposition compatibility with silicon CMOS unifies color conversion efficiency with backend integration economics. |
| CDSCO Regulatory Pathway Investment | Indian diagnostic infrastructure expansion creates entry points for fluorescence-based medical device suppliers. |
| Multi-Year Precursor Supply Agreements | Consolidated procurement contracts displace spot-market purchasing and anchor volume commitments through specialty chemical producers. |
Research Approach
Document review covered SEC filings, ECHA substance registrations, and FDA 510(k) device classifications, complemented by interviews with quantum dot material R&D directors, display panel procurement leads, clinical laboratory assay specialists, and specialty chemical distribution channel managers. Secondary validation drew from customs trade data, patent filings, and nanomaterial regulatory submissions. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across optical, biological, and chemical sensor categories.
Output modeling produced value trajectories across the projection horizon by technology type, end-use vertical, and geographic regulatory cluster. Segmentation dimensions included product type, photodetection versus fluorescence versus electrochemical technology, and application-specific performance tiers. CAGRs were derived from demand elasticity analysis tied to smartphone OEM procurement cycles and clinical diagnostic platform adoption curves. Industry-specific inputs incorporated epitaxial growth capacity utilization rates and REACH authorization timeline assumptions.
Underlying measurement precision varies by segment; optical sensors for display integration carry tighter precision than emerging electrochemical environmental monitor variants. Forecasts reflect documented assumptions regarding regulatory phase-out schedules and precursor supply concentration. Specific risk factors that could revise projections include ECHA substance evaluation delays, rare earth export restriction escalations, and perovskite stability breakthroughs displacing indium phosphide formulations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia Pacific Safety I/O Modules Market
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
RFID Reader Market
Sensors and Controls
Smart Dust Market
Sensors and Controls
Global Signal Conditioning Modules Market
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
Temperature Monitoring Devices Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
Absolute Pressure Sensor Market
Sensors and Controls
Disposable Ph Sensors Market
Sensors and Controls
Europe Bulk Acoustic Wave Sensors Market
Sensors and Controls
Global Sensors and Actuators Market