
 Chip Probing Market | 2026-2036
Chip Probing Market Size, Share, and Industry Trends Forecast 2026-2036
Chip Probing Market Insights
Taiwan's semiconductor fabrication corridor is reconfiguring the geographic distribution of chip probing demand as foundries expand advanced node capacity. FormFactor, Inc. leverages its MEMS probe technology leadership to anchor North American supply relationships with major IDMs. MPI Corporation competes through vertical integration into ceramic substrate manufacturing for high-pin-count probing cards. Technoprobe S.p.A. specializes in cantilever probe architectures that dominate European automotive semiconductor test applications.
Chip probing encompasses the electrical contact and measurement processes used to validate integrated circuit functionality before dicing and packaging, typically requiring probe cards with thousands of cantilever or vertical probes aligned to sub-micron pad pitches. The process serves as the critical quality gate between wafer fabrication and downstream assembly, determining yield recovery and die reliability. Wafer Level probing technology leads product type margins due to its indispensability in advanced packaging roadmaps, while Flip Chip probing represents the fastest-growing technology segment as heterogeneous integration expands. Probing Cards capture the largest value pool within product types because their consumable nature generates recurring revenue streams tied to wafer starts.
FDA device regulations for semiconductor components in medical electronics, EPA hazardous substance restrictions under TSCA, and ISO 9001 quality management standards collectively shape probe material selection and manufacturing process documentation requirements. REACH compliance in European supply chains restricts certain probe metallurgies, redirecting R&D toward alternative contact materials. Stakeholders must monitor how export control classifications for test equipment evolve, since probe system shipments increasingly fall under dual-use technology scrutiny that complicates cross-border sales channel configuration.
Market Dynamics
Advanced packaging roadmaps in high-performance computing are compressing probe pad pitches below 40 micrometers, forcing simultaneous upgrades in probe card architecture and metrology systems. This structural shift is concentrating procurement power among foundries with leading-edge capacity, reshaping supplier qualification timelines and contract structures across the value chain.
Growth Catalysts
- EU Green Deal semiconductor sovereignty targets:Localized test infrastructure investment in Germany and France is redirecting capital toward probe card manufacturing capacity. Domestic sourcing mandates accelerate qualification of regional suppliers.
- Wafer Level probing in advanced packaging:Heterogeneous integration roadmaps for AI accelerators and data center processors require die-level electrical validation before final assembly. This process step is now mandatory for chiplet-based designs.
- Hsinchu Science Park cluster expansion:Taiwan's foundry capacity additions are driving parallel investment in probe card and test socket capacity. Equipment procurement cycles align with fab build-out schedules.
Market Restraints
- Precious metal input volatility:Palladium and rhodium probe tip coatings face price swings that compress probe card gross margins. Long-term supply agreements with South African and Russian refiners carry geopolitical contingency risk.
- Single-source ceramic substrate concentration:High-purity alumina and aluminum nitride substrates for multi-layer probe cards depend on Japanese and Taiwanese suppliers. Earthquake or trade disruption exposure creates supply vulnerability.
- Probe pitch physical limits:Cantilever probe architectures face mechanical interference below 35 micrometer pitches. MEMS vertical probe alternatives require capital-intensive cleanroom fabrication that limits supplier pool expansion.
Strategic Opportunities
- India PLI scheme for semiconductor testing:Gujarat and Karnataka state incentives for electronic manufacturing clusters include test equipment localization requirements. Early entrants capture supplier qualification advantages for emerging fab capacity.
- Automotive MCU probe demand from ISO 26262 functional safety mandates:Zero-defect testing protocols for ADAS and powertrain controllers extend probe card utilization per wafer. Automotive qualification cycles create sticky supplier relationships.
- MEMS-vertical probe convergence with photonics testing:Silicon photonics wafer probing requires optical-electrical hybrid probe cards. This intersection opens design-win opportunities outside traditional IC test markets.
Industry Challenges
- Multi-physics simulation talent scarcity:Probe card design now requires simultaneous electrical, thermal, and mechanical modeling expertise. Competition for finite element analysis specialists with semiconductor packaging backgrounds intensifies hiring costs.
- Dual-use export classification compliance:Probe systems with sub-micron alignment capability fall under US EAR and EU dual-use regulations. License application timelines extend sales cycles and complicate channel partner agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip Probing Market |
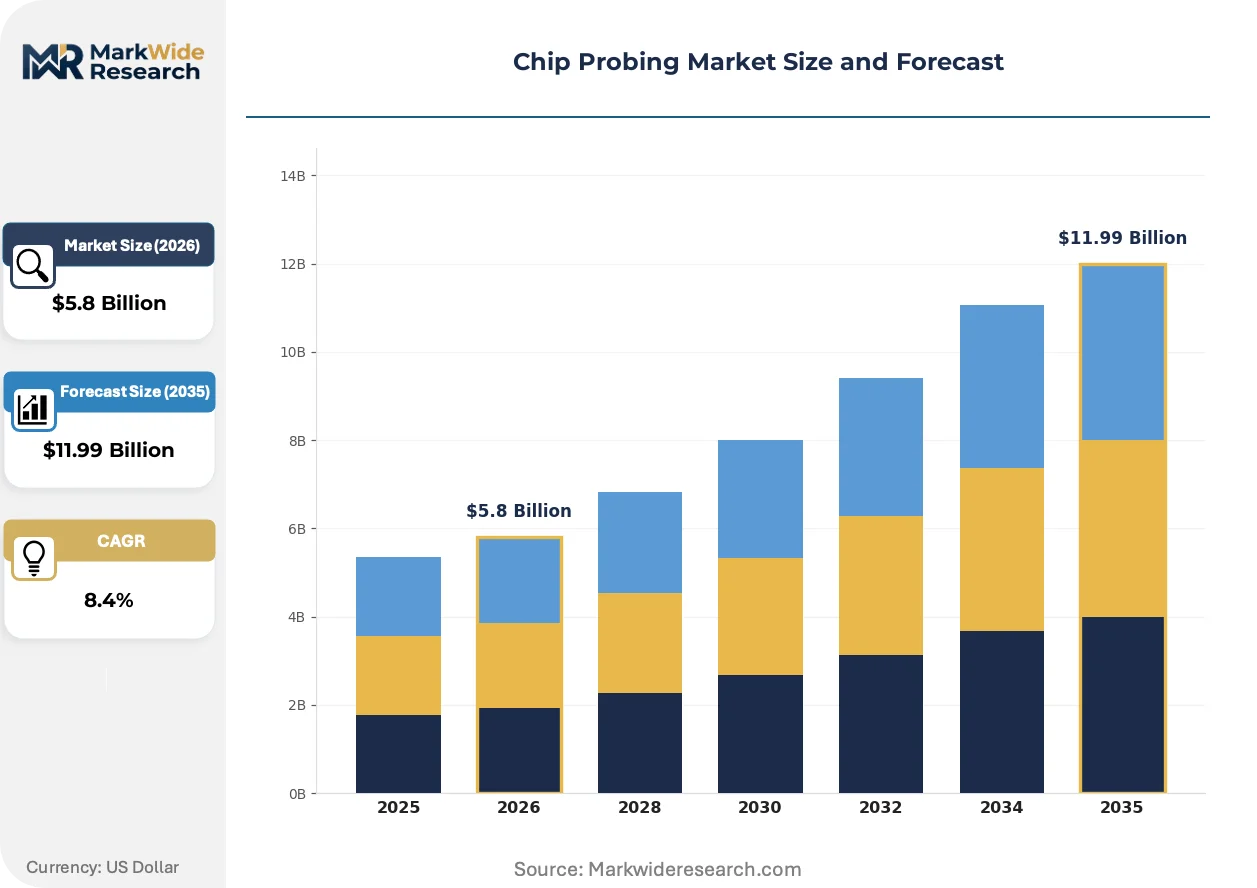
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lead Frame, Flip Chip, Wafer Level, Ball Grid Array Product Type: Probing Cards, Test Sockets, Probing Equipment, Probing Probes Application: Semiconductor Testing, Wafer Testing, R&D Testing, Manufacturing Testing End User: Foundries, IDMs, Outsourced Semiconductor Assembly, OEMs |
| Companies Covered | FormFactor, Inc., MPI Corporation, Technoprobe S.p.A., Tokyo Electron Limited, Advantest Corporation, Japan Electronic Materials Corporation, Micronics Japan Co., Ltd., Accretech (Tokyo Seimitsu), TSE Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip Probing Market Trends and Innovations
Probe technology is bifurcating between evolutionary refinement of MEMS vertical architectures and disruptive alternatives for sub-30 micrometer pitches. This divergence is fragmenting R&D budgets and creating distinct competitive arenas based on customer node migration schedules.
MEMS vertical probe technology is migrating from cantilever-dominant legacy designs toward fully lithographed spring structures. Leading-edge foundries in Taiwan and South Korea are qualifying these architectures for 3nm and 2nm node production. This transition is compressing the supplier base to those with captive MEMS fabrication capabilities.
REACH substance restrictions on hexavalent chromium and cadmium platings are forcing probe metallurgy redesign across European supply chains. ECHA authorization requirements for alternative coatings extend qualification timelines by 12-18 months. Automotive semiconductor test houses in Germany and Italy are prioritizing suppliers with pre-certified green material portfolios.
Foundry-direct procurement models are displacing traditional distributor channels for high-volume probe card contracts. TSMC and Samsung are consolidating supplier panels and negotiating multi-year wafer-start-based pricing. This concentration is most visible in Taiwan, where probe card vendors now maintain dedicated on-site engineering teams at major fab campuses.
Chip Probing Market Segmentation
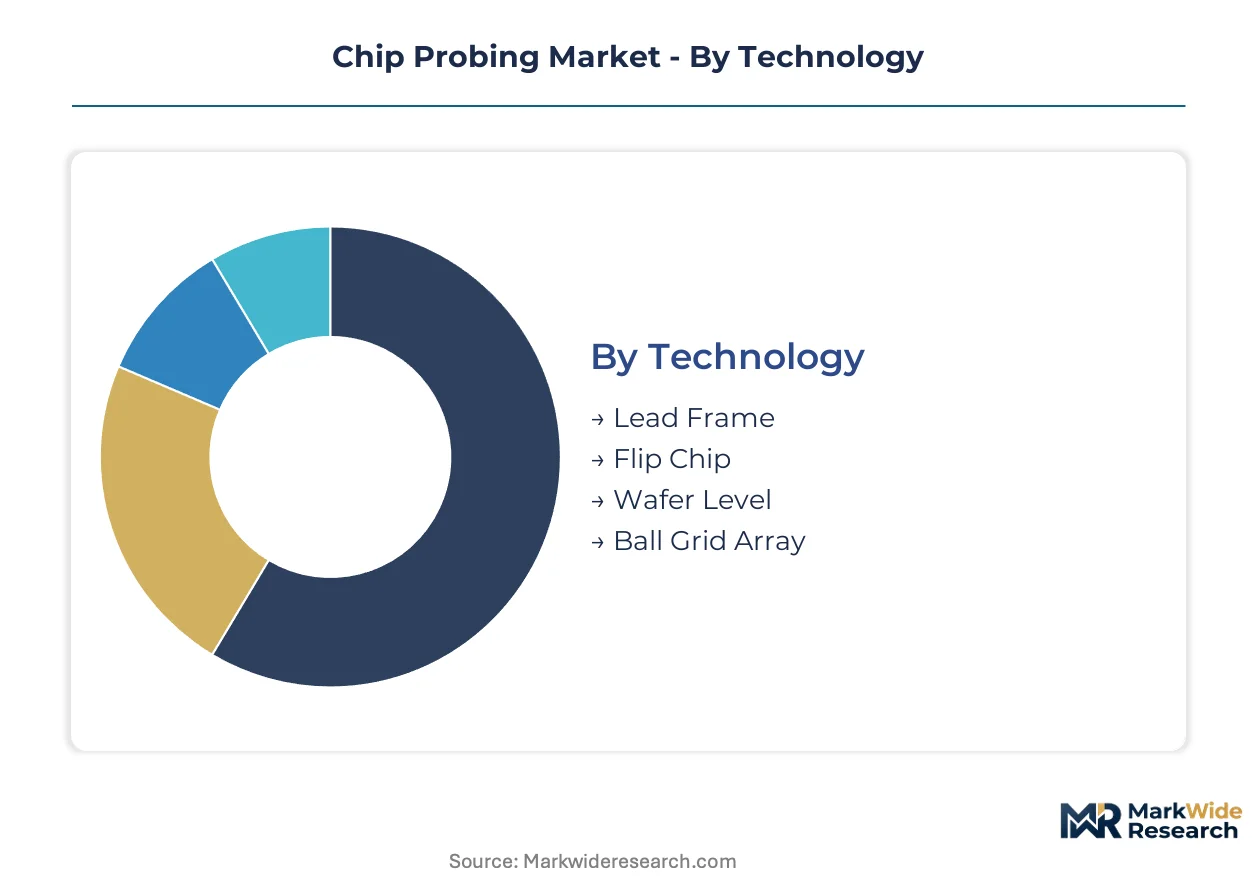
Chip probing market segmentation reveals distinct technology maturity curves and procurement patterns. Each dimension—technology, product type, application, and end user—carries unique margin structures and qualification barriers that reshape supplier strategies.
Technology:
Mature cantilever architectures coexist with emerging MEMS vertical designs across the technology spectrum.
- Wafer Level:Die-level electrical validation before final assembly requires sub-micron alignment precision. Taiwan's foundry cluster and South Korea's memory fabs drive procurement concentration for heterogeneous integration roadmaps.
- Flip Chip:Heterogeneous integration for AI accelerators and data center processors demands bumped-die probing capability. Taiwan's advanced packaging expansion accelerates adoption timelines for this architecture.
- Lead Frame:Legacy discrete and power semiconductor testing maintains steady replacement demand.
- Ball Grid Array:Package-level validation for automotive and industrial MCUs sustains moderate volume.
Wafer Level retains volume leadership; Flip Chip holds the steepest expansion curve.
Product Type:
Cost tier stratification separates consumable probe cards from capital-intensive probing equipment.
- Probing Cards:Consumable probe cards with thousands of cantilever or vertical probes generate recurring revenue tied to wafer starts. Taiwan's Hsinchu Science Park cluster and South Korea's Pyeongtaek semiconductor complex anchor procurement volume for advanced node production.
- Test Sockets:Package-level test interfaces for final packaged device validation. Automotive qualification cycles in Germany and Japan create sticky supplier relationships with extended utilization per socket.
- Probing Equipment:Capital-intensive probe stations and alignment systems face longer replacement cycles.
- Probing Probes:Individual probe replacement and refurbishment services support installed base maintenance.
Probing Cards dominate revenue concentration; Test Sockets expand most quickly alongside automotive MCU demand.
Application:
Customer type differentiation separates high-volume production testing from low-volume R&D validation.
- Semiconductor Testing:Comprehensive electrical validation across design, wafer, and final test stages. Taiwan's foundry-direct procurement models and South Korea's IDM captive testing drive volume concentration.
- Wafer Testing:Pre-dicing electrical screening determines yield recovery and die reliability. Advanced packaging roadmaps in Taiwan and the US make this stage mandatory for chiplet-based designs.
- Manufacturing Testing:In-line quality gates for high-volume production environments.
- R&D Testing:Low-volume characterization for new product introduction and failure analysis.
Semiconductor Testing captures the broadest revenue base; Wafer Testing gains share fastest from advanced packaging complexity.
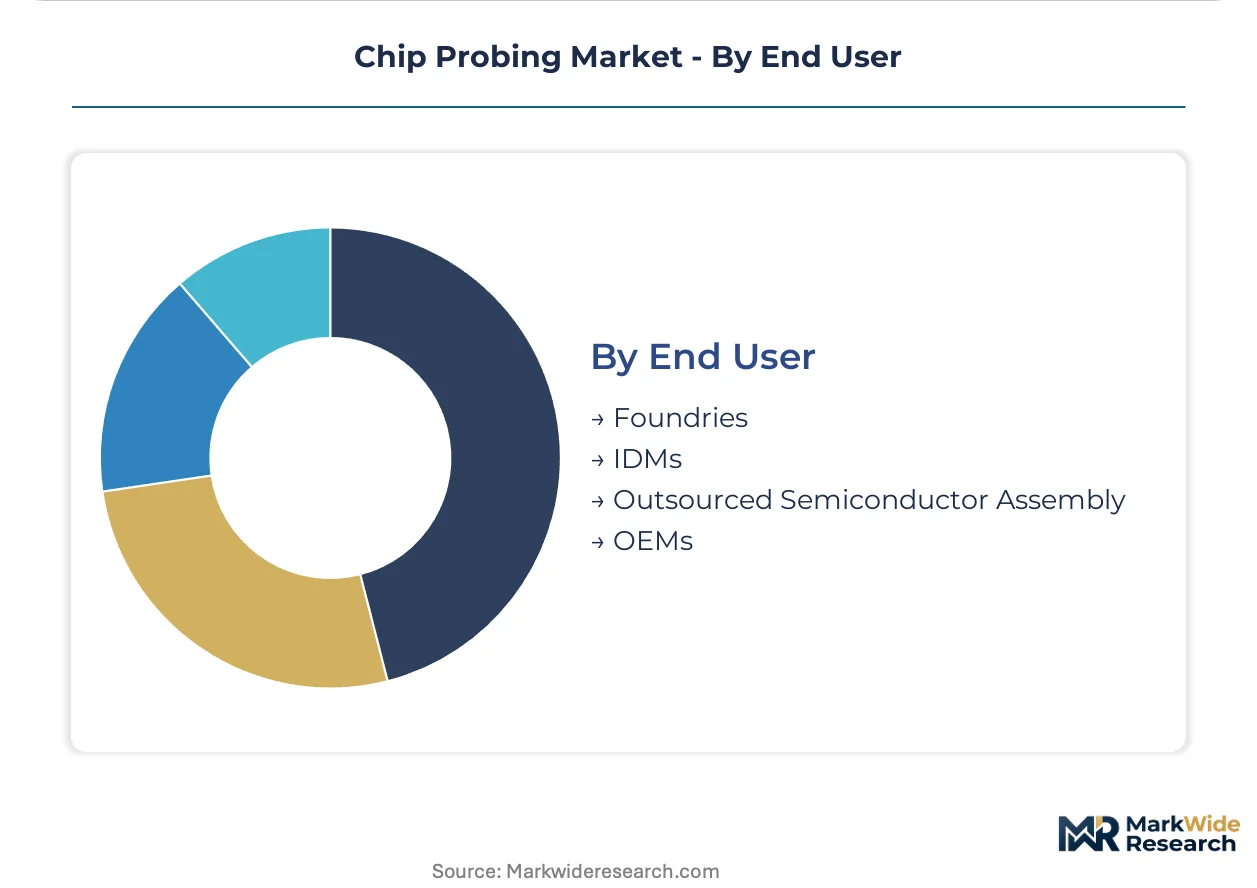
End User:
Supply concentration patterns align with geographic fab capacity distribution and vertical integration strategies.
- Foundries:Taiwan's TSMC and South Korea's Samsung consolidate supplier panels and negotiate multi-year wafer-start-based pricing. Dedicated on-site engineering teams at major fab campuses reshape service delivery models.
- IDMs:Intel, Texas Instruments, and STMicroelectronics maintain captive test operations with proprietary qualification protocols. US and European IDMs prioritize suppliers with dual-use export compliance capabilities.
- Outsourced Semiconductor Assembly:OSATs in Malaysia, Vietnam, and India manage final test and packaging validation.
- OEMs:System-level manufacturers perform incoming inspection and module-level testing.
Foundries command procurement volume concentration; IDMs sustain premium pricing for qualified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Probe card procurement concentrates where foundry capacity expands. Taiwan's Hsinchu Science Park anchors volume, while Germany and India build test infrastructure under sovereignty programs. Each major fab cluster spawns parallel investment in localized probe manufacturing.
Taiwan
TSMC's advanced node expansion in Hsinchu and Tainan drives parallel probe card capacity investment. The National Development Council's semiconductor initiative funds domestic test equipment suppliers. Dedicated on-site engineering teams from probe vendors now maintain permanent presence at major fab campuses.
South Korea
Samsung and SK Hynix memory fab complexes in Pyeongtaek and Icheon generate concentrated demand for high-pin-count probing solutions. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt program subsidizes local probe card manufacturing. Seoul Capital Area suppliers are qualifying MEMS vertical probe architectures for 3nm production.
United States
Intel's Arizona and Ohio fab investments trigger probe equipment procurement aligned with CHIPS Act construction timelines. The Department of Commerce's semiconductor incentives require domestic content verification for test infrastructure. Phoenix and Columbus metro areas are emerging as probe system integration hubs.
Germany
Infineon and Bosch automotive semiconductor operations in Saxony and Bavaria sustain demand for zero-defect testing protocols. The EU Green Deal semiconductor sovereignty targets redirect capital toward Dresden and Regensburg probe manufacturing capacity. ECHA REACH compliance requirements are accelerating qualification of green material probe portfolios.
India
Gujarat and Karnataka state incentives under the PLI scheme for electronic manufacturing clusters include test equipment localization mandates. Tata Electronics and ISMC Digital fab projects in Dholera and Mysore are pre-qualifying probe card suppliers. Early entrants capture supplier approval advantages before production ramp begins.
Chip Probing Market Competitive Landscape
MEMS technology leaders and ceramic substrate specialists split the market into distinct capability tiers. The supplier base concentrates among foundry-qualified vendors with captive cleanroom fabrication. Three archetypes dominate: integrated probe card manufacturers, MEMS foundry operators, and test equipment conglomerates. Capacity expansion and strategic partnerships represent the primary competitive vectors as customers consolidate supplier panels.
Among North American technology developers, FormFactor, Inc. exemplifies the MEMS probe archetype through its established foundry relationships. MPI Corporation anchors the Asia-Pacific supplier tier with its substrate integration capabilities. Technoprobe S.p.A. represents European specialization in automotive test applications. These three occupy positions that reflect broader regional competitive positioning rather than individual strategic differentiation.
| Leading Market Players |
|---|
| FormFactor, Inc. |
| MPI Corporation |
| Technoprobe S.p.A. |
| Tokyo Electron Limited |
| Advantest Corporation |
| Japan Electronic Materials Corporation |
| Micronics Japan Co., Ltd. |
| Accretech (Tokyo Seimitsu) |
| TSE Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Hsinchu Science Park probe card manufacturing concentration grants Taiwanese suppliers outsized leverage over global pricing benchmarks. Foundry-direct procurement models at TSMC and Samsung consolidate buyer power into a handful of volume accounts, compressing margin negotiation space for qualified vendors while elevating entry barriers for unqualified competitors.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European supply chains, separating ECHA pre-certified green material portfolios from standard metallurgy offerings. Three-tier pricing structure across premium MEMS vertical, standard cantilever, and economy legacy architectures reflects certification grade and volume scale differentials. Cost compression in economy cantilever tiers is intensifying because palladium and rhodium price volatility erodes coating cost predictability. IDMs with captive test operations exhibit lowest price sensitivity due to zero-defect automotive qualification requirements, while emerging OSATs in Southeast Asia face acute budget constraints.
Supply Chain Analysis
US EAR and EU dual-use export controls restrict sub-micron alignment probe system flows to certain end markets, fragmenting distribution pathways. High-purity alumina and aluminum nitride ceramic substrates draw from Japanese and Taiwanese suppliers, while MEMS vertical probe fabrication rests on South Korean and Taiwanese cleanroom capacity. Single-source substrate concentration creates earthquake and trade disruption exposure. Distribution runs through foundry-qualified vendor panels with dedicated on-site engineering teams rather than traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry panel consolidation into TSMC, Samsung, and Intel captive procurement structures has shifted bargaining power decisively toward high-volume buyers. Three IDMs now control qualification gates for advanced node probe card vendors.
For Market Incumbents: Pre-empt MEMS vertical probe qualification at 2nm nodes by accelerating lithographed spring structure R&D before South Korean competitors capture design wins. Defend against emerging Chinese probe card vendors through backward integration into ceramic substrate manufacturing in Taiwan and Japan. Lock in multi-year wafer-start-based pricing with dedicated on-site engineering teams at Hsinchu and Pyeongtaek campuses. For New Entrants and Emerging Players: India's Gujarat and Karnataka PLI scheme test equipment localization requirements represent the most penetrable entry point before Tata Electronics and ISMC Digital fabs commence production ramp. Automotive MCU probe demand from ISO 26262 functional safety mandates in Germany and Italy offers sticky supplier relationships with extended utilization cycles. Pursue qualification partnerships with European automotive semiconductor test houses prioritizing green material portfolios. For Investors and Strategic Acquirers: Long-term, this sits as a captive MEMS fabrication capability play because probe card architecture transitions toward lithographed vertical designs compress the qualified supplier pool to cleanroom-equipped vendors. Target acquisition archetypes include ceramic substrate specialists with high-purity alumina expertise and automotive test application engineers with ISO 26262 protocol experience. Monitor EU Green Deal domestic sourcing mandate acceleration as inflection signal for regional manufacturing capacity valuations.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Vertical Probe Qualification | Captures 3nm and 2nm node design wins at TSMC and Samsung foundries. |
| Ceramic Substrate Backward Integration | Secures high-purity alumina supply against Japanese single-source vulnerability. |
| Green Material Portfolio Certification | Accelerates ECHA REACH compliance for European automotive test house procurement. |
| India PLI Scheme Localization | Captures supplier approval advantages at Tata Electronics Dholera fab ahead of production ramp. |
| Silicon Photonics Hybrid Probe Development | Opens design-win opportunities outside traditional IC test markets through optical-electrical convergence. |
Research Methodology
Desk research of SEMI equipment market databases, foundry capex disclosure filings, and ECHA REACH authorization records preceded structured interviews with probe card design engineers, foundry procurement directors, automotive semiconductor test house quality managers, and ceramic substrate manufacturing specialists. Primary fieldwork with Taiwan and South Korea equipment vendors validated secondary trade flow estimates. Bottom-up wafer start projections and top-down equipment spending analysis triangulated market sizing.
Forecast assumptions held EU Green Deal subsidy allocation rates and CHIPS Act construction timelines fixed while varying memory fab utilization cycles and AI accelerator packaging adoption curves. Segmentation modeling spanned technology node, probe architecture, end-use application, and geographic fab cluster. CAGRs derived from equipment procurement cycle alignment with announced foundry build-out schedules, with specific inputs including heterogeneous integration roadmap complexity and automotive MCU functional safety test extension rates.
Practitioners should monitor export control classification expansion for sub-micron alignment systems and palladium price volatility spikes for early signals of supply disruption or margin compression. Material shifts in dual-use technology licensing timelines or ECHA substance restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Ion Beam Etching System Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Global Soldering Equipment Market
Semiconductor Equipment
Chip Mounter Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market
Semiconductor Equipment
Electrolytic Etching Machine Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
150mm Probe Station Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
EUV Mask Inspection and Pellicle Monitoring Systems Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
Semiconductor Wafer Process Control Equipment Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Europe Semiconductor Etch Equipment Market