
 Europe Nondestructive Testing Equipment Market | 2026-2036
Europe Nondestructive Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nondestructive Testing Equipment Market Insights
Equipment-as-a-service and operational leasing is rewriting capital deployment patterns across European NDT procurement. Waygate Technologies GmbH leverages its inspection heritage to dominate radiographic system deployments. Eddyfi Europe SAS specializes in electromagnetic array solutions for pipeline integrity. TÜV Rheinland controls third-party certification workflows that gate market access for equipment vendors.
Europe nondestructive testing equipment encompasses systems that evaluate material integrity without causing damage, typically employing ultrasonic transducers operating at frequencies between 0.5 and 25 MHz or X-ray tubes generating photon energies up to 450 kV for flaw detection in welds, castings, and composites. Its primary purpose is to certify structural soundness in safety-critical infrastructure while minimizing production downtime. Ultrasonic testing leads product type demand due to its portability and depth penetration in thick-section steel, while infrared thermography within the technology dimension captures the fastest growth as aerospace manufacturers adopt it for carbon-fiber delamination screening. Quality control anchors application-level revenue because OEMs mandate 100% inspection protocols before component release.
EMA medical device requirements, REACH substance restrictions on inspection penetrants, and CE marking under the EU Machinery Directive collectively shape equipment design standards and chemical formulation choices across the continent. The EU AI Act introduces conformity obligations for automated defect recognition algorithms that vendors must embed during product development. Stakeholders should monitor how notified body interpretation of these overlapping frameworks affects time-to-certification for next-generation systems.
Market Dynamics
Equipment-as-a-service models are restructuring capital deployment across European NDT procurement, compressing upfront investment requirements while embedding vendors deeper into operational workflows.
Growth Catalysts
- EU F-Gas Regulation phase-down:The mandated reduction in fluorinated gas usage is accelerating equipment refresh cycles as operators replace legacy coolant-dependent systems with compliant alternatives.
- France's nuclear maintenance ecosystem:Reactor pressure vessel inspection mandates under national nuclear safety authority protocols sustain recurring demand for ultrasonic and radiographic testing systems.
- Carbon-fiber composite screening:Aerospace manufacturers are expanding infrared thermography deployment for delamination detection in wing structures and fuselage sections.
Market Restraints
- Helium supply concentration:Leak detection systems depend on helium as a tracer gas, with European supply chains exposed to Qatar and US production bottlenecks.
- REACH substance restrictions:ECHA classification of certain inspection penetrants as substances of very high concern forces formulation reformulation and supply discontinuity.
- Skilled operator scarcity:Certification requirements under EN ISO 9712 create multi-year training pipelines that constrain deployment velocity for advanced electromagnetic techniques.
Strategic Opportunities
- Poland's emerging aerospace cluster:Airbus and Lockheed Martin supplier networks near Rzeszów lack mature NDT infrastructure, creating greenfield equipment demand.
- EU AI Act automated recognition:Conformity obligations for machine-learning defect classification algorithms create first-mover advantages for vendors embedding compliance during product development.
- Wind turbine blade inspection:Offshore installations in the North Sea and Baltic require phased array ultrasonic systems for bond-line integrity verification at scale.
Industry Challenges
- Notified body certification timelines:CE marking under the EU Machinery Directive involves divergent interpretation across TÜV, DEKRA, and SGS entities, delaying product launches.
- Legacy system integration:Digital radiography retrofitting into existing film-based workflows demands custom adapter development and operator retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nondestructive Testing Equipment Market |
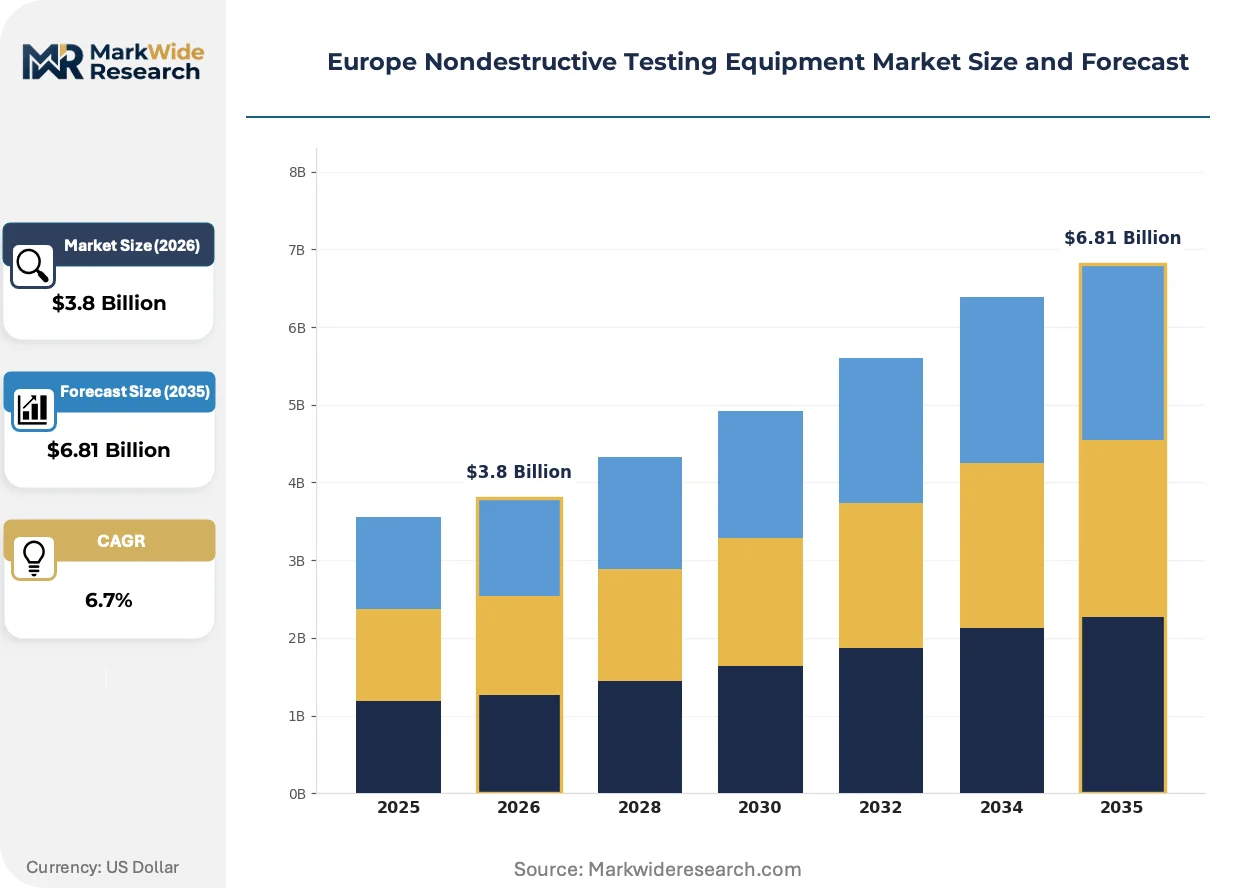
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Testing, Radiographic Testing, Magnetic Particle Testing, Visual Inspection Technology: Electromagnetic Testing, Acoustic Emission Testing, Infrared Thermography, Laser Testing End User: Aerospace, Automotive, Construction, Oil & Gas Application: Quality Control, Equipment Maintenance, Research & Development, Structural Analysis |
| Companies Covered | Waygate Technologies GmbH, YXLON International GmbH, Evident Europe GmbH, Nikon Metrology NV, Eddyfi Europe SAS, TÜV Rheinland, TÜV SÜD, Applus+, Bureau Veritas, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nondestructive Testing Equipment Market Trends and Innovations
Digital twin architectures and cloud-native inspection data management are compressing the feedback loop between field acquisition and engineering decision-making across European manufacturing.
Digital radiography is virtualizing film processing infrastructure across the continent. Foundries in Germany's automotive supply chain have adopted flat-panel detectors for real-time casting verification. This transition is virtualizing darkroom chemical handling and enabling immediate defect classification without intermediate development steps.
The EU AI Act introduces conformity assessment obligations for automated defect recognition algorithms embedded in NDT systems. Industrial software vendors must now document training data provenance and algorithmic transparency before CE marking. Ultrasonic phased array equipment with embedded machine learning faces the steepest compliance pathway, with notified bodies developing sector-specific guidance through 2025.
Asset operators in Scandinavia are unbundling inspection services from equipment ownership. Danish wind farm operators now contract blade integrity verification on availability-based terms rather than capitalizing analyzer systems. This preference compresses vendor business models toward recurring revenue streams and remote diagnostic capabilities.
Europe Nondestructive Testing Equipment Market Segmentation
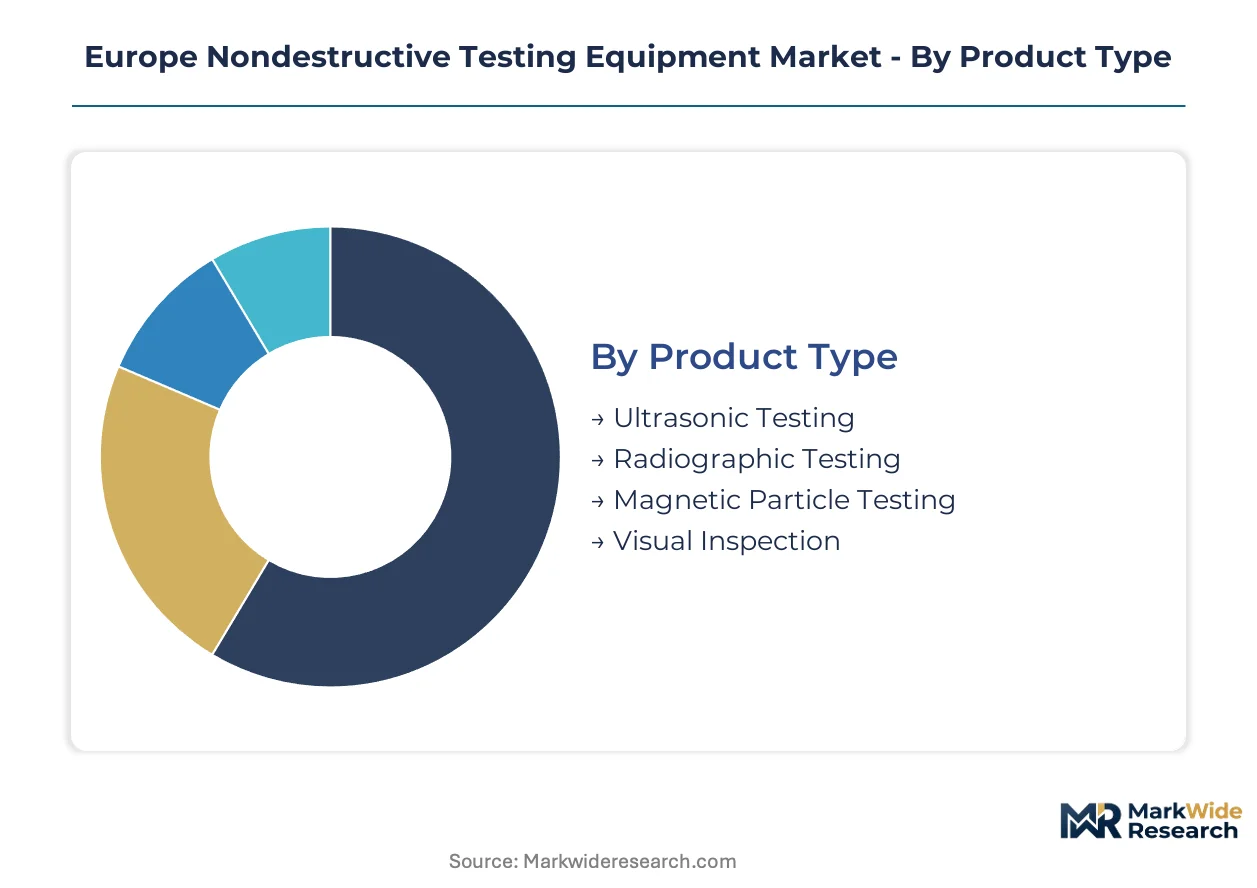
Equipment segmentation across the European NDT landscape reflects divergent technical requirements between heavy industry and precision manufacturing. Each dimension carries distinct procurement patterns, certification obligations, and technology refresh cycles that shape vendor positioning.
Product Type:
Application intensity varies sharply by inspection depth requirements and surface accessibility constraints across European manufacturing clusters.
- Ultrasonic Testing:Systems deploy piezoelectric transducers operating between 0.5 and 25 MHz to detect subsurface discontinuities in thick-section steel. German turbine manufacturers and French nuclear pressure vessel inspectors drive sustained demand for phased array configurations with beam-steering capabilities.
- Radiographic Testing:X-ray tubes generating photon energies up to 450 kV produce permanent defect records for weld certification. Digital radiography panels are displacing film-based workflows in Italian foundries and Spanish shipyards, though darkroom infrastructure persists in Eastern European maintenance depots.
- Magnetic Particle Testing:Surface-breaking crack detection for ferromagnetic components using yoke or coil magnetization methods. Polish rail infrastructure operators and Czech heavy machinery rebuilders constitute the core installed base.
- Visual Inspection:Borescopes and automated optical systems examine accessible surfaces without specialized media. Scandinavian wind turbine service providers favor remote visual systems for blade leading-edge erosion assessment.
Ultrasonic testing commands the established base. The steepest expansion runs through radiographic testing as digital detector adoption accelerates.
Technology:
Technology selection tracks the material composition of inspected assets and the permissible downtime windows for testing execution.
- Electromagnetic Testing:Eddy current arrays and remote field techniques evaluate conductive materials without surface preparation. Pipeline operators across the North Sea and Baltic corridors deploy electromagnetic solutions for corrosion mapping beneath insulation.
- Acoustic Emission Testing:Passive sensors detect stress-wave emissions from active crack growth or fiber breakage. German composite pressure vessel manufacturers and Dutch storage tank farms apply this method for continuous structural health monitoring.
- Infrared Thermography:Thermal cameras identify delamination, moisture ingress, and bonding defects through differential heat signatures. Airbus suppliers in Toulouse and Hamburg have standardized thermographic protocols for carbon-fiber wing inspection.
- Laser Testing:Shearography and holographic interferometry measure nanometer-scale surface deformation under stress. French aerospace tier-1 suppliers employ laser-based methods for honeycomb sandwich structure validation in satellite components.
Electromagnetic testing anchors current deployment volumes. Infrared thermography gains share fastest as composite penetration deepens across European aviation.
End User:
End-user concentration determines equipment specification rigor, with safety-critical sectors mandating certified operator protocols and documented traceability.
- Aerospace:OEMs and tier suppliers enforce 100% inspection coverage on flight-critical components. EASA Part 145 maintenance organizations in France, Germany, and the United Kingdom sustain recurring demand for portable ultrasonic and radiographic systems.
- Automotive:Powertrain foundries and electric vehicle battery pack manufacturers deploy automated inspection cells. German OEM supplier parks near Stuttgart and Munich have integrated eddy current testing into crankshaft and camshaft production lines.
- Construction:Bridge cable, tunnel lining, and welded structural steel verification dominate this segment. Italian infrastructure concessionaires and Spanish high-speed rail operators specify ground-penetrating radar and ultrasonic pulse velocity equipment.
- Oil & Gas:Refinery turnaround inspection and subsea pipeline integrity assessment require explosion-proof certified equipment. Norwegian offshore operators and Rotterdam terminal maintenance crews prioritize radiographic and electromagnetic corrosion mapping tools.
Aerospace represents the premium tier by specification intensity. Automotive offers the broadest volume expansion as electrification reshapes component portfolios.
Application:
Application purpose dictates data management requirements, with quality control demanding permanent records and maintenance favoring rapid turnaround.
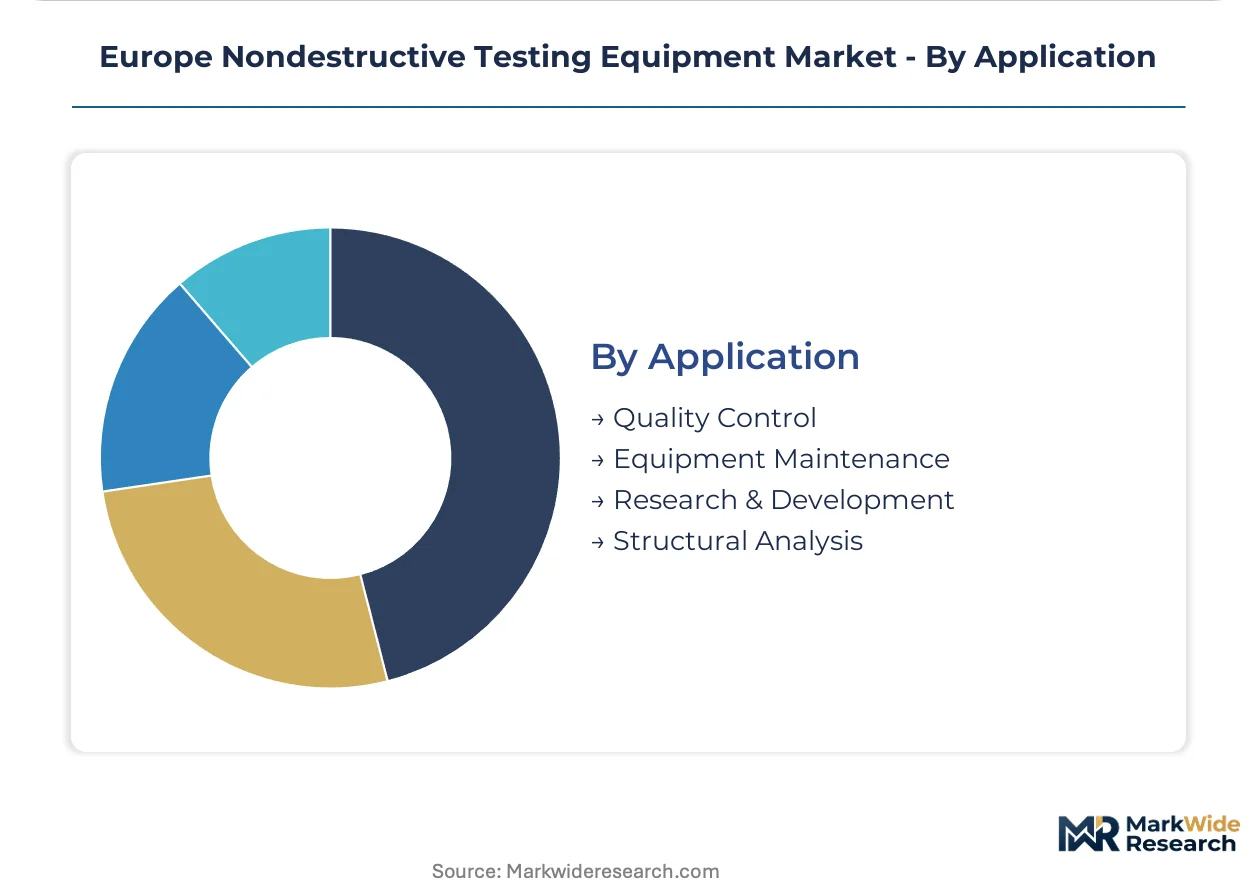
- Quality Control:In-process verification before component release to downstream assembly. German automotive transmission plants and French aeroengine casting facilities mandate statistical process control integration with inspection data systems.
- Equipment Maintenance:Periodic integrity assessment of installed assets during scheduled outages. British North Sea platform operators and Belgian chemical plant maintenance teams contract inspection services on availability-based terms rather than capitalizing equipment.
- Research & Development:Material characterization and failure analysis supporting product design iteration. University laboratories in Switzerland and the Netherlands plus corporate R&D centers in Sweden employ high-resolution computed tomography for additive manufacturing defect studies.
- Structural Analysis:Load-testing and residual stress measurement for civil engineering certification. Danish bridge authorities and Austrian dam safety inspectors apply acoustic emission and strain gauging for long-term performance validation.
Quality control dominates current revenue contribution. Equipment maintenance applications expand most quickly as asset operators unbundle inspection from ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's NDT equipment trade flows reflect a structural import dependence for specialized radiographic sources and phased array transducers, with Germany, France, and the UK serving as the primary demand anchors while component manufacturing concentrates in Switzerland and the Netherlands.
Germany
Bavarian turbine manufacturers and Stuttgart automotive suppliers drive ultrasonic system procurement for thick-section steel verification. The KBA enforces component traceability standards that mandate certified inspection protocols across aerospace supply chains. Hamburg's port infrastructure operators deploy electromagnetic testing for subsea pipeline corrosion mapping in North Sea extraction fields.
France
Île-de-France nuclear maintenance contractors sustain recurring demand for radiographic pressure vessel inspection under ASN oversight. The EU F-Gas Regulation accelerates coolant system replacement in legacy testing equipment across the national fleet. Toulouse aerospace clusters have standardized infrared thermography for carbon-fiber wing structure delamination screening.
United Kingdom
North Sea platform operators contract inspection services on availability terms rather than capitalizing equipment ownership. The Health and Safety Executive mandates periodic structural verification for offshore installations under COMAH regulations. Scottish wind farm developers require phased array ultrasonic systems for blade bond-line integrity at scale.
Italy
Emilian foundries and Lombard automotive transmission plants deploy digital radiography for real-time casting verification. REACH substance restrictions on inspection penetrants force formulation reformulation across the chemical supply base. Turin-based powertrain manufacturers integrate eddy current testing into crankshaft production lines.
Poland
Rzeszów aerospace supplier networks lack mature NDT infrastructure, creating greenfield equipment demand from Airbus and Lockheed Martin contractors. The Polish Centre for Accreditation implements EN ISO 9712 certification pathways that constrain operator deployment velocity. Silesian heavy machinery rebuilders constitute the core installed base for magnetic particle testing systems.
Europe Nondestructive Testing Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around inspection heritage conglomerates, specialized electromagnetic array developers, and third-party certification gatekeepers. Three strategic archetypes dominate: radiographic system deployers leveraging legacy film-to-digital transition, phased array ultrasonic specialists capturing aerospace turbine demand, and notified body affiliates controlling market access workflows. Competitive moves center on equipment-as-a-service business model unbundling and AI-embedded defect recognition algorithm development.
Within the heritage conglomerate tier, Waygate Technologies GmbH and YXLON International GmbH exemplify German-engineered radiographic system deployment. Eddyfi Europe SAS occupies the electromagnetic specialist position. TÜV Rheinland anchors the certification-gatekeeper archetype, with its notified body status shaping vendor time-to-certification timelines across the continent.
| Leading Market Players |
|---|
| Waygate Technologies GmbH |
| YXLON International GmbH |
| Evident Europe GmbH |
| Nikon Metrology NV |
| Eddyfi Europe SAS |
| TÜV Rheinland |
| TÜV SÜD |
| Applus+ |
| Bureau Veritas |
| Others |
Pricing and Supply Chain Analysis
Switzerland's precision transducer manufacturing and Dutch digital radiography panel fabrication concentrate upstream margin capture, while downstream pricing power fragments across German automotive OEMs, French nuclear maintenance contractors, and Scandinavian wind farm operators unbundling inspection from equipment ownership.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to EASA-certified portable systems with embedded AI defect recognition, while economy tiers serve Polish and Czech maintenance depots running legacy film-based workflows. Cost compression in standard-tier ultrasonic equipment is intensifying because German automotive suppliers demand bundled after-sales service contracts. Tier-1 aerospace manufacturers exhibit the lowest price sensitivity due to zero-failure mandates, whereas Silesian heavy machinery rebuilders negotiate aggressively on magnetic particle testing systems.
Supply Chain Analysis
Extended payment terms from Swiss and German component suppliers now stretch to 90-120 days, straining working capital for smaller radiographic system assemblers. X-ray tube manufacturing concentrates in Germany, Switzerland, and the United States, while phased array transducers draw from Dutch and Japanese semiconductor fabrication. Single-source vulnerability runs through helium tracer gas supply from Qatar and US production facilities. Distribution runs through TÜV Rheinland and DEKRA certification channels that gate market access before equipment reaches end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's conformity obligations for automated defect recognition algorithms constitute a regulatory inflection that will concentrate vendor positions among first movers embedding compliance during product development.
For Market Incumbents: Entrench certification relationships with TÜV Rheinland and DEKRA to compress competitor time-to-market. Deepen backward integration into phased array transducer production to offset Swiss supply bottlenecks. The priority lever is preemptive AI Act documentation before notified bodies finalize sector-specific guidance.
For New Entrants and Emerging Players: Pursue Poland's Rzeszów aerospace cluster where Airbus and Lockheed Martin supplier networks lack mature NDT infrastructure. Target equipment-as-a-service contracts with Danish and Scottish wind farm operators who reject capital ownership. The most penetrable entry angle is remote diagnostic subscriptions bundled with blade inspection availability guarantees.
For Investors and Strategic Acquirers: Capital is best deployed toward electromagnetic array specialists with EN ISO 9712 training academy affiliations that constrain operator supply. The five-to-ten year viability window favors vendors controlling both hardware and certified workforce pipelines. Watch for notified body interpretation divergence between TÜV entities as the signal for which compliance-heavy players will capture accelerated market access.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Act Compliance Embedding | First-mover vendors capturing TÜV Rheinland pre-certification lock in aerospace procurement. |
| Equipment-as-a-Service Launch | Danish wind operators contracting blade inspection on availability terms displace capital sales. |
| Phased Array Transducer Backward Integration | Swiss precision manufacturing capture reduces exposure to Dutch semiconductor bottlenecks. |
| Poland Greenfield Infrastructure Deployment | Rzeszów supplier networks lack mature NDT systems for Airbus contractor qualification. |
| Remote Diagnostic Platform Integration | Cloud-native inspection data management compresses feedback loops for Scandinavian asset operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA substance restriction filings, EU notified body guidance documents, and EN ISO 9712 certification registry data. Interviews with maintenance directors at French nuclear pressure vessel contractors, procurement leads at German automotive OEM supplier parks, and aftermarket service heads at British North Sea platform operators informed demand-side validation. Bottom-up equipment shipment tracking triangulates against top-down manufacturing value-added estimates across the analysis window.
Forecast inputs include ultrasonic frequency band penetration rates, digital radiography panel displacement curves, and composite material adoption in European aviation. Segmentation dimensions span product type, technology, end user, and application purpose with regional regulatory cluster overlays. CAGRs derive from installed base refresh cycles, F-Gas Regulation compliance deadlines, and AI Act implementation phasing throughout the projection horizon. Helium supply concentration and REACH substance restriction timelines feed scenario-weighted outcomes.
Macroeconomic conditions sit as an overlay; deviation in European defense spending, offshore wind installation rates, or nuclear plant extension decisions would shift the trajectory. Forecasts reflect documented assumptions about notified body certification timelines and operator training pipeline constraints. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Hybrid Supercapacitor Lifetime and Safety Test Equipment Market
Test and Measurement
Torsion Tester Market
Test and Measurement
E-Beam Wafer Inspection System Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
Digital Weighing Machine Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market
Test and Measurement
Durometer Calibration Service Market
Test and Measurement
United States Signal Generator Market
Test and Measurement
Ground Grid Tester Market
Test and Measurement
Global Laser Tracker Market
Test and Measurement
Miniaturized Package Solder Joint Reliability Test Equipment Market
Test and Measurement
Battery Drop Tester Market
Test and Measurement
Scuff Tester Market
Test and Measurement
Metrology Software Market
Test and Measurement
Tribometer Market
Test and Measurement
Latin America Measurement and Test Equipment Market