
 Wafer Testing Services Market | 2026-2036
Wafer Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Wafer Testing Services Market Analytics
Taiwan is narrowing its already tight supply of advanced probe card and testing capacity as TSMC expands 3nm and 2nm production. Advantest Corporation leverages its dominant position in system-on-chip test equipment to sustain pricing power across leading-edge nodes. ASE Technology Holding anchors backend testing volumes through its massive Kaohsiung operations. FormFactor specializes in MEMS probe technologies that enable finer pitch requirements at sub-7nm geometries.
Wafer testing services encompass electrical verification of semiconductor dies prior to dicing, employing probe stations, automatic test equipment, and parametric analyzers to measure threshold voltages, leakage currents, and switching speeds against design specifications. These services prevent defective dice from entering expensive packaging flows, preserving yield economics for foundries and integrated device manufacturers. Parametric testing captures the largest revenue share as process control requirements intensify at each node shrink, while RF testing grows fastest as gallium nitride and millimeter-wave devices proliferate in 5G base stations and radar systems. Foundries represent the most concentrated end-user segment, with TSMC and Samsung driving disproportionate testing volume through outsourced and captive arrangements.
ISO 9001 quality management and IEC 60749 environmental testing standards govern qualification protocols, while the EU Chips Act's facility certification requirements are redirecting testing investment toward European soil. The U.S. CHIPS and Science Act's domestic content incentives similarly reshape where probe and test capacity gets deployed. Stakeholders must monitor how export control classifications on advanced test equipment affect cross-border service delivery and equipment procurement strategies.
Market Dynamics
Advanced node migration toward 3nm and 2nm geometries is compressing test cycle times while multiplying probe card complexity, forcing foundries to renegotiate service contracts and equipment depreciation schedules.
Growth Catalysts
- Automotive semiconductor qualification mandates:Functional safety standards under ISO 26262 require exhaustive wafer-level screening of power management and sensor dies before automotive module integration.
- The EU Chips Act facility certification:Sovereign capacity incentives are redirecting probe and test investment toward European soil, creating captive demand for localized verification services.
- Gallium nitride RF device proliferation:Millimeter-wave components for 5G base stations and radar systems require specialized parametric testing protocols that command premium service rates.
Market Restraints
- Probe card consumable cost volatility:MEMS-based advanced probe cards require noble metal coatings and precision ceramic substrates subject to supply chain disruptions.
- Equipment concentration in East Asian manufacturing clusters:Advantest and Tokyo Seimitsu dominate ATE supply, creating procurement bottlenecks for non-captive testing facilities.
- Sub-7nm contact resistance variability:Finer pitch geometries introduce measurement noise that degrades test correlation with final packaged device performance.
Strategic Opportunities
- India's semiconductor assembly and test ecosystem:PLI scheme incentives and Micron's Gujarat facility are attracting probe card vendors and third-party testing operations.
- Silicon carbide power device verification:Electric vehicle traction inverters require high-voltage wafer-level testing protocols that established analog testers cannot execute.
- AI-driven adaptive test program generation:Machine learning algorithms are compressing test pattern development cycles from weeks to days for complex SoC architectures.
Industry Challenges
- Multi-physics simulation expertise scarcity:Electromagnetic-thermal-mechanical co-simulation skills required for RF probe card design command salaries that mid-tier service providers cannot match.
- ISO 9001 and IEC 60749 certification timelines:Environmental stress qualification protocols for automotive and aerospace end-uses extend customer onboarding by six to nine months.
- Legacy ATE hardware integration with cloud-native analytics platforms:Decades-old tester architectures lack API compatibility with modern yield management systems, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wafer Testing Services Market |
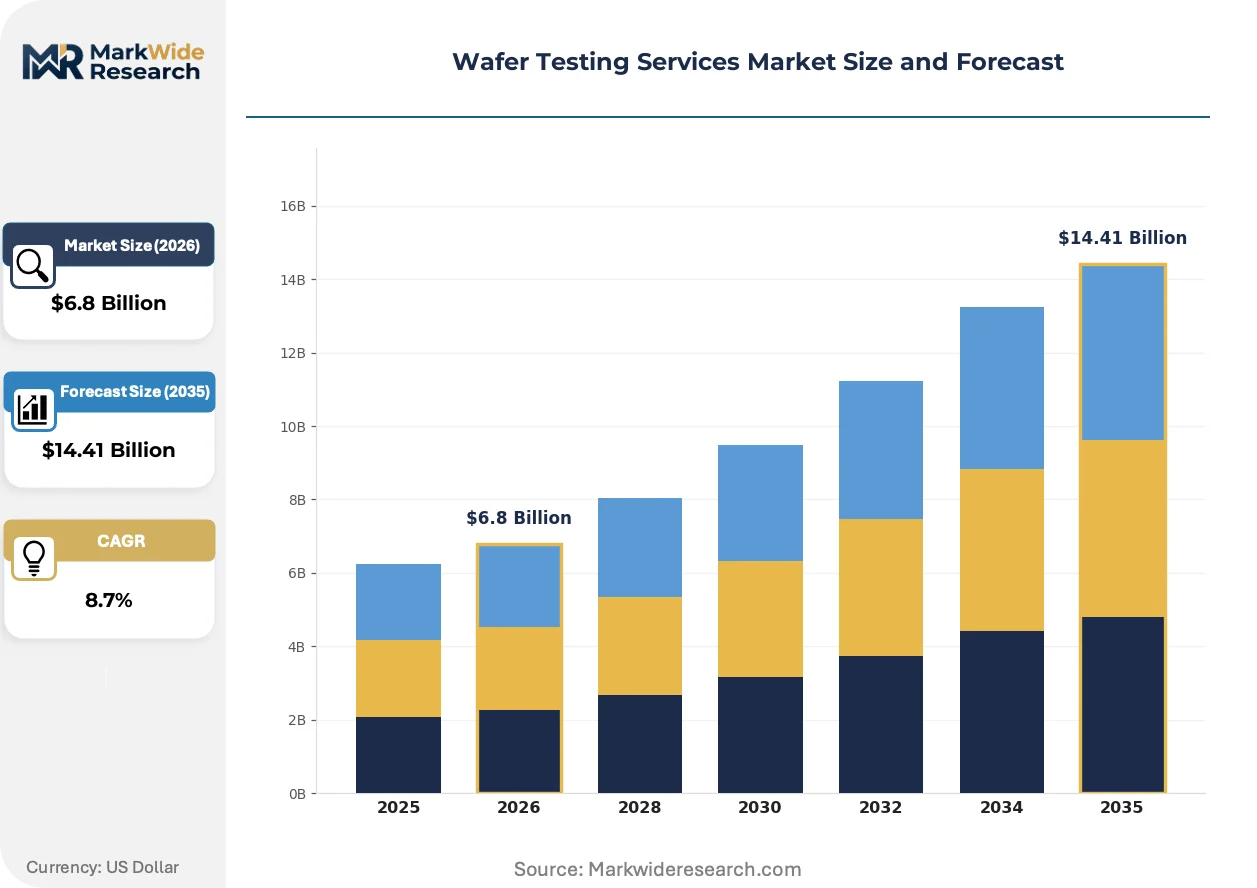
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Parametric Testing, Failure Analysis, Functional Testing, Burn-in Testing Technology: RF Testing, Optical Testing, Digital Testing, Mixed-Signal Testing End User: Semiconductor Manufacturers, Foundries, IC Design Firms, Research Institutions Product Type: Analog ICs, Digital ICs, Memory Chips, Power Devices |
| Companies Covered | Advantest Corporation, ASE Technology Holding Co., Ltd., GlobalFoundries Inc., TSMC, Intel Corporation, FormFactor Inc., Teradyne Inc., Tokyo Electron Limited, MPI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wafer Testing Services Market Evolving Landscape
Cloud-native test data infrastructure is displacing on-premise yield management systems, compressing the feedback loop between wafer fabrication and probe program optimization.
Adaptive test program generation is virtualizing the traditional boundary between device characterization and production screening. Foundries with captive testing operations are deploying machine learning models that dynamically prune test vectors based on real-time defect clustering, reducing average test time per wafer by substantial margins without sacrificing outgoing quality metrics.
The U.S. CHIPS and Science Act's domestic content incentives are reshaping where probe and test capacity gets deployed. Equipment vendors must now qualify local service partners to maintain eligibility for federal facility subsidies, accelerating technician training programs in Arizona and Texas fab clusters.
Foundry customers are consolidating testing spend under long-term partnership frameworks rather than transactional lot-by-lot arrangements. TSMC and Samsung are negotiating multi-year testing commitments that guarantee capacity allocation, displacing spot-market pricing and forcing independent service providers to specialize in niche RF or power device categories where captive capacity remains scarce.
Wafer Testing Services Market Segmentation
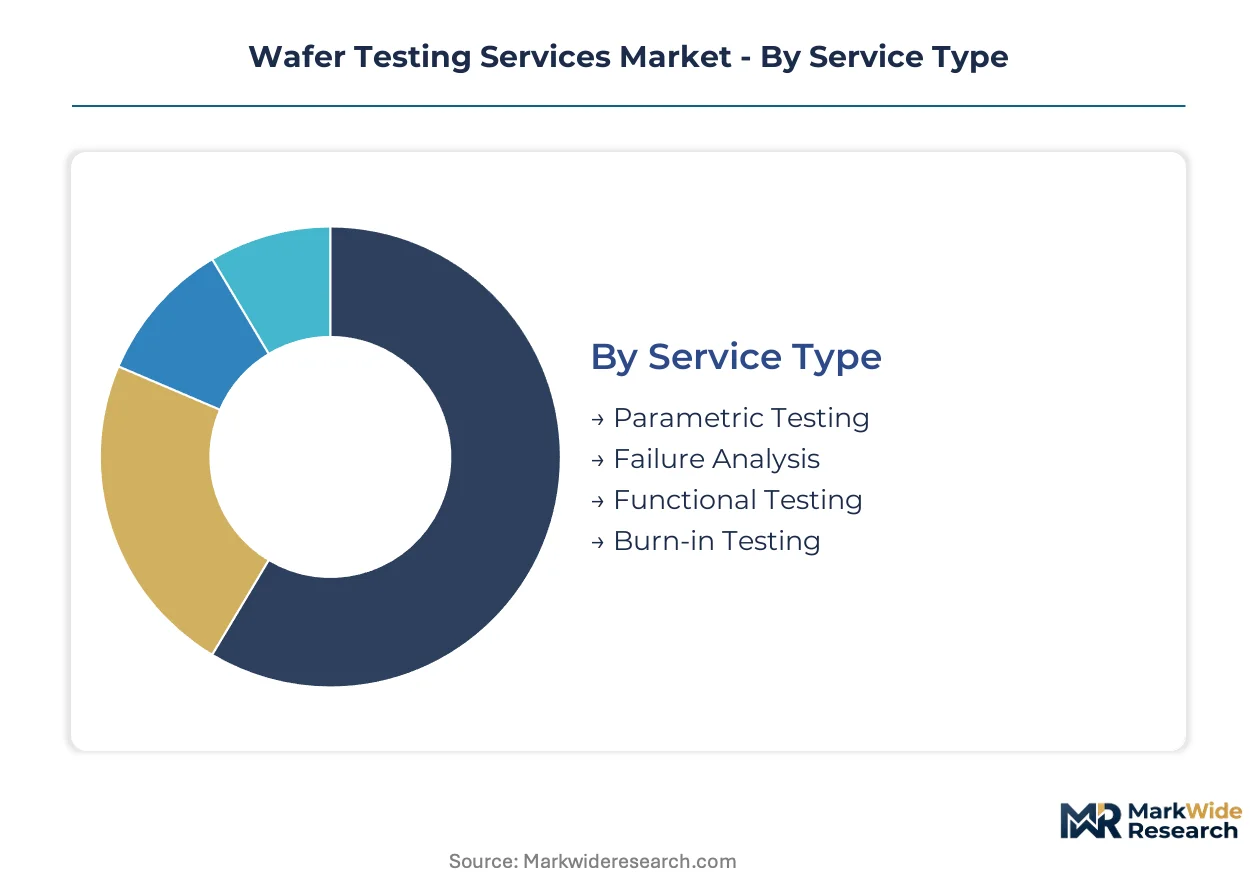
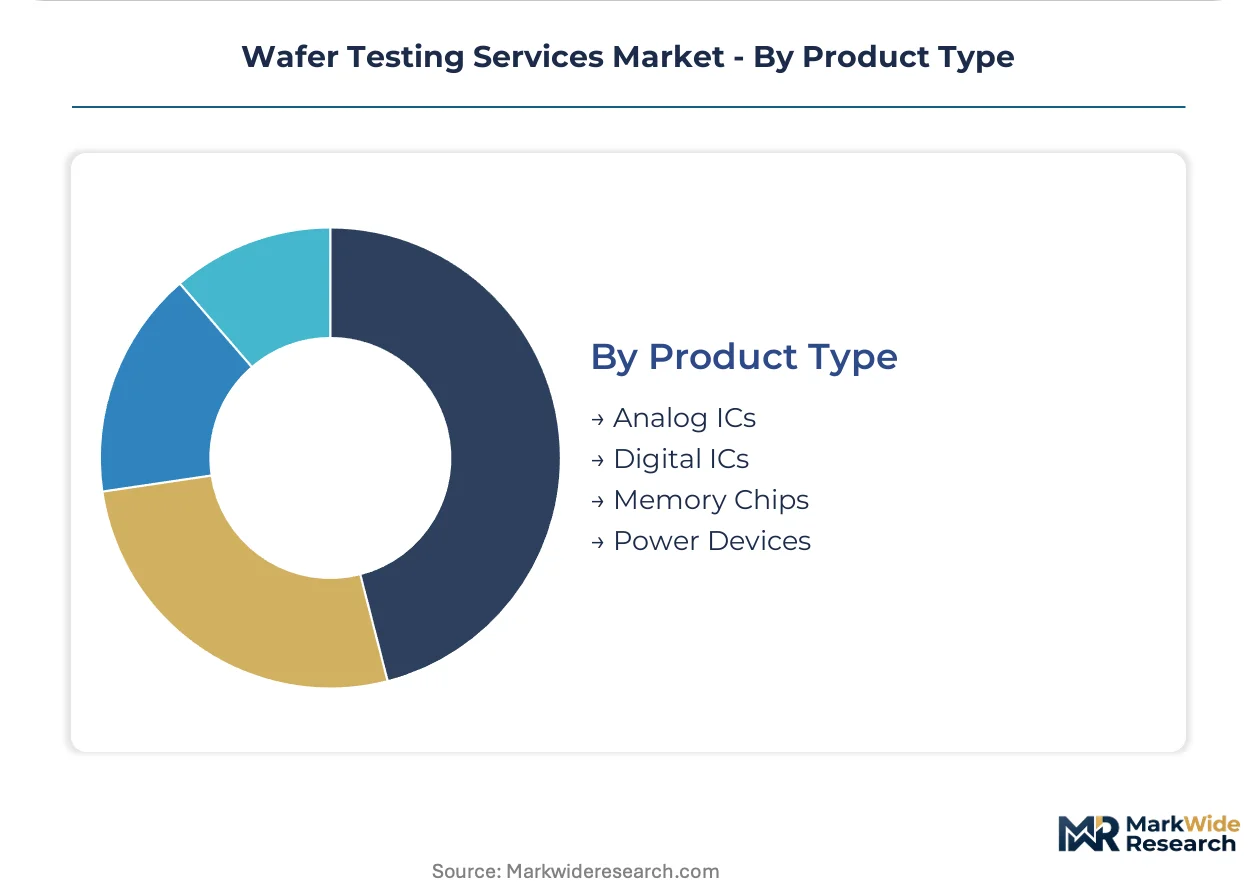
Wafer testing services fragment across four distinct dimensions that shape procurement patterns and margin structures. Service type determines equipment depreciation schedules and consumable intensity. Technology specialization creates pockets of scarcity that command premium pricing. End-user concentration in foundries versus integrated device manufacturers alters contract negotiation leverage. Product type dictates voltage ranges and probe card architectures required.
Service Type:
Cost tier stratification separates routine screening from premium diagnostic services that preserve yield economics at advanced nodes.
- Parametric Testing:Electrical characterization of threshold voltages, leakage currents, and switching speeds against design specifications. Foundries in Taiwan and South Korea drive disproportionate volume through process control requirements that intensify at each node shrink.
- Failure Analysis:Root-cause investigation of electrical anomalies using focused ion beam microscopy and scanning electron microscopy. Automotive semiconductor qualification mandates under ISO 26262 are accelerating adoption of exhaustive wafer-level diagnostic protocols before module integration.
- Functional Testing:Verification of complete device operation against specification sheets. Captures steady demand from mature node production.
- Burn-in Testing:Accelerated life testing under thermal and electrical stress to precipitate early failures. Required for aerospace and defense end-uses with extended reliability requirements.
Parametric testing holds installed capacity. Failure analysis is rotating up the share rankings.
Technology:
Application specialization fragments the market into domains requiring distinct probe architectures and signal conditioning expertise.
- RF Testing:Millimeter-wave and microwave characterization for 5G base stations and radar systems. Gallium nitride device proliferation in telecommunications infrastructure commands premium service rates that exceed standard digital testing margins.
- Mixed-Signal Testing:Simultaneous analog and digital verification for power management and sensor interface devices. Automotive electrification trends in Germany and the United States are concentrating demand for high-voltage mixed-signal protocols.
- Digital Testing:Logic verification at speed for microprocessors and SoC architectures. Foundry captive operations absorb the majority of volume.
- Optical Testing:Photonic device characterization for data center interconnects and LiDAR systems. Emerging demand from silicon photonics integration.
Digital testing holds installed capacity. RF testing is expanding most quickly.
End User:
Customer type determines contract structure, with captive operations favoring long-term partnerships and third-party providers competing on specialized capabilities.
- Foundries:TSMC, Samsung, and GlobalFoundries drive the largest testing volumes through combined captive and outsourced arrangements. Multi-year capacity commitments are displacing spot-market pricing and forcing independent service providers toward niche specializations.
- Semiconductor Manufacturers:Integrated device manufacturers with in-house fabrication maintain captive testing for proprietary process technologies. IDMs in the United States and Japan preserve vertical integration into backend verification.
- IC Design Firms:Fabless semiconductor companies relying on third-party testing services for prototype validation and production screening.
- Research Institutions:Universities and national laboratories requiring flexible, low-volume characterization for advanced materials and novel device architectures.
Foundries hold installed capacity. IC design firms are gaining share fastest.
Product Type:
Volume and margin profiles diverge sharply across device categories, with power devices requiring specialized high-voltage infrastructure that limits supplier participation.
- Power Devices:Silicon carbide and gallium nitride verification for electric vehicle traction inverters and renewable energy systems. High-voltage wafer-level testing protocols exceed capabilities of established analog testers, creating entry barriers for conventional service providers.
- Memory Chips:DRAM and NAND flash testing with massive parallelization requirements. Taiwan and South Korea concentrate manufacturing and associated testing demand.
- Digital ICs:Logic devices including microprocessors, GPUs, and ASICs. Node migration toward 3nm geometries compresses test cycle times while multiplying probe card complexity.
- Analog ICs:Linear devices for signal conditioning and power management. Mature process technologies sustain steady but lower-margin demand.
Memory chips hold installed capacity. Power devices are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TSMC's 3nm and 2nm expansion in Taiwan is compressing probe card supply and testing capacity across the island's Hsinchu and Tainan Science Parks. Taiwan's Industrial Development Bureau coordinates domestic content requirements that align with U.S. CHIPS Act facility certification standards for cross-border equipment flows.
United States
Intel's Ohio and Arizona fab investments are pulling probe and test capacity toward the Southwest and Midwest. The U.S. CHIPS and Science Act's domestic content incentives require equipment vendors to qualify local service partners for federal facility subsidies. Phoenix and Columbus metro areas are absorbing accelerated technician training programs to staff new testing operations.
South Korea
Samsung's Pyeongtaek and Hwaseong foundry complexes drive disproportionate demand for parametric and memory testing protocols. The country's national semiconductor regulator under METI-aligned standards enforces environmental stress qualification for automotive chip exports. Seoul Capital Area suppliers are expanding MEMS probe card fabrication to reduce noble metal coating import dependence.
Japan
Tokyo Seimitsu and Advantest anchor automatic test equipment supply from Nagano and Tokyo prefectures. METI's semiconductor revitalization subsidies prioritize domestic probe card substrate production. Kyoto-Osaka industrial corridor specialists concentrate on ceramic substrate precision manufacturing for sub-7nm contact geometries.
China
Yangtze Memory Technologies and SMIC are scaling captive testing for NAND and mature node logic. MIIT's GB standards and dual carbon goals impose energy efficiency requirements on test floor operations. Shanghai and Beijing clusters are recruiting electromagnetic-thermal simulation talent for RF probe card design.
Germany
Infineon's Dresden and Regensburg power semiconductor fabs require high-voltage wafer-level testing for silicon carbide traction inverters. The EU Chips Act's facility certification redirects probe investment toward Saxony and Bavaria. Munich-area automotive tier-1 suppliers are mandating ISO 26262-compliant screening before module integration.
Wafer Testing Services Market Competitive Landscape
Capability concentration sits with equipment specialists commanding probe card and ATE architectures; scale advantage sits with foundry captive operations absorbing volume through in-house verification. The market structures around three tiers: integrated device manufacturers preserving backward integration into backend testing, pure-play foundries negotiating multi-year capacity commitments, and independent service providers specializing in niche RF or power device categories. Dominant competitive moves include strategic partnerships between equipment vendors and local service providers to secure CHIPS Act eligibility, plus portfolio diversification into silicon carbide and gallium nitride verification protocols.
Within the equipment specialist tier, Advantest Corporation and Tokyo Electron Limited exemplify ATE supply concentration that creates procurement leverage. Teradyne Inc. occupies a position among North American test equipment architects. ASE Technology Holding Co., Ltd. anchors the outsourced assembly and testing segment through its Kaohsiung-scale operations. These three represent distinct archetypes: Japanese precision equipment manufacturing, U.S. system-level test architecture, and Taiwanese backend integration at foundry-adjacent scale.
| Leading Market Players |
|---|
| Advantest Corporation |
| ASE Technology Holding Co., Ltd. |
| GlobalFoundries Inc. |
| TSMC |
| Intel Corporation |
| FormFactor Inc. |
| Teradyne Inc. |
| Tokyo Electron Limited |
| MPI Corporation |
| Others |
Value Network & Pricing Analysis
The Kaohsiung-to-Los Angeles transpacific corridor carries MEMS probe cards and ATE components whose freight cost volatility feeds directly into service pricing spreads between captive foundry operations and independent testing houses.
Pricing Analysis
Geographic price spreads of 40-60% separate Taiwan-based captive testing from European independent providers. Contract-based long-term offtake dominates, with multi-year capacity commitments displacing spot-market transactions. Price differentiation rests on ISO 26262 certification tier and volume scale, with automotive-qualified protocols commanding substantial premiums. Cost compression in standard digital testing is intensifying because foundries are internalizing mature node verification, while RF and power device screening retains pricing power.
Supply Chain Analysis
Upstream feedstock concentration in noble metal coatings and precision ceramic substrates draws from Japan, Germany, and the United States. MEMS probe card fabrication hinges on palladium alloys, alumina nitride substrates, and photoresist chemistries. Single-source vulnerability in Tokyo Seimitsu and Advantest ATE supply creates procurement bottlenecks for non-captive facilities. Distribution runs through foundry-adjacent clusters in Hsinchu, Pyeongtaek, and Phoenix metro areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wafer testing services function as a service-attach opportunity where predictive maintenance contracts and yield analytics subscriptions expand faster than hardware depreciation schedules.
For Market Incumbents: Build switching-cost moats through embedded machine learning diagnostics that lock foundry customers into proprietary data formats. Deepen backward integration into MEMS probe card substrate production to neutralize noble metal supply shocks. TSMC and Samsung's multi-year capacity commitments threaten independent providers with volume starvation. For New Entrants and Emerging Players: India's Gujarat semiconductor cluster represents the most penetrable entry point, with Micron's facility attracting tier-2 probe card vendors and third-party testing operations. Silicon carbide power device verification for electric vehicle traction inverters offers white-space specialization where established analog testers lack capability. Partner with domestic equipment vendors seeking CHIPS Act eligibility through local service qualification. For Investors and Strategic Acquirers: Carve-out targets emerge from IDM captive testing divisions facing margin pressure from foundry outsourcing trends. Five-to-ten year viability favors specialists with RF probe card design expertise and automotive certification credentials. Watch for Infineon and STMicroelectronics divesting non-core verification assets as they consolidate around European fab investments.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Test Program Generation | Machine learning compression of pattern development cycles strengthens Advantest's competitive position against Teradyne. |
| Domestic Content Partnership | Equipment vendors qualifying Arizona and Texas service partners secure U.S. CHIPS Act facility subsidy eligibility. |
| Silicon Carbide Verification Protocol | Specialized high-voltage testing infrastructure addresses electric vehicle inverter demand from Infineon and Wolfspeed. |
| Cloud-Native Yield Analytics Platform | API integration with legacy ATE hardware resolves decades-old middleware compatibility gaps for foundry customers. |
| MEMS Probe Card Substrate Expansion | Kyoto-Osaka ceramic precision manufacturing reduces Japan's import dependence for sub-7nm contact geometries. |
Research Methodology
Cross-validation between equipment vendor shipment disclosures and foundry capex announcements anchors the qualitative findings. Primary interviews with ATE product managers, probe card design engineers, foundry procurement directors, and automotive tier-1 quality assurance leads combined with secondary validation from SEC filings, SEMI equipment market data, and national semiconductor regulator publications. Bottom-up installed capacity estimates and top-down wafer start projections triangulate market sizing.
Calibration against historical node migration patterns and probe card depreciation schedules shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology specialization, end-user category, and product type. CAGRs derive from equipment replacement cycles, foundry capacity expansion timelines, and automotive qualification mandate adoption curves. Node shrink intensity and RF device proliferation serve as industry-specific forecast inputs.
Practitioners should monitor export control classification revisions and sovereign capacity incentive disbursement timelines for early signals. Forecasts reflect assumptions regarding equipment lead times, technician training program graduation rates, and probe card consumable cost trajectories. Cross-checking against SEMI's quarterly equipment billings data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Receptacle Tester Market
Test and Measurement
Latin America Measurement and Test Equipment Market
Test and Measurement
Metrology Services Market
Test and Measurement
Scuff Tester Market
Test and Measurement
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market
Test and Measurement
Rohs Tester Market
Test and Measurement
Test and Measurement Market
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
Continuous Methane Monitoring and Leak Detection Test Equipment Market
Test and Measurement
Surface Vision and Inspection Equipment Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
Digital Height Gauges Market
Test and Measurement
Semiconductor Bond Testing Market
Test and Measurement
Global Non-Destructive Testing and Inspection Market
Test and Measurement
Color Meter Market