
 Global Fixed Zirconia Oxygen Analyzer Market | 2026-2036
Global Fixed Zirconia Oxygen Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fixed Zirconia Oxygen Analyzer Market Analysis
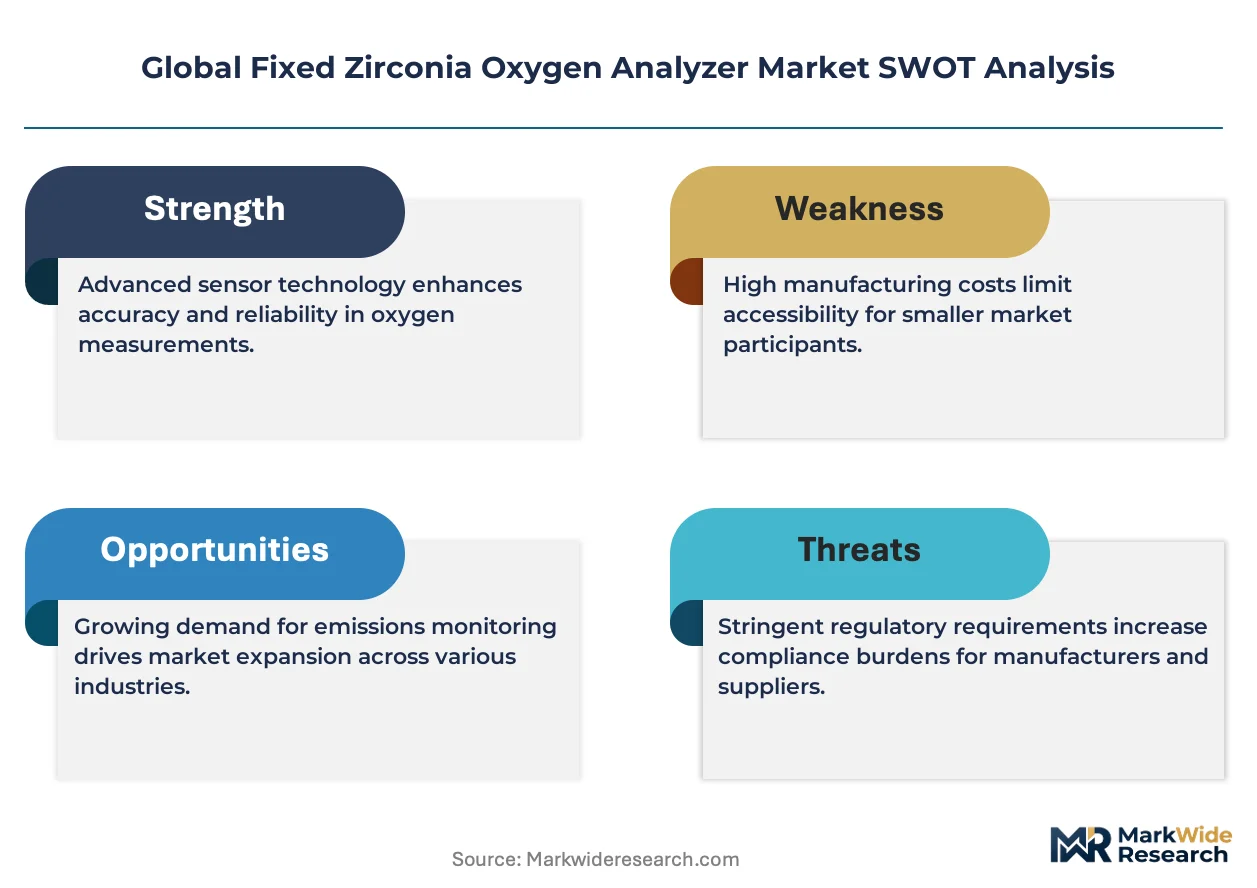
EU Green Deal compliance is consolidating the cost-of-entry calculus for analyzer suppliers targeting European industrial operators. ABB leverages its integrated automation portfolio to anchor long-term service contracts across power generation installations. Yokogawa competes through specialized ceramic sensor expertise that sustains premium positioning in high-temperature combustion applications. Siemens differentiates via digital twin integration, extending hardware margins into software-enabled predictive maintenance revenue streams.
Fixed zirconia oxygen analyzers employ yttria-stabilized zirconia ceramic sensors operating at elevated temperatures, typically generating a voltage signal proportional to the oxygen partial pressure differential between a reference gas and the measured flue gas stream. The primary industrial purpose centers on optimizing combustion efficiency, reducing fuel consumption, and ensuring regulatory emissions compliance in continuous process operations. Fixed analyzers dominate installed capacity across power generation and chemical processing verticals, where continuous monitoring mandates create durable replacement demand cycles. Ceramic sensor technology leads the technology segmentation due to its thermal stability and minimal drift characteristics in aggressive flue gas environments, while electrochemical alternatives occupy cost-sensitive retrofit applications with shorter service intervals.
EPA emissions standards under the Clean Air Act and EU F-Gas Regulation collectively shape product certification requirements and procurement specifications for stack monitoring equipment. China's MEE enforces parallel GB standards that condition market access for imported analyzer systems. Japan's METI administers JIS certification protocols that influence sensor accuracy benchmarks adopted regionally. Stakeholders must monitor evolving carbon border adjustment mechanisms and stack monitoring enforcement intensification as these regulatory instruments progressively harmonize measurement precision requirements across jurisdictions.
Market Dynamics
Power plant operators in China, Germany, and the United States are accelerating boiler retrofit programs to meet tightening stack emissions mandates, compressing replacement cycles for legacy oxygen measurement systems and favoring suppliers with integrated digital service architectures.
Growth Catalysts
- EU F-Gas Regulation Phase-Down:The regulation mandates continuous emissions monitoring for industrial combustion sources, compelling utilities across Germany, Poland, and Italy to upgrade stack analyzer infrastructure.
- Yttria-Stabilized Zirconia Sensors:These ceramic sensors deliver thermal stability above 700°C with minimal drift, sustaining demand in coal-fired and biomass power generation applications where electrochemical alternatives fail.
- China's Dual Carbon Goals:The MEE enforces GB 13223 standards on thermal power plants, driving analyzer procurement from domestic and imported suppliers serving the Yangtze River and Pearl River Delta industrial clusters.
Market Restraints
- Yttrium Oxide Supply Concentration:China controls approximately 90% of global rare earth processing capacity, exposing sensor manufacturers to input cost volatility and export quota uncertainty.
- Electrochemical Substitution:Lower-cost electrochemical analyzers with 12-18 month replacement cycles capture budget-constrained retrofit projects in Southeast Asian and African industrial markets.
- REACH Compliance Burden:The EU's chemical registration requirements add certification timelines and documentation costs for ceramic sensor materials containing stabilizing dopants.
Strategic Opportunities
- India's PLI-Linked Power Sector:Central Electricity Authority mandates for supercritical boiler efficiency create first-mover positioning for analyzer suppliers in Gujarat and Tamil Nadu thermal corridors.
- Hydrogen-Ready Combustion Systems:Hydrogen blending in natural gas turbines demands modified oxygen measurement protocols, opening specification windows for sensor vendors with H2-calibrated product lines.
- Digital Twin Convergence:Integration of analyzer data with plant-level simulation models enables predictive maintenance contracts that extend hardware margins into recurring software revenue.
Industry Challenges
- High-Temperature Ceramic Engineering Talent:Specialized expertise in yttria-stabilized zirconia fabrication and electrode metallization remains concentrated in Japanese and German industrial ceramics clusters, constraining supplier scaling.
- JIS/GB/EPA Multi-Certification Overhead:Analyzer vendors must maintain parallel testing protocols for METI, MEE, and EPA compliance, extending product launch timelines and engineering resource allocation.
- Legacy DCS Integration Complexity:Brownfield power plants operate proprietary distributed control systems from the 1990s, requiring custom signal conditioning hardware that fragments analyzer product standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fixed Zirconia Oxygen Analyzer Market |
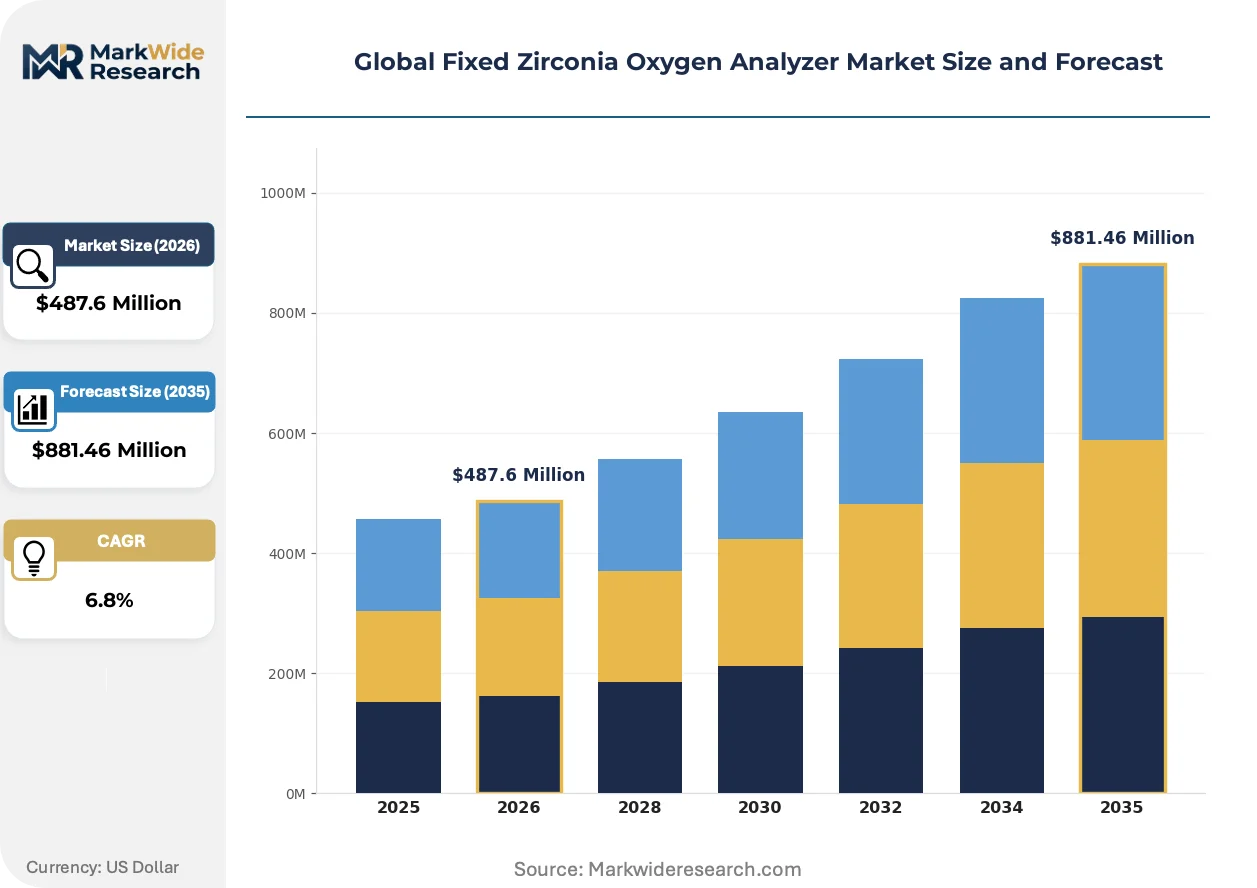
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Fixed Analyzers, Online Analyzers, Laboratory Analyzers Industry Vertical: Power Generation, Oil & Gas, Chemical Processing, Wastewater Treatment Technology: Ceramic Sensors, Infrared Sensors, Electrochemical Sensors, Laser Technology End User: Manufacturers, Utility Providers, Research Institutions, Environmental Agencies |
| Companies Covered | ABB, Yokogawa, AMETEK, Emerson, Fuji Electric, Siemens, Teledyne Analytical Instruments, General Electric, Toray Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fixed Zirconia Oxygen Analyzer Market Emerging Trajectories
Analyzer architecture is converging around edge-computing-enabled sensors that preprocess flue gas data locally, reducing latency for closed-loop combustion control while generating telemetry streams for remote diagnostics.
Multi-parameter sensing modules are unifying oxygen, carbon monoxide, and temperature measurement in single probe housings. Combined-cycle power plants in Texas and North Rhine-Westphalia deploy these integrated sensors to reduce stack penetration points and simplify maintenance access. This convergence is compressing the addressable market for standalone single-gas analyzers while elevating specification requirements for sensor cross-sensitivity compensation algorithms.
The EPA's Good Neighbor Plan and corresponding state implementation plans are tightening ozone precursor emissions limits for cross-state air pollution. Coal and gas-fired generators in the Ohio River Valley and Southwest must demonstrate continuous compliance through certified stack monitoring equipment. Analyzer vendors are responding by pre-certifying sensor configurations for 40 CFR Part 75 protocols, accelerating utility procurement cycles in affected air quality management districts.
Power producers are unbundling hardware procurement from long-term service agreements, separating capital budget ownership from operational expenditure accountability. This split is displacing traditional bundled sales models in US independent power producers and European merchant generation fleets. The shift is most pronounced among private equity-backed thermal assets in Texas ERCOT and UK unabated gas plant portfolios, where operational flexibility outweighs capital efficiency priorities.
Global Fixed Zirconia Oxygen Analyzer Market Segmentation
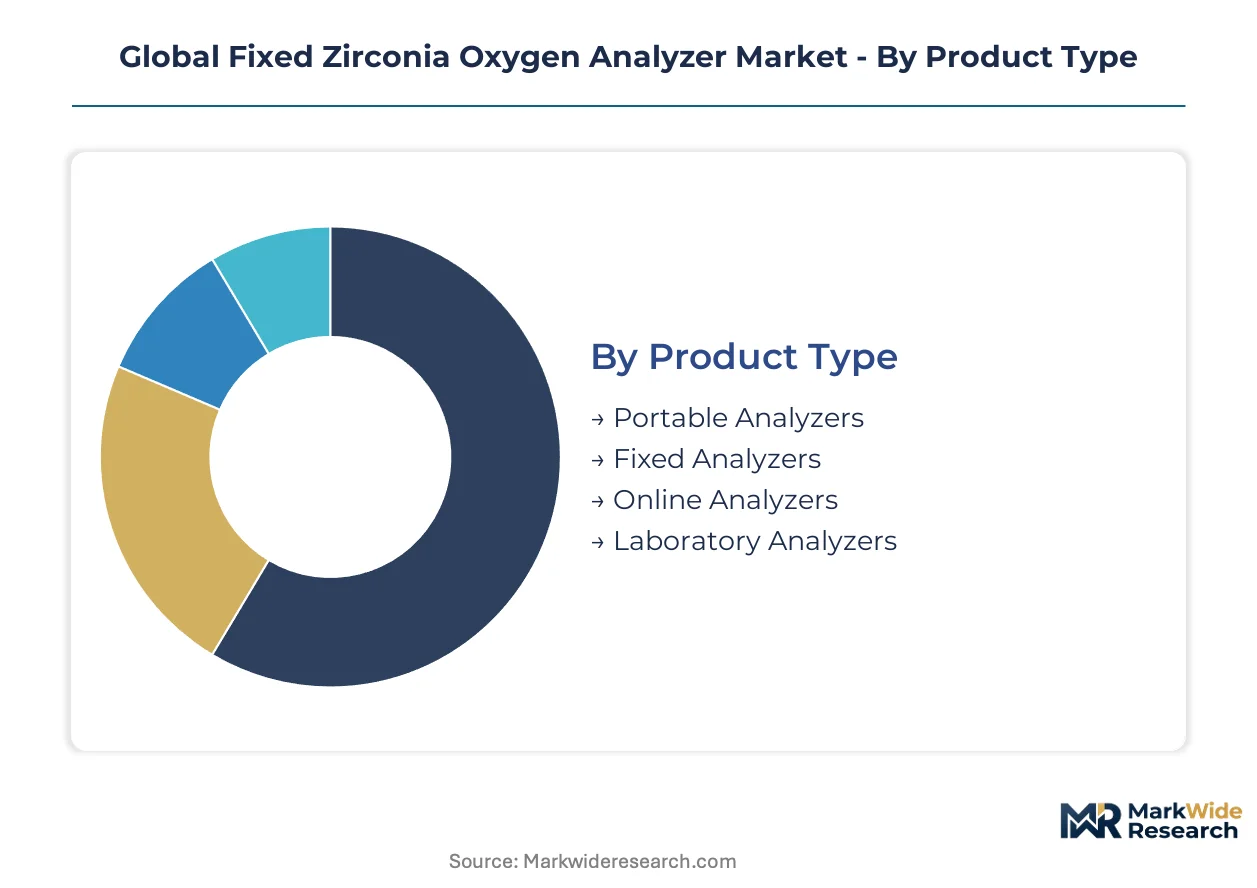
Fixed zirconia oxygen analyzers serve distinct operational regimes across product configurations, industrial applications, and sensing technologies. Segmentation reveals where replacement cycles compress and where specification requirements diverge between continuous process monitoring and intermittent laboratory validation.
Product Type:
Upgrade and replacement cycles vary sharply across installation permanence, with fixed systems commanding decade-long service intervals while portable units face accelerated obsolescence from sensor drift and calibration demands.
- Fixed Analyzers:Permanently installed systems with heated zirconia probe assemblies designed for continuous flue gas monitoring in power plant stacks and industrial boilers. Demand concentrates in China's Yangtze River Delta and Germany's Rhine-Ruhr industrial corridor as MEE and EU F-Gas Regulation enforcement intensifies continuous emissions monitoring mandates.
- Portable Analyzers:Battery-operated handheld units with quick-connect probe adapters for spot-checking combustion efficiency and periodic calibration verification. Field service teams at Texas independent power producers and Polish district heating operators deploy these for stack testing audits where permanent installation proves uneconomical.
- Online Analyzers:Rack-mounted systems integrating sample conditioning and digital communication protocols for centralized control room deployment.
- Laboratory Analyzers:Bench-top precision instruments with temperature-controlled sensor chambers for reference gas calibration and R&D applications.
Volume placements concentrate in Fixed Analyzers; the faster expansion belongs to Portable Analyzers.
Industry Vertical:
Cost-tier differentiation separates capital-intensive continuous monitoring installations from budget-constrained intermittent compliance verification across verticals.
- Power Generation:Coal, gas, and biomass-fired plants deploying zirconia probes for combustion optimization and EPA 40 CFR Part 75 emissions reporting. Supercritical boiler retrofits in India's Gujarat and Tamil Nadu thermal corridors drive procurement from domestic system integrators and imported sensor suppliers.
- Chemical Processing:Ethylene crackers and ammonia synthesis loops requiring oxygen measurement for process safety and yield optimization. Gulf Coast petrochemical complexes in Texas and Louisiana specify explosion-proof probe housings for hazardous area classification compliance.
- Oil & Gas:Refinery fired heaters and gas turbine combustion systems where oxygen trim control reduces fuel gas consumption.
- Wastewater Treatment:Anaerobic digester biogas monitoring and odor control combustion applications with lower temperature operating envelopes.
Revenue concentration sits with Power Generation; Chemical Processing is climbing the fastest on process safety specification tightening.
Technology:
Sensor technology selection tracks operating temperature requirements, drift tolerance, and total cost of ownership across deployment lifecycles.
- Ceramic Sensors:Yttria-stabilized zirconia electrochemical cells operating above 700°C with Nernst voltage output proportional to oxygen partial pressure differential. Japanese and German industrial ceramics clusters supply probe assemblies for high-temperature coal-fired applications where electrochemical alternatives degrade.
- Electrochemical Sensors:Galvanic fuel cell designs with polymer electrolyte membranes for ambient-temperature measurements in confined space safety monitoring. Southeast Asian industrial markets favor these for budget-constrained retrofit projects despite 12-18 month replacement cycles.
- Infrared Sensors:Non-dispersive photometric detection for cross-interference-resistant measurements in complex gas matrices.
- Laser Technology:Tunable diode laser absorption spectroscopy for in-situ measurements without sample extraction systems.
Installed base dominance belongs to Ceramic Sensors; Laser Technology is gaining share fastest on reduced maintenance access requirements.
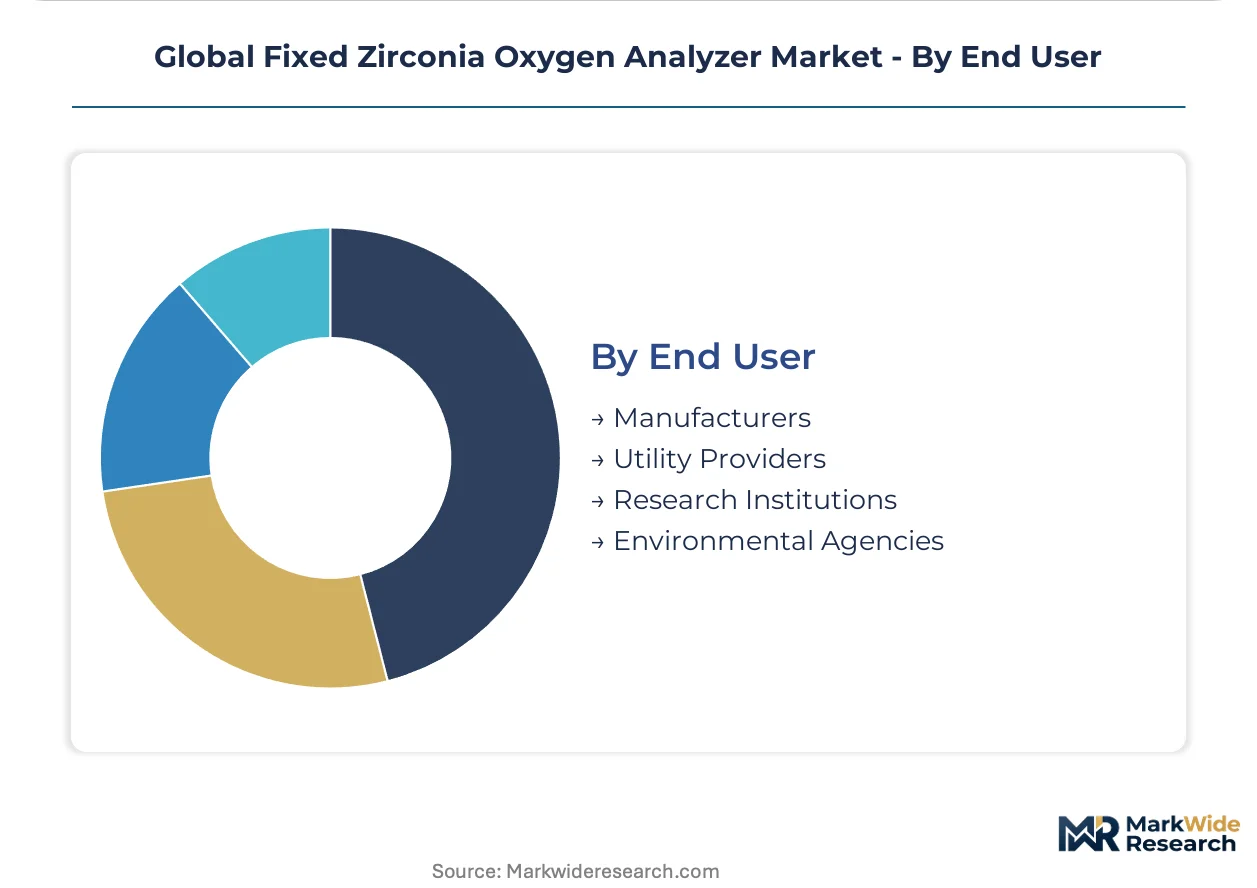
End User:
Procurement authority fragmentation separates capital budget ownership from operational expenditure accountability across user categories.
- Utility Providers:State-owned and independent power producers with centralized procurement departments negotiating multi-site framework agreements. ERCOT merchant generators and UK unabated gas plant portfolios increasingly unbundle hardware purchase from long-term service contracts.
- Manufacturers:Steel mills, cement kilns, and pulp mills with in-house instrumentation teams managing analyzer calibration and probe replacement schedules. German industrial operators under EU ETS compliance pressure prioritize integrated digital service architectures.
- Environmental Agencies:Regulatory enforcement bodies specifying certified reference methods for stack testing and compliance verification.
- Research Institutions:Universities and national laboratories developing next-generation combustion diagnostics and sensor materials.
Procurement volume concentrates among Utility Providers; Manufacturers show the steepest expansion trajectory on industrial decarbonization capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, Germany, and the United States concentrate procurement authority for fixed zirconia oxygen analyzers as industrial decarbonization investments intensify. Boiler retrofit programs across these markets compress replacement cycles for legacy measurement systems.
China
Supercritical boiler deployments in the Yangtze River Delta and Pearl River Delta industrial clusters drive analyzer procurement volumes. The MEE enforces GB 13223 standards on thermal power plants, mandating continuous emissions monitoring infrastructure. Domestic suppliers and imported sensor vendors compete for contracts in Jiangsu and Guangdong provinces where coal-fired capacity upgrades accelerate.
Germany
Rhine-Ruhr industrial corridor operators prioritize integrated digital service architectures under EU ETS compliance pressure. The EU F-Gas Regulation compels utilities across Germany, Poland, and Italy to upgrade stack analyzer infrastructure. Power generators in North Rhine-Westphalia deploy multi-parameter sensing modules to reduce stack penetration points and simplify maintenance access.
United States
Independent power producers in Texas ERCOT and merchant generation fleets increasingly unbundle hardware procurement from long-term service agreements. EPA 40 CFR Part 75 protocols drive pre-certified sensor configurations for coal and gas-fired generators in the Ohio River Valley. Combined-cycle plants in Texas deploy integrated oxygen, carbon monoxide, and temperature sensors for closed-loop combustion control.
India
Central Electricity Authority mandates for supercritical boiler efficiency create first-mover positioning for analyzer suppliers in Gujarat and Tamil Nadu thermal corridors. The PLI-linked power sector attracts domestic system integrators and imported sensor suppliers. Thermal asset operators in these states face compressed procurement timelines as efficiency standards tighten.
Japan
METI-administered JIS certification protocols influence sensor accuracy benchmarks adopted regionally across Asia-Pacific. Industrial ceramics clusters in Japan supply probe assemblies for high-temperature applications where electrochemical alternatives degrade. Domestic vendors leverage specialized ceramic sensor expertise to sustain premium positioning in combustion-intensive process industries.
Global Fixed Zirconia Oxygen Analyzer Market Vendor Landscape
Japanese and German producers anchor the premium-tier sensor supply; Chinese fabricators hold the cost-optimized retrofit segment. The vendor base stratifies across integrated automation conglomerates, specialized ceramic sensor houses, and regional system integrators. Three archetypes dominate: diversified industrial technology groups with service contract ecosystems, focused sensor specialists with materials science depth, and domestic champions leveraging regulatory familiarity. Competitive moves center on digital twin integration for predictive maintenance revenue and hydrogen-calibrated product line extensions.
Within the integrated automation tier, ABB leverages its portfolio breadth to anchor long-term service contracts, while Yokogawa occupies a position exemplifying specialized ceramic sensor expertise. Siemens represents the digital convergence archetype, extending hardware positioning through software-enabled predictive maintenance architectures. These three entities illustrate how competitive positioning fragments across service integration, materials specialization, and digital platform strategies.
| Leading Market Players |
|---|
| ABB |
| Yokogawa |
| AMETEK |
| Emerson |
| Fuji Electric |
| Siemens |
| Teledyne Analytical Instruments |
| General Electric |
| Toray Engineering |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation Phase-Down enforcement gates qualified supply access and premium-tier pricing power for analyzer vendors serving European industrial operators. Compliance-certified ceramic sensor manufacturers command lead-time premiums while non-certified suppliers face procurement exclusion from utility framework agreements.
Pricing Analysis
Short lead-time availability commands premium positioning against spot-inventory discounting in project-driven procurement cycles. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Cost compression in economy-tier electrochemical substitutes is intensifying because Southeast Asian budget retrofit demand pulls manufacturing capacity away from ceramic probe assembly. Independent power producers in Texas ERCOT show highest price sensitivity; German Rhine-Ruhr operators under EU ETS compliance pressure exhibit lowest.
Supply Chain Analysis
China's domestic-content mandates for GB 13223 certified equipment are reshaping sourcing patterns for analyzer system integrators. Yttrium oxide feedstock draws from Chinese rare earth processing clusters, Japanese industrial ceramics houses, and German sensor fabrication facilities. Electrode metallization materials and zirconia substrate supply hinge on concentrated East Asian chemical processing capacity. Single-source vulnerability runs through yttrium oxide export quota administration. Distribution runs through authorized system integrator networks and direct utility procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fixed zirconia oxygen analyzer market constitutes a vertical-integration race where control over yttria-stabilized zirconia ceramic fabrication determines margin capture. Players are pursuing backward integration into rare earth oxide refining and electrode metallization to defend sensor cost structures.
For Market Incumbents: Anchor long-term service contract ecosystems around digital twin-enabled predictive maintenance architectures to lock out electrochemical substitution threats. Deepen backward integration into yttrium oxide supply through offtake agreements with Chinese rare earth processors or alternative Australian feedstock development. Invest in JIS/GB/EPA multi-certification testing infrastructure to compress product launch timelines against emerging Asian competitors.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in India's PLI-linked power sector creates white-space positioning for domestic system integrators with localized service networks. Target Gujarat and Tamil Nadu thermal corridors where Central Electricity Authority mandates compress procurement timelines and foreign suppliers face certification delays. Pursue hydrogen-calibrated product line development ahead of H2-blending turbine specification windows.
For Investors and Strategic Acquirers: First hydrogen-ready combustion system deployments in North Rhine-Westphalia and Texas ERCOT are the leading indicator that sensor vendors with H2-calibrated protocols will command acquisition premiums. Five-to-ten year viability favors specialized ceramic sensor houses with materials science depth over diversified automation conglomerates with service contract saturation. Monitor METI JIS certification protocol revisions as signal for regional accuracy benchmark shifts that could reposition competitive tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Oxide Supply | Secures yttrium oxide feedstock against Chinese export quota volatility for ceramic sensor manufacturers. |
| Hydrogen-Calibrated Product Line Extension | Captures specification windows in H2-blending natural gas turbines across German and US power fleets. |
| Digital Twin Platform Integration | Extends hardware margins into recurring predictive maintenance revenue with Siemens-type software architectures. |
| Multi-Certification Testing Infrastructure Investment | Compresses JIS/GB/EPA parallel launch timelines to accelerate market entry in regulated procurement cycles. |
| Localized Service Network Buildout in India | Positions for PLI-linked power sector procurement where domestic content preferences favor local integrators. |
Methodological Framework
Document review covered EPA 40 CFR Part 75 compliance filings, EU ETS monitoring equipment specifications, and MEE GB standard enforcement records, complemented by interviews with power plant instrumentation managers, ceramic sensor R&D directors, utility procurement officers, and aftermarket service heads. Secondary validation drew from EIA power generation statistics, IEA industrial emissions reports, customs trade data for analyzer equipment, and SEC filings from diversified automation suppliers. Bottom-up unit deployment estimates triangulated against top-down market sizing from regulatory mandate coverage requirements.
Cross-referencing historical replacement cycle patterns with expert panel input on supercritical boiler retrofit timelines shaped the projection framework across the analysis window. Segmentation dimensions modeled include product configuration permanence, industry vertical combustion intensity, sensor technology temperature tolerance, and end-user procurement authority structure. CAGRs derived from regression against regulatory enforcement intensity indices and industrial decarbonization capital deployment trajectories. Hydrogen blending adoption curves and carbon border adjustment mechanism implementation schedules served as scenario-weighting inputs.
Underlying measurement precision varies by segment; fixed analyzer installed base estimates carry tighter precision than portable unit spot-check frequency projections. Forecasts reflect documented assumptions regarding regulatory enforcement continuity, rare earth supply chain stability, and electrochemical substitution elasticity. Ceramic sensor yield rates and yttrium oxide price volatility constitute primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market
Analytical Instruments
Laser-Based Gas Analyzers Market
Analytical Instruments
XRF Analyzer Market
Analytical Instruments
Next Generation Mass Spectrometer Market
Analytical Instruments
ICP-MS System Market
Analytical Instruments
Air Sampling Equipment Market
Analytical Instruments
Global Gel Documentation Systems Market
Analytical Instruments
Signal Analyzer Market
Analytical Instruments
Microplate Instrumentation and Systems Market
Analytical Instruments
Spectroscopy Equipment and Supplies Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Dioxin Analyzer Market
Analytical Instruments
Microplate Absorbance Reader Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market
Analytical Instruments
Array Instruments Market
Analytical Instruments
Air Sampler Market