
 Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market | 2026-2036
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market Insights
Software-defined thermal profiling is consolidating how test protocols get licensed and updated across installed bases. Teradyne leverages its instrumentation heritage to anchor high-throughput fatigue characterization for 2.5D and 3D packages. Keysight Technologies sustains R&D intensity in electrothermal simulation-to-hardware correlation workflows. Advantest competes through specialized chambers that support extreme temperature ramp rates demanded by chiplet architectures.
Chiplet-based system thermal cycling and interconnect fatigue test systems comprise precision environmental chambers, mechanical stress applicators, and electrical continuity monitors that subject multi-die assemblies to repeated temperature excursions between minus sixty-five and one hundred fifty degrees Celsius while tracking solder joint and microbump degradation. These systems verify reliability before high-volume production of advanced packages incorporating heterogeneous dies from multiple process nodes. Fatigue testers command margin pools due to the mechanical complexity of simulating decade-long interconnect lifetimes in compressed test schedules. Hybrid test systems represent the fastest-growing technology category as packaging houses seek consolidated platforms that combine thermal, vibration, and electrical stress in single workflows. Semiconductor validation applications lead volume demand because chiplet disaggregation multiplies the number of inter-die interfaces requiring qualification.
FDA device-quality traceability requirements and EPA energy-efficiency standards for laboratory equipment shape test system design specifications in the United States. Taiwan's Industrial Development Bureau and South Korea's Ministry of Trade, Industry and Energy channel domestic subsidy programs toward local test equipment procurement. Stakeholders must monitor how JEDEC standards evolution for chiplets redefines pass-fail thresholds and whether China's GB standard harmonization opens or constrains cross-border equipment certification paths.
Market Dynamics
Heterogeneous integration roadmaps at Intel, TSMC, and Samsung Foundry are compressing validation timelines for multi-die packages, forcing test equipment suppliers to accelerate thermal ramp rates and expand electrical monitoring channel counts. This structural pressure cascades through procurement specifications at advanced packaging facilities.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases drives replacement of conventional refrigerants in environmental chambers, creating equipment refresh cycles at European semiconductor labs.
- Copper-pillar microbump architectures:Higher current density and thermal stress concentration in 2.5D/3D packages multiply interconnect interfaces requiring fatigue qualification per JEDEC standards.
- Taiwan's Hsinchu Science Park:Concentrated foundry and OSAT capacity generates clustered demand for high-throughput thermal cycling systems with sub-minute ramp capabilities.
Market Restraints
- Helium supply volatility:Cryogenic cooling systems depend on helium for extreme low-temperature cycling, with price spikes and allocation constraints disrupting chamber production schedules.
- Single-source precision motion control:Mechanical stress applicators rely on German and Japanese linear motor suppliers, creating geographic concentration risk for fatigue tester manufacturers.
- EPA energy-efficiency standards:Laboratory equipment efficiency mandates increase chamber insulation and compressor system costs, compressing margins on mid-range test systems.
Strategic Opportunities
- India's semiconductor packaging incentives:PLI scheme subsidies for domestic ATMP facilities create greenfield procurement opportunities as Tata Group and Micron establish operations.
- Hybrid test platform convergence:Integration of thermal, vibration, and electrical stress into single workflows reduces floor space and capital expenditure for OSATs managing diverse package portfolios.
- Software-defined thermal profiling:Cloud-based protocol licensing transforms capital equipment into recurring revenue streams while enabling rapid test algorithm updates across installed bases.
Industry Challenges
- Electrothermal simulation correlation:Bridging finite element modeling predictions with physical hardware measurements requires specialized calibration engineers scarce in the talent pool.
- JEDEC standardization timelines:Evolving chiplet-specific reliability test methods create certification uncertainty, delaying equipment purchase decisions until pass-fail thresholds stabilize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market |
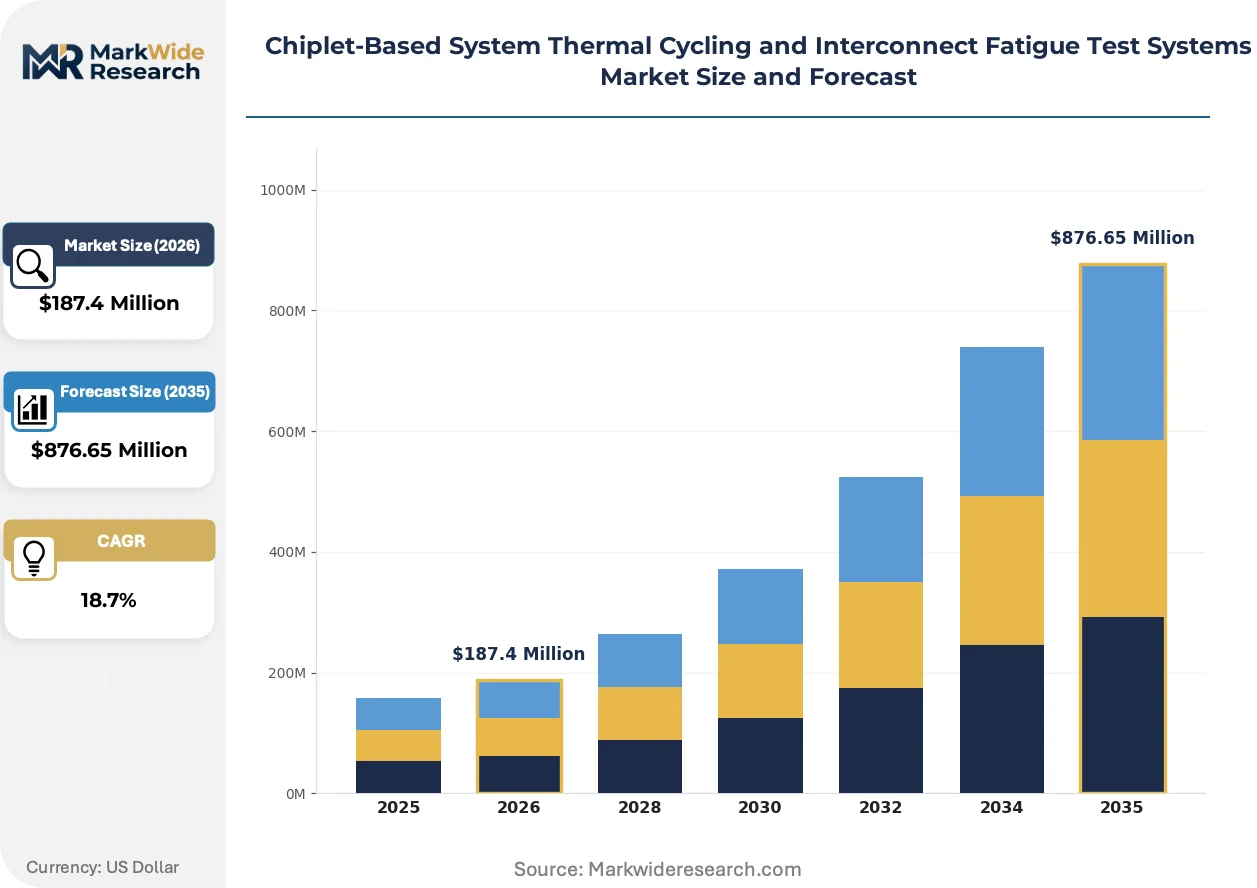
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Cyclers, Fatigue Testers, Hybrid Test Systems, Environmental Chambers Technology: Electrothermal, Laser-Based, Ultrasonic, Vibration Testing, Optical Inspection Application: Semiconductor Validation, Packaging Reliability, System Integration, Component Qualification End User: Chip Manufacturers, Assembly Houses, Quality Labs, Research Institutions |
| Companies Covered | Teradyne, Keysight Technologies, Advantest, Chroma ATE, Test Research, Inc., National Instruments, Amkor Technology, ASE Technology Holding, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market Trends and Innovations
Test system architectures are fragmenting between consolidated hybrid platforms and specialized single-function chambers, with procurement patterns diverging by end-use scale and package complexity. Equipment suppliers must now support both extremes without duplicating development overhead.
Hybrid environmental chambers combining thermal cycling, mechanical vibration, and in-situ electrical monitoring are modularizing validation workflows for advanced packaging houses. OSATs in Taiwan and South Korea are adopting these consolidated systems to compress qualification schedules for chiplet-based products. The technology is modularizing what were previously three separate capital purchases into unified footprints, reducing cleanroom space requirements and technician training burdens.
REACH substance restrictions on lead and cadmium are forcing redesign of solder joint fatigue simulation materials and contact probes used in continuity monitoring. European test labs must now verify that fixture materials comply with SVHC thresholds, adding documentation overhead to equipment shipments. Semiconductor validation facilities in Germany and the Netherlands are responding by specifying RoHS-compliant chamber interiors and probe card materials in procurement tenders.
Subscription-based thermal profile licensing is displacing perpetual software ownership in North American and European accounts. IDMs and OSATs prefer operational expenditure models that spread test protocol costs across multiple product generations, particularly for emerging chiplet standards still under JEDEC development. This pattern is most visible among fabless design houses outsourcing packaging validation to third-party labs, where flexibility outweighs long-term asset ownership.
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market Segmentation
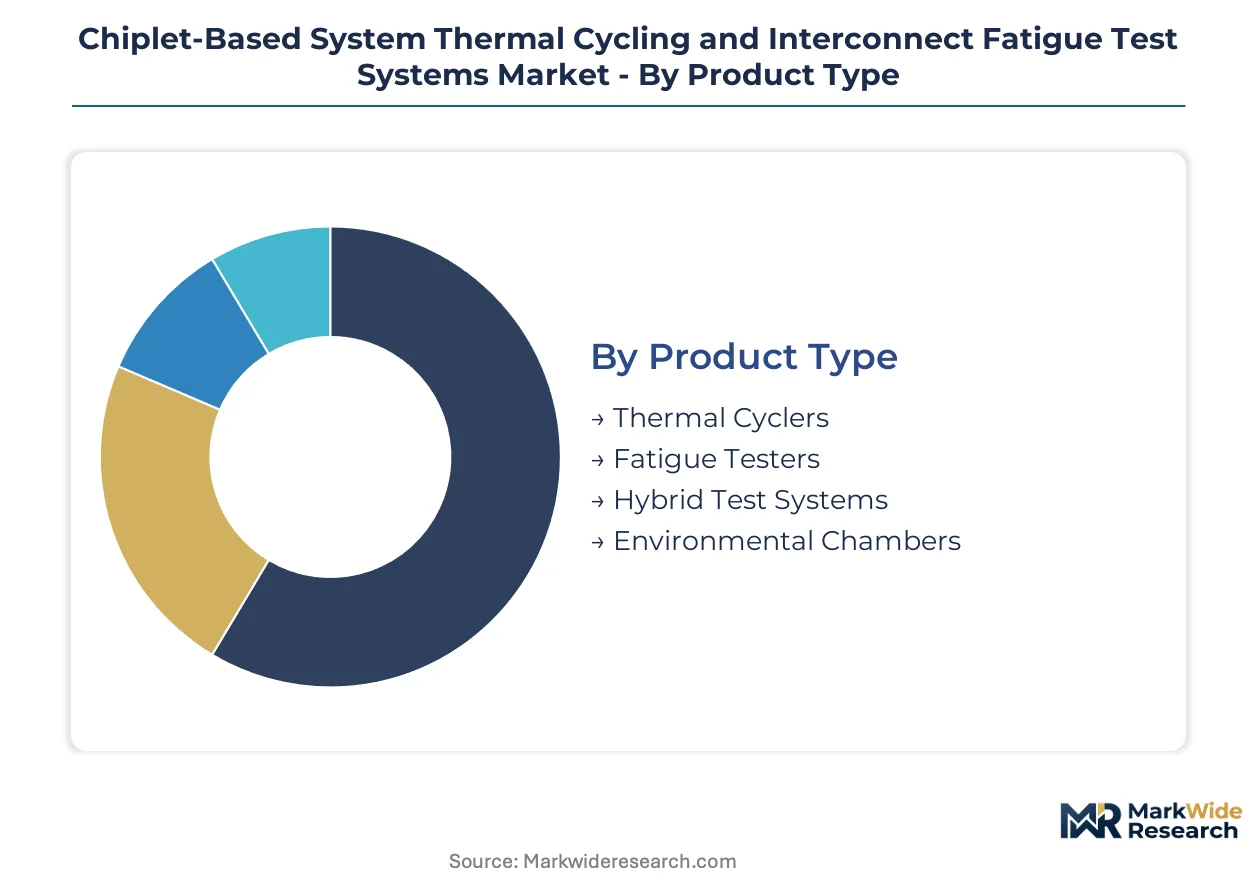
Equipment segmentation in this market tracks how capital deployment splits between specialized single-function tools and consolidated multi-stress platforms. Procurement patterns diverge sharply by end-use scale, with foundries favoring throughput-optimized configurations while research institutions prioritize flexibility.
Product Type:
Capital intensity varies dramatically across product categories, with hybrid platforms demanding the highest upfront investment due to mechanical integration complexity.
- Thermal Cyclers:Precision environmental chambers that execute programmed temperature ramps between minus sixty-five and one hundred fifty degrees Celsius. Foundries in Taiwan's Hsinchu Science Park deploy these in parallel arrays to compress chiplet qualification timelines. Chamber reliability determines throughput economics.
- Hybrid Test Systems:Consolidated platforms integrating thermal cycling, mechanical vibration, and electrical continuity monitoring into unified footprints. OSATs in South Korea's Yongin cluster adopt these to reduce cleanroom space requirements and technician training burdens for diverse package portfolios.
- Fatigue Testers:Mechanical stress applicators simulating decade-long interconnect lifetimes through accelerated thermal-mechanical cycling. German and Japanese linear motor suppliers create geographic concentration risk for chamber manufacturers.
- Environmental Chambers:Standalone temperature-humidity enclosures supporting basic preconditioning and storage tests. Research institutions specify these for protocol development before committing to production-scale equipment.
Most installed capacity flows through thermal cyclers. Expansion is steepest in hybrid test systems.
Technology:
Technology selection correlates with the precision requirements of emerging interconnect architectures, particularly copper-pillar microbumps in 2.5D/3D packages.
- Electrothermal:Combines resistive heating with thermoelectric cooling to achieve sub-minute ramp rates demanded by high-volume foundry operations. Taiwan's Industrial Development Bureau channels subsidies toward local procurement of electrothermal systems.
- Laser-Based:Delivers localized heating for rapid thermal gradient generation across heterogeneous die assemblies. Advanced packaging houses at Intel and TSMC pilot these for chiplet-specific stress profiling.
- Ultrasonic:Applies high-frequency mechanical excitation to accelerate solder joint degradation detection. Quality labs employ these for non-destructive screening before committing samples to destructive cycling.
- Vibration Testing:Mechanical stress modules simulating transportation and operational shock conditions. Assembly houses integrate these into hybrid platforms for consolidated qualification workflows.
- Optical Inspection:In-situ imaging systems tracking microcrack propagation and bump deformation during thermal cycling. Research institutions require these for JEDEC standard development and correlation studies.
Electrothermal systems anchor current installed bases. Laser-based methods are gaining share fastest in advanced packaging validation.
Application:
Application segmentation reflects where chiplet disaggregation multiplies interface counts requiring qualification.
- Semiconductor Validation:Pre-production reliability verification for multi-die assemblies incorporating heterogeneous process nodes. Chip manufacturers in Taiwan and South Korea concentrate procurement here due to foundry roadmap commitments.
- Packaging Reliability:Post-assembly stress testing for completed packages before customer shipment. OSATs drive volume demand as chiplet adoption expands inter-die interface counts.
- System Integration:Board-level and module-level thermal validation for complete computing systems. Server manufacturers specify these for AI accelerator qualification.
- Component Qualification:Discrete stress testing of individual dies, interposers, and substrates before assembly. Research institutions and IDM packaging groups employ these for materials characterization.
Semiconductor validation commands the largest equipment footprint. Packaging reliability applications are expanding most quickly.
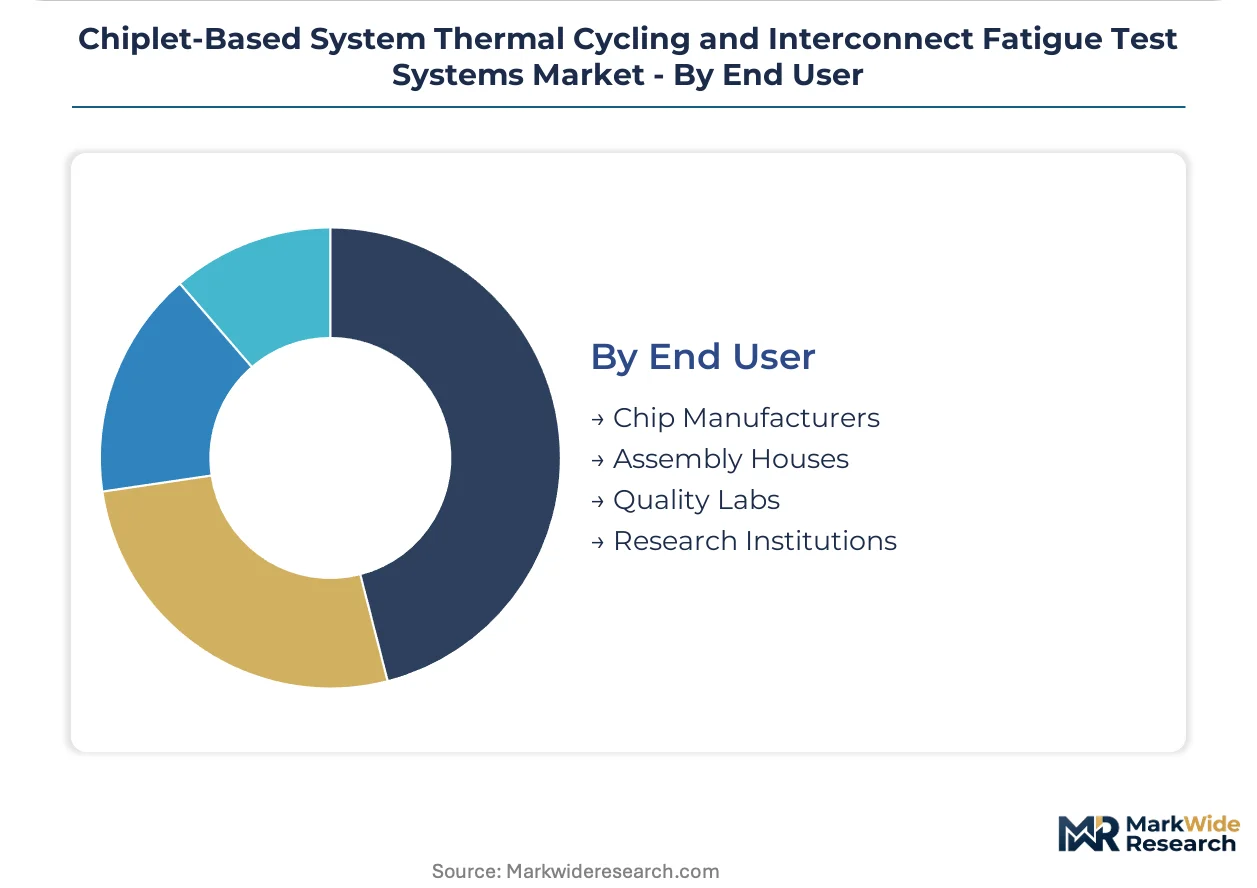
End User:
End user structure reveals how test capacity distributes between captive foundry operations and outsourced validation services.
- Chip Manufacturers:IDMs and foundries operating in-house advanced packaging facilities. Intel and TSMC procurement specifications cascade through equipment supplier development priorities.
- Assembly Houses:OSATs providing packaging services to fabless design houses. Taiwan's Hsinchu Science Park and South Korea's Yongin cluster concentrate this demand.
- Quality Labs:Third-party validation services offering outsourced reliability testing. Subscription-based thermal profile licensing is displacing perpetual software ownership among these users.
- Research Institutions:Universities and national laboratories developing next-generation test protocols. India's PLI scheme beneficiaries including Tata Group and Micron establish greenfield procurement from this segment.
Chip manufacturers hold the deepest installed base. Quality labs are adding capacity fastest as fabless outsourcing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Test equipment procurement concentrates more densely in Taiwan's Hsinchu Science Park than in comparable US clusters, while South Korea's Yongin corridor generates parallel demand for extreme-ramp thermal cycling systems.
United States
Intel's advanced packaging roadmaps in Oregon and Arizona drive captive thermal cycling capacity expansion. EPA energy-efficiency standards for laboratory equipment shape chamber insulation specifications. Greater Phoenix anchors Intel's heterogeneous integration validation facilities.
Taiwan
TSMC's chiplet production commitments multiply interconnect qualification requirements across its supplier base. The Industrial Development Bureau channels domestic subsidy programs toward local test equipment procurement. Hsinchu Science Park concentrates foundry and OSAT demand for sub-minute ramp thermal cyclers.
South Korea
Samsung Foundry's 3D packaging investments intensify fatigue testing requirements for copper-pillar microbump architectures. The Ministry of Trade, Industry and Energy steers support toward domestic equipment vendors. Yongin's semiconductor cluster generates clustered demand for hybrid test platforms.
China
Domestic advanced packaging initiatives at SMIC and Hua Hong Semiconductor expand validation infrastructure requirements. GB standard harmonization efforts create certification pathway uncertainty for imported equipment. Yangtze River Delta packaging houses pilot localized thermal cycling protocols.
Japan
Materials suppliers and equipment component manufacturers anchor precision motion control supply chains for fatigue tester builders. METI technology roadmaps emphasize next-generation interconnect reliability. Kyushu's semiconductor materials cluster feeds specialized chamber component production.
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated test platform vendors commanding premium positioning against modular component suppliers. The vendor base organizes into three tiers: diversified instrumentation conglomerates, specialized semiconductor test equipment builders, and captive foundry engineering groups. Competitive dynamics center on M&A activity consolidating thermal chamber capabilities and strategic partnerships bridging electrothermal simulation with hardware validation workflows.
Within the diversified instrumentation tier, Teradyne and Keysight Technologies occupy positions anchored by broad measurement portfolios, while Advantest exemplifies the specialized semiconductor test archetype with focused environmental chamber expertise. These three companies represent distinct strategic postures: Teradyne leverages high-throughput automation heritage, Keysight sustains R&D intensity in simulation-to-hardware correlation, and Advantest competes through extreme temperature ramp rate specialization demanded by chiplet architectures.
| Leading Market Players |
|---|
| Teradyne |
| Keysight Technologies |
| Advantest |
| Chroma ATE |
| Test Research, Inc. |
| National Instruments |
| Amkor Technology |
| ASE Technology Holding |
| Intel |
| Others |
Pricing and Supply Chain Analysis
Captive integration into precision motion control components anchors both supply security and pricing power for thermal cycling equipment manufacturers, with German and Japanese linear motor suppliers commanding premium positions that cascade through chamber production economics.
Pricing Analysis
Capacity additions in Taiwan's Hsinchu Science Park are reshaping price floors for electrothermal systems as local subsidy programs intensify procurement competition. Three-tier pricing structure across premium, standard, and economy levels stratifies by ramp rate capability and channel count, with EPA energy-efficiency standards compressing margins on mid-range systems. Cost compression in economy-tier chambers is intensifying because helium supply volatility forces refrigerant system redesigns. Fabless design houses outsourcing to quality labs exhibit highest price sensitivity; foundries with captive validation facilities show lowest.
Supply Chain Analysis
Regional distribution centers in Taiwan, South Korea, and Germany anchor hub-and-spoke patterns for chamber component logistics. Precision linear motors draw from Japanese and German suppliers, while thermoelectric cooling modules rest on Chinese and South Korean manufacturing. Single-source vulnerability in high-precision motion control creates geographic concentration risk for fatigue tester builders. Distribution runs through foundry-direct channels for high-volume procurement and specialized distributors for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on software-defined thermal profiling transforming capital equipment into recurring revenue streams, with subscription-based protocol licensing capturing value from JEDEC standard evolution cycles.
For Market Incumbents: Lock in electrothermal simulation-to-hardware correlation capabilities through targeted R&D investments, as emerging laser-based thermal methods threaten established ramp-rate advantages. Deepen backward integration into chamber control electronics to offset single-source precision motion dependencies. Certification investment in EU F-Gas Regulation compliance creates switching costs against modular competitors. For New Entrants and Emerging Players: Quality lab channel partners offer the most penetrable entry vector, as fabless outsourcing expands and subscription pricing models reduce upfront capital barriers. India's PLI scheme beneficiaries including Tata Group and Micron operations present greenfield procurement opportunities with limited incumbent entrenchment. Lead with hybrid platform convergence messaging that reduces cleanroom footprint and technician training burdens. For Investors and Strategic Acquirers: Roll-up economics work for specialized environmental chamber builders because JEDEC standardization timelines create acquisition windows before pass-fail thresholds stabilize. Target electrothermal calibration expertise and software protocol libraries as durable intangible assets. Watch for helium supply contract restructuring as inflection indicator for equipment refresh cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Test Platform Integration | Consolidates thermal, vibration, and electrical stress into single workflows for OSATs. |
| Software-Defined Thermal Profiling | Transforms capital equipment into recurring revenue through cloud-based protocol licensing. |
| Backward Integration into Motion Control | Reduces geographic concentration risk from German and Japanese linear motor suppliers. |
| EU F-Gas Regulation Compliance Investment | Creates equipment refresh cycles at European semiconductor labs requiring refrigerant replacement. |
| Laser-Based Thermal Method Development | Enables localized heating for rapid thermal gradient generation across heterogeneous die assemblies. |
Research Methodology
Multiple input streams — primary interviews with test equipment procurement managers, secondary validation through JEDEC standard documentation, and customs data on chamber component trade flows — were reconciled to build segment-level demand estimates. Foundry packaging engineers, OSAT reliability directors, thermal chamber service technicians, and semiconductor validation lab managers provided operational perspective. SEC filings, EPA energy-efficiency compliance databases, and Taiwan Industrial Development Bureau subsidy disclosures furnished secondary anchors. Bottom-up equipment shipment tracking and top-down foundry capex allocation models were cross-referenced.
Data-stream reconciliation across product type, technology, application, and end-user dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base growth rates and replacement cycle compression. Copper-pillar microbump adoption curves and EUV lithography ramp schedules served as semiconductor-specific demand drivers. Electrothermal versus laser-based technology mix shifts were modeled against foundry roadmap commitments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to JEDEC standardization timeline slippage and helium supply contract restructuring. Outputs reflect documented assumptions about heterogeneous integration roadmaps at Intel, TSMC, and Samsung Foundry. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Production Testing Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
IoT Testing Equipment Market
Test and Measurement
Miniature Atomic Clock Market
Test and Measurement
Surface Vision and Inspection Equipment Market
Test and Measurement
Durometer Calibration Service Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Reverberation Chambers Market
Test and Measurement
Burst Strength Tester Market
Test and Measurement
Radiography Test Equipment Market
Test and Measurement
Radiation Tester Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
Voltage Tester Market