
 Permeation Testing Machines Market | 2026-2036
Permeation Testing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Permeation Testing Machines Market Insights
Modular instrument configurations is expanding buyer flexibility as laboratories seek scalable testing platforms that accommodate both single-gas and multi-chamber protocols without full system replacement. Labthink Instruments Co., Ltd. leverages its vertical integration in sensor manufacturing to control component costs and calibration consistency. MOCON sustains technology leadership in coulometric oxygen detection, a specification pharmaceutical clients specify in procurement tenders. Brugger Feinmechanik anchors European demand through precision engineering traditions tied to German automotive and packaging film sectors.
Permeation testing machines measure the rate at which gases, vapors, or liquids penetrate barrier materials under controlled temperature, pressure, and humidity conditions, typically reporting results in cm³/m²·day or g/m²·day depending on the analyte and standard method employed. These instruments serve critical quality control and R&D functions across industries where barrier integrity directly affects product shelf life, safety, or regulatory compliance. Gas permeation testers dominate current installed bases due to established ASTM and ISO methods for oxygen and carbon dioxide transmission, while sensor-based technology platforms are capturing fastest-growing interest as manufacturers seek real-time data logging and reduced operator intervention. Multi-chamber permeation testers concentrate margin pools by enabling parallel sample processing that reduces per-test labor costs for high-throughput quality control departments.
FDA 21 CFR Part 11 electronic records requirements shape software architecture and data integrity features in instruments sold to pharmaceutical quality control departments, while REACH chemical registration obligations in Europe compel material manufacturers to document barrier performance against substance migration thresholds. ISO 15105 and ASTM D3985 provide the methodological backbone for cross-border test result comparability, reducing friction in international supply chain qualification. Stakeholders must monitor convergence between sensor miniaturization trends and evolving pharmacopeial permeability standards to anticipate which technology platforms will dominate next-generation instrument procurement cycles.
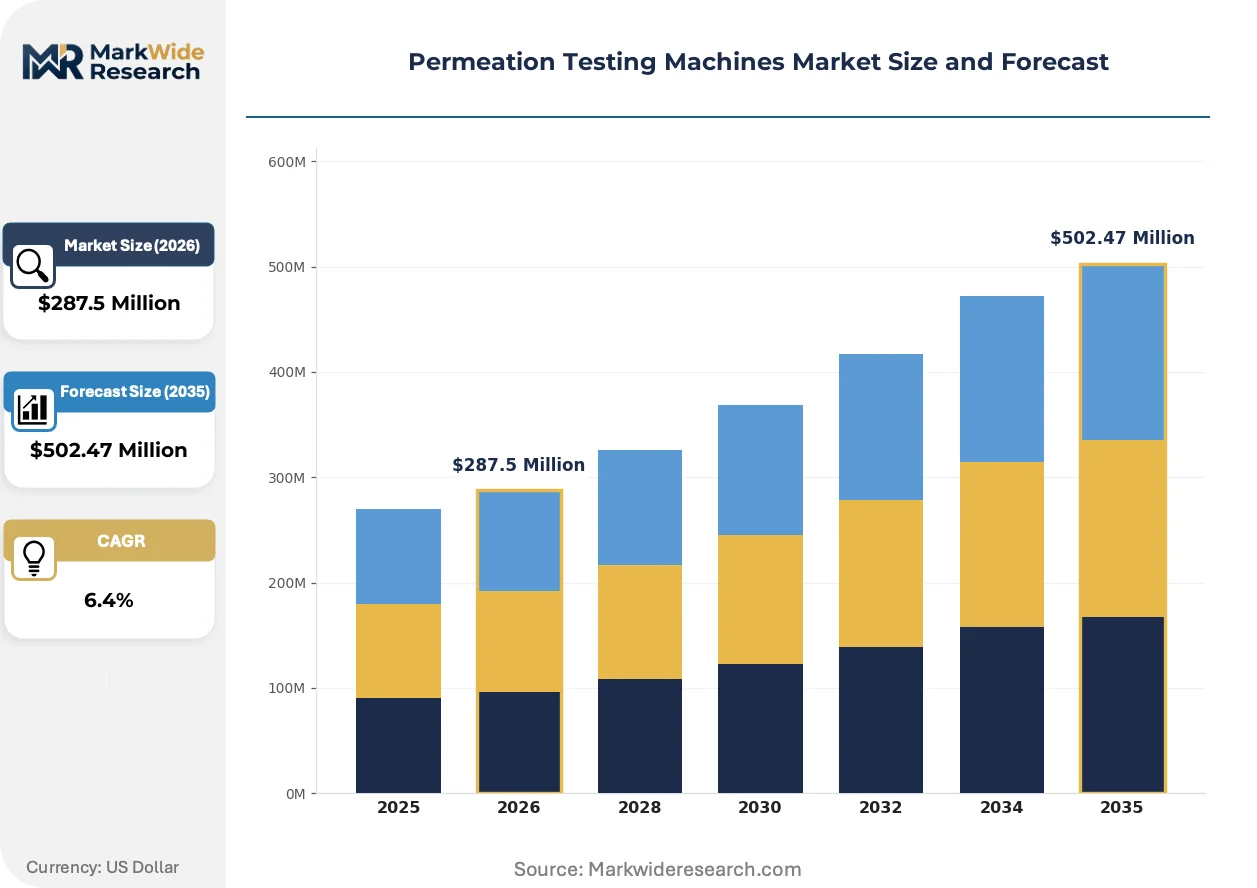
Market Dynamics
Pharmaceutical packaging validation requirements are compressing testing cycles and forcing instrument manufacturers to integrate real-time data logging with audit-ready documentation architectures.
Growth Catalysts
- REACH compliance documentation:European chemical manufacturers must now submit barrier performance data against substance migration thresholds, creating mandatory replacement demand for calibrated permeation systems.
- Blister packaging oxygen sensitivity:Biologic drug formulations require sub-ppm oxygen transmission validation, driving precision instrument upgrades across contract packaging organizations.
- German automotive cluster concentration:Fuel cell membrane development programs in Stuttgart and Munich are absorbing multi-chamber hydrogen permeation testers for stack component qualification.
Market Restraints
- Platinum electrode supply concentration:Coulometric oxygen sensors depend on South African and Russian platinum group metal refining, exposing instrument makers to input cost volatility and sanctions-related disruption.
- Sensor calibration drift:Electrochemical detection cells require 90-day recertification cycles that interrupt high-throughput laboratory operations and inflate total cost of ownership.
- ASTM-ISO method divergence:Subtle differences between D3985 and 15105 test protocols force manufacturers to maintain dual qualification datasets, adding documentation overhead for multinational material suppliers.
Strategic Opportunities
- India pharmaceutical export expansion:CDSCO's alignment with ICH Q1A stability guidelines is compelling domestic generic manufacturers to install barrier testing capacity for EU and US market access.
- Flexible electronics substrate testing:OLED encapsulation film developers require water vapor transmission rates below 10⁻⁶ g/m²·day, opening premium instrument tiers for atomic layer deposition validation.
- EU Packaging Waste Directive Extended Producer Responsibility:Recycled content mandates are forcing brand owners to verify post-consumer film barrier integrity, creating new service revenue streams for testing laboratories.
Industry Challenges
- Metrology technician scarcity:Coupled temperature-humidity-permeability calibration requires specialized expertise that vocational programs in material science have failed to replenish.
- Legacy LIMS integration friction:FDA 21 CFR Part 11-compliant instruments must interface with decade-old laboratory information management systems through expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Permeation Testing Machines Market |
| Market Size in 2026 | $287.5 Million |
| Market Size in 2035 | $502.47 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Permeation Tester, Liquid Permeation Tester, Vapor Permeation Tester, Multi-Chamber Permeation Tester Technology: Chromatography, Gravimetric, Volumetric, Sensor-Based, Spectroscopic Application: Packaging Films, Protective Clothing, Medical Devices, Food & Beverages End User: Research Laboratories, Quality Control Departments, Material Manufacturers, Academic Institutes |
| Companies Covered | Labthink Instruments Co., Ltd., MOCON, Brugger Feinmechanik, Systech Illinois, Qualitest, AMETEK MOCON, Toray Industries, Thwing-Albert Instrument Company, Porous Materials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Permeation Testing Machines Market Trends and Innovations
Sensor miniaturization and cloud-native data architectures are compressing the gap between laboratory-grade precision and at-line quality control deployment.
Quartz crystal microbalance sensors are overtaking traditional gravimetric methods for ultra-low water vapor transmission measurement below 0.005 g/m²·day. Pharmaceutical film developers in Switzerland and Massachusetts are adopting these platforms for accelerated stability screening. The technology is overtaking incumbent infrared detection in applications where sample throughput and operator intervention reduction outweigh absolute accuracy requirements.
EU F-Gas Regulation phase-down schedules are compelling instrument manufacturers to eliminate sulfur hexafluoride tracer gases from permeation testing protocols. This regulatory pressure is redirecting R&D investment toward helium and hydrogen carrier gas alternatives with comparable detection sensitivity. German automotive fuel cell membrane suppliers are experiencing the most acute compliance timeline pressure, with qualification deadlines fixed through 2027.
Contract testing laboratories are unbundling instrument ownership from analytical service delivery, offering permeability data subscriptions that eliminate capital expenditure barriers for mid-tier packaging converters. This model is displacing traditional equipment sales in Southern Europe and Southeast Asia where credit access constrains upfront procurement. Italian flexible packaging cooperatives represent the most concentrated adoption geography, with shared-service hubs now serving multiple SME film extruders.
Permeation Testing Machines Market Segmentation
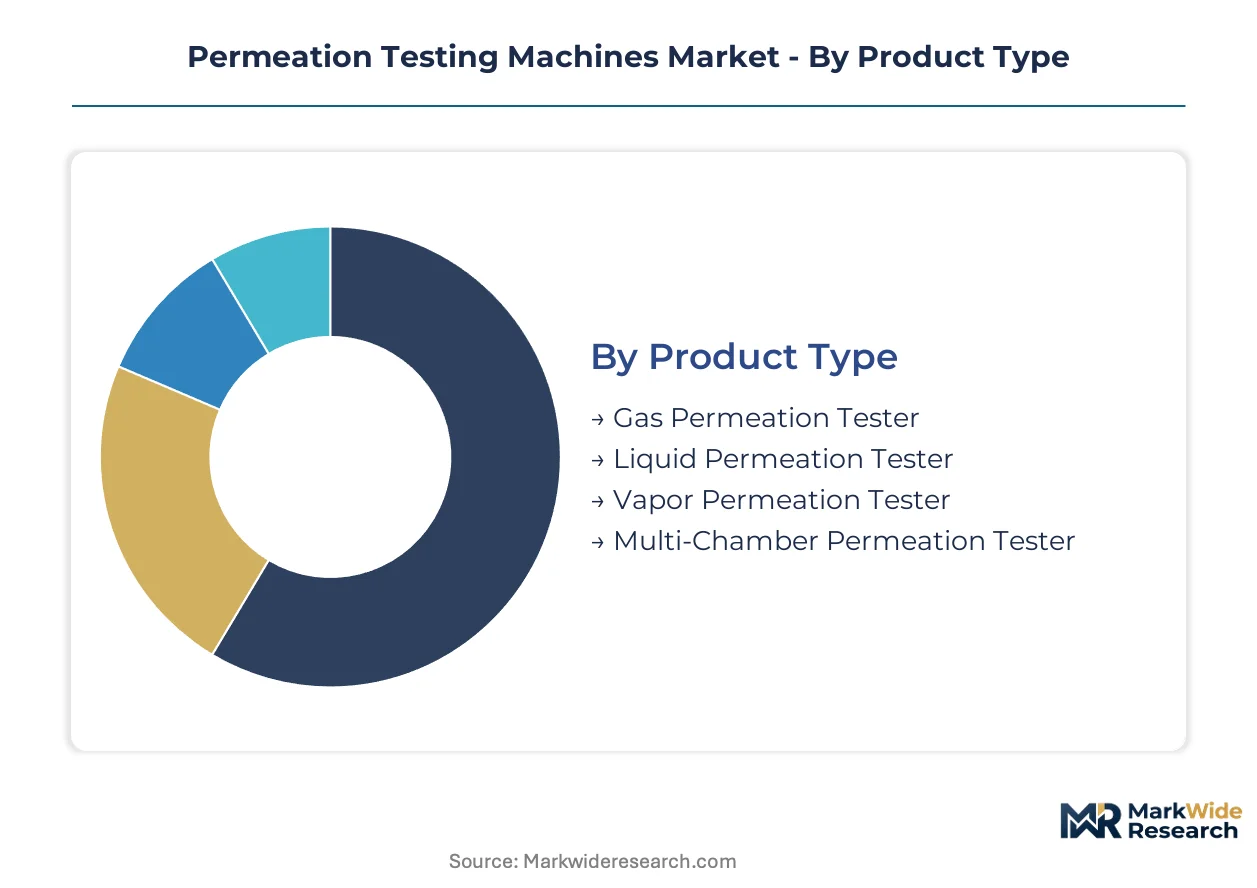
Permeation testing machines serve divergent certification regimes across pharmaceutical, automotive, and food safety sectors. Segmentation reveals where regulatory documentation burdens concentrate procurement budgets and calibration protocols.
Product Type:
Certification requirements vary sharply by product type, with pharmaceutical applications demanding FDA 21 CFR Part 11 compliance while automotive fuel cell testing follows ISO 15105 protocols.
- Gas Permeation Tester:Coulometric oxygen detection cells measure transmission rates through barrier films under controlled temperature and humidity. Pharmaceutical quality control departments in Germany and Switzerland specify these instruments for blister packaging validation against sub-ppm oxygen thresholds.
- Multi-Chamber Permeation Tester:Parallel sample processing architectures reduce per-test labor costs through simultaneous measurement across 6-12 specimen positions. Contract testing laboratories in Italy and Spain are adopting these platforms to serve SME packaging converters through subscription-based service models.
- Liquid Permeation Tester:Hydrostatic pressure-driven systems evaluate solvent and chemical migration through elastomeric seals and gaskets.
- Vapor Permeation Tester:Gravimetric or sensor-based detection quantifies water vapor transmission for humidity-sensitive electronics encapsulation.
Gas permeation testers sit at the top of the volume ranking, with multi-chamber configurations climbing the fastest.
Technology:
Technology selection tracks cost tier and precision requirements, with gravimetric methods dominating budget-constrained settings while sensor platforms command premium positioning.
- Sensor-Based:Real-time data logging with electrochemical or infrared detection eliminates operator intervention and compresses test cycles. Quartz crystal microbalance variants are capturing share in ultra-low water vapor applications below 0.005 g/m²·day for OLED encapsulation film developers in Massachusetts and Switzerland.
- Gravimetric:Weight-loss measurement through calcium chloride or desiccant cups remains the reference method for ASTM E96 compliance. Material manufacturers in India prefer these systems for CDSCO-aligned barrier documentation under constrained capital budgets.
- Chromatography:Gas chromatography separation with thermal conductivity detection enables multi-analyte permeability profiling.
- Volumetric:Pressure differential measurement suits high-permeability materials where rapid gas transmission exceeds gravimetric sensitivity.
- Spectroscopic:Infrared absorption spectroscopy provides non-destructive water vapor quantification for sensitive pharmaceutical films.
Sensor-based platforms are expanding most quickly, while gravimetric methods retain the largest installed base.
Application:
Application segmentation follows end-use regulatory intensity, with medical and pharmaceutical sectors absorbing the highest per-unit instrument investment.
- Packaging Films:Oxygen and moisture barrier validation for flexible food packaging, pharmaceutical blisters, and retort pouches. EU Packaging Waste Directive Extended Producer Responsibility rules are forcing brand owners to verify post-consumer recycled film integrity.
- Medical Devices:Catheter, implant, and drug delivery system materials require biocompatibility-aligned permeability documentation. FDA submission protocols mandate ASTM F1249 or ISO 15105-2 traceability for polymer barrier claims.
- Protective Clothing:Chemical warfare agent and industrial solvent penetration resistance testing for military and hazmat applications.
- Food & Beverages:Modified atmosphere packaging validation for shelf-life extension in meat, dairy, and snack categories.
Packaging films command the greatest shipment volumes, with medical devices showing the steepest expansion trajectory.
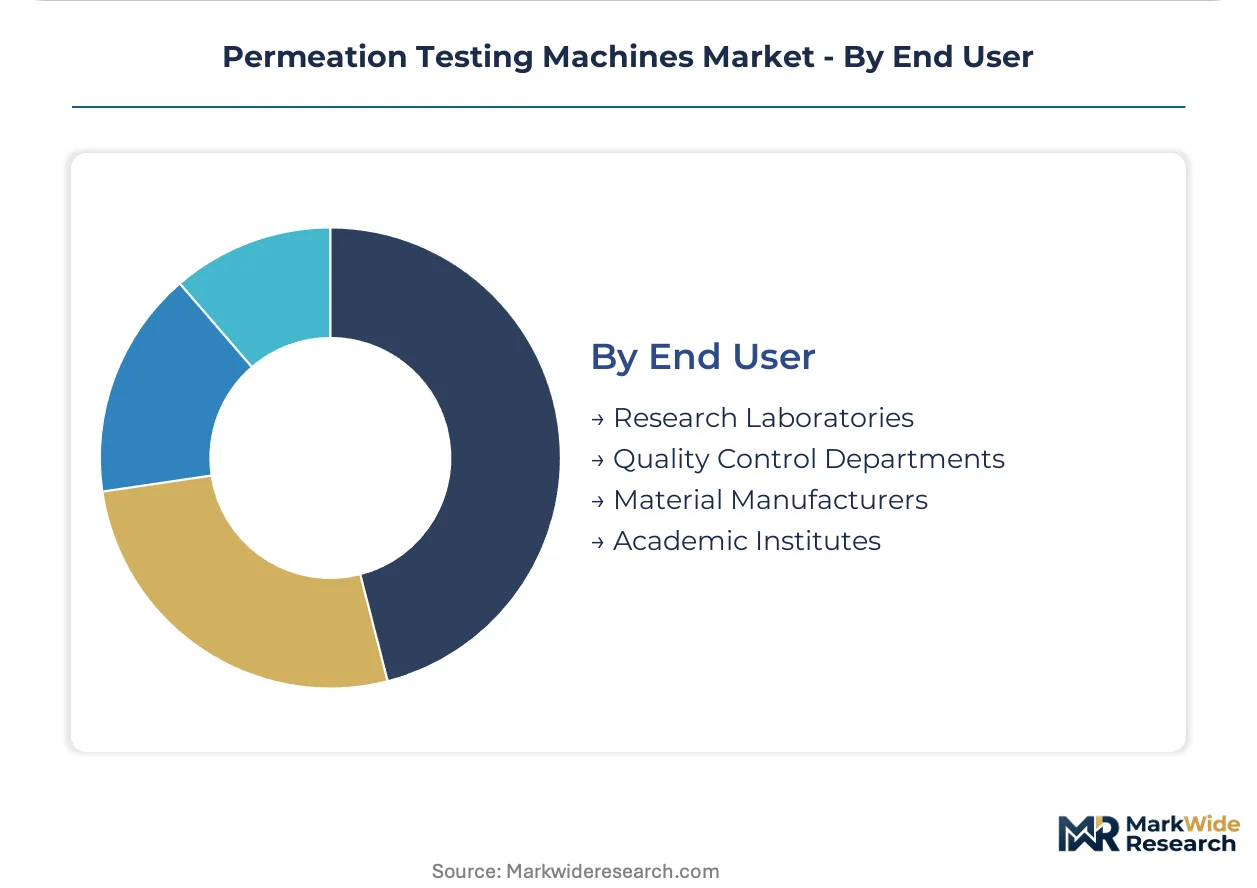
End User:
End user segmentation reflects organizational scale and analytical sophistication, determining whether procurement favors capital purchase or outsourced service models.
- Quality Control Departments:High-throughput testing protocols with LIMS integration and audit-ready documentation architectures. These units specify multi-chamber configurations to amortize capital across thousands of annual tests.
- Research Laboratories:Method development and material screening functions requiring modular platforms with interchangeable sensor modules. Academic and corporate R&D centers in Stuttgart and Munich fuel cell clusters prioritize hydrogen permeation specificity.
- Material Manufacturers:In-house barrier validation for film extruders, coating operations, and laminate suppliers.
- Academic Institutes:Teaching and fundamental diffusion research with lower throughput requirements.
Quality control departments generate the highest absolute demand, with research laboratories gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering traditions established the foundational standards for permeation instrumentation during the post-war industrial reconstruction period. These technical norms subsequently diffused into pharmaceutical quality control protocols across Western Europe and North America.
United States
FDA 21 CFR Part 11 compliance mandates reshape procurement specifications for pharmaceutical quality control departments. The agency's electronic records requirements force instrument manufacturers to embed audit-ready documentation architectures. Massachusetts-based OLED developers drive demand for ultra-low water vapor transmission measurement platforms.
Germany
REACH chemical registration obligations compel material manufacturers to document barrier performance against substance migration thresholds. Stuttgart and Munich fuel cell membrane development programs absorb multi-chamber hydrogen permeation testers for stack component qualification. The country's automotive cluster concentration sustains precision instrument procurement through material science laboratories.
Switzerland
Swissmedic pharmaceutical packaging standards enforce sub-ppm oxygen transmission validation for biologic drug formulations. The regulator's stability guidelines align with ICH Q1A frameworks. Basel-area pharmaceutical film developers adopt quartz crystal microbalance sensors for accelerated stability screening.
India
CDSCO alignment with ICH Q1A stability guidelines compels domestic generic manufacturers to install barrier testing capacity. The national pharmaceutical regulator's harmonization with international standards drives EU and US market access investments. Mumbai and Ahmedabad contract packaging organizations upgrade oxygen sensitivity validation equipment.
Japan
METI industrial standards and PMDA pharmaceutical quality requirements converge on ASTM-ISO method comparability. The ministry's technical specifications influence regional procurement patterns for sensor-based detection platforms. Osaka polymer research institutes prioritize real-time data logging capabilities for reduced operator intervention.
Permeation Testing Machines Market Competitive Landscape
Premium-margin players sit above commodity-margin players across calibration consistency and sensor manufacturing depth. The vendor base stratifies between vertically integrated instrument manufacturers and modular system assemblers sourcing detection cells externally. Three archetypes dominate: precision engineering specialists with captive sensor production, chromatography platform extenders leveraging existing installed bases, and contract testing service providers unbundling instrument ownership from analytical delivery. Competitive moves concentrate on backward integration into platinum electrode supply chains and cloud-native data architecture licensing.
Within the precision engineering tier, Brugger Feinmechanik exemplifies German manufacturing traditions tied to automotive and packaging film sectors. MOCON occupies a position representing coulometric oxygen detection specifications that pharmaceutical clients embed in procurement tenders. Labthink Instruments Co., Ltd. anchors the vertically integrated archetype through in-house sensor manufacturing that controls component costs and calibration consistency.
| Leading Market Players |
|---|
| Labthink Instruments Co., Ltd. |
| MOCON |
| Brugger Feinmechanik |
| Systech Illinois |
| Qualitest |
| AMETEK MOCON |
| Toray Industries |
| Thwing-Albert Instrument Company |
| Porous Materials Inc. |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical quality control departments in Germany and Switzerland anchor premium pricing tiers through FDA 21 CFR Part 11 and Swissmedic compliance mandates that bundle software validation with hardware procurement. Subscription-based service models in Southern Europe compress capital barriers while shifting margin capture toward contract testing laboratories operating multi-chamber platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from automotive-grade ISO 15105 platforms and gravimetric methods for emerging market material manufacturers. Price differentiation rests on certification grade and sensor manufacturing depth, with coulometric oxygen detection commanding substantial premiums over infrared alternatives. Cost compression in the economy tier intensifies because Indian and Southeast Asian packaging converters prioritize capital efficiency over real-time data logging. Academic institutes and SME film extruders exhibit highest price sensitivity, while Basel-area biologic developers accept premium positioning for sub-ppm validation thresholds.
Supply Chain Analysis
EU F-Gas Regulation phase-down schedules are reshaping sourcing patterns by eliminating sulfur hexafluoride tracer gases and redirecting procurement toward helium and hydrogen carrier gas alternatives. Component manufacturing concentrates in Germany, Japan, and China, with platinum electrode supply drawing from South African and Russian refining operations. Raw material dependencies include platinum group metals for coulometric sensors, quartz crystal substrates for microbalance platforms, and precision-machined aluminum chambers. Single-source vulnerability in platinum supply exposes instrument makers to sanctions-related disruption and input cost volatility. Distribution runs through direct OEM sales for pharmaceutical clients and shared-service laboratory hubs for Southern European packaging cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indian pharmaceutical export expansion creates geographic-arbitrage opportunities as CDSCO alignment with ICH Q1A stability guidelines forces domestic generic manufacturers to install barrier testing capacity at cost structures below European equivalents.
For Market Incumbents: Lock in platinum electrode supply through long-term offtake agreements with South African refiners before sanctions tighten further. Deepen backward integration into sensor manufacturing to defend margin position against modular system assemblers sourcing detection cells externally from Chinese suppliers. Prioritize cloud-native data architecture licensing to capture recurring revenue streams as contract testing laboratories unbundle instrument ownership from analytical service delivery. For New Entrants and Emerging Players: Enter via OLED encapsulation film testing for Massachusetts and Switzerland developers requiring water vapor transmission rates below 10⁻⁶ g/m²·day, a premium tier where established players have limited penetration. Target India's contract packaging organizations upgrading oxygen sensitivity validation equipment for EU and US market access. Pursue sensor miniaturization partnerships with polymer research institutes in Osaka to differentiate on real-time data logging capabilities. For Investors and Strategic Acquirers: Precision engineering specialists with captive sensor production are the most active acquirer in this space, seeking to consolidate calibration consistency advantages against chromatography platform extenders. The five-to-ten-year viability window favors vertically integrated instrument manufacturers controlling component costs through in-house production. Acquisition target archetype: German automotive cluster-anchored precision engineering firms with fuel cell membrane testing specialization. Watch for EU Packaging Waste Directive enforcement intensity as the inflection signal indicating recycled content mandate compliance spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Labthink's captive production of detection cells controls calibration consistency and component costs against modular assemblers. |
| Cloud-Native Data Architecture Licensing | Subscription revenue models displace capital sales in Italian flexible packaging cooperatives through shared-service hub offerings. |
| Helium Carrier Gas Protocol Development | German automotive fuel cell suppliers face 2027 qualification deadlines under EU F-Gas Regulation phase-down mandates. |
| Multi-Chamber Platform Expansion | Parallel sample processing reduces per-test labor costs for high-throughput quality control departments in contract laboratories. |
| Quartz Crystal Microbalance Sensor Deployment | Swiss and Massachusetts pharmaceutical film developers adopt these platforms for accelerated stability screening below 0.005 g/m²·day. |
Research Methodology
Direct dialogue with instrument manufacturer R&D directors, pharmaceutical quality control managers, contract testing laboratory operators, and material science procurement leads grounded the qualitative foundation. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, ECHA REACH registration databases, ISO 15105 and ASTM D3985 standard publications, and German automotive cluster economic development reports. Bottom-up triangulation across equipment shipment data and top-down reconciliation against end-use industry capital expenditure surveys ensured cross-verification.
Segmented outputs across product type, technology platform, application vertical, and end-user organizational scale informed the analytical framework across the projection horizon. Modeled dimensions included gas versus vapor versus liquid permeation tester categories, sensor-based versus gravimetric versus chromatographic detection methods, and quality control department versus research laboratory procurement patterns. CAGRs were derived from regression analysis of historical instrument replacement cycles and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated platinum group metal price volatility indices and EU F-Gas Regulation phase-down timeline assumptions.
The model holds under stable regulatory enforcement intensity and continued ICH Q1A harmonization across national pharmaceutical regulators; deviation in sanctions regimes affecting platinum supply or accelerated EU Packaging Waste Directive implementation would shift replacement demand timing and regional procurement concentration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Network Tester Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
Semiconductor Curve Tracer Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Paperless Recorders Market
Test and Measurement
Global Inspection Machines Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Pump Testers Market
Test and Measurement
Calibration Management Software Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
Megohmmeters Market
Test and Measurement
Smart Contact Lens Optical and Telemetry Test Equipment Market
Test and Measurement
Calorimeters Market
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
Data Acquisition Equipment Market