
 Piezoelectric Energy Harvesting System Market | 2026-2036
Piezoelectric Energy Harvesting System Market Size, Share, and Industry Trends Forecast 2026-2036
Piezoelectric Energy Harvesting System Market Intelligence
Multi-source component procurement is decoupling from traditional single-source piezoelectric ceramic supply chains as OEMs diversify supplier bases to mitigate lead-time volatility. STMicroelectronics leverages its MEMS fabrication expertise to sustain captive production of micro-scale harvesters for consumer wearables. Texas Instruments Incorporated anchors its position through integrated power management ICs that condition erratic piezoelectric outputs into stable voltages. EnOcean GmbH differentiates by specializing in building-automation modules that combine energy harvesting with proprietary wireless protocols.
A piezoelectric energy harvesting system converts mechanical strain from vibration, pressure, or footfall into electrical charge through crystalline materials such as lead zirconate titanate or aluminum nitride, typically generating milliwatts to microwatts for powering distributed sensors and low-energy electronics. Vibration energy harvesters dominate commercial revenue due to mature industrial retrofit applications, while MEMS technology captures the fastest expansion as semiconductor foundries scale wafer-level integration for miniaturized devices. Footfall generators occupy niche but high-margin deployments in smart building flooring, whereas nanostructured approaches remain largely pre-commercial despite superior strain sensitivity in laboratory settings.
The EU F-Gas Regulation and REACH framework restrict hazardous substances in battery-dependent electronics, redirecting OEMs toward battery-free architectures that piezoelectric systems enable. EMA and FDA scrutiny of wireless healthcare monitors is tightening electromagnetic compatibility standards, which harvester-integrated sensor designers must satisfy for market access. Stakeholders should monitor how IEC and ISO standards for energy-autonomous IoT devices evolve, as harmonized certification requirements will determine which technology platforms achieve cross-border commercial scale.
Market Dynamics
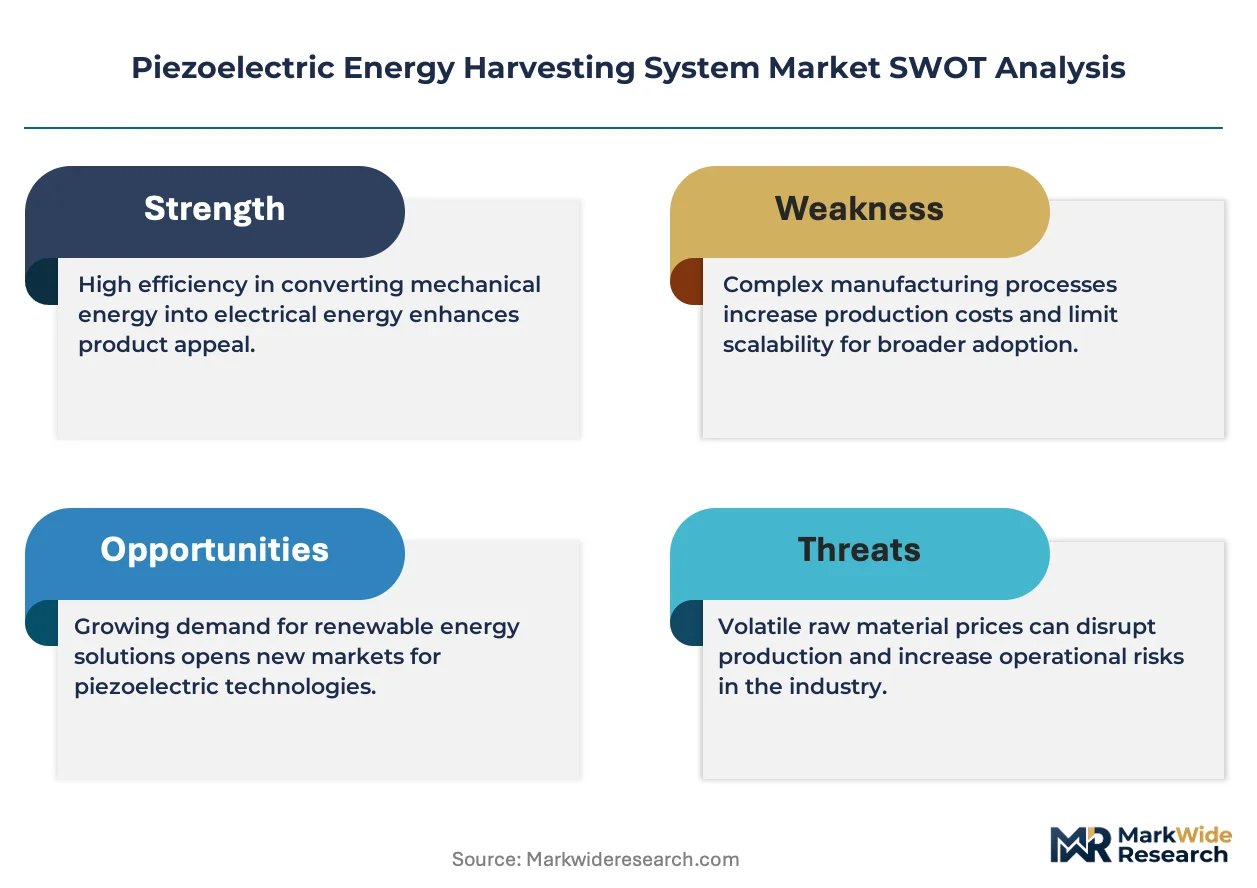
The EU F-Gas Regulation and REACH framework are forcing OEMs to abandon battery-dependent architectures, creating structural pull for vibration harvesters that eliminate hazardous waste streams from wireless sensor networks.
Growth Catalysts
- Industrial automation retrofit:Manufacturing facilities in Germany deploy vibration harvesters to power predictive maintenance sensors without wiring infrastructure.
- EU Green Deal mandates:Energy-autonomous building systems qualify for accelerated permitting under the EU Green Deal's circular economy criteria.
- MEMS fabrication scaling:Semiconductor foundries in Taiwan and South Korea achieve wafer-level integration that compresses harvester unit costs for consumer wearables.
Market Restraints
- Lead zirconate titanate supply concentration:Specialty piezoelectric ceramic production clusters in Japan and China expose OEMs to geopolitical supply disruptions.
- Power output ceiling:Crystalline materials generate milliwatt-range outputs that cannot sustain continuous-transmission wireless protocols.
- REACH substance restrictions:Lead-containing formulations face phase-out timelines that compress R&D runway for alternative chemistries.
Strategic Opportunities
- Smart building flooring:Footfall generators capture untapped revenue in airport terminals and convention centers where high pedestrian density meets maintenance-free power needs.
- Healthcare wireless monitors:FDA electromagnetic compatibility pathways for battery-free patient sensors open reimbursement channels previously blocked by battery replacement protocols.
- Aluminum nitride convergence:Integration with CMOS fabrication lines enables monolithic harvester-processor chips that displace discrete component assemblies.
Industry Challenges
- IEC certification timelines:Absence of harmonized standards for energy-autonomous IoT devices forces redundant national testing that extends product launch cycles.
- MEMS design talent scarcity:Interdisciplinary expertise spanning mechanical engineering and semiconductor physics concentrates at a handful of research institutes.
- Legacy system integration:Vibration harvesters must interface with industrial equipment bearing decades-old analog sensor architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piezoelectric Energy Harvesting System Market |
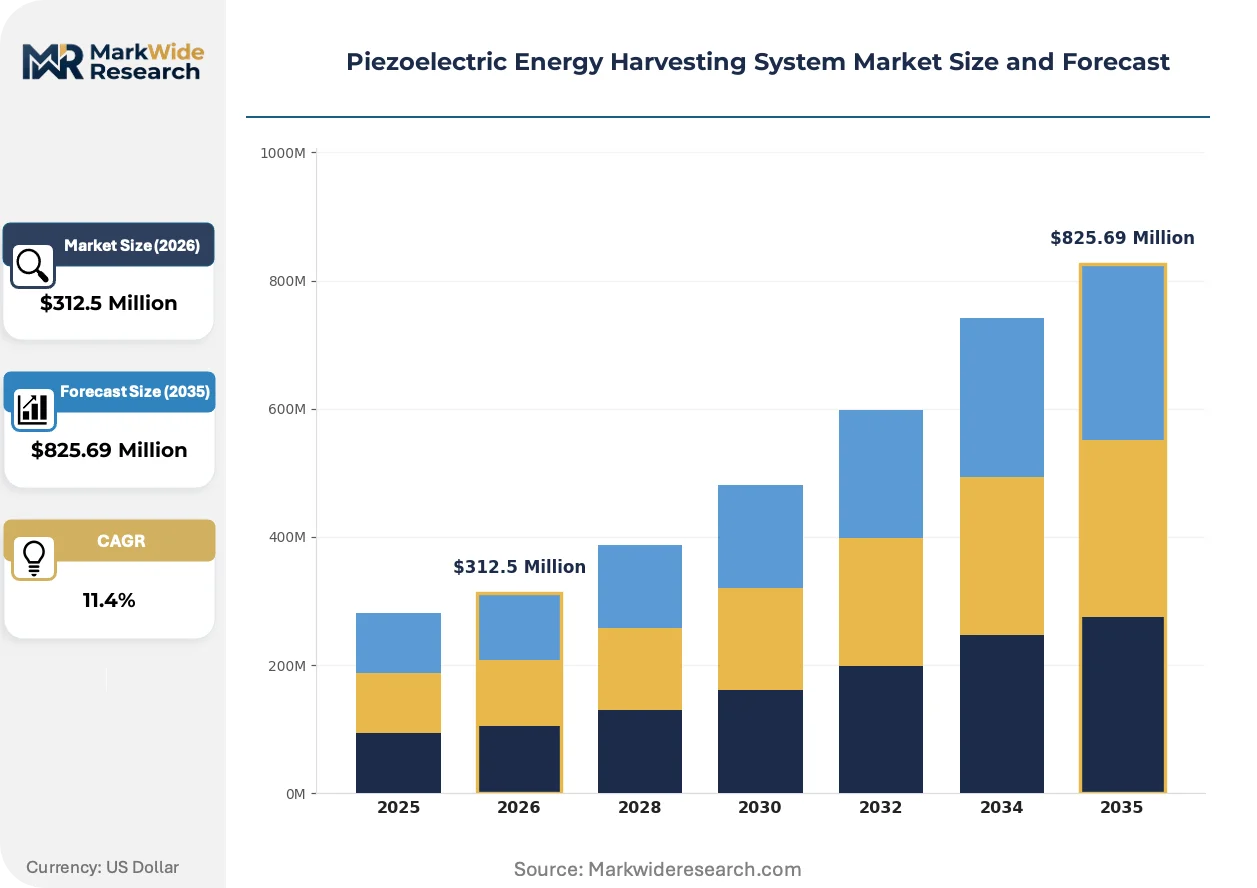
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Footfall Generators, Vibration Energy Harvesters, Acoustic Energy Harvesters, Pressure Sensors Technology: Conventional, MEMS, Hybrid, Nanostructured Application: Wearable Devices, Wireless Sensors, Smart Buildings, Automotive Systems End User: Consumer Electronics, Industrial Automation, Healthcare, Military |
| Companies Covered | ABB, Analog Devices, Inc., STMicroelectronics, Cymbet Corporation, Powercast Corporation, EnOcean GmbH, Honeywell International Inc., Bionic Power Inc., Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piezoelectric Energy Harvesting System Market Strategic Shifts & Innovations
Aluminum nitride thin-film deposition is displacing bulk ceramic approaches, while regulatory pressure on battery waste accelerates architectural redesign across wireless sensor platforms.
MEMS-scale piezoelectric harvesters convert ambient vibration into usable charge through suspended beam structures fabricated on silicon wafers. Automotive OEMs in Stuttgart and Munich integrate these devices into tire pressure monitoring and engine bay sensing. The technology is expanding into predictive maintenance platforms that previously required wired power or scheduled battery replacement.
The EU F-Gas Regulation bans fluorinated greenhouse gases in battery manufacturing processes, elevating total cost of ownership for traditional wireless sensors. Industrial equipment makers face compliance deadlines that compress procurement decisions toward energy-autonomous alternatives. German automotive suppliers now specify piezoelectric power modules in RFQs for new platform architectures.
Buyer procurement committees now mandate lifecycle cost analysis that internalizes battery replacement labor and hazardous waste disposal. Tier-one industrial automation vendors unbundle energy harvesting modules as standalone line items rather than embedded components. This pattern concentrates in German manufacturing clusters where works councils negotiate maintenance burden reductions.
Piezoelectric Energy Harvesting System Market Segmentation
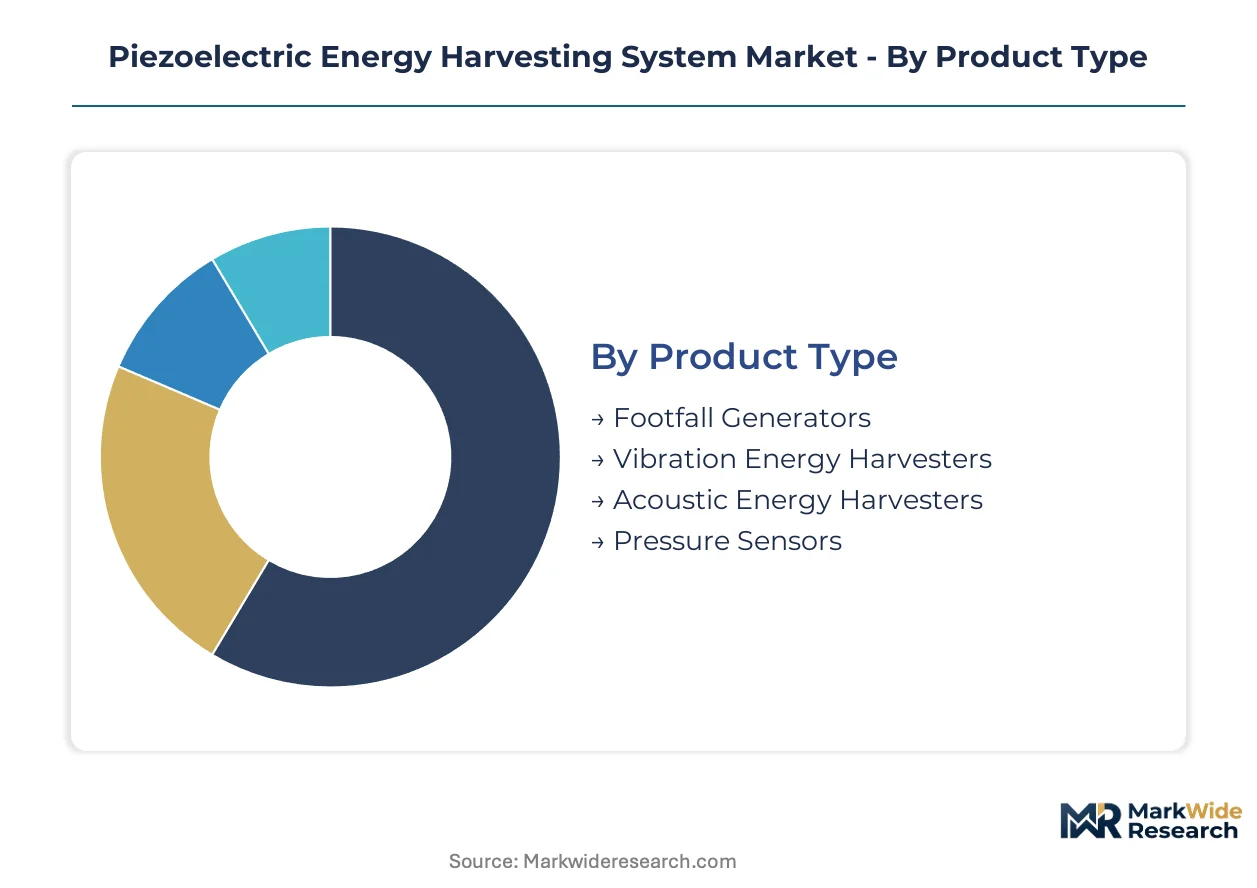
Segmentation in piezoelectric energy harvesting reveals divergent commercialization timelines across product architectures and end-use requirements. Technology maturity, power output specifications, and regulatory compliance burdens create distinct procurement patterns that suppliers must navigate.
Product Type:
Standardized form factors dominate industrial retrofit contracts, while bespoke geometries capture premium smart infrastructure deployments requiring site-specific mechanical coupling.
- Vibration Energy Harvesters:Cantilever-beam and clamped configurations convert ambient mechanical oscillation into electrical charge through lead zirconate titanate or aluminum nitride transducers. Manufacturing facilities in Germany deploy these devices to power predictive maintenance sensors on rotating equipment, eliminating battery replacement labor costs under works council agreements.
- Footfall Generators:Piezoelectric tiles and flooring modules capture kinetic energy from pedestrian traffic through stacked ceramic layers or polymer composites. Airport terminals in Frankfurt and convention centers in Munich integrate these systems to power wayfinding displays and environmental sensors without grid connection.
- Acoustic Energy Harvesters:Diaphragm-coupled piezoelectric elements target industrial noise environments above 80 decibels.
- Pressure Sensors:Force-activated transducers monitor structural loads and fluid dynamics in embedded infrastructure applications.
Most installed capacity flows through vibration energy harvesters. Expansion is steepest in footfall generators.
Technology:
Wafer-scale integration compresses unit economics for high-volume consumer applications, whereas bulk ceramic approaches retain cost advantages in heavy-industrial duty cycles.
- MEMS:Microelectromechanical systems fabricate suspended piezoelectric beams on silicon substrates using semiconductor foundry processes. Taiwan and South Korea foundries achieve wafer-level integration that enables millimeter-scale harvesters for wearable devices and biomedical implants.
- Conventional:Bulk piezoelectric ceramics and single-crystal wafers deliver higher power density for industrial vibration harvesting. Japanese and Chinese specialty ceramic suppliers concentrate production of lead zirconate titanate formulations, exposing OEMs to geopolitical supply chain disruptions.
- Hybrid:Multi-physics architectures combine piezoelectric transduction with electromagnetic or triboelectric mechanisms.
- Nanostructured:Zinc oxide nanowires and two-dimensional materials remain pre-commercial despite superior strain sensitivity in laboratory demonstrations.
Conventional technology retains the largest installed base. MEMS is gaining share fastest in consumer-facing segments.
Application:
Automotive qualification requirements impose longer development cycles than building automation, creating divergent time-to-revenue profiles across application categories.
- Wireless Sensors:Distributed monitoring nodes for industrial equipment, structural health, and environmental parameters constitute the primary revenue pool. EU F-Gas Regulation compliance deadlines accelerate procurement of battery-free architectures that eliminate hazardous waste streams.
- Smart Buildings:Energy-autonomous systems qualify for accelerated permitting under EU Green Deal circular economy criteria. German building automation integrators specify piezoelectric power modules in tenders for new construction and deep retrofit projects.
- Wearable Devices:Fitness trackers and medical monitors leverage MEMS-scale harvesters for supplementary charging.
- Automotive Systems:Tire pressure monitoring and engine bay sensing require AEC-Q100 qualification and electromagnetic compatibility certification.
Wireless sensors account for the dominant share of current installations. Smart buildings show the steepest expansion trajectory.
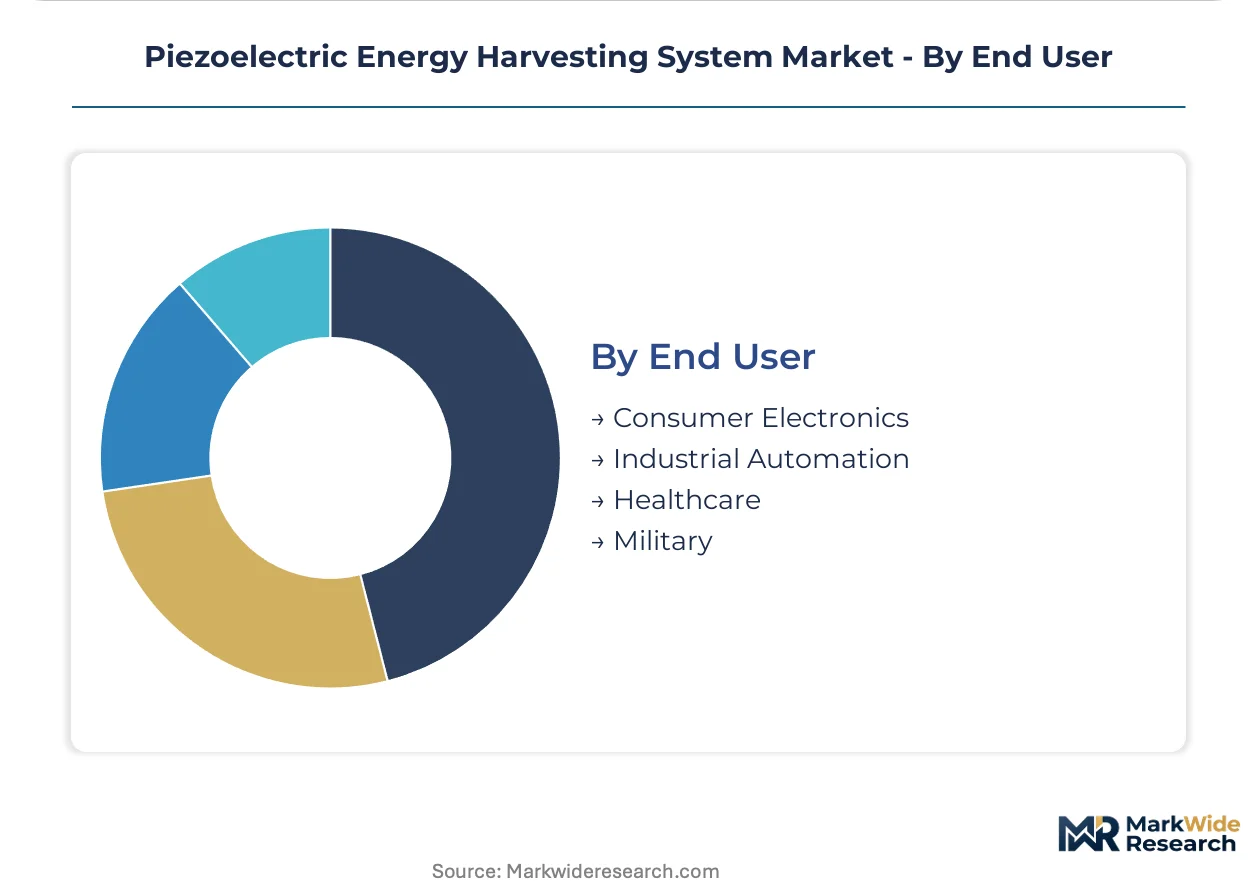
End User:
Healthcare procurement committees prioritize electromagnetic compatibility certification, while military buyers emphasize supply chain security and operational resilience.
- Industrial Automation:Manufacturing facilities deploy vibration harvesters to eliminate battery replacement schedules on predictive maintenance networks. German automotive OEMs and tier-one suppliers now specify energy-autonomous sensors in RFQs for new platform architectures.
- Healthcare:FDA electromagnetic compatibility pathways for battery-free patient monitors open reimbursement channels previously blocked by battery replacement protocols. EMA scrutiny of wireless medical devices tightens certification requirements for harvester-integrated designs.
- Consumer Electronics:Wearable and portable device manufacturers evaluate MEMS harvesters for supplementary power.
- Military:Unattended ground sensors and battlefield monitoring systems demand ruggedized harvesters with extended operational lifespans.
Industrial automation channels the majority of current demand. Healthcare represents the fastest-climbing end-user segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting piezoelectric harvester production toward jurisdictions with streamlined REACH compliance pathways and concentrated MEMS fabrication capacity. The EU F-Gas Regulation imposes steeper cost-of-compliance burdens on battery-dependent architectures, accelerating supplier migration to Germany and Taiwan where energy-autonomous certifications converge with semiconductor manufacturing ecosystems.
Germany
Automotive OEMs in Stuttgart and Munich specify vibration harvesters for predictive maintenance platforms on new vehicle architectures. The EU Green Deal's circular economy criteria accelerate permitting for battery-free building automation systems. Industrial equipment makers in Bavaria integrate piezoelectric power modules into RFQs for Industry 4.0 retrofits.
United States
FDA electromagnetic compatibility pathways for wireless healthcare monitors open reimbursement channels for battery-free patient sensors. EPA hazardous waste regulations tighten total cost of ownership calculations for traditional battery-powered industrial sensors. Automotive suppliers in Michigan evaluate MEMS harvesters for tire pressure monitoring systems.
China
MIIT standards for industrial IoT devices mandate energy efficiency benchmarks that favor vibration harvesting in wireless sensor networks. Dual carbon goals compress procurement timelines toward battery-free architectures in smart manufacturing facilities. Specialty ceramic production clusters in Jiangsu and Zhejiang supply lead zirconate titanate formulations for heavy-industrial harvesters.
Japan
METI funding programs for energy-autonomous infrastructure support deployment of footfall generators in Tokyo transit hubs. JIS standards for building automation systems harmonize with EU Green Deal criteria, facilitating export-oriented production. Osaka-based industrial equipment makers integrate vibration harvesters into predictive maintenance contracts for Southeast Asian manufacturing clients.
Taiwan
Semiconductor foundries achieve wafer-level integration of aluminum nitride thin-film harvesters for consumer wearable applications. The absence of REACH substance restrictions on lead-free formulations accelerates R&D timelines for MEMS-scale devices. Hsinchu Science Park fabs compress unit economics for millimeter-scale harvesters targeting biomedical implant markets.
Piezoelectric Energy Harvesting System Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue MEMS-scale miniaturization and building-automation specialization. The vendor base stratifies across three maturity tiers: diversified electronics conglomerates with captive MEMS fabrication, specialty energy harvesting module suppliers, and semiconductor foundries scaling wafer-level integration. Competitive positioning crystallizes around technology licensing agreements, strategic partnerships with industrial automation OEMs, and geographic expansion into EU Green Deal-compliant jurisdictions.
Among diversified electronics conglomerates, STMicroelectronics and Texas Instruments Incorporated exemplify the integrated-circuit anchoring archetype, while EnOcean GmbH occupies the building-automation specialization tier. STMicroelectronics leverages MEMS fabrication expertise for micro-scale harvester production. Texas Instruments Incorporated anchors its position through power management ICs that condition piezoelectric outputs. EnOcean GmbH differentiates by combining energy harvesting with proprietary wireless protocols for smart infrastructure.
| Leading Market Players |
|---|
| ABB |
| Analog Devices, Inc. |
| STMicroelectronics |
| Cymbet Corporation |
| Powercast Corporation |
| EnOcean GmbH |
| Honeywell International Inc. |
| Bionic Power Inc. |
| Texas Instruments Incorporated |
| Others |
Cost & Logistics Intelligence
Lead zirconate titanate ceramic costs cascade through three pricing tiers as specialty suppliers in Japan and China pass through raw material volatility to OEM procurement committees. Buyers in German automotive and industrial automation segments absorb premium pricing for REACH-compliant formulations, while cost-sensitive building automation integrators in Asia-Pacific negotiate volume discounts on standard-grade harvesters.
Pricing Analysis
Input-cost pass-through from specialty ceramic suppliers compresses margins at the standard tier while premium-tier pricing holds firm on compliance differentiation. Pricing stratifies across AEC-Q100 automotive qualification, ISO-certified industrial grade, and uncertified economy tiers for consumer applications. Cost compression in the economy tier intensifies as Taiwanese foundries scale aluminum nitride MEMS production. Industrial automation buyers exhibit highest price sensitivity due to works council pressure on maintenance budgets, whereas healthcare procurement committees prioritize electromagnetic compatibility certification over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German automotive and industrial equipment makers, while distribution partners serve fragmented building automation integrators. Supply concentrates in Japan and China for lead zirconate titanate ceramics, Taiwan and South Korea for MEMS fabrication, and Germany for system integration. Raw material dependencies include specialty piezoelectric ceramics, silicon wafers, and power management ICs. Single-source vulnerability in Japanese ceramic supply exposes OEMs to geopolitical disruption. Distribution runs through authorized distributors for industrial accounts and direct sales teams for strategic automotive partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation compounds demand for battery-free architectures, creating structural pull for piezoelectric harvesters as OEMs face compliance deadlines that eliminate hazardous waste streams from wireless sensor networks.
For Market Incumbents: Lock in long-term supply agreements with Japanese and Chinese specialty ceramic producers before REACH phase-out timelines accelerate. Defend position by accelerating captive MEMS fabrication investments in Taiwan to offset commodity pressure in bulk ceramic segments. Prioritize AEC-Q100 certification pipelines for automotive OEMs in Stuttgart and Munich who now specify energy-autonomous sensors in platform RFQs. For New Entrants and Emerging Players: Launch via direct partnerships with German building automation integrators who qualify for accelerated EU Green Deal permitting. Target footfall generator deployments in airport terminals and convention centers where high pedestrian density meets maintenance-free power requirements. Pursue white-space opportunities in FDA electromagnetic compatibility pathways for battery-free patient monitors, opening reimbursement channels previously blocked by battery replacement protocols. For Investors and Strategic Acquirers: Consolidation pressure builds where MEMS design talent scarcity concentrates at a handful of research institutes and semiconductor foundries. Frame long-term viability around aluminum nitride convergence with CMOS fabrication lines enabling monolithic harvester-processor chips. Target acquisition profiles emphasizing proprietary wireless protocol integration and energy harvesting module specialization. Monitor IEC harmonization progress for energy-autonomous IoT devices as the inflection signal determining which technology platforms achieve cross-border commercial scale.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Ceramic Development | Alternative chemistries secure market access as lead-containing formulations face phase-out deadlines under EU substance restrictions. |
| Wafer-Level MEMS Integration | Taiwanese foundries compress unit economics for millimeter-scale harvesters targeting consumer wearable and biomedical implant markets. |
| AEC-Q100 Certification Investment | Automotive qualification opens tire pressure monitoring and engine bay sensing contracts with Stuttgart and Munich OEMs. |
| Building Automation Partnership | EnOcean GmbH demonstrates value of combining energy harvesting with proprietary wireless protocols for smart infrastructure tenders. |
| Healthcare Regulatory Pathway | FDA electromagnetic compatibility certification unlocks reimbursement channels for battery-free patient monitoring devices. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MEMS design engineers, industrial automation procurement leads, building automation integrators, and healthcare regulatory affairs specialists with secondary validation against SEC filings, EU regulatory databases, and semiconductor foundry capacity disclosures. Bottom-up segment sizing triangulated against top-down market envelope checks to ensure consistency across technology, application, and end-user dimensions.
Historical reference periods anchored the forecast window to observed adoption curves in industrial vibration harvesting and emerging penetration rates in MEMS-scale consumer applications. The analytical framework modeled product type, technology maturity, application qualification requirements, and end-user procurement behavior across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers and regulatory milestone timing. Forecast inputs included EU F-Gas Regulation compliance deadlines, MIIT energy efficiency benchmarks, and FDA electromagnetic compatibility pathway developments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated REACH substance restrictions or geopolitical disruption to Japanese ceramic supply. Periodic stress-testing of base assumptions is recommended, particularly regarding aluminum nitride thin-film deposition yield rates and IEC harmonization timelines for energy-autonomous IoT certification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Thermoelectric Assemblies Market
Power Systems
Shunt Voltage References Market
Power Systems
Generator Circuit Breaker Market
Power Systems
Semiconductor Rectifier Market
Power Systems
Europe Variable Frequency Drive Market
Power Systems
Low Voltage AC Drive Market
Power Systems
Pulse Generator Market
Power Systems
Shunt Reactor Market
Power Systems
Global Rectifier Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Low Voltage Drives Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Shunt Capacitor Market
Power Systems
DC Power Supplies Market
Power Systems
EV Power Module Market
Power Systems
Solid State Transformer Market