
 Product Design Verification and Validation Solution Market | 2026-2036
Product Design Verification and Validation Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Product Design Verification and Validation Solution Market Analytics
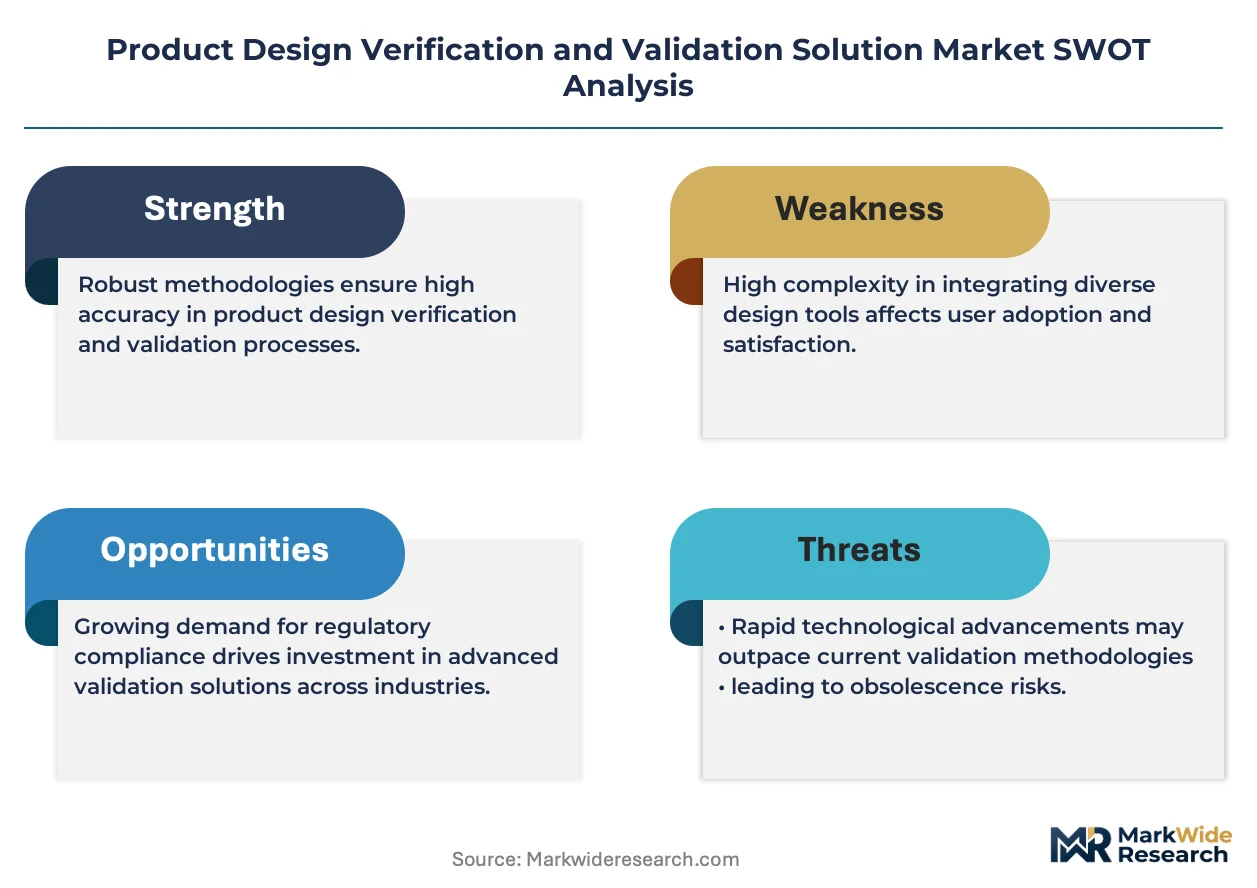
The CAPEX gap between full-stack platform owners and point-tool vendors is reorganizing competitive tiers in this space. Siemens leverages its digital industries software portfolio to anchor integrated verification workflows across automotive and aerospace accounts. Altair Engineering specializes in high-performance computing simulation, competing on solver speed and cloud elasticity rather than breadth.
Product design verification and validation solutions encompass software tools and engineering services that confirm a product meets specified requirements through simulation, physical testing, and compliance documentation prior to mass production. These systems typically integrate finite element analysis, computational fluid dynamics, and model-based systems engineering to predict performance under operational stress, thermal load, and fatigue cycles. Simulation tools command the largest revenue share among technology segments, though testing frameworks are gaining traction as OEMs outsource physical validation to certified service providers. Quality assurance platforms serve as the fastest-expanding category, driven by traceability mandates that require automated audit trails across distributed supplier networks.
FDA software validation guidelines, EU MDR technical documentation requirements, and ISO 9001 quality management standards collectively shape procurement criteria and platform certification roadmaps for solution vendors. EMA and FAA airworthiness directives further tighten the evidence burden for medical device and aerospace applications, forcing developers to demonstrate closed-loop requirement traceability. Stakeholders must evaluate whether their current tool chains can absorb emerging AI-assisted verification modules without fragmenting audit readiness.
Market Dynamics
Simulation-driven validation workflows are compressing physical testing cycles as automotive OEMs pursue parallel digital-physical development tracks. The EU AI Act and FDA software validation guidelines are elevating compliance verification spend across safety-critical product categories.
Growth Catalysts
- Automotive Electrification Mandates:Battery pack validation requirements under EU Battery Regulation are forcing OEMs to expand thermal-runaway simulation capacity. Germany's engineering clusters anchor this demand concentration.
- EU AI Act Compliance Burden:High-risk AI system documentation requirements are elevating automated traceability platform procurement. Medical device manufacturers face the steepest evidence thresholds.
- Cloud-Native Solver Architectures:Elastic compute access is decomposing capital-intensive on-premise HPC ownership. Tier-2 suppliers now access simulation fidelity previously reserved for prime contractors.
Market Restraints
- Specialized Talent Scarcity:Model-based systems engineering expertise concentrates in Germany, the United States, and Japan. Salary inflation for verification engineers exceeds 15% annually in these markets.
- Legacy Tool Entrenchment:Decades of embedded MATLAB and Simulink workflows create switching friction. Aerospace primes face decade-long platform migration timelines.
- Physical Testing Infrastructure:Environmental chamber and crash-test facility capex requirements lock out mid-market entrants. Certification body accreditation timelines extend 18-24 months.
Strategic Opportunities
- India Manufacturing Expansion:PLI scheme incentives for automotive and electronics are attracting validation service providers. BIS certification requirements for domestic market access create localized platform demand.
- Digital Twin Convergence:Integration of IoT operational data with design simulation is enabling predictive validation. Asset-intensive industries in China are piloting closed-loop verification.
- FDA Software as Medical Device Pathway:SaMD classification expansion is creating dedicated validation service demand. Cybersecurity verification modules represent adjacent revenue capture.
Industry Challenges
- Multi-Domain Integration Complexity:Coupled thermal-structural-electromagnetic simulations require cross-functional coordination. Organizational silos between mechanical and software teams fragment traceability.
- Supplier Network Audit Burden:Tier-n visibility mandates under ISO 9001 and EU MDR require automated evidence collection. Platform vendors must orchestrate distributed certification workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Product Design Verification and Validation Solution Market |
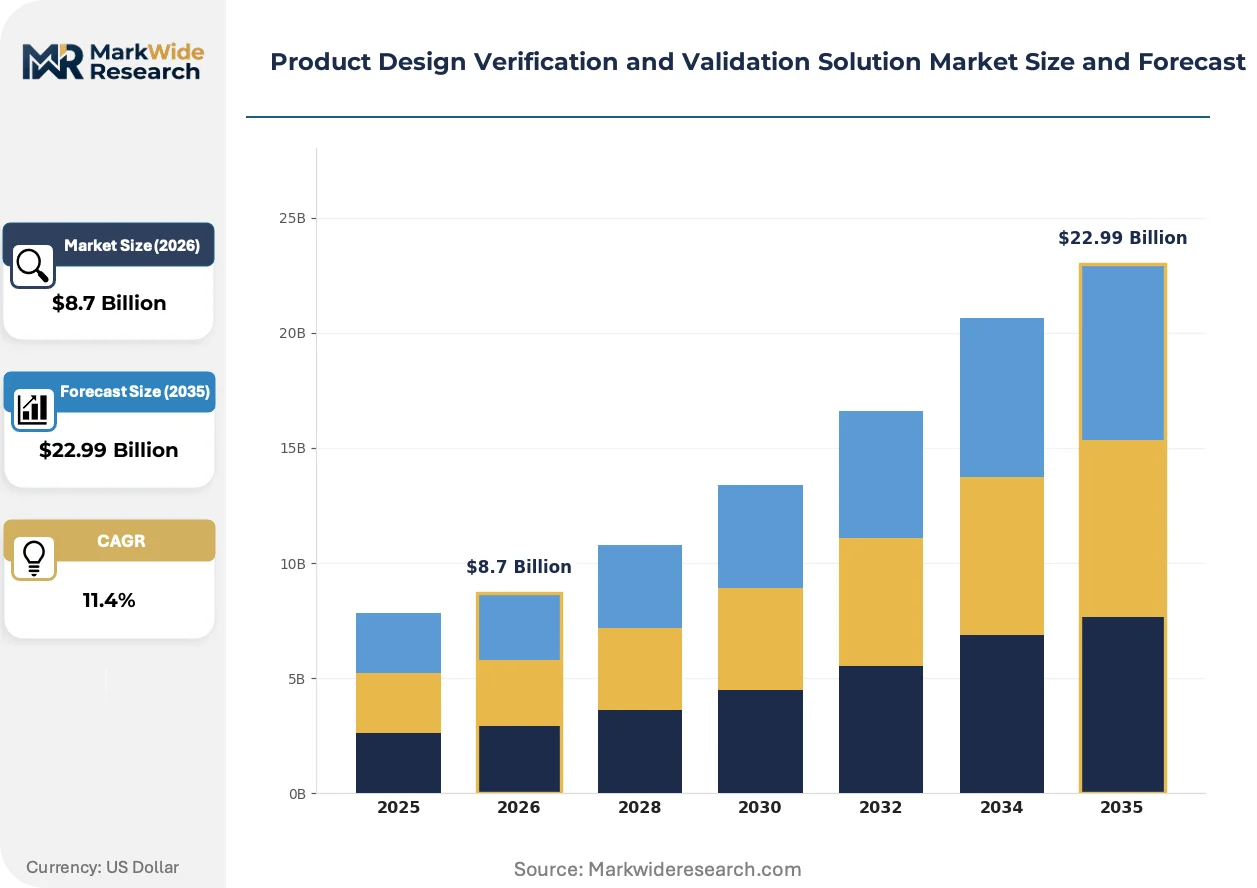
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design Validation, Functional Testing, Compliance Verification, Prototype Assessment Technology: Simulation Tools, CAD Software, Testing Frameworks, Quality Assurance Platforms End User: Manufacturers, Product Developers, R&D Departments, Quality Control Teams Application: Aerospace, Automotive, Electronics, Consumer Goods |
| Companies Covered | Siemens, Dassault Systemes, PTC, ANSYS, Altair Engineering, Autodesk, Hexagon, Zuken, Mentor Graphics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Product Design Verification and Validation Solution Market Evolving Landscape
Artificial intelligence is penetrating verification workflows through surrogate modeling and automated test generation. Regulatory bodies are codifying AI-assisted validation evidence standards. Buyer procurement criteria are elevating platform interoperability above point-tool performance.
Surrogate modeling via neural networks is decomposing traditional finite element analysis bottlenecks. Automotive crash simulation teams at BMW and Ford deploy physics-informed machine learning to compress solver runtime from days to hours. This acceleration is decomposing the hardware-in-the-loop testing phase, allowing virtual sign-off prior to physical prototype commitment.
The EU AI Act's high-risk system documentation requirements are mandating algorithmic audit trails for verification software itself. Medical device manufacturers must demonstrate that their simulation tools produce reproducible, explainable outputs. FDA draft guidance on predetermined change control plans is forcing platform vendors to bake regulatory evidence generation into software architecture.
Subscription pricing for simulation platforms is displacing perpetual license models among mid-market engineering firms. ANSYS and Dassault Systèmes report 60% recurring revenue ratios as buyers prioritize operational flexibility over capital ownership. This shift is most pronounced in the United States, where private-equity-backed manufacturing rollups favor opex-light tooling stacks.
Product Design Verification and Validation Solution Market Segmentation
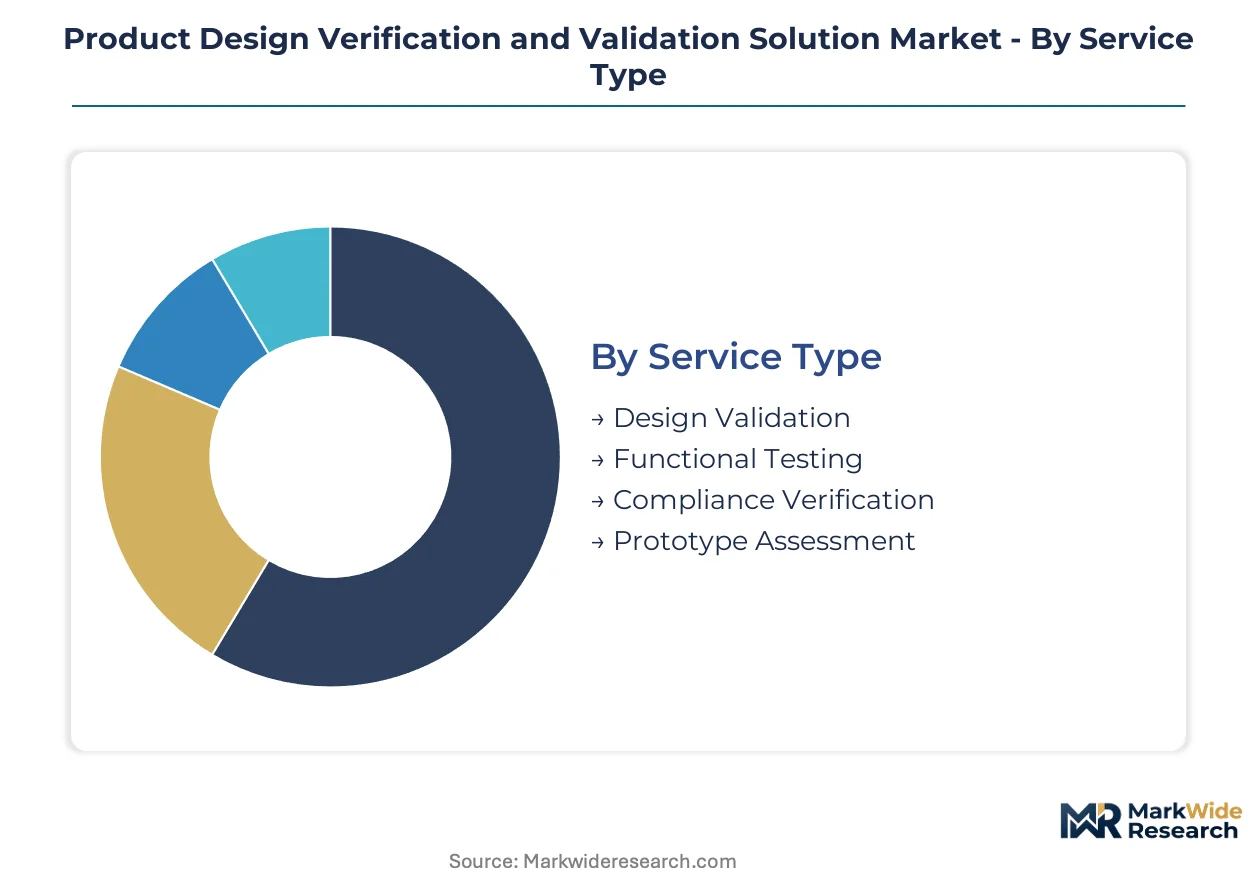
Segmentation in this market reveals distinct procurement patterns across engineering maturity tiers. Automotive and aerospace primes prioritize integrated platform stacks, while mid-market electronics firms favor modular point solutions with elastic licensing.
Service Type:
Demand spreads unevenly across geographies, with compliance verification services concentrated in regulated European markets and prototype assessment dominating export-led Asian manufacturing hubs.
- Design Validation:Finite element analysis and computational fluid dynamics workflows dominate early-stage product development. German automotive clusters anchor demand for thermal-runaway simulation capacity under EU Battery Regulation mandates. OEMs compress physical testing cycles through parallel digital-physical development tracks.
- Functional Testing:Hardware-in-the-loop and software-in-the-loop protocols verify subsystem integration before prototype commitment. China's electronics manufacturing corridors drive volume, with domestic BIS certification requirements creating localized service demand for India market access. Battery management system validation represents the fastest-expanding sub-segment.
- Compliance Verification:Automated documentation for FDA software validation and EU AI Act high-risk system requirements.
- Prototype Assessment:Physical testing coordination through certified third-party laboratories.
Design validation holds the largest share; momentum sits with compliance verification.
Technology:
Cost tier differentiation separates enterprise platform subscriptions from pay-per-simulation cloud access for mid-market engineering teams.
- Simulation Tools:Multiphysics solvers for structural, thermal, and electromagnetic analysis command premium pricing. United States private-equity-backed manufacturing rollups favor opex-light subscription models over perpetual licenses. Surrogate modeling via neural networks compresses solver runtime from days to hours at BMW and Ford crash simulation teams.
- Quality Assurance Platforms:Automated audit trail generation for ISO 9001 and EU MDR traceability mandates. Medical device manufacturers face the steepest evidence thresholds under FDA predetermined change control plan guidance. These platforms orchestrate distributed certification workflows across tier-n supplier networks.
- CAD Software:Geometry preparation and design-for-manufacturability verification.
- Testing Frameworks:Test sequence automation and results documentation for physical validation.
Simulation tools dominate revenue; quality assurance platforms are expanding most quickly.
End User:
Volume concentration varies by organizational scale, with R&D departments at tier-1 primes representing high-value contracts and quality control teams at tier-2 suppliers driving seat-count expansion.
- Manufacturers:Production-scale verification spanning incoming inspection through final acceptance testing. Germany's engineering-intensive manufacturing clusters deepen digital twin investments, anchoring integrated workflow procurement. Stricter safety mandates from EMA and FAA airworthiness directives elevate compliance verification spend.
- R&D Departments:Early-stage concept validation and technology readiness level advancement. Japan's METI-funded automotive electrification programs concentrate demand for battery pack thermal simulation. Model-based systems engineering expertise scarcity in these markets drives 15% annual salary inflation for verification engineers.
- Product Developers:Cross-functional coordination between mechanical and software engineering teams.
- Quality Control Teams:Statistical process control and non-conformance documentation.
Manufacturers capture the largest share; R&D departments show the steepest expansion trajectory.
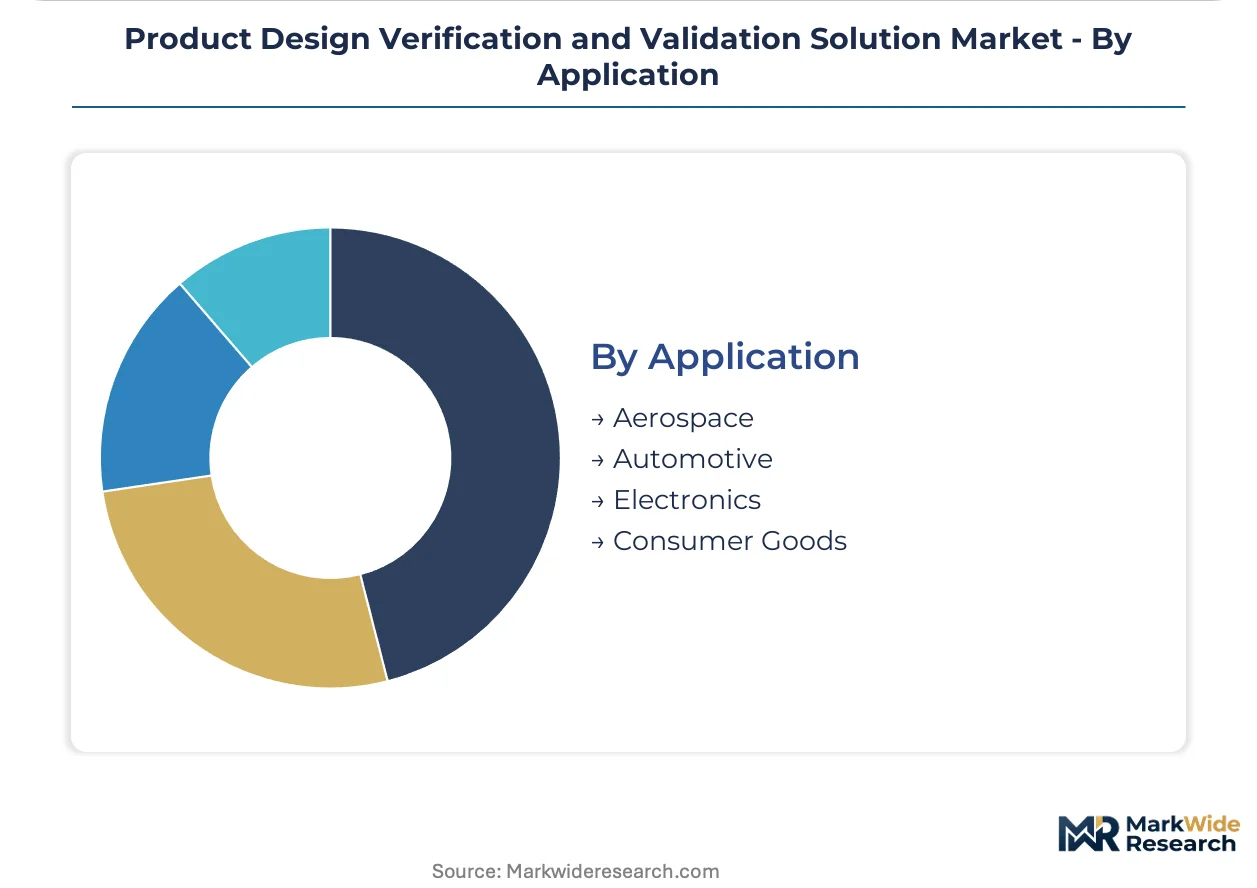
Application:
Maturity differentiation separates aerospace's decade-long platform migration timelines from automotive's aggressive simulation-driven compression of development cycles.
- Automotive:Electrification mandates under EU Battery Regulation force thermal-runaway simulation capacity expansion. Cloud-native solver architectures enable tier-2 suppliers to access fidelity previously reserved for prime contractors. BMW and Ford deploy physics-informed machine learning for virtual sign-off prior to physical prototype commitment.
- Aerospace:FAA airworthiness directives and EMA certification requirements demand closed-loop requirement traceability. Legacy MATLAB and Simulink workflow entrenchment creates switching friction, extending platform migration timelines to decade horizons. Cybersecurity verification modules represent adjacent revenue capture as SaMD classification expands.
- Electronics:Signal integrity and electromagnetic compatibility validation for high-speed designs.
- Consumer Goods:Accelerated life testing and packaging validation for retail distribution.
Automotive leads absolute spend; aerospace commands the highest per-seat pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German automotive clusters prioritize integrated digital twin platforms, while United States buyers favor subscription elasticity. Chinese manufacturers emphasize rapid physical prototyping, and Indian export hubs concentrate on compliance documentation for Western market access.
United States
Private-equity-backed manufacturing rollups drive opex-light tooling procurement. FDA software validation guidelines elevate compliance verification spend across medical device corridors in Massachusetts and Minnesota. Boston's medtech cluster anchors automated traceability platform demand.
Germany
EU Battery Regulation thermal-runaway mandates force OEM simulation capacity expansion. KBA type-approval requirements tighten evidence standards for automotive software. Stuttgart and Munich engineering clusters deepen multiphysics solver investments.
China
Domestic EV manufacturers compress development cycles through parallel digital-physical tracks. MIIT new energy vehicle certification creates localized platform requirements. Shenzhen and Shanghai electronics corridors drive battery management system validation volume.
India
PLI scheme incentives attract automotive and electronics validation service providers. BIS certification requirements for domestic market access create localized quality assurance demand. Tamil Nadu and Gujarat manufacturing belts anchor export-oriented prototype assessment.
Japan
METI-funded automotive electrification programs concentrate battery pack thermal simulation demand. PMDA software as medical device pathways tighten cybersecurity verification requirements. Nagoya and Tokyo R&D hubs face 15% annual salary inflation for model-based systems engineering talent.
Product Design Verification and Validation Solution Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in this market. Full-stack platform owners command premium pricing through workflow integration, while point-tool vendors compete on solver speed and cloud elasticity. Three archetypes dominate: diversified industrial software conglomerates, simulation specialists, and emerging cloud-native entrants. Competitive intensity centers on M&A-driven portfolio expansion and strategic partnerships for AI-assisted verification modules.
Among diversified industrial software conglomerates, Siemens and Dassault Systemes exemplify the integrated platform approach, anchoring end-to-end verification workflows across automotive and aerospace accounts. Altair Engineering occupies a specialist position, competing on high-performance computing simulation and cloud elasticity rather than breadth. These three represent distinct strategic postures within a market where buyer procurement criteria increasingly favor interoperability above point-tool performance.
| Leading Market Players |
|---|
| Siemens |
| Dassault Systemes |
| PTC |
| ANSYS |
| Altair Engineering |
| Autodesk |
| Hexagon |
| Zuken |
| Mentor Graphics |
| Others |
Value Network & Pricing Analysis
Capacity utilization at certified physical testing facilities in Germany, the United States, and China creates natural price floors for validation services, compressing margins for mid-market entrants while anchoring premium tiers for integrated platform vendors with captive solver infrastructure.
Pricing Analysis
After-sales revenue from extended validation service contracts and compliance documentation subscriptions drives lifetime value for platform vendors. Pricing stratifies across premium, standard, and economy tiers based on solver fidelity and certification grade, with FDA-validated medical device modules commanding substantial premiums over general-purpose simulation seats. Cost compression in cloud-native solver access is intensifying because elastic compute democratizes high-fidelity simulation previously reserved for prime contractors. Tier-2 automotive suppliers exhibit the highest price sensitivity, while aerospace primes prioritize traceability depth over per-seat cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate software delivery, though strategic stockpiling of HPC compute reservations secures solver capacity during peak validation windows for automotive program launches. Supply concentrates in Germany, the United States, and China for multiphysics solver development, with specialized talent pools in Japan feeding model-based systems engineering expertise. Raw material dependencies span semiconductor accelerators for GPU-based simulation, environmental chamber components for physical testing, and rare-earth elements for electromagnetic validation hardware. Single-source vulnerability runs through cloud hyperscaler infrastructure for elastic compute. Distribution runs through direct enterprise sales teams for platform vendors and certified service provider networks for outsourced physical validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act high-risk system documentation mandates are accelerating procurement of automated traceability platforms, creating a regulatory inflection that favors vendors with pre-built compliance modules over point-tool specialists.
For Market Incumbents: Fortify platform stickiness through embedded regulatory evidence generation that satisfies FDA predetermined change control plan requirements. Deepen vertical integration into cloud-native solver infrastructure to defend margin position against elastic-compute entrants. Prioritize certification investments in EU MDR and FAA airworthiness directive compliance to lock out mid-market challengers lacking audit-ready architecture. For New Entrants and Emerging Players: Differentiate on AI-assisted verification modules that compress surrogate modeling runtime for automotive crash simulation teams. Target India's PLI scheme manufacturing corridors where BIS certification requirements create localized platform demand underserved by incumbent direct-sales coverage. Pursue channel partnerships with certified third-party testing laboratories to bypass decade-long aerospace platform migration timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among quality assurance platform vendors orchestrating tier-n supplier network certification workflows, suggesting superior cash-flow predictability over project-based physical testing services. Long-term viability hinges on regulatory moat depth across EU AI Act and FDA software validation guideline evolution. Watch for inflection when AI-assisted verification modules achieve formal acceptance from EMA and FAA as primary evidence sources.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates simulation, testing, and compliance workflows under single audit trails for automotive OEMs. |
| Regulatory Certification Investment | Pre-validated FDA and EU MDR modules accelerate procurement cycles for medical device manufacturers. |
| Cloud-Native Solver Deployment | Elastic compute access democratizes high-fidelity simulation for tier-2 suppliers in China and India. |
| AI-Assisted Verification Module Launch | Surrogate modeling via neural networks compresses BMW and Ford crash simulation runtime from days to hours. |
| Strategic Partnership with Testing Laboratories | Certified third-party physical validation extends platform reach without environmental chamber capex. |
Research Methodology
Operator-level perspectives from simulation engineering directors, regulatory affairs leads at medical device manufacturers, Tier 1 automotive procurement officers, and cloud platform integration specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA technical documentation databases, SEC 10-K software segment disclosures, and hyperscaler capex reports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Sensitivity analysis tested forecast robustness across adoption rate scenarios for AI-assisted verification modules and regulatory enforcement intensity variations. Segmentation dimensions modeled span service type, technology tier, end-user organization scale, and application vertical across the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking procurement pattern indicators, with specific inputs including automotive electrification program timelines and medical device software classification expansion rates.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of EU AI Act documentation requirements or accelerated cloud migration timelines would require recalibration. Forecasts reflect assumptions regarding talent availability for model-based systems engineering and hyperscaler infrastructure investment continuity. Revision becomes warranted when FAA or EMA guidance on AI-assisted validation evidence crosses formal acceptance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Electrical Test Equipment Market
Test and Measurement
Battery Drop Tester Market
Test and Measurement
Test Benches Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Dosimeter Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Compression Testing Machines Market
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
Modular Test Equipment Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market
Test and Measurement
Oscilloscope Market
Test and Measurement
Industrial Metrology Market
Test and Measurement
Diamond Tester Market
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Battery Testing Market
Test and Measurement
Reverberation Chambers Market