
 North America Electrical Testing Services Market | 2026-2036
North America Electrical Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electrical Testing Services Market Analytics
Digital twin integration with live sensor networks is reconfiguring how electrical testing firms deliver predictive diagnostics. SGS SA leverages its North American laboratory footprint to anchor large-scale industrial commissioning contracts. Bureau Veritas competes through specialized high-voltage substation testing protocols. Doble Engineering Company sustains technology leadership in dissolved gas analysis for transformer health monitoring.
Electrical testing services encompass the measurement, verification, and certification of electrical system performance against defined safety and operational parameters, typically involving insulation resistance testing, contact resistance measurement, and power factor analysis at voltages ranging from low-tension distribution to extra-high-voltage transmission levels. These services ensure operational continuity, personnel safety, and regulatory compliance across energized infrastructure. Diagnostic testing commands premium pricing due to specialized engineering labor and predictive value, while digital testing technology is displacing manual methods in utility-scale deployments. Mobile testing solutions are gaining traction among data center operators seeking minimized downtime during facility upgrades.
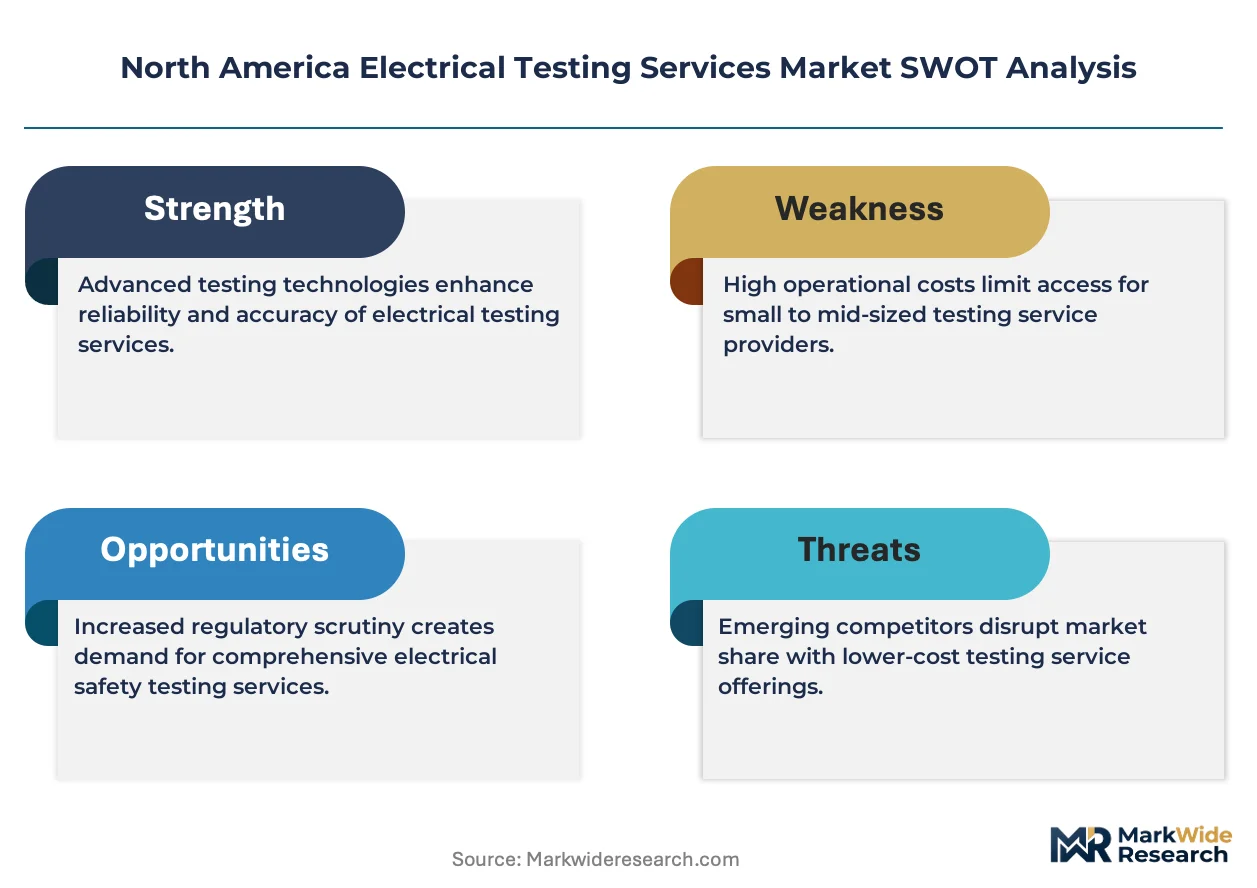
OSHA electrical safety standards, the National Electrical Code, and NFPA 70E arc-flash requirements collectively mandate periodic testing intervals and documented compliance records for commercial and industrial facilities. Health Canada and provincial electrical authorities enforce parallel certification regimes that shape cross-border service standardization. Stakeholders must weigh capital deployment between automated testing platforms and specialized diagnostic engineering talent as the technology mix shifts.
Market Dynamics
Digital twin architectures fused with live sensor networks are compressing testing intervals across critical infrastructure. Predictive diagnostics now command premium positioning as facility operators trade scheduled outages for continuous condition monitoring.
Growth Catalysts
- OSHA electrical safety mandates:Tightened compliance windows for facility managers are expanding mandatory testing scopes across industrial and commercial installations.
- Data center power infrastructure:Operators across the United States and Canada are lengthening preventive maintenance contracts to minimize downtime during capacity expansions.
- Gulf Coast industrial corridor concentration:Petrochemical and LNG facility buildouts are generating sustained demand for arc-flash and transformer testing protocols.
Market Restraints
- Specialized engineering labor scarcity:Diagnostic testing requires certified technicians whose training pipelines cannot match deployment velocity.
- High-voltage equipment capital intensity:Mobile testing platforms for extra-high-voltage transmission levels demand seven-figure equipment investments.
- NFPA 70E documentation friction:Arc-flash compliance record-keeping creates administrative overhead that elongates contract negotiation cycles.
Strategic Opportunities
- Canadian provincial electrical authorities:Cross-border certification regime harmonization creates standardization arbitrage for testing firms with dual accreditation.
- Dissolved gas analysis convergence:Transformer health monitoring platforms are integrating chromatographic sensors with cloud-based degradation modeling.
- Utility-scale automation tailwind:Digital testing technology displacing manual methods opens retrofit contracts across aging transmission infrastructure.
Industry Challenges
- IEC 61850 protocol integration:Substation automation standards create interoperability complexity when merging legacy electromechanical assets with digital testing suites.
- Certified technician retention:High-voltage testing specialists face poaching from utilities offering superior benefit structures and geographic stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electrical Testing Services Market |
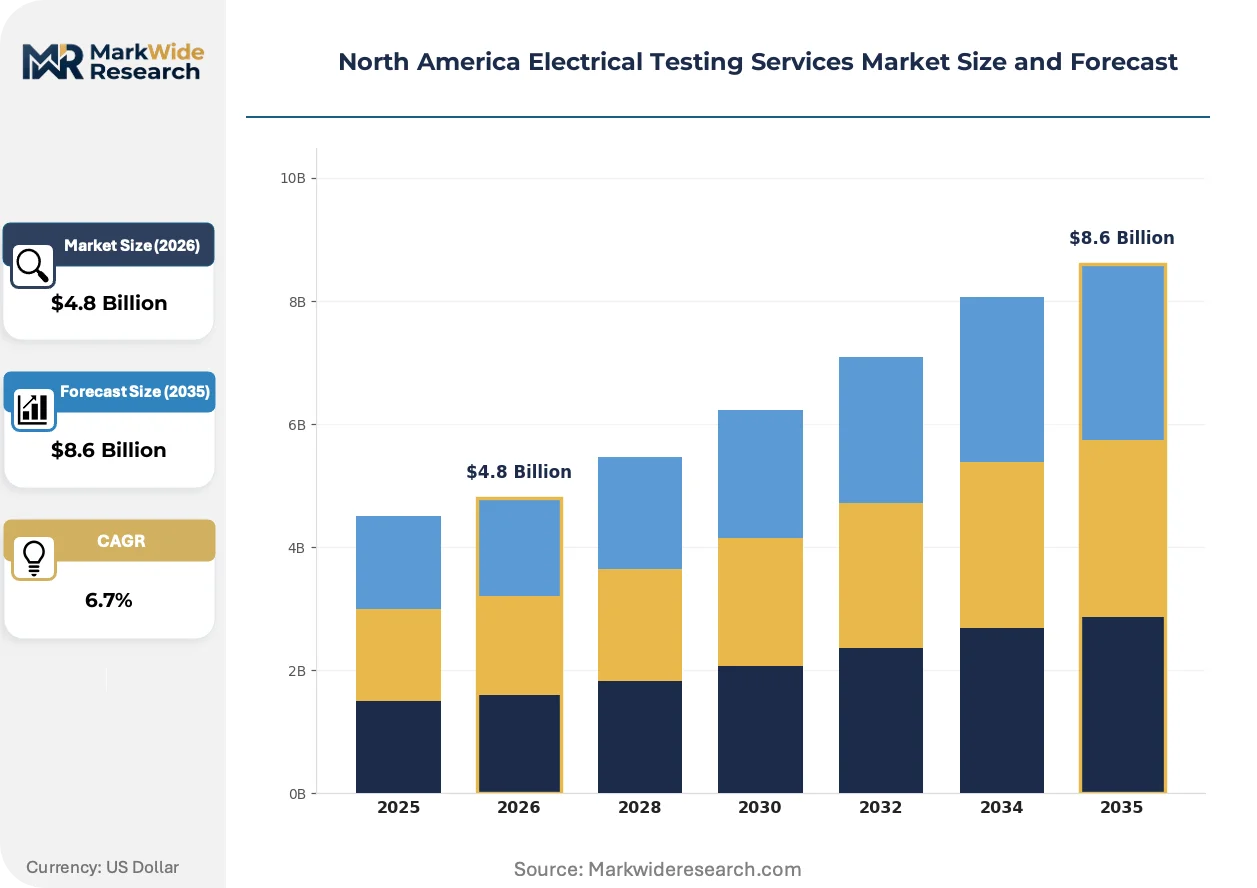
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Routine Testing, Diagnostic Testing, Calibration Services, Safety Testing Application: Industrial Facilities, Commercial Buildings, Power Generation, Telecommunications Technology: Traditional Testing, Digital Testing, Automated Testing, Mobile Testing Solutions End User: Utilities, Manufacturing, Construction, Data Centers |
| Companies Covered | TÜV SÜD, ALS Limited, SGS SA, RESA Power, Doble Engineering Company, Bureau Veritas, Applus+, American Electrical Testing Co. LLC, Intertek Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electrical Testing Services Market Evolving Landscape
Condition-based maintenance architectures are supplanting time-based inspection regimes across transmission and distribution networks. Technology deployment now centers on predictive capability rather than diagnostic confirmation.
Sensor-embedded transformer monitoring is hybridizing dissolved gas analysis with thermal imaging and partial discharge detection into unified health indices. Major utilities in Texas and California are deploying these platforms at 345kV substations. The convergence is hybridizing equipment procurement decisions, with buyers now evaluating integrated sensor suites rather than standalone testing instruments.
The National Electrical Code update cycle has compressed from three-year to annual amendment reviews, accelerating compliance recertification demands. Industrial facility managers must now track interim amendments between formal code editions. Food processing and pharmaceutical manufacturing sites in the Midwest are responding by embedding electrical testing clauses directly into capital project budgets.
Service contract unbundling is fragmenting traditional comprehensive testing agreements into discrete diagnostic modules. Data center operators now procure insulation resistance testing, contact resistance measurement, and power factor analysis as separate line items. This granularity is most pronounced in Northern Virginia and Dallas-Fort Worth colocation markets, where uptime guarantees drive precise scope delineation.
North America Electrical Testing Services Market Segmentation
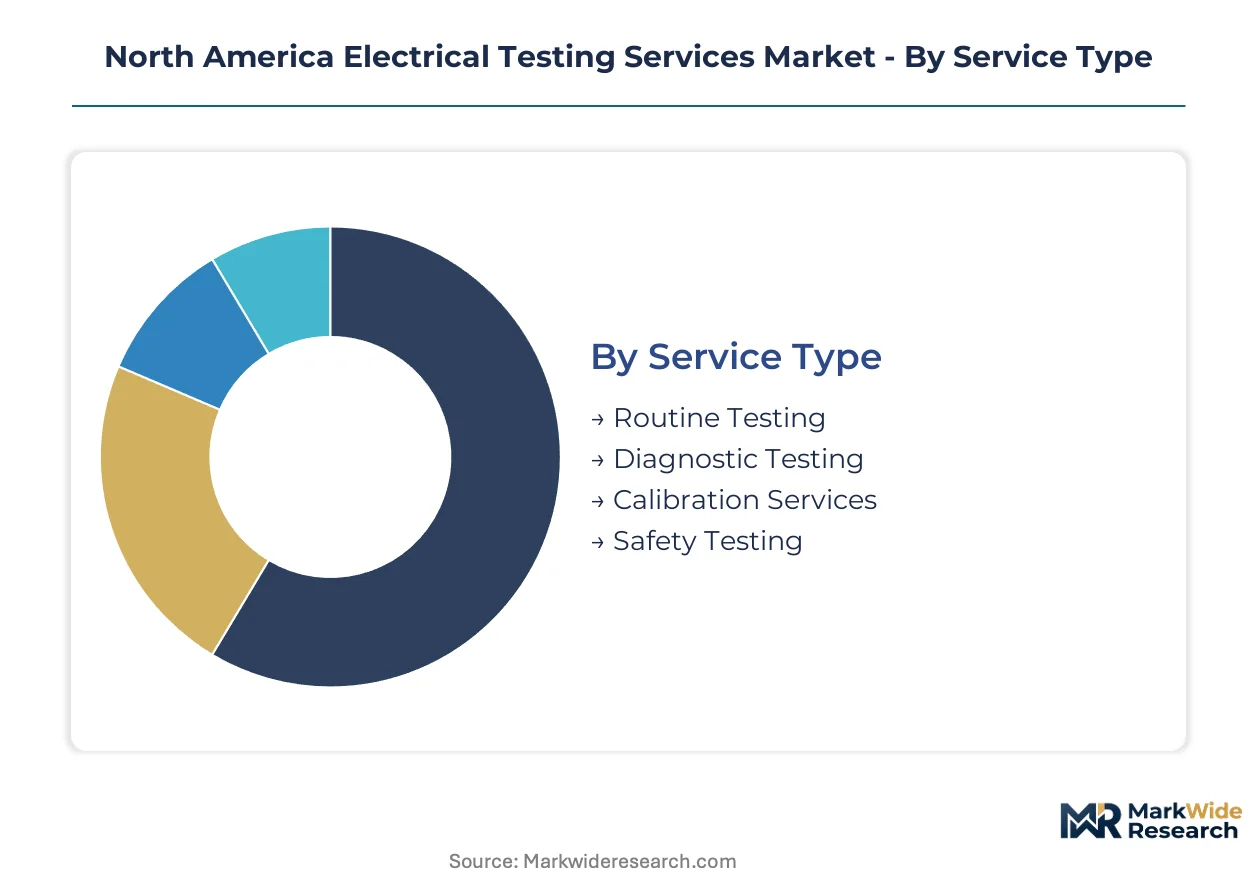
Service differentiation across the North America Electrical Testing Services Market determines contract pricing, technician certification requirements, and equipment capital intensity. Segmentation reveals where predictive capabilities command premium positioning versus commoditized compliance verification.
Service Type:
Diagnostic testing contracts turn over fastest with quarterly or semi-annual renewal cycles, while calibration services lock in multi-year agreements through embedded instrument fleets.
- Routine Testing:Scheduled insulation resistance, continuity, and ground fault verification at fixed intervals. Gulf Coast petrochemical facilities in Texas and Louisiana anchor volume demand as OSHA mandates compress testing windows.
- Diagnostic Testing:Dissolved gas analysis, partial discharge detection, and power factor diagnostics requiring specialized engineering labor. Data center operators in Northern Virginia and Dallas-Fort Worth procure these services to minimize unplanned outages during capacity expansions.
- Calibration Services:Traceable certification of measurement instruments against NIST standards. Utilities maintain captive calibration programs, while industrial facilities outsource to regional laboratories.
- Safety Testing:Arc-flash hazard analysis, NFPA 70E compliance verification, and energized work permits. Construction sites in California and Florida drive seasonal demand spikes tied to project commissioning schedules.
Routine testing dominates installed base. Diagnostic testing is where expansion concentrates.
Application:
Industrial facilities absorb the highest per-site service expenditure, while commercial buildings fragment demand across thousands of low-value contracts.
- Industrial Facilities:Continuous process operations requiring 24/7 power reliability. Petrochemical complexes along the Texas Gulf Coast sustain the densest concentration of arc-flash and transformer testing protocols.
- Commercial Buildings:Periodic compliance verification for office towers, retail centers, and hospitality properties. Property management firms in Chicago and Toronto consolidate vendor relationships to reduce administrative overhead.
- Power Generation:Commissioning and maintenance testing for gas turbines, solar inverters, and battery storage systems. Renewable buildouts in California and Texas are displacing coal-plant testing volumes.
- Telecommunications:DC power plant and battery backup verification for cell towers and central offices. 5G densification in urban corridors is fragmenting site footprints and complicating logistics.
Industrial facilities anchor revenue per engagement. Power generation applications are climbing the fastest as renewable interconnection queues lengthen.
Technology:
Digital testing platforms achieve payback through reduced labor hours per test, while mobile solutions trade capital intensity for deployment flexibility.
- Traditional Testing:Manual instrument operation with paper-based documentation. Aging utility workforces in the Midwest sustain residual demand despite digitization pressure.
- Digital Testing:Software-defined measurement with automated data logging and cloud storage. Major California utilities are deploying these platforms at 345kV substations to enable remote analysis.
- Automated Testing:Robotic probe positioning and unattended data acquisition for repetitive sequences. High-volume transformer manufacturing facilities in Mexico are adopting in-house automated lines.
- Mobile Testing Solutions:Self-contained laboratories mounted on trailers or trucks for on-site high-voltage work. Data center operators seeking minimized downtime during facility upgrades are driving adoption in Northern Virginia.
Traditional testing retains legacy installed base. Mobile testing solutions are gaining share fastest among operators with uptime-critical infrastructure.
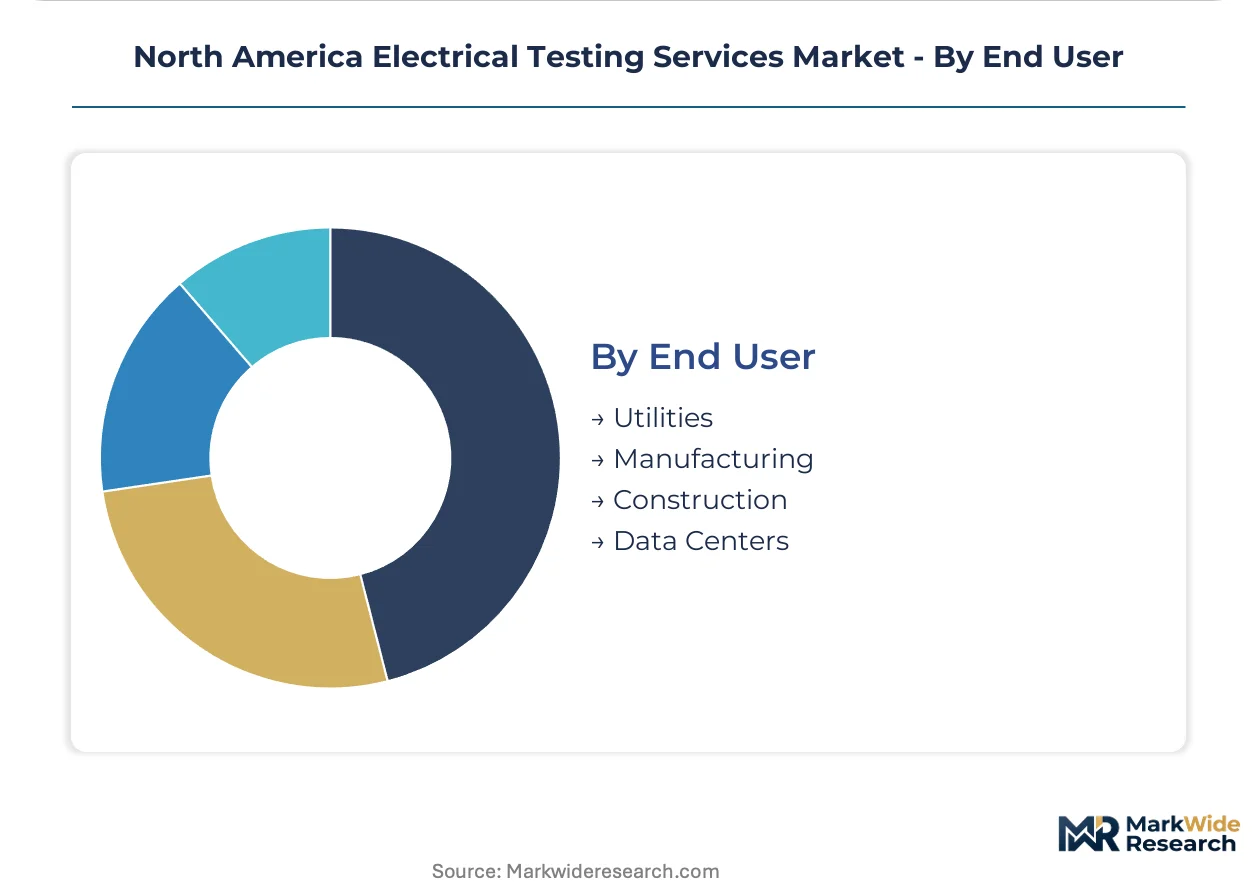
End User:
Utilities internalize testing capability through captive engineering departments, while data centers externalize to specialized contractors with rapid response commitments.
- Utilities:Vertically integrated testing organizations with centralized laboratories and field crews. Investor-owned utilities in Texas and California maintain the largest captive testing capacities.
- Manufacturing:Plant electrical maintenance teams supplemented by contracted specialists for high-voltage work. Automotive and semiconductor fabs in the Midwest and Southwest prioritize predictive programs.
- Construction:Project-based commissioning and turnover testing with no recurring revenue. Infrastructure stimulus programs are expanding contract volumes in the Northeast and Pacific Northwest.
- Data Centers:Hyperscale operators and colocation providers with stringent uptime guarantees. Northern Virginia and Dallas-Fort Worth markets exhibit the most granular service unbundling.
Utilities dominate internalized testing capacity. Data centers are where external service expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian testing laboratories export diagnostic services to United States data center operators seeking rapid turnaround on transformer health assessments. Cross-border certification harmonization under CSA and NEC standards accelerates contract execution between Ontario-based firms and Michigan industrial facilities.
United States
OSHA electrical safety mandates compress compliance windows for facility managers across Texas and Louisiana petrochemical complexes. The National Electrical Code annual amendment cycle forces continuous recertification of installed infrastructure. Gulf Coast industrial corridors anchor dense concentrations of arc-flash and transformer testing protocols serving LNG export terminal expansions.
Canada
Health Canada and provincial electrical authorities enforce parallel certification regimes that shape cross-border service standardization. CSA Group standards alignment with NEC protocols enables Ontario-based testing firms to bid on Michigan and New York industrial contracts. Alberta oil sands electrification projects sustain demand for high-voltage substation commissioning services through Calgary engineering clusters.
Mexico
Automotive manufacturing electrification in Nuevo León and Baja California generates transformer testing demand for paint shop and welding line power quality verification. The national electrical utility CFE mandates third-party certification for industrial interconnections above 34.5kV. Monterrey industrial parks concentrate preventive maintenance contracts among maquiladora operations serving United States supply chains.
North America Electrical Testing Services Market Competitive Landscape
On the supply side, the industry is consolidating around multi-service inspection conglomerates with captive laboratory networks. Three strategic archetypes dominate: global testing houses with diversified industrial portfolios, specialized high-voltage engineering boutiques, and utility-captive service divisions. Competitive positioning hinges on geographic accreditation breadth and technician certification density rather than equipment differentiation alone. M&A activity targets regional electrical testing firms with established utility relationships and certified field crews.
Among global testing conglomerates, SGS SA and Bureau Veritas exemplify the diversified inspection model with North American laboratory footprints anchoring large-scale industrial commissioning contracts. Doble Engineering Company occupies a specialist position in dissolved gas analysis technology for transformer health monitoring. These three firms represent contrasting competitive vectors: breadth versus depth versus technology-led diagnostics.
| Leading Market Players |
|---|
| TÜV SÜD |
| ALS Limited |
| SGS SA |
| RESA Power |
| Doble Engineering Company |
| Bureau Veritas |
| Applus+ |
| American Electrical Testing Co. LLC |
| Intertek Group plc |
| Others |
Value Network & Pricing Analysis
Undercapacity in high-voltage diagnostic equipment manufacturing across the United States and Canada is compressing supplier margins while elevating pricing power for firms with certified mobile testing fleets. This utilization squeeze simultaneously rewards early capital deployment in automated platforms and penalizes labor-dependent service models.
Pricing Analysis
The technology-generation pricing gap separates legacy manual testing contracts from digital platform deployments and emerging automated diagnostic suites. Three-tier pricing structure across premium, standard, and economy levels reflects certification density and sensor integration depth. Cost compression in routine testing is intensifying because digital platforms reduce labor hours per engagement. Data center operators exhibit lowest price sensitivity due to uptime guarantee penalties, while commercial property managers fragment demand across cost-optimized compliance verification.
Supply Chain Analysis
Contract manufacturing concentration for high-voltage test equipment rests with specialized electrical instrument producers in the United States, Germany, and Japan. Supply chains draw from precision sensor components, calibrated reference standards, and ruggedized computing hardware. Single-source vulnerability concentrates in chromatographic sensor modules for dissolved gas analysis systems. Distribution runs through direct field service organizations rather than third-party channels, with major testing firms maintaining captive equipment fabrication relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin integration with live electrical infrastructure is compressing testing intervals and recasting service value from reactive diagnosis to predictive prevention, a regulatory inflection amplified by OSHA's tightened compliance windows.
For Market Incumbents: Build technician certification density as the primary moat against digital platform commoditization. Consolidate regional electrical testing firms with established utility relationships to lock in multi-year commissioning contracts. Expand mobile testing fleet capacity in Northern Virginia and Dallas-Fort Worth to capture data center preventive maintenance elongation. Invest in dissolved gas analysis sensor integration to defend premium positioning against automated platform entrants. For New Entrants and Emerging Players: Pursue unbundled diagnostic modules in colocation markets where hyperscale operators seek precise scope delineation. Target Canadian provincial electrical authority harmonization gaps to arbitrage cross-border certification standards. Capture arc-flash compliance documentation friction through software-enabled record-keeping platforms. Establish rapid-response commitments as the primary go-to-market angle against incumbent scheduling constraints. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic testing providers with embedded sensor networks and multi-year calibration agreements. Long-term viability centers on predictive capability ownership rather than commoditized compliance verification. Acquisition target archetype: regional firms with dual CSA-NEC accreditation and concentrated utility relationships. Monitor IEC 61850 protocol adoption rates as the signal to watch for substation automation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Testing Fleet Expansion | Captures data center uptime-critical demand in Northern Virginia and Dallas-Fort Worth corridors. |
| Dual Certification Investment | Enables Ontario-based firms to bid on Michigan and New York industrial contracts under harmonized standards. |
| Sensor Network Integration | Fuses dissolved gas analysis with thermal imaging at 345kV substations for unified health indices. |
| Technician Training Pipeline | Addresses certified specialist scarcity that constrains diagnostic testing deployment velocity. |
| Digital Platform Deployment | Displaces manual methods across aging transmission infrastructure in California and Texas utilities. |
Research Methodology
A spread of perspectives from utility planning officers, data center facility managers, electrical testing firm executives, and OSHA compliance specialists converged on the working assumptions. Primary field interviews combined with secondary validation from EIA power infrastructure data, FERC interconnection filings, NEC amendment records, and utility capital expenditure disclosures. Bottom-up service contract analysis triangulated against top-down market sizing from equipment manufacturer shipment data.
Demand-supply balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled include service type tier, application vertical, technology generation, and end-user procurement pattern. CAGRs derived from historical contract renewal velocity and capital project pipeline tracking. Forecast inputs incorporated OSHA enforcement intensity indices and data center construction permit flows.
Sensitivities concentrate around NEC amendment frequency, certified technician graduation rates, and digital twin adoption curves in utility substations. Forecasts reflect assumptions about regulatory enforcement continuity and infrastructure stimulus program durability. Quarterly review of transformer failure incident reports and utility RFP issuance patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Shock Testing System Market
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
Global Micrometer Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Volte Testing Market
Test and Measurement
Air Leak Testing Market
Test and Measurement
Wafer-Level Test and Burn-In [WLTBI] Market
Test and Measurement
Smart Implant Telemetry and Reliability Test Equipment Market
Test and Measurement
Digital Oscilloscope Market
Test and Measurement
Torsion Tester Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Hipot Tester Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Air Measuring Equipment Market
Test and Measurement
Handheld Digital Multimeter Market
Test and Measurement
Data Acquisition Equipment Market