
 EMC Shielding and Test Equipment Market | 2026-2036
EMC Shielding and Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
EMC Shielding and Test Equipment Market Analysis
Aftermarket calibration and recertification revenue is fragmenting across regional service networks and eroding the historical concentration of margin pools in original equipment sales. Keysight Technologies sustains technology leadership through R&D intensity in vector network analyzers for shielding effectiveness validation. Rohde & Schwarz GmbH & Co. KG anchors European demand with comprehensive test suites spanning radiated immunity and conducted emission protocols. Parker Hannifin Corp differentiates through vertical integration into conductive elastomer formulations that supply both aerospace and automotive tiers.
EMC shielding and test equipment encompasses materials, instruments, and enclosures engineered to attenuate electromagnetic interference across frequencies typically ranging from 30 MHz to 40 GHz, ensuring electronic systems operate without disruption in shared spectral environments. Test instruments dominate current revenue as 5G base station deployments and radar module proliferation multiply certification cycles. Shielding materials represent the fastest-growing product category as conductive coatings replace legacy metal housings in weight-sensitive aerospace and electric vehicle applications. Custom solutions command premium pricing where military-grade Tempest specifications or medical imaging compatibility requirements exceed commercial standards.
The FCC enforces Part 15 emission limits that mandate pre-market compliance testing for all digital devices sold in the United States, directly expanding demand for anechoic chambers and spectrum analyzers. ETS-Lindgren Inc. competes on chamber design expertise while TE Connectivity specializes in shielded interconnect systems that preempt test failures at the component level. The EU AI Act and MDR framework in Europe are layering algorithmic reliability and medical device safety requirements atop traditional EMC mandates, broadening the scope of mandatory testing. Stakeholders must monitor whether China's GB standards and dual carbon goals will harmonize with IEC frameworks or create parallel certification burdens that fragment supply chain planning.
Market Dynamics
Automotive electrification is compressing EMC compliance cycles as OEMs integrate 40-70 electronic control units per vehicle, forcing simultaneous shielding redesigns across powertrain, infotainment, and ADAS subsystems.
Growth Catalysts
- EU Radio Equipment Directive:Tightened emission limits for wireless devices sold in Europe are mandating additional pre-market testing phases.
- Conductive polymer formulations:Weight-sensitive aerospace and EV manufacturers are substituting metal housings with spray-applied shielding coatings to meet gram-level targets.
- Shanghai-Shenzhen corridor:Concentrated EV battery and inverter production in these Chinese manufacturing hubs is generating localized demand for anechoic chambers and spectrum analyzers.
Market Restraints
- Silver price volatility:Conductive elastomers and coatings rely on silver flake fillers, exposing material costs to precious metal commodity swings.
- Chamber manufacturing concentration:Anechoic chamber fabrication capacity clusters in Germany and the United States, creating 12-16 month delivery backlogs for Asian test lab expansions.
- Legacy metal shielding substitution ceiling:Military Tempest and medical imaging applications still require machined aluminum enclosures, limiting polymer penetration in high-specification segments.
Strategic Opportunities
- India's PLI scheme for electronics:Contract manufacturers establishing smartphone and component assembly in Noida and Chennai require captive EMC testing infrastructure.
- 5G mmWave base station deployment:Shielding effectiveness validation above 24 GHz demands vector network analyzer upgrades that incumbent labs have deferred.
- EU AI Act algorithmic reliability mandates:Medical device and automotive AI modules now face combined functional safety and EMC certification, broadening test scope.
Industry Challenges
- RF engineer scarcity:Test lab expansion in China and Germany outpaces university pipeline output for antenna measurement and spectrum analysis specialists.
- Multi-standard certification stacking:A single automotive radar module now requires sequential FCC Part 15, EU RED, and GB standard testing, extending time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMC Shielding and Test Equipment Market |
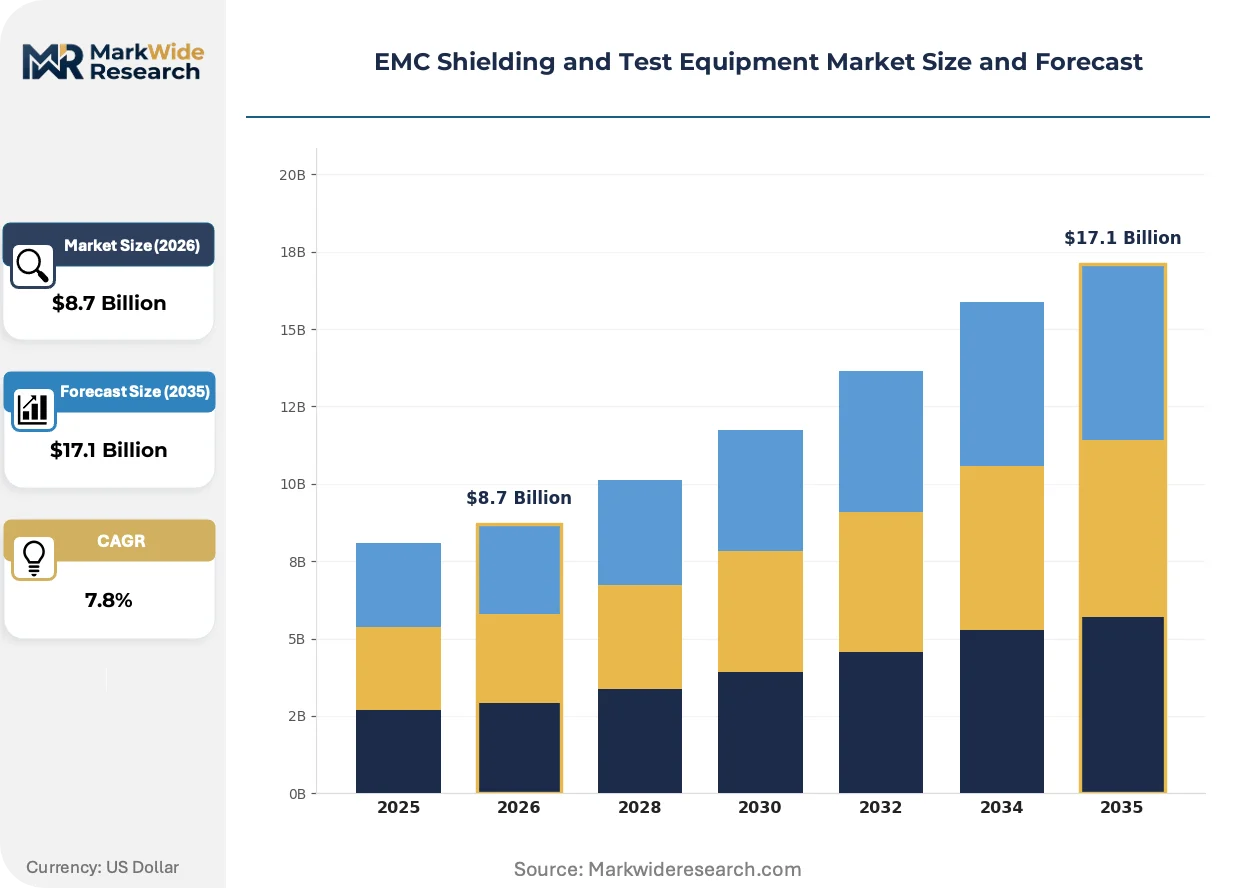
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shielding Materials, Test Instruments, Enclosures, Custom Solutions End User: Telecommunications, Aerospace, Automotive, Medical Devices Technology: Conductive Coatings, Radiated Emission, Shielded Cables, Filters Application: Shielding, Testing, Compliance, Signal Integrity |
| Companies Covered | 3M Company, Rohde & Schwarz GmbH & Co. KG, Keysight Technologies, Inc., Parker Hannifin Corp, DuPont de Nemours, Inc., ETS-Lindgren Inc., TE Connectivity, AMETEK, Inc., Laird Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMC Shielding and Test Equipment Market Emerging Trajectories
Shielding material science and test automation architectures are converging to address frequency extension demands from 5G mmWave and automotive radar bands. Three developments are restructuring competitive positioning.
Additive manufacturing of lattice-structured conductive polymers is collapsing the trade-off between electromagnetic attenuation and mechanical weight in aerospace radomes and EV battery enclosures. Boeing and Airbus suppliers are qualifying electron-beam-melted titanium mesh geometries that achieve 60 dB shielding effectiveness at 40% lower mass than solid aluminum. This compression of the performance-weight frontier is forcing incumbent sheet-metal fabricators to defend position through integrated thermal-shielding multifunctionality.
The FCC's 2023 expansion of unlicensed device operation into the 6 GHz band has triggered redesign cycles for Wi-Fi 6E and 7 equipment manufacturers. Pre-market testing now requires anechoic chamber validation across 5.925-7.125 GHz, a range previously exempt from Part 15 radiated emission limits. Test equipment vendors are responding with software-defined spectrum analyzer platforms that span 30 MHz to 50 GHz without hardware band-switching.
Aftermarket calibration contracts are unbundling from original equipment sales as independent service networks achieve ISO 17025 accreditation for vector network analyzer verification. German automotive suppliers now source annual recertification from regional metrology labs rather than manufacturer service departments. This channel fragmentation is visible most acutely in Stuttgart and Munich, where Tier 1 suppliers operate captive test facilities requiring external calibration audit trails.
EMC Shielding and Test Equipment Market Segmentation
EMC shielding and test equipment vendors structure their service organizations around product lifecycle intensity. Calibration contracts and recertification revenue now rival original equipment margins in telecommunications and automotive verticals where certification cycles compress annually.
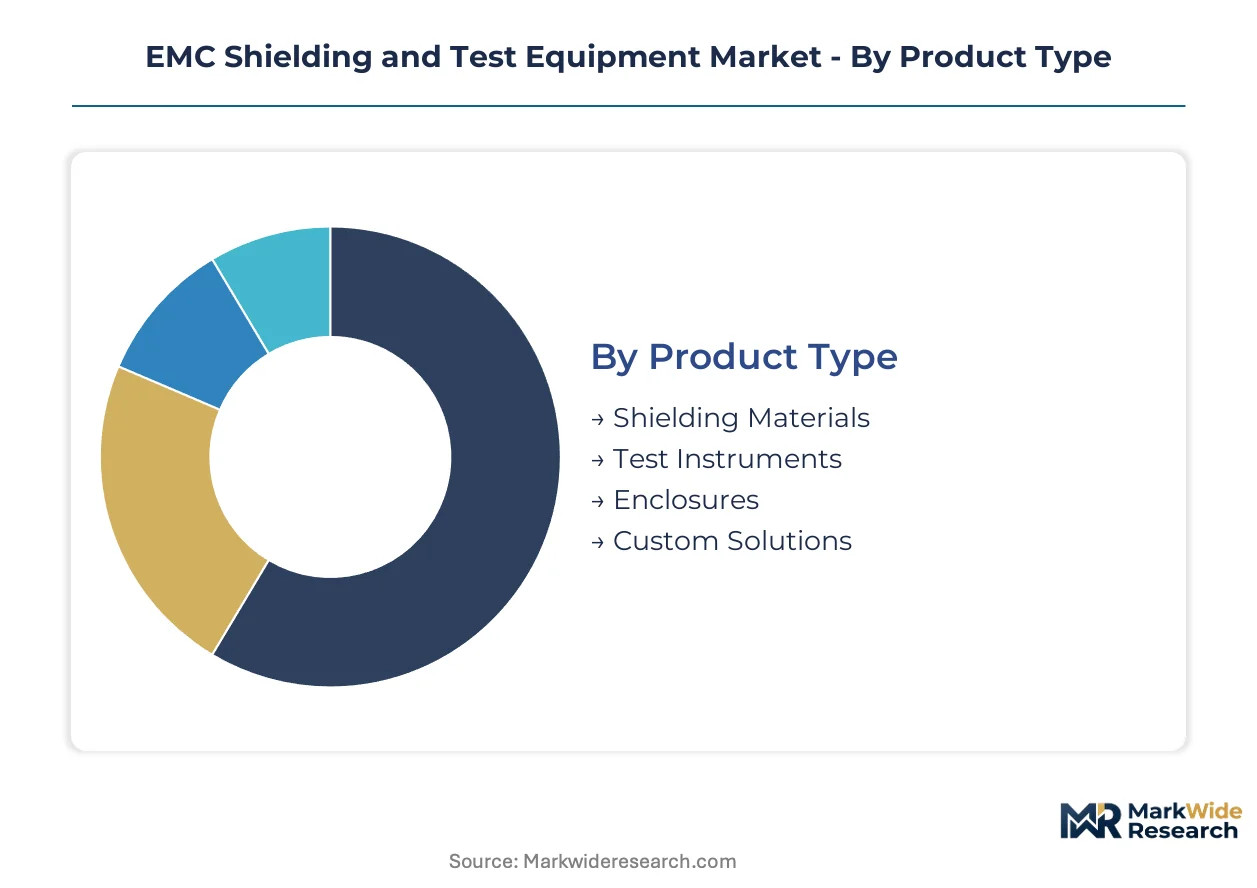
Product Type:
After-sales-service intensity varies dramatically across product categories, with test instruments generating recurring calibration revenue while shielding materials drive single-purchase replacement cycles.
- Test Instruments:Spectrum analyzers, vector network analyzers, and signal generators require annual ISO 17025 calibration to maintain measurement traceability for FCC Part 15 and EU RED compliance submissions. German automotive suppliers in Stuttgart and Munich now outsource recertification to regional metrology labs rather than manufacturer service departments.
- Shielding Materials:Conductive elastomers, metal meshes, and spray-applied coatings attenuate electromagnetic interference across 30 MHz to 40 GHz. Aerospace manufacturers in Toulouse and Hamburg substitute solid aluminum with electron-beam-melted titanium lattice structures to achieve gram-level weight targets without sacrificing shielding effectiveness.
- Enclosures:Machined aluminum housings and ventilated shielded cabinets protect sensitive electronics in medical imaging and military Tempest applications where polymer penetration remains limited by specification rigidity.
- Custom Solutions:Application-specific shielding assemblies address military-grade Tempest specifications or MRI compatibility requirements that exceed commercial standards, commanding premium pricing through engineering-intensive design cycles.
Test instruments hold the largest share; momentum sits with shielding materials as conductive coatings displace legacy metal housings in weight-sensitive electric vehicle and aerospace platforms.
End User:
Cost tier differentiation separates high-specification military and medical applications from volume-driven automotive and telecommunications procurement.
- Automotive:OEMs integrate 40-70 electronic control units per vehicle across powertrain, infotainment, and ADAS subsystems, forcing simultaneous shielding redesigns and multiplying pre-market EMC validation cycles for radar and battery management modules.
- Telecommunications:5G base station deployments and Wi-Fi 6E/7 equipment proliferation demand anechoic chamber validation across 5.925-7.125 GHz following FCC expansion into the 6 GHz band.
- Aerospace:Boeing and Airbus suppliers qualify additive-manufactured conductive polymers that collapse the trade-off between electromagnetic attenuation and mechanical weight in radome and satellite payload applications.
- Medical Devices:EU MDR framework and FDA electromagnetic compatibility requirements for imaging equipment and implantable devices mandate shielding effectiveness validation beyond commercial standards.
Automotive captures the largest share; telecommunications exhibits the steepest expansion trajectory as mmWave infrastructure deployment accelerates spectrum analyzer demand.
Technology:
Volume concentration favors conductive coating application methods that scale across high-volume automotive and consumer electronics manufacturing.
- Conductive Coatings:Spray-applied silver-filled polymers and vacuum-deposited metal films replace machined housings in smartphone and EV battery enclosures where weight reduction targets exceed 40%.
- Radiated Emission:Anechoic chamber and open-area test site measurements validate electromagnetic field strength against FCC Part 15 and EU RED limits, with chamber fabrication capacity clustering in Germany and the United States creating delivery backlogs for Asian test lab expansions.
- Shielded Cables:Braided copper and foil-wrapped interconnects prevent signal leakage in high-frequency data transmission between 5G antennas and baseband processing units.
- Filters:Pi-section and T-section EMI filters suppress conducted interference on power and signal lines entering shielded enclosures.
Conductive coatings hold the largest share; radiated emission testing gains share fastest as frequency extension demands multiply certification complexity.
Application:
Customer type separates captive Tier 1 automotive test facilities from independent commercial laboratories serving fragmented electronics manufacturing.
- Testing:Pre-market validation spans radiated emission, conducted emission, radiated immunity, and conducted immunity protocols with multi-standard stacking extending time-to-market for automotive radar modules requiring sequential FCC, EU RED, and GB standard certification.
- Compliance:Documentation and regulatory submission support accompanies physical testing, with EU AI Act algorithmic reliability mandates now layering functional safety requirements atop traditional EMC certification for medical and automotive AI modules.
- Shielding:Material selection and architectural integration address electromagnetic interference at the enclosure, board, and component levels across aerospace radomes and EV battery packs.
- Signal Integrity:High-speed digital design verification ensures data transmission integrity in 25 Gbps+ interconnects used in data center and telecommunications infrastructure.
Testing commands the largest share; compliance applications expand most quickly as regulatory scope broadens beyond traditional electromagnetic limits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German automotive OEMs prioritize shielding effectiveness validation for dense ECU architectures, while Chinese manufacturers emphasize high-volume chamber deployment for EV battery certification cycles.
United States
FCC Part 15 enforcement mandates pre-market testing for all digital devices, expanding demand for anechoic chambers and spectrum analyzers. The IRA's domestic manufacturing incentives accelerate test lab construction near semiconductor fabrication clusters. Greater Boston and Austin host concentrated defense electronics testing facilities serving Tempest-grade specifications.
Germany
EU RED tightened emission limits force additional pre-market validation phases for wireless equipment. KBA automotive homologation requirements layer EMC compliance atop functional safety mandates for ADAS modules. Stuttgart and Munich anchor captive Tier 1 test facilities requiring external calibration audit trails.
China
GB standards and dual carbon goals drive substitution of metal housings with conductive polymers in EV battery enclosures. MIIT certification requirements for telecommunications equipment multiply spectrum analyzer procurement cycles. Shanghai and Shenzhen corridor concentrates anechoic chamber demand from battery and inverter manufacturers.
Japan
METI industrial standards emphasize high-frequency validation for 5G base station exports. JIS certification frameworks maintain rigorous shielding effectiveness thresholds for medical imaging equipment. Nagoya automotive suppliers integrate EMC testing into radar module production lines for export markets.
India
BIS electronics safety regulations and PLI scheme incentives attract contract manufacturers requiring captive EMC infrastructure. TRAI spectrum management rules mandate emission testing for telecommunications equipment. Noida and Chennai emerge as smartphone assembly hubs driving localized chamber deployment.
EMC Shielding and Test Equipment Market Vendor Landscape
Capability concentration sits with precision instrument specialists; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: test equipment vendors with software-defined architectures, materials suppliers with conductive polymer formulations, and chamber fabricators with electromagnetic design expertise. Dominant competitive moves include backward integration into raw material supply and geographic expansion through regional calibration service networks.
Among precision measurement specialists, Keysight Technologies, Inc. and Rohde & Schwarz GmbH & Co. KG occupy positions exemplifying the test equipment archetype, while Parker Hannifin Corp represents diversified industrial participation through materials science capabilities.
| Leading Market Players |
|---|
| 3M Company |
| Rohde & Schwarz GmbH & Co. KG |
| Keysight Technologies, Inc. |
| Parker Hannifin Corp |
| DuPont de Nemours, Inc. |
| ETS-Lindgren Inc. |
| TE Connectivity |
| AMETEK, Inc. |
| Laird Technologies, Inc. |
| Others |
Supply Flow & Price Mechanics
Chamber fabrication undercapacity in Germany and the United States stretches delivery timelines to 12-16 months for Asian test lab expansions, compressing supplier pricing power for anechoic chamber vendors while amplifying margin capture for spectrum analyzer manufacturers with software-defined architectures.
Pricing Analysis
Long-term offtake contracts dominate anechoic chamber procurement for automotive OEMs and telecommunications infrastructure deployers, while spot purchasing prevails for silver-filled conductive polymer feedstocks exposed to commodity volatility. Pricing stratifies across military-grade Tempest specifications, commercial EMC certification tiers, and economy-grade consumer electronics shielding, with ISO 17025 calibration bundling commanding 15-25% premiums over bare equipment sales. Cost compression in conductive elastomer formulations is intensifying because silver flake filler prices swing with precious metal markets. Tier 1 automotive suppliers in Stuttgart and Munich exhibit lowest price sensitivity due to captive test facility mandates, while Indian contract manufacturers under PLI scheme constraints drive hardest bargain negotiations for chamber deployment.
Supply Chain Analysis
Silver mining concentrates in Mexico, Peru, and China feed conductive coating formulations, while precision machining capacity for aluminum enclosures clusters in Germany, Japan, and the United States. Electron-beam melting equipment for titanium lattice structures sources from specialized additive manufacturing OEMs in Germany and the United States, with shielded cable braiding capacity concentrated in China and South Korea. Single-source vulnerability sits with anechoic chamber absorber foam formulations protected by proprietary chemistry from two German suppliers. Distribution runs through direct sales forces for test instruments above $500K unit value, regional distributors for shielding materials, and systems integrators for custom enclosure assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive OEMs and Chinese EV battery manufacturers operating captive test facilities, fragmenting demand across fewer large-scale procurement decision-makers with extended calibration contract leverage.
For Market Incumbents: Pre-empt silver price volatility exposure through backward integration into recycled precious metal recovery or long-term offtake agreements with Mexican and Peruvian mining consortiums. Lock in chamber fabrication capacity expansion in Southeast Asia to defuse the 12-16 month delivery backlog vulnerability before Chinese test lab competitors develop indigenous absorber foam chemistry. Certification investment in EU AI Act algorithmic reliability testing protocols represents the priority capability extension as regulatory scope broadens beyond traditional EMC mandates. For New Entrants and Emerging Players: India's Noida and Chennai smartphone assembly clusters under PLI scheme incentives represent the most penetrable entry point for mid-scale anechoic chamber deployment, with TRAI emission testing mandates creating immediate procurement pull. Regional calibration service networks in Stuttgart and Munich offer white-space acquisition targets as German automotive suppliers unbundle aftermarket recertification from original equipment vendors. Partner with established metrology labs for ISO 17025 accreditation rather than building captive service infrastructure from zero. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among test instrument vendors with annual calibration contract attachment above 60% of installed base, positioning these archetypes for superior cash flow quality across the analysis window. Acquisition targets should screen for conductive polymer formulation IP with aerospace qualification heritage and EV battery enclosure design wins. Monitor MIIT certification requirement announcements for Chinese telecommunications equipment as the inflection signal for spectrum analyzer demand acceleration above historical replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Recovery | Secures feedstock cost stability against London Metal Exchange price swings for conductive coating margins. |
| ISO 17025 Accreditation Expansion | Captures German automotive unbundling of calibration contracts from Keysight and Rohde & Schwarz service departments. |
| EU AI Act Testing Protocol Development | Positions test labs for combined functional safety and EMC certification of automotive AI modules under KBA oversight. |
| Southeast Asian Chamber Fabrication | Defuses delivery backlog vulnerability for Chinese EV battery and inverter manufacturers in Shanghai-Shenzhen corridor. |
| Additive Manufacturing Qualification | Enables electron-beam-melted titanium lattice structures for Boeing and Airbus radome suppliers at 40% weight reduction. |
Methodological Framework
Desk research of FCC Part 15 enforcement databases, EU RED implementation guidance, MIIT certification registries, and SEC 10-K filings from precision instrument vendors preceded structured interviews with EMC test lab directors, automotive Tier 1 supplier procurement managers, aerospace radome design engineers, and conductive polymer R&D leads. Secondary validation drew from customs trade data for silver flake imports, anechoic chamber installation permits in German industrial zones, and IHS Markit vehicle production databases. Bottom-up equipment shipment tallies triangulated against top-down OEM spending surveys.
Assumptions held fixed include regulatory emission limit stringency trajectories for FCC Part 15 and EU RED, while silver price volatility and EV battery enclosure design win rates were varied across sensitivity scenarios. The analytical framework modeled product type, end user vertical, technology application, and geographic production cluster dimensions across the projection horizon. CAGRs derived from logistic diffusion curves fitted to 5G base station deployment schedules and automotive ECU integration density trends, with cross-reference to vector network analyzer upgrade cycles and anechoic chamber capacity utilization rates.
Practitioners should monitor GB standard harmonization announcements with IEC frameworks, silver price movements above 20% annual volatility bands, and KBA homologation requirement expansions for early signals necessitating forecast revision. Cross-checking against ETS-Lindgren and TE Connectivity order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Test and Measurement Market
Test and Measurement
Water Leakage Tester Market
Test and Measurement
Ground Resistance Testers Market
Test and Measurement
Brightness Meter Market
Test and Measurement
Pump Testers Market
Test and Measurement
Four-Quadrant Battery Simulator Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
Sound Level Meter Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Ultrasonic Testing Equipment Market
Test and Measurement
Electronic Test Instrument Market
Test and Measurement
Telescopic Inspection Mirror Market
Test and Measurement
Global Inspection Machines Market